
 Curbside Recyclable Packaging Market | 2026-2036
Curbside Recyclable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Curbside Recyclable Packaging Market Outlook
A shift from single-source virgin material contracts toward multi-source recycled fiber supply is expanding across the Curbside Recyclable Packaging value chain. WestRock leverages its North American containerboard footprint to secure post-consumer fiber streams. Mondi anchors European kraft paper operations with integrated pulp-to-pack recycling loops. Sealed Air competes through barrier film innovations that maintain shelf stability while qualifying for curbside polyethylene streams.
Curbside recyclable packaging encompasses containers, wraps, and enclosures engineered for collection, sorting, and reprocessing through standard municipal recycling infrastructure without requiring drop-off or specialty streams. These formats typically incorporate mono-material polyethylene or uncoated paperboard constructions with melt temperatures and fiber lengths compatible with existing materials recovery facility optical sorters and pulping lines. Flexible packaging leads volume contribution due to lightweighting advantages in e-commerce parcel films, though rigid containers capture disproportionate margin pools through premium food-grade recycled content certification. Bio-based plastics represent the fastest-expanding material segment as brand owners seek drop-in alternatives that preserve existing curbside sortation equipment compatibility.
The EPA promotes national recycling strategy consistency across United States municipalities, while the EU Green Deal embeds packaging recyclability mandates through revised Extended Producer Responsibility frameworks. FDA food-contact notification requirements constrain rapid material substitutions for curbside-recyclable formats serving perishable goods. Stakeholders must monitor emerging state-level labeling standards that threaten to fragment what qualifies as curbside recyclable across American markets.
Market Dynamics
Extended producer responsibility frameworks are forcing brand owners to redesign packaging portfolios around mono-material compatibility, compressing multi-layer barrier formats that previously dominated shelf-stable food and personal care categories.
Growth Catalysts
- EU Green Deal packaging mandates:The revised Extended Producer Responsibility framework imposes recyclability targets that compel food and beverage brands to convert flexible multilayer films into curbside-compatible polyethylene constructions.
- E-commerce parcel volume concentration:Lightweight flexible films for shipping envelopes and protective wraps capture demand from online retail fulfillment centers seeking to reduce dimensional weight charges while maintaining municipal stream compatibility.
- Bio-based polyethylene scale-up:Drop-in bio-derived resins from sugarcane and agricultural waste streams integrate into existing high-density polyethylene recycling infrastructure without requiring optical sorter recalibration.
Market Restraints
- Post-consumer resin supply fragmentation:Collection infrastructure gaps in mid-sized American municipalities create feedstock shortages for food-grade recycled content certification programs.
- Multi-material legacy equipment lock-in:Converting lines optimized for polyester-polyethylene laminates face extended retooling cycles and capital expenditure requirements to process mono-material alternatives.
- FDA food-contact notification timelines:Novel barrier coatings and adhesive systems for curbside-recyclable formats endure 12-24 month regulatory review periods before commercial deployment.
Strategic Opportunities
- India municipal collection expansion:Urban local bodies in Maharashtra and Karnataka are piloting source-segregated dry waste streams that create entry points for imported curbside-compatible packaging specifications.
- Digital watermark integration:Invisible marker technologies combined with AI-powered optical sorters enable flexible packaging identification at materials recovery facilities previously limited to rigid container sortation.
- Pharmaceutical blister pack conversion:Regulatory pressure from the EU Green Deal drives demand for paper-fiber alternatives to PVC-aluminum laminates in over-the-counter medication packaging.
Industry Challenges
- Materials recovery facility contamination tolerance:Flexible films labeled as recyclable frequently fail sortation due to adhesive residues and incompatible melt indices, triggering downstream reprocessor rejection.
- Recycled content certification backlog:Third-party auditors face capacity constraints verifying post-consumer fiber percentages for paperboard food containers, delaying premium pricing realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curbside Recyclable Packaging Market |
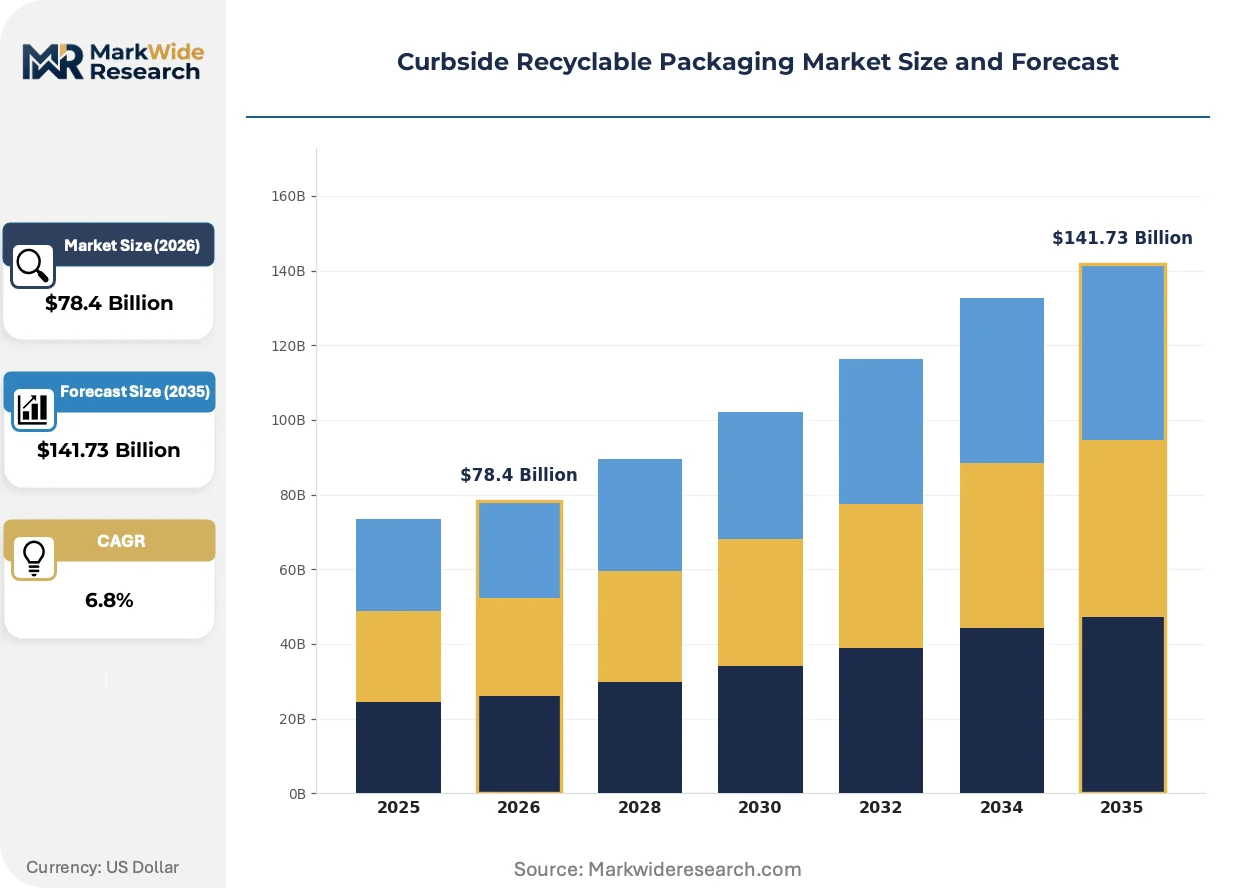
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Cartons, Film Material: Paper, Polyethylene, Polypropylene, Bio-based Plastics Application: Food & Beverage, Personal Care, Household Products, Healthcare End User: Retailers, Manufacturers, Distributors, E-commerce |
| Companies Covered | WestRock, Amcor, Mondi, Sealed Air, DS Smith, Sonoco, Stora Enso, Tetra Pak, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curbside Recyclable Packaging Market Strategic Shifts
Active research in barrier chemistry and fiber engineering is collapsing the performance gap between curbside-compatible formats and their multi-layer predecessors across moisture-sensitive and oxygen-sensitive product categories.
Mono-material polyethylene barrier films incorporating plasma-deposited silicon oxide coatings are unifying oxygen and moisture protection within single-resin streams. Premium pet food and specialty coffee roasters are adopting these constructions at accelerated procurement cycles. The technology is unifying previously separate flexible and rigid supply chains into consolidated polyethylene recycling pools.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorinated treatments from molded fiber foodservice containers. European quick-service restaurant chains are converting to PFAS-free barrier coatings ahead of 2025 enforcement deadlines. Bakery and fried food packaging segments face accelerated reformulation timelines to maintain market access.
Retailer-imposed recyclability scorecards are compressing supplier qualification cycles for private-label packaging procurement. Mass-market grocery chains in Germany and France now require third-party verification of curbside compatibility claims before shelf placement. Brand owners are consolidating supplier relationships toward converters with integrated recycling loop certifications and documented post-consumer resin offtake agreements.
Curbside Recyclable Packaging Market Segmentation
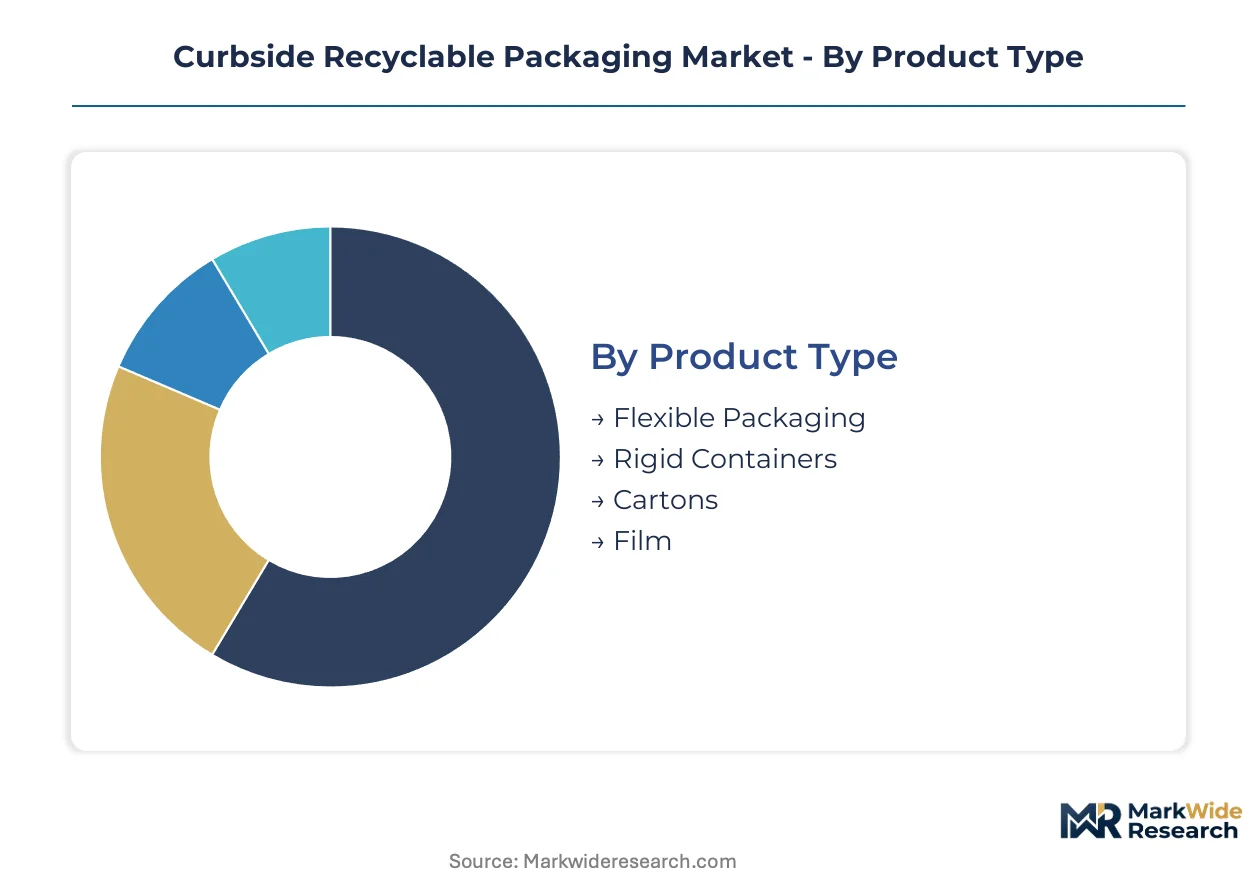
Curbside recyclable packaging segmentation reflects divergent technical requirements across municipal collection infrastructure. Material compatibility with optical sorters and pulping systems determines qualification for mainstream recovery streams.
Product Type:
Format selection hinges on barrier performance requirements versus sortation simplicity trade-offs.
- Flexible Packaging:Mono-material polyethylene films and pouches integrate into existing high-density polyethylene recycling pools without optical sorter recalibration. E-commerce parcel films concentrate demand in Germany and France where dimensional weight charges drive lightweighting adoption.
- Rigid Containers:Injection-molded polyethylene and polypropylene tubs, bottles, and jars maintain structural integrity through multiple reprocessing cycles. Premium food-grade recycled content certification commands disproportionate margin pools in North American dairy and ready-meal segments.
- Cartons:Uncoated paperboard constructions with specified fiber lengths compatible with standard pulping lines.
- Film:Stretch and shrink wraps engineered for polyethylene stream aggregation at materials recovery facilities.
Mature deployment sits with Rigid Containers. Newer deployment is concentrated in Flexible Packaging.
Material:
Feedstock economics and regulatory pressure on carbon intensity reshape procurement priorities across converter networks.
- Paper:Unbleached kraft and recycled fiber grades with controlled contamination thresholds for municipal pulping operations. German quick-service restaurant chains drive specification tightening ahead of EU Green Deal enforcement.
- Polyethylene:High-density and low-density resins with melt indices calibrated to existing reprocessor equipment. Post-consumer resin supply fragmentation in mid-sized American municipalities constrains food-grade certification scale-up.
- Polypropylene:Clarified and impact-copolymer grades for rigid container applications.
- Bio-based Plastics:Drop-in polyethylene derived from sugarcane and agricultural waste streams preserves existing curbside sortation compatibility without equipment modification.
Volume concentration favors Polyethylene. Steepest expansion trajectory belongs to Bio-based Plastics.
Application:
Shelf-stability requirements and consumer safety protocols create divergent barrier specification pathways.
- Food & Beverage:Oxygen-sensitive and moisture-sensitive categories drive plasma-deposited silicon oxide coating adoption in mono-material films. Specialty coffee roasters and premium pet food brands accelerate procurement cycles for barrier-enhanced polyethylene constructions.
- Personal Care:Pump dispensers and tubes convert from polyester-polyethylene laminates to mono-material alternatives under retailer-imposed recyclability scorecards.
- Household Products:Concentrated detergents and cleaning formulations in rigid containers.
- Healthcare:Regulatory pressure from EU Green Deal mandates drives paper-fiber alternatives to PVC-aluminum blister packs in over-the-counter medication packaging.
Margin realization peaks in Food & Beverage. Regulatory conversion urgency concentrates in Healthcare.
End User:
Procurement authority and specification influence distribute unevenly across value chain positions.
- Retailers:Mass-market grocery chains in Germany and France impose third-party curbside compatibility verification requirements before private-label shelf placement. Supplier consolidation accelerates toward converters with integrated recycling loop certifications.
- Manufacturers:Food and beverage brand owners redesign portfolios around mono-material compatibility under extended producer responsibility frameworks.
- Distributors:Logistics intermediaries with limited direct specification authority.
- E-commerce:Fulfillment centers prioritize lightweight flexible films for shipping envelopes to reduce dimensional weight charges while maintaining municipal stream qualification.
Specification control concentrates with Retailers. Volume growth velocity favors E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for curbside recyclable packaging concentrates in Germany, France, and the United Kingdom, where municipal collection infrastructure reaches high coverage and extended producer responsibility frameworks enforce strict recyclability mandates.
United States
Food and beverage brands drive procurement of mono-material polyethylene formats as the EPA promotes national recycling strategy consistency across municipalities. FDA food-contact notification requirements constrain rapid material substitutions for perishable goods. Collection infrastructure gaps in mid-sized municipalities create feedstock shortages for food-grade recycled content certification programs in the Midwest and Southeast.
Germany
Quick-service restaurant chains accelerate conversion to PFAS-free barrier coatings ahead of REACH enforcement deadlines for molded fiber foodservice containers. The EU Green Deal embeds packaging recyclability mandates through revised Extended Producer Responsibility frameworks. Mass-market grocery chains in Bavaria and North Rhine-Westphalia impose third-party curbside compatibility verification before private-label shelf placement.
France
Specialty coffee roasters and premium pet food brands accelerate procurement cycles for barrier-enhanced mono-material polyethylene constructions. Retailer-imposed recyclability scorecards compress supplier qualification cycles for private-label packaging procurement in the Île-de-France region. The country's national environmental regulator enforces strict contamination thresholds for municipal pulping operations.
United Kingdom
E-commerce fulfillment centers prioritize lightweight flexible films for shipping envelopes to reduce dimensional weight charges while maintaining municipal stream qualification. Extended producer responsibility frameworks compel brand owners to redesign packaging portfolios around mono-material compatibility. London-based converters consolidate supplier relationships toward partners with integrated recycling loop certifications.
India
Urban local bodies in Maharashtra and Karnataka pilot source-segregated dry waste streams that create entry points for imported curbside-compatible packaging specifications. The country's national standards body develops certification protocols for post-consumer fiber integration. Mumbai and Bangalore clusters attract converter investment targeting the food and beverage export segment.
Curbside Recyclable Packaging Market Competitive Environment
Portfolio diversification dominates the current landscape as converters retool legacy equipment for mono-material compatibility. The vendor base spans integrated paperboard producers, flexible film specialists, and rigid container manufacturers with varying degrees of recycling loop integration. Three archetypes define positioning: fiber-integrated paperboard conglomerates, barrier film innovators, and rigid container specialists. M&A activity and capacity expansion for post-consumer resin processing represent the dominant competitive vectors.
Within the fiber-integrated tier, WestRock and Mondi exemplify contrasting geographic anchoring strategies. WestRock leverages its North American containerboard footprint to secure post-consumer fiber streams, while Mondi anchors European kraft paper operations with integrated pulp-to-pack recycling loops. Sealed Air occupies a distinct position among barrier film specialists, competing through innovations that maintain shelf stability while qualifying for curbside polyethylene streams.
| Leading Market Players |
|---|
| WestRock |
| Amcor |
| Mondi |
| Sealed Air |
| DS Smith |
| Sonoco |
| Stora Enso |
| Tetra Pak |
| Smurfit Kappa |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal packaging mandates gate qualified supply and premium-tier pricing access, as converters lacking post-consumer resin offtake agreements or third-party curbside compatibility certification face exclusion from retailer procurement scorecards in Germany and France. Brand owners with verified recycling loop integration capture margin premiums while uncertified competitors absorb cost compression in standard-grade polyethylene segments.
Pricing Analysis
Volume concentrates in commodity-grade mono-material polyethylene films where price compression runs through mid-sized American municipalities with fragmented post-consumer resin supply, while margin pools accrue to rigid containers with food-grade recycled content certification. Three-tier pricing structure across premium certified, standard compliant, and economy unverified levels separates converters by audit status. Pricing pressure stems from FDA food-contact notification timelines extending commercialization cycles for novel barrier coatings. Small-brand food and beverage manufacturers exhibit highest price sensitivity; premium pet food and specialty coffee roasters show lowest.
Supply Chain Analysis
Third-party curbside compatibility certification gates supplier qualification for mass-market grocery chains in Germany, France, and the United Kingdom, concentrating qualified supply among integrated paperboard producers and barrier film specialists with documented recycling loop partnerships. Raw material procurement draws from post-consumer fiber streams, sugarcane-derived bio-polyethylene, and plasma-deposited silicon oxide barrier precursors. Single-source vulnerability sits with optical sorter equipment calibration dependencies at materials recovery facilities. Distribution runs through converter-direct relationships with retailer private-label procurement teams and e-commerce fulfillment center specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive post-consumer resin processing capacity determines pricing power and retailer shelf access, with upstream fiber securing and downstream certification partnerships serving as the critical levers.
For Market Incumbents: Deepen backward integration into municipal collection infrastructure partnerships to secure post-consumer fiber streams against feedstock fragmentation in mid-sized American markets. Expand capacity in Maharashtra and Karnataka to capture India municipal collection pilot demand before specification standards crystallize. For New Entrants and Emerging Players: Enter via digital watermark integration for flexible packaging sortation, targeting materials recovery facilities previously limited to rigid container processing. White-space concentrates in pharmaceutical blister pack conversion away from PVC-aluminum laminates under EU Green Deal pressure. For Investors and Strategic Acquirers: FDA food-contact notification clearance for novel barrier coatings is the leading indicator that mono-material formats will achieve shelf-stable food penetration at premium pricing tiers. Acquisition targets should display integrated pulp-to-pack recycling loops or documented post-consumer resin offtake agreements with municipal collectors. Long-term viability hinges on certification capacity expansion outpacing auditor backlog constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Capacity Expansion | Captive fiber supply secures retailer scorecard qualification ahead of EU Green Deal enforcement. |
| Digital Watermark Technology Deployment | AI-powered optical sorter integration unlocks flexible packaging recovery previously rejected at materials recovery facilities. |
| PFAS-Free Barrier Coating Certification | REACH compliance ahead of 2025 deadlines preserves quick-service restaurant chain supply relationships. |
| India Municipal Collection Partnership | Pilot source-segregated dry waste streams in Maharashtra create first-mover specification influence. |
| Third-Party Curbside Compatibility Audit | Verified claims satisfy mass-market grocery chain procurement requirements in Germany and France. |
Study Parameters
Independent corroboration across converter procurement directors, materials recovery facility operations managers, brand owner sustainability leads, and retailer private-label buyers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from EPA national recycling strategy documents, EU Green Deal implementation guidance, FDA food-contact notification databases, and municipal collection infrastructure audits. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Comparable-period anchoring to historical post-consumer resin pricing cycles and certification program adoption curves shaped the projection horizon. The analytical framework models material type, product format, application barrier requirements, and end-user procurement authority across the forecast period. CAGRs derive from segment-level volume build-ups calibrated to extended producer responsibility framework implementation timelines and e-commerce parcel growth trajectories. Bio-based plastics expansion rates and optical sorter technology penetration serve as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under materials recovery facility contamination tolerance revisions or state-level labeling standard fragmentation. Forecasts reflect assumptions regarding EU Green Deal enforcement consistency and FDA review timeline stability. A model refresh is warranted upon material change in retailer recyclability scorecard requirements or municipal collection infrastructure funding allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Reusable Food Wrap Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market