
 Reusable Water Bottle Market | 2026-2036
Reusable Water Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Water Bottle Market Analysis
Chinese stainless steel manufacturing is consolidating around export-oriented fabrication hubs that supply global bottle brands. SIGG Switzerland AG leverages its alpine heritage and precision engineering to sustain premium positioning across European specialty retail. Hydro Flask anchors the North American insulated segment through colorway innovation and direct-to-consumer channel control. CamelBak Products LLC competes in the outdoor performance niche with integrated hydration systems that extend beyond standalone bottles.
A reusable water bottle is a portable, refillable vessel engineered from food-grade materials—typically 18/8 stainless steel, borosilicate glass, BPA-free Tritan copolyester, or anodized aluminum—with capacities ranging from 12 to 64 ounces and thermal retention achieved through double-wall vacuum insulation. Its primary commercial purpose is to replace single-use plastic containers in daily hydration routines, reducing per-consumer waste generation while enabling temperature-stable beverage transport. Stainless steel dominates value contribution due to durability premiums and vacuum insulation performance, while collapsible silicone designs represent the fastest-growing design type among ultralight travelers and space-constrained commuters. The sports design type remains mature with stable margin pools anchored by institutional athletic contracts, whereas wide-mouth cap configurations capture disproportionate aftermarket accessory revenue.
The EU Single-Use Plastics Directive and FDA food-contact substance regulations jointly shape material compliance burdens, with REACH chemical restrictions further narrowing acceptable polymer formulations for European import. The EU F-Gas Regulation indirectly pressures insulated bottle producers by tightening foam-blowing agent standards for manufacturing equipment. California's SB 54 extended producer responsibility law creates state-level packaging reduction mandates that cascade into retailer procurement requirements. Stakeholders must monitor evolving extended producer responsibility frameworks and thermal performance certification standards to anticipate compliance-driven product redesign cycles.
Market Dynamics
Material substitution pressure from the EU Single-Use Plastics Directive is compressing demand for polymer bottles while amplifying stainless steel and glass fabrication capacity. This regulatory pivot forces manufacturers to requalify supply chains and absorb higher input costs.
Growth Catalysts
- Corporate Wellness Mandates:Large employers in Germany and the United States now subsidize reusable bottle purchases as part of hydration-focused employee health programs.
- REACH Chemical Restrictions:ECHA's tightening polymer safety standards block low-grade plastic imports, creating protected market space for certified stainless steel and borosilicate glass alternatives.
- Municipal Refill Infrastructure:Berlin and Vienna have deployed dense networks of public drinking fountains that normalize carrying empty vessels and accelerate replacement cycles.
Market Restraints
- Nickel Price Volatility:18/8 stainless steel input costs fluctuate with London Metal Exchange nickel futures, squeezing margin stability for vacuum-insulated producers.
- Zhejiang Supply Concentration:Over 60% of global stainless steel bottle fabrication clusters in Yiwu and Yongkang, creating single-point-of-failure risk for brands without dual-source strategies.
- EU F-Gas Regulation:Tightened foam-blowing agent standards for insulation equipment raise capital requirements for vacuum-seal manufacturing lines.
Strategic Opportunities
- India Urban Transit:Metro rail expansion in Mumbai and Delhi creates captive commuter populations underserved by quality hydration retail.
- Smart Bottle Convergence:Integration of hydration-tracking sensors with mobile health apps opens premium pricing tiers for fitness-integrated vessels.
- California SB 54 Procurement Mandates:Extended producer responsibility laws force retailers to prioritize reusable packaging suppliers in state-level purchasing.
Industry Challenges
- Vacuum-Seal Technician Scarcity:Double-wall insulation fabrication requires specialized welding expertise that outpaces vocational training output in manufacturing hubs.
- Multi-Jurisdiction Certification Lag:Simultaneous FDA food-contact, REACH chemical, and ISO thermal retention approvals extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Water Bottle Market |
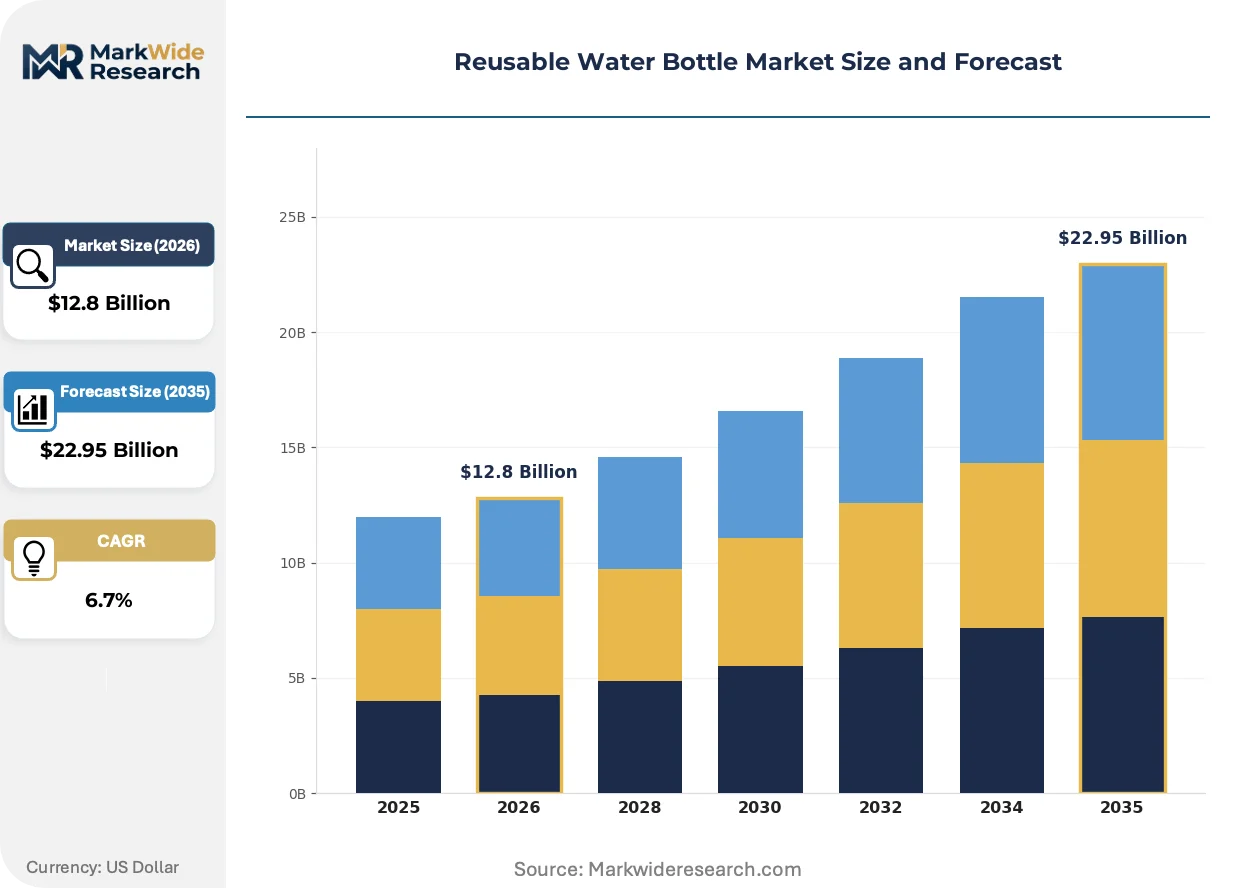
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Glass, Plastic, Aluminum Design Type: Collapsible, Insulated, Sports, Classic Cap Type: Screw Top, Flip Top, Straw Lid, Wide Mouth Target Audience: Outdoor Enthusiasts, Students, Office Workers, Athletes |
| Companies Covered | SIGG Switzerland AG, CamelBak Products LLC, Hydro Flask, Contigo, Nalgene, Stanley, Thermos LLC, YETI, Klean Kanteen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Water Bottle Market Emerging Trajectories
Product architecture is fragmenting into interchangeable subsystems that let users customize capacity, mouthpiece geometry, and carrying hardware without replacing entire vessels. This shift rewards component-standardized ecosystems over monolithic designs.
Modular bottle architecture is modularizing around threaded midsections that separate base chambers from neck assemblies. Outdoor enthusiasts and urban commuters adopt these systems fastest, swapping filtration modules or insulation sleeves as conditions demand. The approach compresses replacement frequency while expanding aftermarket accessory revenue pools.
The EU F-Gas Regulation is tightening manufacturing equipment standards for foam-blowing agents used in vacuum insulation production. European fabricators must retool production lines or relocate capacity to jurisdictions with looser environmental equipment rules. Insulated bottle categories face 12-18 month compliance windows that favor larger capitalized producers.
Subscription-based hydration services are displacing single-transaction retail in North American corporate channels. Employers contract directly with bottle brands for annual replenishment programs, bypassing traditional sporting goods distributors. This model concentrates most visibly in technology sector campuses where sustainability procurement officers control vendor selection.
Reusable Water Bottle Market Segmentation
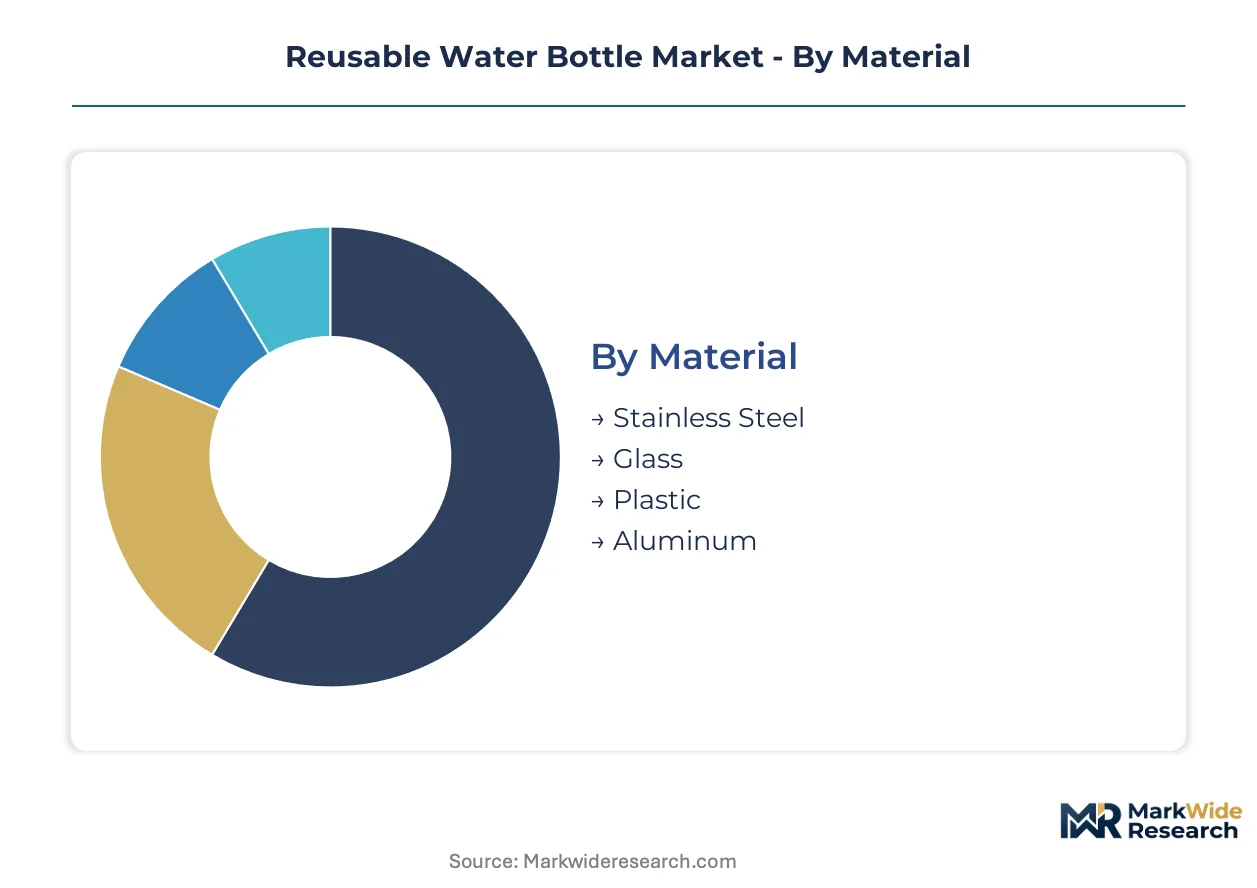
Material composition determines thermal performance, regulatory compliance burden, and replacement cycle economics. Design architecture shapes use-case portability and aftermarket accessory revenue. Cap geometry and target audience alignment complete the commercial positioning matrix for manufacturers competing across premium and mass-market tiers.
Material:
Stainless steel commands premium shelf space while glass and aluminum fragment the mid-market; plastic faces regulatory compression across European import channels.
- Stainless Steel:Double-wall 18/8 construction with vacuum insulation delivers 12-24 hour temperature retention for hot and cold beverages. Demand concentrates in Germany and the United States where corporate wellness subsidies offset higher unit costs and REACH-compliant sourcing requirements filter out lower-grade competitors.
- Glass:Borosilicate formulations resist thermal shock and eliminate metallic taste transfer for flavor-pure hydration. Adoption accelerates among office workers in Berlin and Vienna municipal refill networks where breakage risk is offset by infrastructure density and strict packaging laws normalize higher replacement frequency.
- Plastic:BPA-free Tritan copolyester offers lightweight portability at entry price points. FDA food-contact certification remains achievable but ECHA polymer restrictions narrow European market access.
- Aluminum:Anodized single-wall construction serves cycling and climbing enthusiasts requiring sub-200-gram vessel weights. Niche positioning limits volume but sustains margin through specialty outdoor retail.
Today's leader: Stainless Steel. Tomorrow's challenger: Glass.
Design Type:
Insulated and sports configurations anchor established revenue pools while collapsible formats capture emerging commuter and travel segments.
- Collapsible:Food-grade silicone bodies compress to 20% of expanded volume for space-constrained transit. Ultralight travelers and Mumbai metro commuters adopt fastest where bag capacity is strictly limited.
- Insulated:Double-wall vacuum architecture maintains beverage temperature across extended durations. Institutional athletic contracts and North American direct-to-consumer channels sustain stable margin pools.
- Sports:Ergonomic grip geometry and one-handed operation optimize high-intensity hydration. Mature demand from team sports and fitness facilities limits growth velocity.
- Classic:Cylindrical single-wall construction prioritizes cost efficiency and universal compatibility with cup holders and backpack pockets. Volume concentration in educational procurement and bulk corporate gifting.
Collapsible designs are expanding most quickly among space-constrained urban commuters.
Cap Type:
Screw top and wide mouth configurations dominate replacement part economics while straw lid and flip top innovations target specific activity profiles.
- Screw Top:Threaded polypropylene or stainless steel closures create leak-proof seals for bag transport. Standardization across bottle diameters enables cross-brand compatibility and reduces inventory complexity for retailers.
- Flip Top:Hinged snap mechanisms permit single-handed drinking during cycling or driving. Seal degradation over repeated use accelerates aftermarket replacement demand.
- Straw Lid:Integrated silicone or Tritan sipping tubes reduce spill risk for children and mobile professionals. Cleaning complexity limits institutional adoption.
- Wide Mouth:63mm+ apertures accommodate ice cubes, filtration modules, and direct drinking. Disproportionate aftermarket accessory revenue from interchangeable lids and protective boots.
Wide mouth variants capture the steepest expansion trajectory in modular ecosystem strategies.
Target Audience:
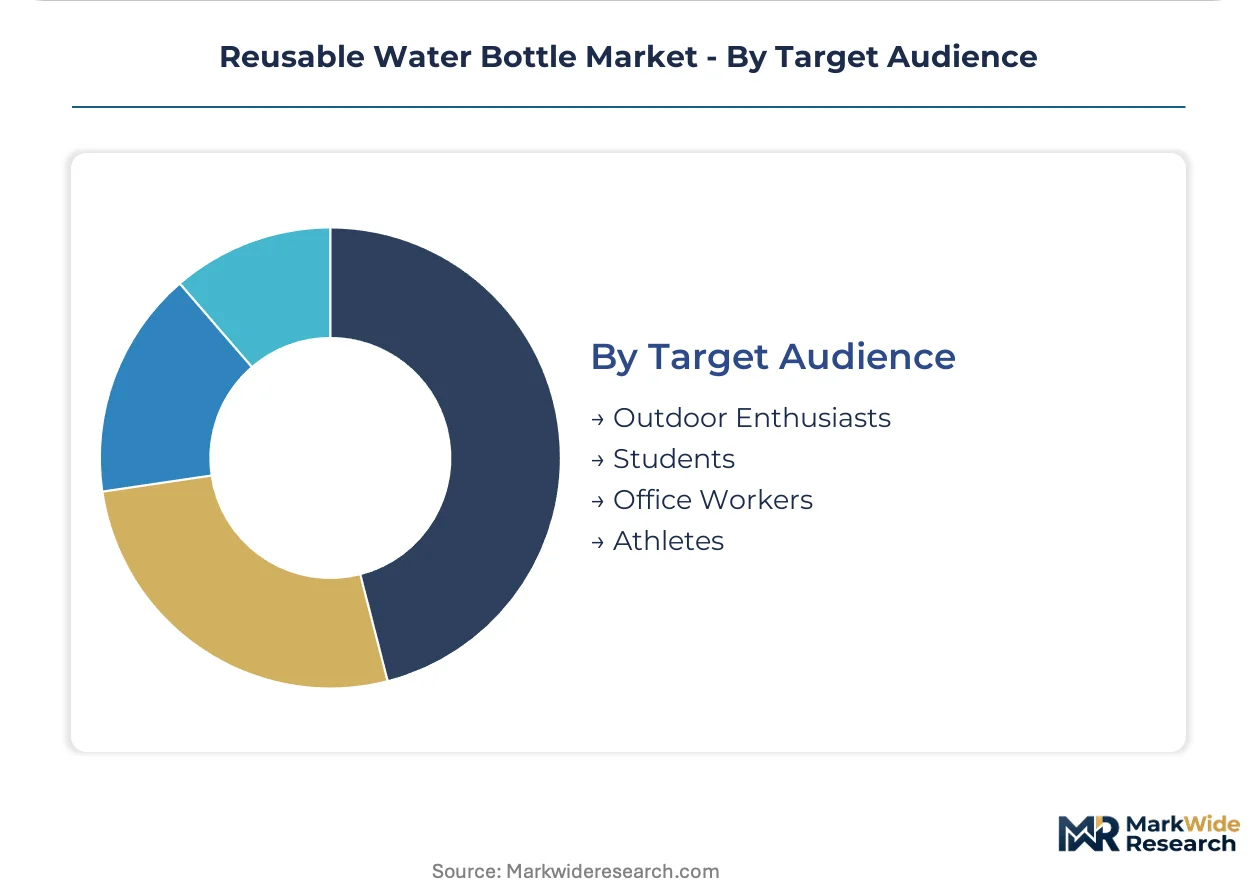
Outdoor enthusiasts and athletes sustain premium pricing tolerance while students and office workers drive volume through institutional procurement channels.
- Outdoor Enthusiasts:Durability specifications and integrated filtration compatibility command price premiums. SIGG Switzerland AG and CamelBak Products LLC anchor positioning through alpine heritage and hydration system integration.
- Students:Cost-sensitive volume demand concentrated in back-to-school retail cycles and campus bookstore procurement. Colorway personalization drives selection criteria.
- Office Workers:Corporate wellness program subsidies in German and US technology campuses normalize desk-side hydration infrastructure. Hydro Flask color innovation sustains brand loyalty.
- Athletes:Team sports contracts and gym chain partnerships create institutional volume with compressed margins. Performance metrics and squeeze-bottle compatibility outweigh thermal retention.
Office workers represent the fastest-climbing demand segment through employer-funded wellness mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between REACH-compliant European fabrication and cost-optimized Asian supply chains is redistributing production capacity across jurisdictions with divergent environmental equipment standards and chemical safety mandates.
United States
Corporate wellness subsidies and California SB 54 procurement mandates drive institutional volume. FDA food-contact substance regulations govern polymer formulations for domestic brands. Manufacturing concentrates in Pacific Northwest fabrication clusters serving direct-to-consumer insulated bottle channels.
Germany
Municipal refill station networks in Berlin and Vienna normalize daily vessel carrying and accelerate replacement cycles. EU Single-Use Plastics Directive and ECHA REACH restrictions block low-grade polymer imports. Stainless steel fabrication clusters in North Rhine-Westphalia supply vacuum-insulated bottles across the European Union.
China
Zhejiang Province fabrication hubs in Yiwu and Yongkang process over sixty percent of global stainless steel bottle output. MIIT industrial standards and dual carbon goals pressure equipment retooling for export-oriented producers. Yangtze River Delta manufacturing bases supply vacuum-seal welding expertise for international brand contracts.
India
Metro rail expansion in Mumbai and Delhi creates captive commuter populations with space-constrained transit needs. BIS certification requirements and FSSAI food-contact standards regulate domestic polymer and metal vessel sales. Gujarat fabrication clusters serve price-sensitive educational procurement channels with aluminum and plastic alternatives.
Switzerland
Alpine heritage positioning sustains premium pricing tolerance for precision-engineered vessels across European specialty retail. Swissmedic-equivalent material safety protocols exceed baseline EU requirements. Zurich-based design houses influence modular bottle architecture trends adopted by German and Austrian brands.
Reusable Water Bottle Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue collapsible silicone and smart-sensor adjacent spaces. The vendor base stratifies around three capability clusters: precision-engineered alpine heritage specialists, North American direct-to-consumer insulated brands, and scale-driven Asian fabricators serving private-label retail. Competitive positioning hardens through M&A consolidation of European distribution networks and capacity expansion in REACH-compliant manufacturing jurisdictions.
Within the alpine heritage tier, SIGG Switzerland AG exemplifies precision-engineered positioning sustained across European specialty retail channels. Among North American insulated specialists, Hydro Flask anchors direct-to-consumer channel control through colorway innovation. At the integrated hydration systems end, CamelBak Products LLC occupies the outdoor performance niche extending beyond standalone vessels into modular equipment ecosystems.
| Leading Market Players |
|---|
| SIGG Switzerland AG |
| CamelBak Products LLC |
| Hydro Flask |
| Contigo |
| Nalgene |
| Stanley |
| Thermos LLC |
| YETI |
| Klean Kanteen |
| Others |
Supply Flow & Price Mechanics
Vacuum-seal welding expertise in Yangtze River Delta fabrication clusters anchors labor-cost differentials that separate premium insulated tiers from commoditized single-wall alternatives. REACH-compliant European sourcing commands 40-60% manufacturing cost premiums over Zhejiang export hubs, compressing mid-market margin pools.
Pricing Analysis
Distributor margin stacking from Asian fabrication through European specialty retail sustains three-tier pricing structure across premium, standard, and economy levels. Premium tiers absorb stainless steel input volatility through vacuum insulation performance certification and colorway exclusivity, while standard tiers compete on BPA-free Tritan copolyester volume scale. Cost compression in economy plastic segments is intensifying because ECHA polymer restrictions block low-grade imports, forcing price-sensitive buyers toward aluminum alternatives.
Supply Chain Analysis
Dual-sourcing requirements from North American direct-to-consumer brands now mandate qualification of secondary fabrication capacity outside Zhejiang Province. Global stainless steel bottle output draws from China, India, and Vietnam, with nickel cathode and 18/8 steel coil as critical inputs. Single-source vulnerability concentrates in Yiwu and Yongkang welding equipment clusters, while distribution runs through sporting goods distributors, corporate procurement channels, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable water bottle demand is shifting toward vacuum-insulated stainless steel specifications that command durability premiums and thermal performance certification. Corporate wellness mandates in German and US technology campuses normalize employer-funded hydration infrastructure.
For Market Incumbents: Acquire REACH-certified European fabrication capacity to defend against regulatory arbitrage from emerging Asian competitors. Hydro Flask and SIGG Switzerland AG should deepen backward integration into vacuum-seal welding equipment to offset technician scarcity in Yangtze River Delta clusters. Capacity addition in North Rhine-Westphalia fabrication hubs protects EU market access against F-Gas Regulation compliance windows. For New Entrants and Emerging Players: Capture Mumbai and Delhi metro rail commuter segments through collapsible silicone designs that address space-constrained transit needs. Smart bottle convergence with hydration-tracking sensors offers the most penetrable premium tier for fitness-integrated vessels. Direct-to-employer subscription models bypass traditional sporting goods distributor margin stacking. For Investors and Strategic Acquirers: Private equity firms with consumer goods portfolios are the most active acquirer in this space, targeting modular architecture specialists with component-standardized ecosystems. Long-term viability hinges on replacement cycle economics from municipal refill infrastructure expansion. Watch ECHA polymer restriction enforcement intensity as the inflection indicator for stainless steel demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum-Seal Welding | Yangtze River Delta technician scarcity makes captive welding capacity a margin defense mechanism for insulated bottle producers. |
| REACH-Compliant European Capacity Expansion | North Rhine-Westphalia fabrication clusters protect EU market access against F-Gas Regulation equipment retooling mandates. |
| Direct-to-Employer Subscription Launch | Technology sector sustainability procurement officers bypass sporting goods distributors through annual replenishment contracts. |
| Modular Architecture Ecosystem Development | Threaded midsection standardization expands aftermarket accessory revenue pools for outdoor enthusiasts and urban commuters. |
| Smart Sensor Integration Partnership | Hydration-tracking mobile app convergence opens premium pricing tiers for fitness-integrated vessel categories. |
Methodological Framework
Coverage spans Germany, the United States, China, India, and Switzerland, with primary inputs from each market cluster. Primary interviews with brand managers at stainless steel fabricators, category buyers at European specialty retailers, sustainability procurement officers at technology sector employers, and supply planners at Zhejiang export hubs combined with secondary validation from EU Single-Use Plastics Directive implementation filings, ECHA REACH restriction updates, and customs trade data. Bottom-up channel volume estimates and top-down macroeconomic absorption models were triangulated for convergence.
Granularity-level modeling captured material composition, design architecture, cap geometry, and target audience alignment across the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by thermal performance certification tiers and replacement cycle economics. Forecast inputs included municipal refill infrastructure deployment timelines, corporate wellness program subsidy expansion rates, and nickel futures price volatility assumptions.
EU F-Gas Regulation enforcement intensity, nickel price volatility spikes, and REACH polymer restriction scope expansion are the dominant revision risks to modeled outputs. Deviation in municipal refill station network density would shift replacement cycle assumptions and volume outlooks materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Greenwrap Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Reusable Food Wrap Market