
 Re-Sealable Packaging Bags Market | 2026-2036
Re-Sealable Packaging Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Re-Sealable Packaging Bags Market Analytics
The capital-intensity gap between integrated film producers and standalone converters is collapsing as resin volatility and equipment automation costs compress margins across the value chain. Amcor Plc leverages its global extrusion footprint to secure polyethylene supply chains ahead of seasonal demand spikes. Berry Global Inc. anchors North American volume through proprietary zipper-applicator lines that reduce changeover times for mid-size food brands. Mondi competes in European sustainable packaging tenders with kraft-paper barrier laminates that replace multi-layer plastic constructions.
Re-sealable packaging bags are flexible containers incorporating interlocking zipper profiles, adhesive strips, or press-to-seal mechanisms to enable repeated opening and closing without compromising contents; typical constructions range from 2-mil single-ply polyethylene to 7-mil nylon-reinforced laminates with oxygen transmission rates below 0.5 cc per square meter per day, serving primary functions of moisture exclusion, aroma retention, and portion control across retail and institutional channels. Stand-up pouches now dominate shelf-ready presentations in the Food & Beverage end user segment due to their vertical stability and billboard-like front-panel surface area, while biodegradable material formulations represent the fastest-growing structural category as brand owners respond to extended producer responsibility frameworks. Zip closure mechanisms command the widest installed base across automated filling equipment, though press-to-seal formats are gaining traction in pharmaceutical end user applications where child-resistance specifications apply.
FDA food-contact notification requirements govern resin additives and migration limits for U.S.-distributed re-sealable bags, while REACH and the EU Packaging and Packaging Waste Regulation shape material composition and recyclability claims across European markets. China's GB standards for plastic food packaging, administered by SAMR, mandate specific labeling and layer-disclosure rules that affect import qualification timelines for foreign converters. Stakeholders must monitor regulatory divergence between mono-material recyclability mandates and the functional barrier requirements of oxygen-sensitive applications, as this tension will determine which material platforms receive capital commitment in the next investment cycle.
Market Dynamics
Mono-material recyclability mandates from ECHA and FDA food-contact rules are forcing converters to abandon multi-layer barrier laminates, collapsing the technical moat that historically separated integrated film producers from standalone pouch converters.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility frameworks in Germany and France are mandating recyclable formats, pulling brand owners toward certified mono-material structures.
- E-commerce fulfillment standardization:Automated warehouse systems in China and the United States now specify uniform pouch footprints to optimize pick-and-pack robotics throughput.
- Oxygen-sensitive food categories:Chilled ready-meal processors in Japan and South Korea are adopting high-barrier re-sealable formats to replace rigid trays.
Market Restraints
- Resin price volatility:Polyethylene and polypropylene feedstock costs swing with crude oil indices, compressing converter margins during contract renegotiations with retail chains.
- Barrier performance trade-offs:Mono-material polyethylene structures cannot match the oxygen transmission rates of nylon-reinforced laminates, limiting adoption in ambient shelf-stable categories.
- Equipment lock-in:Zipper-applicator lines from dominant machinery suppliers require proprietary profile geometries, raising switching costs for mid-size converters.
Strategic Opportunities
- Pharmaceutical child-resistance specifications:Press-to-seal mechanisms compliant with FDA pediatric testing protocols open a premium segment beyond food applications.
- India organized retail expansion:Reliance Retail and DMart are standardizing private-label pouch specifications, creating volume anchors for converters establishing local extrusion capacity.
- Paper-plastic hybrid structures:Kraft-paper barrier laminates with heat-sealable coatings qualify for fiber recycling streams in EU circular-economy tenders.
Industry Challenges
- Migration testing complexity:FDA food-contact notification timelines for novel adhesive formulations stretch 12-18 months, delaying product launches.
- Automation skill scarcity:Servo-driven pouch-making equipment requires mechatronics technicians that converter workforces in Eastern Europe and Southeast Asia lack.
- Legacy filling line incompatibility:Stand-up pouch formats demand modified form-fill-seal machines that institutional foodservice operators resist replacing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Re-Sealable Packaging Bags Market |
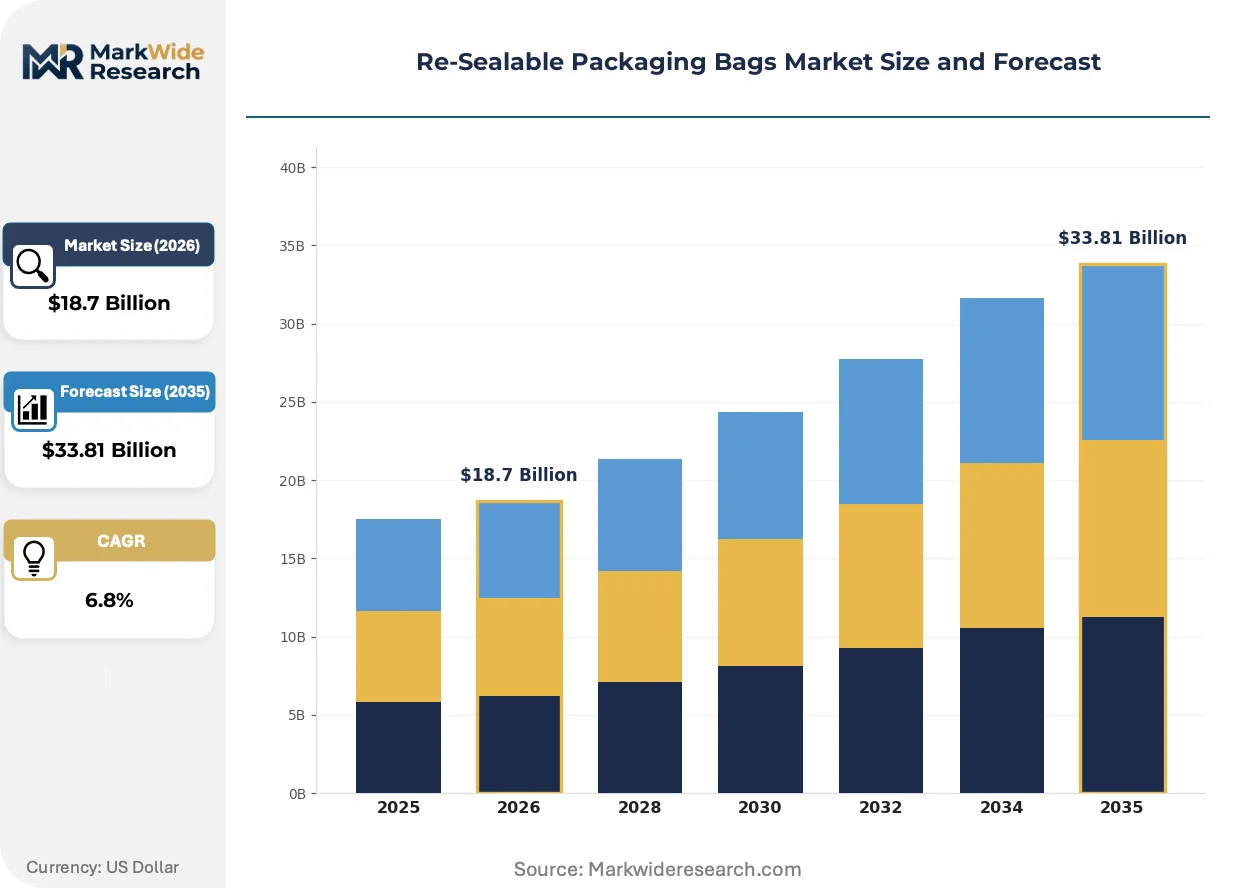
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Bags, Gusseted Bags, Zipper Bags Material: Plastic, Paper, Aluminum Foil, Biodegradable End User: Food & Beverage, Household, Personal Care, Pharmaceutical Closure Type: Zip Closure, Adhesive Seal, Press-to-Seal, Others |
| Companies Covered | Amcor Plc, Berry Global Inc., Sealed Air Corporation, Constantia Flexibles, Mondi, ProAmpac, Sonoco Products Company, Glenroy, Zip-Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Re-Sealable Packaging Bags Market Evolving Landscape
Material science breakthroughs and regulatory compliance automation are compressing development cycles for next-generation barrier structures. Converters now compete on certification speed as much as unit economics.
Digital printing with water-based inks is fragmenting the traditional rotogravure-dominated flexible packaging supply chain. Mid-size food brands in Germany and the Netherlands are adopting short-run customized pouch designs for seasonal SKUs. This technology is fragmenting volume concentration among large integrated converters by enabling regional players to serve national brand portfolios without cylinder inventory costs.
REACH SVHC disclosure requirements are tightening supply chain documentation burdens for any converter selling into EU member states. Substances of very high concern in slip agents and anti-static coatings now trigger mandatory downstream communication through the SCIP database. Food-contact laminators with Asian resin sourcing are most affected, accelerating migration to ECHA-registered additive packages.
Direct-to-consumer subscription models are reshaping primary packaging specifications for specialty food brands. Monthly delivery services in the United States and United Kingdom now specify puncture-resistant mailer-compatible pouches with tear-notches rather than retail shelf-ready formats. This shift is most visible in premium pet food and specialty coffee verticals where brand owners control last-mile presentation.
Re-Sealable Packaging Bags Market Segmentation
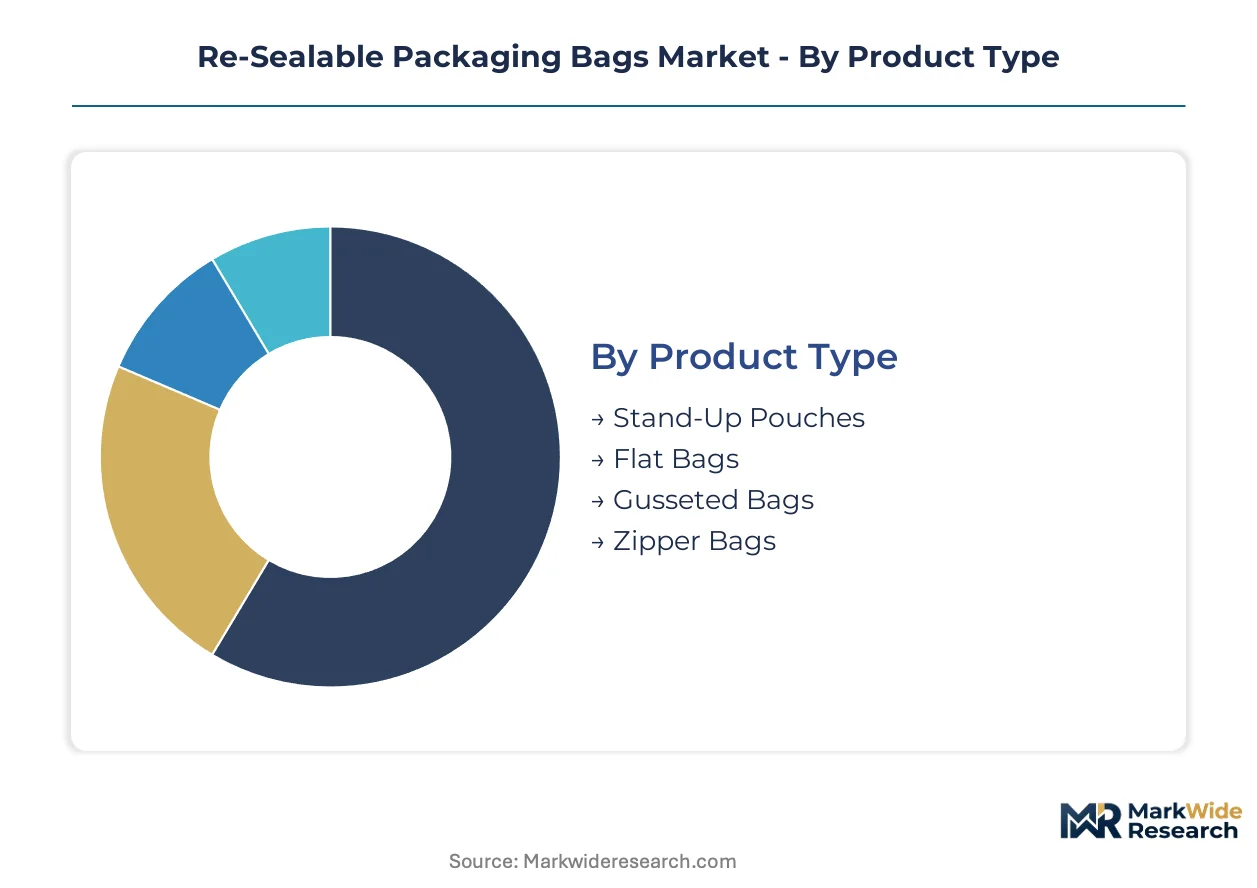
Segmentation in re-sealable packaging bags determines converter capital allocation and regulatory compliance pathways. Material composition and closure mechanisms dictate recycling stream qualification and automated filling line compatibility across end-use verticals.
Product Type:
Regulatory differentiation across EU member states favors formats that qualify for existing recycling infrastructure without format-specific exemptions.
- Stand-Up Pouches:Vertical stability and billboard front-panel surface area dominate shelf-ready presentations. Chilled ready-meal processors in Japan and South Korea specify these formats to replace rigid trays under extended producer responsibility frameworks.
- Flat Bags:Two-dimensional construction minimizes material usage for ambient dry goods. E-commerce fulfillment standardization in China and the United States specifies uniform flat footprints to optimize automated pick-and-pack robotics throughput.
- Gusseted Bags:Side-folded expansion panels accommodate bulk dry goods with minimal headspace. Coffee roasters and specialty grain distributors specify these for club-store multipacks.
- Zipper Bags:Interlocking profile mechanisms enable repeated access without compromising barrier integrity. Pharmaceutical compounders favor these for API storage under USP <661> container qualification protocols.
Established volume favors Stand-Up Pouches; emerging adoption favors Flat Bags.
Material:
Cost tier differentiation separates commodity converters from specialty laminators serving oxygen-sensitive applications.
- Plastic:Polyethylene and polypropylene structures dominate unit economics through in-house extrusion. Mono-material polyethylene cannot match nylon-reinforced laminates for oxygen transmission rates, limiting ambient shelf-stable category penetration.
- Biodegradable:PLA and starch-based formulations respond to extended producer responsibility mandates in Germany and France. Brand owners seeking EU circular-economy tender qualification specify these despite 15-30% unit cost premiums over conventional structures.
- Paper:Kraft-paper barrier laminates with heat-sealable coatings qualify for fiber recycling streams. Mondi and similar European converters compete on these structures in sustainable packaging tenders.
- Aluminum Foil:Metallized layers provide oxygen transmission rates below 0.5 cc per square meter per day. Premium coffee and pharmaceutical desiccant applications specify these despite incompatibility with mechanical recycling streams.
Plastic retains dominant share; biodegradable formulations are climbing the fastest.
End User:
Application-specific barrier requirements determine margin structure and certification burden across converter customer portfolios.
- Food & Beverage:Extended shelf-life specifications drive specification of high-barrier laminates with oxygen scavenging layers. Ambient and chilled category processors now mandate re-sealable formats as default primary packaging.
- Pharmaceutical:FDA pediatric testing protocols for child-resistance govern press-to-seal mechanism adoption. USP <661> and <671> container qualification timelines stretch 12-18 months for novel adhesive formulations.
- Household:Detergent pod and cleaning wipe applications prioritize puncture resistance over oxygen barrier. Private-label concentration in mass retail channels drives price compression.
- Personal Care:Cosmetic and hygiene product specifications emphasize aesthetic surface finish and fragrance retention. Short-run digital printing adoption is highest in this segment for seasonal SKU customization.
Food & Beverage anchors volume concentration; pharmaceutical offers steepest expansion trajectory.
Closure Type:
Customer type differentiation separates industrial procurement from retail brand owner specifications.
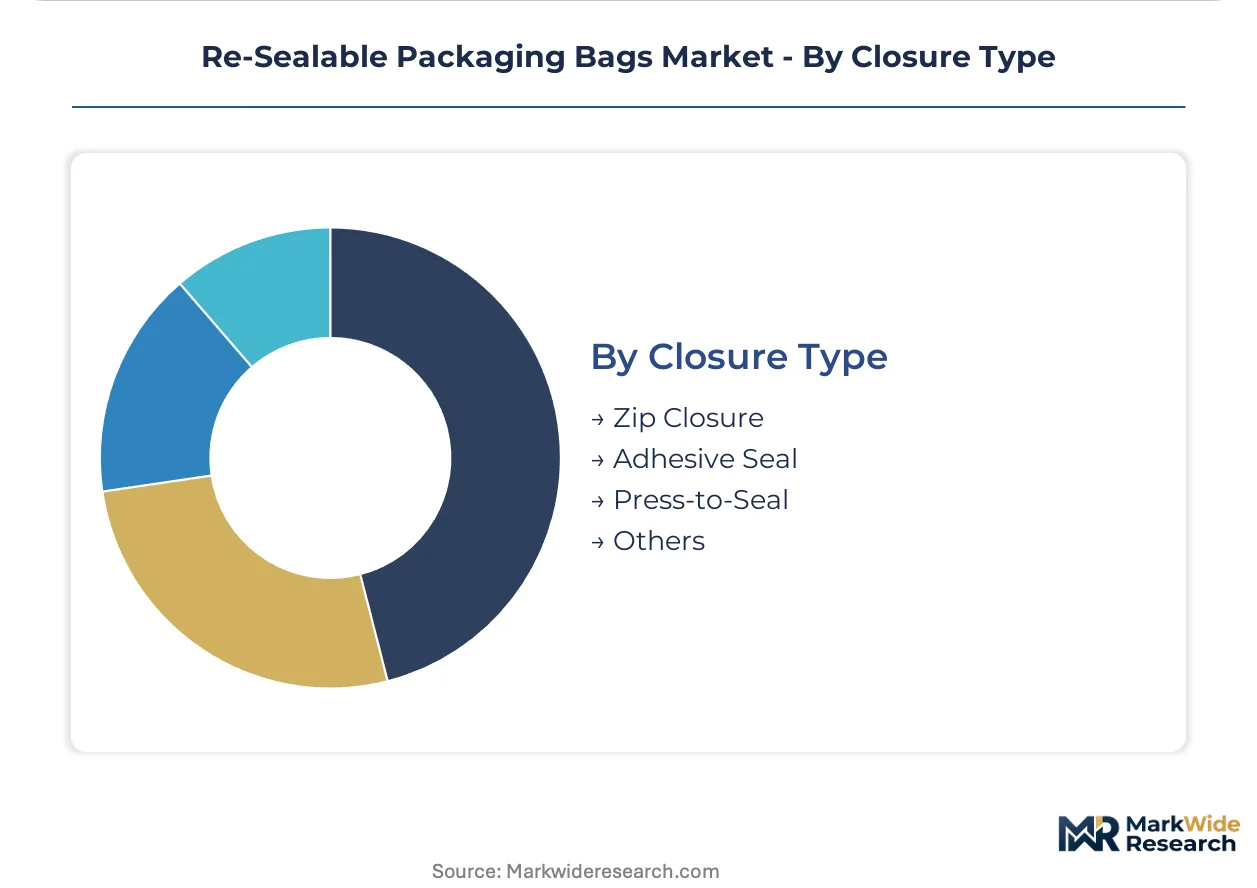
- Zip Closure:Interlocking profile geometries command the widest installed base across automated filling equipment. Proprietary applicator lines from dominant machinery suppliers raise switching costs for mid-size converters.
- Press-to-Seal:Child-resistant mechanisms compliant with FDA pediatric testing protocols open premium segments beyond food applications. Pharmaceutical end users specify these for OTC and prescription compliance packaging.
- Adhesive Seal:Pressure-sensitive strips enable single-use security indication. Direct-to-consumer subscription services in specialty coffee and pet food specify tear-notch variants for mailer compatibility.
- Others:Slider mechanisms and tamper-evident tear strips serve niche institutional and security applications. Correctional facility and forensic specimen packaging specify these for chain-of-custody verification.
Zip Closure dominates installed equipment; press-to-seal gains share fastest in regulated applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in re-sealable packaging machinery and barrier films, while China and the United States absorb the bulk of global pouch imports to serve e-commerce fulfillment networks and food processing clusters.
United States
FDA food-contact notification requirements govern resin additives and migration limits for distributed re-sealable bags. The agency's evolving rules on recyclable mono-material structures redirect converter investment away from multi-layer laminates. Chicago and Milwaukee anchor North American flexible packaging manufacturing, with automated filling equipment suppliers clustering near Midwestern food processing corridors.
Germany
REACH compliance and the EU Packaging and Packaging Waste Regulation mandate recyclable formats, pulling brand owners toward certified mono-material structures. Extended producer responsibility frameworks in France and Germany accelerate tender qualification requirements for circular-economy packaging. The Rhine-Ruhr industrial belt concentrates extrusion capacity and zipper-applicator machinery production serving pan-European distribution.
China
GB standards for plastic food packaging administered by SAMR mandate specific labeling and layer-disclosure rules affecting import qualification timelines. E-commerce fulfillment standardization specifies uniform pouch footprints to optimize pick-and-pack robotics throughput in automated warehouse systems. The Yangtze River Delta and Pearl River Delta regions host the densest concentrations of pouch converters serving domestic retail and export markets.
India
Reliance Retail and DMart standardize private-label pouch specifications, creating volume anchors for converters establishing local extrusion capacity. FSSAI food-contact material regulations govern plastic additive approvals and migration testing protocols for domestic distribution. Maharashtra and Gujarat lead organized retail expansion, with Mumbai-Pune and Ahmedabad-Vadodara corridors attracting regional converter investment.
Japan
Chilled ready-meal processors adopt high-barrier re-sealable formats to replace rigid trays under extended producer responsibility frameworks. METI circular-economy roadmaps pressure converters toward mono-material recyclability without sacrificing oxygen barrier performance. The Kanto region around Tokyo concentrates food processing innovation, while Osaka-Kobe anchors pharmaceutical packaging specialization serving export markets.
Re-Sealable Packaging Bags Market Competitive Landscape
Concentration sits with integrated film producers and global converters capable of securing polyethylene supply chains ahead of seasonal demand spikes. The vendor base spans three strategic tiers: multinational integrated players with captive resin supply, regional specialists in sustainable material formulations, and mid-size converters serving private-label retail chains. Competitive moves center on capacity expansion in mono-material extrusion lines and strategic partnerships with e-commerce fulfillment platforms.
Within the integrated multinational tier, Amcor Plc and Berry Global Inc. exemplify scale-driven positioning through global extrusion footprints and proprietary zipper-applicator technologies. Mondi occupies a position among European sustainable packaging specialists competing on kraft-paper barrier laminates. These three entities represent the dominant archetypes: resin-integrated volume players, machinery-integrated format innovators, and fiber-based sustainable alternatives.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Sealed Air Corporation |
| Constantia Flexibles |
| Mondi |
| ProAmpac |
| Sonoco Products Company |
| Glenroy |
| Zip-Pak |
| Others |
Value Network & Pricing Analysis
REACH SVHC disclosure requirements gate both supplier qualification timelines and price differentiation across European tender participation, compressing margins for converters reliant on Asian resin sourcing while rewarding ECHA-registered additive packages with certification premiums.
Pricing Analysis
Configured-to-order pricing for custom barrier laminates commands 25-40% premiums over standard mono-material polyethylene structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by oxygen transmission performance and recyclability certification grade. Cost compression in standard-grade pouches is intensifying because of polyethylene resin volatility and retail chain procurement consolidation. Private-label retail chains exhibit highest price sensitivity, while pharmaceutical compounders accept premium positioning for USP-compliant child-resistant formats.
Supply Chain Analysis
Inventory cycles for zipper-profile mechanisms stretch 8-12 weeks longer than base film stockpiles, constraining converter responsiveness to seasonal demand spikes. Supply concentrates in Germany for machinery production, China for resin extrusion and pouch conversion, and the United States for automated filling equipment integration. Raw material dependencies center on polyethylene and polypropylene feedstocks, nylon barrier layers, and proprietary zipper-profile resins. Single-source vulnerability sits with dominant zipper-applicator machinery suppliers whose proprietary geometries lock converters into long-term relationships. Distribution runs through regional converter networks serving food processing clusters and direct e-commerce fulfillment platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Re-sealable packaging sits in early-cycle expansion as extended producer responsibility frameworks in Germany and France mandate recyclable formats, pulling brand owners toward certified mono-material structures ahead of regulatory deadlines.
For Market Incumbents: Secure polyethylene supply chains through backward integration or long-term offtake agreements ahead of seasonal demand spikes. Add mono-material extrusion capacity in the Rhine-Ruhr corridor to serve pan-European sustainable packaging tenders. Defend against regional converter fragmentation by embedding proprietary zipper-applicator technologies that raise switching costs for mid-size food brands.
For New Entrants and Emerging Players: Differentiate on kraft-paper barrier laminates with heat-sealable coatings that qualify for EU fiber recycling streams. Target pharmaceutical press-to-seal applications where FDA pediatric testing protocols create certification barriers for commodity converters. Enter through private-label partnerships with Reliance Retail and DMart in Maharashtra and Gujarat corridors where organized retail standardization creates volume anchors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across standalone pouch conversion as equipment automation costs compress margins and collapse the technical moat separating integrated film producers. Over the projection horizon, viable acquisition targets include regional specialists with ECHA-registered additive packages and established mono-material extrusion lines. Watch for inflection in FDA food-contact notification timelines for novel adhesive formulations, as acceleration signals regulatory pathway maturation for barrier material innovation.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Capacity Expansion | Qualifies converters for EU circular-economy tenders under extended producer responsibility frameworks. |
| Proprietary Zipper-Applicator Technology Investment | Raises switching costs for mid-size food brands dependent on rapid changeover flexibility. |
| Pharmaceutical Certification Pathway Development | Opens premium segments beyond food applications through FDA pediatric testing protocol compliance. |
| Kraft-Paper Barrier Laminate Product Line | Positions Mondi and similar converters for sustainable packaging tenders requiring fiber recyclability. |
| E-Commerce Fulfillment Platform Partnership | Secures volume anchors as automated warehouse systems standardize uniform pouch footprints. |
Research Methodology
Desk research of customs and trade data, SEC filings from integrated packaging multinationals, and EU regulatory databases preceded structured interviews with converter operations managers, brand owner packaging engineers, zipper-applicator machinery suppliers, and retail procurement directors. Primary fieldwork combined with secondary validation from FDA food-contact notification records, ECHA SCIP database disclosures, and SAMR GB standard filings. Bottom-up volume estimates triangulated against top-down market sizing from trade association reports.
Variance decomposition across material composition, closure mechanism, and end-use verticals shaped the analytical framework over the projection horizon. Modeled segmentation dimensions include product type, material platform, closure technology, and geographic regulatory cluster. CAGRs derived from regression analysis of historical resin price elasticity and converter capacity utilization rates. Industry-specific forecast inputs incorporated e-commerce fulfillment standardization timelines and extended producer responsibility implementation schedules.
Material uncertainties — resin price volatility, FDA notification timeline delays, and REACH SVHC list expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory harmonization and automation adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Greenwrap Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Curbside Recyclable Packaging Market