
 Reusable Transport Packs Market | 2026-2036
Reusable Transport Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Transport Packs Market Analytics
Modular container pooling is realigning procurement patterns across food services and automotive supply chains. Schoeller Allibert leverages its European manufacturing footprint to dominate standardized foldable crate lines. Mauser Packaging Solutions anchors its position through captive supply of intermediate bulk containers for chemical and pharmaceutical sectors. Brambles competes via its global pallet and container pooling network, sustaining density advantages in grocery retail logistics.
Reusable transport packs are engineered containers designed for multiple trip cycles, typically fabricated from high-density polyethylene, aluminum, or fiberboard composites with specified load ratings and nesting ratios to maximize return-trip cube utilization. Their primary purpose is to replace single-use shipping materials while protecting goods through controlled temperature, impact resistance, or stack stability during inter-facility transit. Collapsible containers command the largest volume share within product type segments due to their return-efficiency in closed-loop retail distribution. Insulated bags represent the fastest-expanding category, capturing margin pools in healthcare cold-chain and premium meal-kit delivery where thermal performance specifications determine vendor selection.
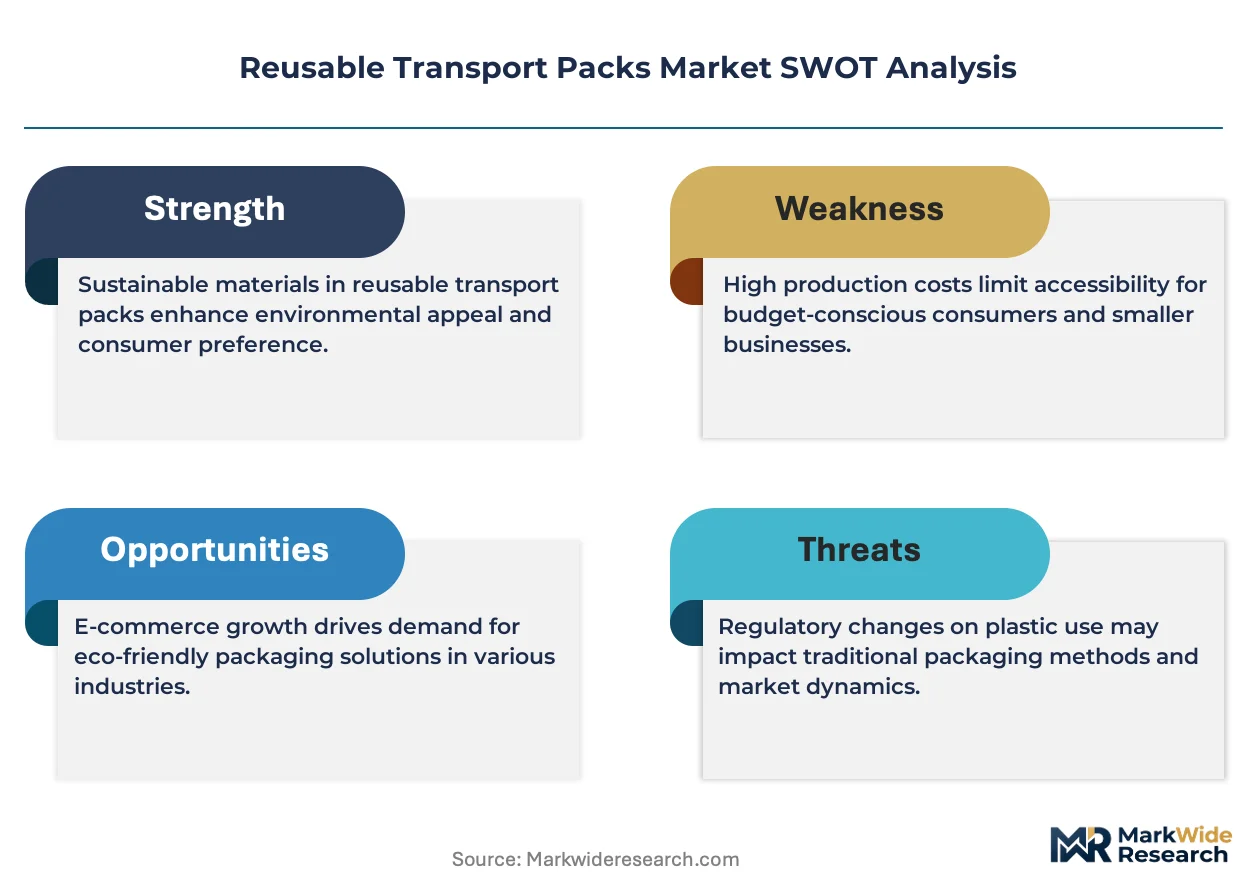
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recyclability thresholds that directly expand demand for certified reusable formats across member states. The EPA promotes waste reduction hierarchies in the United States that incentivize large distributors to shift from corrugated single-use to durable transport assets. ISO 18600 series standards govern returnable packaging performance testing, creating compliance barriers for unqualified suppliers. Stakeholders must monitor how tightening recycled-content mandates in Europe and emerging state-level packaging laws in the United States reshape total cost-of-ownership calculations for fleet investments.
Market Dynamics
EU Packaging and Packaging Waste Regulation enforcement is compressing single-use packaging lifecycles while automotive and pharmaceutical closed-loop logistics demand standardized, trackable container pools. This regulatory-industrial convergence is forcing asset-light distributors toward third-party pooling services.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates and recyclability thresholds are expanding certified reusable format procurement across Germany, France, and Netherlands food retail networks.
- Pharmaceutical cold-chain integrity requirements:Temperature-validated insulated bags are displacing expanded polystyrene in last-mile vaccine and biologics distribution, particularly in urban hospital clusters.
- Automotive just-in-sequence manufacturing:German OEMs and tier-1 suppliers are standardizing foldable large load carriers to reduce inbound packaging waste and line-side footprint at assembly plants.
Market Restraints
- HDPE resin price volatility:Feedstock cost swings directly compress container manufacturer margins and deter long-term fleet investment commitments from mid-size distributors.
- Pool operator concentration in Western Europe:Three providers control over 70 percent of standardized automotive container pools, creating bottleneck risk for new market entrants.
- RFID tracking infrastructure gaps:Real-time asset visibility remains limited in Eastern European and rural logistics corridors, reducing return-trip efficiency calculations.
Strategic Opportunities
- Poland and Czech Republic manufacturing corridors:Underdeveloped pooling infrastructure in these automotive-heavy regions offers first-mover positioning for standardized container-as-a-service models.
- Meal-kit and premium grocery delivery:Insulated bag rental programs targeting urban fulfillment centers are capturing margin pools from single-use thermal packaging in London, Paris, and Amsterdam.
- EU Green Deal public procurement incentives:Government-mandated sustainable packaging quotas in healthcare and defense logistics are creating preferential contracting windows for certified reusable suppliers.
Industry Challenges
- ISO 18600 series certification timelines:Six-to-twelve month validation cycles for new container designs delay product launches and lock capital in pre-revenue testing phases.
- Legacy ERP integration with pool management platforms:Food distributors running on-premise warehouse management systems face data synchronization failures when onboarding third-party container tracking services.
- Specialized repair technician scarcity:Insulated bag thermal liner refurbishment requires skilled labor that pool operators struggle to recruit in Eastern European service hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Transport Packs Market |
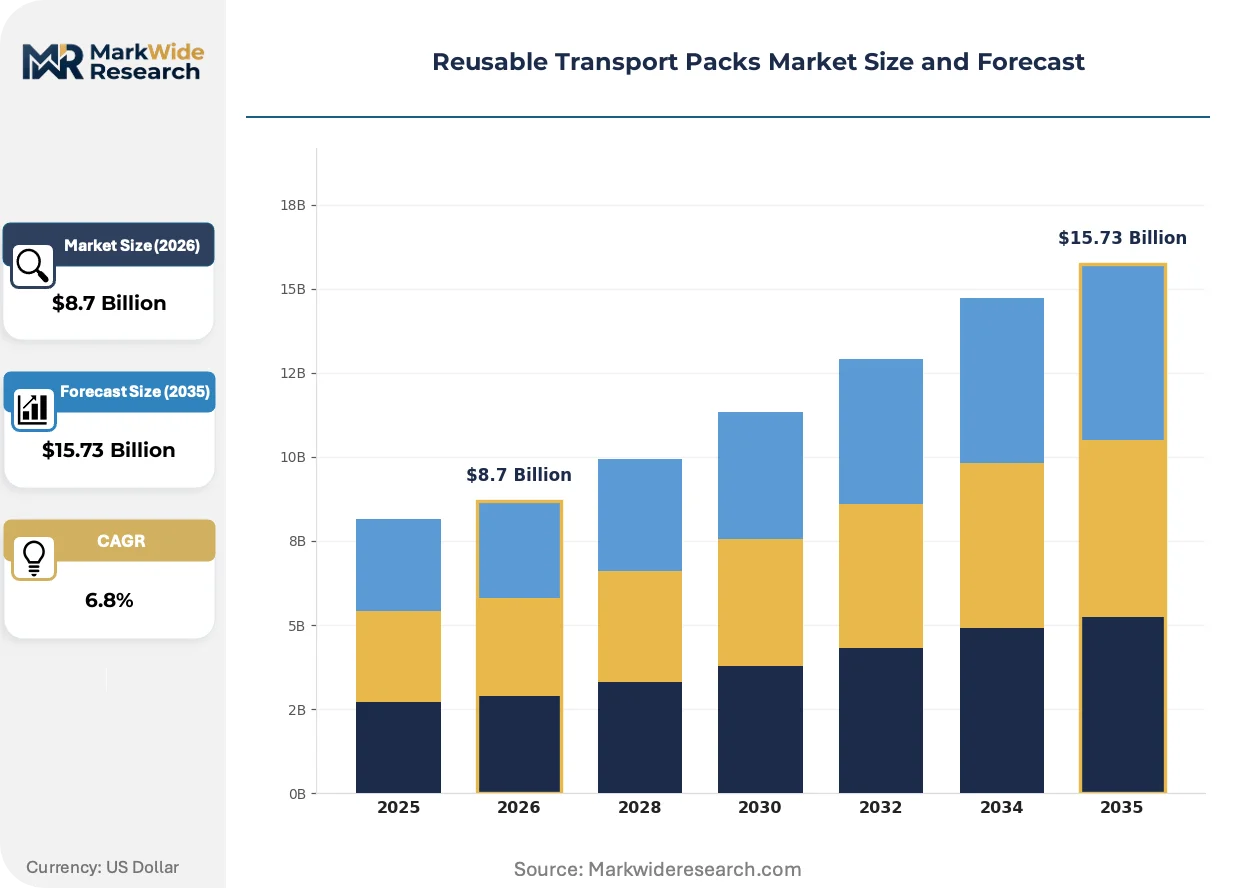
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Bags, Collapsible Containers, Cargo Pallets, Carton Boxes Material: Polyethylene, Aluminum, Fiberboard, Nylon Application: Food Services, Healthcare, Retail, Logistics End User: Restaurants, Hospitals, E-commerce, Warehouses |
| Companies Covered | Schoeller Allibert, Mauser Packaging Solutions, DS Smith, Brambles, Menasha Corporation, IFCO Systems, Polymer Logistics, Myers Industries, Greif, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Transport Packs Market Evolving Landscape
Active RFID and sensor-embedded container technologies are compressing asset recovery cycles while EU regulatory tightening accelerates format standardization. Material science advances in fiber-reinforced composites are challenging traditional HDPE dominance in heavy-load applications.
Sensor-embedded tracking modules are expanding into reusable transport packs through battery-assisted passive RFID and low-power cellular connectivity. Pharmaceutical 3PL providers in Belgium and Netherlands are deploying these units at 40 percent annual fleet penetration rates. Real-time temperature and shock monitoring is expanding into contract terms, enabling outcome-based liability allocation between shippers and pool operators.
REACH restrictions on persistent organic pollutants are tightening chemical compliance for recycled HDPE feedstocks used in container manufacturing. Compounders must now certify flame-retardant and UV-stabilizer absence in post-consumer resin streams. Automotive container producers serving Stuttgart and Munich assembly networks are responding by qualifying virgin-alternative bio-based polypropylene grades from certified European suppliers.
Asset-light procurement through pay-per-trip contracts is displacing capital purchase models among mid-size food distributors. Third-party pool operators in Germany and France are capturing these accounts with guaranteed availability clauses and reverse logistics bundling. This behavioral shift is most visible in fresh produce distribution, where seasonal volume spikes previously forced ownership of underutilized peak-capacity fleets.
Reusable Transport Packs Market Segmentation
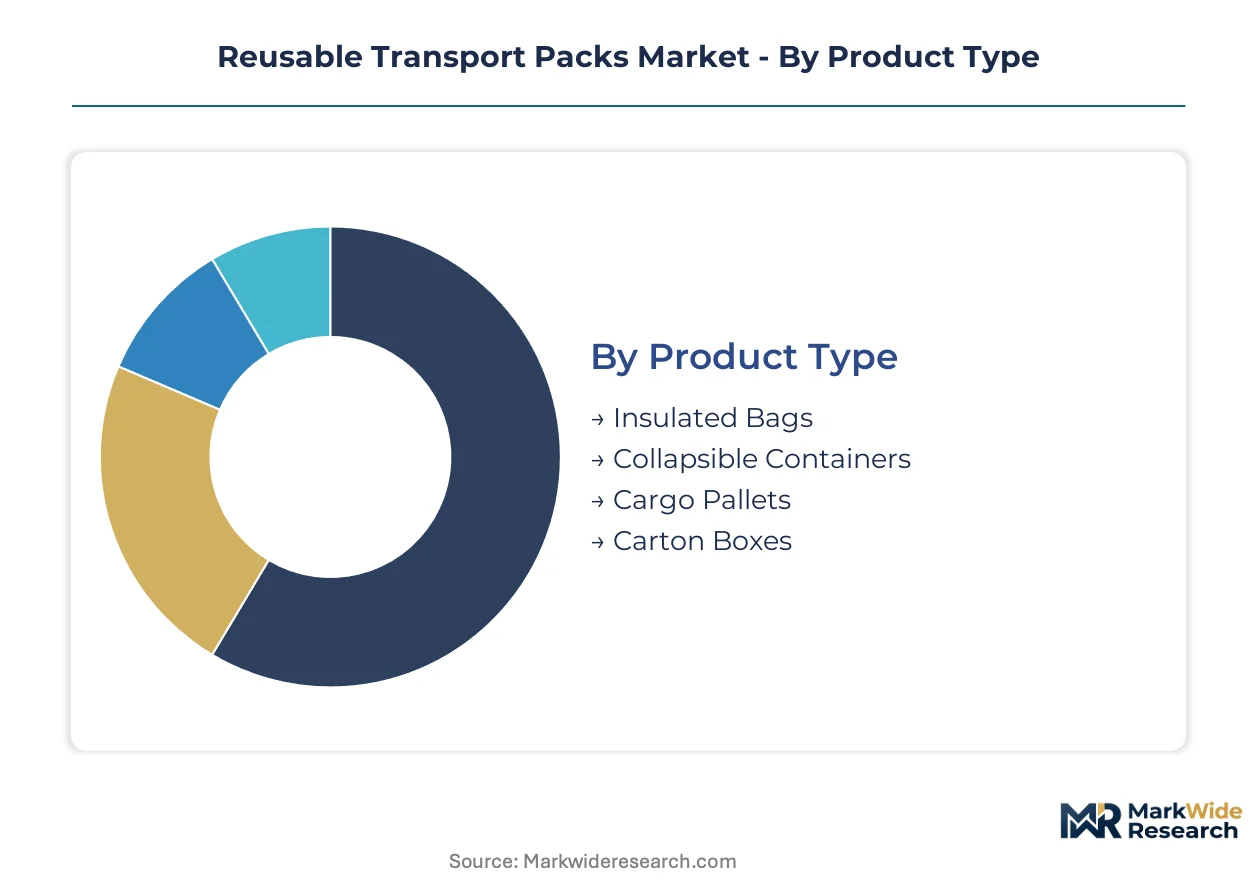
Reusable transport packs serve distinct operational requirements across temperature-controlled, space-constrained, and heavy-load scenarios. Procurement decisions hinge on nesting ratios, thermal performance specifications, and pool-operator network density rather than unit cost alone.
Product Type:
Standalone container formats dominate closed-loop logistics, while embedded thermal solutions integrate into third-party delivery infrastructure.
- Collapsible Containers:HDPE or polypropylene structures with 4:1 nesting ratios maximize cube utilization on return trips. German automotive OEMs and French hypermarket chains standardize these formats through multi-operator pool agreements to reduce inbound packaging waste.
- Insulated Bags:Multi-layer constructions with phase-change material liners maintain 2-8°C thermal bands for 4-6 hours. Demand concentrates in Netherlands and Belgium pharmaceutical 3PL networks where EMA cold-chain validation requirements determine vendor qualification.
- Cargo Pallets:Aluminum or composite deck platforms with four-way entry for forklift and pallet-jack compatibility.
- Carton Boxes:Fiberboard-composite designs with specified edge crush test ratings for multi-trip durability in produce distribution.
Volume placements concentrate in Collapsible Containers; the faster expansion belongs to Insulated Bags.
Material:
Cost tiers separate commodity resin grades from performance-engineered substrates with regulatory compliance certifications.
- Polyethylene:High-density and linear-low formulations dominate injection-molded container production. REACH restrictions on persistent organic pollutants in recycled feedstocks are forcing compounders toward virgin-alternative bio-based grades for automotive sector supply.
- Aluminum:Extruded and cast alloys provide structural rigidity for heavy-load pallets and thermal conductivity for cold-plate integration. Premium pricing reflects energy-intensive production and scrap recovery value retention.
- Fiberboard:Corrugated and solid-board composites with moisture-resistant coatings for produce and dry-goods applications.
- Nylon:Woven and non-woven textiles with polyurethane coatings for insulated bag outer shells and strap reinforcement.
Polyethylene commands the greatest shipment volumes; Aluminum captures the highest per-unit margins in pharmaceutical-grade applications.
Application:
Customer maturity separates asset-heavy operators with captive fleets from asset-light distributors relying on third-party pooling services.
- Food Services:Restaurant chains and meal-kit operators deploy insulated bags for last-mile thermal integrity. London, Paris, and Amsterdam urban fulfillment centers are converting single-use thermal packaging to rental programs with reverse logistics bundling.
- Healthcare:Hospital clusters and pharmaceutical distributors require temperature-validated containers with ISO 18600 series certification. EMA inspections and national pharmacy regulators mandate documentation trails that favor established pool operators with embedded tracking infrastructure.
- Retail:Grocery and general merchandise distributors use collapsible containers for store replenishment cycles.
- Logistics:Contract carriers and freight forwarders manage mixed container pools across multiple shipper accounts.
Food Services generates the largest absolute demand; Healthcare shows the steepest expansion trajectory as biologics distribution scales.
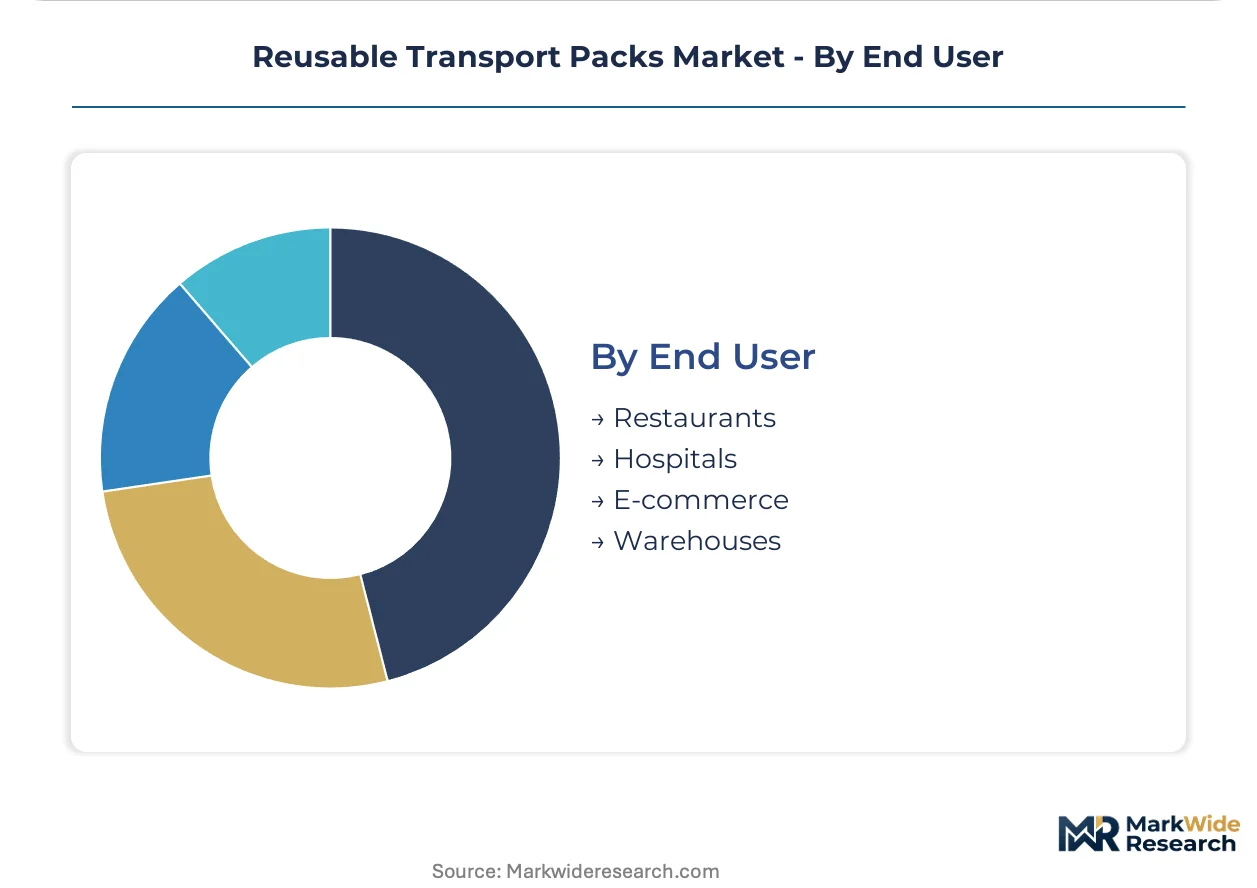
End User:
Facility scale determines whether procurement favors capital purchase, long-term lease, or per-trip rental models.
- E-commerce:Urban fulfillment centers and dark store operators prioritize collapsible totes and insulated bags for same-day delivery density. Seasonal volume spikes drive adoption of pay-per-trip contracts with guaranteed availability clauses.
- Hospitals:Pharmacy and materials management departments specify temperature-mapped containers for vaccine and blood product transport. Belgian and Dutch hospital networks are deploying sensor-embedded units with real-time monitoring at accelerating fleet penetration rates.
- Restaurants:Independent operators and regional chains with limited storage space favor compact, nestable formats.
- Warehouses:Third-party logistics providers maintain diversified container pools to serve multiple industry verticals.
E-commerce accounts for the dominant share of new fleet deployments; Hospitals are gaining share fastest through regulatory-mandated cold-chain upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for reusable transport packs sits in Germany and the Netherlands, while consumption spreads across Western European automotive corridors and North American pharmaceutical distribution networks. This geographic split shapes logistics costs and regulatory compliance requirements differently across supply chains.
Germany
Automotive OEMs in Stuttgart and Munich drive standardized foldable large load carrier adoption through just-in-sequence manufacturing contracts. The KBA enforces packaging waste reduction targets that accelerate pool-system standardization. Bavarian and Baden-Württemberg assembly plants now mandate returnable packaging for all tier-1 inbound supply.
United States
Pharmaceutical 3PL networks and meal-kit operators in New Jersey and California deploy insulated bags for cold-chain integrity. EPA waste reduction hierarchies incentivize corrugated-to-durable shifts among large distributors. The Boston-Washington corridor hosts dense clusters of hospital procurement departments specifying temperature-validated containers.
Netherlands
Rotterdam and Amsterdam logistics hubs anchor European container pooling operations with dense reverse logistics infrastructure. EMA cold-chain validation requirements determine vendor qualification for pharmaceutical distribution. Belgian and Dutch hospital networks deploy sensor-embedded units at accelerating fleet penetration rates.
France
Paris and Lyon urban fulfillment centers convert single-use thermal packaging to insulated bag rental programs for premium grocery delivery. ANSM inspections mandate documentation trails that favor established pool operators. Île-de-France hypermarket chains standardize collapsible formats through multi-operator agreements.
Poland
Automotive-heavy manufacturing corridors near Poznań and Wrocław present first-mover opportunities for container-as-a-service models. EU Packaging and Packaging Waste Regulation enforcement expands certified reusable procurement across new member states. Underdeveloped pooling infrastructure creates bottleneck risk for just-in-time supply to German assembly plants.
Reusable Transport Packs Market Competitive Landscape
The competitive structure tilts toward integrated pool operators with captive manufacturing assets. Three providers control over 70 percent of standardized automotive container pools in Western Europe, creating high barriers for asset-light entrants. Strategic archetypes separate vertically integrated European fabricators, global pallet and container pooling networks, and specialized intermediate bulk container suppliers. Dominant competitive moves include geographic expansion into underdeveloped Central European corridors and technology licensing for sensor-embedded tracking modules.
Among integrated European operators, Schoeller Allibert and Mauser Packaging Solutions occupy positions exemplifying the manufacturing-anchored archetype, with Schoeller Allibert representing standardized foldable crate specialization and Mauser Packaging Solutions anchoring intermediate bulk container supply for chemical and pharmaceutical sectors. Brambles sits within the global pooling network tier, sustaining density advantages through asset-light procurement models that displace capital purchase among mid-size distributors. These three companies collectively illustrate how regulatory-industrial convergence favors operators with embedded tracking infrastructure and reverse logistics bundling capabilities.
| Leading Market Players |
|---|
| Schoeller Allibert |
| Mauser Packaging Solutions |
| DS Smith |
| Brambles |
| Menasha Corporation |
| IFCO Systems |
| Polymer Logistics |
| Myers Industries |
| Greif |
| Others |
Value Network & Pricing Analysis
HDPE resin futures volatility cascades through container manufacturing tiers, compressing margins at compounder level while forcing automotive OEMs in Germany toward long-term offtake contracts that lock in standardized foldable crate pricing. Raw material swings amplify the spread between virgin-alternative bio-based grades and recycled feedstocks, reshaping procurement calculus for pharmaceutical cold-chain operators.
Pricing Analysis
Margin tightening in mid-size food distributor tiers reflects HDPE feedstock cost swings and REACH compliance premiums on recycled resin streams. Three-tier pricing structure across premium, standard, and economy levels separates ISO 18600-certified pharmaceutical-grade containers from uncertified commercial formats. Cost-down pressure on collapsible containers accelerates because pool operators in Western Europe bundle reverse logistics into per-trip contracts. Asset-light distributors exhibit highest price sensitivity; German automotive OEMs with captive fleet investments show lowest.
Supply Chain Analysis
ISO 18600 series certification timelines gate supplier qualification, stretching six-to-twelve months and concentrating production among established European fabricators with in-house testing labs. Manufacturing gravity centers on Germany, the Netherlands, and Belgium, drawing from Saudi and Qatari virgin resin feedstocks plus regional bio-based polypropylene development. Single-source vulnerability concentrates in HDPE resin supply to injection molders serving Stuttgart automotive corridors. Distribution runs through Rotterdam and Amsterdam logistics hubs with dense reverse logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container pooling capacity constraints in Central European automotive corridors prop pricing premiums, as underdeveloped infrastructure in Poland and Czech Republic creates bottleneck risk for just-in-time supply to German assembly plants.
For Market Incumbents: Hedge resin price exposure through backward integration into compounder relationships or long-term offtake agreements with certified bio-based polypropylene suppliers. Defend pool density advantages by expanding RFID tracking infrastructure into Eastern European service hubs where technician scarcity threatens asset recovery cycles. For New Entrants and Emerging Players: EU Packaging and Packaging Waste Regulation enforcement in Poland and Czech Republic opens a window for container-as-a-service models targeting automotive tier-1 suppliers with standardized foldable large load carriers. White-space concentration sits in underdeveloped pooling infrastructure near Poznań and Wrocław manufacturing corridors. Go-to-market through pay-per-trip contracts with guaranteed availability clauses displaces capital purchase models among seasonal produce distributors. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized insulated bag operators with EMA cold-chain validation in Belgium and Netherlands hospital networks. Long-term viability hinges on sensor-embedded fleet penetration rates and real-time monitoring contract integration. Watch RFID tracking infrastructure deployment velocity in Eastern European corridors as inflection indicator for pool operator margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Fleet Deployment | Real-time temperature monitoring enables outcome-based liability allocation between pharmaceutical 3PLs and pool operators in Belgian hospital networks. |
| Backward Integration into Resin Supply | Captive compounder relationships insulate container manufacturers from HDPE feedstock volatility and REACH compliance premiums. |
| Central European Pool Infrastructure Buildout | First-mover positioning in Poland and Czech Republic automotive corridors captures just-in-sequence manufacturing contracts from German OEMs. |
| Insulated Bag Rental Program Expansion | Urban fulfillment centers in London, Paris, and Amsterdam convert single-use thermal packaging to reverse-logistics-bundled contracts. |
| Bio-Based Polypropylene Qualification | Automotive container producers serving Stuttgart assembly networks substitute virgin-alternative grades for REACH-restricted recycled feedstocks. |
Research Methodology
Multi-period observation of pool operator fleet deployment rates, resin price indices, and regulatory enforcement timelines anchored the trend analysis, supplemented by interviews with container manufacturing executives, pharmaceutical 3PL procurement leads, automotive tier-1 supply chain managers, and food distributor logistics directors. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, EMA cold-chain validation databases, KBA packaging waste reduction targets, and customs trade data for HDPE and polypropylene resin flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Input-output matrices modeled container stock turnover, nesting ratio utilization, and pool network density effects across product type, material grade, application vertical, and end-user facility scale dimensions. CAGRs derived from regression analysis of historical fleet penetration rates against regulatory mandate timelines. Forecast inputs incorporated pharmaceutical cold-chain integrity requirement escalation and automotive just-in-sequence manufacturing adoption curves.
The model assumes a particular technology adoption path for sensor-embedded tracking modules; alternative pathways for battery-assisted passive RFID or low-power cellular connectivity would alter the outlook for real-time asset visibility premiums. Forecasts reflect assumptions about EU regulatory enforcement consistency and resin price volatility moderation. A model refresh is warranted upon material change in REACH restriction scope or HDPE feedstock supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Greenwrap Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Reusable Produce Mesh Bag Market