
 Pallet Tines Market | 2026-2036
Pallet Tines Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Tines Market Analytics
Skilled welder availability is rotating toward shortage across European and North American fabrication hubs, pressuring OEMs to automate forging lines or relocate capacity. KION Group AG leverages its captive steel processing in Germany to insulate output from labor volatility. Toyota Industries Corporation anchors Southeast Asian supply through integrated casting-to-assembly operations near Bangkok and Nagoya.
Pallet tines are load-bearing fork arms, typically forged from high-carbon or alloy steel with rated capacities from 1,500 kg to over 10,000 kg, designed to engage pallet entry openings for lifting and transport. Heavy-Duty Tines command premium positioning in steel mill and port applications where fatigue resistance determines replacement cycles. Custom Tines represent the fastest-expanding material segment as aluminum and composite variants penetrate food-grade and corrosion-sensitive environments.
OSHA enforces operator visibility and load stability mandates that directly shape tine length and deflection specifications in US markets. ISO 2330 and FEM 4.001 standards govern dimensional tolerances and testing protocols, creating compliance barriers for non-certified imports. Stakeholders must monitor divergence between regional certification regimes as dual-carbon regulations in Europe and China's GB standards begin embedding embodied-carbon thresholds into material sourcing requirements.
Market Dynamics
Warehouse automation intensification across e-commerce distribution centers is compressing replacement cycles and elevating fatigue-resistance specifications for load-bearing fork arms. Labor scarcity in European and North American fabrication hubs is simultaneously pressuring OEMs toward captive steel processing or geographic relocation of forging capacity.
Growth Catalysts
- OSHA Forklift Safety Standards:Visibility and load stability mandates in US distribution centers are lengthening tine specifications and accelerating upgrade schedules for legacy fleets.
- Alloy Steel Forging Advances:High-carbon and micro-alloy heat treatment protocols are extending rated lifespans in steel mill and port applications where downtime costs dominate procurement decisions.
- German Industrial Cluster Density:KION Group and Jungheinrich anchor captive supply chains near Frankfurt and Hamburg, insulating regional output from transatlantic shipping volatility.
Market Restraints
- Skilled Welder Scarcity:European and North American fabrication hubs face rotating shortages of certified forging technicians, forcing automation capex or capacity relocation.
- Scrap Steel Price Volatility:High-carbon and alloy steel input costs fluctuate with electric arc furnace capacity constraints in Germany and Japan.
- ISO 2330 Compliance Barriers:Dimensional tolerance and testing protocol certifications block non-certified imports from penetrating regulated European and North American procurement channels.
Strategic Opportunities
- Composite and Aluminum Variants:Food-grade and corrosion-sensitive environments in pharmaceutical and cold-chain logistics are opening premium positioning for non-ferrous tine materials.
- China GB Standards Evolution:Embodied-carbon thresholds in material sourcing requirements are creating first-mover advantage for OEMs with verified low-carbon steel supply.
- Aftermarket Service Unbundling:Independent refurbishment and recertification providers are capturing margin from OEMs in mature European forklift fleets.
Industry Challenges
- FEM 4.001 Certification Timelines:Extended testing protocols for fatigue resistance and deflection ratings delay new product introductions by 8-14 months.
- Legacy Fleet Integration Complexity:Automated guided vehicle systems require retrofitted tine interfaces incompatible with standard fork carriage dimensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Tines Market |
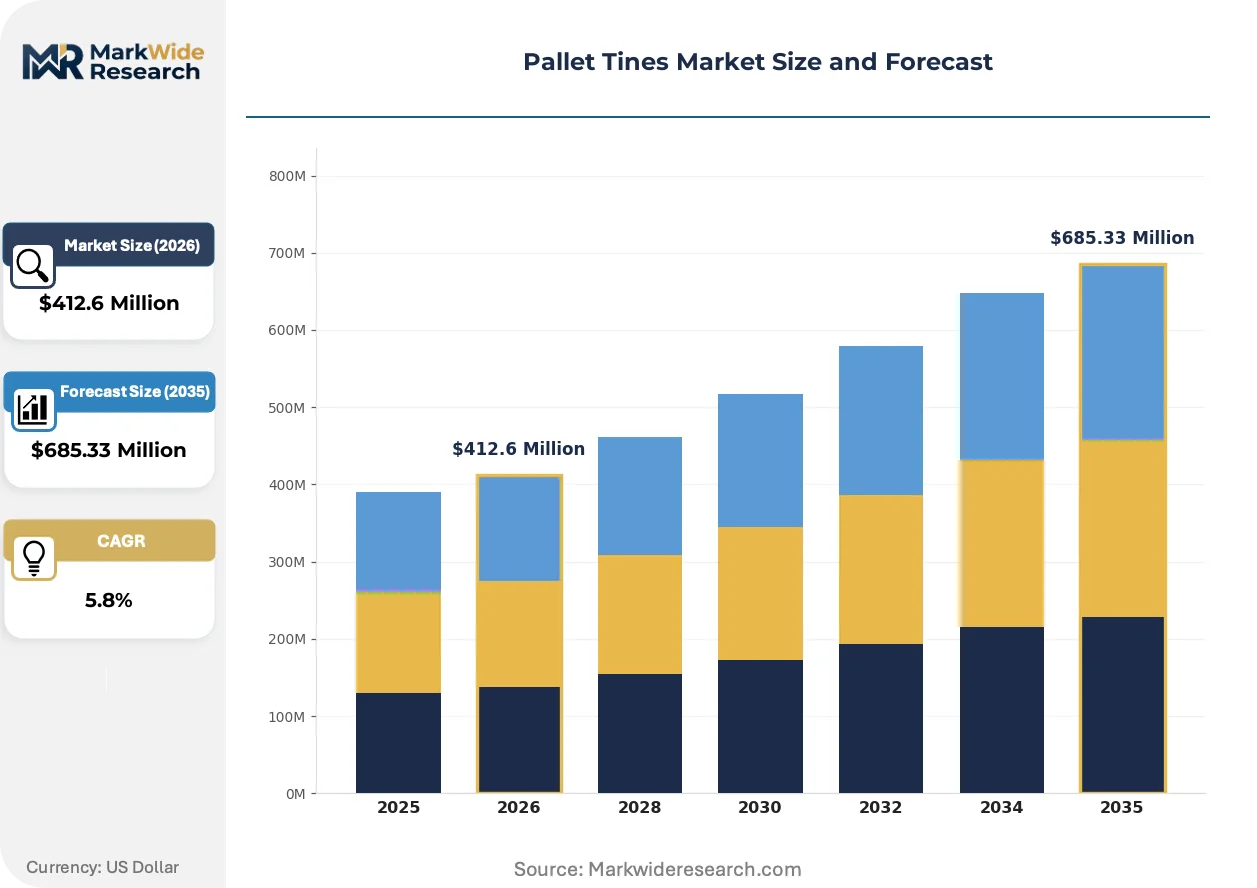
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tines, Heavy-Duty Tines, Custom Tines, Fork Extensions Material: Steel, Aluminum, Composite, Plastic Application: Warehouse Handling, Logistics, Manufacturing, Inventory Management End User: Retailers, Wholesalers, E-commerce, Distribution Centers |
| Companies Covered | Crown Equipment Corporation, KION Group AG, Toyota Industries Corporation, Jungheinrich AG, Hyster-Yale Materials Handling, Inc., Mitsubishi Logisnext Co., Ltd., Cascade Corporation, Caterpillar Inc., KINSHOFER GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Tines Market Evolving Landscape
Material science divergence and regulatory embedding of carbon accounting are reshaping competitive positioning in load-bearing component markets. Technology adoption patterns are splitting between premium fatigue-resistant alloys and lightweight corrosion-proof alternatives.
Hybrid composite-metal tine construction is fragmenting traditional steel-dominated procurement patterns. Cold-chain logistics operators and pharmaceutical distributors are piloting glass-fiber reinforced polymer overlays on aluminum cores to eliminate corrosion-induced downtime. This technology is fragmenting the historical link between rated capacity and material mass, enabling lighter designs that retain ISO 2330 deflection tolerances.
EU Green Deal embodied-carbon disclosure requirements are tightening material provenance documentation for imported steel components. OEMs serving German and French distribution centers must now certify cradle-to-gate emissions for high-carbon alloy inputs. Heavy-Duty Tine segments face the steepest compliance cost escalation, as port and steel mill applications resist material substitution despite carbon penalties.
Buyer consolidation among third-party logistics providers is compressing switching cycles and unbundling after-sales service contracts. Amazon and DHL supply chain divisions now mandate fatigue-monitoring sensor integration on new tine installations, displacing traditional calendar-based replacement schedules. This pattern concentrates in German and US Midwest distribution corridors where fleet standardization yields procurement leverage.
Pallet Tines Market Segmentation
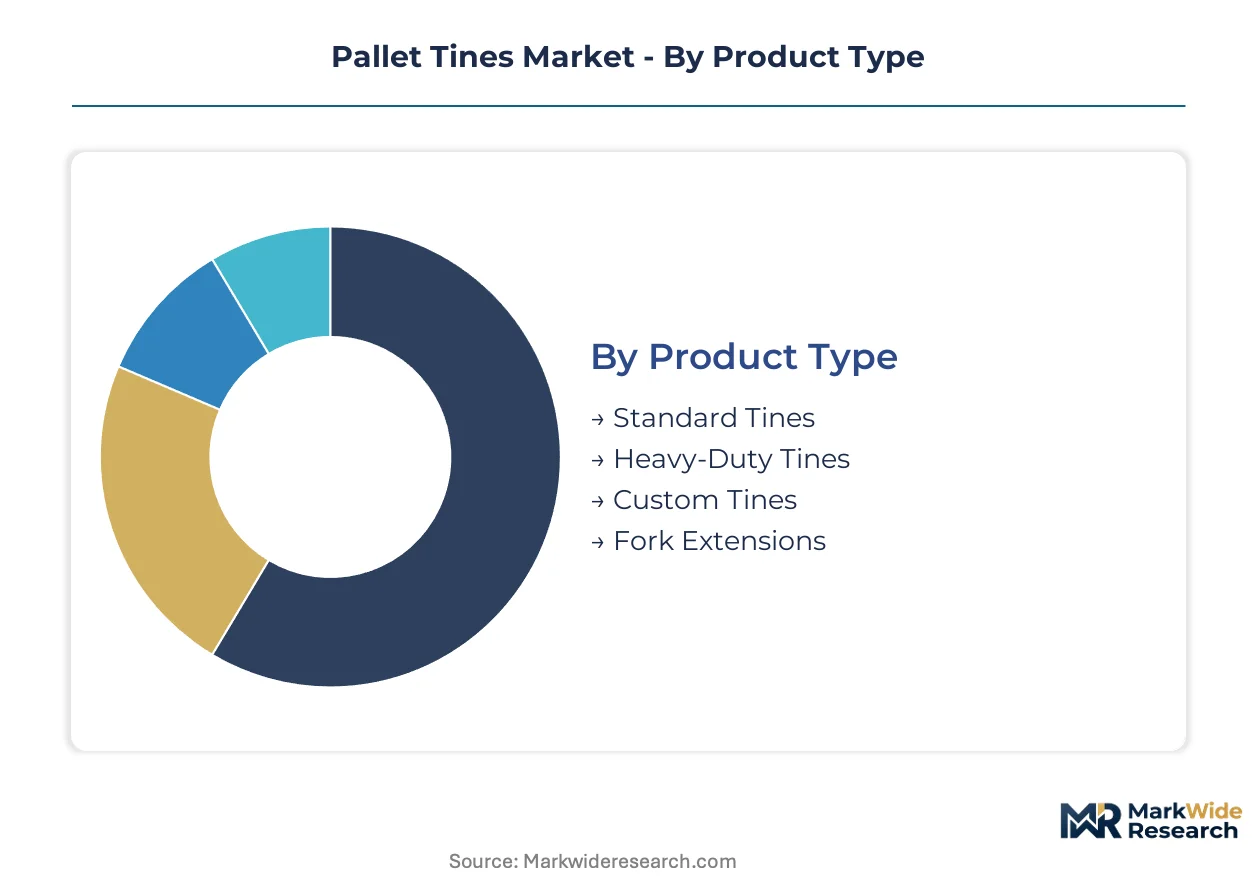
Pallet tine procurement splits across divergent regulatory and operational requirements. Buyers select specifications based on load capacity mandates, corrosion exposure, and automation compatibility rather than commodity pricing alone.
Product Type:
OSHA visibility standards and ISO 2330 deflection tolerances create tiered compliance costs that separate premium from standard offerings.
- Standard Tines:Forged from high-carbon steel with rated capacities between 1,500 kg and 5,000 kg, these units dominate fleet replacement cycles in US distribution centers where OSHA mandates drive scheduled upgrades.
- Heavy-Duty Tines:Alloy steel construction rated above 10,000 kg serves steel mills and port terminals in Germany and Japan, where fatigue resistance determines replacement intervals and downtime costs override procurement price sensitivity.
- Custom Tines:Application-specific geometries for automated guided vehicle systems and non-standard pallet formats.
- Fork Extensions:Bolt-on attachments extending reach for oversized loads without carriage replacement.
Standard Tines handle the majority of throughput; Custom Tines are expanding most quickly on share.
Material:
Input cost volatility and embodied-carbon disclosure rules are fragmenting traditional steel-dominated supply chains.
- Steel:High-carbon and micro-alloy grades remain the default for heavy-load applications, with German OEMs leveraging captive processing near Frankfurt to insulate output from scrap price swings.
- Aluminum:Cold-chain logistics operators in pharmaceutical corridors favor anodized grades for corrosion immunity, though rated capacity drops versus steel equivalents.
- Composite:Glass-fiber reinforced polymer overlays on aluminum cores are gaining trials in food-grade environments.
- Plastic:Limited to light-duty disposable applications with minimal load-bearing requirements.
Steel retains volume dominance; Aluminum is climbing the fastest as cold-chain infrastructure expands.
Application:
Warehouse automation intensity varies sharply by sector, compressing replacement cycles in e-commerce while extending them in legacy manufacturing.
- Warehouse Handling:High-frequency pallet movements in Amazon and DHL facilities demand fatigue-monitoring integration and accelerated replacement schedules.
- Logistics:Third-party providers standardize across mixed fleets, favoring interchangeable tine specifications.
- Manufacturing:Steel production and automotive assembly lines prioritize Heavy-Duty Tines with extended lifespans.
- Inventory Management:Lower utilization rates permit longer replacement intervals and standard-grade procurement.
Warehouse Handling absorbs the highest unit volume; Logistics is gaining share fastest as 3PL consolidation proceeds.
End User:
Procurement centralization among large operators is displacing fragmented buying patterns.
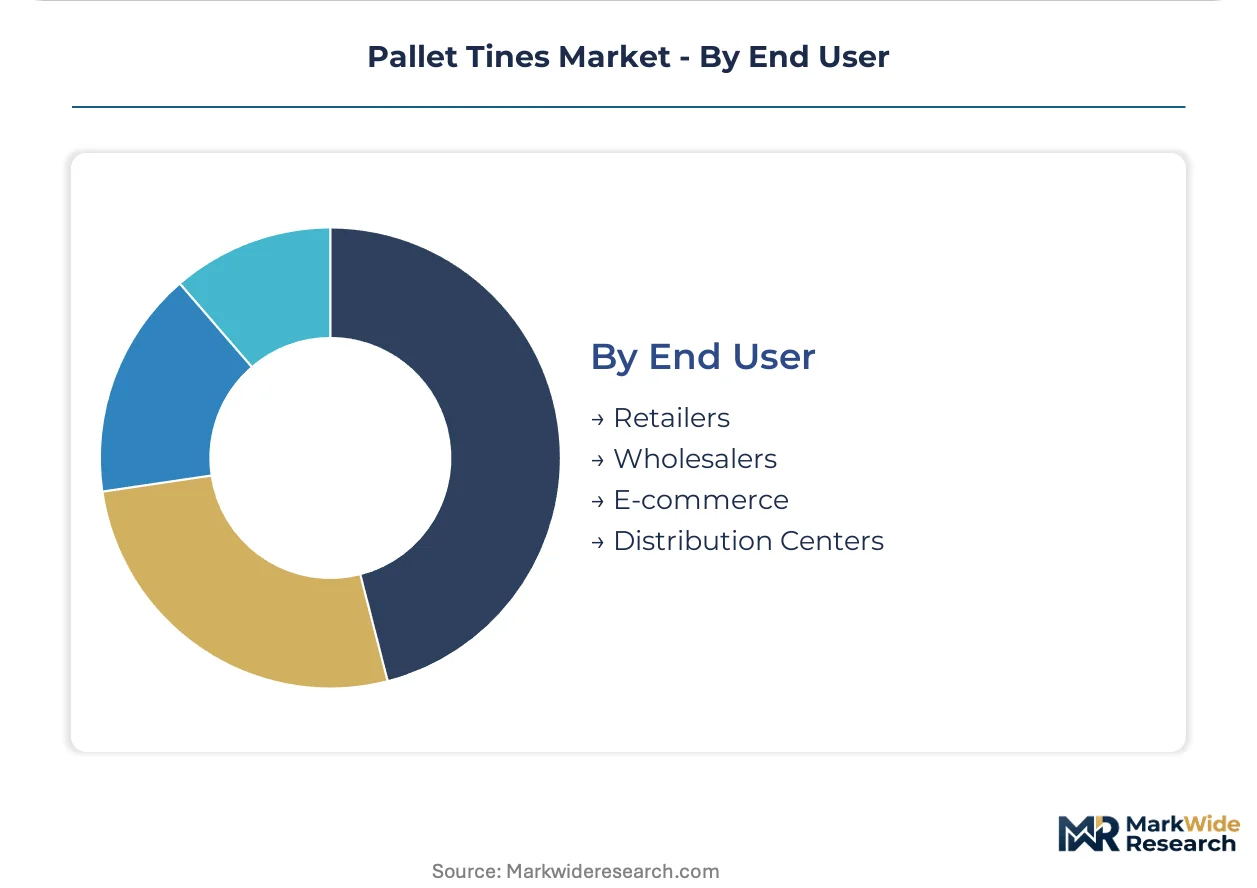
- Retailers:Big-box chains with private fleet operations mandate standardized specifications across regional distribution nodes.
- Wholesalers:Independent operators retain price-sensitive spot purchasing for replacement cycles.
- E-commerce:Amazon and Alibaba infrastructure divisions specify sensor-integrated tines with predictive maintenance contracts.
- Distribution Centers:Dedicated facilities serving single clients align specifications with shipper requirements.
E-commerce directs the steepest volume expansion; Distribution Centers show the fastest procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: German and Japanese buyers prioritize fatigue-resistant alloy grades for heavy-load cycles, while US distribution centers favor standardized specifications driven by OSHA-mandated fleet upgrades. Chinese procurement increasingly weights embodied-carbon documentation alongside GB standard compliance.
Germany
Steel mill and port terminal operators drive demand for Heavy-Duty Tines rated above 10,000 kg, where downtime costs dominate procurement decisions. EU Green Deal embodied-carbon disclosure requirements now mandate cradle-to-gate emissions certification for imported alloy inputs. KION Group and Jungheinrich anchor captive steel processing clusters near Frankfurt and Hamburg, insulating regional output from transatlantic shipping volatility.
United States
E-commerce distribution centers in the Midwest and Southeast corridors compress replacement cycles through fatigue-monitoring sensor integration. OSHA forklift safety standards enforce operator visibility and load stability mandates that directly shape tine length and deflection specifications. Amazon and DHL supply chain divisions now mandate predictive maintenance contracts, displacing traditional calendar-based replacement schedules.
China
Domestic logistics infrastructure expansion sustains volume demand for Standard Tines in the 1,500–5,000 kg capacity range. GB standards evolution embeds embodied-carbon thresholds into material sourcing requirements, creating compliance barriers for non-certified imports. Yangtze River Delta fabrication hubs face pressure to document low-carbon steel provenance as dual-carbon regulations tighten.
Japan
Automotive assembly lines and steel production facilities prioritize extended-lifecycle Heavy-Duty specifications. METI industrial policy supports integrated casting-to-assembly operations near Nagoya, preserving technical workforce density. Toyota Industries Corporation anchors Southeast Asian supply through Bangkok-based forging capacity, reducing exposure to domestic labor scarcity.
India
Emerging cold-chain logistics infrastructure drives trials of aluminum and composite variants for corrosion-sensitive pharmaceutical corridors. BIS certification requirements for material handling equipment create compliance friction for non-domestic suppliers. Maharashtra and Gujarat industrial zones concentrate fabrication capacity serving both domestic consumption and export markets.
Pallet Tines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive steel processing and geographic diversification separating premium positioning from commodity supply. The market structure reflects consolidation around forging-scale advantages and certification depth, while mid-scale fabricators compete on regional responsiveness and aftermarket service bundling. Strategic archetypes include vertically integrated OEMs with captive metallurgy operations, independent forging specialists serving multiple carriage manufacturers, and aftermarket refurbishment providers capturing margin from mature fleet bases. Dominant competitive moves center on automation capex to offset welder scarcity and geographic relocation of forging capacity toward Southeast Asian labor pools.
Among Germany-based integrated manufacturers, KION Group AG exemplifies the captive-processing archetype through its Frankfurt-region steel operations, while Jungheinrich AG occupies a parallel position with Hamburg-cluster metallurgy integration. Toyota Industries Corporation represents the Asia-Pacific diversification vector, with Nagoya and Bangkok forging assets reducing single-geography exposure. These three anchors illustrate how metallurgy control and multi-regional production footprints now separate durable competitive position from spot-market vulnerability.
| Leading Market Players |
|---|
| Crown Equipment Corporation |
| KION Group AG |
| Toyota Industries Corporation |
| Jungheinrich AG |
| Hyster-Yale Materials Handling, Inc. |
| Mitsubishi Logisnext Co., Ltd. |
| Cascade Corporation |
| Caterpillar Inc. |
| KINSHOFER GmbH |
| Others |
Value Network & Pricing Analysis
Aluminum substitution for high-carbon steel in cold-chain tine applications is simultaneously redrawing procurement geography toward Southeast Asian smelters and compressing margin structures for European forging specialists locked into legacy alloy supply contracts.
Pricing Analysis
Long-term offtake contracts dominate procurement between KION Group, Jungheinrich, and their captive steel suppliers near Frankfurt, insulating premium Heavy-Duty Tine production from scrap price volatility. Three-tier pricing structure across premium, standard, and economy levels separates ISO 2330-certified fatigue-resistant grades from uncertified imports and disposable light-duty alternatives. Cost compression in standard-grade segments is intensifying because Chinese fabricators with GB-compliant low-carbon documentation are undercutting European spot pricing. Wholesale fleet operators exhibit the highest price sensitivity, while steel mill maintenance directors prioritize lifecycle cost over unit procurement.
Supply Chain Analysis
Strait of Malacca transit congestion periodically disrupts bauxite feedstock flows to Southeast Asian aluminum processors, creating ripple effects for composite tine manufacturers. Supply concentrates in Germany, Japan, and China, with KION and Jungheinrich anchoring European forging capacity, Toyota Industries controlling Nagoya and Bangkok operations, and Yangtze River Delta hubs serving domestic Chinese logistics expansion. High-carbon steel billets, micro-alloy additives, and anodized aluminum sheet constitute critical input dependencies. Single-source vulnerability runs through German electric arc furnace capacity constraints. Distribution runs through OEM-direct channels for integrated manufacturers and independent aftermarket refurbishers for mature fleet bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified forging technician scarcity across European and North American fabrication hubs is constraining output elasticity and amplifying automation capex returns for first movers.
For Market Incumbents: Consolidate captive steel processing advantages near Frankfurt and Hamburg against emerging low-carbon import competition from Chinese GB-certified suppliers. Deepen backward integration into scrap recycling and electric arc furnace operations to offset skilled welder availability gaps. Prioritize FEM 4.001 certification depth as a compliance moat against non-certified entrants. For New Entrants and Emerging Players: ISO 2330 fast-track accreditation for aluminum-composite hybrid tines opens immediate penetration channels in pharmaceutical cold-chain corridors where corrosion immunity commands premium positioning. Target Indian BIS certification pathways for Maharashtra and Gujarat industrial zones serving domestic cold-chain infrastructure buildout. Lead with sensor-integrated predictive maintenance bundles to displace calendar-based replacement incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated OEMs with metallurgy control and multi-regional production footprints. Long-term viability rests on automation capex deployment and geographic diversification toward Southeast Asian labor pools. Monitor divergence between EU Green Deal embodied-carbon thresholds and China's dual-carbon enforcement as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Recycling | KION Group's Frankfurt captive steel operations insulate output from German electric arc furnace capacity constraints. |
| Aluminum-Composite Hybrid Development | Glass-fiber reinforced polymer overlays on aluminum cores penetrate pharmaceutical cold-chain logistics corridors. |
| FEM 4.001 Certification Fast-Track | Accelerated fatigue resistance testing protocols compress 8-14 month approval timelines for new product introductions. |
| Southeast Asian Forging Relocation | Toyota Industries' Bangkok capacity reduces exposure to Japanese domestic labor scarcity and METI policy shifts. |
| Sensor-Integrated Predictive Maintenance | Amazon and DHL supply chain divisions mandate fatigue-monitoring integration displacing calendar-based replacement schedules. |
Research Methodology
Initial hypotheses were tested against primary input from OEM procurement directors, aftermarket service managers, plant engineers at steel mill and port terminal operators, and logistics fleet maintenance heads, then refined through secondary validation against customs trade data, SEC 10-K filings of listed material handling equipment manufacturers, ISO certification registries, and EU Green Deal embodied-carbon disclosure filings. Bottom-up unit shipment estimates by product type, material grade, and application were triangulated against top-down market value reconstruction.
Variance decomposition across product type, material composition, rated capacity tier, end-use application intensity, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by average selling price evolution. Industry-specific forecast inputs included OSHA-mandated fleet upgrade schedules, EU Green Deal carbon accounting implementation timelines, and Chinese GB standards evolution for material sourcing documentation.
Underlying assumptions cover sustained e-commerce distribution center automation intensity, stable alloy steel input cost corridors, and gradual China-EU regulatory convergence on embodied-carbon thresholds, with deviation risk concentrated in scrap steel price volatility and skilled welder availability shocks. Practitioners should keep alternative scenarios live as dual-carbon enforcement divergence and cold-chain infrastructure buildout rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
China Pallets Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Global Wood Pallet Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Pallet Slip Sheets Market