
 Europe Refillable and Reusable Packaging Market | 2026-2036
Europe Refillable and Reusable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Refillable and Reusable Packaging Market Insights
Reusable packaging digitization is tilting the technology stack toward IoT-enabled asset tracking and blockchain-verified return cycles. CHEP Europe leverages its pooled pallet network to sustain circular logistics infrastructure across the continent. IFCO Systems anchors fresh produce crate pooling through standardized RPC formats that dominate supermarket supply chains.
Europe Refillable and Reusable Packaging comprises durable containers engineered for multiple use cycles, typically fabricated from glass, metal, or engineered plastics with wall thicknesses exceeding single-use equivalents by factors of three to ten, designed to withstand industrial washing protocols and maintain product integrity across return loops. Glass packaging leads in beverage applications where thermal sterilization compatibility and chemical inertness command premium positioning, while plastic variants in closed-loop logistics represent the fastest-expanding segment driven by weight reduction and nestability advantages. Composite materials occupy niche positions where barrier performance requirements exceed monomaterial capabilities.
The EU Packaging and Packaging Waste Regulation imposes mandatory reuse quotas that reshape product design obligations, while ECHA's REACH framework governs chemical safety in recycled material streams and the EU Green Deal's circular economy action plan channels investment toward reuse infrastructure. National transposition varies, with Germany's existing VerpackG deposit system providing regulatory precedent that other member states now adapt. Stakeholders must monitor how delegated acts under the revised PPWR define performance criteria for reusable packaging certification.
Market Dynamics
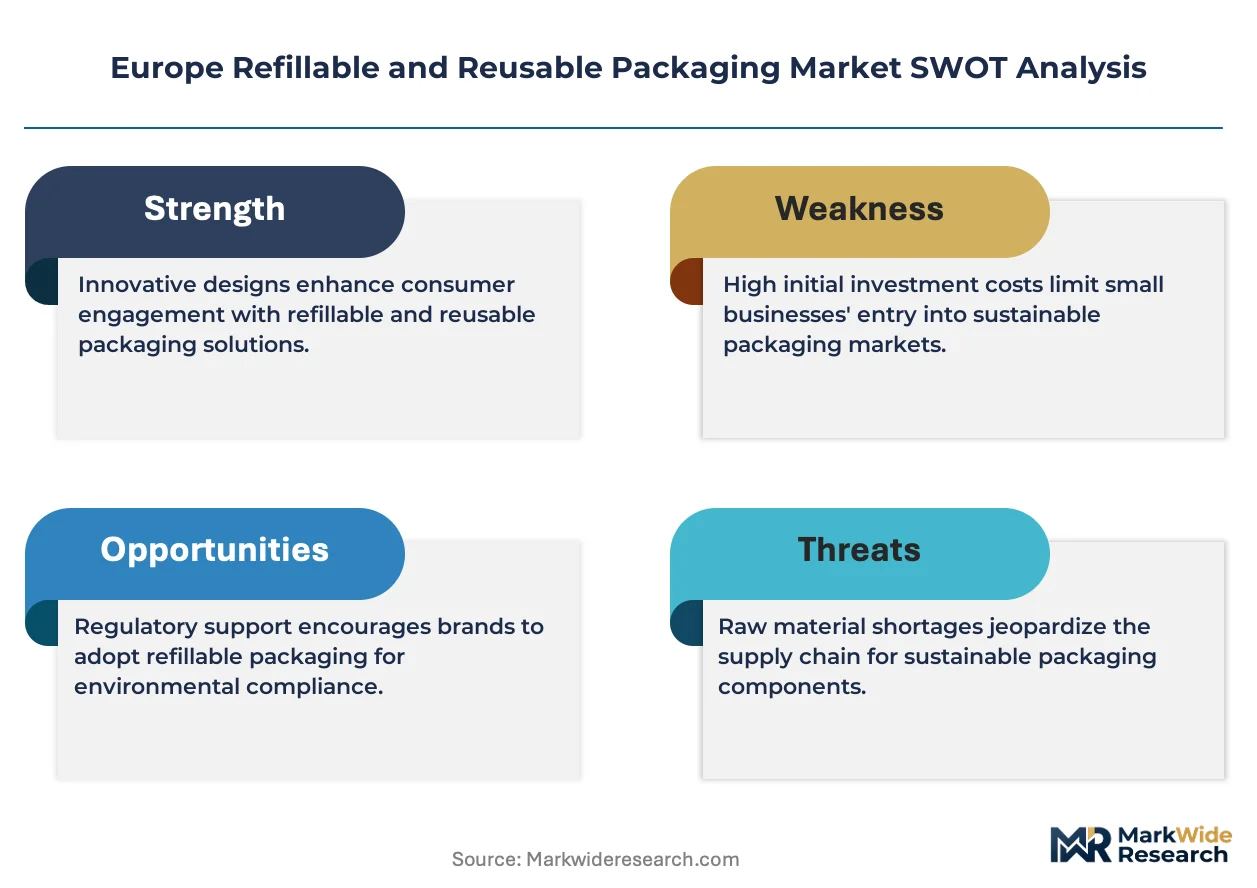
The EU Packaging and Packaging Waste Regulation is forcing a structural redesign of packaging economics across Europe, converting voluntary reuse pilots into mandatory compliance obligations that reshape capital allocation and supply chain architecture.
Growth Catalysts
- Deposit-Return Infrastructure:Germany's VerpackG system demonstrates that high-return logistics networks create viable unit economics for refillable beverage containers, prompting France and the Netherlands to replicate this framework.
- REACH Chemical Safety:ECHA's framework for recycled material streams ensures that post-consumer resins meet safety thresholds, enabling closed-loop plastic pooling systems in fresh produce supply chains.
- IoT-Enabled Tracking:RFID and blockchain verification protocols reduce asset loss rates in pooled packaging networks, cutting per-cycle costs for logistics operators managing multi-use containers.
Market Restraints
- Capital Intensity:Industrial washing and sterilization equipment requires substantial upfront investment, creating barriers for mid-sized manufacturers entering refillable packaging segments.
- Material Cost Volatility:Engineered polymers and specialized glass formulations face price pressure from energy-intensive production processes concentrated in Central European manufacturing clusters.
- Regulatory Fragmentation:Divergent national transpositions of the EU Green Deal's circular economy targets create compliance complexity for cross-border packaging pool operators.
Strategic Opportunities
- Pharmacy Retail Networks:Personal care refill stations in Germany and France remain underdeveloped relative to grocery channels, offering expansion white space for cosmetic and household product categories.
- Composite Barrier Materials:Multi-layer structures combining polymer and metal films address oxygen sensitivity in premium food applications where monomaterials fail.
- Delegated Acts Timeline:Pending EU certification criteria for reusable packaging will create first-mover advantages for producers with established testing protocols and documentation systems.
Industry Challenges
- Reverse Logistics Coordination:Integrating return cycles with existing retail distribution networks requires reconfiguring warehouse layouts and transport routing algorithms.
- Standardization Delays:Absence of unified container formats across national markets forces pooling operators to maintain incompatible asset fleets, diluting economies of scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Refillable and Reusable Packaging Market |
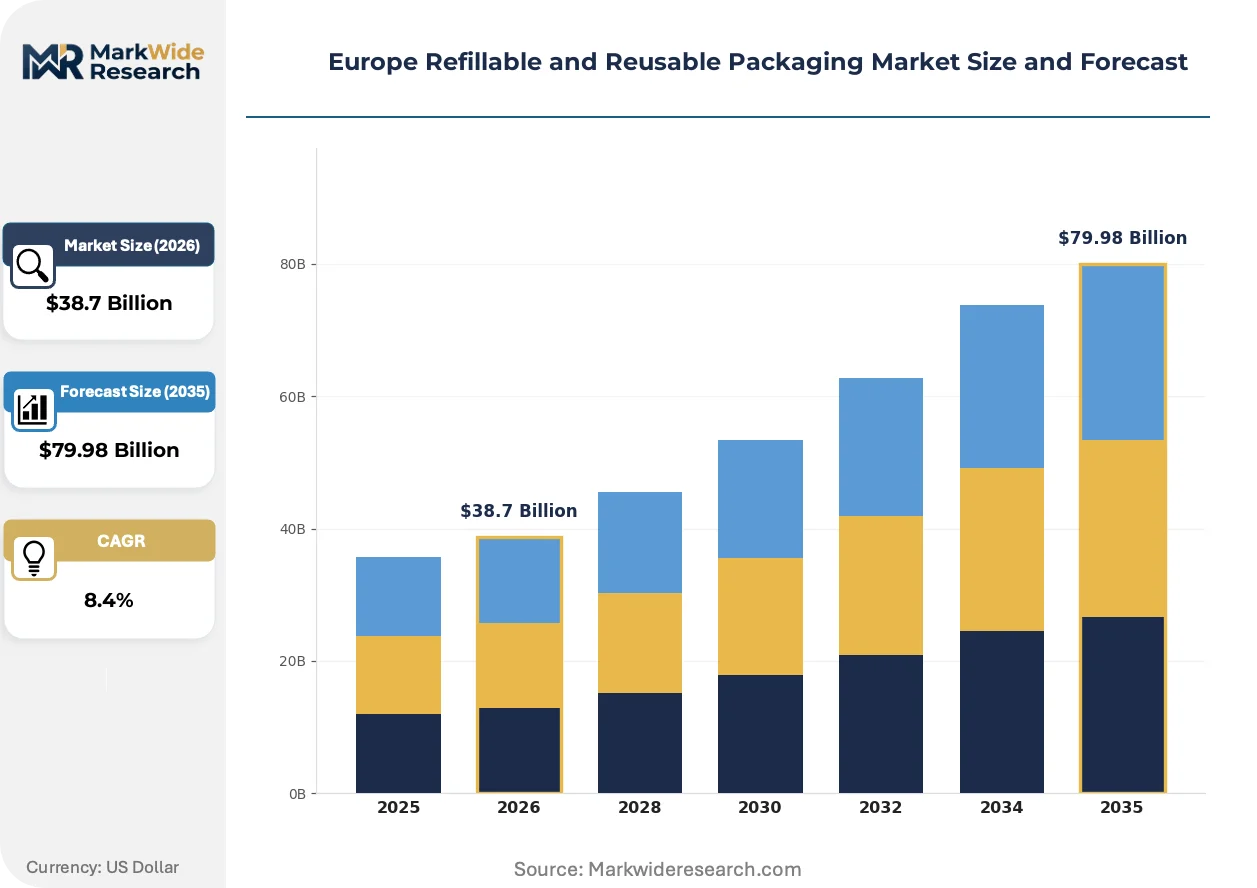
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass, Metal, Plastic, Composite End Use Industry: Food & Beverage, Cosmetics, Cleaning Products, Consumer Electronics Functionality: Transport, Storage, Dispensing, Branding Distribution Channel: Direct Sales, E-commerce, Retail Stores, Wholesalers |
| Companies Covered | Schoeller Allibert Services BV, IFCO Systems, CHEP Europe, Nefab Group AB, Vetropack Holding AG, Mondi Group, Greif, Euro Pool System, DS Smith Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Refillable and Reusable Packaging Market Trends and Innovations
Digital verification systems and material science advances are converging to transform reusable packaging from a compliance cost into a data-generating asset class.
RFID-tagged containers with embedded sensors are migrating from pilot programs to scaled deployment across European grocery retail networks. Supermarket chains in Scandinavia and the Benelux region are outfitting RPCs with track-and-trace capabilities at rates exceeding other European markets. This migration from manual scanning to automated asset management compresses cycle time visibility and enables dynamic pooling optimization.
The EU Green Deal's circular economy action plan channels public investment toward reuse infrastructure through delegated acts under the Packaging and Packaging Waste Regulation. Industrial stakeholders must now design for disassembly and washing compatibility rather than single-use optimization. Beverage and fresh produce segments face the steepest compliance curves, with producers accelerating pilot programs to secure certification ahead of mandatory quotas.
Buying committees at major retail groups are consolidating supplier relationships around pooling operators offering integrated logistics services rather than standalone container leasing. This procurement consolidation favors vertically integrated providers with captive washing facilities and transport networks. The shift is most pronounced in Germany's grocery sector, where centralized buying power has compressed vendor lists for standardized crate formats.
Europe Refillable and Reusable Packaging Market Segmentation
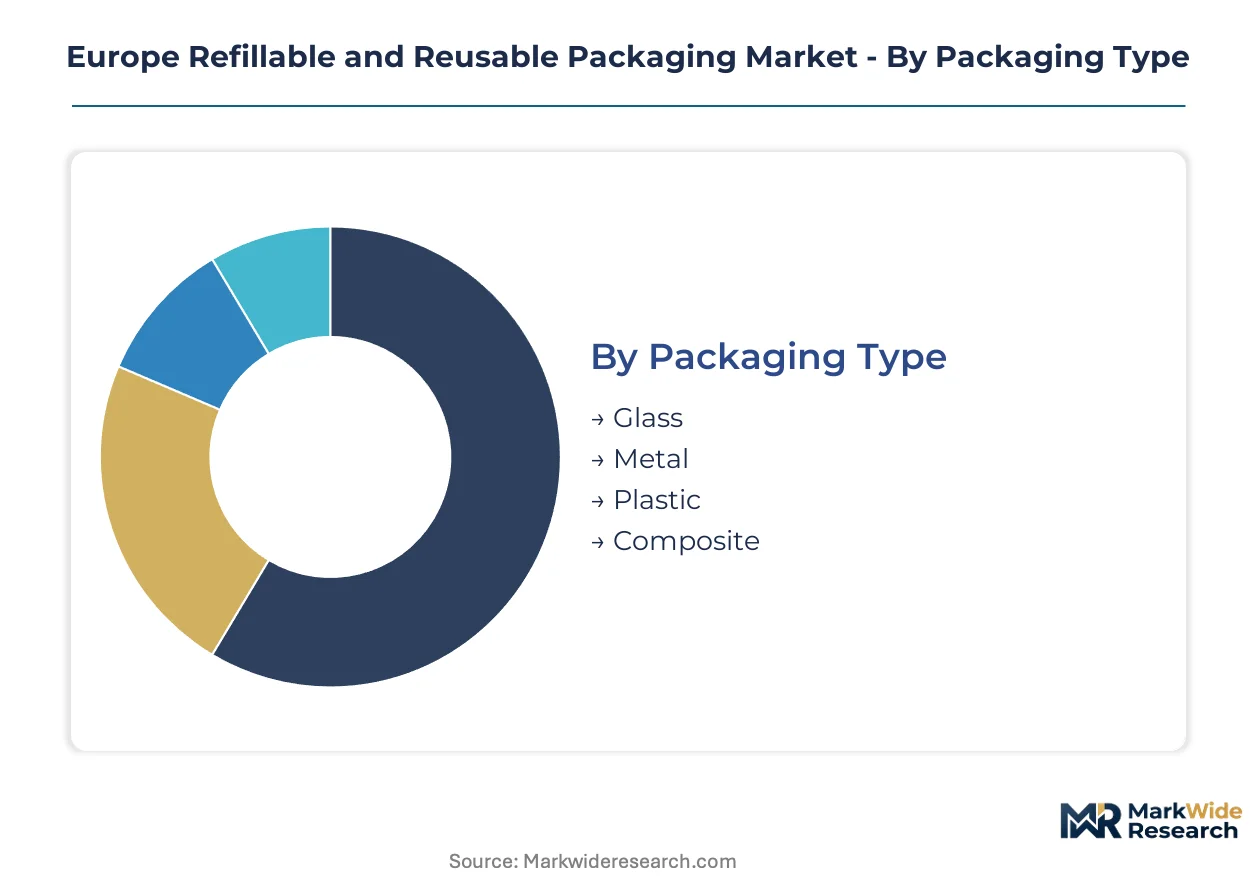
Reusable packaging economics hinge on material durability, end-use hygiene requirements, and return-loop logistics density. Segment boundaries in this market reflect washing-protocol compatibility and pooling-network reach rather than conventional packaging specifications.
Packaging Type:
Cost tier stratification separates premium thermal-resistant formats from commodity-weight alternatives competing on per-cycle depreciation.
- Glass:Soda-lime and borosilicate formulations withstand industrial sterilization temperatures exceeding 80°C. Beverage producers in Germany's deposit-return corridors concentrate procurement here, drawn by chemical inertness and established washing infrastructure.
- Plastic:HDPE and PP variants dominate fresh produce pooling through nestability advantages and weight reduction against glass equivalents. Benelux supermarket chains are expanding RPC fleets fastest, compressing transport cost per return cycle.
- Metal:Stainless steel and aluminum containers serve premium cosmetics and specialty food segments where barrier performance and aesthetic durability justify higher unit costs.
- Composite:Multi-layer polymer-metal laminates address oxygen-sensitive applications where monomaterial barriers fail, occupying niche positions in pharmaceutical and high-end food preservation.
Glass holds installed capacity. Plastic is rotating up the share rankings.
End Use Industry:
Application-specific hygiene standards and return-frequency economics segment demand across divergent washing-protocol intensities.
- Food & Beverage:Deposit-return schemes in Germany and the Netherlands create closed-loop density for refillable bottles and RPCs. Dairy and beverage subsegments face the steepest regulatory compliance curves under EU Packaging and Packaging Waste Regulation reuse quotas.
- Cosmetics:Refill station networks in French and German pharmacy retail are expanding fastest for shampoo and skincare categories, though penetration lags grocery channels significantly.
- Cleaning Products:Concentrate refill formats reduce transport weight and packaging mass, with household brands piloting returnable dispensing containers in Scandinavian markets.
- Consumer Electronics:Protective transit packaging for high-value components utilizes standardized returnable totes, with pooling operators serving contract manufacturers in Central European electronics clusters.
Food & Beverage anchors volume. Cosmetics is climbing the fastest.
Functionality:
Volume throughput and asset-utilization rates differentiate segments based on cycle frequency and dwell-time constraints.
- Transport:Pooled pallets and crates move through high-velocity grocery supply chains, with CHEP and IFCO networks achieving maximum turns per year in Benelux and German retail corridors.
- Storage:Intermediate bulk containers and warehouse totes serve manufacturing and distribution staging, with longer dwell times but lower per-cycle handling costs.
- Dispensing:Refillable pump bottles and dosing containers for personal care and cleaning products require consumer-facing design compatibility with retail station infrastructure.
- Branding:Premium cosmetic and gift packaging prioritizes aesthetic differentiation over cycle efficiency, with shorter return loops and higher loss tolerance.
Transport commands asset velocity. Dispensing is gaining share fastest.
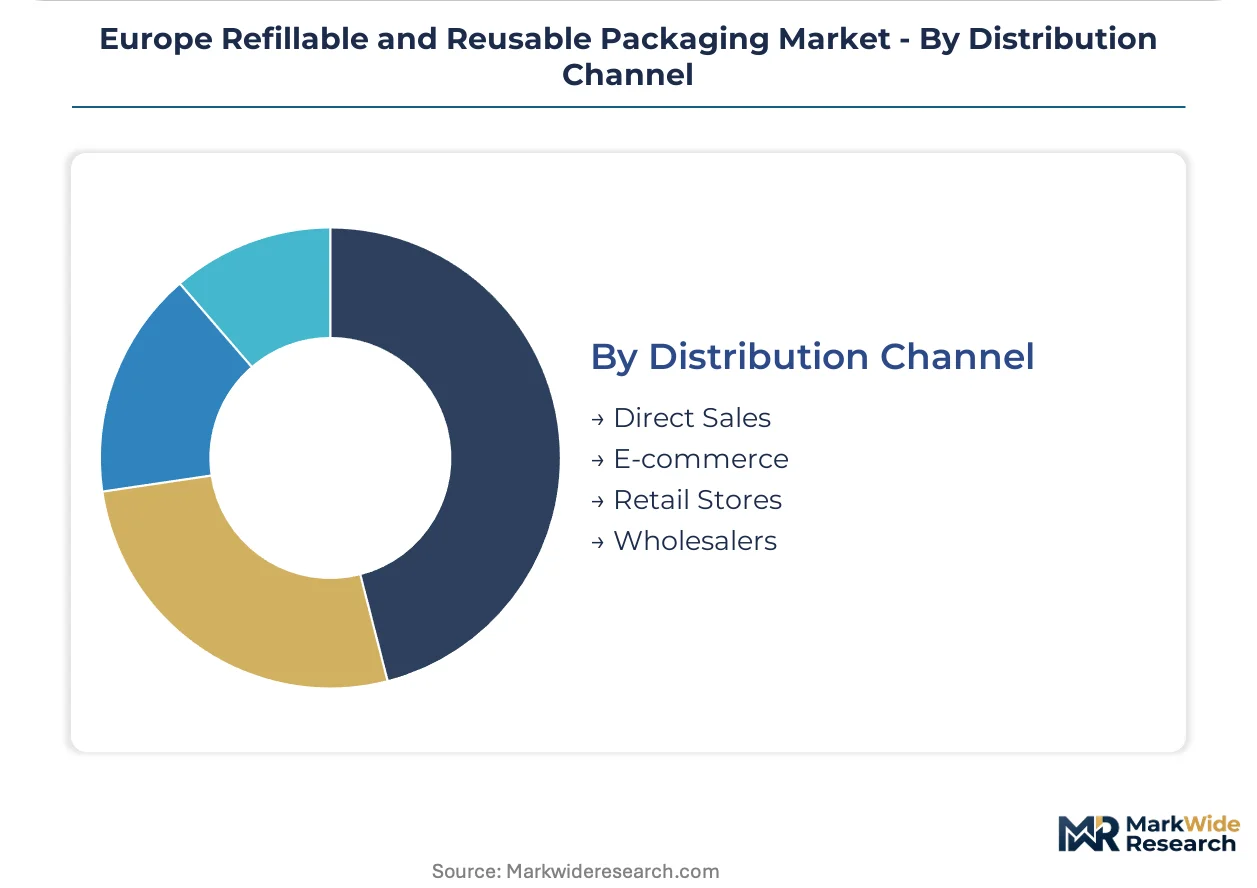
Distribution Channel:
Customer-type concentration determines pooling-network design and return-point density requirements.
- Direct Sales:Manufacturer-controlled return loops for institutional buyers and foodservice operators enable standardized container formats with dedicated washing contracts.
- E-commerce:Last-mile return logistics for reusable shipping containers remain underdeveloped, with pilot programs concentrated in urban Dutch and German delivery corridors.
- Retail Stores:Supermarket refill stations and crate return points provide consumer-facing infrastructure density, with centralized buying power compressing supplier lists in Germany.
- Wholesalers:Intermediate distribution layers for foodservice and hospitality sectors utilize pooled packaging with lower return-frequency requirements than grocery retail.
Retail Stores holds network density. E-commerce is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail buying committees in Germany and France concentrate procurement power for refillable packaging systems, while Benelux logistics operators achieve the densest pooling-network coverage per square kilometer.
Germany
Grocery retailers operating deposit-return corridors drive demand for standardized glass bottles and plastic crates. The VerpackG framework mandates producer responsibility for return logistics, creating regulatory precedent across the EU. Bavarian beverage producers and North Rhine-Westphalian washing facilities anchor the continent's most mature closed-loop infrastructure.
France
Pharmacy retail chains are expanding personal care refill stations faster than any neighboring market. ANSM guidelines on packaging contact materials shape safety protocols for cosmetic dispensing formats. The Île-de-France corridor hosts pilot programs for IoT-tracked returnable containers serving Paris metro distribution networks.
Netherlands
Fresh produce logistics operators achieve maximum RPC utilization rates through centralized pooling coordination. REACH compliance documentation for recycled polymer streams enables rapid material qualification cycles. Rotterdam's port-centric distribution clusters support cross-border crate circulation into Belgian and German retail networks.
Italy
Specialty food producers in Emilia-Romagna and Lombardy utilize premium glass formats for preserved goods requiring thermal sterilization. National transposition of EU Packaging and Packaging Waste Regulation reuse quotas lags northern neighbors, creating compliance preparation windows. Milan-based design studios are prototyping composite barrier containers for oxygen-sensitive regional products.
Sweden
Scandinavian retail cooperatives lead RFID deployment rates for automated asset tracking in grocery supply chains. ECHA guidance on chemical safety in washing protocols informs national hygiene standards for multi-use containers. Stockholm logistics hubs are testing blockchain-verified return cycles for high-value electronics protective packaging.
Europe Refillable and Reusable Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent scale vectors. The market exhibits tiered consolidation, with pooled logistics operators commanding network density advantages while material-specific fabricators retain design differentiation. Two strategic archetypes dominate: vertically integrated pooling operators with captive washing infrastructure, and component-specialist manufacturers focusing on barrier performance engineering. Competitive moves concentrate on geographic network expansion and certification pre-positioning ahead of delegated acts under EU regulations.
Among pooled logistics operators, CHEP Europe, IFCO Systems, and Euro Pool System exemplify the network-scale archetype, each representing distinct regional density strategies within continental supply chains. Schoeller Allibert Services BV and Nefab Group AB occupy positions on the protective packaging and returnable transit equipment vector, anchoring specialist tiers where custom engineering commands premium positioning. Material-anchored players including Vetropack Holding AG and Mondi Group sit within substrate-specific segments where thermal performance and print compatibility differentiate procurement decisions.
| Leading Market Players |
|---|
| Schoeller Allibert Services BV |
| IFCO Systems |
| CHEP Europe |
| Nefab Group AB |
| Vetropack Holding AG |
| Mondi Group |
| Greif |
| Euro Pool System |
| DS Smith Plc |
| Others |
Pricing and Supply Chain Analysis
North Rhine-Westphalia's washing facility corridor concentrates industrial sterilization capacity for pooled glass and plastic containers, anchoring downstream pricing power for logistics operators serving German grocery retail networks. This geographic concentration of capital-intensive infrastructure enables cost-plus contracting with energy-indexed pass-through mechanisms that protect margins against input volatility.
Pricing Analysis
Cost-plus contracts with energy-indexed adjustments dominate procurement between pooling operators and retail buying committees. Three-tier pricing structure across premium thermal-resistant glass, standard HDPE crates, and economy-weight polypropylene separates tiers by washing-cycle durability and RFID tracking integration. Pricing pressure stems from electricity-intensive sterilization protocols concentrated in Central European manufacturing clusters. Mid-sized manufacturers exhibit highest price sensitivity due to capital barriers for captive washing infrastructure, while vertically integrated pooling operators with captive energy hedging demonstrate lowest sensitivity.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms anchor working capital management for crate and pallet manufacturers serving pooled logistics networks. Production concentrates in Germany, the Netherlands, and Italy, with Benelux achieving densest pooling-network coverage per square kilometer. Raw material dependencies center on engineered polypropylene resins, borosilicate glass formulations, and stainless steel alloys for premium cosmetic applications. Single-source vulnerability runs through specialized industrial washing equipment manufacturers concentrated in Bavaria. Distribution runs through centralized retail buying committees in Germany and France that compress vendor lists for standardized formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use flexible packaging substitution threatens refillable format economics as incumbent producers navigate compliance-driven capital reallocation under EU Packaging and Packaging Waste Regulation mandates.
For Market Incumbents: Harden certification pre-positioning ahead of delegated acts defining reusable packaging performance criteria, securing first-mover advantage in documentation protocols. Deepen backward integration into captive polymer recycling streams to offset virgin resin cost volatility. Defend against flexible pouch substitution by accelerating IoT-enabled asset tracking deployment that generates data revenue streams beyond per-cycle leasing fees.
For New Entrants and Emerging Players: Establish a beachhead in French pharmacy retail refill stations for personal care categories where penetration lags German grocery channels significantly. Target composite barrier material niches for oxygen-sensitive specialty foods where monomaterials fail. Pursue direct sales contracts with institutional foodservice operators that enable standardized formats without competing for supermarket shelf space controlled by incumbent pooling networks.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU Green Deal circular economy investment channels public capital toward reuse infrastructure with mandatory compliance timelines creating demand inelasticity. Acquisition targets should emphasize vertically integrated pooling operators with captive washing facilities and established RFID deployment. Monitor delegated act publication timing as inflection signal for certification-driven procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Delegated Act Certification Pre-Positioning | First-mover documentation protocols secure preferred supplier status under pending EU PPWR performance criteria. |
| IoT-Enabled Asset Tracking Deployment | RFID and blockchain verification transforms containers from compliance cost into data-generating revenue assets. |
| Backward Integration into Polymer Recycling | Captive post-consumer resin streams hedge virgin material volatility under REACH compliance frameworks. |
| Pharmacy Retail Network Expansion | French and German personal care refill stations offer underdeveloped white space versus saturated grocery channels. |
| Composite Barrier Material Development | Multi-layer polymer-metal laminates address oxygen-sensitive applications where monomaterials fail certification thresholds. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary regulatory documentation anchors the qualitative findings in this study. Conversations with pooling logistics operators, retail category buyers, industrial washing facility managers, and ECHA compliance officers informed operational dynamics. Secondary sources include EU Packaging and Packaging Waste Regulation delegated act drafts, ECHA REACH guidance documents, national transposition texts for Germany's VerpackG and France's AGEC law, and trade data from European plastics associations. Bottom-up segment sizing triangulates against top-down regulatory mandate volume projections.
Calibration against historical return-rate data from Germany's deposit-return corridors and Benelux RPC utilization benchmarks shapes the analytical framework across the analysis window. Segmentation dimensions modeled include packaging material type, end-use industry hygiene requirements, functionality tier, and distribution channel density. CAGRs derive from regression analysis against regulatory compliance timeline assumptions and infrastructure investment flow projections. Industry-specific inputs incorporate washing-cycle depreciation rates and asset-loss ratios from pooled network operators.
Stress conditions across energy price volatility, regulatory timeline delays, and substitute material penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EU PPWR implementation sequencing and national transposition coherence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Greenwrap Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Refillable and Reusable Packaging Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Reusable Straw Market