
 Reusable Corrugated Plastic Boxes Market | 2026-2036
Reusable Corrugated Plastic Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Corrugated Plastic Boxes Market Analytics
North American thermoforming capacity is consolidating around integrated sheet-to-box producers. ORBIS Corporation leverages captive resin compounding and regional molding networks to anchor supply for automotive tier-one suppliers. MDI sustains dominance in heavy-duty agricultural and industrial pooling systems through proprietary flute geometries. Flex Container competes on folding-box modularity for e-commerce reverse-logistics programs.
Reusable corrugated plastic boxes consist of extruded polypropylene twin-wall sheet thermoformed or die-cut into rigid, hollow-profile containers rated for multi-trip durability cycles exceeding fifty rotations. The material resists moisture, chemicals, and impact fracture where fiberboard fails, serving closed-loop distribution in automotive, food, and pharmaceutical supply chains. Folding boxes command expanding share in e-commerce returns infrastructure due to collapsibility reducing backhaul cube by eighty percent versus rigid alternatives. Heavy-duty boxes retain margin concentration in automotive parts sequencing where OEMs mandate exacting dimensional tolerances. Stackable containers lead volume in food storage applications governed by FDA food-contact compliance and washdown sanitation protocols.
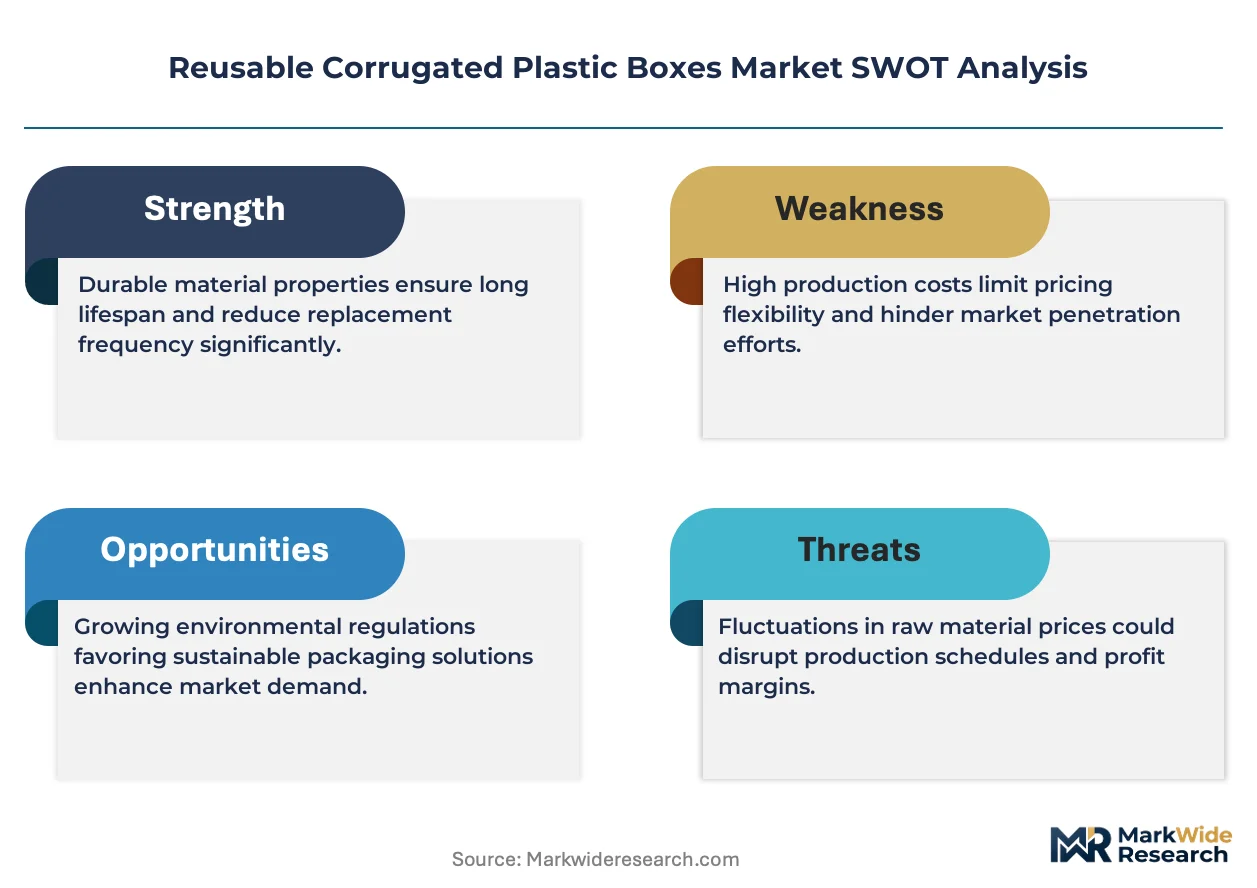
FDA Title 21 CFR standards for food-contact polypropylene, EPA Sustainable Materials Management priorities, and ISO 18600 series packaging reuse metrics collectively shape product certification requirements and buyer qualification thresholds. The EU Packaging and Packaging Waste Regulation extends these compliance burdens for exporters serving European manufacturing and retail accounts. Stakeholders must monitor evolving extended producer responsibility frameworks and resin recycling content mandates to preserve market access and pricing power.
Market Dynamics
The EPA's Sustainable Materials Management priorities and EU Packaging and Packaging Waste Regulation are forcing OEM procurement departments to retire single-use fiberboard in favor of certified reusable alternatives, compressing supplier qualification timelines and reshaping resin sourcing strategies.
Growth Catalysts
- Automotive Sequencing Mandates:OEM assembly plants in Mexico and the US Midwest now specify twin-wall polypropylene totes for just-in-time parts delivery, eliminating cardboard contamination risks.
- REACH and RoHS Compliance Burdens:European exporters face mandatory Extended Producer Responsibility frameworks that favor durable, trackable packaging with verified recycling content.
- Closed-Loop Pooling Networks:Third-party logistics operators deploy RFID-tracked container fleets across pharmaceutical distribution, cutting per-trip packaging costs through rotational efficiency.
Market Restraints
- Polypropylene Resin Volatility:Feedstock costs for extruded twin-wall sheet fluctuate with propylene monomer supply disruptions from Gulf Coast petrochemical complexes.
- Tooling Concentration Risk:Heavy-duty box thermoforming molds require 20-week lead times from specialized German and Italian toolmakers, constraining capacity expansion.
- Fiberboard Substitution Persistence:Low-value, non-returnable shipments in agricultural bulk still default to wax-coated corrugated despite moisture failure rates.
Strategic Opportunities
- India Pharmaceutical Cold Chain:CDSCO temperature-validation requirements for biologics distribution create demand for insulated twin-wall shippers with phase-change lining integration.
- Carbon Border Adjustment Mechanism:The EU CBAM incentivizes exporters to adopt lightweight, reusable packaging to reduce embedded emissions in trade-weighted carbon calculations.
- E-Commerce Reverse Logistics:Folding box modularity addresses the eighty-percent cube-reduction requirement for empty-container backhaul from last-mile distribution centers.
Industry Challenges
- Multi-Site Sanitation Protocols:FDA Title 21 CFR food-contact compliance requires validated washdown procedures across decentralized pooling networks, complicating fleet standardization.
- Legacy WMS Integration:ERP systems at tier-two automotive suppliers lack container-level tracking modules, delaying RFID-tagged box deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Corrugated Plastic Boxes Market |
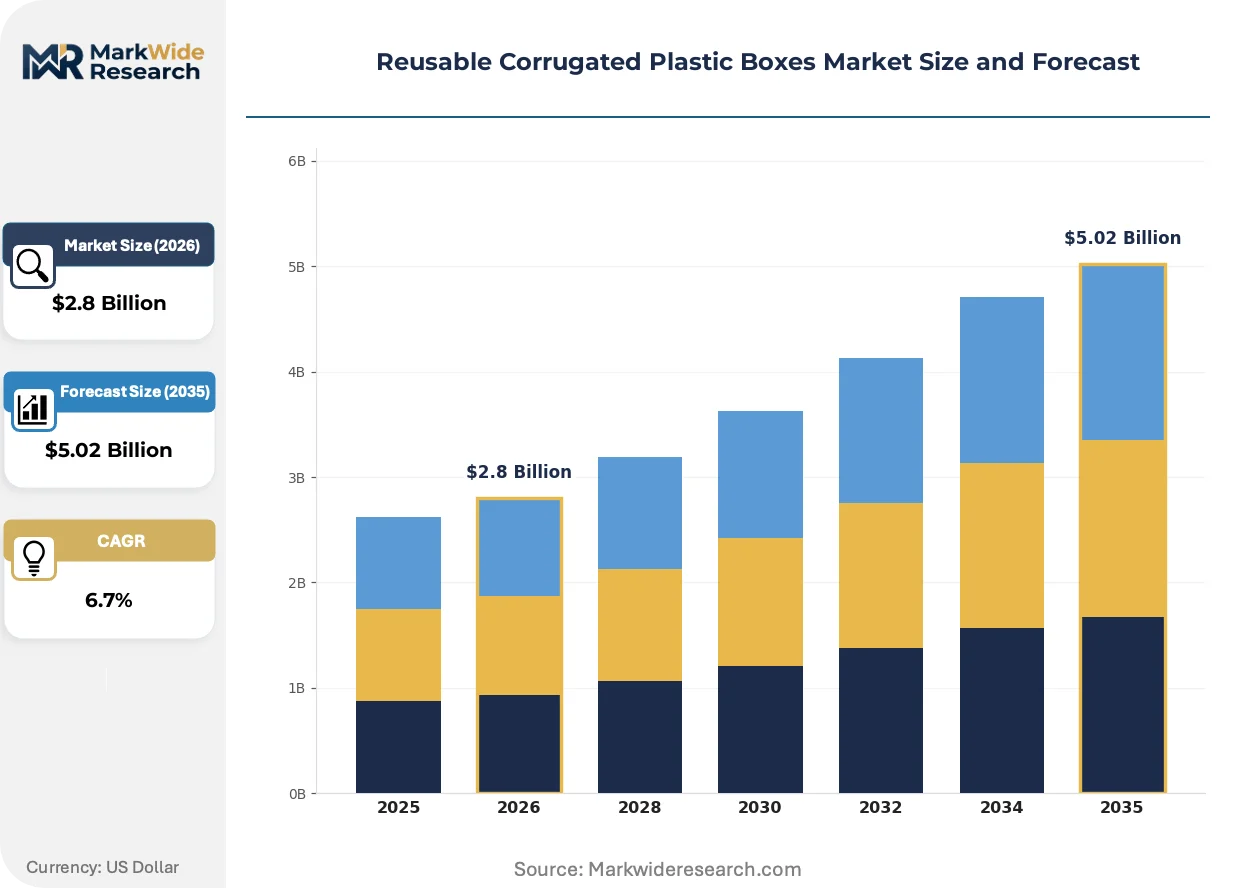
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Boxes, Stackable Containers, Pallet Boxes, Folding Boxes Application: Retail Packaging, Automotive Parts, Food Storage, Logistics End User: E-Commerce, Manufacturing, Food & Beverage, Pharmaceuticals Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributor |
| Companies Covered | MDI, ORBIS Corporation, Flex Container, Logimarkt, KISHOR PLASTIC, Technology Container Corp., Suzhou Huiyuan Plastic Products Co., Ltd, Kiva Container, New-Tech Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Corrugated Plastic Boxes Market Evolving Landscape
Material science advances and regulatory compliance automation are compressing product development cycles while expanding addressable applications beyond traditional automotive and food verticals.
Recycled-content twin-wall sheet is absorbing virgin polypropylene demand as FDA-validated post-industrial flake achieves structural parity in heavy-duty totes. Tier-one automotive suppliers in Stuttgart and Detroit have accelerated qualification of fifty-percent recycled-content boxes for non-structural parts sequencing. This substitution is compressing resin cost exposure while satisfying OEM sustainability scorecard requirements.
The EU Packaging and Packaging Waste Regulation mandates recyclability-by-design standards and reuse-target thresholds that reshape export packaging specifications. Manufacturers serving European retail accounts must now certify flute geometries and closure systems for automated sorting compatibility. Pharmaceutical shippers to the Netherlands and Germany face the strictest compliance timelines, driving investment in mono-material construction.
Buyer consolidation among third-party logistics providers is concentrating procurement authority at regional fleet managers who negotiate multi-year container-pooling agreements. Traditional distributor networks lose influence as direct manufacturer-to-pool-operator contracts displace spot purchasing. This restructuring is most visible in the Yangtze River Delta, where electronics contract manufacturers now source exclusively through certified pool operators.
Reusable Corrugated Plastic Boxes Market Segmentation
Segmentation in the reusable corrugated plastic boxes market reveals how upgrade cycles and replacement decisions vary by load rating, application intensity, and channel economics. Procurement managers prioritize durability specifications against trip-count targets, while channel structures determine fleet standardization versus spot purchasing.
Product Type:
Replacement-cycle timing diverges sharply across load ratings, with heavy-duty automotive totes running 50-100 rotations before retirement while folding boxes for e-commerce face compression damage at 30-40 trips.
- Heavy-Duty Boxes:Twin-wall polypropylene construction rated for 50-kilogram dynamic loads serves automotive parts sequencing in Stuttgart and Detroit assembly plants. OEM mandates for dimensional tolerances within 0.5 millimeters drive specification rigidity, though 20-week thermoforming mold lead times constrain supplier responsiveness.
- Folding Boxes:Collapsible twin-wall designs reduce backhaul cube by eighty percent versus rigid alternatives, capturing e-commerce returns infrastructure investment. Amazon and regional 3PLs in Germany and the Netherlands standardize on 600x400 millimeter footprints for automated sortation compatibility.
- Stackable Containers:FDA Title 21 CFR food-contact compliance governs washdown protocols for dairy and produce distribution, with closed-loop pooling networks in California's Central Valley and Florida's tomato belt demanding validated sanitation records.
- Pallet Boxes:Bulk agricultural harvesting in Mexico's Sinaloa corridor and Spain's Almeria province relies on 1200x1000 millimeter footprints for field-to-processor tomato and pepper transport, though wax-coated fiberboard persists in low-value commodity lanes.
Volume placements concentrate in heavy-duty boxes; the faster expansion belongs to folding boxes.
Application:
Cost-tier stratification separates premium validated systems from economy-grade alternatives, with automotive and pharmaceutical procurement commanding price premiums against agricultural bulk applications.
- Automotive Parts:Just-in-time sequencing mandates from BMW, Ford, and Volkswagen specify RFID-tracked twin-wall totes for door panels and dashboard assemblies. Tier-one suppliers in Mexico's Queretaro and the US Midwest absorb per-unit premiums for contamination-free delivery guarantees.
- Logistics:Third-party pooling operators deploy standardized container fleets across pharmaceutical distribution in the Netherlands and electronics contract manufacturing in China's Yangtze River Delta. Rotational efficiency metrics drive procurement decisions over upfront capital cost.
- Food Storage:Cold-chain dairy distribution in Wisconsin and New York state requires insulated twin-wall construction with phase-change lining integration, though FDA washdown validation adds fleet management complexity.
- Retail Packaging:European supermarket chains in France and Germany face EU Packaging and Packaging Waste Regulation reuse-target thresholds, accelerating qualification of mono-material corrugated plastic for produce display and backroom storage.
Revenue concentrates in automotive parts; retail packaging climbs the fastest on regulatory compliance deadlines.
End User:
Customer-type segmentation distinguishes between fleet-owning manufacturers and pool-dependent intermediaries, with ownership models dictating specification authority and replacement-cycle control.
- Manufacturing:Automotive OEMs and tier-one suppliers in Germany and the US Midwest operate captive container fleets with 7-10 year depreciation schedules. Direct manufacturer relationships with thermoformers like ORBIS and MDI displace distributor influence.
- E-Commerce:Returns infrastructure investment by Amazon, Zalando, and regional 3PLs drives folding-box standardization for last-mile cube reduction. Pooling network participation versus direct ownership varies by seasonal volume volatility.
- Food & Beverage:Dairy processors in California and Wisconsin and beverage distributors in Texas operate closed-loop sanitation protocols, with FDA Title 21 CFR compliance requiring validated washdown procedures at each rotation node.
- Pharmaceuticals:Biologics distribution in India faces CDSCO temperature-validation requirements, creating demand for insulated twin-wall shippers with integrated phase-change materials and real-time tracking.
Fleet ownership concentrates in manufacturing; the steepest expansion trajectory belongs to e-commerce on returns infrastructure buildout.
Distribution Channel:
Channel economics determine specification control, with direct sales enabling custom tooling investment while wholesale and distributor networks favor standardized footprints for inventory efficiency.
- Direct Sales:Automotive tier-one suppliers in Detroit and Stuttgart negotiate multi-year container-pooling agreements with integrated sheet-to-box producers. Captive resin compounding and regional molding networks anchor supply security.
- Distributor:Regional packaging distributors in the US Southeast and Midwest serve fragmented food processing and agricultural customers with standardized 600x400 and 1200x1000 millimeter footprints, sacrificing customization for availability.
- Wholesale:Volume purchasing cooperatives among Mexican agricultural exporters aggregate demand for pallet boxes, though specification standardization lags automotive and pharmaceutical precision requirements.
- Online Retail:Alibaba and regional B2B platforms serve small-batch purchasers in India's pharmaceutical and electronics sectors, with delivery reliability constraints limiting adoption for time-critical production schedules.
Contract value concentrates in direct sales; online retail gains share fastest among small-batch and emerging-market purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast propylene monomer supply anchors North American twin-wall sheet production, with automotive assembly corridors in Mexico and the US Midwest driving container demand density.
United States
Automotive OEMs in Detroit and tier-one suppliers across Michigan and Ohio specify RFID-tracked polypropylene totes for just-in-time sequencing. EPA Sustainable Materials Management priorities compress procurement timelines for certified reusable alternatives. Wisconsin and New York dairy processors operate closed-loop pooling networks with FDA-validated washdown protocols.
Germany
BMW and Volkswagen assembly plants in Stuttgart and Wolfsburg mandate exacting dimensional tolerances within 0.5 millimeters for parts sequencing containers. EU Packaging and Packaging Waste Regulation reuse-target thresholds accelerate qualification of mono-material corrugated plastic. The Netherlands and German pharmaceutical distribution corridor demands automated sortation-compatible footprints.
China
Electronics contract manufacturers in the Yangtze River Delta source exclusively through certified pool operators for container standardization. National dual carbon goals reshape resin sourcing strategies toward recycled-content validation. Suzhou and Shanghai thermoforming clusters serve domestic automotive and export packaging specifications.
Mexico
Queretaro automotive assembly plants absorb per-unit premiums for contamination-free twin-wall tote delivery from tier-one suppliers. The country's national environmental regulator advances extended producer responsibility frameworks favoring durable, trackable packaging. Sinaloa agricultural exporters aggregate pallet box demand through volume purchasing cooperatives for field-to-processor tomato transport.
India
CDSCO temperature-validation requirements for biologics distribution create demand for insulated twin-wall shippers with phase-change lining integration. The country's national pharmaceutical regulator tightens cold-chain compliance timelines for export qualification. Maharashtra and Gujarat pharmaceutical clusters drive fleet standardization among third-party logistics operators.
Reusable Corrugated Plastic Boxes Market Competitive Landscape
Global majors compete with regional champions across resin compounding and thermoforming capabilities, with integrated sheet-to-box producers commanding automotive tier-one supply security. The vendor base stratifies into three archetypes: captive resin compounders with regional molding networks, heavy-duty pooling specialists with proprietary flute geometries, and folding-box modularity competitors serving e-commerce reverse logistics. M&A activity concentrates around automotive sequencing mandates, while capacity expansion targets FDA-validated food-contact production lines.
Within the integrated production tier, ORBIS Corporation and MDI exemplify divergent strategic positioning—ORBIS anchors North American automotive supply through captive resin operations, while MDI occupies a position in heavy-duty agricultural and industrial pooling systems. Flex Container represents the folding-box modularity archetype competing on collapsibility for e-commerce returns infrastructure. Suzhou Huiyuan Plastic Products Co., Ltd. sits within the Asia-Pacific regional specialist tier serving electronics contract manufacturing demand.
| Leading Market Players |
|---|
| MDI |
| ORBIS Corporation |
| Flex Container |
| Logimarkt |
| KISHOR PLASTIC |
| Technology Container Corp. |
| Suzhou Huiyuan Plastic Products Co., Ltd |
| Kiva Container |
| New-Tech Packaging |
| Others |
Value Network & Pricing Analysis
Recycled-content twin-wall sheet qualification is compressing virgin polypropylene demand while concentrating procurement authority among integrated sheet-to-box producers with captive resin compounding capabilities. This production-method transition simultaneously reshapes cost economics across automotive tier-one supply agreements and extends supply concentration toward Gulf Coast petrochemical corridors.
Pricing Analysis
Multi-year container-pooling agreements bundle fleet management, RFID tracking infrastructure, and washdown validation services into contracted per-rotation fees rather than pure hardware transactions. Pricing stratifies across premium, standard, and economy tiers based on FDA Title 21 CFR compliance grade and customization depth for dimensional tolerances. Cost compression in standard-grade folding boxes is intensifying because e-commerce 3PLs aggregate volume through certified pool operators. Agricultural bulk purchasers exhibit highest price sensitivity, while pharmaceutical cold-chain distributors absorb premiums for temperature-validated systems.
Supply Chain Analysis
Dual-sourcing mandates from BMW and Volkswagen assembly plants require tier-one suppliers to qualify thermoforming capacity across at least two integrated producers with regional molding networks. Supply concentrates in Germany, the United States, and China, with extruded twin-wall sheet production drawing from Gulf Coast propylene monomer and Yangtze River Delta compounding clusters. Raw material dependencies rest on polypropylene resin, specialized thermoforming molds from Italian and German toolmakers, and RFID tracking modules. Single-source vulnerability in precision mold fabrication constrains capacity expansion. Distribution runs through direct manufacturer-to-pool-operator contracts displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation erects a formidable barrier-to-entry moat: non-compliant exporters forfeit European retail and manufacturing accounts, concentrating margin capture among validated mono-material producers.
For Market Incumbents: Acquire specialized thermoforming mold fabrication capacity to compress 20-week lead times and defend against emerging Asian entrants with government-backed resin subsidies. Anchor supply security through backward integration into post-industrial polypropylene flake processing for recycled-content validation. Prioritize FDA-validated food-contact production line expansion to capture dairy and produce distribution mandates. For New Entrants and Emerging Players: CDSCO temperature-validation requirements in India open a window for insulated twin-wall shippers with phase-change lining integration, a white-space segment underserved by established automotive-focused incumbents. Target Maharashtra and Gujarat pharmaceutical clusters through third-party logistics operator partnerships rather than direct manufacturer sales. Lead with real-time tracking integration as a differentiated service bundle. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated packaging conglomerates seeking automotive sequencing credentials. The five-to-ten year viability window favors targets with captive resin compounding and established OEM qualification records. Watch for EU Carbon Border Adjustment Mechanism implementation as an inflection signal accelerating lightweight packaging substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Flake Processing | Captive post-industrial polypropylene supply secures FDA-validated fifty-percent recycled-content qualification for automotive OEM scorecards. |
| RFID-Enabled Fleet Tracking Deployment | Real-time container location data enables rotational efficiency guarantees that win multi-year pharmaceutical pooling contracts. |
| Precision Thermoforming Mold Acquisition | In-house mold fabrication compresses lead times from twenty weeks and unlocks responsive capacity for just-in-time sequencing mandates. |
| EU Mono-Material Certification Investment | Automated sortation-compatible flute geometries preserve market access under Packaging and Packaging Waste Regulation reuse thresholds. |
| Pharmaceutical Cold-Chain Partnership | Phase-change lining integration with CDSCO validation opens biologics distribution revenue streams beyond saturated automotive verticals. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with automotive tier-one procurement directors, pharmaceutical logistics fleet managers, FDA compliance officers, thermoforming plant engineers, and third-party pooling operators. Bottom-up triangulation against top-down macroeconomic indicators validated shipment volumes and capacity utilization estimates across the projection horizon.
Data-stream reconciliation incorporated production capacity databases, resin price indices, and OEM container specification sheets to model segment-level demand. The analytical framework spanned product type, application intensity, end-user ownership model, and channel structure throughout the forecast period. CAGRs derived from replacement-cycle timing divergence across load ratings and regulatory compliance deadline acceleration. Industry-specific inputs included automotive sequencing mandate adoption curves and EU extended producer responsibility framework implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for recycled-content twin-wall sheet qualification at structural parity would alter the outlook for virgin polypropylene demand. Forecasts reflect documented assumptions regarding propylene monomer supply stability and thermoforming capacity expansion timelines. Deviation in EU Carbon Border Adjustment Mechanism enforcement intensity or FDA washdown protocol harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Reusable Food Wrap Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Reusable Consumer Packaging Market