
 Micro-Packaging Market | 2026-2036
Micro-Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Packaging Market Outlook
Modular single-dose configurations is hardening as the dominant purchasing logic across pharmaceutical and personal care channels. Amcor Plc leverages its film extrusion network to anchor high-barrier blister supply for regulated drug formats. Berry Global Inc. specializes in multi-layer rigid containers that sustain shelf-life claims for probiotic and active-ingredient portfolios. Sealed Air Corporation dominates vacuum-packaging equipment tied to micro-format food preservation lines.
Micro-packaging denotes primary and secondary containment systems engineered for unit doses below fifty milliliters, typically employing coextruded polymer films, cold-form aluminum laminates, or precision-molded thermoforms to deliver barrier control, tamper evidence, and patient compliance features. Flexible pouches lead volume in food sampling and condiment sachets while blister packs command premium positioning in pharmaceutical compliance packaging where child-resistance and senior-friendly access standards apply. Aluminum foil substrates capture margin pools in high-barrier pharmaceutical applications despite pressure from metallized film alternatives in cost-sensitive personal care segments.
The US FDA enforces unit-dose labeling and child-resistant packaging mandates that elevate testing costs for new market entrants. The EU Green Deal and REACH restrictions on per- and polyfluoroalkyl substances compel reformulation of grease-resistant coatings in paperboard micro-packaging. China's GB standards for food-contact materials and Japan's METI recycling directives add compliance layers for multinational suppliers. Stakeholders must decide whether to absorb certification costs across multiple regulatory regimes or concentrate capacity in jurisdictions with mutual recognition agreements.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is forcing material recovery targets upward, compelling converters to redesign multi-layer laminates for recyclability while maintaining barrier performance for pharmaceutical unit-dose formats.
Growth Catalysts
- REACH restrictions on PFAS:The EU's per- and polyfluoroalkyl substance bans are accelerating migration toward fluorine-free barrier coatings in paperboard micro-packaging for food-contact applications.
- Pharmaceutical compliance packaging:FDA unit-dose labeling mandates and child-resistant packaging requirements are elevating demand for precision-molded blister packs with tamper-evident features.
- Germany's precision manufacturing corridor:Concentrated demand from automotive and industrial chemical sectors for high-barrier single-dose lubricant and adhesive sachets sustains specialized film extrusion capacity.
Market Restraints
- Aluminum foil price volatility:Cold-form aluminum laminates for pharmaceutical blister packs face input cost pressure from energy-intensive smelting operations concentrated in specific geographies.
- Multi-layer film recyclability:Coextruded polymer structures combining EVOH, nylon, and polyethylene lack economically viable mechanical recycling pathways under current EU waste directives.
- Metallized film substitution:Vacuum-deposited aluminum on polyester substrates is capturing share in cost-sensitive personal care sachets, compressing margins for traditional foil converters.
Strategic Opportunities
- China's GB standards compliance:Food-contact material regulations are creating certified-supplier premiums for multinational converters able to navigate dual carbon goals and SAMR registration requirements.
- Biodegradable barrier films:PLA and PHA-based structures with oxygen scavenging functionality are converging with home-composting certification schemes for single-serve condiment and sampling applications.
- Direct-to-patient pharmacy channels:Mail-order pharmaceutical dispensing is expanding demand for senior-friendly blister formats with integrated compliance tracking and temperature assurance.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and PMDA filings for novel drug-device combination packaging extend time-to-revenue by eighteen to thirty-six months.
- Legacy thermoforming asset retrofit:Converting existing forming stations for recyclable mono-material PET or PP formats requires substantial capital for mold redesign and sealing temperature recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Packaging Market |
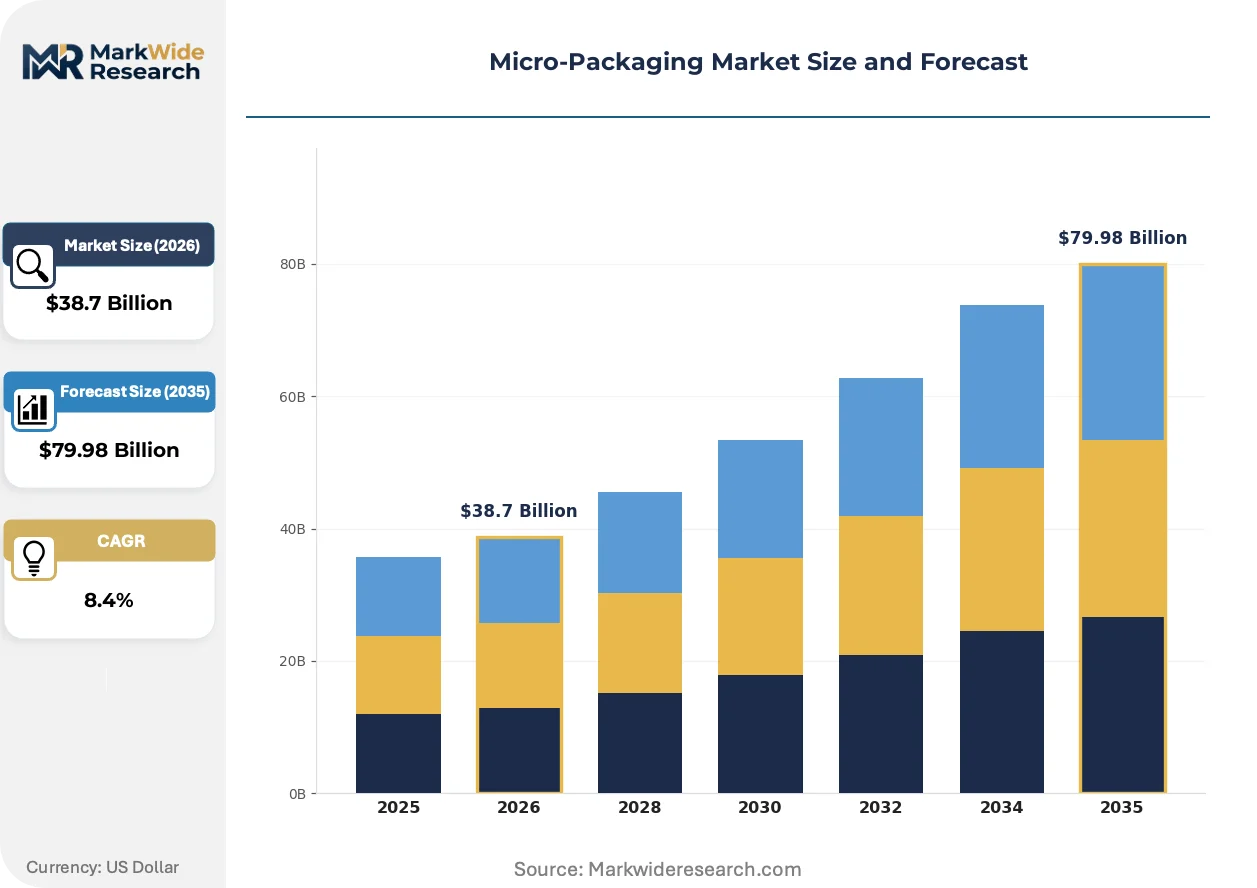
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Pouches, Blister Packs, Rigid Containers, Micro Containers Material: Plastic Films, Glass, Paperboard, Aluminum Foil End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Packaging Type: Shrink Sleeves, Vacuum Packaging, Pressure Sensitive Labels, Others |
| Companies Covered | Amcor Plc, Berry Global Inc., Avery Dennison Corporation, Sealed Air Corporation, Tetra Pak International S.A., Mondi Plc, 3M Company, Uflex Ltd., CCL Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Packaging Market Strategic Shifts
Digital printing and connected packaging technologies are converging with sustainability mandates to reshape how micro-format containment systems communicate compliance, provenance, and disposal instructions to end-users.
Mono-material polypropylene structures with plasma-enhanced barrier coatings are converging with pharmaceutical blister applications previously reserved for aluminum laminates. European generics manufacturers are piloting these formats for moisture-sensitive solid oral dosages. The technology is converging with metallized film cost structures while preserving the senior-friendly opening features required by aging patient populations.
Japan's METI recycling directives now mandate explicit material identification markings on all primary packaging below fifty milliliters. This policy is accelerating adoption of near-infrared detectable black pigments and standardized resin coding across imported personal care sachets. Premium cosmetic brands targeting Japanese distribution channels are reformulating multi-layer pouches to achieve single-polymer classification.
Hospital and long-term care procurement teams are consolidating supplier relationships around vendors offering integrated compliance packaging with embedded NFC tags for medication adherence monitoring. This consolidation is displacing fragmented purchasing of commodity blister packs across individual pharmacy departments. The shift is most pronounced in Germany and the Netherlands where insurer reimbursement models reward measurable patient outcomes.
Micro-Packaging Market Segmentation
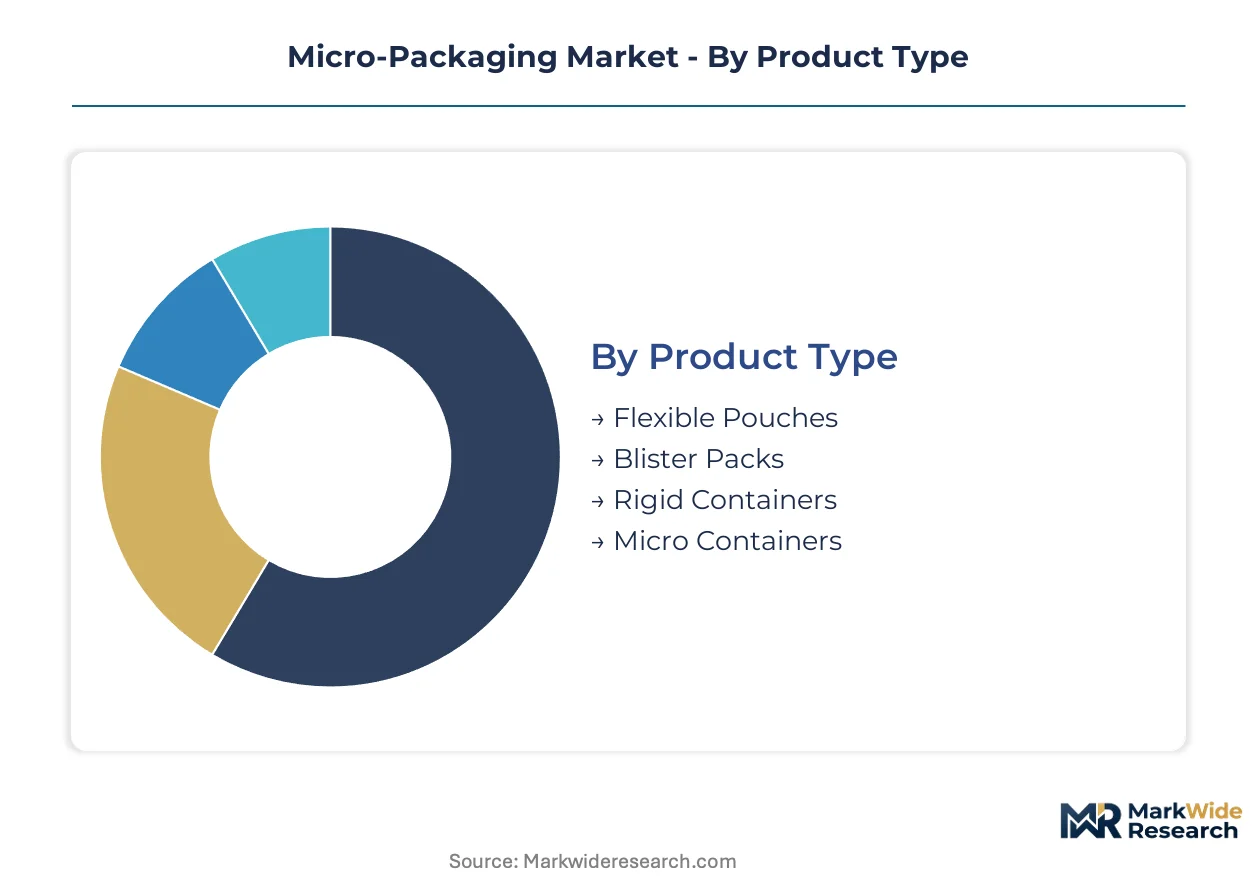
Micro-packaging segmentation reveals divergent margin structures across pharmaceutical compliance formats and commodity food sachets. Material choices and barrier specifications create distinct competitive arenas with incompatible manufacturing assets and certification requirements.
Product Type:
Volume leadership sits with flexible formats, while premium positioning clusters around pharmaceutical-grade barrier systems.
- Flexible Pouches:Coextruded polymer laminates dominate condiment, sampling, and single-serve food applications where cost-per-unit drives procurement decisions. Demand concentrates in North American quick-service restaurant supply chains and European retail private-label programs, with REACH-compliant fluorine-free barrier coatings now mandatory for EU-bound shipments.
- Blister Packs:Cold-form aluminum and thermoformed PVC/PVDC structures deliver tamper-evidence, child-resistance, and senior-friendly access for regulated drug formats. Germany's precision manufacturing corridor and the US Southeast pharmaceutical cluster sustain dedicated thermoforming capacity, with FDA unit-dose labeling mandates elevating testing costs for new entrants.
- Rigid Containers:Multi-layer injection-molded formats preserve probiotic viability and active-ingredient stability in personal care applications.
- Micro Containers:Precision-molded vials and ampoules serve diagnostic reagent and high-value cosmetic sample markets.
Mature deployment sits with Flexible Pouches. Newer deployment is concentrated in Blister Packs with integrated compliance tracking features.
Material:
Barrier performance requirements stratify procurement across pharmaceutical, food-contact, and cosmetic end-uses with divergent regulatory burdens.
- Plastic Films:Mono-material PP and PET structures with plasma-enhanced coatings are displacing multi-layer laminates in recyclable pharmaceutical blister pilots. European generics manufacturers and Japanese cosmetic brands drive adoption, with METI recycling directives mandating near-infrared detectable pigments for sub-fifty-milliliter formats.
- Aluminum Foil:Cold-form laminates capture margin pools in high-barrier pharmaceutical applications despite energy-intensive smelting cost pressure. Demand from moisture-sensitive solid oral dosages and transdermal patches sustains specialized converting capacity in Germany and Switzerland.
- Glass:Borosilicate and neutral pH formats serve parenteral and high-value cosmetic sampling where inertness outweighs fragility costs.
- Paperboard:Grease-resistant micro-flute and folding carton structures face PFAS-driven reformulation pressure under EU Green Deal restrictions.
Glass maintains entrenched positions in parenteral formats. Paperboard is gaining share fastest in home-compostable single-serve food applications.
End User:
Regulatory intensity and patient safety liability create order-of-magnitude pricing spreads between pharmaceutical and food-contact segments.
- Pharmaceuticals:Unit-dose compliance packaging with embedded NFC adherence tracking commands premium positioning. Hospital procurement consolidation in Germany and the Netherlands favors integrated suppliers over fragmented commodity blister vendors, with insurer reimbursement models rewarding measurable patient outcomes.
- Food & Beverage:Condiment sachets, sampling formats, and single-serve portions drive volume through quick-service and retail channels. China's GB standards for food-contact materials create certified-supplier premiums for converters navigating SAMR registration and dual carbon goals.
- Personal Care:Active-ingredient protection and shelf-life claims sustain multi-layer rigid container demand for probiotic and retinol formulations.
- Electronics:Anti-static and moisture-barrier formats serve semiconductor and precision component shipping requirements.
Food & Beverage represents the volume anchor. Pharmaceuticals deliver the steepest expansion trajectory through direct-to-patient pharmacy channels.
Packaging Type:
Equipment integration requirements and line speed specifications determine converter specialization and customer switching costs.
- Vacuum Packaging:Thermoform-fill-seal systems with modified atmosphere capabilities preserve micro-format food portions. Sealed Air Corporation and European equipment specialists dominate installed base in protein and prepared meal segments.
- Shrink Sleeves:Full-body printed films deliver 360-degree branding and tamper-evidence for beverage and cosmetic samples.
- Pressure Sensitive Labels:Unit-dose pharmaceutical labeling with Braille and traceability coding satisfies FDA and EMA mandates.
- Others:Stretch wrap, cling film, and specialty formats for irregular geometries.
Vacuum Packaging holds established deployment in protein preservation. Pressure Sensitive Labels are expanding most quickly through track-and-trace pharmaceutical mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany's precision manufacturing corridor and Switzerland's pharmaceutical converting belt, while consumption spreads across regulated pharmaceutical markets and food-service channels in North America and Asia-Pacific.
Germany
Automotive and industrial chemical sectors sustain demand for high-barrier single-dose lubricant and adhesive sachets. The EU's Packaging and Packaging Waste Regulation tightens material recovery targets for multi-layer laminates. Stuttgart-Mannheim corridor hosts specialized film extrusion capacity serving precision dosing formats.
United States
Pharmaceutical unit-dose compliance packaging and quick-service restaurant condiment supply chains drive procurement volumes. FDA unit-dose labeling and child-resistant packaging mandates elevate testing costs for new market entrants. New Jersey-Pennsylvania pharmaceutical cluster sustains dedicated thermoforming infrastructure for regulated drug formats.
China
Food-contact material regulations and expanding retail private-label programs create certified-supplier premiums. GB standards for food-contact materials and SAMR registration requirements add compliance layers for multinational suppliers. Yangtze River Delta concentration of converting capacity serves both domestic consumption and export markets.
Japan
METI recycling directives mandate explicit material identification markings on primary packaging below fifty milliliters. Near-infrared detectable black pigments and standardized resin coding accelerate across imported personal care sachets. Kansai-Osaka region maintains precision molding capacity for cosmetic sampling formats.
Switzerland
High-barrier pharmaceutical applications for moisture-sensitive solid oral dosages sustain specialized converting capacity. Swissmedic regulatory requirements align with EMA standards for unit-dose compliance packaging. Basel-Zurich corridor anchors cold-form aluminum laminate production for transdermal patch formats.
Micro-Packaging Market Competitive Environment
The competitive structure tilts toward integrated material converters with captive film extrusion networks. Tier-one players combine high-barrier material science with pharmaceutical certification infrastructure, while mid-scale specialists concentrate on mono-material recyclable formats for cost-sensitive segments. Strategic moves center on backward integration into polymer resin compounding and selective licensing of plasma-enhanced coating technologies.
Within the integrated packaging tier, Amcor Plc and Berry Global Inc. occupy positions spanning flexible films and rigid container formats. Sealed Air Corporation exemplifies the equipment-integrated archetype, anchoring vacuum-packaging system supply for micro-format food preservation lines. These three represent distinct capability configurations: film-network dominance, multi-layer rigid specialization, and thermoform-fill-seal equipment integration.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Avery Dennison Corporation |
| Sealed Air Corporation |
| Tetra Pak International S.A. |
| Mondi Plc |
| 3M Company |
| Uflex Ltd. |
| CCL Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
Aluminum ingot and polymer resin feedstock costs cascade through three distinct pricing tiers for micro-packaging converters, with cold-form pharmaceutical laminates commanding premiums over commodity food sachets due to energy-intensive smelting concentration in specific geographies and multi-jurisdiction certification burdens.
Pricing Analysis
Margin tightening in pharmaceutical blister formats reflects aluminum foil price volatility from energy-intensive smelting operations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified unit-dose compliance packs from REACH-compliant food-contact laminates and unregulated sampling sachets. Cost-down pressure on commodity flexible pouches accelerates because metallized film substitutes capture share in personal care segments. Quick-service restaurant procurement teams exhibit highest price sensitivity, while hospital pharmacy consolidations in Germany and the Netherlands absorb premiums for integrated compliance packaging with embedded adherence tracking.
Supply Chain Analysis
Dual-sourcing mandates from pharmaceutical OEMs require qualified film extrusion capacity in both Germany and Switzerland, compelling converters to maintain redundant thermoforming lines across the Stuttgart-Mannheim and Basel-Zurich corridors. Raw material dependencies center on biaxially oriented polypropylene, ethylene vinyl alcohol copolymers, and cold-rolled aluminum coil. Single-source vulnerability concentrates in specialized EVOH resin compounding. Distribution runs through converter-direct relationships with pharmaceutical packaging departments and food-service distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized thermoforming capacity for pharmaceutical-grade blister packs operates at effective utilization ceilings, propping pricing power for converters with captive film extrusion and multi-jurisdiction certification infrastructure.
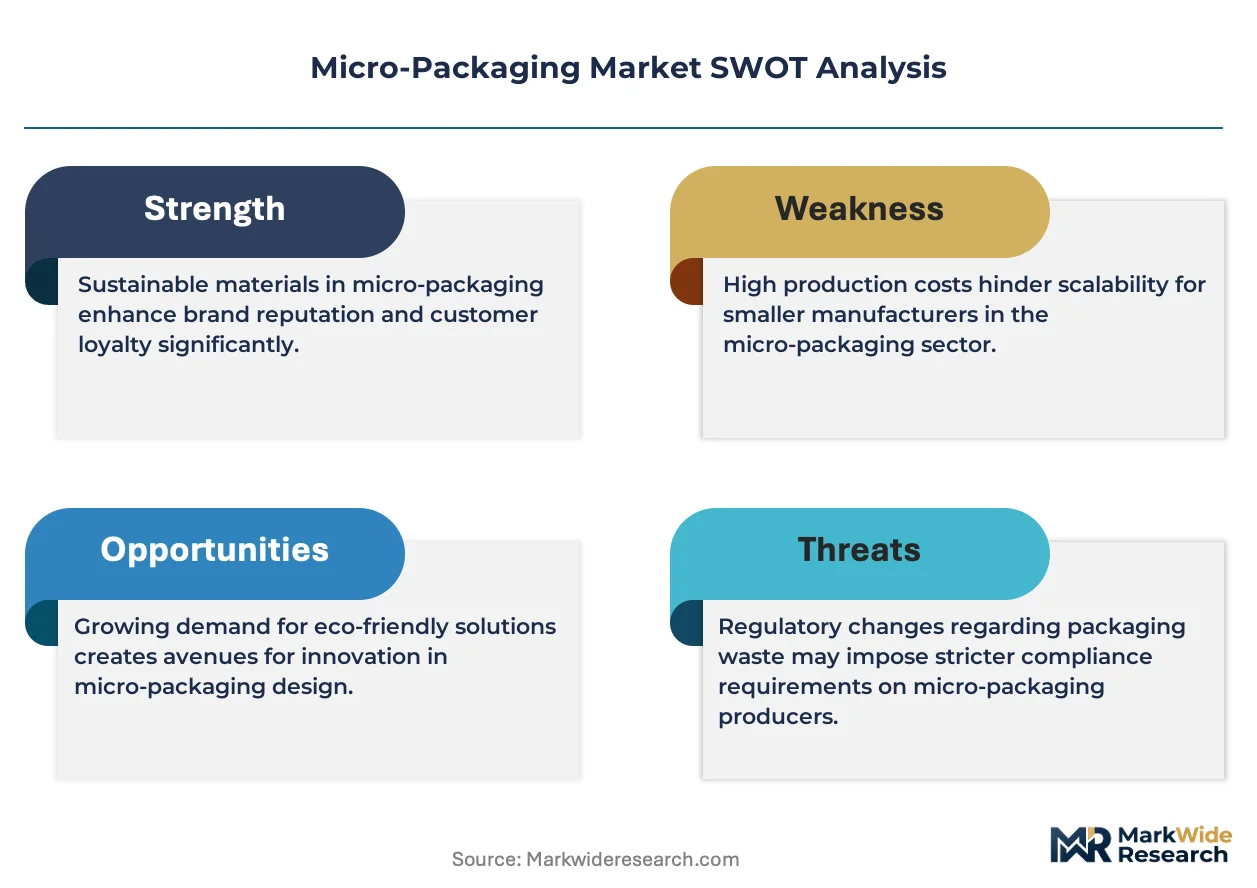
For Market Incumbents: To counter metallized film substitution in cost-sensitive personal care sachets, backward integration into polymer resin compounding secures feedstock cost control, while selective licensing of plasma-enhanced barrier coating technology defends premium positioning against mono-material recyclable alternatives. For New Entrants and Emerging Players: Enter via biodegradable barrier film segments for home-compostable single-serve food applications, where PLA and PHA-based structures with oxygen scavenging functionality face limited incumbent concentration. China's GB standards compliance for food-contact materials offers the most penetrable entry point, with certified-supplier premiums rewarding converters who navigate SAMR registration and dual carbon goals alongside multinational competitors. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale mono-material specialists in European jurisdictions with mutual recognition agreements for pharmaceutical packaging certifications. Long-term viability hinges on recyclability-aligned asset bases capable of serving tightening EU Packaging and Packaging Waste Regulation targets. Watch for inflection signals in hospital procurement consolidation velocity across Germany and the Netherlands, where insurer reimbursement models rewarding measurable patient outcomes accelerate integrated supplier preference over fragmented commodity vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Compounding | Captive EVOH and PP supply secures margin control against volatile petrochemical feedstock markets. |
| Plasma-Enhanced Barrier Coating Licensing | Mono-material PET and PP structures with enhanced barriers displace aluminum laminates in moisture-sensitive dosages. |
| Biodegradable Film Certification Investment | Home-compostable PLA and PHA formats capture emerging single-serve condiment demand under EU Green Deal. |
| Multi-Jurisdiction Certification Infrastructure | Simultaneous FDA, EMA, and PMDA qualification capabilities accelerate time-to-revenue for novel drug-device combinations. |
| Integrated Compliance Packaging with NFC Embedding | Embedded adherence tracking aligns with hospital procurement consolidation and insurer outcome-based reimbursement in Germany. |
Study Parameters
Trade databases, regulatory filing repositories, and industry association publications formed the secondary backbone, supplemented by primary interviews with pharmaceutical packaging engineers, food-contact material compliance officers, thermoforming equipment specialists, and hospital procurement directors. Bottom-up segment sizing across product type, material, end user, and packaging type dimensions combined with top-down macro validation to establish market boundaries.
Historical trendline analysis of pharmaceutical unit-dose adoption rates and food-service sampling format deployment informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, material barrier specification, end-use regulatory intensity, and regional certification cluster. CAGRs derived from slope analysis of volume and value trajectories, calibrated against aluminum foil price indices and polymer resin cost curves.
Revisions become necessary when REACH PFAS restriction timelines accelerate, China's SAMR registration requirements tighten, or hospital procurement consolidation patterns shift materially. Deviation in aluminum smelting energy costs or EU mechanical recycling infrastructure deployment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Greenwrap Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Reverse Logistics for Reusable Packaging and Containers Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Reusable Straw Market