
 Tea Packing Machine Market | 2026-2036
Tea Packing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Packing Machine Market Analytics
Specialty and premium tea retail is decoupling from traditional bulk loose-leaf distribution, pulling investment toward precision dosing and hermetic sealing equipment. Ishida leverages its gravimetric technology leadership to anchor high-speed weighing modules in Japanese and Southeast Asian tea factories. Krones AG sustains geographic dominance across European black tea co-packers through integrated rinsing-filling-sealing lines. Syntegon Technology differentiates in the sachet and pyramid tea bag segment with ultrasonic sealing systems that reduce film waste.
A tea packing machine is an electromechanical system designed to meter, form, fill, and seal tea into primary packages at speeds ranging from 30 to 600 units per minute, using heat-sealable filter paper, laminates, or biodegradable films depending on the infusion format. Its commercial purpose centers on preserving volatile aromatic compounds, preventing moisture ingress, and ensuring portion consistency for retail and foodservice channels. Vertical machines occupy the largest installed base among product types due to their compact footprint and compatibility with both tea bags and loose-leaf pouches. Multi-lane machines represent the fastest-growing configuration as contract packers seek throughput multiplication without proportional floor space expansion. Fully automated systems command the deepest margin pools because they integrate check-weighing, metal detection, and serialization in a single line.
The FDA enforces 21 CFR Part 110 for current Good Manufacturing Practice in food packaging facilities, directly shaping stainless steel specifications and clean-in-place protocols for tea contact surfaces. EFSA guidance on food contact materials and the EU Packaging and Packaging Waste Regulation constrain film composition choices, pushing OEMs toward mono-material and compostable sealant development. India's FSSAI mandates label integrity and net quantity verification, compelling domestic machine builders to incorporate vision-based inspection modules. Stakeholders must monitor how diverging biodegradability timelines across these jurisdictions reshape equipment upgrade cycles and aftermarket retrofit demand.
Market Dynamics
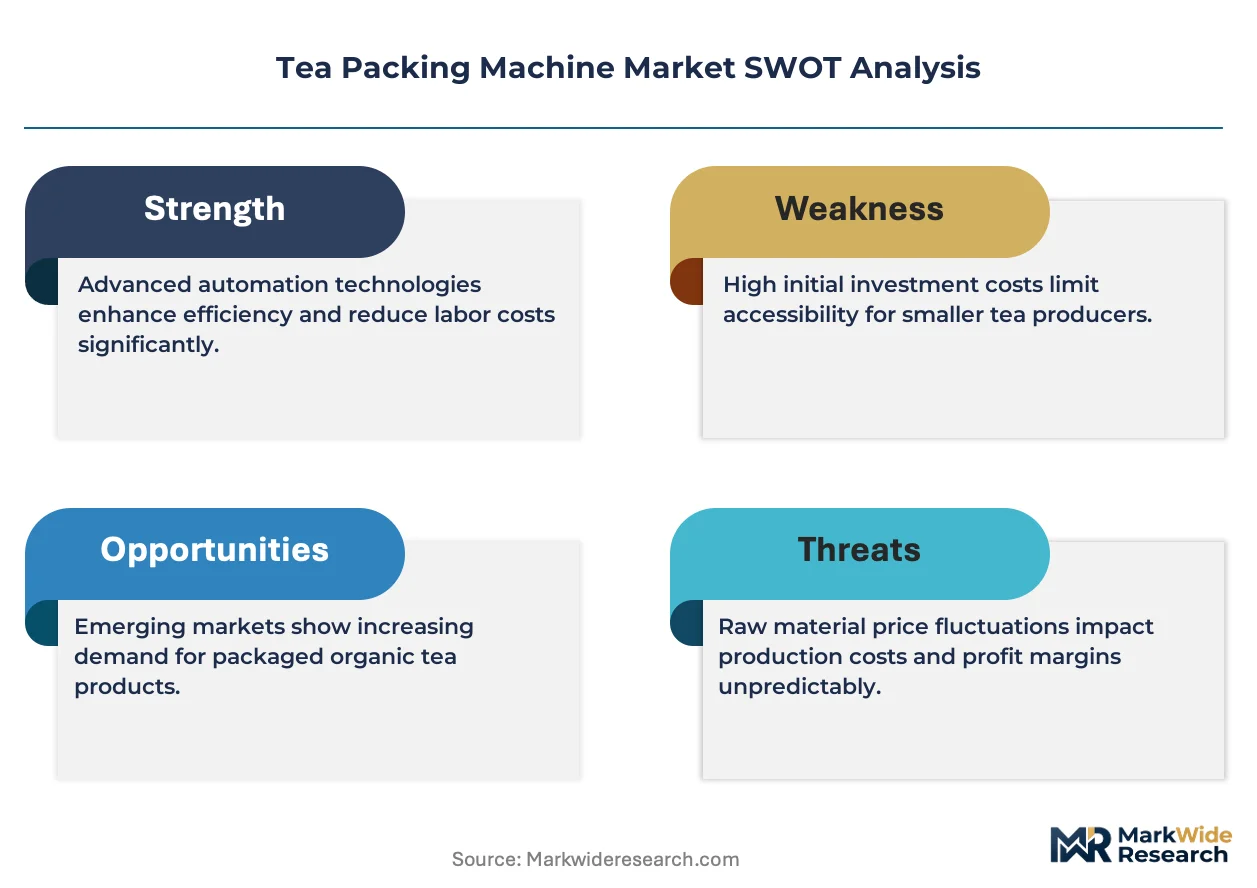
Specialty tea brands are forcing equipment upgrades as hermetic sealing and nitrogen flushing displace conventional packaging for volatile aromatic preservation. Contract packers face simultaneous pressure from FDA hygiene mandates and EFSA film composition rules, compressing procurement timelines for stainless steel lines with integrated metal detection.
Growth Catalysts
- EFSA Food Contact Material Guidance:European regulators are tightening migration limits on multilayer films, compelling packers to source ultrasonic sealing systems that eliminate adhesive layers and reduce compliance testing burden.
- Pyramid Tea Bag Format Expansion:Premium loose-leaf presentation in three-dimensional sachets is pulling investment toward multi-lane machines with servo-driven forming collars that handle non-woven filter materials.
- China Domestic Modernization:Provincial tea processors in Zhejiang and Fujian are retiring manual filling stations for automated vertical form-fill-seal lines to serve both local consumption and export certification requirements.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L sheet and sanitary tubing price swings compress OEM margins on hygienic machine frames, particularly for mid-capacity builders without long-term metallurgy contracts.
- Sealing Component Supply Concentration:Precision ceramic heater bands and PTFE-coated sealing jaws concentrate among Japanese and German component suppliers, creating lead time vulnerability for machine builders in India and Southeast Asia.
- Biodegradable Film Performance Gap:Compostable sealant layers derived from polylactic acid exhibit inferior moisture barrier properties versus conventional laminates, limiting their deployment in high-humidity climates without secondary overwrap.
Strategic Opportunities
- India Contract Packing White Space:Domestic specialty chai and herbal blend brands lack access to multi-lane sachet capacity, creating demand for toll packing services that European and Japanese OEMs can serve through local assembly partnerships.
- 21 CFR Part 11 Electronic Records Convergence:FDA digital traceability requirements for pharmaceutical-grade food facilities are pulling tea packers toward machines with built-in serialization and batch record integration, opening aftermarket software retrofit demand.
- Direct-to-Consumer Subscription Channels:Small-batch tea curators require micro-lot packing flexibility that conventional high-speed lines cannot deliver, creating niche demand for compact tabletop machines with quick-change tooling.
Industry Challenges
- Servo Motion Programming Talent Scarcity:Multi-axis forming and sealing sequences require specialized automation engineers that machine builders and end-users struggle to recruit in secondary manufacturing clusters.
- Legacy Pneumatic System Integration Friction:Brownfield tea facilities with compressed air infrastructure face complex retrofitting when upgrading to all-electric servo drives for precision dosing.
- Organic Certification Audit Trail Complexity:USDA NOP and EU organic handling requirements demand segregated production lines and cleaning validation documentation that stretches commissioning timelines for multi-product packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Packing Machine Market |
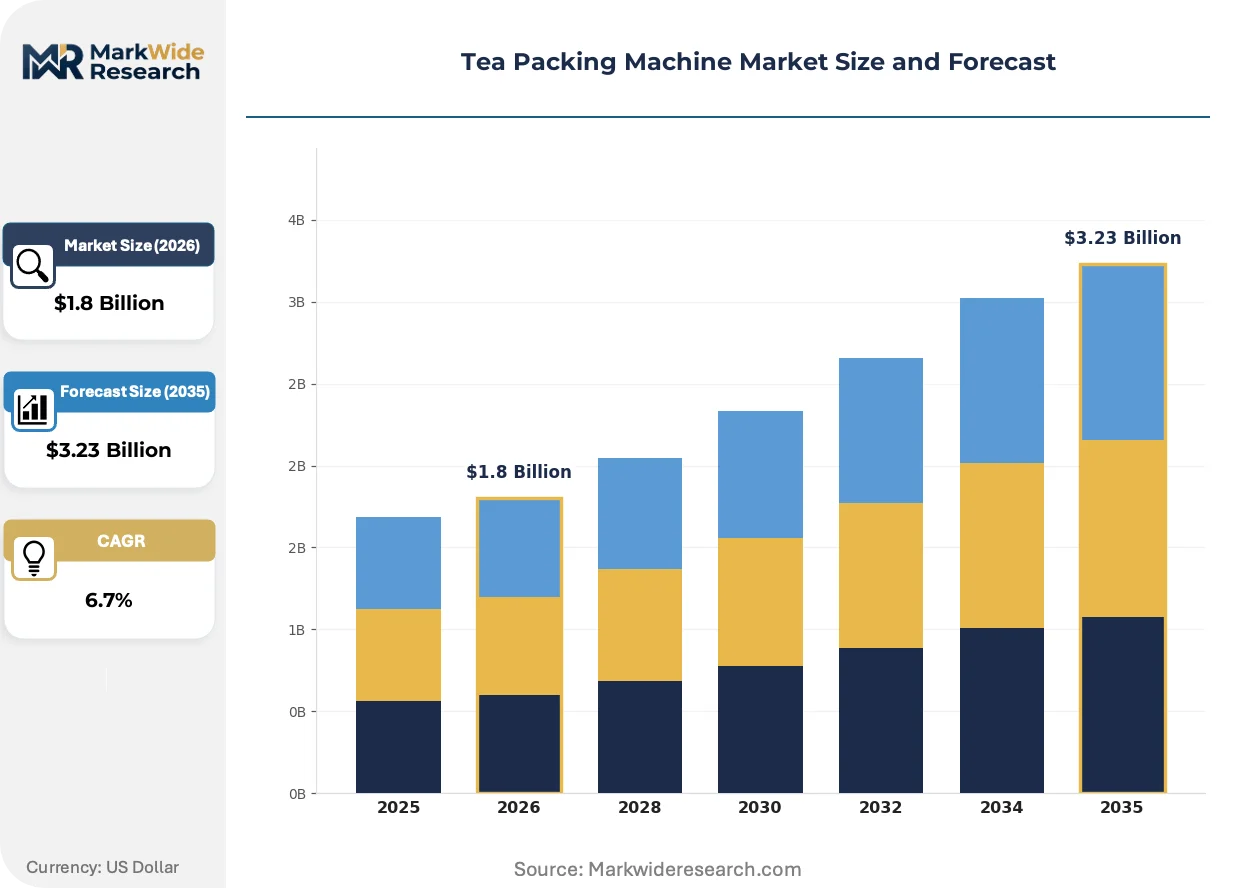
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Machines, Horizontal Machines, Multi-Lane Machines, Automatic Machines End User: Tea Manufacturers, Food Processors, Retailers, Online Vendors Packaging Type: Tea Bags, Loose Leaf Packaging, Jars, Sachets Automation Level: Fully Automated, Semi-Automated, Manual, Customized Solutions |
| Companies Covered | Ishida, Krones AG, IMA Group, Coesia Group, MULTIVAC, Syntegon Technology, ULMA Packaging, Kenwei, Tetra Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Packing Machine Market Evolving Landscape
Machine intelligence and material science are converging to compress changeover times and eliminate film waste. Packagers now demand equipment that self-optimizes for batch size variation while satisfying divergent biodegradability mandates across destination markets.
Vision-guided robotic pick-and-place systems are automating the feeding of delicate pyramid tea bags into cartons at speeds matching conventional vertical machines. Japanese and Korean specialty brands are adopting these cells to preserve leaf integrity in premium presentations. The technology is automating quality inspection tasks previously requiring manual sampling, reducing labor headcount in high-wage manufacturing environments.
REACH restrictions on per- and polyfluoroalkyl substances are forcing European OEMs to reformulate non-stick coatings on sealing jaws and replace PTFE-based solutions with ceramic or silicone alternatives. The regulatory pressure is accelerating R&D collaboration between machine builders and chemical suppliers. Black tea co-packers in Germany and the Netherlands face the steepest retrofit burden as existing coating inventories deplete.
Small-batch procurement patterns are fragmenting equipment demand as craft tea brands reject minimum order quantities imposed by legacy contract packers. Regional co-manufacturing networks in California and Victoria are installing modular lines with 15-minute tooling swaps to capture this volume. The shift is most visible in cold-brew and functional tea segments where formulation turnover exceeds seasonal rotation cycles.
Tea Packing Machine Market Segmentation
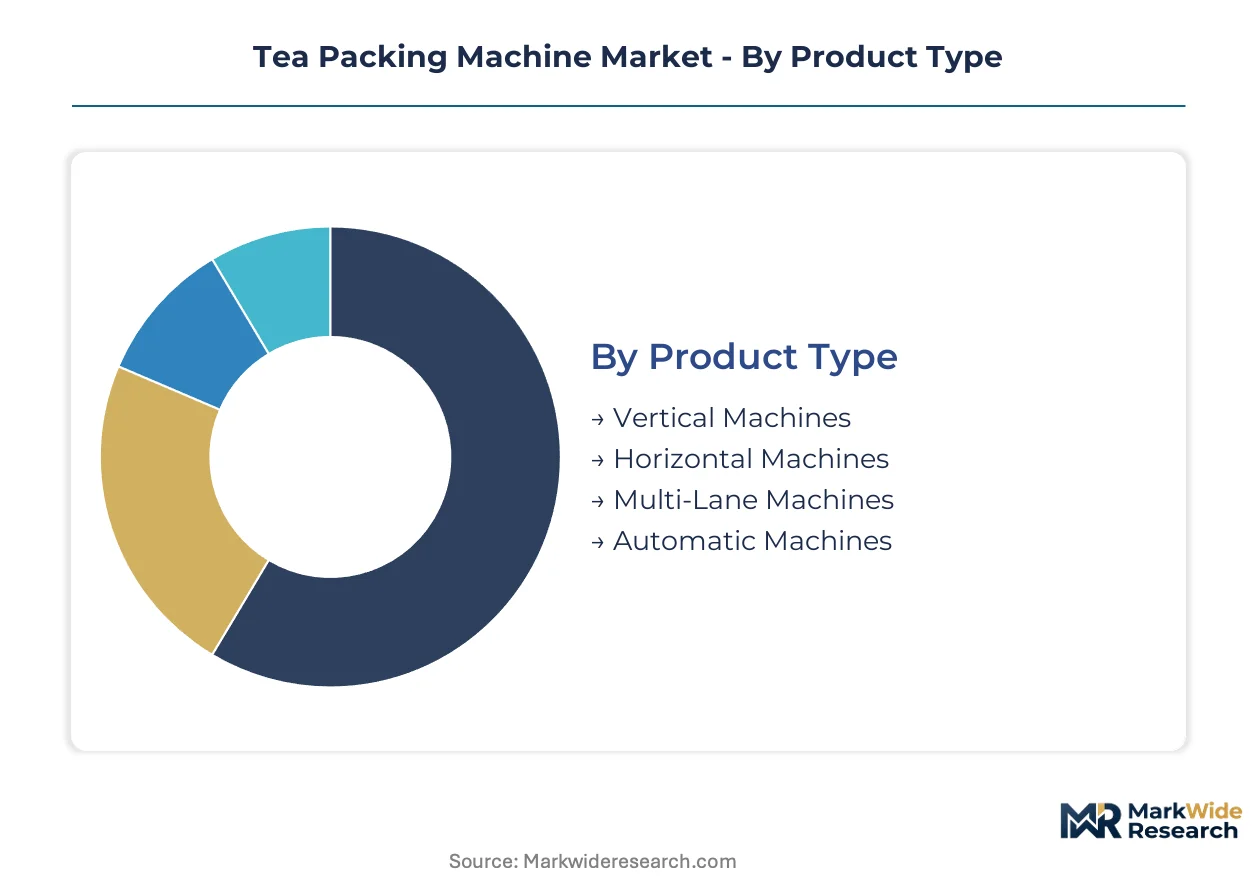
Equipment specification varies sharply across tea packing applications, with certification requirements from FDA, EFSA, and FSSAI dictating stainless steel grades and sealing protocols for each configuration. Understanding segment boundaries helps procurement teams align capital expenditure with volume targets and regulatory exposure.
Product Type:
FDA 21 CFR Part 110 compliance shapes stainless steel specifications across all configurations, with EFSA migration limits further constraining film-handling components in European-bound equipment.
- Vertical Machines:These units form, fill, and seal pouches from a continuous roll of film using a vertical forming tube and jaw-sealing mechanism. Chinese processors in Zhejiang and Fujian are retiring manual stations for these systems to meet export certification requirements. Vertical machines sit at the top of the volume ranking, with multi-lane machines climbing the fastest.
- Multi-Lane Machines:Parallel forming stations multiply throughput without proportional floor space expansion, using servo-driven collars to handle non-woven filter materials for pyramid tea bags. Specialty brands in Japan and Korea are accelerating adoption for premium loose-leaf presentation.
- Horizontal Machines:Side-seal configurations accommodate pre-made bags and cartons for retail-ready formats, common in European black tea co-packing operations.
- Automatic Machines:Integrated lines combine weighing, filling, sealing, and inspection in continuous operation, commanding premium positioning for pharmaceutical-grade food facilities.
Cost tiering separates compact vertical units from capital-intensive automatic lines, with mid-capacity processors clustering in the vertical-to-multi-lane transition zone.
End User:
Customer type determines batch size flexibility requirements and audit trail complexity, with organic certification demands concentrated among specialty manufacturers.
- Tea Manufacturers:Integrated producers from raw leaf through retail package require segregated organic handling lines and USDA NOP documentation, stretching commissioning timelines. Indian domestic brands lack access to multi-lane sachet capacity, creating toll packing white space.
- Food Processors:Diversified co-manufacturers serving multiple beverage categories prioritize 15-minute tooling swaps for formulation turnover exceeding seasonal cycles.
- Retailers:Private-label packagers for supermarket chains emphasize hermetic sealing and nitrogen flushing to preserve volatile aromatics through extended shelf life.
- Online Vendors:Direct-to-consumer subscription curators demand micro-lot flexibility that conventional high-speed lines cannot deliver, driving compact tabletop demand.
Tea manufacturers anchor installed base volume, with online vendors expanding most quickly as subscription channels fragment procurement patterns.
Packaging Type:
Material science constraints from REACH and EFSA regulations are forcing coating reformulations that affect sealing jaw compatibility across formats.
- Tea Bags:Heat-sealable filter paper and non-woven materials require precision temperature control to prevent fiber tear, with ultrasonic sealing systems eliminating adhesive layers for European compliance.
- Sachets:Three-dimensional pyramid formats use servo-driven forming collars for premium loose-leaf presentation, expanding fastest among Japanese and Korean specialty brands.
- Loose Leaf Packaging:Pouch and bag-in-box configurations preserve leaf integrity for bulk foodservice and retail channels.
- Jars:Rigid container lines integrate capping and induction sealing for gift and specialty retail segments.
Tea bags retain dominant volume share, with sachets gaining share fastest as premium positioning accelerates.
Automation Level:
21 CFR Part 11 electronic records requirements are pulling pharmaceutical-grade facilities toward built-in serialization and batch record integration.
- Fully Automated:Integrated check-weighing, metal detection, and vision inspection command deepest margin pools, with FSSAI label integrity mandates compelling Indian builders to incorporate vision modules.
- Semi-Automated:Hybrid configurations balance labor and capital for mid-volume processors modernizing from manual operations.
- Manual:Basic filling and sealing stations persist in artisanal and developing-market contexts with limited capital access.
- Customized Solutions:Application-specific engineering addresses unique film compositions or regulatory jurisdictions, common in organic and export-certified operations.
Fully automated systems lead volume deployment, with customized solutions showing steepest expansion trajectory as regulatory divergence multiplies configuration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment procurement as tea processors migrate production toward jurisdictions with lower compliance burdens or stronger domestic subsidy programs. Cost-of-compliance gaps between FDA-enforced facilities and emerging-market alternatives are accelerating cross-border investment flows.
China
Provincial processors in Zhejiang and Fujian are retiring manual filling stations for automated vertical form-fill-seal lines to meet export certification requirements. SAMR food contact material standards and GB hygiene mandates are tightening stainless steel specifications for domestic equipment builders. Hangzhou and Xiamen industrial clusters are absorbing the bulk of modernization capital as regional brands scale for European and North American private-label contracts.
United States
Specialty tea subscription curators in California and New York are driving demand for compact tabletop machines with quick-change tooling capabilities. FDA 21 CFR Part 110 enforcement shapes stainless steel procurement across co-packing facilities. Los Angeles and Brooklyn manufacturing corridors are consolidating micro-lot toll packing capacity to serve direct-to-consumer channels with formulation turnover exceeding seasonal cycles.
Germany
Black tea co-packers face steep retrofit burdens as REACH restrictions on per- and polyfluoroalkyl substances deplete existing PTFE coating inventories. EFSA migration limits on multilayer films are compelling ultrasonic sealing system adoption. Cologne and Hamburg processing hubs are leading equipment upgrade cycles as European private-label demand concentrates in Rhine-Ruhr logistics corridors.
India
Domestic specialty chai and herbal blend brands lack access to multi-lane sachet capacity, creating white space for toll packing services. FSSAI label integrity and net quantity verification mandates are compelling machine builders to incorporate vision-based inspection modules. Maharashtra and Gujarat industrial belts are emerging as assembly partnership targets for Japanese and European OEMs seeking local fabrication footholds.
Japan
Premium loose-leaf presentation in three-dimensional sachets is pulling investment toward multi-lane machines with servo-driven forming collars. METI energy efficiency standards and JIS sanitation protocols constrain equipment specifications for domestic facilities. Shizuoka and Kagoshima tea-growing prefectures are modernizing legacy processing infrastructure to preserve market share against Chinese and Taiwanese import competition.
Tea Packing Machine Market Competitive Landscape
Capacity expansion dominates the current landscape as OEMs respond to fragmented demand across specialty and mass-market segments. The vendor base stratifies between integrated packaging conglomerates with beverage line heritage and precision weighing specialists with gravimetric technology leadership. Three archetypes anchor competitive positioning: stainless steel hygienic line builders serving pharmaceutical-grade facilities, ultrasonic sealing specialists capturing European compliance-driven replacement cycles, and compact modular fabricators targeting craft subscription channels. Geographic expansion and technology licensing represent the dominant competitive moves as mid-cap builders seek metallurgy and servo programming capabilities through partnership rather than in-house development.
Among Japanese precision equipment builders, Ishida Co., Ltd. exemplifies gravimetric technology leadership in high-speed weighing modules. German engineering conglomerates including Krones AG occupy positions serving integrated beverage packaging lines across European black tea co-packing operations. Syntegon Technology GmbH represents the ultrasonic sealing archetype with systems designed for reduced film waste in sachet and pyramid tea bag formats. These three anchors illustrate how competitive positioning fragments across technology specializations rather than consolidating around full-line dominance.
| Leading Market Players |
|---|
| Ishida |
| Krones AG |
| IMA Group |
| Coesia Group |
| MULTIVAC |
| Syntegon Technology |
| ULMA Packaging |
| Kenwei |
| Tetra Pak |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap machine builders in Germany and Japan anchor supply discipline through generational metallurgy relationships and captive servo programming capabilities, translating input cost stability into pricing power over Asian contract assemblers lacking long-term steel contracts. This ownership pattern insulates premium tier pricing from Grade 316L volatility while compressing margins for toll-dependent packers in India and Southeast Asia.
Pricing Analysis
Distributor margins of 12-18 percent separate OEM list pricing from end-user landed costs, with direct-to-factory arrangements common among Chinese provincial processors modernizing Zhejiang and Fujian facilities. Three-tier pricing structure across pharmaceutical-grade, food-grade, and artisanal equipment levels reflects stainless steel certification tiers and integrated inspection module bundling. Cost compression in mid-capacity vertical machines intensifies because Indian and Southeast Asian builders lack metallurgy contracts, forcing spot-market steel procurement. Contract packers serving European private-label brands exhibit lowest price sensitivity due to EFSA compliance-driven replacement cycles, while domestic Indian chai brands face acute capital constraints.
Supply Chain Analysis
Refurbishment flows for servo drives and sealing jaws concentrate in German and Japanese industrial corridors, extending component lifecycles and creating secondary supply channels for budget-constrained processors. Precision ceramic heater bands and PTFE-coated sealing jaws draw from Japanese and German component suppliers, creating lead time vulnerability for machine builders in India and Southeast Asia. Single-source vulnerability pervades ultrasonic transducer supply, with European OEMs dependent on two dominant specialty manufacturers. Distribution runs through integrated packaging conglomerates with beverage line heritage and precision weighing specialists with gravimetric technology leadership, fragmenting channel control across technology archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty tea's decoupling from bulk loose-leaf distribution signals late-cycle quality migration, with hermetic sealing and nitrogen flushing specifications now table stakes for equipment procurement. Premium positioning accelerates as volatile aromatic preservation becomes non-negotiable across Japanese, Korean, and European brand portfolios.
For Market Incumbents: Cement gravimetric technology leadership through exclusive metallurgy contracts with Grade 316L suppliers, insulating margin pools from input volatility that compresses Asian competitor pricing power. Defend against ultrasonic sealing specialists by integrating ceramic jaw coatings compliant with REACH restrictions, capturing European replacement cycles as PTFE inventories deplete. Prioritize certification investment in FDA 21 CFR Part 11 electronic records modules for pharmaceutical-grade food facilities. For New Entrants and Emerging Players: Begin with toll packing white space in Maharashtra and Gujarat industrial belts, where domestic specialty chai and herbal blend brands lack multi-lane sachet capacity. Target compact tabletop machines with 15-minute tooling swaps for California and New York subscription curators, whose formulation turnover exceeds seasonal cycles. Pursue local assembly partnerships with Japanese and European OEMs seeking fabrication footholds without greenfield facility investment. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap builders without long-term steel contracts or servo programming capabilities, facing margin compression from Grade 316L price swings. Five-to-ten year viability favors ultrasonic sealing specialists with REACH-compliant coating formulations and integrated vision inspection modules. Watch for inflection in FSSAI enforcement intensity across Indian processing hubs, which would accelerate vision-based inspection retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Sealing System Adoption | REACH restrictions on PTFE coatings force ceramic jaw migration across European black tea co-packers. |
| Local Assembly Partnership Formation | Japanese OEMs leverage Maharashtra fabrication capacity to serve Indian toll packing white space. |
| Vision Inspection Module Integration | FSSAI label integrity mandates pull Indian builders toward camera-based verification systems. |
| Servo Programming Capability Acquisition | Multi-axis forming sequences require specialized automation engineers scarce in secondary clusters. |
| Biodegradable Film Sealant Development | Compostable polylactic acid barriers limit high-humidity deployment without secondary overwrap. |
Research Methodology
Bottom-up tea processor procurement modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with plant engineers, aftermarket service heads, OEM procurement teams, and maintenance directors at Zhejiang, Fujian, Shizuoka, and Kagoshima facilities combined with secondary validation from SAMR food contact material standards, FDA 21 CFR Part 110 guidance documents, EFSA migration limit databases, and FSSAI label integrity circulars. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map machine configuration demand across vertical, multi-lane, horizontal, and automatic product types against end-user archetypes including tea manufacturers, food processors, retailers, and online vendors. Segmentation dimensions span automation level, packaging format, and geographic regulatory cluster throughout the forecast period. CAGRs derive from equipment replacement cycle analysis, brownfield modernization capital allocation patterns, and greenfield facility commissioning timelines across Chinese provincial processors and Indian contract packing networks.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalation, abrupt biodegradable film performance breakthroughs, and sovereign subsidy program cancellations. Forecasts reflect assumptions regarding stainless steel price mean-reversion, servo programming talent pipeline development, and regulatory enforcement intensity continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Binding & Lamination Machines Market
Packaging Machinery
Chocolate Wrapping Machine Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Sliding Injection Molding Machine Market