
 Reusable Produce Mesh Bag Market | 2026-2036
Reusable Produce Mesh Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Produce Mesh Bag Market Insights
Organic cotton is pivoting away from conventional polyester as the dominant fiber in premium reusable produce mesh bags, driven by compostability certifications and consumer preference for natural fibers. ECOBAGS leverages its vertically integrated organic cotton supply chain to sustain price competitiveness across European retail channels. Earthwise anchors North American distribution through dominant placement in Whole Foods Market and regional cooperative grocery networks. ChicoBag differentiates through patented stuff-and-stow designs that occupy minimal storage space in urban households.
Reusable produce mesh bags are woven or knitted containers typically constructed from natural fibers or synthetic polymers with mesh apertures ranging from 2 to 5 millimeters, designed for breathable storage and transport of fresh fruits and vegetables while permitting water rinsing without removal of contents. Cotton and hemp segments command premium shelf positioning due to compostability credentials and alignment with zero-waste retail mandates, while polyester variants lead volume through lower unit economics and durability advantages in commercial laundry environments. Distribution through supermarkets generates the largest revenue pool, though online retailers represent the fastest-growing channel as direct-to-consumer subscription models for plastic-free kitchen starter kits gain traction.
The EU Single-Use Plastics Directive and California's SB 54 legislation shape product standards by mandating extended producer responsibility for packaging waste and incentivizing reusable alternatives in fresh produce retail. REACH compliance and OEKO-TEX Standard 100 certification function as de facto market access requirements for European distribution, while the USDA BioPreferred program influences federal procurement preferences in the United States. Stakeholders must monitor evolving state-level plastic bag bans and fiber certification schemes to anticipate which material platforms will secure retail shelf space in regulated jurisdictions.
Market Dynamics
Single-use plastic bans are compressing adoption timelines for fiber-based alternatives, forcing retailers to reconfigure produce section packaging before compliance deadlines in Germany, France, and California.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory reduction targets for plastic packaging are pulling cotton and hemp mesh bags into mainstream grocery retail across member states.
- Municipal composting infrastructure:Cities in the Netherlands and Belgium operate industrial composting facilities that accept certified organic cotton at end-of-life, closing material loops.
- Recycled polyester rPET:Post-consumer plastic recycling yields durable mesh filaments that satisfy commercial laundry requirements in food service and institutional procurement.
Market Restraints
- Organic cotton price volatility:Weather-driven supply fluctuations in India and Turkey inflate raw material costs unpredictably for woven bag converters.
- Polyester microfiber shedding:Synthetic mesh releases plastic particles during washing, triggering scrutiny from environmental regulators in California and the European Union.
- REACH compliance costs:Chemical registration and testing burdens for imported textiles disproportionately impact small-scale Asian manufacturers seeking European market access.
Strategic Opportunities
- Subscription-based starter kits:Direct-to-consumer platforms bundle mesh bags with beeswax wraps and silicone lids, capturing lifetime value from zero-waste households.
- USDA BioPreferred program:Federal procurement preferences create a dedicated demand channel for domestically produced biobased mesh alternatives in government cafeterias and military commissaries.
- Blockchain traceability:Fiber provenance verification from farm to retail shelf commands price premiums in Scandinavian markets with stringent transparency expectations.
Industry Challenges
- OEKO-TEX Standard 100 certification timelines:Testing backlogs at accredited laboratories delay product launches by four to six months for new market entrants.
- Retail slotting fee structures:Dominant supermarket chains charge placement fees that erode margins for independent mesh bag brands competing against private-label programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Produce Mesh Bag Market |
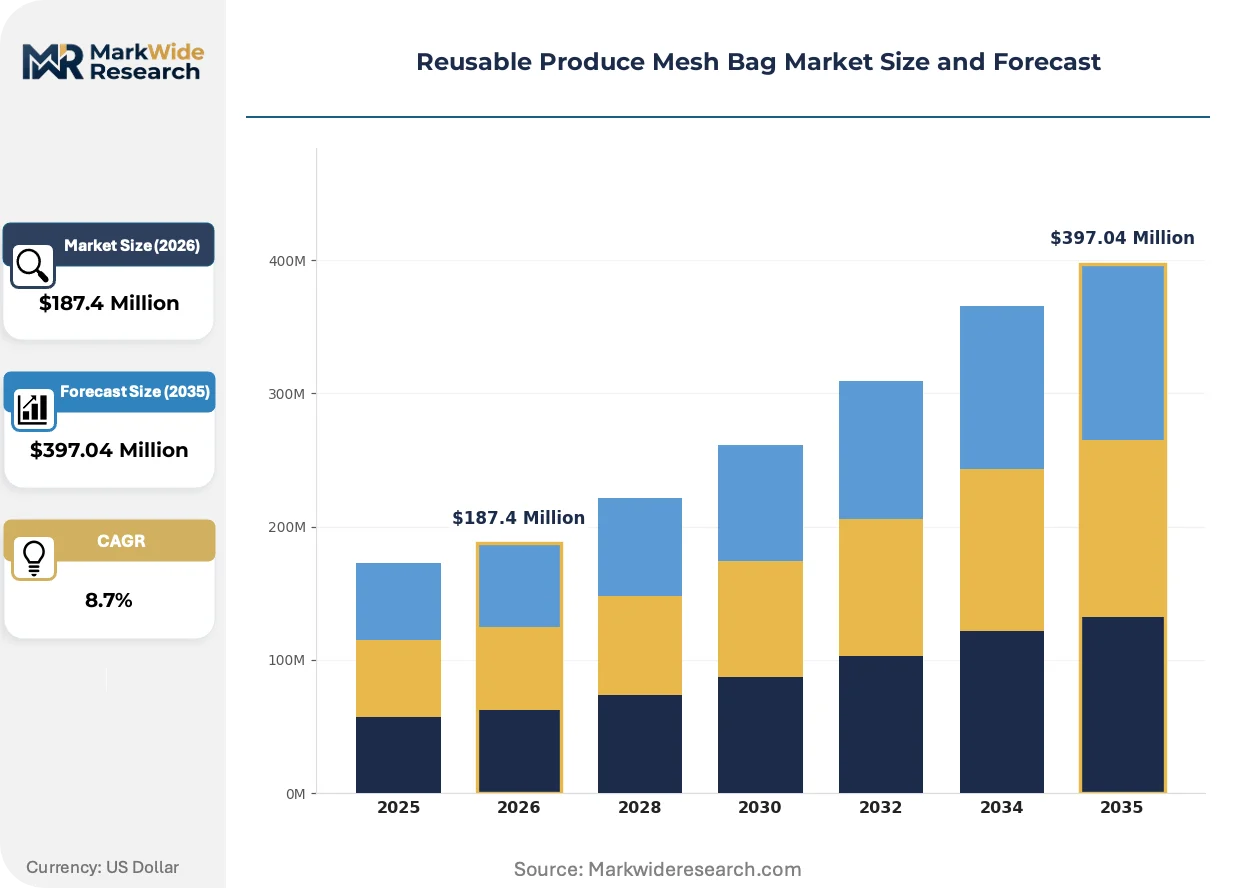
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Cotton, Jute, Polyester, Nylon, Hemp, Bamboo Product Size: Small, Medium, Large, Extra Large Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Farmers Markets End User: Households, Grocery Stores, Restaurants, Catering Services |
| Companies Covered | ECOBAGS, Earthwise, ChicoBag, Onya Life, Simple Ecology, Colony Co., Purifyou, Knack Packaging, Karatzis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Produce Mesh Bag Market Trends and Innovations
Material science advances and retail compliance pressures are converging to redefine performance standards for breathable produce storage across natural and synthetic fiber platforms.
Biodegradable polymer coatings are integrating into cotton mesh constructions to enhance moisture resistance without compromising compostability. European cooperative grocery networks are piloting these hybrid formulations for berry and leafy green packaging. The technology is integrating wash-durability benchmarks previously exclusive to synthetic alternatives, narrowing the performance gap between fiber types.
California's SB 54 legislation mandates 25% source reduction of single-use plastic packaging by 2032, with interim targets accelerating retailer procurement of reusable alternatives. Extended producer responsibility frameworks shift financial liability for packaging waste to brand owners and retailers. Fresh produce departments in Kroger and Albertsons chains are responding with dedicated mesh bag fixtures and deposit-return pilot programs.
Zero-waste kitchen curation is displacing single-item purchasing as consumers seek bundled solutions that eliminate multiple plastic categories simultaneously. Independent online retailers and specialty housewares channels are capturing this demand through themed collections that position mesh bags within broader plastic-free lifestyle transitions. This pattern concentrates in urban coastal markets in the United States and United Kingdom where municipal waste diversion targets align with household purchasing priorities.
Reusable Produce Mesh Bag Market Segmentation
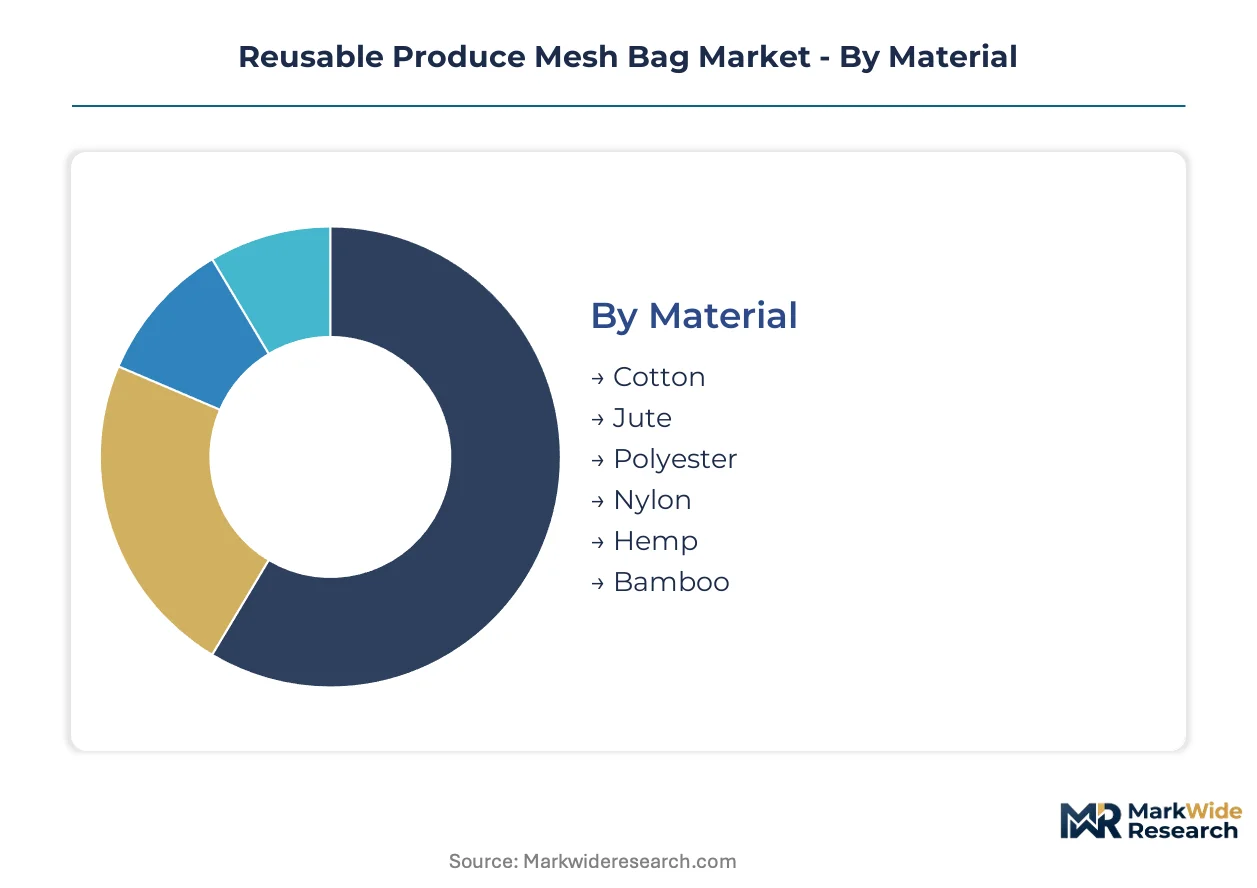
Material composition dictates end-of-life pathways and compliance eligibility across regulated jurisdictions. Product sizing and distribution channel selection determine margin structures and customer acquisition economics for mesh bag suppliers.
Material:
Raw material sourcing concentrates in agricultural basins with established textile processing infrastructure, creating geographic lock-in for fiber-based segments.
- Cotton:Certified organic varieties dominate European retail due to compostability alignment with municipal organic waste streams. German and French supermarkets mandate GOTS certification for private-label placement.
- Polyester:Recycled PET filaments satisfy commercial laundry durability requirements in institutional food service procurement. California's SB 54 implementation is accelerating rPET adoption despite microfiber shedding concerns.
- Hemp:Lower water intensity cultivation attracts sustainability-positioned brands in the Netherlands and Belgium where industrial composting infrastructure supports fiber recovery.
- Jute:Coarser weave structures target root vegetable storage in South Asian export markets with limited synthetic fiber penetration.
- Nylon:High-tenacity monofilaments serve reusable bag rental programs requiring extended wash cycles in commercial kitchen environments.
- Bamboo:Rapid-regrowth feedstock appeals to direct-to-consumer subscription brands targeting zero-waste household curation in urban coastal markets.
Cotton absorbs the bulk of installed capacity; bamboo is expanding most quickly.
Product Size:
Size tiering reflects produce category weight distribution and checkout conveyor compatibility requirements in automated retail environments.
- Medium:8-12 inch aperture dimensions match standard apple, orange, and onion bulk purchasing patterns. Kroger and Albertsons fixture specifications prioritize this tier for produce section display.
- Small:Berry and cherry tomato containment drives demand in farmers market channels where portion-controlled purchasing dominates.
- Large:Root vegetable and melon capacity requirements align with restaurant and catering procurement for kitchen prep storage.
- Extra Large:Bulk grain and bread loaf applications extend utility beyond produce into zero-waste pantry organization.
Medium sizing commands the highest production volume; extra large formats are climbing the fastest as multi-purpose utility marketing gains traction.
Distribution Channel:
Channel selection determines certification burden and working capital intensity through divergent payment terms and inventory ownership structures.
- Supermarkets:Slotting fees and quarterly planogram resets favor established suppliers with private-label manufacturing capability. Whole Foods Market's regional cooperative networks anchor North American volume.
- Online Retailers:Direct-to-consumer subscription models bundle mesh bags with complementary plastic-free kitchen products. Customer lifetime value metrics drive acquisition spending in this channel.
- Specialty Stores:Zero-waste refill shops and housewares boutiques command price premiums for certified organic and blockchain-traced provenance verification.
- Farmers Markets:Seasonal demand concentration and cash-transaction economics limit scale but support local brand building and product testing.
Supermarkets retain the dominant revenue share; online retailers are gaining share fastest through subscription bundling strategies.
End User:
User segmentation separates household discretionary purchasing from institutional procurement governed by extended producer responsibility frameworks.
- Households:Urban coastal consumers in California and the United Kingdom drive replacement purchasing through zero-waste lifestyle adoption and municipal waste diversion target alignment.
- Grocery Stores:Private-label mesh bag programs function as compliance mechanisms for plastic reduction mandates under EU Single-Use Plastics Directive and California SB 54.
- Restaurants:Farm-to-table establishments utilize branded mesh bags for ingredient transport visibility and sustainability narrative reinforcement.
- Catering Services:Commercial laundry durability requirements favor synthetic fiber constructions despite compostability trade-offs in event and institutional food service.
Households represent the largest addressable base; grocery stores are scaling fastest as regulatory deadlines compress adoption timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer demand clusters in Germany, France, and the United Kingdom where municipal composting infrastructure supports fiber-based end-of-life pathways for organic cotton mesh bags. Regulatory mandates across these jurisdictions are compressing adoption timelines for reusable alternatives ahead of single-use plastic compliance deadlines.
Germany
Whole Foods Market's regional cooperative networks and REWE Group's private-label programs drive procurement volume for GOTS-certified organic cotton bags. The Packaging Act (VerpackG) mandates extended producer responsibility for retail packaging waste, incentivizing reusable produce container adoption. Berlin and Hamburg anchor industrial composting facility networks that accept certified fiber waste from household collection streams.
France
Carrefour and Intermarché chains are expanding dedicated mesh bag fixtures in produce sections ahead of AGEC law plastic reduction milestones. The Anti-Waste for a Circular Economy Act imposes annual reporting requirements on single-use plastic elimination progress for retailers exceeding €50 million turnover. Lyon and Marseille municipal waste authorities operate industrial composting infrastructure supporting cotton fiber recovery at end-of-life.
United Kingdom
Sainsbury's and Waitrose private-label mesh bag programs respond to Plastic Packaging Tax compliance requirements and consumer zero-waste adoption in urban centers. The Environment Act 2021 establishes legally binding waste reduction targets and extended producer responsibility frameworks for packaging. London and Bristol concentration of zero-waste refill shops creates specialty channel demand for premium certified organic variants.
United States
California's SB 54 legislation mandates 25% source reduction of single-use plastic packaging by 2032, with Kroger and Albertsons chains deploying mesh bag deposit-return pilots in fresh produce departments. Whole Foods Market anchors North American volume through regional cooperative network placement. Los Angeles and San Francisco municipal composting programs accept BPI-certified fiber bags, closing material loops for household users.
Netherlands
Albert Heijn and Jumbo Supermarkten are accelerating private-label mesh bag rollout under EU Single-Use Plastics Directive implementation timelines. National waste management policy prioritizes industrial composting infrastructure expansion to support fiber-based packaging end-of-life pathways. Amsterdam and Rotterdam operate advanced organic waste processing facilities that certify compost output for agricultural reuse.
Reusable Produce Mesh Bag Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated cotton suppliers commanding premium positioning in European retail channels while Asian converters dominate volume production for private-label programs. The vendor base organizes into three strategic archetypes: organic cotton specialists with farm-to-retail traceability systems, recycled polyester fabricators serving institutional laundry-durable requirements, and diversified reusable bag houses with multi-material portfolios. Capacity expansion and certification acquisition constitute the dominant competitive moves as players race to secure OEKO-TEX and GOTS credentials before retail compliance deadlines.
Within the organic cotton specialist tier, ECOBAGS and Simple Ecology exemplify vertically integrated supply chain control from agricultural sourcing through retail distribution. Among North American branded houses, Earthwise and ChicoBag occupy positions anchored by dominant placement in Whole Foods Market regional networks and patented stuff-and-stow design differentiation. These named entities represent archetype anchors rather than exhaustive market coverage, with substantial share held by unlisted regional converters and emerging direct-to-consumer subscription platforms.
| Leading Market Players |
|---|
| ECOBAGS |
| Earthwise |
| ChicoBag |
| Onya Life |
| Simple Ecology |
| Colony Co. |
| Purifyou |
| Knack Packaging |
| Karatzis |
| Others |
Pricing and Supply Chain Analysis
Captive control over organic cotton gins in India and Turkey anchors pricing power for European mesh bag suppliers, insulating GOTS-certified producers from spot fiber volatility while forcing non-integrated converters into margin compression during monsoon-driven supply disruptions.
Pricing Analysis
Volume production of recycled polyester bags runs through contract manufacturing networks in Bangladesh and Vietnam, while premium organic cotton variants command shelf price multiples through GOTS and OEKO-TEX certification tiers. Price differentiation hinges on compostability credentials and blockchain traceability premiums in Scandinavian retail channels. Cost compression in the standard tier is intensifying as private-label programs at Kroger and Albertsons squeeze converter margins through volume commitments. Household consumers in urban coastal markets show lowest price sensitivity for certified organic variants, whereas institutional food service procurement prioritizes unit economics over fiber provenance.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg coordinate hub-and-spoke replenishment for European supermarket chains, consolidating shipments from textile clusters in India, Turkey, and China. Raw material flows draw from cotton basins in Gujarat and Aegean regions, rPET flake processors in Southeast Asia, and hemp cultivation cooperatives in the Netherlands. Single-source vulnerability concentrates in Indian organic cotton gins supplying GOTS-certified fiber to European converters. Distribution runs through importer-of-record arrangements that transfer REACH compliance liability to brand owners before warehouse intake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive erects a cost-of-compliance moat that favors incumbent suppliers with established certification infrastructure, locking out speculative entrants lacking OEKO-TEX and GOTS credentialing capacity.
For Market Incumbents: Deepen backward integration into certified organic cotton gins in India and Turkey to secure fiber supply during climate-driven harvest volatility. Expand captive OEKO-TEX testing laboratory capacity to circumvent four-to-six-month accreditation backlogs that delay private-label program launches. Channel control through exclusive Whole Foods Market regional cooperative networks defends against direct-to-consumer subscription entrants. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription bundling of mesh bags with beeswax wraps and silicone lids, capturing lifetime value from zero-waste households in London and San Francisco municipal composting jurisdictions. Specialty zero-waste refill shops in Bristol and Amsterdam offer the most penetrable channel for blockchain-traced provenance premiums. Digital-native curation marketing displaces single-item purchasing psychology. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical integration plays by private-label manufacturers seeking GOTS-certified supply chain control. Five-to-ten year viability favors converters with dual-material capability across cotton and rPET platforms. Watch California SB 54 implementation pace as inflection signal for institutional procurement volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Acquisition | Unlocks private-label placement at Carrefour and REWE Group under EU directive compliance timelines. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue from zero-waste households in municipal composting cities like San Francisco and Amsterdam. |
| Backward Integration into Cotton Gins | Insulates margin position against Indian monsoon-driven supply disruptions and spot price spikes. |
| Blockchain Traceability Implementation | Commands Scandinavian retail premiums through farm-to-shelf fiber provenance verification systems. |
| rPET Filament Capacity Expansion | Satisfies California SB 54 institutional procurement requirements for commercial laundry durability standards. |
Research Methodology
Trade databases, customs filings, and GOTS certification registries formed the secondary backbone, cross-referenced against primary interviews with sustainable textile procurement managers, private-label program directors at cooperative grocery networks, OEKO-TEX laboratory accreditation officers, and zero-waste retail channel buyers. Bottom-up and top-down triangulation validated fiber volume estimates against supermarket point-of-sale data and converter production disclosures.
Bottom-up modeling anchored projections across material composition, product sizing tiers, distribution channel economics, and end-user segmentation through the analysis window. CAGR derivation incorporated EU Single-Use Plastics Directive implementation pacing, California SB 54 interim target compliance trajectories, and municipal composting infrastructure expansion curves. Fiber price elasticity assumptions drew from historical organic cotton spot volatility patterns and rPET flake supply dynamics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated plastic ban enforcement or prolonged OEKO-TEX laboratory backlogs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Greenwrap Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market