
 Reusable Food Wrap Market | 2026-2036
Reusable Food Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Food Wrap Market Intelligence
ISO 18606 certification for compostable and biodegradable packaging is reorganizing competitive entry barriers for reusable food wrap suppliers. Stasher leverages platinum-grade silicone chemistry to sustain premium positioning across North American retail channels. Abeego Designs Inc. anchors its formulation leadership in organic cotton infused with beeswax, jojoba oil, and tree resin blends. LilyBee Wrap competes through hand-crafted production scale and direct-to-consumer channel control in Australasia.
Reusable food wrap denotes pliable, wash-cloth substrates—typically organic cotton, hemp, or cellulose—impregnated with beeswax, plant waxes, or cured silicone elastomers to create an airtight, moisture-resistant seal for food preservation. The substrate undergoes saturation-dipping or roller-coating at controlled temperatures, followed by cooling to achieve tack adhesion without synthetic adhesives. Beeswax formulations dominate current volume owing to established artisan supply chains and consumer familiarity, while silicone variants capture accelerating growth through dishwasher durability and higher temperature tolerance. Food service providers represent an expanding end-user segment as commercial kitchens phase out polyethylene cling film under operational sustainability mandates.
The EU Green Deal and REACH restrictions on petrochemical-derived single-use articles are redirecting procurement budgets toward certified reusable alternatives across European food service operations. FDA food-contact substance notifications govern silicone wrap compositions in the United States, creating dual-track compliance obligations for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate certification harmonization between jurisdictions to secure shelf placement and institutional contract eligibility.
Market Dynamics
The EU Green Deal's single-use plastics directive is compressing demand migration toward certified reusable alternatives, forcing substrate suppliers to requalify formulations under REACH and ISO 18606 protocols simultaneously.
Growth Catalysts
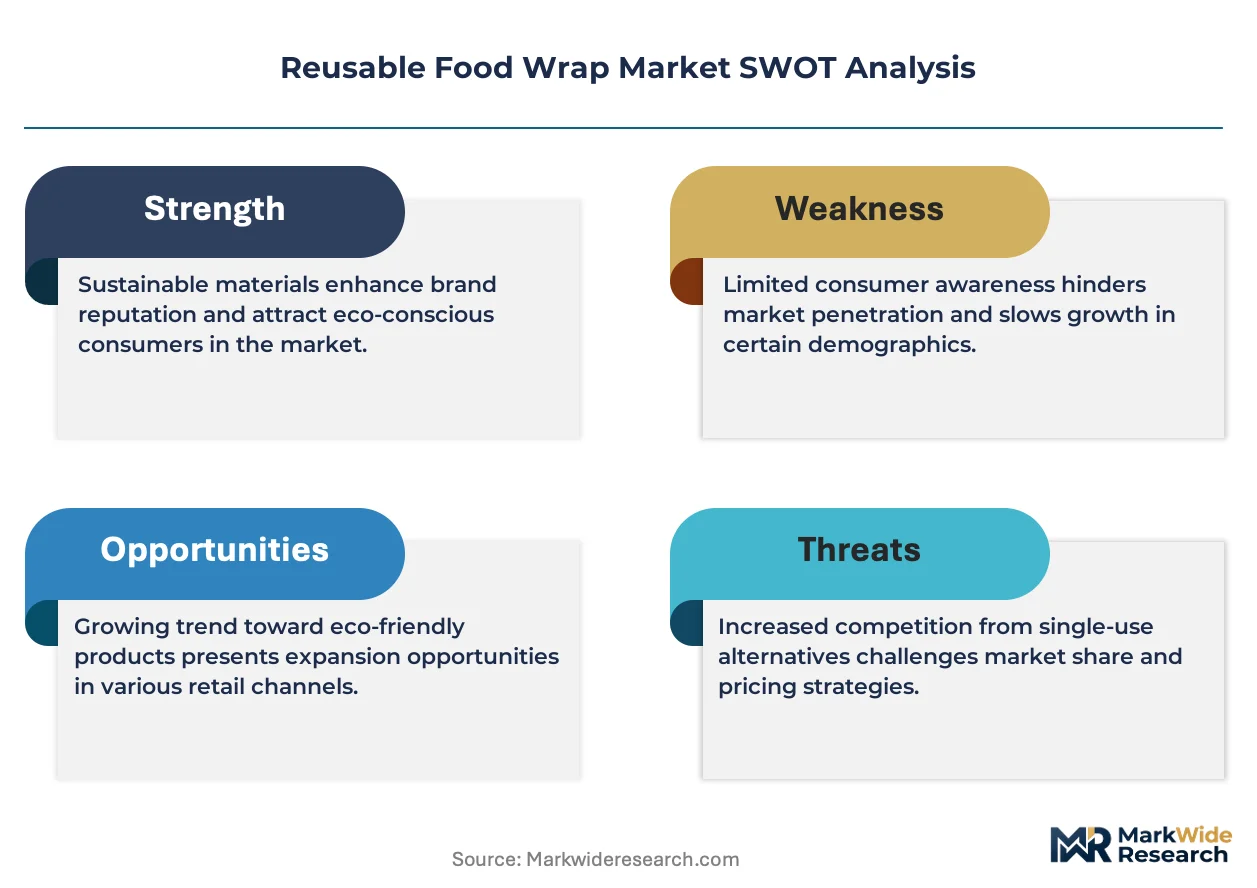
- REACH petrochemical restrictions:The European Chemicals Agency's tightening controls on disposable polyethylene articles are redirecting institutional procurement budgets toward beeswax and silicone wrap suppliers with compliant material passports.
- Food service sustainability mandates:Commercial kitchens across Germany, France, and the United Kingdom face operational phase-out deadlines for cling film, creating immediate replacement demand for dishwasher-durable silicone variants.
- Beeswax supply chain maturation:Artisan apiary networks in Romania and Bulgaria have scaled cold-pressed extraction capacity, stabilizing raw material costs for organic cotton substrate producers.
Market Restraints
- Platinum-grade silicone cost volatility:Medical-grade silicone elastomer feedstock prices fluctuate with semiconductor and healthcare demand cycles, squeezing margin structures for wrap manufacturers dependent on high-purity inputs.
- Artisan production concentration:Hand-poured beeswax wrap output clusters in small-batch workshops across New Zealand and Australia, creating volume ceilings and quality inconsistency at scale.
- Temperature tolerance limitations:Beeswax formulations degrade above 60°C, excluding their use from sous-vide and high-heat commercial applications where silicone dominates at 3-4x unit cost.
Strategic Opportunities
- Extended producer responsibility frameworks:France's AGEC law and upcoming EU-wide packaging waste regulations will mandate take-back infrastructure, favoring suppliers with closed-loop recycling partnerships for silicone elastomers.
- Direct-to-consumer subscription channels:Replenishment models for wrap refresh kits bypass retail margin capture and build usage-data relationships with household segments.
- Cellulose substrate innovation:Agricultural waste-derived cellulose from hemp and corn stalks converges with plant-based wax coatings to create compostable alternatives without cotton's water-intensive cultivation footprint.
Industry Challenges
- ISO 18606 certification timelines:Third-party biodegradability testing for new substrate-wax combinations requires 180-day soil burial protocols, delaying product launches and freezing R&D budgets during validation.
- Multi-jurisdiction compliance stacking:Suppliers serving both FDA-notified US markets and REACH-governed EU markets must maintain dual formulation tracks, complicating inventory segmentation and quality documentation.
- Consumer education gaps:Proper wash-care protocols for beeswax wraps differ sharply from silicone dishwasher compatibility, driving premature product failure and brand switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Food Wrap Market |
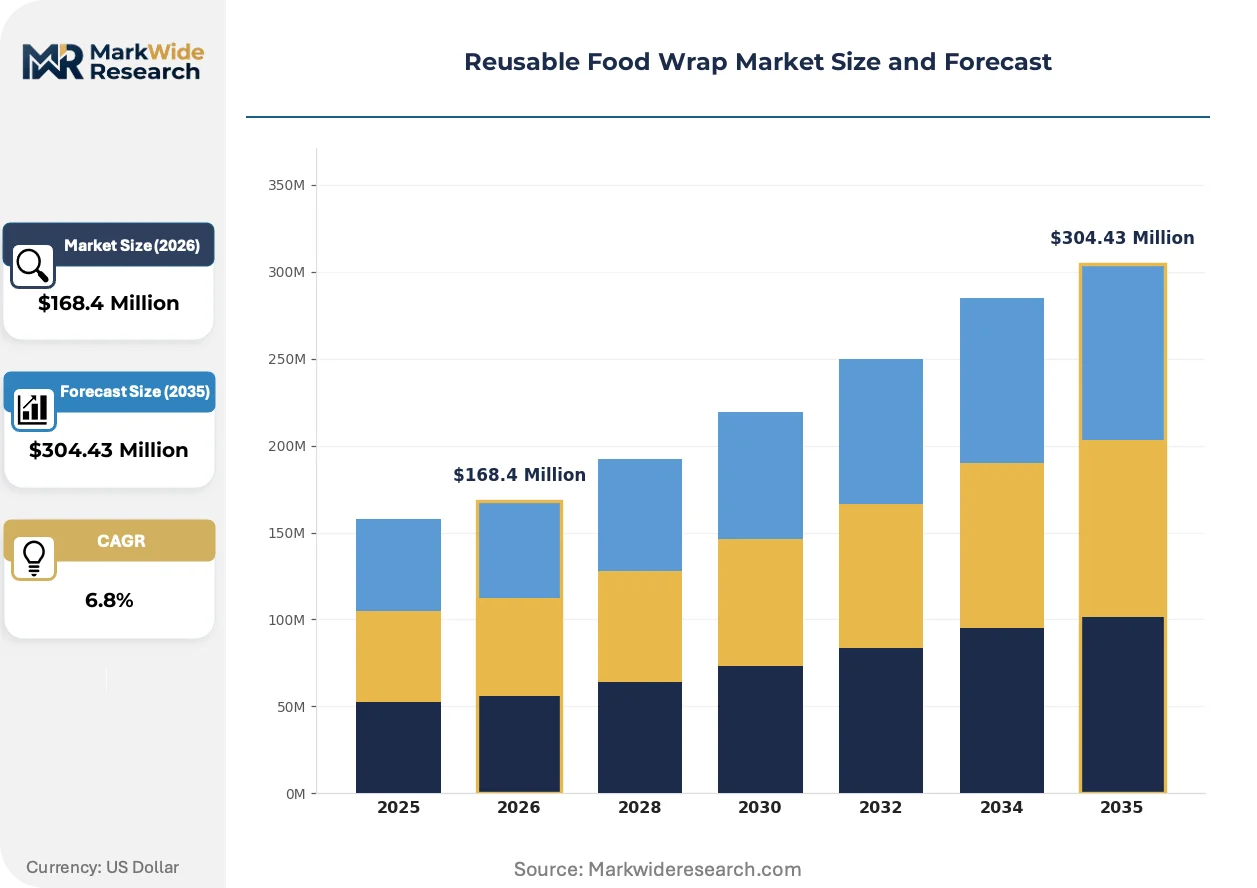
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $304.43 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Beeswax, Silicone, Cotton Fabric, Bamboo Fiber, Wood Pulp Application: Food Storage, Food Packaging, Meal Preparation, Household Use, Picnic & Outdoors End User: Households, Food Service Providers, Culinary Schools, Specialty Stores, Eco-Friendly Retailers Distribution Channel: Online Retailers, Supermarkets, Specialty Eco-Shops, Farmers Markets, Direct-to-Consumer Sales |
| Companies Covered | Stasher, LilyBee Wrap, Keep Leaf, Ecolunchbox, Hexton Bee Company, Abeego Designs Inc., U-KONSERVE, ReWrap, Bee's Wrap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Food Wrap Market Strategic Shifts & Innovations
Active coating deposition methods and substrate engineering are compressing performance gaps between artisan beeswax wraps and industrial silicone alternatives, reshaping competitive tier boundaries.
Plasma-enhanced chemical vapor deposition of fluorine-free barrier coatings onto cellulose substrates is miniaturizing the performance advantage previously held by thick silicone elastomer sheets. Food service distributors in the Netherlands and Denmark are piloting these ultra-thin wraps for deli counter applications where conformability and grease resistance must match polyethylene benchmarks. The technology is miniaturizing the premium tier's insulation from economy-grade competition.
The EU Green Deal's 2025 single-use plastics ban implementation timeline is forcing national regulators to harmonize enforcement protocols across member states. ECHA guidance documents published in 2024 clarified biodegradability testing equivalencies, reducing certification duplication costs for cross-border suppliers. German food contact material compliance bodies have responded by accelerating approval queues for plant-resin formulations previously restricted under legacy mineral oil migration standards.
Household buyers are consolidating wrap purchases through zero-waste retail cooperatives that bundle education, repair services, and end-of-life collection. These member-owned channels displace conventional supermarket placement in urban centers of Copenhagen, Amsterdam, and Barcelona. The shift is most visible among millennial household formations prioritizing transparent supply chain documentation over brand recognition.
Reusable Food Wrap Market Segmentation
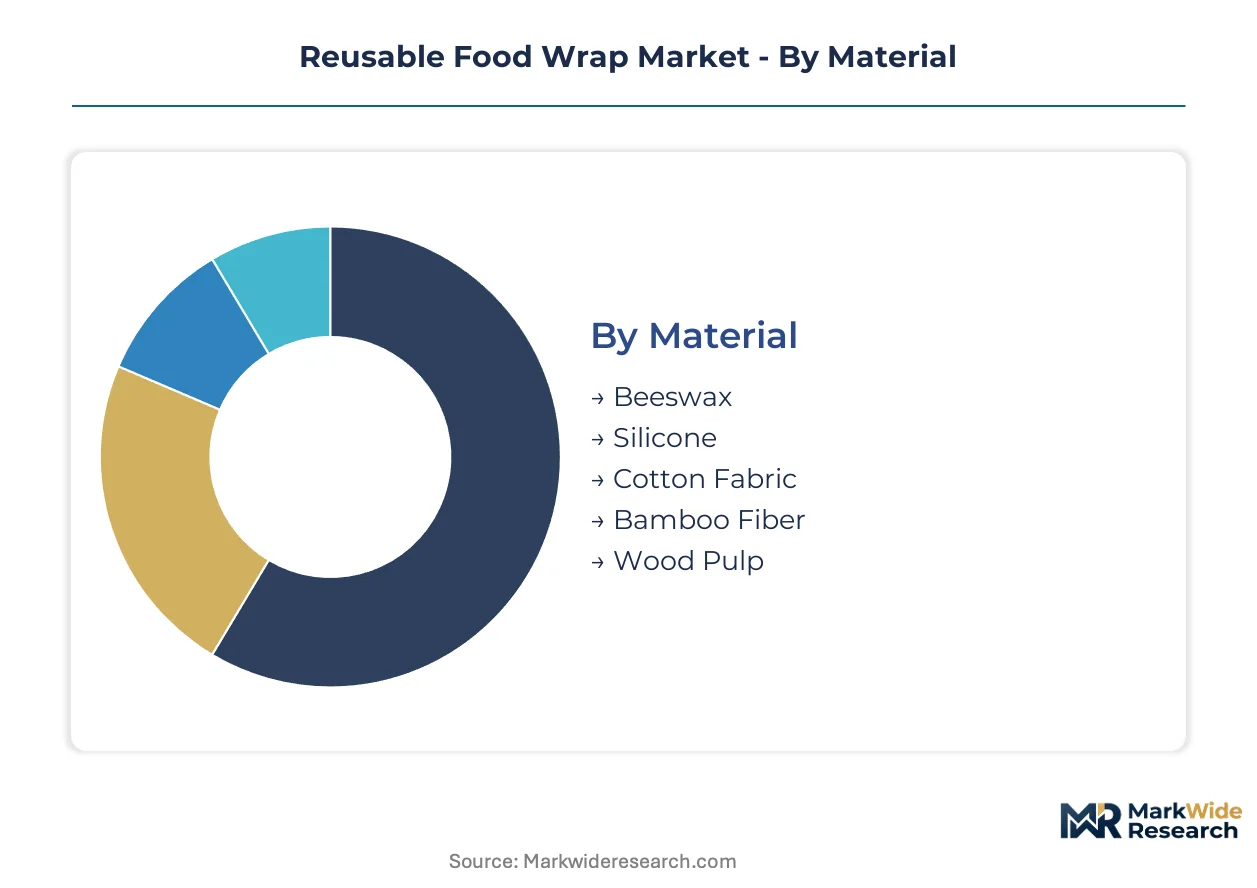
Segmentation in the reusable food wrap market reveals how material chemistry, application context, and channel economics create distinct competitive arenas. Each dimension carries unique margin profiles and regulatory exposure that determine supplier positioning strategies.
Material:
Channel economics diverge sharply by material type, with premium silicone commanding placement in specialty eco-shops and direct-to-consumer platforms while beeswax saturates farmers markets and supermarket value tiers.
- Beeswax:Organic cotton substrates impregnated with refined beeswax, jojoba oil, and tree resin blends create pliable wraps with natural tack adhesion. Artisan production networks in Romania and Bulgaria supply cold-pressed wax to household buyers through farmers markets and zero-waste cooperatives in Copenhagen and Amsterdam, though temperature degradation above 60°C limits commercial kitchen adoption.
- Silicone:Platinum-grade silicone elastomer sheets cured to food-contact specifications deliver dishwasher durability and sous-vide compatibility. Food service providers across Germany, France, and the United Kingdom source these through specialty distributors under operational sustainability mandates, paying unit premiums of 3-4x over beeswax alternatives for heat tolerance.
- Cotton Fabric:Woven organic cotton bases without wax impregnation serve as absorbent covers for bread and produce storage.
- Bamboo Fiber:Cellulose extracted from bamboo pulp offers rapid renewability and antimicrobial properties for meal preparation applications.
- Wood Pulp:Agricultural waste-derived cellulose substrates coated with plant-based waxes target compostable certification under ISO 18606 protocols.
Beeswax dominates installed base through volume accessibility. Silicone is where expansion concentrates among institutional buyers.
Application:
Cost tier stratification separates commodity household use from premium commercial deployments where durability specifications justify higher per-unit expenditure.
- Food Storage:Short-term refrigeration of cut produce, cheese, and leftovers represents the foundational use case driving household trial and repeat purchase frequency.
- Food Packaging:Deli counter and takeaway applications in the Netherlands and Denmark are piloting plasma-coated cellulose wraps to replace polyethylene benchmarks in food service environments.
- Meal Preparation:Pre-portioning and marinating workflows in culinary schools favor silicone variants for dishwasher sanitation cycles.
- Household Use:General kitchen coverage including bowl sealing and sandwich wrapping sustains the largest volume segment through supermarket and online retail channels.
- Picnic & Outdoors:Lightweight, disposable-adjacent usage patterns favor lower-cost beeswax options sold through seasonal retail placements.
Household use commands the broadest channel presence. Food packaging is climbing the fastest as commercial kitchens phase out cling film.
End User:
Customer type determines pricing power, with food service providers negotiating volume contracts while specialty stores curate premium assortments for environmentally conscious consumers.
- Households:Individual consumers purchasing through replenishment subscriptions or retail cooperatives prioritize transparent supply chain documentation over brand recognition.
- Food Service Providers:Commercial kitchens across Germany, France, and the United Kingdom face mandated phase-out deadlines for single-use plastics, creating immediate replacement demand.
- Culinary Schools:Training institutions require standardized, durable wraps for high-frequency student use and sanitation compliance.
- Specialty Stores:Curated retail channels bundle education, repair services, and end-of-life collection to displace conventional supermarket placement.
- Eco-Friendly Retailers:Member-owned zero-waste cooperatives in Barcelona and Amsterdam consolidate wrap purchases with usage-data relationships.
Households anchor volume throughput. Food service providers are where margin expansion concentrates.
Distribution Channel:
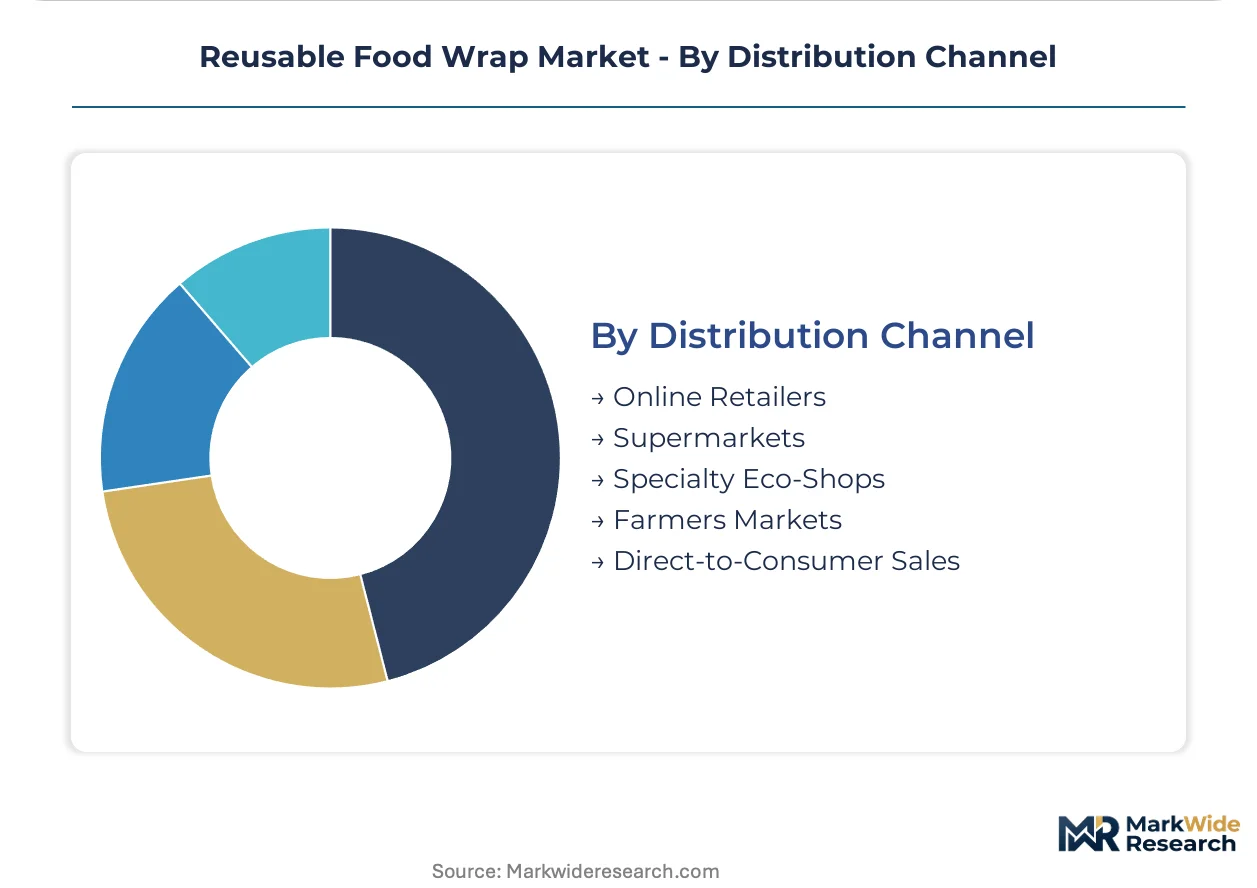
Supply concentration varies by channel, with direct-to-consumer platforms enabling refresh kit subscriptions while farmers markets sustain artisan producer viability.
- Online Retailers:E-commerce platforms capture household buyers seeking product education and comparison shopping convenience.
- Supermarkets:Mass retail placement in Germany and France drives beeswax volume through price-accessible tiering.
- Specialty Eco-Shops:Curated assortments with staff expertise command premium positioning for silicone and certified organic variants.
- Farmers Markets:Direct producer-to-consumer sales sustain small-batch beeswax wrap workshops in New Zealand and Australia.
- Direct-to-Consumer Sales:Subscription models for wrap refresh kits bypass retail margin capture and build proprietary customer data assets.
Supermarkets dominate installed base reach. Direct-to-consumer channels are where supplier relationship value concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Households seeking plastic alternatives concentrate in Germany, France, the United Kingdom, Australia, and the United States. Each market exhibits distinct regulatory timelines and channel structures.
Germany
Commercial kitchens in Berlin and Hamburg drive silicone wrap procurement under operational sustainability mandates. The EU Green Deal's single-use plastics directive forces institutional buyers to phase out polyethylene cling film by 2025. Bavarian food service distributors are consolidating procurement contracts for dishwasher-durable variants.
France
Zero-waste retail cooperatives in Paris and Lyon displace conventional supermarket channels for beeswax wraps. The AGEC law mandates extended producer responsibility frameworks, favoring suppliers with closed-loop recycling infrastructure. Provençal artisan producers supply cold-pressed wax to these member-owned networks.
United Kingdom
London households anchor demand through direct-to-consumer subscription models. REACH compliance requirements for food contact materials filter out uncertified imports. Specialty eco-shops in Brighton and Bristol curate premium assortments with transparent supply chain documentation.
Australia
Hand-crafted beeswax wrap workshops in Melbourne and Sydney sustain small-batch production for farmers market channels. Temperature tolerance limitations exclude these artisans from commercial kitchen procurement. Direct producer-to-consumer sales bypass retail margin capture in urban centers.
United States
FDA food-contact substance notifications govern silicone wrap compositions entering North American retail. California and New York metro areas concentrate zero-waste store formations. Platinum-grade silicone suppliers target these coastal markets through specialty distributors.
Reusable Food Wrap Market Key Industry Players
Player mix skews toward artisan-scale beeswax specialists and industrial silicone fabricators. The vendor base splits between hand-poured organic cotton workshops and platinum-grade elastomer manufacturers. Three archetypes dominate: formulation-led organic brands, scale-driven silicone molders, and hybrid cellulose innovators. Competitive moves center on certification stacking for multi-jurisdiction compliance and direct-to-consumer channel capture.
Among North American specialists, Stasher and Abeego Designs Inc. occupy distinct tier positions. Stasher anchors the premium silicone vector with platinum-grade chemistry positioning. Abeego Designs Inc. exemplifies the formulation-led organic archetype through substrate-wax blending expertise. LilyBee Wrap represents the artisan-scale, geography-concentrated model with hand-crafted production control. These three illustrate how material chemistry choices dictate channel access and margin structure across the competitive map.
| Leading Market Players |
|---|
| Stasher |
| LilyBee Wrap |
| Keep Leaf |
| Ecolunchbox |
| Hexton Bee Company |
| Abeego Designs Inc. |
| U-KONSERVE |
| ReWrap |
| Bee's Wrap |
| Others |
Cost & Logistics Intelligence
Silicone elastomer substitution for beeswax formulations is redrawing procurement geography toward platinum-grade feedstock suppliers in Germany and the United States while compressing artisan wrap margins through industrial scale economies. This material transition simultaneously elevates price floors for heat-tolerant variants and destabilizes small-batch production networks dependent on apiary wax sourcing.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-indexed silicone feedstock clauses dominate institutional procurement for food service providers. Three-tier pricing structure across premium platinum-grade, standard industrial-grade, and economy beeswax tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from semiconductor and healthcare demand cycles competing for medical-grade silicone elastomer supply. Household buyers through direct-to-consumer channels exhibit highest price sensitivity, while commercial kitchens under sustainability mandates accept 3-4x unit premiums for dishwasher durability.
Supply Chain Analysis
Cold-pressed beeswax extraction capacity in Romania and Bulgaria constitutes a chokepoint for organic cotton substrate producers serving European household demand. Raw material dependencies center on platinum-grade silicone from Germany and the United States, organic cotton from Turkey and India, and tree resin from Portugal and Spain. Single-source vulnerability concentrates in artisan apiary networks unable to scale beyond workshop output ceilings. Distribution runs through specialty eco-shops and direct-to-consumer platforms for premium tiers, with mass retail capturing beeswax volume in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise and multi-jurisdiction certification navigation represent scarce capabilities that constrain supplier expansion and consolidate advantage among incumbent specialists with established compliance infrastructure.
For Market Incumbents: Secure ISO 18606 certification pre-qualification for cellulose substrate innovations before EU packaging waste regulations mandate take-back infrastructure. Anchor supply relationships with Romanian and Bulgarian apiary cooperatives through long-term wax offtake agreements to defend against silicone substitution threats in household segments. For New Entrants and Emerging Players: ECHA guidance document fast-tracks for plant-resin formulations previously restricted under legacy mineral oil migration standards offer entry pathways into German food contact material approvals. Target Netherlands and Denmark food service distributors piloting plasma-coated cellulose wraps for deli counter applications, leveraging compostable certification as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors vertically integrated suppliers with captive beeswax sourcing and in-house silicone compounding capabilities. Acquisition targets should demonstrate established FDA notification pathways for North American expansion and REACH-compliant material passports for European institutional contracts. Watch ECHA enforcement harmonization across member states as the inflection signal for certification-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Apiary Networks | Captive beeswax supply from Romanian and Bulgarian cooperatives secures raw material cost stability against silicone volatility. |
| ISO 18606 Certification Investment | Third-party biodegradability validation unlocks French AGEC law compliance and EU Green Deal procurement eligibility. |
| Direct-to-Consumer Subscription Launch | Replenishment models for wrap refresh kits bypass retail margin capture in United Kingdom and United States urban centers. |
| Plasma Coating Technology Licensing | Fluorine-free barrier deposition from Netherlands and Denmark pilots enables deli counter penetration against polyethylene benchmarks. |
| Closed-Loop Recycling Partnership | Silicone elastomer take-back infrastructure aligns with upcoming EU extended producer responsibility frameworks. |
Research Approach
The analysis maps beeswax wrap artisan networks, platinum-grade silicone molders, and cellulose substrate innovators, each validated through procurement directors at German and French food service distributors, regulatory affairs specialists navigating REACH and FDA dual tracks, and category buyers at zero-waste retail cooperatives in Copenhagen and Amsterdam. Primary fieldwork combined with secondary validation from ECHA guidance documents, FDA food-contact substance notification databases, and EU Green Deal implementation timelines. Bottom-up volume estimates from substrate production capacity and top-down value sizing from channel revenue flows underwent cross-triangulation for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include material chemistry tier, application context from household storage to commercial food packaging, end-user type from individual consumers to institutional procurement, and distribution channel economics. CAGRs derived from material substitution elasticity estimates and regulatory deadline impacts. Industry-specific forecast inputs incorporated artisan production capacity ceilings and silicone feedstock price cycle correlations with semiconductor demand.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and REACH petrochemical restriction assumptions; material deviation in regulatory harmonization speed or silicone supply shock magnitude would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA biodegradability testing equivalency interpretations and FDA notification queue processing rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Greenwrap Market
Reusable Packaging
Refillable and Reusable Packaging Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Reusable Egg Containers Market