
 Reusable Straw Market | 2026-2036
Reusable Straw Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Straw Market Intelligence
REACH compliance is decoupling material certification from legacy supply chains in the European reusable straw sector. Klean Kanteen leverages stainless steel sourcing partnerships to sustain premium positioning across German retail channels. Eco-Products, Inc anchors its competitive stance through compostable packaging integration that extends brand credibility into foodservice procurement.
A reusable straw is a cylindrical drinking tube manufactured from food-grade materials such as 18/8 stainless steel, borosilicate glass, or platinum-cured silicone, designed for repeated cleaning and use across hundreds of cycles. Stainless steel variants dominate commercial procurement due to thermal durability and dishwasher compatibility, while silicone segments capture household demand through child-safe flexibility and collapsible portability. The jumbo size category leads restaurant adoption for smoothie and bubble-tea applications, whereas on-the-go use cases drive pouch-format packaging growth among commuter demographics.
The EU Single-Use Plastics Directive, FDA food-contact substance regulations, and California SB 54 collectively mandate material traceability and recycled-content thresholds that reshape supplier qualification criteria. Germany's national packaging law and France's AGEC anti-waste statute impose extended producer responsibility fees that favor durable formats over disposables. Stakeholders must monitor evolving state-level procurement mandates and polymer-content disclosure rules to anticipate which material platforms will retain channel access.
Market Dynamics
Extended producer responsibility laws across Germany, France, and California are forcing quick-service restaurants to internalize lifecycle costs of serviceware, compressing payback periods for durable formats below eighteen months.
Growth Catalysts
- EU Single-Use Plastics Directive:Germany's national packaging law imposes fees on disposable alternatives that make stainless steel straws cost-competitive at volume. Restaurant chains accelerate fleet-wide conversion to avoid compliance penalties.
- Bubble-tea consumption clusters:Taiwanese-style beverage shops in Los Angeles and London drive jumbo-format stainless steel procurement. These operators require 12mm bore diameters that single-use paper cannot satisfy.
- Silicone molding advances:Platinum-cured medical-grade silicone enables collapsible straws that pass dishwasher durability testing. Commuter demographics in metropolitan rail corridors favor pouch-format portability.
Market Restraints
- Nickel price volatility:18/8 stainless steel contains 8% nickel, subject to London Metal Exchange fluctuations. Producers in Shandong Province face margin compression when feedstock spikes.
- Glass fragility liability:Borosilicate variants carry breakage risk in high-turnover foodservice. Insurers in California classify these as product liability exposures, elevating coverage costs.
- Sanitation certification timelines:FDA food-contact substance notifications require 120-day review cycles. New coating technologies face launch delays that cede early-mover advantage to incumbents.
Strategic Opportunities
- Municipal procurement mandates:California SB 54 requires recycled-content thresholds in state-contracted foodservice. Certified sustainable serviceware suppliers gain preferential vendor status in Los Angeles and San Francisco school districts.
- Quick-service robotics integration:Automated beverage dispensers in McDonald's and Starbucks pilot locations require standardized straw geometries. Durable formats with precise outer diameters lock in equipment compatibility.
- France AGEC anti-waste statute:On-premise dining establishments must eliminate single-use plastics by 2025. Reusable deposit systems at highway rest stops create closed-loop revenue models.
Industry Challenges
- REACH substance inventory compliance:ECHA requires full chemical disclosure for silicone colorants and metal alloys. Small-batch artisans lack toxicology documentation capacity, forcing exit from German retail channels.
- Reverse logistics infrastructure:Deposit-return schemes require collection, sanitization, and redistribution networks. Operators must build washing facilities that meet HACCP standards at regional hub scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Straw Market |
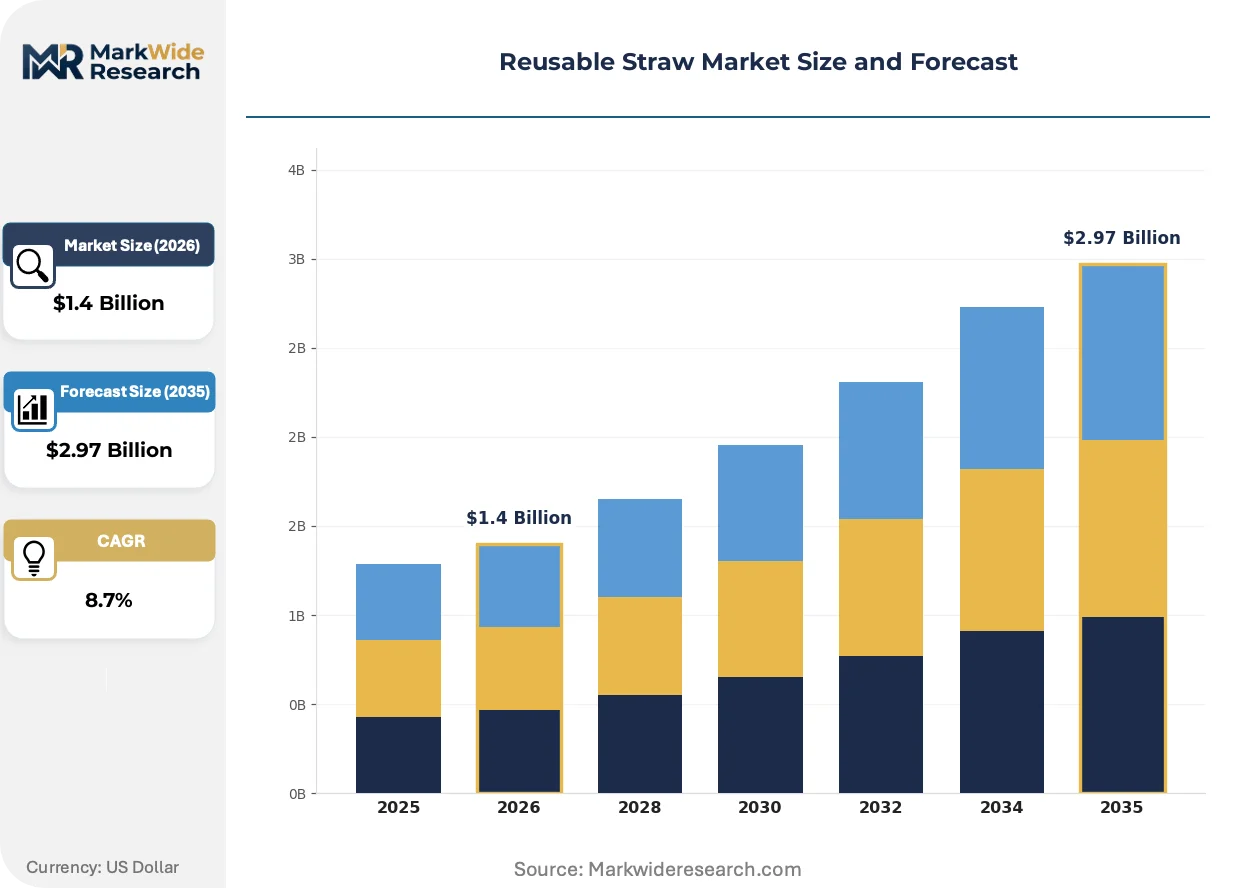
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silicone, Stainless Steel, Bamboo, Glass Size: Regular, Jumbo, Mini, Extra Tall Use Case: Household, Restaurants, Events, On-the-Go Packaging Type: Boxed, Pouch, Bundle, Dispenser |
| Companies Covered | Klean Kanteen, Simply Straws, The Final Co. LLC, Eco-Products, Inc, Greens Steel, Buluh Straws, GoSili, FinalStraw, Glass Dharma LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Straw Market Strategic Shifts & Innovations
Material science advances and regulatory precision are compressing product development cycles. Manufacturers now optimize for simultaneous compliance across multiple jurisdictions rather than sequential market entry.
Laser-welded seamless stainless steel construction is overtaking crimped designs in commercial foodservice. Quick-service chains in Germany specify seamless interiors that eliminate bacterial harborage points. Dishwasher-safe durability ratings now exceed five hundred cycles, collapsing total cost of ownership below paper alternatives.
France's AGEC anti-waste statute mandates reusable tableware for on-premise consumption. Full-service restaurants must deploy durable straws or face per-cover penalties. Parisian brasseries respond by branding house-designed stainless steel formats as signature table elements.
Certification-driven preference rotation is visible in California municipal procurement. School districts and airport concessionaires now require BPI or CMA compostability adjacent to reusability credentials. Buyers bundle straw specifications with broader serviceware sustainability scorecards that weight lifecycle impact above unit price.
Reusable Straw Market Segmentation
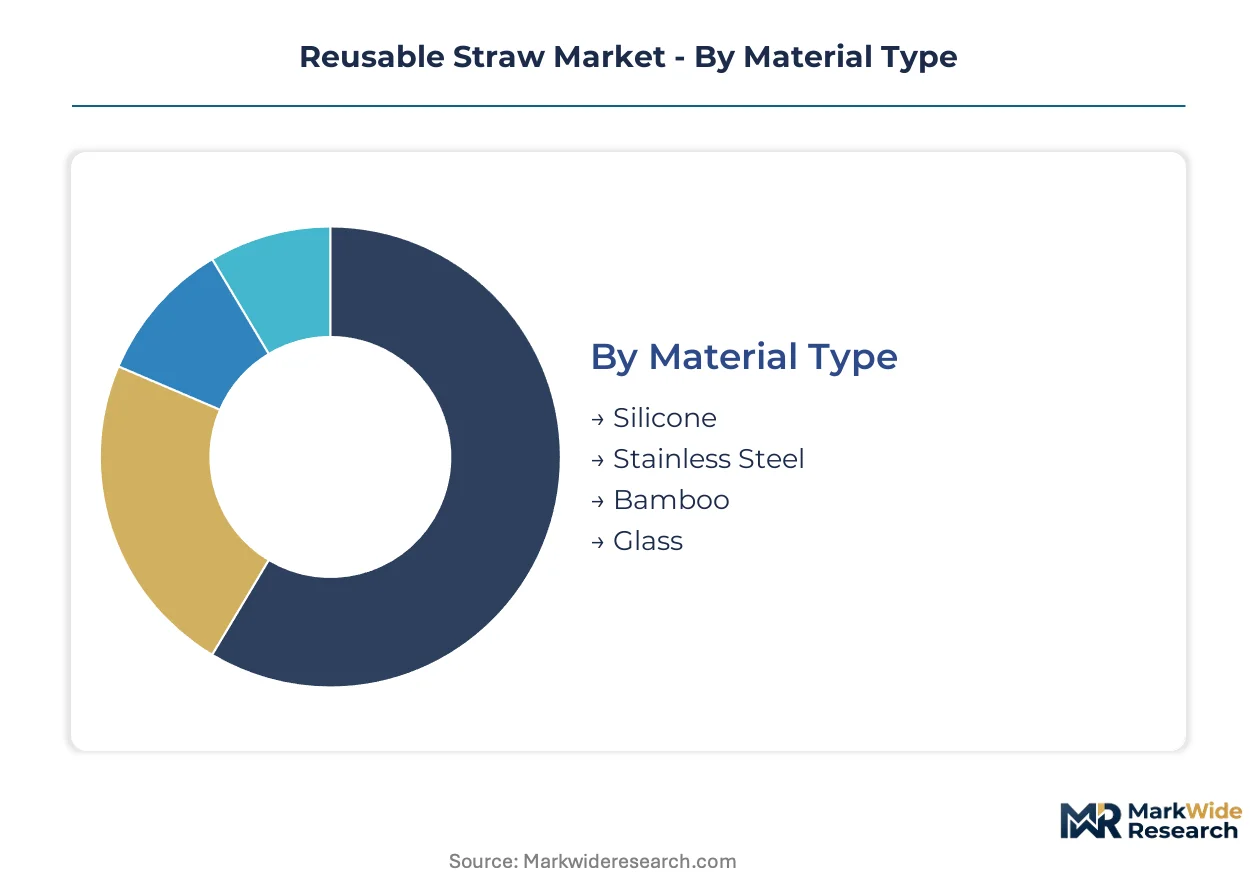
Material specifications determine compliance pathways across jurisdictions with divergent food-contact regulations. Size geometries and packaging formats shape channel economics and procurement eligibility for quick-service operators.
Material Type:
Technical composition governs thermal performance, dishwasher compatibility, and regulatory clearance across FDA, ECHA, and national packaging laws.
- Stainless Steel:18/8 austenitic grade delivers thermal durability and seamless laser-welded construction that eliminates bacterial harborage. Quick-service chains in Germany specify this format for fleet-wide conversion to meet extended producer responsibility fee structures.
- Silicone:Platinum-cured medical-grade formulation enables collapsible geometries that pass five-hundred-cycle dishwasher testing. Commuter demographics in metropolitan rail corridors favor pouch-format portability for daily carry.
- Bamboo:Cellulose-lignin composite requires moisture-resistant coating to prevent microbial degradation. Artisan producers face REACH substance inventory documentation gaps that restrict German retail channel access.
- Glass:Borosilicate variant offers chemical inertness but carries breakage liability in high-turnover foodservice. California insurers classify these as product liability exposures, elevating coverage costs for restaurant operators.
Mature deployment sits with Stainless Steel. Newer deployment is concentrated in Silicone.
Size:
Bore diameter and length specifications align with beverage viscosity and vessel geometry across household and commercial applications.
- Jumbo:12mm bore diameter accommodates tapioca pearls and smoothie particulates that paper alternatives cannot satisfy. Taiwanese-style beverage shops in Los Angeles and London drive procurement concentration for this specification.
- Regular:Standard 6-8mm diameter serves carbonated and still beverages across household and casual dining contexts. Mass-market retail channels in California school districts favor this format for cost-effective volume procurement.
- Mini:Reduced diameter targets espresso and cortado applications in specialty coffee formats. Limited commercial penetration restricts this segment to premium household gifting contexts.
- Extra Tall:Extended length accommodates tumbler and venti-format vessels popular in commuter demographics. On-the-go use cases in metropolitan rail corridors favor this geometry for compatibility with reusable bottle ecosystems.
Volume concentration clusters around Jumbo for commercial foodservice. Household penetration favors Regular.
Use Case:
End-use context determines durability requirements, sanitation protocols, and replacement cycle economics.
- Restaurants:High-turnover environments demand seamless stainless steel construction with dishwasher-safe ratings exceeding five hundred cycles. France's AGEC anti-waste statute mandates reusable tableware for on-premise consumption, compressing payback periods below eighteen months.
- On-the-Go:Commuter and travel contexts prioritize collapsible silicone formats with pouch packaging for pocket portability. Metropolitan rail corridors in Germany and California show concentration for this use case.
- Household:Domestic settings favor multi-material assortments with cleaning brushes and storage cases. Child-safe flexibility in silicone variants captures family demographics concerned with injury risk.
- Events:Temporary gatherings require deposit-return schemes or branded disposable alternatives that satisfy single-use plastics directives. Reverse logistics infrastructure gaps limit scalable deployment for this segment.
Procurement scale is expanding most quickly in Restaurants. Margin stability sits with Household.
Packaging Type:
Distribution format shapes retail shelf presence, e-commerce shipping economics, and foodservice procurement bundling.
- Pouch:Flexible fabric or silicone sleeve enables pocket storage and commuter portability. On-the-go demographics in metropolitan rail corridors favor this format for daily carry integration.
- Boxed:Rigid presentation supports retail shelf placement and gifting contexts. Premium positioning in German retail channels leverages this format for brand differentiation.
- Bundle:Multi-unit assortments with cleaning brushes and cases serve household replacement cycles. California municipal procurement favors bundled specifications for school district volume purchasing.
- Dispenser:Countertop or wall-mounted units support quick-service robotics integration and standardized straw geometries. McDonald's and Starbucks pilot locations specify this format for automated beverage dispenser compatibility.
Channel access concentrates in Pouch for commuter retail. Institutional procurement favors Dispenser.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shenzhen and Hamburg drive manufacturing concentration for stainless steel feedstock. Special economic zones in California and Tamil Nadu accelerate assembly capacity for export markets. Municipal procurement mandates in these zones compress supplier qualification timelines.
United States
California school districts and Los Angeles bubble-tea clusters anchor domestic procurement. FDA food-contact substance notifications govern silicone colorant approvals. San Francisco airport concessionaires mandate BPI-certified bundled formats for volume purchasing.
Germany
Extended producer responsibility fees under the national packaging law compress payback periods for restaurant chains. REACH substance inventory requirements govern silicone and metal alloy documentation. Berlin quick-service robotics pilots specify seamless laser-welded geometries for equipment compatibility.
France
AGEC anti-waste statute mandates reusable tableware for on-premise dining by 2025. Parisian brasseries brand house-designed stainless steel formats as signature elements. Highway rest-stop deposit systems create closed-loop revenue models in the Île-de-France corridor.
United Kingdom
Taiwanese-style beverage shops in London drive jumbo-format stainless steel procurement. The UK Environment Bill extends single-use plastics restrictions beyond EU baselines. Manchester metropolitan rail corridors show concentration for pouch-format commuter portability.
China
Shandong Province 18/8 stainless steel producers face margin compression from nickel price volatility. GB standards govern food-contact metal specifications for export markets. Shenzhen special economic zone assembles silicone collapsible formats for North American and European distribution.
Reusable Straw Market Key Industry Players
Shandong-based metal fabricators anchor one tier; California and Oregon specialists hold premium positioning through design differentiation. The vendor base spans three tiers: commodity stainless steel producers, platinum-cured silicone specialists, and vertically integrated lifestyle brands. Strategic archetypes include feedstock-integrated metalworkers, medical-grade silicone molders, and direct-to-consumer sustainability marketers. Capacity expansion and certification-driven portfolio diversification dominate competitive moves.
Among US-based sustainability marketers, Klean Kanteen and Simply Straws exemplify premium-tier positioning through geographic branding. The Final Co. LLC occupies a position within the collapsible silicone archetype, representing medical-grade formulation capabilities. These three entities anchor distinct competitive vectors without overlapping material specializations.
| Leading Market Players |
|---|
| Klean Kanteen |
| Simply Straws |
| The Final Co. LLC |
| Eco-Products, Inc |
| Greens Steel |
| Buluh Straws |
| GoSili |
| FinalStraw |
| Glass Dharma LLC |
| Others |
Cost & Logistics Intelligence
Nickel feedstock volatility from London Metal Exchange trading cascades through 18/8 stainless steel pricing tiers, compressing margins for Shandong Province fabricators while elevating premiums for REACH-certified European suppliers serving German quick-service restaurant chains.
Pricing Analysis
Lead-time premiums reward rapid fulfillment for California bubble-tea operators facing AGEC compliance deadlines, while spot inventory discounts clear excess pouch-format silicone stock. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and dishwasher-cycle durability ratings. Pricing pressure stems from nickel cost pass-through in metal grades, with California school districts exhibiting highest price sensitivity against German brasseries absorbing premiums for seamless laser-welded construction.
Supply Chain Analysis
Direct-to-foodservice channels handle fleet-scale procurement from McDonald's and Starbucks pilot locations, bypassing retail markup. Manufacturing concentrates in China's Shandong Province for stainless steel feedstock, Germany for REACH-compliant finishing, and California for silicone assembly serving West Coast distribution. Raw material flows draw from Indonesian nickel mines, platinum-cured silicone resin from German chemical suppliers, and borosilicate glass tubing from specialty foundries. Single-source vulnerability in nickel supply creates tariff exposure for metal-dependent producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reusable straw market occupies a material-transition phase where platinum-cured silicone collapsible formats displace legacy borosilicate glass in commuter applications, driven by dishwasher durability testing advances and child-safety liability concerns.
For Market Incumbents: To counter nickel price volatility eroding stainless steel margins, anchor feedstock security through backward integration into scrap metal recycling networks or long-term offtake agreements with Indonesian mining consortia. Simultaneously, deepen certification moats by accelerating FDA food-contact substance notifications for novel coating technologies ahead of 120-day review cycles. For New Entrants and Emerging Players: France's AGEC anti-waste statute opens a window for deposit-system operators to capture closed-loop revenue at highway rest-stop locations, where reverse logistics infrastructure gaps persist. Target Parisian brasseries seeking house-branded stainless steel formats as signature table elements, leveraging direct sales relationships bypassing distributor markups. For Investors and Strategic Acquirers: McDonald's and Starbucks robotics integration announcements are the leading indicator that standardized straw geometries will lock in equipment compatibility winners. Position for five-to-ten year consolidation around medical-grade silicone molders with platinum-curing capabilities and established dishwasher-testing protocols, monitoring municipal procurement mandate expansions beyond California into New York and Washington state as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Investment | Unlocks German retail channel access blocked from artisan bamboo producers lacking toxicology documentation. |
| Platinum-Cured Silicone Scale-Up | Captures commuter demographic demand for five-hundred-cycle dishwasher durability in metropolitan rail corridors. |
| Deposit-Return System Deployment | Creates closed-loop revenue models at France's highway rest stops mandated by AGEC anti-waste compliance. |
| Robotics Compatibility Standardization | Locks in equipment integration with McDonald's and Starbucks automated beverage dispenser pilots. |
| Municipal Procurement Certification | Secures preferential vendor status in California school districts requiring BPI-adjacent sustainability credentials. |
Research Approach
Multi-period observation of nickel price volatility, municipal procurement mandate adoption rates, and dishwasher durability testing standards anchored the trend analysis, supplemented by interviews with quick-service restaurant procurement directors, platinum-cured silicone molders, REACH compliance consultants, and foodservice equipment manufacturers. Secondary validation drew from FDA food-contact substance notification databases, ECHA substance inventory filings, California SB 54 implementation guidance, and EU Single-Use Plastics Directive enforcement records. Bottom-up volume modeling triangulated against top-down regulatory impact assessments.
Input-output matrices mapped material feedstock flows through fabrication tiers to end-use segments across the projection horizon, with segmentation dimensions spanning material type, size geometry, use case context, and packaging format. CAGRs derived from regression analysis of historical procurement volume against regulatory enforcement timelines, incorporating bubble-tea consumption cluster expansion and robotics integration adoption curves as industry-specific demand drivers.
Caveats apply where nickel supply disruptions, REACH substance inventory expansion, or municipal procurement mandate delays could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Reverse Logistics for Reusable Packaging and Containers Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Refillable and Reusable Packaging Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Reusable Water Bottle Market