
 Returnable Transport Packaging (RTP) Market | 2026-2036
Returnable Transport Packaging (RTP) Market Size, Share, and Industry Trends Forecast 2026-2036
Returnable Transport Packaging (RTP) Market Analytics
Asset-light leasing and pooled-loop financing is reconfiguring competitive entry barriers in RTP, allowing mid-tier logistics providers to deploy fleets without capital-heavy balance sheets. Schoeller Allibert leverages European manufacturing scale to dominate reusable container supply for automotive tier-one suppliers. Brambles Limited anchors global pallet pooling through CHEP's closed-loop infrastructure across grocery and retail channels. Rehrig Pacific Company specializes in dairy and beverage sector totes with embedded RFID tracking capabilities.
Returnable Transport Packaging comprises durable, multi-trip containers, pallets, totes, and bins engineered from plastic, metal, wood, or composite materials to protect goods through repeated distribution cycles. Polypropylene injection-molded containers typically withstand 50 to 100 rotation cycles, while steel stillages serve heavy automotive component transport across assembly plant networks. Plastic pallets lead volume share in food and beverage cold chains due to hygienic washdown compatibility and consistent dimensional tolerance for automated handling systems. Composite material adoption accelerates in pharmaceutical end-use where lightweight strength and contamination resistance command premium positioning against traditional wood alternatives.
The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds and reuse targets that directly shape RTP product design and pooling service economics. FDA food contact material compliance in the United States governs plastic resin selection and wash validation protocols for beverage and dairy sector totes. ISO 8611 pallet testing standards and ECHA REACH substance restrictions on additives further constrain material formulation choices across export-oriented manufacturing bases. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded asset pools that fail cross-border compliance verification.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing automotive and food sector suppliers to abandon single-use packaging in favor of pooled RTP assets, compressing payback periods for multi-trip container investments and reshaping supplier-buyer contracting terms.
Growth Catalysts
- EU reuse mandates:The EU Packaging and Packaging Waste Regulation establishes binding reuse targets that directly accelerate RTP deployment across grocery retail and automotive supply chains.
- Cold chain expansion:Food and beverage distributors in the United States and Brazil are scaling refrigerated RTP fleets to replace expanded polystyrene single-use shippers in protein and dairy distribution.
- Embedded tracking:RFID and NFC sensor integration into plastic totes enables real-time location monitoring, reducing asset loss rates and unlocking usage-based leasing models for mid-tier logistics providers.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs fluctuate with crude oil and natural gas markets, compressing margins for injection-molded container manufacturers without long-term supply agreements.
- Pool fragmentation:Incompatible container specifications across regional pooling networks create stranded assets that cannot rotate across Germany, Mexico, and United States automotive assembly corridors.
- Steel stillage weight:Heavy metal transport packaging limits fuel efficiency gains in long-haul trucking, constraining adoption despite superior durability for powertrain components.
Strategic Opportunities
- Pharmaceutical cold chain:Temperature-validated composite RTP with embedded phase-change materials addresses contamination resistance requirements that exclude wood pallets from vaccine distribution.
- Asset-light financing:Third-party logistics providers in Brazil and Mexico are accessing RTP fleets through pay-per-use contracts rather than capital purchase, expanding addressable demand.
- REACH compliance arbitrage:ECHA substance restrictions on plastic additives create first-mover advantage for suppliers with validated alternative formulations certified for EU cross-border pooling.
Industry Challenges
- Wash validation protocols:FDA food contact material compliance requires documented thermal and chemical cleaning cycles for dairy sector totes, extending deployment timelines for new resin formulations.
- Legacy WMS integration:Enterprise resource planning systems at tier-one automotive suppliers lack API connectivity to RTP pool management platforms, forcing manual inventory reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Returnable Transport Packaging (RTP) Market |
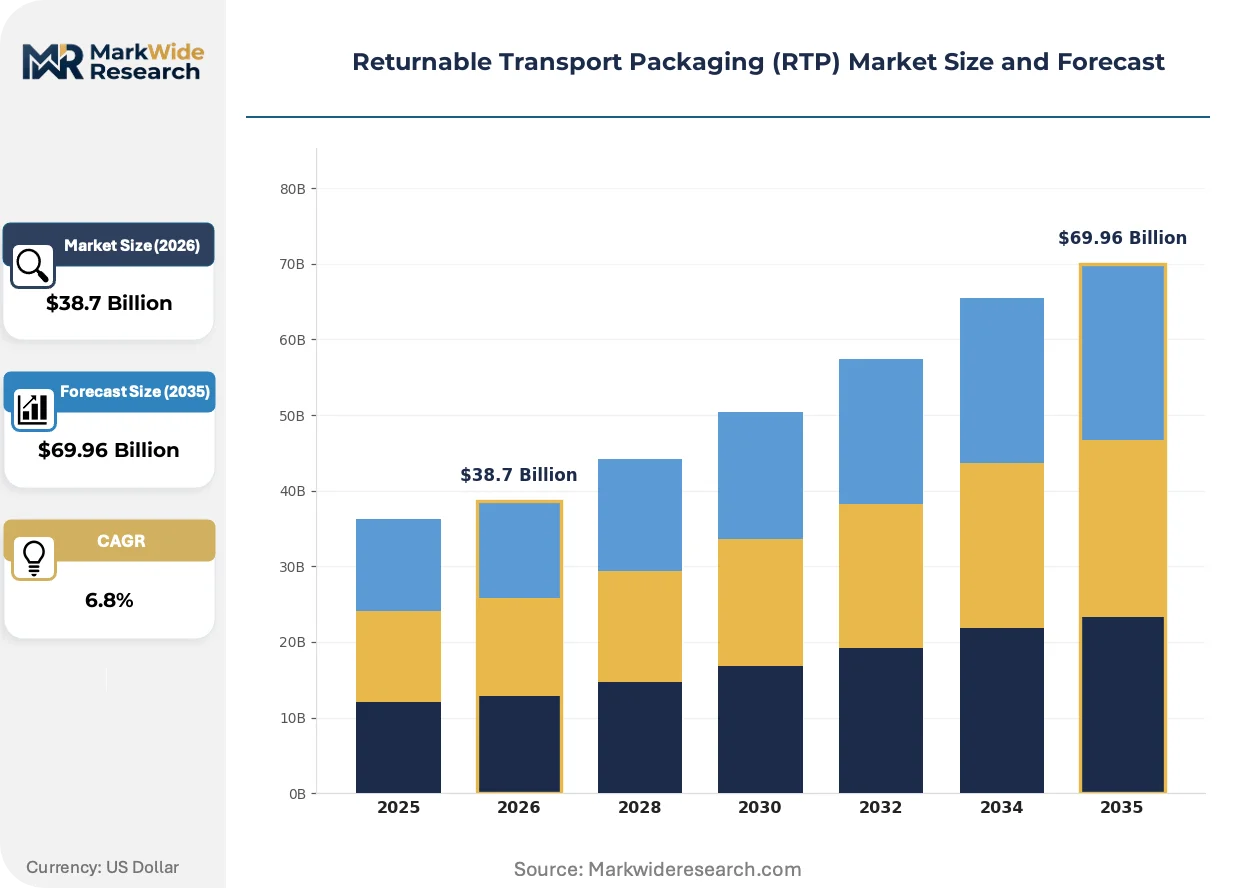
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Pallets, Totes, Bins Material: Plastic, Metal, Wood, Composite End User: Food & Beverage, Automotive, Consumer Goods, Pharmaceuticals Distribution Channel: Direct Sales, Retail, E-commerce, Third-Party Logistics |
| Companies Covered | Brambles Limited (CHEP), Mauser Packaging Solutions, Schoeller Allibert, Nefab Group, DS Smith, Orbis Corporation, Greif Inc., Rehrig Pacific Company, IFCO Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Returnable Transport Packaging (RTP) Market Evolving Landscape
Digital asset tracking and material science advances are converging to transform RTP from passive shipping equipment into intelligent supply chain infrastructure with predictive maintenance capabilities.
Composite sandwich panels combining fiberglass skins with polypropylene honeycomb cores are migrating from aerospace material transfer to pharmaceutical distribution, where Bayer and Sanofi procurement teams specify lightweight, x-ray-transparent containers for high-value biologics. These structures cut tare weight by 40% versus steel equivalents while maintaining ISO 8611 dynamic load ratings, compressing total cost of ownership calculations for international lane operators.
ECHA REACH substance restrictions on short-chain chlorinated paraffins and certain phthalate plasticizers are compelling polypropylene compounders to reformulate container resins ahead of 2025 sunset dates. Automotive tier-one suppliers in Germany now require full material disclosure certificates for RTP entering their plants, shifting procurement evaluation criteria from unit price to compliance documentation completeness and audit trail reliability.
Buyers in the United States beverage sector are consolidating vendor relationships from fragmented regional pool operators toward national contracts with integrated tracking and billing platforms. Anheuser-Busch and Coca-Cola bottling partners now specify RFID-tagged totes with automated damage assessment at return depots, replacing visual inspection workflows and compressing settlement cycles from 45 days to weekly reconciliation. This procurement concentration favors logistics providers with captive washing networks and multi-state depot density.
Returnable Transport Packaging (RTP) Market Segmentation
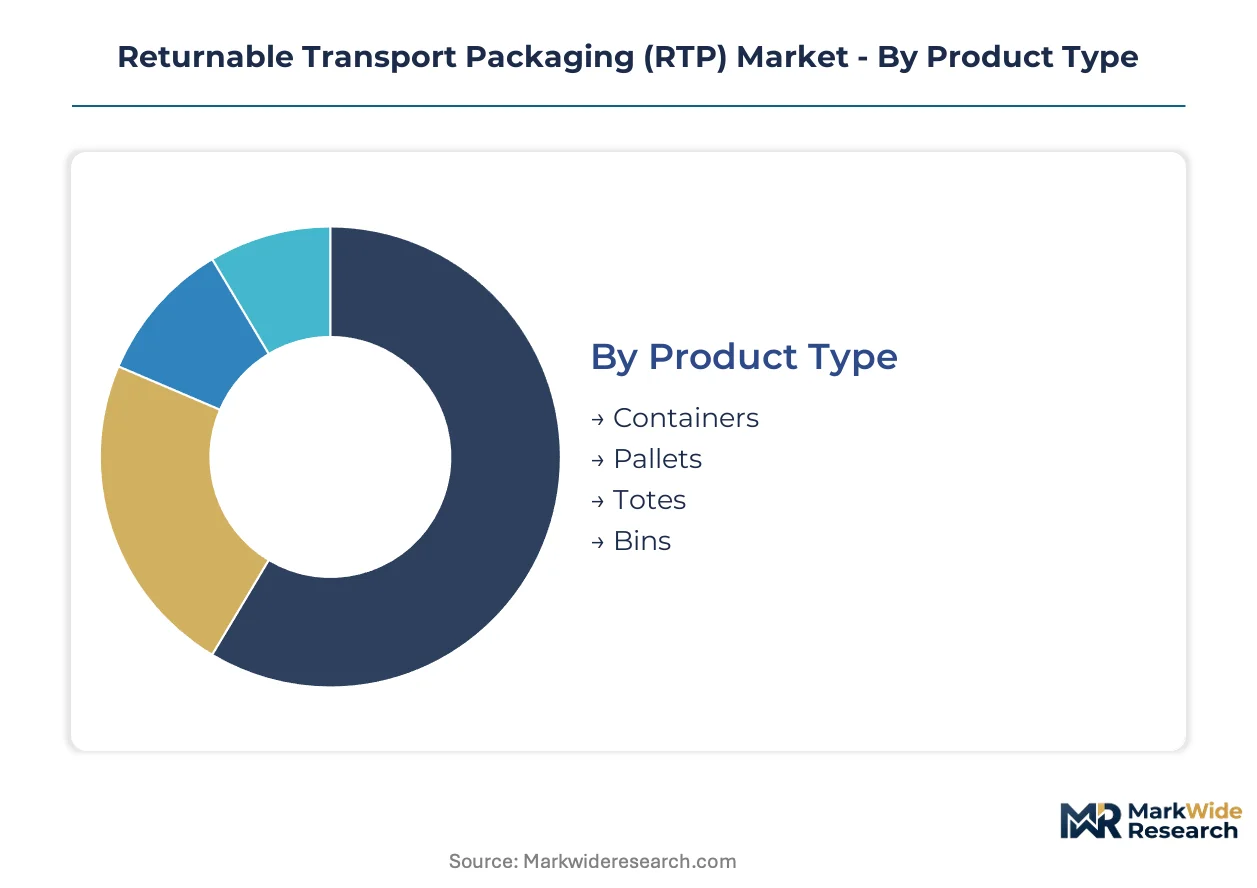
RTP segmentation reveals how material properties, product form factors, and end-use requirements create distinct competitive arenas with diverging margin profiles and technology investment priorities. Procurement patterns across these dimensions determine whether suppliers compete on manufacturing scale, compliance documentation, or embedded digital capabilities.
Product Type:
Mature container formats dominate installed bases, while emerging pallet pooling models are capturing capital reallocation from single-use alternatives.
- Containers:Injection-molded polypropylene units withstand 50 to 100 rotation cycles with standardized footprints for automated handling. Food and beverage cold chains in the United States and Brazil are replacing expanded polystyrene shippers with refrigerated container fleets to meet sustainability mandates.
- Pallets:Plastic variants lead volume in hygienic washdown environments, with consistent dimensional tolerance enabling automated warehouse integration. Grocery retail consolidation toward national contracts with integrated tracking platforms favors providers with multi-state depot density and captive washing networks.
- Totes:Dairy and beverage sector specifications demand FDA food contact material compliance with documented thermal cleaning cycles. Embedded RFID tracking capabilities enable real-time location monitoring and usage-based leasing models for mid-tier logistics providers.
- Bins:Bulk agricultural and industrial applications favor collapsible designs for backhaul efficiency. Steel reinforcements address heavy component transport across automotive assembly plant networks.
Containers retain volume leadership; pallets hold the steepest expansion curve.
Material:
Cost tiers separate commodity resins from premium formulations, with compliance arbitrage emerging as a procurement differentiator.
- Plastic:Polypropylene injection-molding commands the broadest application range, though resin price volatility tied to crude oil and natural gas markets compresses margins without long-term supply agreements. ECHA REACH restrictions on short-chain chlorinated paraffins are compelling compounders to reformulate ahead of regulatory sunset dates.
- Metal:Steel stillages deliver superior durability for powertrain components across Germany and Mexico automotive corridors. Heavy tare weight limits fuel efficiency gains in long-haul trucking, constraining adoption despite structural integrity advantages.
- Wood:Pallet manufacturing concentrates in low-cost production basins, though contamination susceptibility excludes the material from pharmaceutical and premium food applications. ISPM-15 heat treatment requirements add documentation burden for cross-border pooling.
- Composite:Fiberglass-polypropylene honeycomb sandwich panels cut tare weight by 40% versus steel while maintaining ISO 8611 dynamic load ratings. Bayer and Sanofi procurement teams specify these structures for high-value biologics distribution where x-ray transparency and contamination resistance command premium positioning.
Plastic retains volume leadership; composite holds the steepest expansion curve.
End User:
Application-specific compliance requirements fragment procurement evaluation criteria across verticals with diverging validation protocols.
- Food & Beverage:Cold chain expansion drives refrigerated RTP fleet scaling, with protein and dairy distributors in the United States and Brazil abandoning single-use shippers. FDA wash validation protocols extend deployment timelines for new resin formulations entering dairy sector totes.
- Automotive:OEMs in Germany and Mexico are expanding RTP programs to reduce single-use packaging waste, compressing payback periods for multi-trip container investments. Tier-one suppliers now require full material disclosure certificates, shifting procurement criteria from unit price to compliance documentation completeness.
- Consumer Goods:Retail consolidation favors national contracts with integrated tracking and billing platforms over fragmented regional pool operators. Automated damage assessment at return depots compresses settlement cycles from 45 days to weekly reconciliation.
- Pharmaceuticals:Temperature-validated composite RTP with embedded phase-change materials addresses contamination resistance requirements that exclude wood pallets from vaccine distribution. Lightweight strength properties support international lane operator total cost of ownership calculations.
Food & Beverage retains volume leadership; Pharmaceuticals holds the steepest expansion curve.
Distribution Channel:
Customer type determines capital deployment models, with asset-light financing expanding addressable demand among capital-constrained intermediaries.
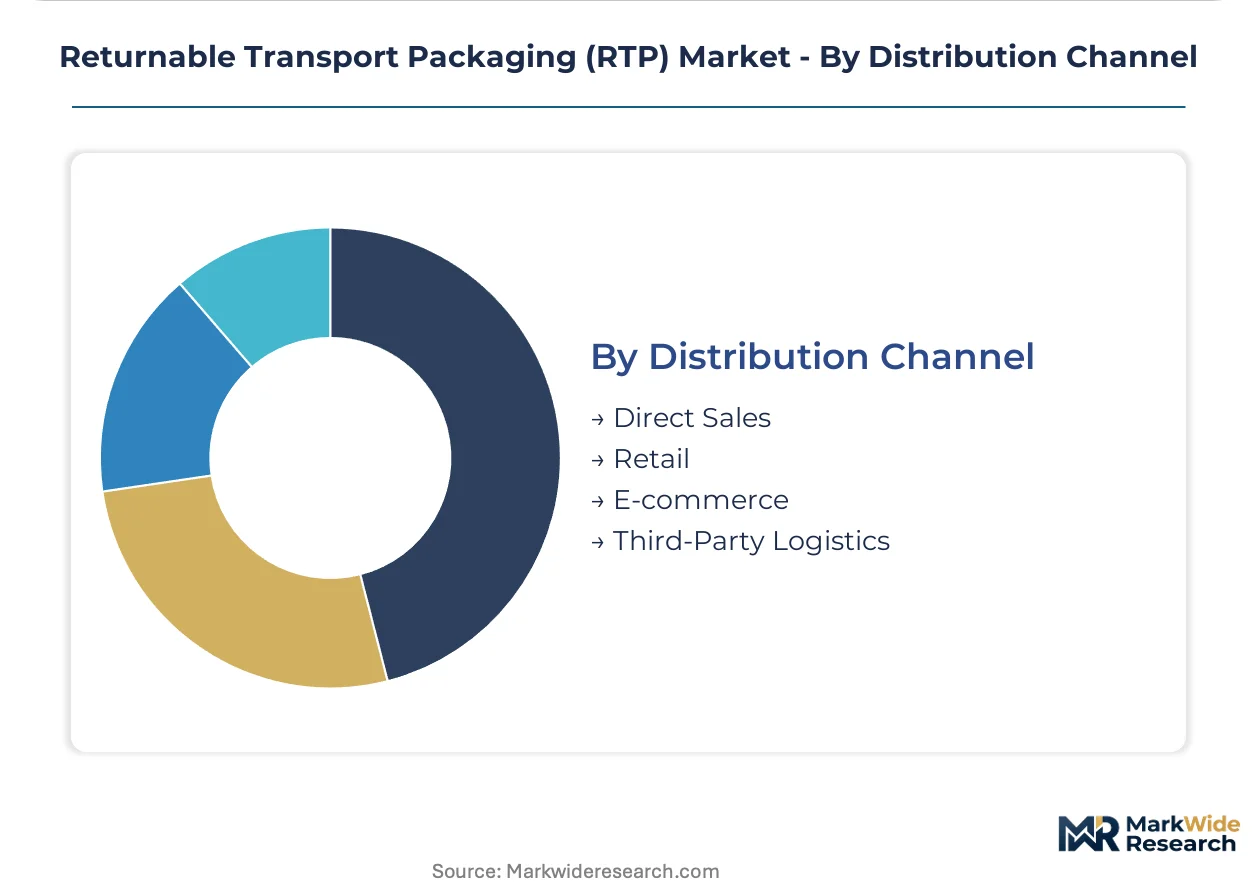
- Direct Sales:Automotive OEMs and tier-one suppliers favor direct procurement relationships with manufacturers capable of custom specification development and compliance documentation. Long-term contracts embed volume commitments with penalty structures for pool fragmentation.
- Retail:Grocery chains consolidate vendor relationships toward integrated national platforms with RFID-tagged assets and automated reconciliation. Procurement concentration favors logistics providers with captive washing networks.
- E-commerce:Fulfillment center throughput requirements drive demand for standardized container footprints compatible with robotic handling systems. Return logistics complexity limits RTP penetration relative to single-use alternatives.
- Third-Party Logistics:Asset-light leasing and pooled-loop financing allow mid-tier providers to deploy fleets without capital-heavy balance sheets. Pay-per-use contracts in Brazil and Mexico are expanding addressable demand among regional distributors.
Direct Sales retains volume leadership; Third-Party Logistics holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where automotive OEMs and beverage distributors negotiate multi-year pooled fleet contracts, while Brazilian and Mexican markets absorb higher per-unit costs due to fragmented pool infrastructure and import-dependent resin supply chains.
United States
Cold chain expansion in protein and dairy distribution drives refrigerated RTP fleet scaling across the Midwest and Southeast. FDA food contact material compliance governs plastic resin selection and wash validation protocols for beverage sector totes. Anheuser-Busch and Coca-Cola bottling partners in Missouri and Georgia now specify RFID-tagged assets with automated damage assessment.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are expanding RTP programs to eliminate single-use packaging waste from tier-one supplier networks. ECHA REACH substance restrictions on short-chain chlorinated paraffins compel polypropylene compounders to reformulate container resins ahead of regulatory sunset dates. Stuttgart and Munich procurement teams require full material disclosure certificates.
Mexico
Automotive assembly plant networks in Nuevo León and the Bajío Region generate concentrated demand for steel stillages transporting powertrain components. The absence of domestic resin production exposes injection-molded container manufacturers to polypropylene price volatility tied to US Gulf Coast feedstock markets. Third-party logistics providers in Querétaro access RTP fleets through pay-per-use contracts.
Brazil
Food and beverage distributors in São Paulo and Minas Gerais are scaling refrigerated RTP fleets to replace expanded polystyrene single-use shippers. ANVISA sanitary regulations extend deployment timelines for new resin formulations entering dairy sector applications. Regional pool fragmentation creates stranded assets that cannot rotate across Mercosur trade corridors.
China
Manufacturing scale in the Yangtze River Delta and Pearl River Delta supports export-oriented RTP production for automotive and electronics supply chains. GB standards and MIIT circular economy directives push domestic suppliers toward reusable packaging models. Shenzhen and Shanghai logistics hubs face pool incompatibility with EU and North American container specifications.
Returnable Transport Packaging (RTP) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between pooled-loop operators managing captive washing networks and injection-molding fabricators supplying standardized container footprints. Three archetypes dominate: European manufacturing-scale suppliers, North American pallet-pooling platforms, and regional specialists with embedded tracking capabilities. Competitive moves concentrate on geographic expansion through depot density acquisition and portfolio diversification into temperature-validated composite materials.
Among European manufacturing-scale suppliers, Schoeller Allibert and Nefab Group exemplify the compliance-documentation archetype serving automotive tier-one networks. Brambles Limited anchors the pooled-loop platform tier through CHEP's closed-loop infrastructure. Rehrig Pacific Company occupies a specialist position with dairy and beverage sector concentration. These three represent distinct competitive vectors: continental manufacturing scale, global pooling network density, and vertical application expertise.
| Leading Market Players |
|---|
| Brambles Limited (CHEP) |
| Mauser Packaging Solutions |
| Schoeller Allibert |
| Nefab Group |
| DS Smith |
| Orbis Corporation |
| Greif Inc. |
| Rehrig Pacific Company |
| IFCO Systems |
| Others |
Value Network & Pricing Analysis
Polypropylene resin production concentration in the US Gulf Coast and Middle Eastern petrochemical corridors feeds directly into margin compression dynamics for injection-molded container manufacturers lacking long-term supply agreements. Automotive OEM procurement teams in Germany and beverage distributors in the United States capture downstream value through multi-year pooled fleet contracts that lock in volume discounts.
Pricing Analysis
Configured-to-order pricing for custom automotive stillages commands 35-50% premiums over standard container footprints, with FDA food-contact certification tiers and embedded RFID tracking capabilities as the primary price differentiation drivers. Cost compression in commodity-grade plastic pallets is intensifying because resin price volatility tied to crude oil markets squeezes manufacturers without backward integration into compounder networks. Tier-one automotive suppliers demonstrate the lowest price sensitivity due to compliance documentation requirements, while regional dairy distributors in Brazil exhibit acute sensitivity to per-unit lease rates.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for automotive tier-one suppliers in Germany, with supply-chain finance facilities increasingly bridging working capital gaps for injection-molding fabricators. Manufacturing capacity concentrates in Germany, China, and the United States, with raw material dependencies on polypropylene feedstock, steel coil, and fiberglass roving. Single-source vulnerability in specialized resin formulations creates exposure to ECHA REACH regulatory restrictions. Distribution runs through captive washing networks and third-party depot operators that manage pool rotation logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RTP is crossing into platform-economics territory where interoperability standards and embedded digital infrastructure determine competitive survival, with the EU Packaging and Packaging Waste Regulation's reuse mandates forcing ecosystem-wide coordination.
For Market Incumbents: Build compliance-documentation moats by investing in full material disclosure certificate databases and audit trail systems that automotive OEMs now mandate. Add captive washing capacity in Nuevo León and São Paulo to defend against regional pool fragmentation that strands assets across Mercosur corridors. Threat substitution from single-use fiber-based alternatives is accelerating as sustainability mandates tighten.
For New Entrants and Emerging Players: Build out pay-per-use financing platforms targeting mid-tier third-party logistics providers in Brazil and Mexico who lack capital-heavy balance sheets for fleet ownership. Pharmaceutical cold chain applications represent the most penetrable white-space, with temperature-validated composite containers for biologics distribution offering premium positioning. Go-to-market through national beverage distributor contracts with automated damage assessment capabilities.
For Investors and Strategic Acquirers: Capital is best deployed toward pooled-loop operators with multi-state depot density and integrated tracking platforms that capture procurement consolidation in US grocery retail. Long-term viability over the next decade hinges on interoperability with automated warehouse systems and robotic handling infrastructure. Watch for inflection signals in ECHA alternative formulation certifications that create first-mover advantage for REACH-compliant resin suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Interoperable container footprints enable rotation across Germany-Mexico-US automotive corridors without asset stranding. |
| Backward Integration into Resin Compounding | In-house polypropylene formulation control insulates margins from Gulf Coast feedstock volatility and REACH sunset risks. |
| Captive Washing Network Expansion | Multi-state depot density in US Midwest and Southeast secures national beverage distributor procurement concentration. |
| Embedded Sensor Integration | RFID-tagged totes with automated damage assessment compress settlement cycles from 45 days to weekly reconciliation. |
| Temperature-Validated Composite Development | Phase-change material integration addresses Bayer and Sanofi specifications for high-value biologics distribution. |
Research Methodology
The analysis maps container, pallet, tote, and bin sub-sectors, each validated through procurement directors at automotive OEMs, beverage distribution executives, cold chain logistics operators, and resin compounder technical leads. Primary interview findings triangulate against secondary sources including FDA food contact material guidance, ECHA REACH substance restriction databases, customs trade flow records, and ISO 8611 pallet testing documentation. Bottom-up unit economics modeling and top-down market sizing converge through cross-validation against pooled fleet operator transaction data.
Assumptions held fixed include EU Packaging and Packaging Waste Regulation reuse mandate enforcement timelines, polypropylene resin price band stability, and automotive production cluster geographic distribution. Segmentation dimensions modeled span product type, material formulation, end-use vertical, and distribution channel complexity. CAGRs derive from installed base rotation velocity, replacement cycle compression, and cold chain fleet expansion trajectories across protein and dairy distribution networks.
Stress conditions across resin price volatility bands, regulatory sunset date acceleration, and automotive production shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding compliance trajectory and technology adoption curves. Macroeconomic contraction, unilateral regulatory deviation, or breakthrough single-use material substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Reverse Logistics for Reusable Packaging and Containers Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Greenwrap Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Reconditioned Packaging Market