
 Reusable Egg Containers Market | 2026-2036
Reusable Egg Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Egg Containers Market Analytics
European molded-fiber and rigid plastic capacity is rebalancing toward reusable formats as supermarkets de-list disposable polystyrene egg packs. Tupperware Brands Corporation leverages direct-to-consumer channels and party-plan distribution to sustain brand loyalty in household segments across North America and Asia-Pacific. Tosca Ltd anchors the commercial foodservice channel through pooled container programs that dominate supply chain logistics for grocery retailers and egg processors. Huhtamäki competes in the European retail sector with fiber-based and reusable hybrid designs that navigate tightening packaging waste directives.
Reusable egg containers are durable, multi-trip vessels engineered from food-grade polymers, tempered glass, or molded pulp composites, typically designed with 6-cavity to 24-cavity configurations and snap-lock or hinged closures to protect shell integrity through repeated handling cycles. Plastic containers lead unit volume due to low production cost and impact resistance, though biodegradable alternatives represent the fastest-growing material category as retailers and foodservice operators respond to extended producer responsibility mandates. Cartons and clamshells capture the dominant share of packaging type demand, while 12-cavity sizes occupy the core household segment and 24-cavity formats concentrate margin pools in farm-direct and restaurant procurement channels.
The EU Packaging and Packaging Waste Regulation and REACH compliance frameworks shape material selection and recyclability thresholds for containers sold across European markets, while FDA food-contact substance notifications govern polymer and additive approvals in the United States. California's SB 54 and similar state-level extended producer responsibility laws in Oregon and Colorado are forcing domestic manufacturers to redesign for circularity and post-consumer recycled content minimums. Stakeholders must monitor evolving patchwork regulations and decide whether to regionalize product lines or pursue unified global designs that exceed the strictest jurisdictional standards.
Market Dynamics
Supermarket de-listing of disposable polystyrene egg packs is forcing container manufacturers to retool molded-fiber and rigid plastic capacity toward reusable formats. This supply-side pivot concentrates investment in Europe where deposit-return infrastructure already exists.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Compliance deadlines for disposable alternatives are accelerating retailer procurement of multi-trip containers across Germany, France, and the Netherlands.
- Zero-waste retail formats:Specialty grocery stores and unpackaged food chains are embedding reusable egg containers into circular logistics programs.
- Molded pulp composites:Advances in biodegradable fiber technology are opening shelf space previously reserved for petroleum-based packaging.
Market Restraints
- Food-grade polymer cost volatility:Virgin polypropylene and polyethylene prices fluctuate with petrochemical feedstock markets, compressing margins for rigid plastic container producers.
- Single-use substitution persistence:Lightweight disposable cartons retain cost advantages in price-sensitive institutional foodservice channels.
- REACH additive restrictions:ECHA scrutiny of certain plasticizers and colorants limits material formulation flexibility for European market entry.
Strategic Opportunities
- Pooled logistics programs:Closed-loop container pooling services for restaurant chains and institutional kitchens create recurring revenue streams outside retail.
- California SB 54 compliance:Extended producer responsibility mandates in Oregon and Colorado are generating first-mover advantages for circular-design specialists.
- Hybrid fiber-polymer designs:Combining biodegradable bases with durable snap-lock closures addresses both waste directives and handling durability requirements.
Industry Challenges
- Post-consumer recycled content verification:FDA food-contact substance notifications and state-level PCR minimums require costly third-party certification timelines.
- Legacy washing infrastructure incompatibility:Commercial dishwashing systems in foodservice operations often damage fiber-based containers, limiting format adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Egg Containers Market |
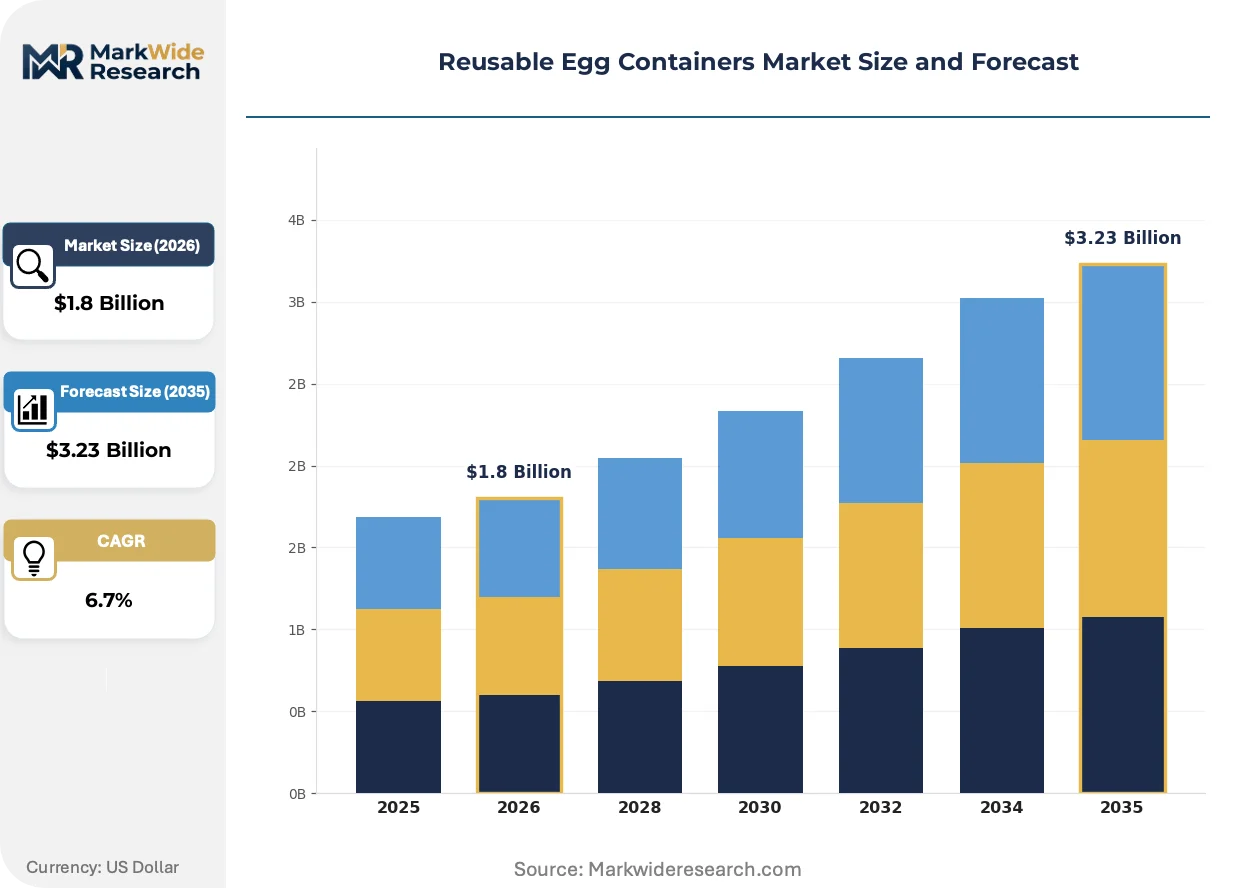
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Glass, Biodegradable, Metal Packaging Type: Cartons, Trays, Clamshells, Baskets End User: Households, Restaurants, Grocery Stores, Farms Size: 6-Cavity, 12-Cavity, 18-Cavity, 24-Cavity |
| Companies Covered | Snips S.r.l., Tosca Ltd, Tupperware Brands Corporation, Huhtamäki, Pactiv Evergreen, LocknLock Co., Ltd., Progressive International Corp., Anhui Yinling Plastic Industry Co., Ltd., Rubbermaid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Egg Containers Market Evolving Landscape
Material science breakthroughs and regulatory compliance architectures are converging to redefine container performance standards. Manufacturers now engineer for multi-trip durability while navigating biodegradability mandates.
Interlocking snap-lock mechanisms using food-grade silicone gaskets are modularizing protective closure systems across 6-cavity to 24-cavity formats. European supermarket chains are specifying these designs for their private-label reusable lines. The technology is modularizing how processors configure container families for different channel requirements without retooling entire production lines.
REACH compliance frameworks are tightening recyclability thresholds for polymer additives and colorants sold across European markets. Industrial consequence includes accelerated R&D spending on additive-free natural fiber alternatives. Germany's packaging sector is responding fastest, with several processors already certifying cradle-to-cradle material flows.
Restaurant procurement officers now specify outcome-verified circularity metrics rather than unit price in container tenders. Farm-direct supply contracts are displacing traditional distributor relationships in the 24-cavity institutional segment. This pattern is most visible in the Netherlands where agricultural cooperatives operate integrated packing-washing-return logistics.
Reusable Egg Containers Market Segmentation
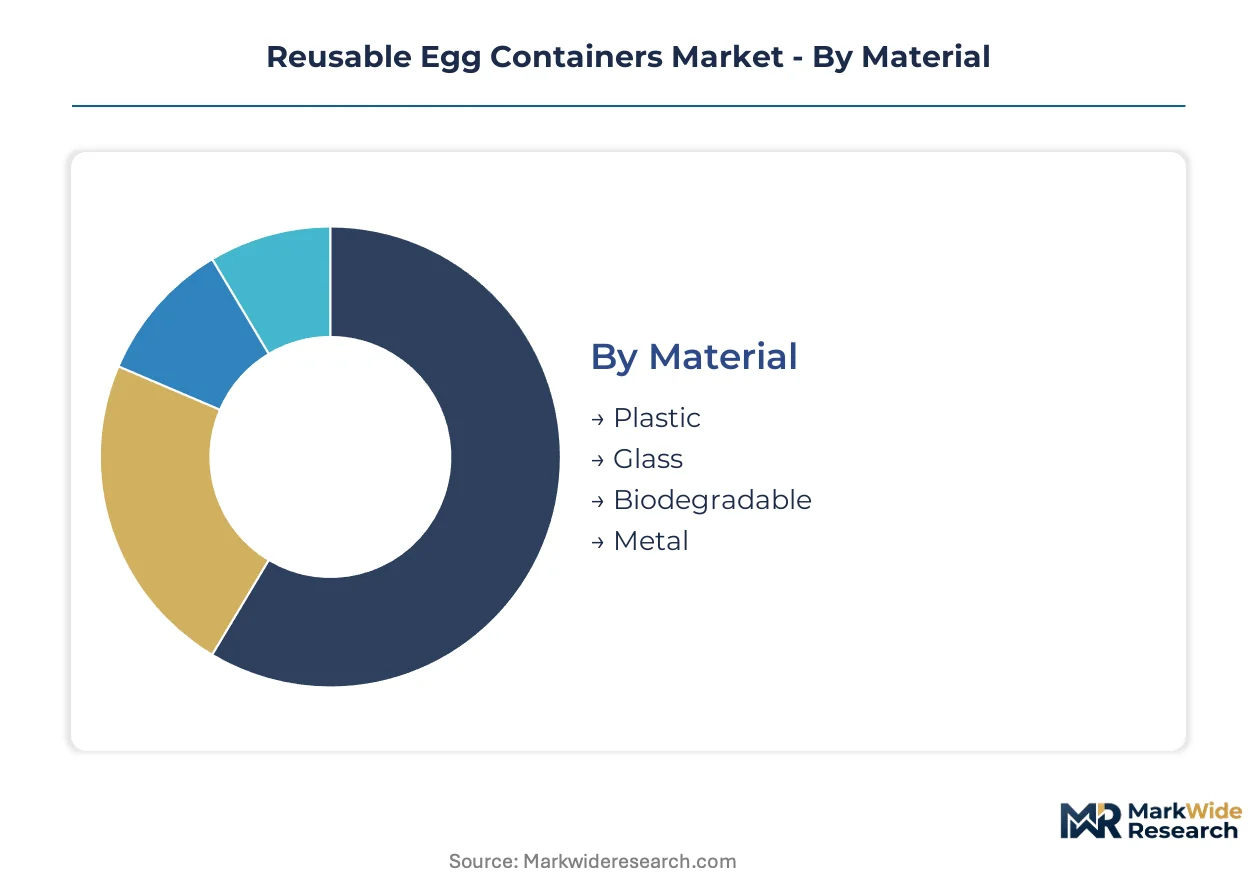
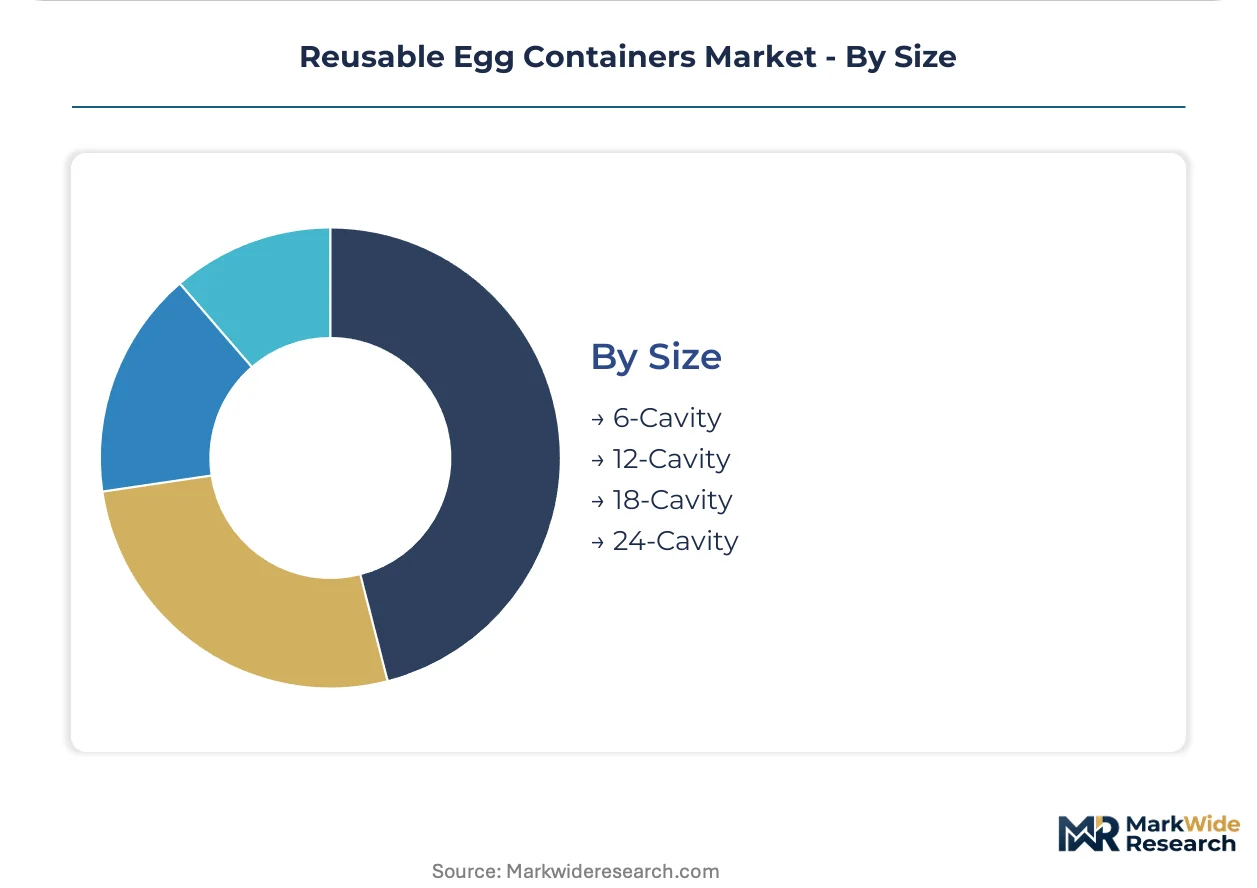
Reusable egg container procurement varies sharply across material grades, packaging geometries, and channel requirements. Manufacturers configure product lines around washing durability, nesting density, and closure mechanics rather than one-size-fits-all specifications.
Material:
Polymer composition and biodegradability credentials determine regulatory compliance pathways and end-use eligibility across jurisdictions.
- Plastic:Food-grade polypropylene and polyethylene formulations dominate unit economics through injection-molded production at scale. Demand concentrates in German and Dutch supermarket private-label programs where deposit-return infrastructure supports multi-trip logistics.
- Glass:Tempered soda-lime construction delivers premium shelf presentation and chemical inertness for farm-direct channels. French agricultural cooperatives specify glass for organic egg distribution where consumer willingness-to-pay absorbs higher per-unit cost.
- Biodegradable:Molded pulp composites from agricultural residues navigate EU Packaging and Packaging Waste Regulation thresholds. Netherlands-based retailers are embedding these into zero-waste store formats.
- Metal:Stainless-steel variants serve institutional kitchen environments requiring commercial dishwashing compatibility.
Mature deployment sits with Plastic. Newer deployment is concentrated in Biodegradable.
Packaging Type:
Structural geometry governs nesting efficiency, shell protection, and automated handling compatibility across retail and foodservice workflows.
- Cartons:Hinged-lid rectangular formats with individual cavity dividers remain the household standard. German discount chains specify cartons for their deposit-return egg programs.
- Trays:Open-top designs without lids optimize commercial kitchen throughput where speed of access outweighs retail presentation requirements.
- Clamshells:Single-piece hinged constructions with snap-lock closures dominate grocery retail shelf placement. French hypermarkets are transitioning clamshell specifications toward fiber-polymer hybrid materials.
- Baskets:Perforated designs with carry handles serve farm-direct and farmers-market channels where visual product inspection drives purchase decisions.
Cartons retain the widest installed base. Clamshells are climbing the fastest as retailers phase out single-use polystyrene.
End User:
Procurement specifications diverge between consumer convenience priorities and institutional operational constraints.
- Households:12-cavity formats with refrigerator-stackable profiles capture recurring purchase patterns. North American direct-to-consumer channels sustain brand loyalty through color-customization options.
- Restaurants:High-throughput kitchens specify 24-cavity trays with commercial-dishwasher tolerance. Pooled container programs in the Netherlands serve this segment through closed-loop logistics.
- Grocery Stores:Private-label reusable lines require shelf-ready presentation and deposit-system compatibility. EU supermarket chains are consolidating specifications to reduce SKU complexity.
- Farms:Direct-sales operations favor 18-cavity and 24-cavity formats with farm-branding surfaces. Agricultural cooperatives in France operate integrated packing-washing-return systems.
Grocery Stores anchor current procurement volume. Farms represent the steepest expansion trajectory as direct-to-consumer channels disintermediate distributors.
Size:
Cavity count determines nesting economics, consumer purchase frequency, and channel margin structure.
- 6-Cavity:Compact formats target single-person households and specialty egg varieties. Premium positioning in urban European markets supports higher per-egg packaging cost.
- 12-Cavity:The standard household configuration balances weekly consumption patterns with refrigerator storage efficiency. German and French retailers specify this as their baseline reusable offering.
- 18-Cavity:Mid-scale formats serve small restaurants and extended-family households. Farm-direct channels in the Netherlands favor this size for mixed-grade egg sales.
- 24-Cavity:Institutional-scale designs concentrate in restaurant procurement and agricultural cooperative distribution. Margin pools are deepest here due to volume contracting and logistics integration.
12-Cavity maintains the broadest adoption. 24-Cavity formats are gaining share fastest as foodservice operators consolidate container specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene feedstock from the US Gulf Coast and petrochemical clusters in Rotterdam anchor container manufacturing capacity. Deposit-return infrastructure in Northern Europe and extended producer responsibility mandates in California shape procurement patterns. Retail consolidation in Germany and France concentrates demand for standardized reusable formats.
Germany
Discount supermarket chains and agricultural cooperatives drive container procurement through integrated deposit-return systems. The EU Packaging and Packaging Waste Regulation mandates compliance deadlines that accelerate retailer transitions from disposable formats. Bavaria-based processors operate closed-loop washing facilities serving farm-direct distribution networks.
France
Hypermarket private-label programs and organic egg cooperatives specify tempered glass and fiber-polymer hybrid containers. REACH compliance frameworks restrict additive formulations, pushing manufacturers toward natural fiber alternatives. The Île-de-France region hosts packaging innovation clusters developing cradle-to-cradle certified material flows.
Netherlands
Zero-waste retail formats and institutional foodservice pooling programs create concentrated demand for 24-cavity formats. The national packaging waste covenant enforces extended producer responsibility on importers and domestic producers. Agricultural cooperatives in the Randstad operate integrated packing-washing-return logistics for restaurant supply chains.
United States
Direct-to-consumer channels and specialty grocery chains sustain demand for color-customized household formats. California SB 54 and parallel state laws in Oregon and Colorado mandate post-consumer recycled content minimums. The Pacific Northwest hosts molders retooling capacity toward circular-design specifications.
China
Export-oriented manufacturers supply fiber-based and injection-molded containers to European and North American retailers. GB standards and evolving dual carbon goals shape domestic material selection and energy efficiency requirements. The Yangtze River Delta concentrates molding capacity serving global private-label programs.
Reusable Egg Containers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable material certifications and regional compliance specializations. The vendor base spans multinational household brands, commercial pooling operators, and contract molders serving private-label programs. Three archetypes dominate: direct-to-consumer specialists leveraging brand loyalty, logistics integrators managing closed-loop container pools, and private-label fabricators customizing for retailer specifications. Competitive moves concentrate on portfolio diversification into hybrid fiber-polymer designs and geographic expansion through distributor partnerships.
Among Italy-based specialists, Snips S.r.l. exemplifies the European household-format archetype with heritage positioning in kitchen storage categories. Tosca Ltd anchors the commercial pooling tier through supply chain integration with grocery retailers and egg processors. Tupperware Brands Corporation occupies the direct-to-consumer vector, sustaining brand equity through party-plan distribution and color-customization programs across North American and Asia-Pacific markets.
| Leading Market Players |
|---|
| Snips S.r.l. |
| Tosca Ltd |
| Tupperware Brands Corporation |
| Huhtamäki |
| Pactiv Evergreen |
| LocknLock Co., Ltd. |
| Progressive International Corp. |
| Anhui Yinling Plastic Industry Co., Ltd. |
| Rubbermaid |
| Others |
Value Network & Pricing Analysis
EU supermarket chains consolidating private-label specifications around deposit-return compatibility are forcing container molders to absorb certification and redesign costs that compress per-unit margins across standard-grade offerings.
Pricing Analysis
Warranty-bundled washing durability guarantees now separate premium tiers from unbundled economy alternatives in commercial procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume contracting scale. Cost compression in standard-grade plastic containers is intensifying because virgin polypropylene feedstock volatility passes through from Rotterdam petrochemical clusters. Institutional foodservice buyers exhibit highest price sensitivity due to operational throughput priorities, while farm-direct channels absorb premium positioning for branded presentation formats.
Supply Chain Analysis
Food-grade polypropylene supply rests on US Gulf Coast crackers, Rotterdam petrochemical complexes, and Yangtze River Delta resin distributors. Container production draws from virgin polymer pellets, molded pulp agricultural residues, and tempered soda-lime glass feedstocks. Single-source vulnerability concentrates in specialty silicone gasket suppliers serving snap-lock mechanism specifications. Distribution runs through supermarket private-label procurement offices, agricultural cooperative logistics hubs, and foodservice pooling operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container manufacturers are racing to secure backward integration into washing infrastructure and fiber-pulp sourcing to capture margin pools currently leaking to third-party logistics providers.
For Market Incumbents: Deploy closed-loop washing facility networks to defend against emerging pooling-service entrants. Expand molded-pulp composite capacity in the Netherlands to preempt biodegradable format demand acceleration. EU Packaging and Packaging Waste Regulation compliance timelines threaten incumbents lacking cradle-to-cradle certification pathways. For New Entrants and Emerging Players: Small restaurant chains without pooled logistics access represent the most penetrable buyer archetype currently underserved by incumbent pooling programs. Target 18-cavity hybrid fiber-polymer formats for farm-direct channels displacing traditional distributor relationships. A direct sales force embedded with agricultural cooperatives offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with biodegradable material specialists given EU regulatory mandates accelerating format transitions. The five-to-ten year viability window favors processors with verified cradle-to-cradle flows and integrated washing-return infrastructure. Watch for California SB 54 enforcement patterns as the signal indicating North American demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Washing Infrastructure | Captures recurring revenue streams currently flowing to third-party pooling operators in the Netherlands. |
| Hybrid Fiber-Polymer Format Launch | Addresses both EU biodegradable mandates and commercial dishwasher durability requirements in foodservice. |
| Agricultural Cooperative Partnership | Secures farm-direct volume contracting that displaces traditional distributor relationships in France. |
| Deposit-Return System Certification | Unlocks German supermarket private-label procurement specifications requiring interoperability. |
| Direct-to-Consumer Channel Expansion | Sustains brand premium capture through color-customization programs in North American households. |
Research Methodology
Trade association filings, EU regulatory databases, and customs shipment records formed the secondary backbone of this analysis. Primary interviews with supermarket category buyers, agricultural cooperative logistics managers, container molding plant engineers, and foodservice procurement officers validated demand-side assumptions. Bottom-up unit shipment estimates and top-down market value reconciliation triangulated across these sources.
Bottom-up modeling tracked cavity count configurations, material grade specifications, and channel-specific procurement patterns across the analysis window. Segmentation dimensions included packaging geometry, end-user operational requirements, and regional regulatory compliance clusters. CAGRs derived from trend extrapolation of deposit-return system adoption curves and extended producer responsibility enforcement trajectories. Forecast inputs incorporated molded-pulp composite capacity buildout timelines and polymer feedstock price elasticity assumptions.
Revisions become necessary when EU Packaging and Packaging Waste Regulation enforcement accelerates beyond modeled timelines or when virgin polypropylene price volatility exceeds historical bands. Forecasts reflect assumptions about supermarket de-listing commitments and agricultural cooperative integration rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Returnable Transport Packaging (RTP) Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Refillable and Reusable Packaging Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Micro-Packaging Market