
 Returnable Packaging Systems Market | 2026-2036
Returnable Packaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Returnable Packaging Systems Market Analytics
Closed-loop logistics networks are rewriting how manufacturers manage packaging assets across multi-site operations. ORBIS Corporation leverages its North American manufacturing footprint to sustain just-in-time container programs for automotive and food processing clients. Schoeller Allibert competes through pan-European pool management services that dominate reusable crate circulation in grocery retail.
Returnable packaging systems comprise durable, multi-trip containers, pallets, crates, and dunnage engineered from high-density polyethylene, steel, or engineered fiberboard to withstand standardized handling cycles of 50 to 500 uses. Their primary purpose is to replace single-use shipping materials with trackable, recoverable assets that lower total cost of ownership in high-volume supply chains. Plastic pallets lead the product category due to moisture resistance and RFID compatibility, while metal containers command premium positioning in heavy-automotive applications where load ratings exceed two tons. Dunnage represents the fastest-growing segment as custom-molded interior protection reduces part damage rates in electronics and precision component logistics.
The EPA promotes sustainable materials management guidelines that incentivize reusable transport packaging in federal procurement, while ISO 18600 series standards establish environmental performance criteria for packaging reuse systems. The EU Green Deal accelerates demand through binding waste-reduction targets that directly favor returnable formats over disposable alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks that shift financial liability for packaging recovery onto brand owners and their logistics partners.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing automotive OEMs and food retailers to replace single-use shipping materials with trackable, multi-trip assets, compressing payback periods for returnable container investments from years to months.
Growth Catalysts
- EU Green Deal waste-reduction mandates:Binding targets for packaging waste diversion accelerate replacement of disposable formats with reusable alternatives in German and French automotive supply chains.
- Automotive OEM container standardization:Tier-1 suppliers adopt modular crate systems to synchronize just-in-time delivery with assembly line sequencing, cutting per-trip packaging expenditure.
- RFID-embedded tracking infrastructure:Real-time location systems enable closed-loop asset recovery across multi-site manufacturing networks, reducing container loss rates.
Market Restraints
- High-density polyethylene price volatility:Resin cost swings compress margins for injection-molded pallet and crate manufacturers, deterring capacity expansion.
- China-centric dunnage tooling concentration:Custom-molded interior protection relies on specialized mold fabrication concentrated in East Asian supplier bases, exposing lead time risk.
- Legacy warehouse automation incompatibility:Existing conveyor and AS/RS systems designed for single-use corrugated struggle to handle rigid returnable container dimensions without retrofit.
Strategic Opportunities
- Indian pharmaceutical cold chain:Temperature-validated reusable shippers penetrate vaccine and biologics distribution where single-use expanded polystyrene faces regulatory scrutiny.
- CSRD-aligned ESG reporting:Corporate sustainability disclosure requirements create procurement preference for returnable packaging with verified lifecycle carbon data.
- Blockchain-IoT convergence:Immutable chain-of-custody records combined with sensor telemetry unlock outcome-based packaging-as-a-service pricing models.
Industry Challenges
- Asset pool balancing expertise scarcity:Manufacturers struggle to hire operations research analysts capable of optimizing container fleet sizing across stochastic demand patterns.
- ISO 18600 certification timelines:Third-party environmental performance verification for reuse systems extends sales cycles by six to twelve months in regulated industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Returnable Packaging Systems Market |
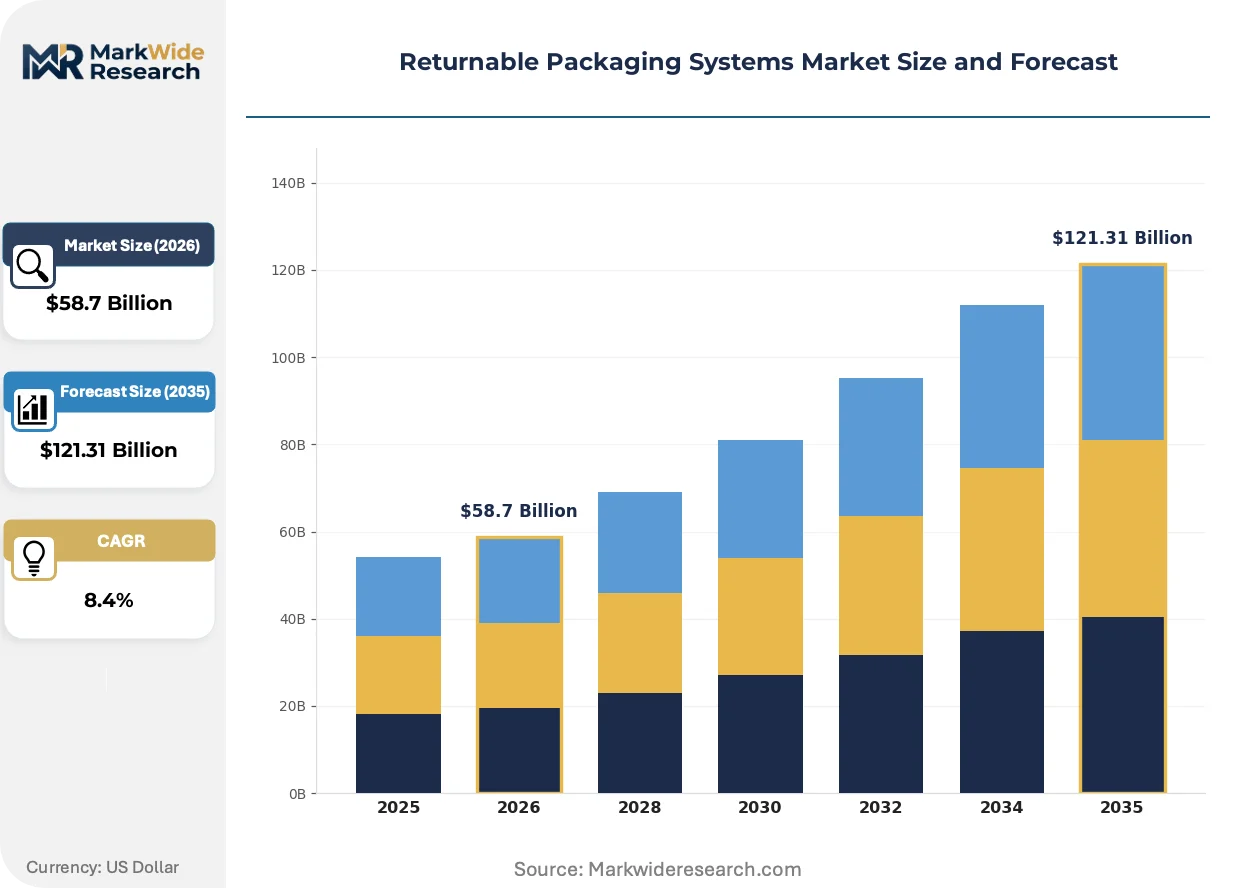
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pallets, Crates, Containers, Dunnage Material: Plastic, Metal, Fiberboard, Wood End User: Automotive OEMs, Food & Beverage, Retail, Electronics Distribution Channel: Direct Sales, Distributors, Online, Third-party Logistics |
| Companies Covered | ORBIS Corporation, Schoeller Allibert, Brambles, NEFAB Group, Myers Industries, DS Smith, Menasha Corporation, CHEP, Rehrig Pacific Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Returnable Packaging Systems Market Evolving Landscape
Digital traceability infrastructure and material science advances are compressing the cost-performance gap between returnable systems and disposable alternatives, while regulatory pressure locks in preference for circular formats.
Embedded RFID and NFC transponders in high-density polyethylene pallets enable real-time inventory visibility without manual scanning. Automotive manufacturers in Stuttgart and Wolfsburg deploy these tags to synchronize container returns with production schedules. Manual barcode tracking is rendering obsolete in high-velocity supply chains where labor cost and error rates determine competitive position.
The EU Green Deal's binding packaging waste targets are tightening recycled content thresholds for transport packaging placed on the market. This regulatory pressure forces fast-moving consumer goods distributors in Germany and the Netherlands to accelerate pool conversions from corrugated to reusable crate systems. Heavy-duty plastic pallets with post-consumer recycled content command procurement preference in retail grocery networks.
Consolidated buying by multinational automotive OEMs is compressing supplier margins while demanding extended geographic service coverage. Tier-1 packaging vendors respond with regional hub-and-spoke pool management networks that displace fragmented local container rental operations. This concentration is most visible in Bavaria and Baden-Württemberg, where supplier parks cluster around final assembly plants.
Returnable Packaging Systems Market Segmentation
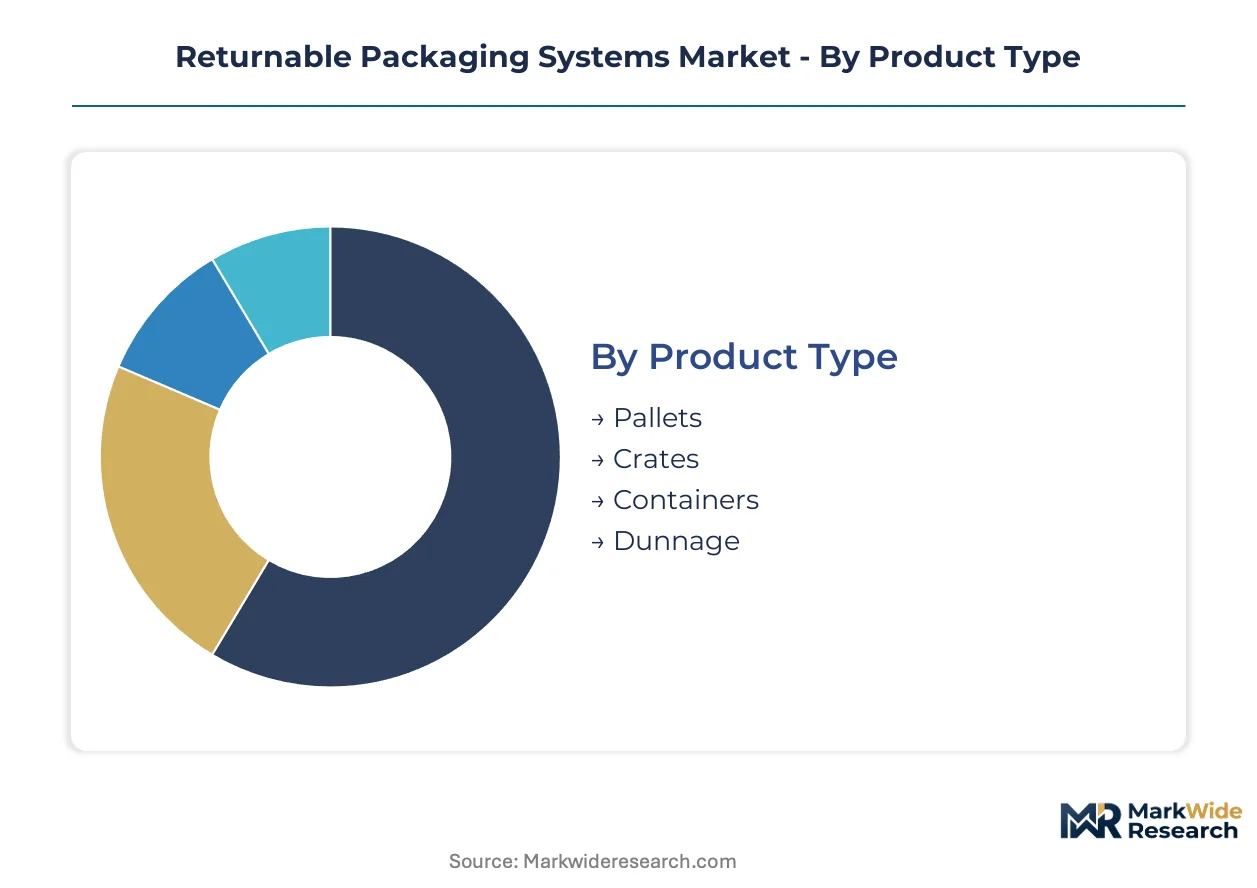
Returnable packaging systems demand precise segmentation because asset lifecycle economics vary dramatically by material durability, product geometry, and end-user handling intensity. Procurement patterns diverge sharply between automotive OEMs running closed-loop pool systems and food retailers managing seasonal crate flows.
Product Type:
After-sales service intensity climbs with product complexity, as dunnage requires custom mold maintenance while pallets need only fleet balancing.
- Pallets:Flat transport structures molded from high-density polyethylene or steel, engineered for fork truck entry and conveyor compatibility. German automotive clusters in Stuttgart and Wolfsburg deploy RFID-embedded plastic pallets to synchronize just-in-time returns with assembly sequencing, compressing payback periods through loss-rate reduction.
- Dunnage:Custom-molded interior protection fabricated from engineered foam or thermoformed plastics to cradle precision components during transit. Electronics manufacturers in Bavaria drive specification intensity here, as anti-static dunnage designs reduce damage rates for semiconductor shipments where single-trip packaging costs would prove prohibitive.
- Crates:Stackable rigid containers standardized for grocery retail pool systems.
- Containers:Large-capacity bulk bins for heavy automotive components.
Pallets hold the largest share; momentum sits with dunnage.
Material:
Cost tier stratification separates premium metal solutions from commodity fiberboard alternatives, with resin pricing volatility compressing mid-market plastic margins.
- Plastic:Injection-molded high-density polyethylene dominates through moisture resistance, chemical inertness, and embedded RFID compatibility. EU Green Deal recycled content mandates push German food retailers toward post-consumer resin formulations, though virgin resin price swings deter capacity expansion among molders.
- Metal:Steel and aluminum containers engineered for load ratings exceeding two tons in heavy-automotive powertrain logistics. Stuttgart-based OEMs specify metal for engine block transport where structural integrity failures would halt assembly lines, justifying premium positioning despite higher upfront capital.
- Fiberboard:Engineered corrugated alternatives for lighter-duty closed-loop applications.
- Wood:Traditional pallet material losing share to hygiene-sensitive plastic in food processing.
Plastic holds the largest share; metal gains share fastest in heavy-automotive applications.
End User:
Application-specific handling protocols create divergent asset turnover economics, with automotive demanding 500-use cycles versus retail accepting 50-use durability.
- Automotive OEMs:Tier-1 suppliers and final assembly plants operating synchronized supplier parks around Wolfsburg, Ingolstadt, and Stuttgart. Container standardization across Volkswagen Group and BMW supply bases enables modular crate systems that cut per-trip packaging expenditure while supporting just-in-time sequencing.
- Food & Beverage:Grocery retailers and beverage distributors managing high-velocity crate pools. Dutch supermarket chains accelerate conversion from corrugated to reusable crate systems under EU Packaging and Packaging Waste Regulation pressure, with Schoeller Allibert's pan-European pool services dominating circulation logistics.
- Retail:General merchandise distributors with seasonal demand volatility.
- Electronics:Precision component manufacturers requiring anti-static dunnage protection.
Automotive OEMs hold the largest share; food and beverage is expanding most quickly under regulatory pressure.
Distribution Channel:
Customer type concentration favors direct relationships with large OEMs, while fragmented mid-market demand flows through distributor networks.
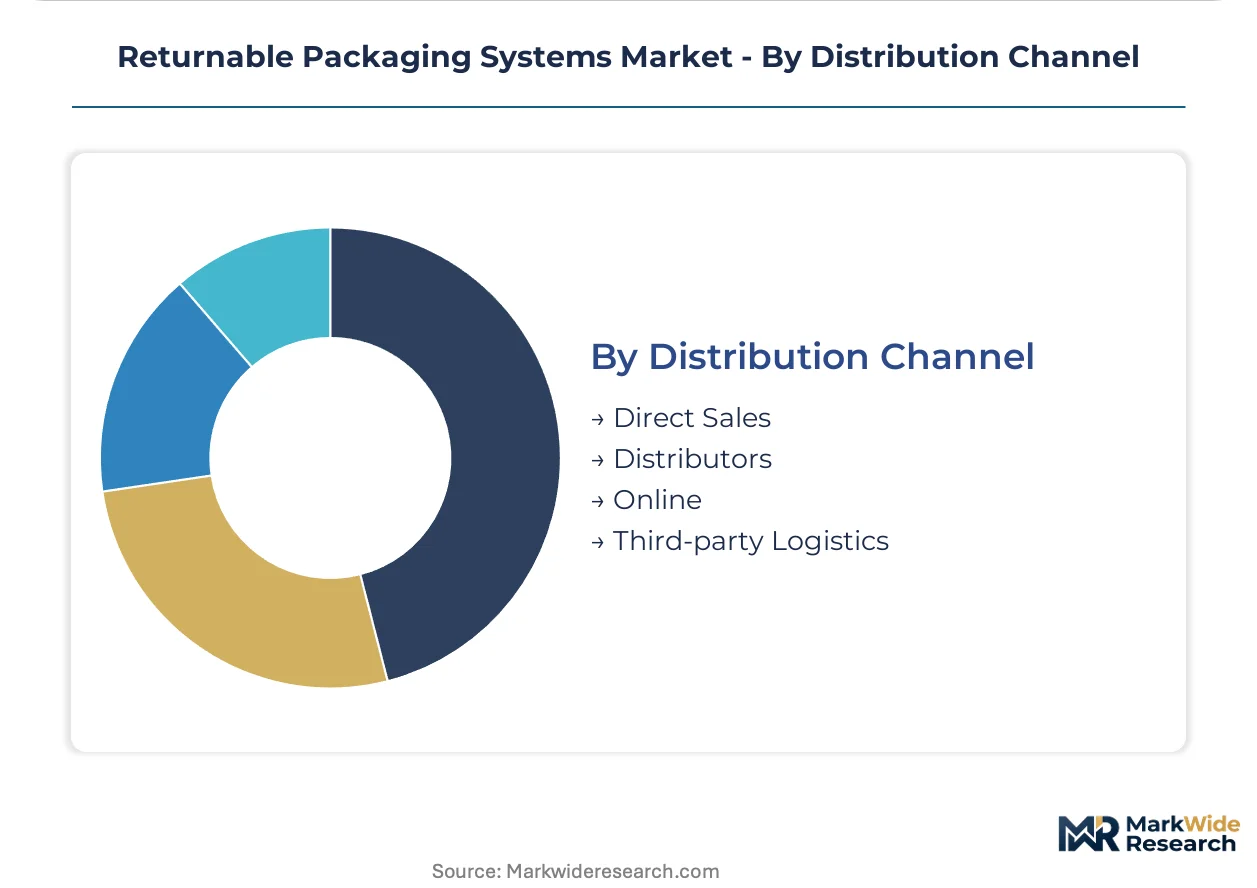
- Direct Sales:Manufacturer-to-OEM contracts for customized container programs with embedded asset tracking. ORBIS Corporation sustains direct relationships with North American automotive and food processing clients through regional manufacturing footprint proximity.
- Distributors:Regional inventory and technical service intermediaries serving mid-tier manufacturers lacking pool management expertise.
- Online:Digital procurement platforms for standardized pallet and crate specifications.
- Third-party Logistics:3PL-managed container pooling services outsourcing fleet balancing and recovery operations.
Direct sales holds the largest share; third-party logistics is climbing the fastest as OEMs outsource asset pool complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European regulatory pressure, while automotive OEMs and food retailers across Germany, the United States, China, Japan, and India reshape procurement patterns through closed-loop container investments.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive standardized crate adoption to synchronize just-in-time sequencing with assembly lines. The EU Packaging and Packaging Waste Regulation tightens recycled content mandates for transport packaging placed on the market. Bavaria and Baden-Württemberg concentrate supplier parks where Tier-1 vendors convert corrugated flows to reusable pool systems.
United States
Food processing clients and automotive manufacturers expand RFID-embedded pallet programs to cut asset loss rates across multi-site networks. The EPA promotes sustainable materials management guidelines that incentivize reusable transport packaging in federal procurement. ORBIS Corporation leverages its North American manufacturing footprint to sustain direct container programs near Detroit and Chicago industrial corridors.
China
Domestic automotive production clusters and export-oriented electronics manufacturers demand durable bulk containers for precision component logistics. The country's national standards administration enforces GB standards for reusable packaging performance in cross-border trade. Yangtze River Delta manufacturing hubs concentrate injection-molded pallet production serving both domestic OEMs and multinational assembly plants.
Japan
Precision electronics and automotive Tier-1 suppliers specify anti-static dunnage for semiconductor shipments where damage rates must approach zero. METI guidelines encourage resource-efficient packaging systems in manufacturing supply chains. Kanto and Kansai industrial belts host closed-loop crate pools serving Toyota and Honda supplier networks with standardized handling protocols.
India
Pharmaceutical cold chain distributors pilot temperature-validated reusable shippers for vaccine and biologics distribution. The national pharmaceutical regulator scrutinizes single-use expanded polystyrene alternatives under evolving environmental compliance frameworks. Maharashtra and Gujarat pharmaceutical clusters test returnable thermal packaging to replace disposable formats in temperature-sensitive logistics.
Returnable Packaging Systems Market Competitive Landscape
Pan-European pool operators and North American manufacturing specialists split the market between service-intensive asset management and proximity-driven direct sales models. The vendor base concentrates around three strategic archetypes: integrated pool managers sustaining multi-country crate circulation, regional manufacturers embedding RFID tracking at production origin, and diversified packaging conglomerates cross-selling disposable and reusable formats. Competitive moves center on hub-and-spoke network expansion and backward integration into resin compounding to hedge raw material volatility.
Among pool management specialists, Schoeller Allibert exemplifies the pan-European service archetype, while ORBIS Corporation anchors North American manufacturing proximity strategies. Brambles occupies a position representing the scale-driven asset network tier with CHEP-branded pallet pooling infrastructure.
| Leading Market Players |
|---|
| ORBIS Corporation |
| Schoeller Allibert |
| Brambles |
| NEFAB Group |
| Myers Industries |
| DS Smith |
| Menasha Corporation |
| CHEP |
| Rehrig Pacific Company |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta injection-molding clusters anchor global pallet supply, with capacity utilization swings in Ningbo and Taizhou directly transmitting to HDPE container pricing power in European automotive procurement offices.
Pricing Analysis
Price spreads between German automotive-specification pallets and Southeast Asian commodity-grade alternatives span threefold, with ISO 18600 certification tiers and embedded RFID functionality commanding substantial premiums. Three-tier pricing structure across premium, standard, and economy levels separates validated cold-chain dunnage from generic grocery crates from fiberboard substitutes. Pricing pressure stems from consolidated OEM buying power compressing Tier-1 supplier margins, while small-batch food processors prove most price-sensitive due to limited pool management scale.
Supply Chain Analysis
Upstream HDPE resin production concentrates in China, Saudi Arabia, and the United States, with automotive-grade colorant and RFID inlay components drawing from specialized Taiwanese and South Korean electronics suppliers. Raw material dependencies span petrochemical feedstocks, engineered foam formulations, and steel coil for heavy-automotive applications. Single-source vulnerability in custom dunnage mold fabrication exposes lead time risk. Distribution runs through regional hub-and-spoke pool networks displacing fragmented local rental operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Returnable packaging systems fragment across service models and material tiers, with EU Green Deal compliance deadlines creating urgent niche demand for certified pool operators lacking geographic coverage.
For Market Incumbents: Pre-empt margin compression from consolidated automotive procurement by anchoring backward integration into resin compounding near Stuttgart and Detroit production corridors. Extend ISO 18600 certification pipelines to compress six-to-twelve-month sales cycles threatening Tier-1 vendor retention.
For New Entrants and Emerging Players: Indian pharmaceutical cold chain distributors represent the most penetrable entry point, with temperature-validated reusable shippers replacing scrutinized expanded polystyrene in Maharashtra and Gujarat vaccine logistics. Target 3PL-managed container pooling partnerships to outsource asset balancing complexity while building regional density.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors RFID-embedded tracking infrastructure specialists over commodity molding capacity. Long-term viability hinges on blockchain-IoT convergence enabling packaging-as-a-service monetization. Monitor CSRD-aligned ESG procurement preference shifts as inflection signal for premium pool operator valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive HDPE supply hedges against virgin resin volatility compressing injection-molder margins. |
| RFID-NFC Embedded Tracking Deployment | Real-time location infrastructure enables outcome-based pricing models for automotive OEM contracts. |
| Pan-European Pool Network Expansion | Hub-and-spoke density in Bavaria and Baden-Württemberg displaces fragmented local container rental. |
| ISO 18600 Certification Acceleration | Third-party environmental verification unlocks regulated industry procurement preference under EU Green Deal. |
| Blockchain-IoT Platform Integration | Immutable chain-of-custody records support outcome-based packaging-as-a-service revenue models. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade databases, EPA sustainable materials management guidelines, EU regulatory filings, and automotive OEM procurement disclosures. Primary interviews spanned pool management operators, Tier-1 supplier procurement directors, 3PL fleet managers, and resin compounders. Secondary validation drew from ISO 18600 certification registries, IHS Markit vehicle production data, and SEC filings of diversified packaging conglomerates. Bottom-up asset fleet sizing estimates triangulate against top-down packaging expenditure allocations across end-use verticals.
Forecast inputs incorporate product type lifecycle economics, material durability tiers, and end-user handling intensity protocols across the analysis window. Segmentation dimensions span pallets, dunnage, crates, and containers by plastic, metal, fiberboard, and wood substrates, with automotive OEMs, food and beverage, retail, and electronics end-use categories modeled separately. CAGRs derive from regression against automotive production indices, EU packaging waste diversion targets, and RFID adoption curves in supply chain logistics.
Practitioners should monitor HDPE resin price volatility, EU Packaging and Packaging Waste Regulation enforcement timelines, and automotive OEM supplier consolidation announcements for early signals of forecast revision. Quarterly review of container loss rate trends and pool operator margin disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Greenwrap Market
Reusable Packaging
Reusable Food Wrap Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Refillable and Reusable Packaging Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Reusable Water Bottle Market