
 Portable Medical Devices Market | 2026-2036
Portable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Medical Devices Market Outlook
Asset-light leasing and pay-per-use project finance is tilting competitive access toward mid-tier manufacturers that previously faced capital barriers. Medtronic leverages captive financing arms to place continuous glucose monitors in hospital systems without upfront procurement. Siemens Healthineers anchors its portable imaging portfolio through long-term service contracts that bundle hardware with cloud analytics. OMRON Corporation differentiates in homecare channels by controlling pharmacy distribution networks across Asian markets.
Portable medical devices comprise battery-powered diagnostic and monitoring instruments engineered to operate outside fixed clinical installations, typically weighing under five kilograms with wireless data transmission capability. These instruments serve the primary commercial purpose of extending clinical-grade measurement accuracy to ambulatory, home-based, or emergency environments where stationary equipment proves impractical. Wearable monitors and handheld ECG units represent the fastest-expanding product categories as cardiac and metabolic patient cohorts shift toward continuous remote oversight. Bluetooth and cellular connectivity technologies command the deepest margin pools because subscription-based data routing creates recurring revenue streams beyond hardware sales. Homecare settings now absorb the dominant volume share as reimbursement frameworks in developed markets expand coverage for remote patient monitoring.
FDA premarket notification requirements under 21 CFR Part 820 enforce design controls and risk management protocols that shape product development timelines for US market entry. EU MDR and ISO 13485 quality system standards impose clinical evidence thresholds and post-market surveillance obligations that filter out undercapitalized applicants seeking CE marking. Japan's PMDA enforces QMS ministerial ordinances that demand in-country testing for wireless medical devices, adding a geographic compliance layer for cellular-enabled products. Stakeholders must weigh regulatory capital requirements against connectivity monetization potential when prioritizing market entry sequences.
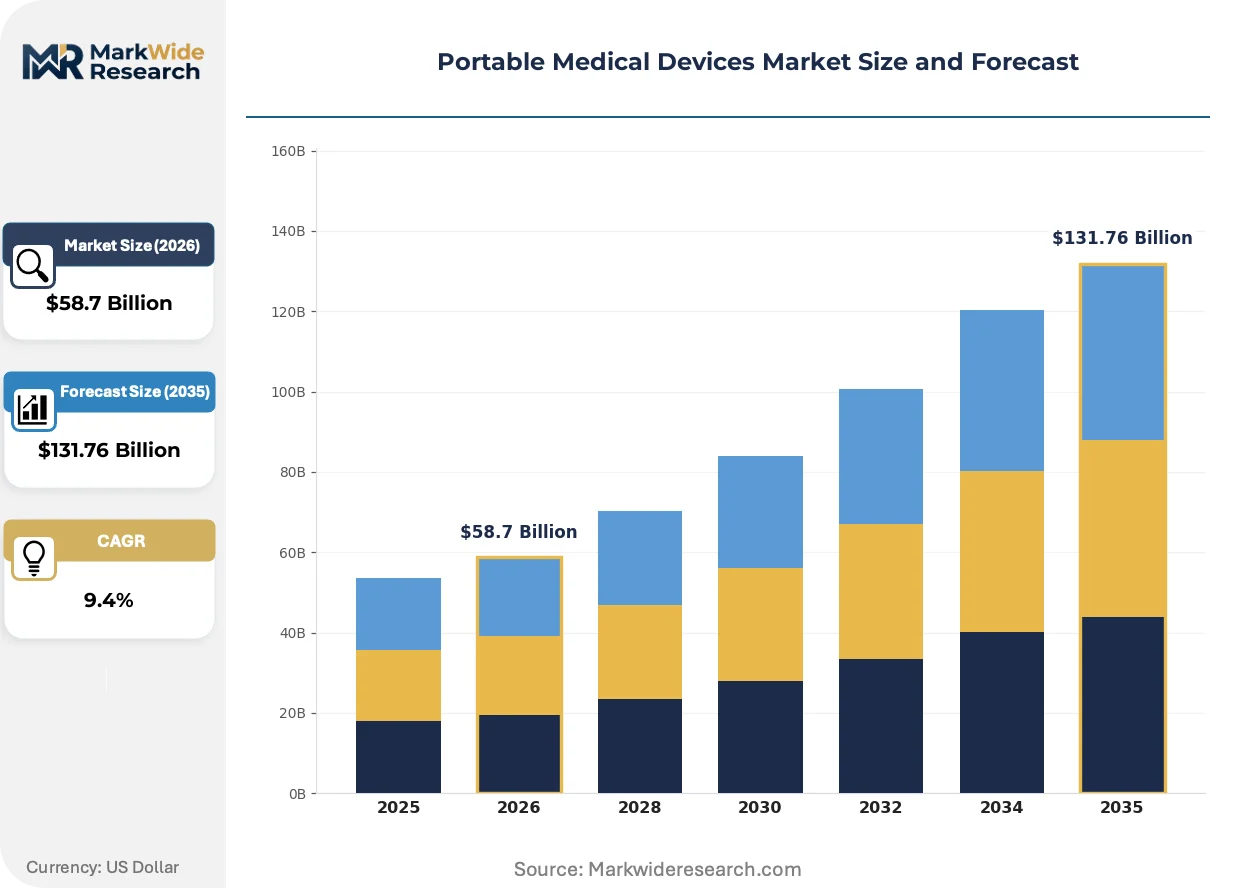
Market Dynamics
Reimbursement frameworks in developed markets are accelerating the shift from institutional care to home-based monitoring, forcing manufacturers to reengineer devices for untrained operators while maintaining clinical-grade accuracy.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS expanded billing codes for continuous physiologic monitoring in the United States, creating direct payment pathways for ambulatory cardiac and metabolic devices.
- EU MDR Quality Benchmarks:Stricter clinical evidence requirements under the Medical Device Regulation are filtering out low-quality competitors and elevating trusted brands in European markets.
- Bluetooth Low Energy:This wireless protocol enables 30-day battery life in wearable glucose monitors, removing the infrastructure barrier that previously limited home deployment.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production clusters in East Asia create single-source vulnerability for portable device manufacturers dependent on compact power density.
- FDA 510(k) Timeline Compression:Pre-market notification backlogs for software-as-medical-device submissions now extend review cycles beyond 180 days for wireless-enabled diagnostics.
- Stationary Diagnostic Substitution:Hospital systems in capital-rich markets retain high-resolution imaging modalities that outperform portable alternatives for complex cases.
Strategic Opportunities
- Rural India Penetration:Telemedicine infrastructure expansion under the National Digital Health Mission creates first-mover advantage for handheld diagnostic distributors.
- Continuous Temperature Monitoring:Post-operative recovery and oncology patient cohorts represent underserved demand for wearable thermometric devices outside critical care settings.
- Japan PMDA Fast-Track:Sakigake designation for breakthrough devices shortens approval timelines for AI-integrated portable monitors targeting aging-related conditions.
Industry Challenges
- Firmware Validation Expertise:Shortage of engineers qualified in IEC 62304 medical device software lifecycle processes delays product releases and strains development budgets.
- Legacy Health Record Integration:Proprietary data formats in established EHR systems force costly middleware development for seamless device-to-clinic transmission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Medical Devices Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Portable Ultrasound, Handheld ECG, Mobile Blood Glucose Meters End User: Hospitals, Homecare Settings, Clinics, Emergency Services Technology: Bluetooth, Wi-Fi, NFC, Cellular Connectivity Application: Chronic Disease Management, Vital Sign Monitoring, Rehabilitation, Health Monitoring |
| Companies Covered | Medtronic, GE Healthcare, Koninklijke Philips N.V., OMRON Corporation, Samsung, F. Hoffmann-La Roche Ltd, Siemens Healthineers, VYAIRE, ResMed Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Medical Devices Market Strategic Shifts
Edge computing architectures and AI inference on-device are eliminating the latency and connectivity dependencies that previously constrained portable diagnostic performance in ambulatory settings.
Silicon photonics is digitizing optical biosensing by replacing benchtop spectrometers with chip-scale photonic circuits that detect biomarkers through interferometric measurement. Home dialysis providers in Germany and Japan are piloting these modules for real-time metabolite tracking. The technology is digitizing laboratory workflows into palm-sized formats that patients operate without phlebotomy training.
EU MDR post-market surveillance requirements now mandate periodic safety update reports and proactive vigilance data collection for all wireless-enabled devices. Manufacturers must maintain clinical evidence registries that track real-world performance across distributed patient populations. Class IIa portable monitors face the steepest compliance cost escalation as notified bodies expand audit scope beyond design files to active field monitoring systems.
Hospital procurement committees are unbundling hardware acquisition from service contracts, treating connectivity subscriptions as separate line items subject to annual renewal review. This purchasing pattern shift compresses vendor lock-in duration and elevates interoperability standards as primary selection criteria. The United States exhibits the most aggressive unbundling behavior as health system consolidation creates centralized sourcing leverage against device manufacturers.
Portable Medical Devices Market Segmentation
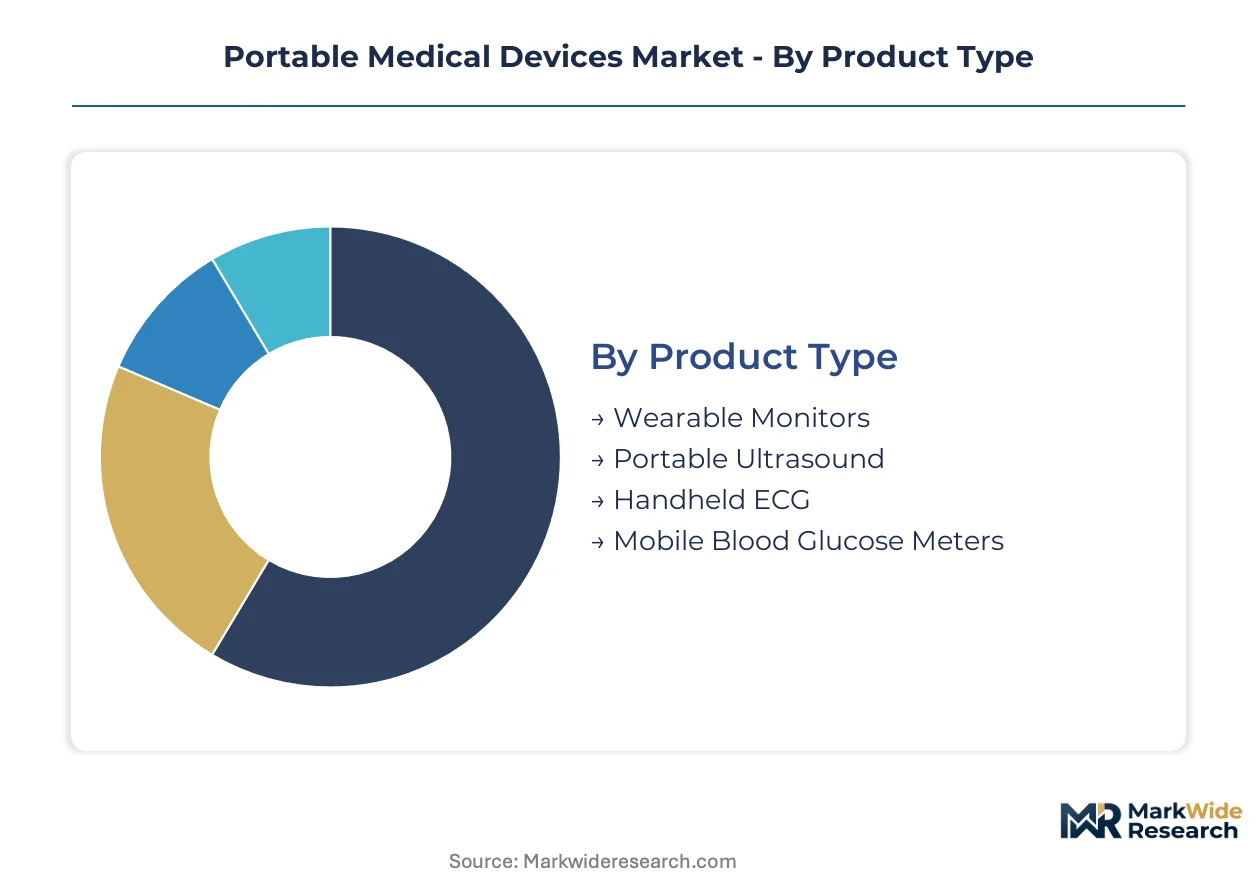
Portable medical devices fragment across four critical dimensions that determine regulatory pathway, reimbursement eligibility, and distribution strategy. Product type dictates hardware specifications and battery requirements. End user setting shapes training protocols and connectivity infrastructure. Technology selection governs data security architecture and subscription monetization potential.
Product Type:
Cost tier separates premium diagnostic imaging from commoditized consumer-grade monitoring devices.
- Wearable Monitors:Continuous physiologic sensors integrate photoplethysmography and accelerometry in sub-50-gram form factors. Demand concentrates in United States homecare settings where CMS reimbursement codes now cover ambulatory cardiac and metabolic surveillance. Bluetooth Low Energy protocols enable 30-day battery cycles that eliminate daily charging friction for elderly patient cohorts.
- Portable Ultrasound:Phased-array transducers and software-beamforming processors deliver point-of-care imaging in sub-2-kilogram enclosures. German hospital systems deploy these for emergency department triage where space constraints prevent fixed radiology suite installation. Image quality trade-offs against cart-based systems limit adoption to procedural guidance rather than diagnostic confirmation.
- Handheld ECG:Single-lead or 12-lead acquisition modules with embedded AI arrhythmia detection algorithms.
- Mobile Blood Glucose Meters:Electrochemical strip readers with cellular data transmission for automated endocrinologist alerting.
Wearable monitors command the established base. The steepest expansion runs through portable ultrasound.
End User:
Application setting determines operator training requirements and regulatory classification intensity.
- Homecare Settings:Untrained patient operators demand simplified interfaces with automated error correction and cloud-connected nurse oversight. United States reimbursement expansion under remote patient monitoring billing codes accelerates deployment for chronic disease cohorts. Device manufacturers must engineer for Wi-Fi credential entry by elderly users with limited digital literacy.
- Hospitals:Trained clinical staff operate devices within ISO 13485-controlled environments with institutional cybersecurity infrastructure. Japanese hospital procurement committees require PMDA QMS ministerial ordinance compliance for wireless-enabled diagnostics. Capital equipment committees unbundle hardware from service contracts, compressing vendor lock-in duration.
- Clinics:Physician office laboratories with moderate throughput and space constraints.
- Emergency Services:Pre-hospital care teams requiring military-grade durability and satellite backup connectivity.
Hospitals command the established base. Homecare settings are gaining share fastest.
Technology:
Customer type segments across consumer-grade Bluetooth and enterprise-grade cellular with diverging margin structures.
- Bluetooth:Short-range 2.4 GHz protocols enable smartphone-tethered data transmission with minimal power draw. Wearable glucose monitors in Germany leverage this for patient-owned device ecosystems that bypass institutional IT procurement. Range limitations and pairing complexity create friction for elderly users with limited technical support access.
- Cellular Connectivity:LTE-M and NB-IoT modules enable standalone operation without smartphone intermediation. Demand concentrates in Japan where aging demographics and PMDA fast-track pathways reward autonomous monitoring devices. Recurring data routing subscriptions generate margin pools that exceed hardware sale profitability within 18 months.
- Wi-Fi:Institutional network integration for stationary home monitoring hubs with continuous power supply.
- NFC:Tap-to-pair authentication and medication adherence verification in controlled clinical environments.
Bluetooth commands the established base. Cellular connectivity shows the steepest trajectory.
Application:
Volume concentration aligns with chronic disease prevalence and reimbursement coverage expansion.
- Chronic Disease Management:Diabetes, heart failure, and hypertension monitoring protocols require longitudinal data streams for medication titration. United States CMS billing codes now reimburse continuous physiologic monitoring outside institutional walls. Device manufacturers bundle algorithmic risk scoring to justify subscription pricing to payers.
- Vital Sign Monitoring:Post-acute surveillance and early warning score calculation for deteriorating patients. German home dialysis providers pilot silicon photonics modules for real-time metabolite tracking without phlebotomy. Regulatory capital requirements for FDA 510(k) clearance filter out undercapitalized entrants.
- Rehabilitation:Orthopedic recovery and stroke therapy with motion tracking and compliance verification.
- Health Monitoring:Wellness-oriented consumer applications with limited clinical validation requirements.
Chronic disease management commands the established base. Vital sign monitoring climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States command the largest capital deployment for wireless-enabled diagnostics, while aging patient cohorts in Germany and Japan accelerate homecare reimbursement expansion. Geographic demand clusters around regulatory pathways that reward connectivity monetization and remote patient monitoring coverage.
United States
CMS billing codes now reimburse continuous physiologic monitoring for ambulatory cardiac and metabolic patients, creating direct payment pathways that bypass institutional procurement. FDA 510(k) premarket notification requirements under 21 CFR Part 820 enforce design controls that extend review cycles for software-as-medical-device submissions. The Boston-Minneapolis corridor concentrates wearable glucose monitor development as venture-backed firms cluster near academic medical centers with clinical trial infrastructure.
Germany
Hospital systems deploy portable ultrasound for emergency department triage where space constraints prevent fixed radiology suite installation. EU MDR quality system standards and ISO 13485 impose clinical evidence thresholds that filter out undercapitalized applicants seeking CE marking. The Baden-Württemberg industrial belt anchors silicon photonics module production for home dialysis metabolite tracking without phlebotomy.
Japan
Aging demographics and PMDA fast-track pathways reward autonomous monitoring devices with standalone cellular operation. METI enforces QMS ministerial ordinances that demand in-country testing for wireless medical devices, adding compliance layers for cellular-enabled products. The Kanto region around Tokyo concentrates AI-integrated portable monitor development targeting breakthrough device designation under Sakigake.
India
Telemedicine infrastructure expansion under the National Digital Health Mission creates first-mover advantage for handheld diagnostic distributors reaching rural populations. CDSCO medical device rules enforce registration requirements for wireless-enabled diagnostics that previously operated in regulatory gray zones. The Maharashtra-Gujarat pharmaceutical corridor is piloting pharmacy-linked distribution networks for sub-50-gram wearable monitors.
South Korea
MFDS fast-track approval pathways for digital therapeutics accelerate deployment of smartphone-tethered diagnostic ecosystems. Government-backed smart hospital initiatives subsidize Bluetooth Low Energy infrastructure for post-acute surveillance in metropolitan health systems. The Seoul Capital Area concentrates battery-efficient sensor development as electronics conglomerates backward integrate into medical-grade photoplethysmography chips.
Portable Medical Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Consolidated multinational conglomerates anchor premium pricing through captive financing arms and long-term service contracts that bundle hardware with cloud analytics. Mid-tier manufacturers leverage asset-light leasing to overcome capital barriers that previously blocked hospital procurement committee access. Competitive moves concentrate on unbundling hardware from connectivity subscriptions and expanding interoperability certifications that reduce vendor lock-in duration.
Within the diversified health technology tier, Medtronic plc and Koninklijke Philips N.V. exemplify channel-controlling archetypes that anchor market positioning through integrated financing and distribution infrastructure. Siemens Healthineers AG occupies a position emphasizing service contract bundling over standalone hardware sales. Among Asia-Pacific specialists, OMRON Corporation represents the pharmacy-network control model that differentiates through retail channel dominance rather than institutional procurement.
| Leading Market Players |
|---|
| Medtronic |
| GE Healthcare |
| Koninklijke Philips N.V. |
| OMRON Corporation |
| Samsung |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| VYAIRE |
| ResMed Inc. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor shapes cost dynamics for lithium-ion cell imports, concentrating supply-side leverage among East Asian battery producers while forcing European and North American device manufacturers into three-tier pricing structures across premium, standard, and economy levels based on certification grade and connectivity sophistication.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate component procurement, embedding commodity volatility into manufacturer margins. Pricing stratifies across premium, standard, and economy tiers driven by FDA 510(k) clearance status and Bluetooth versus cellular architecture. Cost compression in consumer-grade glucose meters intensifies as pharmacy chains consolidate purchasing leverage. Hospital systems exhibit lowest price sensitivity due to reimbursement pass-through, while direct-to-consumer channels face acute margin pressure from unbranded Asian imports.
Supply Chain Analysis
Contract manufacturing concentrates at Foxconn, Jabil, and Flex facilities across Shenzhen, Penang, and Guadalajara for final device assembly. Lithium-ion cells draw from South Korean and Japanese chemical suppliers, while MEMS sensors rest on Taiwanese foundry output. Single-source vulnerability runs through rare earth magnet supply for miniature motor assemblies. Distribution runs through GPO contracts with hospital systems and pharmacy-linked networks for homecare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable medical devices function as a service-attach opportunity where data routing subscriptions and algorithmic risk scoring layers expand faster than hardware unit economics, rewarding manufacturers that bundle connectivity with clinical-grade measurement.
For Market Incumbents: Pre-empt software-as-medical-device entrants by accelerating IEC 62304-certified firmware development in-house, eliminating third-party validation bottlenecks. Anchor hospital procurement relationships through captive financing arms that absorb upfront capital burdens. Defend against mid-tier disrupters by securing exclusive pharmacy distribution in aging Asian markets.
For New Entrants and Emerging Players: Establish a beachhead in rural Indian telemedicine channels where CDSCO registration requirements filter out undercapitalized competitors. Target continuous temperature monitoring for post-operative cohorts as the most penetrable white-space segment. Pursue white-label partnerships with German home dialysis providers seeking silicon photonics integration without R&D investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with dormant medical-grade sensor divisions lacking FDA regulatory infrastructure. Long-term viability hinges on recurring revenue attachment rates exceeding hardware depreciation cycles. Monitor CMS billing code expansion velocity as the primary inflection signal for homecare monetization potential.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortens premarket notification timelines for wireless-enabled diagnostics under 21 CFR Part 820 design controls. |
| EU MDR CE Marking Pathway | Unlocks European homecare reimbursement through notified body clinical evidence validation. |
| Hospital System Partnership | Secures long-term service contracts that bundle hardware with cloud analytics and nurse oversight portals. |
| Software Companion Development | Creates algorithmic risk scoring layers that justify subscription pricing to CMS and private payers. |
| Reimbursement Strategy | Aligns device connectivity features with remote patient monitoring billing codes for ambulatory cardiac surveillance. |
Study Parameters
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and homecare reimbursement specialists anchored the qualitative base. Primary interview findings triangulated against FDA 510(k) clearance databases, CMS Medicare reimbursement filings, EU MDR notified body audit records, and hospital procurement contract registries. Bottom-up unit economics modeling cross-validated with top-down market sizing across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling product type, end user setting, connectivity technology, and application segments independently. CAGRs derived from weighted average of historical reimbursement expansion rates and connectivity subscription attachment trajectories. Forecast inputs incorporated PMDA Sakigake designation velocity and EU MDR post-market surveillance cost escalation assumptions.
Stress conditions across lithium supply disruption, FDA review timeline extension, and CMS code reimbursement contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of notified body audit queue depth and CMS billing code proposal dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Europe Surgical Microscopes Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Education Microscope Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Mediastinoscope Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Oxygen Concentrators Market