
 Engine-Driven Endodontic File Market | 2026-2036
Engine-Driven Endodontic File Market Size, Share, and Industry Trends Forecast 2026-2036
Engine-Driven Endodontic File Market Insights
Specialty endodontic centers is realigning procurement priorities toward reciprocating and adaptive motion technologies. Dentsply Sirona leverages vertical integration across nickel-titanium alloy sourcing and file manufacturing. Envista Holdings anchors its position through sustained R&D intensity in heat-treated file systems. COLTENE Group specializes in European market access with CE-marked rotary portfolios.
Engine-driven endodontic files are precision instruments manufactured from nickel-titanium alloys or stainless steel, typically featuring tapered geometries between 0.02 and 0.12 mm/mm and rotational speeds from 150 to 650 rpm, designed to mechanically shape and clean root canal systems during endodontic therapy. Nickel titanium files dominate volume due to superelasticity and fatigue resistance, though heat-treated variants command margin premiums for complex canal anatomies. Continuous rotation technology retains installed base dominance while adaptive motion systems represent the fastest-growing technology segment as clinicians seek reduced file separation rates. Root canal shaping applications capture the largest revenue share within the application dimension.
FDA 510(k) premarket notifications govern US commercial entry for engine-driven endodontic files, while EU MDR Class IIa certification requirements extend conformity assessment timelines for rotary and reciprocating systems. ISO 3630-1 standards define dimensional and performance benchmarks that manufacturers must satisfy for international market access. Stakeholders must monitor evolving sterilization validation protocols and biocompatibility testing requirements as regulators tighten post-market surveillance for nickel-titanium instruments.
Market Dynamics
Reciprocating motion systems are displacing continuous rotation as the dominant mechanical platform, forcing incumbent manufacturers to reconfigure alloy processing lines and heat-treatment protocols to maintain procurement relationships with specialty endodontic centers.
Growth Catalysts
- EU MDR Class IIa certification pathways:Streamlined conformity assessment routes for adaptive motion files accelerate commercialization timelines for manufacturers with established quality management systems.
- Superelastic nickel-titanium alloys:Metallurgical advances in fatigue resistance enable single-file shaping protocols that reduce chair time and instrument consumption per procedure.
- Germany:Reimbursement frameworks under statutory health insurance explicitly favor precision endodontics, directing procurement budgets toward heat-treated file systems.
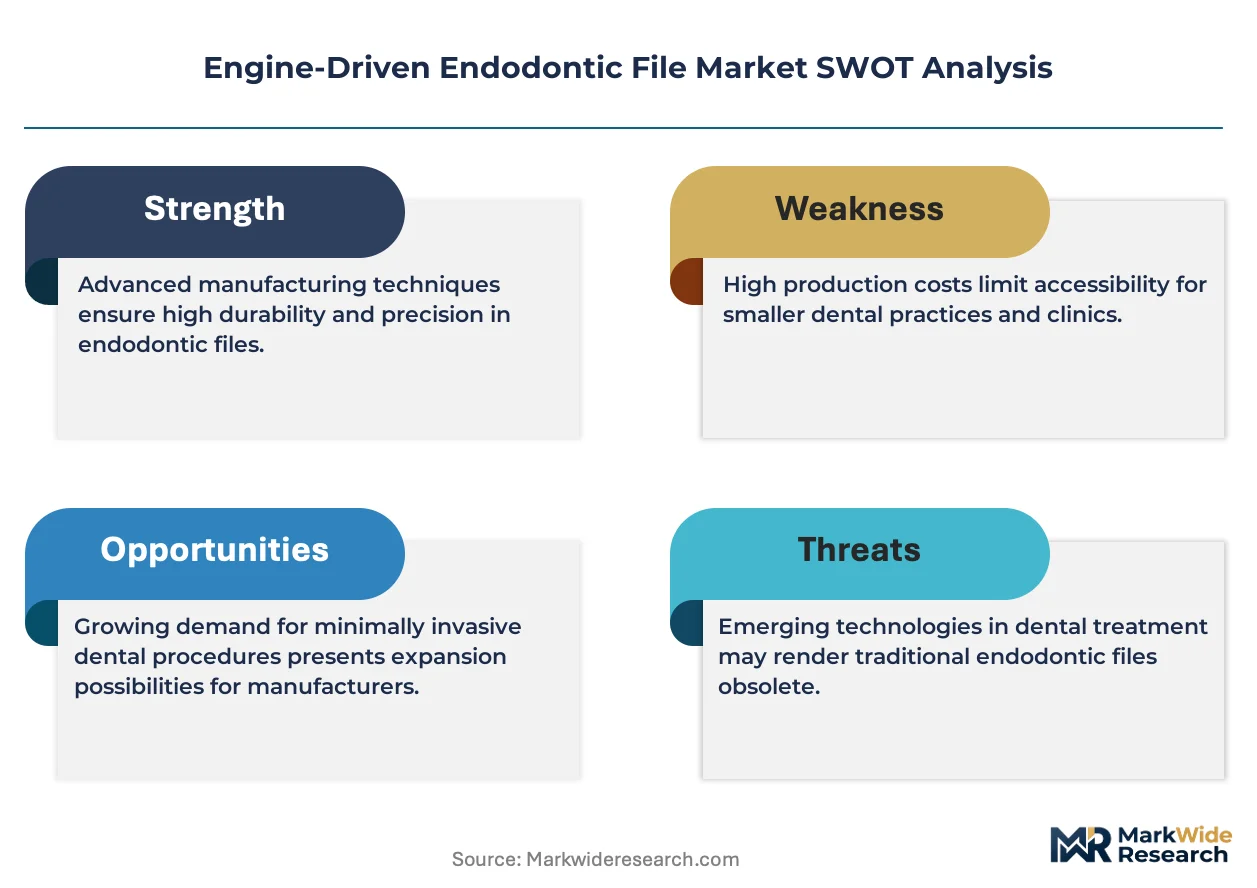
Market Restraints
- Nickel price volatility:Raw material cost swings for nickel-titanium alloy feedstock compress margin structures for file manufacturers without captive smelting operations.
- FDA 510(k) notification requirements:Premarket submission timelines and substantive equivalence determinations create friction for novel file geometries entering the United States.
- Manual stainless steel files:Low-cost hand instrumentation persists in price-sensitive dental clinics, constraining premium engine-driven penetration in emerging markets.
Strategic Opportunities
- Japan:Aging demographics and elevated per-capita dental expenditure create underpenetrated demand for adaptive motion systems in metropolitan Tokyo and Osaka clinic networks.
- 3D-printed file blanks:Additive manufacturing convergence with precision grinding technology enables patient-specific canal-matching geometries at production scale.
- Direct-to-clinic distribution:E-procurement platforms bypass traditional dental dealer networks, capturing margin previously allocated to intermediary stocking.
Industry Challenges
- ISO 3630-1 dimensional compliance:Tolerance verification for tapered geometries requires capital-intensive coordinate measuring infrastructure that strains mid-tier manufacturers.
- Legacy motor handpiece incompatibility:Adaptive motion file systems demand torque-responsive motor electronics that clash with installed base equipment in older dental operatories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine-Driven Endodontic File Market |
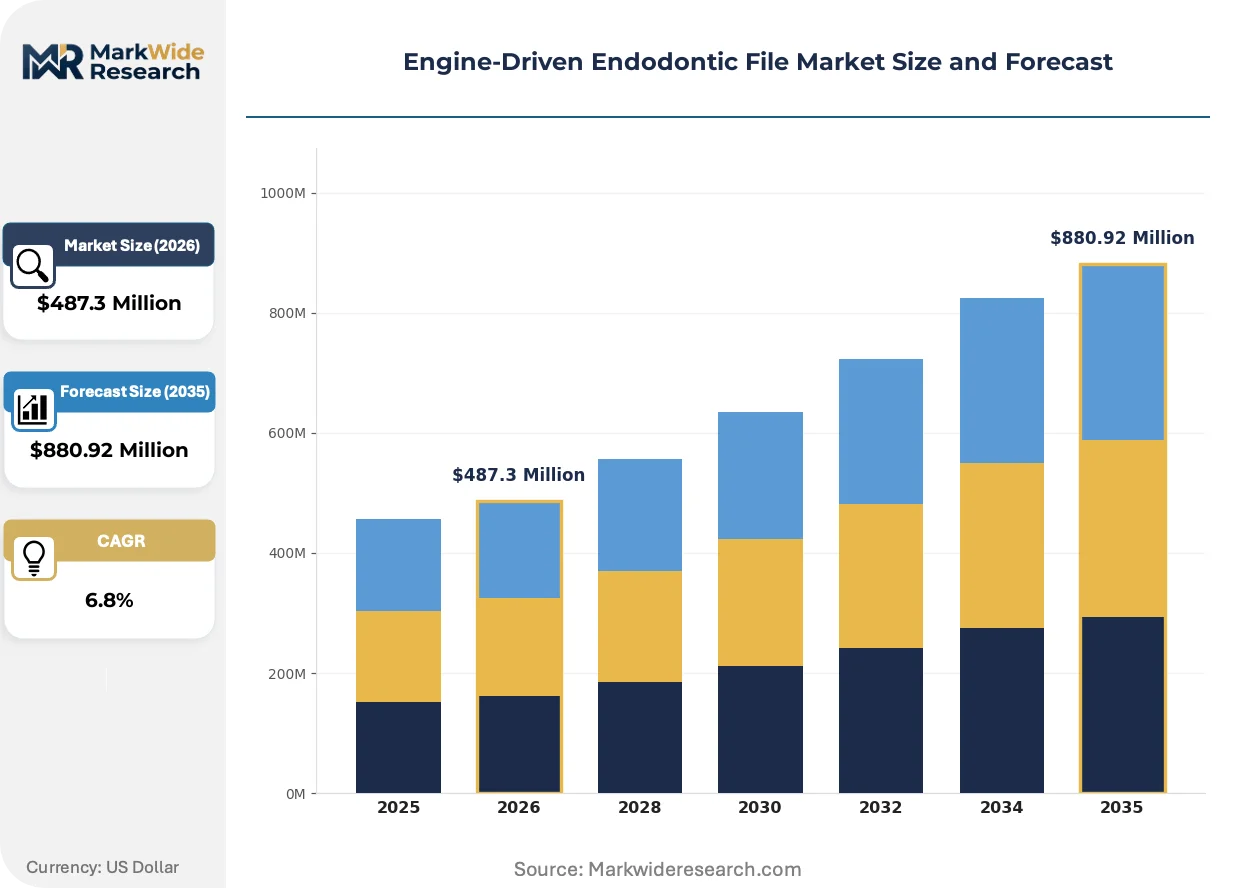
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | File Type: Nickel Titanium, Stainless Steel, Carbon Steel, Heat Treated, Hybrid Systems Technology: Reciprocation, Continuous Rotation, Adaptive Motion, Rotary Systems, Manual Assisted Application: Root Canal Shaping, Cleaning, Debridement, Retreatment, Apexification End User: Dental Clinics, Specialty Endodontic Centers, Academic Institutes, Mobile Dental Units |
| Companies Covered | Dentsply Sirona, Envista Holdings, COLTENE Group, Brasseler USA, FKG Dentaire, Mani, Ultradent Products, VDW, META-BIOMED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine-Driven Endodontic File Market Trends and Innovations
Heat-treated metallurgy and motion-control algorithms are converging to redefine clinical performance benchmarks, while regulatory documentation requirements and procurement centralization reshape how manufacturers commercialize precision instruments.
Adaptive reciprocation technology is decentralizing clinical decision-making around file selection by enabling general practitioners to safely navigate complex canal anatomies previously requiring specialist referral. Community dental clinics in the United States are adopting these systems at accelerating rates. The technology is decentralizing case complexity from academic centers to primary-care settings.
EU MDR post-market surveillance mandates now require systematic tracking of file separation incidents and biocompatibility batch testing. Manufacturers must maintain technical documentation for ten years and report serious incidents within fifteen days. Rotary and reciprocating system portfolios face extended conformity assessment timelines, compressing product refresh cycles.
Group purchasing organizations are consolidating procurement authority across multi-clinic dental networks, unbundling after-sales technical support from instrument pricing. Dealer representatives lose access to purchasing committees as centralized buying desks negotiate annual contracts. This concentration is most visible in Germany's KZVen-regulated ambulatory care sector.
Engine-Driven Endodontic File Market Segmentation
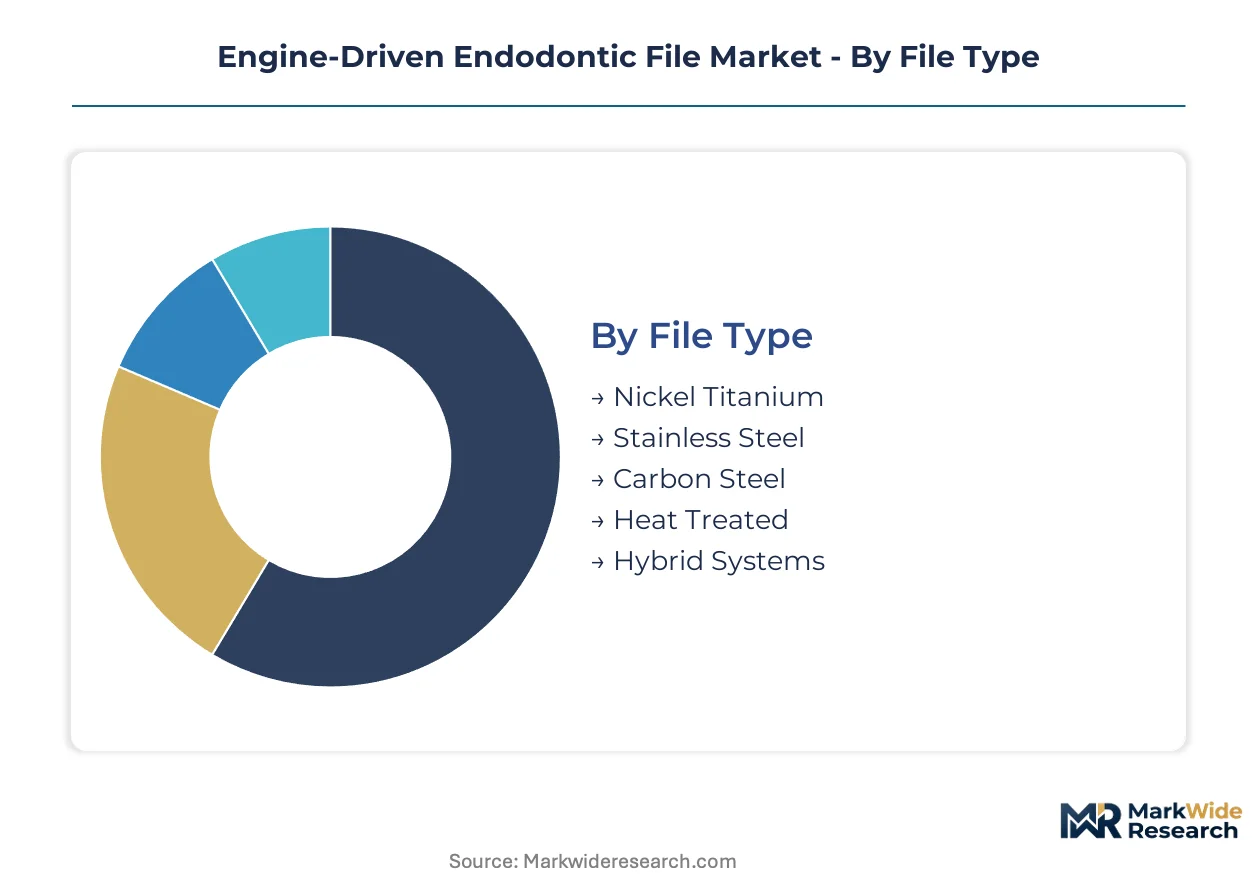
Engine-driven endodontic file manufacturers configure production lines around distinct metallurgical grades and motion-control platforms. Procurement patterns across dental clinics and specialty centers fragment demand across four critical dimensions that determine pricing power and margin capture.
File Type:
Capital intensity escalates sharply with metallurgical sophistication, as heat-treatment furnaces and cryogenic processing equipment require seven-figure installation commitments.
- Nickel Titanium:Superelastic alloys with austenite finish temperatures between 15°C and 25°C dominate volume through fatigue resistance and shape memory. Specialty endodontic centers in Germany prioritize these files for complex canal anatomies under precision-focused reimbursement schedules.
- Heat Treated:Controlled thermal processing enhances cyclic fatigue resistance by 40-60% over conventional nickel-titanium, commanding premium positioning for curved canal cases. Japan's aging patient population drives replacement demand for these advanced metallurgical variants.
- Stainless Steel:Lower-cost rotary files retain installed base in price-sensitive clinic networks without torque-responsive motor systems.
- Carbon Steel:Hand-finished instruments persist in emerging market dental education programs for initial technique training.
- Hybrid Systems:Composite metallurgy combining nickel-titanium cores with surface-modified cutting edges targets retreatment applications.
Most installed capacity flows through nickel titanium. Expansion is steepest in heat treated.
Technology:
Motion-control electronics differentiate procurement tiers, with adaptive algorithms requiring firmware development investments absent from mechanical continuous rotation platforms.
- Reciprocation:Oscillating clockwise-counterclockwise motion reduces torsional stress and file separation incidence. United States group purchasing organizations are consolidating annual contracts around these systems for multi-clinic networks.
- Adaptive Motion:Torque-responsive algorithms modulate rotation based on canal resistance feedback, enabling general practitioners to manage cases previously requiring specialist referral. Community dental clinics across metropolitan Tokyo and Osaka clinic networks are adopting these platforms at accelerating rates.
- Continuous Rotation:Legacy 150-650 rpm mechanical systems retain dominance in older dental operatories with incompatible motor handpiece infrastructure.
- Rotary Systems:Fixed-speed mechanical platforms persist in academic training curricula for fundamental canal shaping technique instruction.
- Manual Assisted:Hybrid protocols combining engine-driven coronal preparation with hand-file apical finishing address complex anatomies in retreatment scenarios.
Procurement volume concentrates in reciprocation. Technology transition is accelerating fastest in adaptive motion.
Application:
Procedure complexity determines file consumption rates and instrument replacement frequency, with retreatment applications requiring 2-3x file sets per case versus initial therapy.
- Root Canal Shaping:Tapered geometry preparation from orifice to apex consumes the largest file volume per procedure. Germany's KZVen-regulated ambulatory care sector directs procurement budgets toward precision shaping systems under statutory health insurance frameworks.
- Retreatment:Removal of gutta-percha and post systems demands specialized file geometries with enhanced torsional resistance. Specialty endodontic centers in Japan report elevated case complexity from aging patient populations with prior endodontic history.
- Cleaning:Irrigant delivery optimization drives file design prioritizing fluting geometry over cutting efficiency.
- Debridement:Pulp tissue and biofilm removal applications favor files with aggressive cutting angles for necrotic canal cases.
- Apexification:Immature root end closure procedures require specialized minimal-taper files for delicate apical control.
Procedure volume clusters in root canal shaping. Clinical expansion is most pronounced in retreatment.
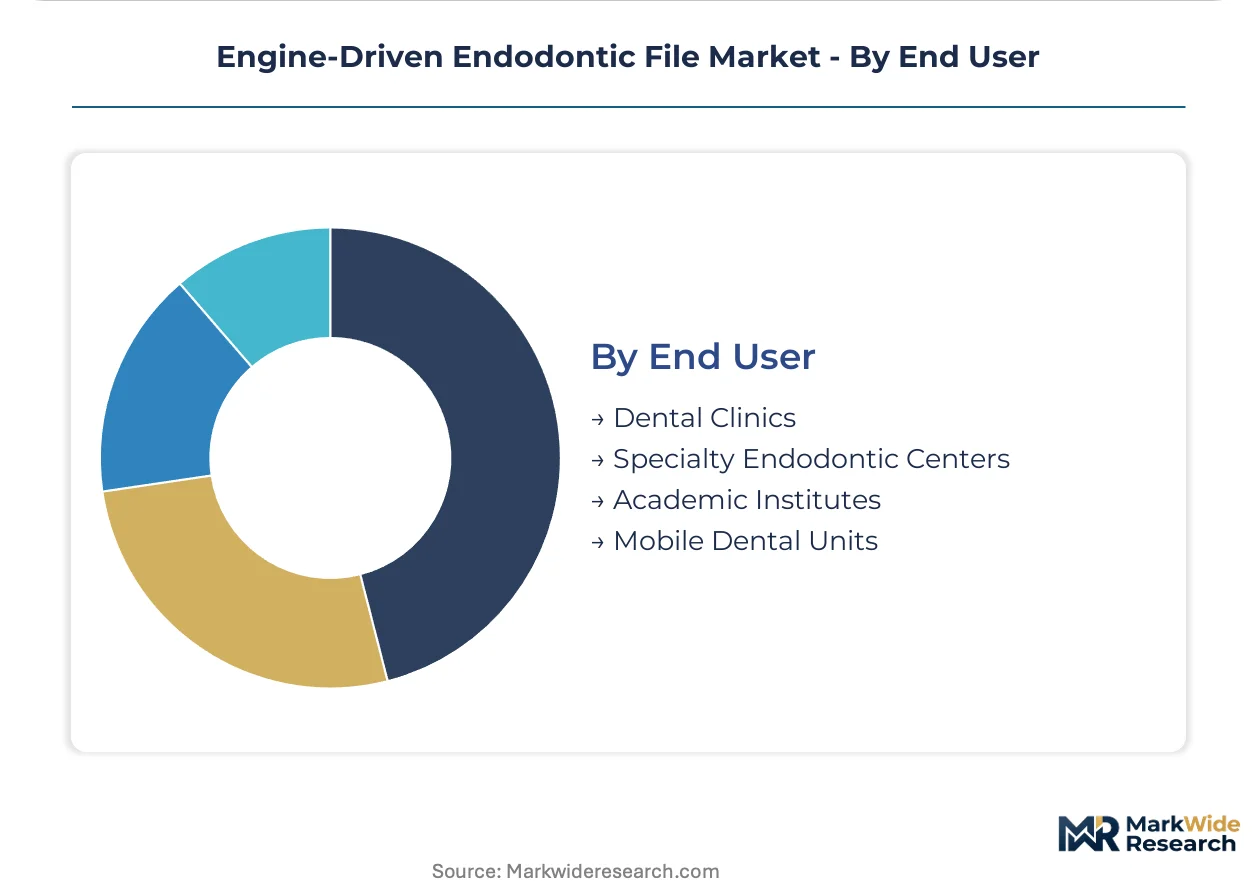
End User:
Customer concentration patterns vary dramatically, with specialty endodontic centers purchasing 5-8x file units per practitioner versus general dental clinics.
- Specialty Endodontic Centers:High-volume practitioners prioritize adaptive motion systems and heat-treated metallurgy for complex case portfolios. These facilities negotiate directly with manufacturers, bypassing traditional dental dealer networks through e-procurement platforms.
- Dental Clinics:General practice settings concentrate demand for single-file reciprocating systems that reduce chair time and inventory complexity. United States community dental clinics are decentralizing case complexity from academic centers through technology adoption.
- Academic Institutes:Training programs maintain diversified file inventories across all metallurgical grades for comparative technique instruction.
- Mobile Dental Units:Portable service providers favor compact, single-system portfolios with minimal sterilization infrastructure requirements.
Revenue concentration aligns with specialty endodontic centers. Account growth is expanding most quickly in dental clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EU MDR conformity assessment timelines and FDA 510(k) notification requirements create divergent cost-of-compliance thresholds across jurisdictions.
United States
Group purchasing organizations concentrate procurement authority across multi-clinic dental networks, unbundling after-sales support from instrument pricing. FDA 510(k) premarket notifications govern commercial entry, with substantive equivalence determinations creating friction for novel file geometries. Community dental clinics in metropolitan areas are adopting adaptive motion systems at accelerating rates.
Germany
Reimbursement frameworks under statutory health insurance explicitly favor precision endodontics, directing procurement budgets toward heat-treated file systems. KZVen-regulated ambulatory care sectors consolidate buying desks that negotiate annual contracts directly with manufacturers. Specialty endodontic centers in Bavaria and North Rhine-Westphalia prioritize adaptive motion technologies for complex canal anatomies.
Japan
Aging demographics and elevated per-capita dental expenditure create underpenetrated demand for adaptive motion systems in metropolitan Tokyo and Osaka clinic networks. METI industrial standards govern medical device quality management systems, while PMDA oversight ensures biocompatibility validation. Specialty centers report elevated retreatment case complexity from aging patient populations with prior endodontic history.
China
NMPA medical device registration requirements and GB standards for dental instruments shape domestic manufacturing compliance costs. Nickel-titanium alloy feedstock availability supports vertical integration into file production for regional supply. Manufacturing clusters in the Yangtze River Delta serve both domestic clinic networks and export markets.
Switzerland
Swissmedic certification requirements and precision manufacturing heritage position the jurisdiction as a hub for premium file system development. Heat-treatment metallurgy expertise concentrates in industrial clusters around Basel and Zurich. Domestic manufacturers supply specialty endodontic centers across European markets with CE-marked rotary portfolios.
Engine-Driven Endodontic File Market Competitive Landscape
Technology licensing dominates the current landscape as manufacturers seek rapid access to adaptive motion algorithms and heat-treatment metallurgy patents. The vendor base clusters around three tiers: diversified dental conglomerates with captive alloy processing, mid-cap specialists focused on single-file reciprocating systems, and regional fabricators serving price-sensitive clinic networks. Strategic archetypes include backward-integrated alloy producers, motion-control technology licensors, and direct-to-clinic distributors. M&A activity and capacity expansion in heat-treatment furnaces represent the dominant competitive moves as firms defend procurement relationships with specialty endodontic centers.
Among diversified dental conglomerates, Dentsply Sirona and Envista Holdings exemplify the backward-integrated archetype with in-house nickel-titanium alloy sourcing and file manufacturing capabilities. COLTENE Group occupies a position within the European specialist tier, anchoring market access through CE-marked rotary portfolios. These three entities represent distinct strategic postures: captive metallurgical supply, sustained R&D intensity in heat-treated systems, and regional regulatory navigation expertise.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista Holdings |
| COLTENE Group |
| Brasseler USA |
| FKG Dentaire |
| Mani |
| Ultradent Products |
| VDW |
| META-BIOMED |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-caps in Germany and Switzerland anchor premium-tier production through captive heat-treatment expertise, translating metallurgical control into pricing discipline that resists commoditization pressure from Asian contract manufacturers. This ownership pattern concentrates supply-side bargaining power while reinforcing three-tier pricing stratification across adaptive motion, reciprocating, and legacy continuous rotation platforms.
Pricing Analysis
Distributor margin compression runs through traditional dental dealer networks as group purchasing organizations extract 15-25 point concessions by consolidating multi-clinic procurement authority. Three-tier pricing structure across premium, standard, and economy levels separates heat-treated adaptive systems from conventional nickel-titanium reciprocating files and stainless steel rotary alternatives. Pricing pressure stems from nickel-titanium alloy feedstock volatility and e-procurement platform transparency. General dental clinics exhibit highest price sensitivity, while specialty endodontic centers absorb premium positioning for complex case throughput.
Supply Chain Analysis
Single-source vulnerability sits with nickel-titanium alloy smelters in China and Germany, where austenite finish temperature control requires proprietary vacuum arc remelting expertise. Manufacturing draws from nickel-titanium feedstock, precision grinding spindles, and torque-responsive motor electronics as critical inputs. Tariff exposure on Chinese-origin alloy compresses margin structures for non-integrated manufacturers. Distribution runs through direct-to-clinic e-procurement platforms that disintermediate legacy dental dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on metallurgical premiumization and motion-control firmware differentiation, with heat-treated file systems capturing widening spreads over commodity nickel-titanium alternatives as reimbursement frameworks reward precision outcomes.
For Market Incumbents: Lock in procurement relationships with specialty endodontic centers through long-term e-procurement platform contracts that bundle adaptive motion file systems with technical training support. Add heat-treatment furnace capacity in Switzerland or Germany to defend against Asian contract manufacturers with backward integration into nickel-titanium alloy sourcing. FDA 510(k) notification backlogs for novel file geometries threaten first-mover positioning, making regulatory affairs capacity expansion the priority lever. For New Entrants and Emerging Players: Community dental clinics in Japan's metropolitan Osaka and Tokyo networks represent an underserved buyer archetype with accelerating adaptive motion adoption but limited manufacturer direct access. Single-file reciprocating systems for general practitioners offer the most penetrable entry point, bypassing specialist referral complexity. A direct-to-clinic distribution model with localized Japanese regulatory support captures margin otherwise allocated to importer intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap European specialists with CE-marked rotary portfolios but limited adaptive motion R&D pipelines. Long-term viability over a 5-10 year window favors targets with proprietary heat-treatment metallurgy patents and established EU MDR quality management systems. Watch for inflection in group purchasing organization contract renewal cycles as signal of pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Furnace Capacity Expansion | Captures margin premium on fatigue-resistant files for curved canal anatomies in Germany. |
| Adaptive Motion Firmware Development | Enables general practitioners to manage complex cases previously requiring specialist referral. |
| EU MDR Class IIa Certification Investment | Accelerates commercialization timelines for reciprocating systems in KZVen-regulated German procurement. |
| Direct-to-Clinic E-Procurement Platform Launch | Bypasses dental dealer networks to capture margin and strengthen specialty center relationships. |
| Nickel-Titanium Alloy Backward Integration | Insulates margin structure from raw material volatility and Chinese supply concentration risk. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with endodontic specialists, dental clinic procurement managers, biomedical engineers at file manufacturers, and group purchasing organization contract directors with secondary validation against FDA 510(k) premarket notification databases, EU MDR conformity assessment records, ISO 3630-1 dimensional standard documentation, and statutory health insurance reimbursement schedules in Germany and Japan. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Historical reference periods spanning installed base evolution, regulatory transition impacts, and metallurgical technology adoption curves anchored the projection horizon across the analysis window. Segmentation dimensions modeled include file metallurgy grade, motion-control technology platform, clinical application complexity, and end-user facility type. CAGRs derived from procedure volume growth rates, replacement frequency trends, and premium-tier mix shift assumptions. Forecast inputs incorporated nickel-titanium alloy price trajectories and EU MDR post-market surveillance compliance cost burdens.
Underlying measurement precision varies by segment; adaptive motion system adoption rates and specialty center procurement patterns carry tighter precision than emerging market manual file displacement estimates. Forecasts reflect documented assumptions regarding reimbursement framework stability, regulatory clearance timelines, and clinician training adoption curves. Nickel price volatility, FDA substantive equivalence determination delays, and legacy motor handpiece replacement cycles constitute primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Films Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
India Anesthesia Devices Market
Medical Devices
IV Poles Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Cardiac Implants Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Mexico Artificial Organs and Bionic Implants Market
Medical Devices
Smart Stairlift Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Medical Device Complaint Management Market