
 Intra-Abdominal Pressure Measurement Devices (IPMD) Market | 2026-2036
Intra-Abdominal Pressure Measurement Devices (IPMD) Market Size, Share, and Industry Trends Forecast 2026-2036
Intra-Abdominal Pressure Measurement Devices (IPMD) Market Foresight
A capital-intensity divergence between integrated sensor manufacturers and assembly-only device makers is rotating competitive advantage toward firms with in-house transducer fabrication. BD leverages backward integration into pressure-sensor MEMS fabrication to sustain margin control across catheter-monitor bundles. Spiegelberg GmbH & Co. KG anchors its European position through specialized neurosurgical and abdominal pressure monitoring lines that dominate German-speaking hospital procurement.
Intra-abdominal pressure measurement devices comprise catheters, electronic sensors, bedside monitors, and disposable accessories designed to quantify pressure within the abdominal cavity, typically via bladder or gastric instillation protocols with saline and electronic transduction. These systems serve the primary commercial purpose of enabling early detection of intra-abdominal hypertension and abdominal compartment syndrome in critically ill surgical and trauma patients. Catheter-based invasive technology occupies the largest installed base across hospital ICUs, while wireless and fiber-optic modalities represent the fastest-growing segments as facilities seek to reduce catheter-associated infection risks and enable ambulatory step-down monitoring. The end-user landscape tilts heavily toward hospitals and surgical centers where bundled critical-care contracts concentrate purchasing power, though emergency departments represent an emerging margin pool as pre-hospital trauma protocols expand.
The FDA's Class II medical device controls and the EU MDR's enhanced clinical-evidence requirements for invasive pressure-monitoring systems are elevating barriers to market access and accelerating consolidation among smaller accessory suppliers. ISO 81060-1 standards for non-invasive pressure measurement and IEC 60601-1 electrical safety protocols further shape product design cycles for monitor manufacturers seeking multi-regional approval. Stakeholders must monitor how evolving CMS reimbursement codes for continuous hemodynamic monitoring in the United States and comparable health-technology assessment pathways in Germany and Japan will determine whether wireless IPMD platforms achieve premium pricing parity with established invasive systems.
Market Dynamics
Continuous monitoring protocols are compressing replacement cycles for invasive catheter systems while wireless transduction architectures are fragmenting installed-base loyalty across ICU procurement departments.
Growth Catalysts
- Trauma Center Certification Mandates:United States hospital accreditation standards now require documented intra-abdominal pressure surveillance for Level I trauma designations. These mandates force catheter-monitor bundle refreshes at certified facilities.
- FDA Class II Device Controls:Enhanced quality-system requirements for invasive pressure sensors elevate barriers for accessory-only suppliers. Incumbent integrated manufacturers capture displaced volume from exiting competitors.
- Bladder Instillation Protocol Standardization:Critical care societies in Germany and Japan have issued consensus guidelines normalizing hourly IAP measurement in mechanically ventilated surgical patients. Protocol adoption drives disposable catheter consumption.
Market Restraints
- MEMS Foundry Concentration:Pressure-sensor wafer fabrication concentrates among Taiwanese and German specialty semiconductor houses. Single-source dependency exposes device assemblers to allocation risk during capacity crunches.
- EU MDR Clinical Evidence Burden:Invasive pressure-monitoring systems now require post-market surveillance data and notified-body recertification. Small accessory manufacturers lack capital to sustain compliance documentation.
- Catheter-Associated Infection Liability:Urinary tract infection claims from prolonged bladder catheterization create institutional risk aversion. Some surgical ICUs delay IAP monitoring until compartment syndrome suspicion peaks.
Strategic Opportunities
- Japanese Step-Down Units:Post-ICU surgical wards remain underserved by continuous monitoring infrastructure. Wireless IPMD platforms can penetrate this white space without displacing hardwired bedside systems.
- Pre-Hospital Trauma Triage:Emergency medical services in the United States are expanding field hemodynamic assessment protocols. Ruggedized disposable pressure sensors address this emerging application.
- ISO 81060-1 Harmonization:Convergence of non-invasive pressure measurement standards across Japan, Germany, and the United States enables single-SKU monitor designs. Manufacturers reduce regional compliance fragmentation costs.
Industry Challenges
- Biomedical Sensor Integration Expertise:Wireless IPMD development demands rare combinations of MEMS physics, RF engineering, and sterilization validation. Talent scarcity extends product development timelines.
- Legacy Monitor Retrofit Complexity:Hospital capital cycles prevent wholesale bedside monitor replacement. New sensor architectures must interface with decade-old analog input architectures through costly adapter modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intra-Abdominal Pressure Measurement Devices (IPMD) Market |
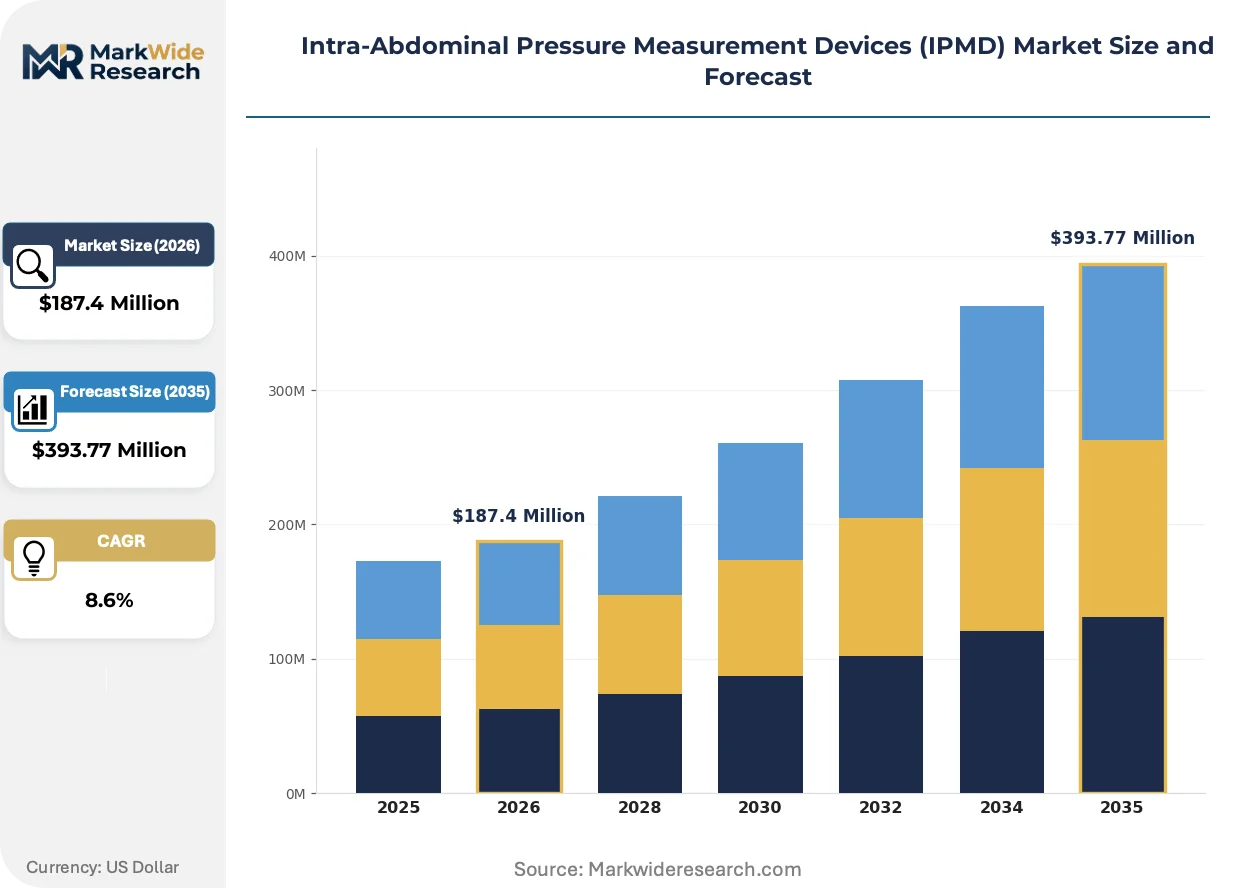
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheter, Sensor, Monitor, Accessory End User: Hospitals, Clinics, Surgical Centers, Emergency Departments Technology: Invasive, Non-Invasive, Wireless, Fiber Optic Application: Postoperative Monitoring, Trauma Care, Critical Care, Diagnostics |
| Companies Covered | Biometrix Corporation, Gaeltec Devices Ltd., BD, C2DX, Inc., Spiegelberg GmbH & Co. KG, Convatec Group PLC, Medline Industries, Inc., Potrero Medical, Accuryn Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intra-Abdominal Pressure Measurement Devices (IPMD) Market Shifts & Advancements
Silicon photonics and printed electronics are compressing transducer form factors while regulatory evidence requirements are lengthening product development horizons. These forces are reshaping competitive positioning between integrated and modular system architectures.
Fiber-optic pressure sensing technology is miniaturizing transducer heads to sub-millimeter diameters compatible with 5-French catheters. German trauma centers are piloting these systems for pediatric abdominal compartment syndrome surveillance. The technology is miniaturizing hardware footprints enough to enable ambulatory pressure telemetry during patient transport.
EU MDR Article 10 clinical-evaluation requirements are forcing invasive pressure-monitoring manufacturers to generate post-market performance data. German notified bodies now demand five-year follow-up studies for Class IIa device renewals. Japanese PMDA is observing these European precedents and tightening comparable evidentiary standards for imported devices.
Hospital procurement departments are unbundling sensor-disposable contracts from monitor hardware leases. United States group purchasing organizations now run separate competitive events for catheter supplies and capital equipment. This bifurcation is compressing pricing power for bundled system vendors and elevating standalone disposable suppliers in surgical center segments.
Intra-Abdominal Pressure Measurement Devices (IPMD) Market Segmentation
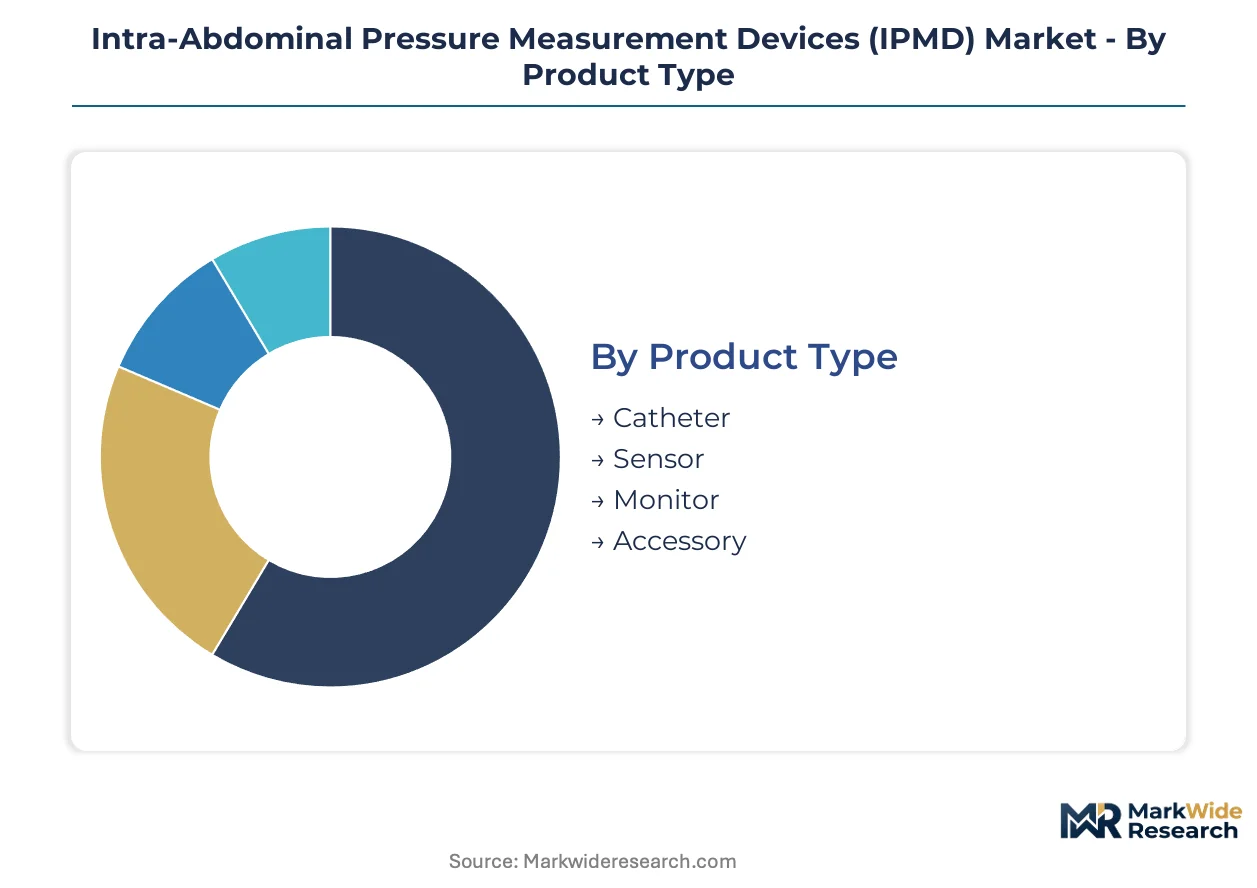
IPMD procurement patterns fragment sharply across clinical settings and technological architectures. Understanding these divides reveals where pricing power concentrates and which innovation pathways face adoption resistance.
Product Type:
Catheter systems dominate domestic hospital procurement in the United States, Germany, and Japan, while sensor components drive export manufacturing from Taiwanese MEMS foundries and German specialty semiconductor houses.
- Catheter:Polyurethane or silicone tubing assemblies with integrated pressure lumens, designed for bladder or gastric instillation protocols. Demand concentrates in Level I trauma centers across the United States where certification mandates force quarterly disposable consumption. Supply bottlenecks emerge when Taiwanese foundry capacity tightens.
- Sensor:MEMS-based pressure transducers converting fluid-column pressure to electrical signals. German trauma centers and Japanese university hospitals anchor European and Asian demand respectively, drawn by precision specifications for abdominal compartment syndrome surveillance. PMDA evidentiary requirements delay new sensor introductions.
- Monitor:Bedside devices with analog-digital conversion and alarm thresholds for sustained intra-abdominal hypertension detection.
- Accessory:Saline instillation bags, stopcocks, and connection tubing completing disposable circuits.
Catheter holds the largest share; momentum sits with Sensor as wireless architectures displace hardwired bedside systems.
End User:
Cost tier stratification separates capital-intensive hospital installations from margin-compressed outpatient settings where disposable economics dominate purchasing decisions.
- Hospitals:Integrated ICU departments with bundled critical-care contracts and dedicated biomedical engineering support. United States academic medical centers and German Maximalversorgung hospitals concentrate purchasing volume, though replacement cycles stretch to seven years for monitor hardware. CMS reimbursement codes for continuous hemodynamic monitoring sustain capital allocation.
- Surgical Centers:Ambulatory facilities performing laparoscopic and open abdominal procedures requiring postoperative pressure surveillance. Day-clinic expansion in Japan's urban corridors and United States suburban markets drives compact, disposable-heavy system demand. Group purchasing organization leverage compresses pricing power.
- Clinics:Outpatient settings with intermittent monitoring needs and limited capital budgets.
- Emergency Departments:Pre-hospital and triage environments where rapid assessment protocols are expanding.
Hospitals command the revenue base; surgical centers are climbing the fastest as ambulatory migration accelerates.
Technology:
Application context dictates architecture selection, with invasive systems retaining surgical ICU dominance while wireless platforms penetrate step-down and transport scenarios.
- Invasive:Catheter-based bladder or gastric instillation with direct fluid-column pressure measurement. Retains installed-base dominance across United States and German surgical ICUs where protocol standardization and liability frameworks favor established methods. Catheter-associated infection risk creates institutional resistance in prolonged monitoring cases.
- Wireless:RF telemetry eliminating tethered connections between sensor and monitor. Japanese post-ICU step-down units and United States emergency medical services represent white-space penetration opportunities without displacing hardwired legacy infrastructure. Battery life and sterilization validation extend development timelines.
- Non-Invasive:External abdominal wall tension or ultrasonic estimation methods.
- Fiber Optic:Miniaturized transducer heads using light interference patterns for pressure quantification.
Invasive technology retains the largest installed base; fiber optic platforms are expanding most quickly as German pediatric trauma centers pilot sub-millimeter catheter compatibility.
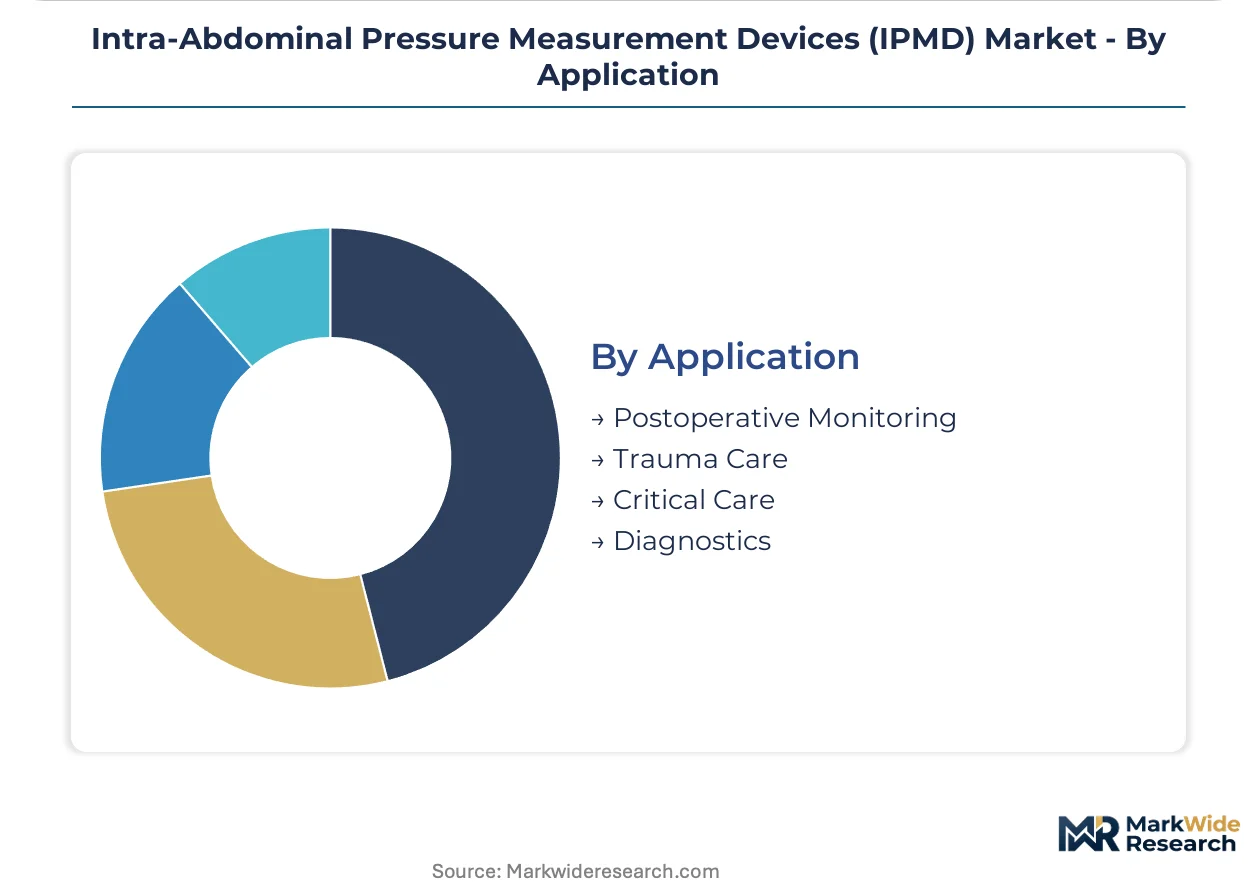
Application:
Customer type stratification separates scheduled surgical workflows from emergent trauma protocols with divergent equipment durability and speed-to-measurement requirements.
- Trauma Care:Rapid intra-abdominal pressure assessment in hemorrhagic shock and blunt abdominal injury. Level I United States trauma centers and Japanese designated emergency hospitals mandate documented surveillance, forcing catheter-monitor bundle refreshes. Field triage expansion into emergency medical services creates ruggedized disposable demand.
- Critical Care:Sustained monitoring in mechanically ventilated surgical patients for early abdominal compartment syndrome detection. German and Japanese critical care society guidelines normalizing hourly measurement drive disposable catheter throughput. ICU staffing ratios limit continuous protocol adherence.
- Postoperative Monitoring:Scheduled surveillance following major abdominal surgery.
- Diagnostics:Intermittent pressure measurement for suspected but unconfirmed pathology.
Trauma care captures the premium pricing tier; critical care holds the volume base as protocol standardization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japanese post-ICU wards exhibit the highest price elasticity as wireless platforms compete against established hardwired systems, while German Maximalversorgung hospitals show the least sensitivity given protocol mandates and bundled critical-care contracts.
United States
Level I trauma center certification mandates and CMS reimbursement codes for continuous hemodynamic monitoring sustain capital allocation to catheter-monitor bundles. FDA Class II device controls elevate quality-system burdens that favor integrated manufacturers over accessory-only suppliers. The Southeast trauma corridor spanning Atlanta, Houston, and Miami concentrates replacement-cycle demand as facilities refresh aging installed bases.
Germany
Critical care society guidelines normalizing hourly IAP measurement in mechanically ventilated surgical patients drive disposable catheter throughput. EU MDR Article 10 clinical-evaluation requirements and notified-body recertification demands compress margins for smaller players. The Baden-Württemberg medical technology cluster around Tübingen and Freiburg anchors specialized neurosurgical and abdominal pressure monitoring production.
Japan
Post-ICU surgical wards remain underserved by continuous monitoring infrastructure, creating white-space penetration opportunities for wireless platforms. PMDA evidentiary standards for imported devices are tightening in observation of European MDR precedents. The Kansai region surrounding Osaka concentrates university hospital procurement volume for precision-specification sensor demand.
Taiwan
MEMS foundry concentration for pressure-sensor wafer fabrication exposes device assemblers to allocation risk during semiconductor capacity crunches. The island's specialty semiconductor houses serve as the dominant upstream supply node for transducer components. Hsinchu Science Park anchors wafer fabrication capacity that feeds catheter system manufacturers across North America and Europe.
United Kingdom
NHS procurement frameworks for critical care equipment concentrate purchasing power through national competitive tendering. MHRA alignment with EU MDR standards maintains elevated clinical-evidence requirements for invasive pressure-monitoring systems. The Oxford-Cambridge-London golden triangle concentrates academic medical center demand where research protocols drive early adoption of fiber-optic modalities.
Intra-Abdominal Pressure Measurement Devices (IPMD) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated sensor fabricators commanding premium positioning while assembly-focused device makers compete on disposable economics. The market structure tilts toward consolidation as regulatory barriers and MEMS foundry concentration squeeze mid-tier participants. Three archetypes dominate: backward-integrated multinationals with captive transducer production, specialized European manufacturers with neurosurgical lineage, and modular disposable suppliers serving price-sensitive surgical centers. Competitive moves center on unbundling sensor-disposable contracts from monitor hardware leases and securing Taiwanese foundry allocation through long-term supply agreements.
Among integrated multinationals, BD exemplifies the backward-integrated archetype with in-house pressure-sensor MEMS fabrication, while Spiegelberg GmbH & Co. KG anchors the specialized European tier through its neurosurgical and abdominal pressure monitoring heritage. C2DX, Inc. occupies a position within the modular disposable segment where unbundled procurement patterns elevate standalone suppliers. These three represent the competitive spectrum from upstream component control to clinical-application specialization and cost-optimized assembly.
| Leading Market Players |
|---|
| Biometrix Corporation |
| Gaeltec Devices Ltd. |
| BD |
| C2DX, Inc. |
| Spiegelberg GmbH & Co. KG |
| Convatec Group PLC |
| Medline Industries, Inc. |
| Potrero Medical |
| Accuryn Medical |
| Others |
Supply & Pricing Matrix
FDA Class II device controls and EU MDR certification regimes simultaneously gate supplier qualification and enable price differentiation across catheter-monitor bundles and standalone disposable tiers. These regulatory barriers concentrate pricing power with backward-integrated manufacturers while compressing margins for assembly-only competitors lacking in-house transducer fabrication.
Pricing Analysis
After-sales revenue from disposable catheter replacements and sensor calibration services drives lifetime customer value beyond initial monitor hardware leases. Three-tier pricing structure across premium, standard, and economy levels separates integrated system vendors from modular disposable suppliers and private-label catheter assemblers. Cost compression in the economy tier is intensifying because group purchasing organizations now unbundle sensor-disposable contracts from capital equipment leases. Surgical centers exhibit the highest price sensitivity as ambulatory migration accelerates, while German Maximalversorgung hospitals show the least sensitivity given protocol mandates and bundled critical-care contracts.
Supply Chain Analysis
Inbound logistics costs from Taiwanese MEMS foundries through transpacific trade lanes expose device assemblers to container availability volatility and port congestion at Los Angeles and Rotterdam. Supply concentrates in Taiwan for pressure-sensor wafer fabrication, Germany for specialty semiconductor finishing, and the United States for final monitor assembly and sterilization validation. Raw material dependencies span silicon wafers, medical-grade polyurethane tubing, and biocompatible adhesives. Single-source vulnerability in Taiwanese foundry capacity creates allocation risk during semiconductor demand surges. Distribution runs through hospital group purchasing organizations and specialized critical-care distributors serving Level I trauma centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable catheter replacement cycles and sensor calibration contracts represent a recurring-revenue layer expanding faster than bedside monitor hardware sales, positioning the market as a service-attach opportunity for vendors with installed-base penetration.
For Market Incumbents: Secure long-term supply agreements with Taiwanese MEMS foundries to defend against allocation risk during capacity crunches. Deepen backward integration into pressure-sensor fabrication to maintain margin control as group purchasing organizations unbundle contracts and compress pricing power for bundled system vendors. For New Entrants and Emerging Players: Lead with wireless IPMD platforms targeting Japanese post-ICU step-down units where continuous monitoring infrastructure remains underserved and hardwired legacy systems face no displacement risk. Penetrate United States emergency medical services with ruggedized disposable pressure sensors designed for pre-hospital trauma triage protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across wireless IPMD development as MEMS physics, RF engineering, and sterilization validation expertise scarcity extends product timelines. Over the medium-term horizon, acquisition targets include modular disposable suppliers with GPO contracts and standalone sensor manufacturers with PMDA or FDA submission experience. The signal to watch is EU MDR notified-body recertification delays that would accelerate consolidation among smaller accessory manufacturers lacking post-market surveillance documentation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined FDA Class II submissions reduce time-to-revenue for catheter-monitor bundles in Level I trauma centers. |
| EU MDR Notified Body Partnership | Early engagement with German notified bodies secures Article 10 clinical-evaluation compliance for invasive pressure-monitoring renewals. |
| Taiwanese Foundry Allocation Agreement | Long-term wafer supply contracts with Hsinchu Science Park fabs insulate against MEMS capacity crunches. |
| Wireless Platform Development | RF telemetry architectures penetrate Japanese step-down units without displacing hardwired ICU infrastructure. |
| Reimbursement Strategy Investment | CMS code alignment for continuous hemodynamic monitoring sustains capital allocation in United States academic medical centers. |
Research Methodology
Cross-validation between primary interviews with ICU clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, CMS reimbursement databases, EU MDR notified-body documentation, and hospital procurement records. Bottom-up demand modeling triangulates with top-down market sizing across product type, end user, technology, and application dimensions.
Sensitivity analysis frames volume and value outputs across the analysis window, with segmentation dimensions spanning invasive versus wireless technology architectures, trauma center versus surgical center end users, and catheter versus sensor versus monitor product types. CAGRs derive from installed-base replacement cycles, protocol adoption curves, and wireless penetration assumptions in step-down environments. Forecast inputs incorporate Taiwanese foundry capacity utilization, EU MDR recertification timelines, and Japanese PMDA evidentiary precedent observations.
Forecasts assume regulatory continuity in FDA Class II device controls and EU MDR Article 10 requirements; material policy shifts would require re-modeling. Specific risk factors include catheter-associated infection liability frameworks that could delay IAP monitoring adoption and MEMS foundry concentration that could constrain sensor supply. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
Tissue Expanders Market
Medical Devices
Corneal Implants Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Infusion Management Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Gracey Curette Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Heel Incision Devices Market