
 Global Oxygen Conservation Devices Market | 2026-2036
Global Oxygen Conservation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oxygen Conservation Devices Market Foresight
China is fragmenting as domestic manufacturers scale oxygen conservation device production for regional export. Philips Healthcare leverages its integrated respiratory portfolio to sustain hospital channel dominance across North America. ResMed Inc. anchors its position through sleep apnea therapy crossover demand, while Inogen Inc. competes aggressively in portable device segments. Invacare Corporation differentiates via long-term care facility relationships, and Precision Medical Inc. specializes in precision valve engineering for pulse dose systems.
Oxygen conservation devices regulate oxygen delivery through demand-triggered pulse dosing, continuous flow modulation, or hybrid reservoir systems, typically operating at 2-15 liters per minute with conservation ratios of 2:1 to 7:1 compared to standard continuous flow. These devices reduce cylinder consumption and extend ambulatory mobility for patients with chronic respiratory insufficiency. Pulse dose technology leads installed base volumes due to established reimbursement codes, yet wearable deployment formats are capturing fastest-growing demand as lithium-ion power density improves. Home healthcare providers represent the deepest margin pool because recurring cannula and battery purchases generate sustained aftermarket revenue.
The FDA governs 510(k) premarket notification requirements for oxygen conservation devices in the United States, while the EU MDR imposes stricter clinical evidence standards for Class IIa respiratory equipment marketed in Europe. Japan's PMDA maintains distinct pharmacovigilance reporting that shapes post-market surveillance obligations for manufacturers. India's CDSCO has aligned with ISO 13485 quality management standards under revised Medical Device Rules, accelerating import substitution. Stakeholders must monitor how WHO technical specifications for oxygen systems in low-resource settings reshape procurement criteria for humanitarian and public health tenders.
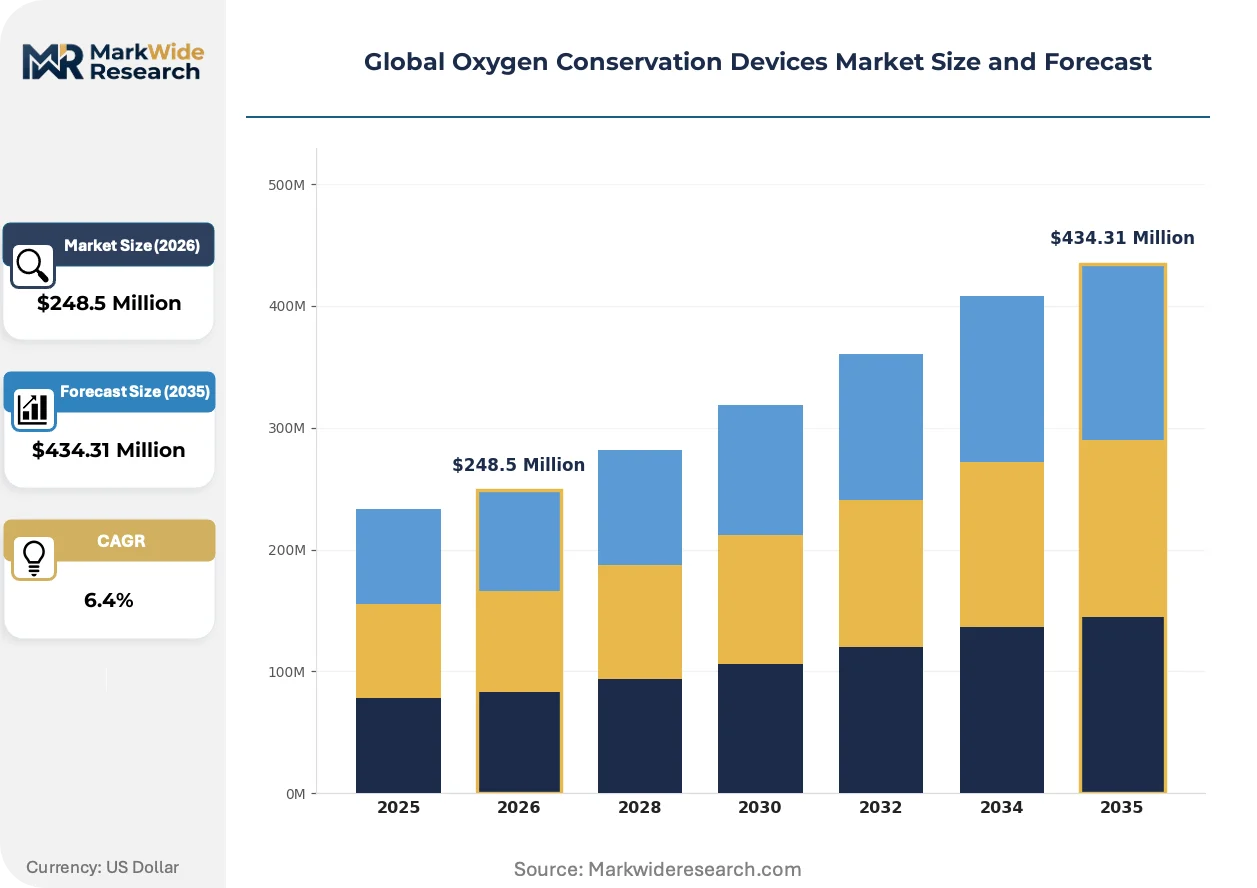
Market Dynamics
Post-acute care decentralization is compressing hospital oxygen delivery volumes while amplifying ambulatory device demand across home healthcare networks. Lithium-ion power density improvements are collapsing the size-performance tradeoff that previously constrained wearable formats.
Growth Catalysts
- India's PLI scheme for medical devices:Domestic manufacturing capacity expansion reduces import dependency and shortens fulfillment cycles for regional distributors serving South Asian markets.
- Pulse dose reimbursement codes:Established coding in Medicare and commercial payor schedules anchors clinician prescribing behavior toward conservation-enabled ambulatory therapy.
- Chronic respiratory insufficiency prevalence:COPD and interstitial lung disease patient pools in aging populations sustain recurring device replacement cycles and consumable attachment rates.
Market Restraints
- Lithium supply concentration:Battery cell production gravity in China creates input cost volatility and geopolitical exposure for portable device manufacturers.
- EU MDR clinical evidence requirements:Stricter documentation burdens for Class IIa respiratory equipment extend certification timelines and elevate regulatory compliance spend.
- Continuous flow oxygen concentrators:Stationary alternatives retain preference in severe hypoxemia cases where pulse dose titration risks desaturation events.
Strategic Opportunities
- Humanitarian procurement under WHO technical specifications:Low-resource setting tenders for oxygen systems create volume anchors for simplified, durable device architectures.
- Wearable form factor convergence:Integration of pulse oximetry and telemetry into conservation hardware enables remote patient monitoring reimbursement stacking.
- Japan's PMDA pharmacovigilance alignment:Post-market surveillance infrastructure investments position early entrants for premium positioning in aging, regulation-attentive markets.
Industry Challenges
- ISO 13485 quality management implementation:Small manufacturers face capability gaps in risk management documentation and supplier audit protocols required for CE marking.
- Legacy cannula compatibility:Proprietary connector designs fragment aftermarket consumable ecosystems and complicate patient switching between device brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oxygen Conservation Devices Market |
| Market Size in 2026 | $248.5 Million |
| Market Size in 2035 | $434.31 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Dose, Continuous Flow, Hybrid, Reservoir Application: Chronic Obstructive Pulmonary Disorders, Interstitial Lung Disease, Pneumonia Management, Sleep Apnea Therapy, Cystic Fibrosis End User: Hospitals, Pulmonary Clinics, Home Healthcare Providers, Long-term Care Facilities, Rehabilitation Centers Deployment: Portable Devices, Stationary Systems, Wearable Devices, Vehicle-mounted Units |
| Companies Covered | Philips Healthcare, ResMed Inc., Invacare Corporation, Chart Industries, Drive DeVilbiss Healthcare, Inogen Inc., Precision Medical Inc., GCE Group, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oxygen Conservation Devices Market Shifts & Advancements
Device miniaturization and software-defined dosing algorithms are dissolving the boundary between stationary and portable oxygen therapy. Three interconnected developments are compressing product lifecycles and reshaping competitive entry points.
Microelectromechanical flow sensors combined with adaptive valve control are collapsing the performance gap between pulse dose and continuous flow systems. Home healthcare providers are deploying these hybrid architectures to reduce cylinder inventory carrying costs while preserving clinical flexibility. The compression of format distinctions is forcing manufacturers to compete on software personalization rather than hardware specifications alone.
The EU MDR's expanded clinical evidence requirements for Class IIa respiratory devices are elevating post-market surveillance obligations across European markets. Manufacturers must now maintain active implantable-grade vigilance systems for conservation devices previously regulated under lighter touch regimes. German and French notified bodies are extending review timelines, compressing product launch windows for mid-tier competitors lacking established quality infrastructures.
Direct-to-patient subscription models are displacing durable medical equipment distributor intermediaries in North American markets. Sleep therapy crossover vendors are leveraging existing patient databases to bypass traditional respiratory homecare channels. This channel compression is most visible in United States metropolitan corridors where Medicare competitive bidding has already thinned distributor margins and reduced field service intensity.
Global Oxygen Conservation Devices Market Segmentation
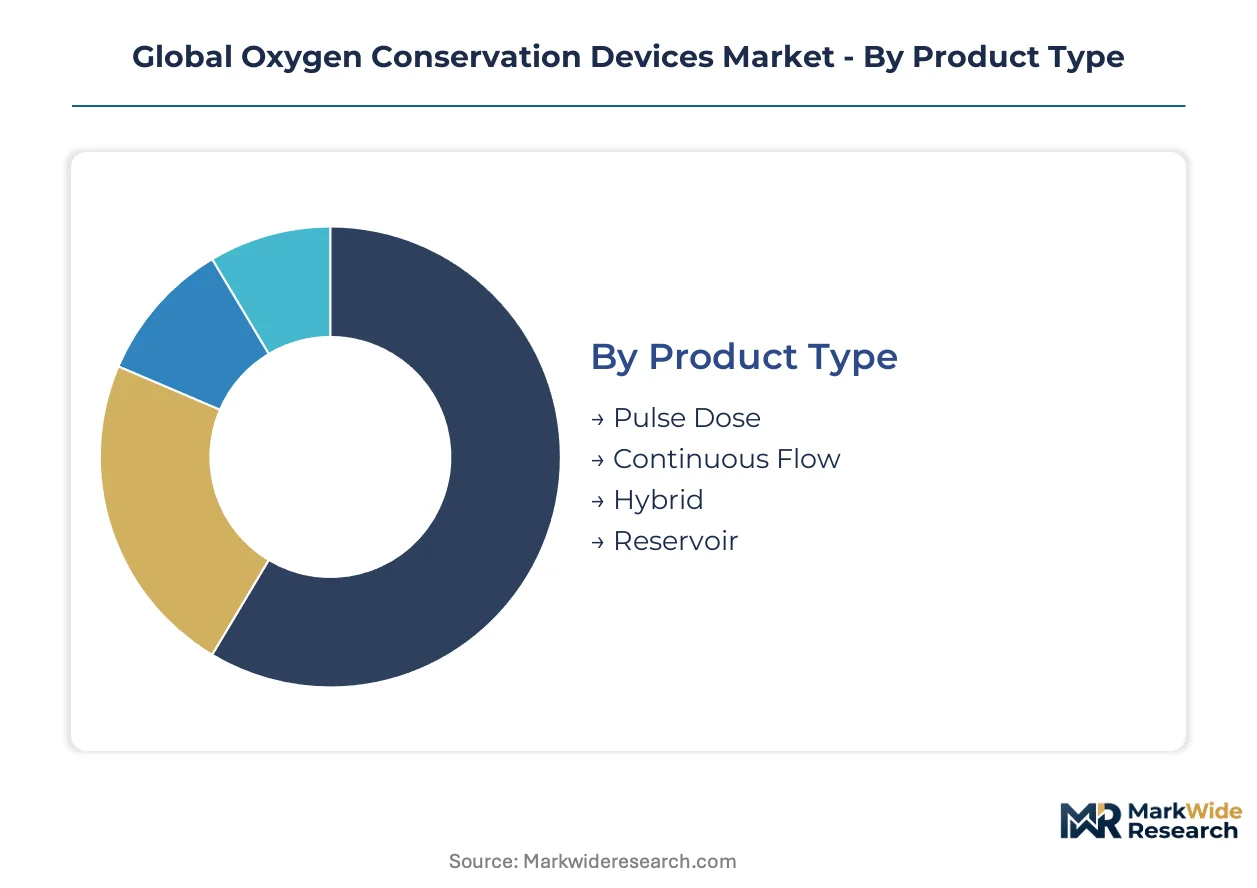
Oxygen conservation devices fragment across four intersecting dimensions that determine procurement patterns and margin structures. Product type governs reimbursement eligibility while deployment format dictates battery chemistry requirements and replacement cadence.
Product Type:
Pulse dose systems turn over fastest due to cannula degradation and valve wear, while reservoir devices cycle slowest given their mechanical simplicity and limited moving parts.
- Pulse Dose:Demand-triggered valve systems release oxygen boluses at the onset of inhalation, achieving conservation ratios up to 7:1 versus continuous flow. Medicare reimbursement codes in the United States anchor hospital discharge prescribing toward this modality, though desaturation risks in severe hypoxemia limit penetration in intensive care settings.
- Continuous Flow:Fixed-rate delivery maintains stable FiO2 for patients with inconsistent breathing patterns or high minute ventilation. Long-term care facilities in Germany and Japan retain preference for this architecture where clinical staff density supports closer monitoring.
- Hybrid:Microprocessor-controlled switching between pulse and continuous modes adapts to activity level changes.
- Reservoir:Nasal cannula with integrated storage chamber captures exhaled oxygen for subsequent inhalation.
Pulse dose anchors the volume base while hybrid architectures gain share at the steepest rate as lithium-ion power density improvements enable adaptive software control.
Application:
Cost tier stratification separates high-acuity hospital-managed conditions from home-monitored chronic diseases with predictable progression curves.
- Chronic Obstructive Pulmonary Disorders:Progressive airflow limitation drives the largest installed base of conservation devices globally. Home healthcare providers in the United States capture recurring revenue through monthly cannula shipments and annual device replacements as Medicare competitive bidding compresses upfront margins.
- Interstitial Lung Disease:Fibrotic parenchymal changes create resting hypoxemia requiring continuous supplementation. Japanese pulmonary clinics prescribe wearable formats at higher rates given METI subsidies for remote monitoring integration.
- Pneumonia Management:Acute infection episodes typically resolve within weeks, shortening device rental periods.
- Sleep Apnea Therapy:Crossover demand from CPAP vendors compresses traditional respiratory homecare channel margins.
- Cystic Fibrosis:Pediatric onset extends device lifecycle value through multiple replacement cycles into adulthood.
COPD concentrates the revenue base while sleep apnea therapy climbs the fastest as sleep therapy vendors leverage existing patient databases for vertical expansion.
End User:
Customer type determines service intensity requirements and consumable attachment rates across the ownership lifecycle.
- Hospitals:Acute care settings prioritize rapid patient turnover and standardized device fleets. India's CDSCO-aligned procurement under revised Medical Device Rules is accelerating import substitution for public hospital tenders.
- Home Healthcare Providers:Recurring cannula and battery purchases generate sustained aftermarket revenue streams. Direct-to-patient subscription models in United States metropolitan corridors are displacing traditional distributor intermediaries.
- Pulmonary Clinics:Specialist prescribing concentrates high-margin wearable deployments.
- Long-term Care Facilities:Staff-to-patient ratios favor simpler continuous flow systems with minimal training requirements.
- Rehabilitation Centers:Transitional care settings bridge hospital discharge to home oxygen therapy.
Home healthcare providers anchor the margin pool while pulmonary clinics drive the steepest expansion trajectory for premium wearable formats.
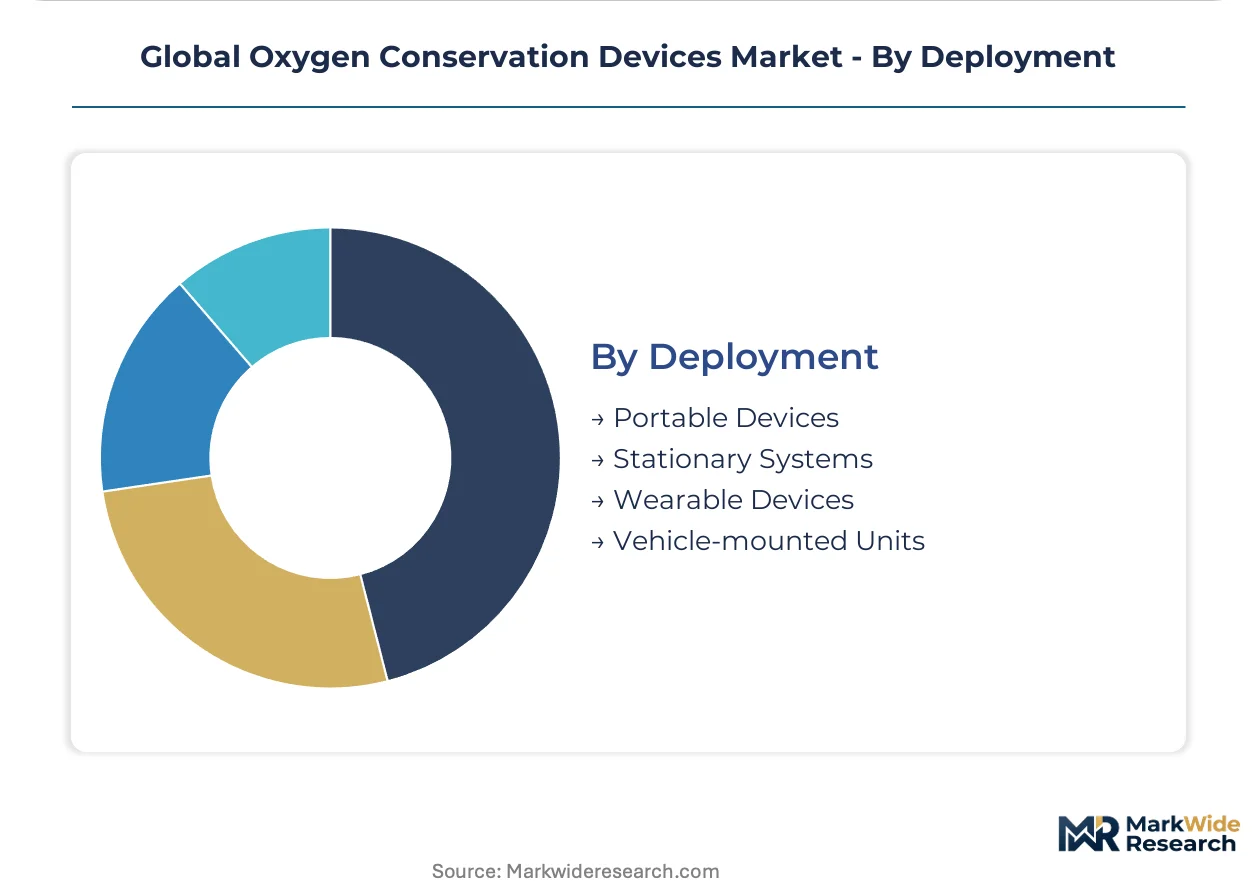
Deployment:
Supply concentration in Chinese battery cell manufacturing creates input cost volatility that fragments pricing power across portable versus stationary formats.
- Portable Devices:Cylinder-mounted or concentrator-integrated systems enable ambulatory mobility for active patients. Lithium supply concentration in China's Yangtze River Delta creates geopolitical exposure for manufacturers dependent on NMC cathode chemistry.
- Wearable Devices:Belt-worn or pendant-form architectures integrate pulse oximetry and telemetry for remote patient monitoring. EU MDR clinical evidence requirements for Class IIa respiratory equipment extend certification timelines for European market entry.
- Stationary Systems:Bedside or wheelchair-mounted devices dominate severe hypoxemia cases.
- Vehicle-mounted Units:DC-powered systems support mobile oxygen delivery for transportation-dependent patients.
Portable devices anchor the installed base while wearable formats gain share most quickly as software-defined dosing algorithms compress size-performance tradeoffs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 510(k) clearance pathways anchor the United States as the regulatory benchmark shaping product entry timelines for respiratory device manufacturers worldwide. Post-acute care decentralization is compressing hospital oxygen delivery volumes across mature markets while amplifying ambulatory device demand. India's PLI scheme for medical devices is stimulating domestic manufacturing capacity for regional export.
United States
Medicare competitive bidding and established pulse dose reimbursement codes anchor clinician prescribing behavior toward conservation-enabled ambulatory therapy. The FDA governs 510(k) premarket notification requirements, streamlining product entry compared to European pathways. Metropolitan corridors in California and Texas are witnessing direct-to-patient subscription models displace traditional durable medical equipment distributor intermediaries.
Germany
Long-term care facilities retain preference for continuous flow systems where clinical staff density supports closer monitoring of severe hypoxemia cases. The EU MDR imposes stricter clinical evidence standards for Class IIa respiratory equipment, extending certification timelines and elevating compliance spend. Notified bodies in Berlin and Munich are compressing product launch windows for mid-tier competitors lacking established quality infrastructures.
India
Public hospital tenders under revised Medical Device Rules are accelerating import substitution as CDSCO aligns with ISO 13485 quality management standards. The PLI scheme for medical devices reduces import dependency and shortens fulfillment cycles for regional distributors serving South Asian markets. Manufacturing clusters in Maharashtra and Gujarat are scaling oxygen conservation device production for regional export.
Japan
Pulmonary clinics prescribe wearable formats at higher rates given METI subsidies for remote monitoring integration for interstitial lung disease patients. PMDA maintains distinct pharmacovigilance reporting that shapes post-market surveillance obligations for manufacturers. The Kanto region around Tokyo anchors premium positioning in this aging, regulation-attentive market.
China
Domestic manufacturers are scaling oxygen conservation device production for regional export as market fragmentation intensifies. NMPA oversight and MIIT industrial policy shape quality standards and manufacturing investment flows. The Yangtze River Delta concentration of battery cell production creates input cost volatility and geopolitical exposure for portable device manufacturers dependent on lithium-ion supply chains.
Global Oxygen Conservation Devices Market Competitive Landscape
Integrated respiratory portfolio vendors and portable device specialists split the market between hospital channel dominance and ambulatory mobility segments. The vendor base concentrates around sleep therapy crossover players leveraging existing patient databases and precision valve engineering specialists serving pulse dose system demand. Two strategic archetypes anchor competitive positioning: diversified medical technology conglomerates with respiratory divisions, and focused oxygen therapy pure-plays competing on form factor innovation. M&A activity targets remote patient monitoring capabilities, while capacity expansion concentrates in Indian PLI-eligible facilities and Chinese battery integration hubs.
Within the diversified medical technology tier, Philips Healthcare and Medtronic plc occupy positions anchored by integrated hospital channel relationships and broad respiratory portfolios. Among portable device specialists, Inogen Inc. exemplifies the pure-play archetype competing aggressively on wearable form factors and lithium-ion power density improvements. ResMed Inc. sits within the sleep therapy crossover category, leveraging existing patient databases to bypass traditional respiratory homecare channels in North American metropolitan corridors. These three company types represent the competitive structure without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Philips Healthcare |
| ResMed Inc. |
| Invacare Corporation |
| Chart Industries |
| Drive DeVilbiss Healthcare |
| Inogen Inc. |
| Precision Medical Inc. |
| GCE Group |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta battery cell manufacturing cluster in China anchors lithium-ion supply for portable oxygen conservation devices, concentrating cathode chemistry pricing power among NMC suppliers and forcing downstream manufacturers into long-term offtake negotiations to secure cell allocation.
Pricing Analysis
Geographic price spreads between North American and South Asian markets exceed 30% for equivalent pulse dose systems, driven by FDA 510(k) certification premiums and EU MDR clinical evidence compliance costs. Three-tier pricing structure across premium wearable formats, standard portable devices, and economy stationary systems separates reimbursement-eligible configurations from cash-pay alternatives. Cost compression in economy tiers intensifies because Indian PLI-subsidized manufacturing is flooding regional export markets with ISO 13485-certified alternatives. Home healthcare providers exhibit highest price sensitivity due to Medicare competitive bidding margin compression, while Japanese pulmonary clinics demonstrate lowest sensitivity given METI remote monitoring subsidies.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for lithium-ion cell procurement, with supply-chain finance facilities emerging as working capital bridges for mid-tier device assemblers. Manufacturing capacity concentrates in China, India, and Germany, with the Yangtze River Delta feeding battery inputs, Maharashtra-Gujarat clusters handling final assembly under PLI incentives, and Bavarian precision valve specialists supplying pulse dose components. Raw material dependencies span lithium carbonate, nickel-manganese-cobalt cathode powders, and medical-grade silicone cannula tubing. Single-source vulnerability in Chinese battery cell production creates geopolitical exposure for portable device manufacturers. Distribution runs through durable medical equipment distributors in North America, direct-to-patient subscription platforms in metropolitan corridors, and public hospital procurement tenders in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oxygen conservation device incumbents face substitution pressure from sleep therapy crossover vendors leveraging CPAP patient databases to bypass traditional respiratory homecare channels, requiring defensive repositioning around remote monitoring integration and consumable lock-in.
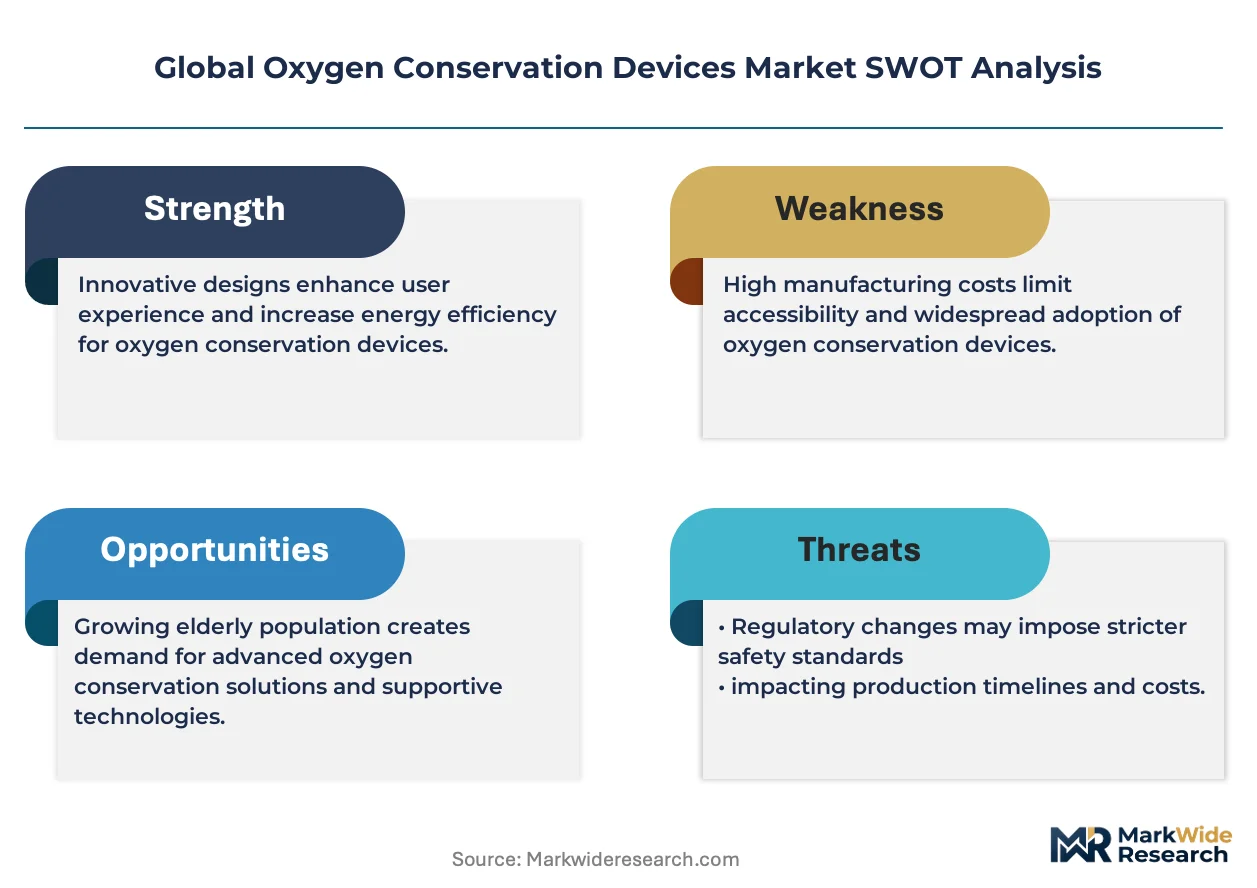
For Market Incumbents: Entrench hospital channel relationships through biomedical engineering training programs and GPO contract exclusivity clauses that complicate vendor switching. Deepen backward integration into precision valve manufacturing to defend margin position against Indian PLI-subsidized competitors. Prioritize FDA 510(k) clearance stacking for software-defined dosing algorithms that create regulatory moats against sleep therapy crossover entrants lacking respiratory device quality infrastructures.
For New Entrants and Emerging Players: Build out wearable form factor capabilities targeting Japanese pulmonary clinics where METI subsidies for remote monitoring integration reduce customer acquisition costs and accelerate reimbursement stacking. Target India's CDSCO-aligned public hospital tenders under revised Medical Device Rules, where import substitution mandates create procurement preference for domestic manufacturers. Pursue humanitarian procurement channels under WHO technical specifications for low-resource settings, where simplified device architectures and volume anchors offset premium positioning limitations.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core respiratory divisions amid portfolio rationalization pressures. Long-term viability hinges on software companion development capabilities and telemetry integration rather than hardware manufacturing scale alone. Monitor lithium supply contract renegotiation cycles as inflection indicators for portable device manufacturer margin trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates US market entry against EU MDR's extended clinical evidence timelines. |
| CE Marking Pathway | Unlocks German and French hospital procurement despite notified body review delays. |
| Hospital System Partnership | Secures GPO contract anchoring against sleep therapy crossover channel displacement. |
| Software Companion Development | Enables remote patient monitoring reimbursement stacking in Japanese METI-subsidized clinics. |
| Reimbursement Strategy | Aligns pulse dose coding with Medicare schedules to anchor clinician prescribing behavior. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, home healthcare procurement managers, pulmonary clinic prescribing physicians, GPO contracts administrators, and CDSCO regulatory consultants. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, CMS Medicare competitive bidding records, and Indian PLI scheme beneficiary disclosures. Bottom-up installed base modeling triangulated against top-down expenditure flow analysis across the projection horizon.
Calibration against historical pulse dose system replacement cycles and cannula consumable attachment rates anchored volume projections. Segmentation dimensions spanned product type architecture, deployment format battery chemistry, application severity tier, and end-user service intensity. CAGRs were derived from logistic diffusion curves fitted to wearable format adoption patterns and lithium-ion power density improvement trajectories. Forecast inputs incorporated COPD prevalence demographic modeling and interstitial lung disease diagnostic rate trends.
Stress conditions across lithium supply disruption, EU MDR certification timeline extension, and Medicare reimbursement code revision were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PLI scheme continuation and ISO 13485 quality management standard alignment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Subdural Electrodes Market
Medical Devices
Cholecystectomy Devices Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Germany Minimally Invasive Surgery Devices Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market