
 Neurointerventional Devices Market | 2026-2036
Neurointerventional Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neurointerventional Devices Market Outlook
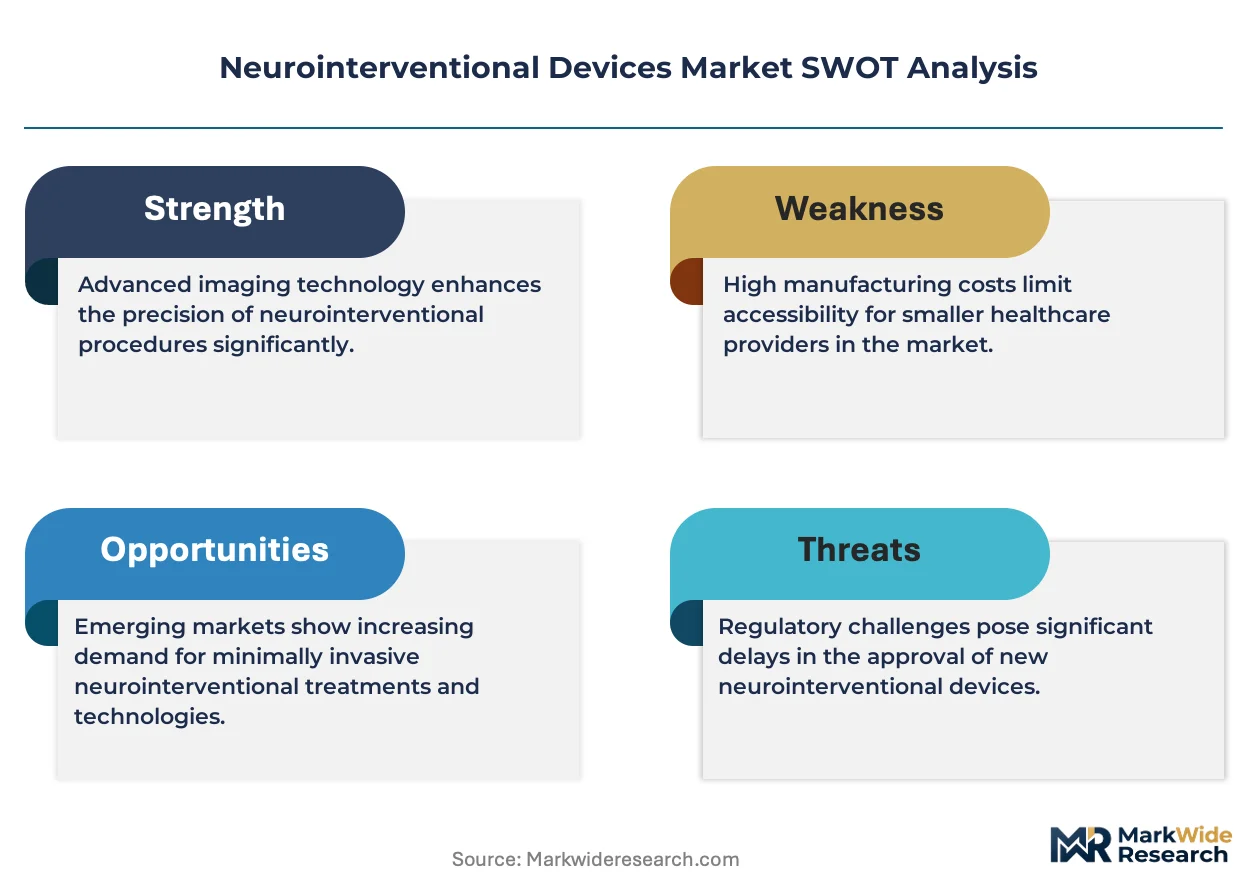
The EU Medical Device Regulation is repositioning the cost-of-entry calculus for neurointerventional manufacturers, demanding expanded clinical evidence and notified body recertification. Stryker leverages its stroke systems portfolio to dominate thrombectomy hardware installations across European stroke centers. Medtronic anchors its position through deep R&D intensity in flow diversion technology for cerebral aneurysms. Penumbra differentiates via specialized aspiration catheters that compete directly with stent-retriever approaches in acute ischemic stroke.
Neurointerventional devices comprise minimally invasive instruments—typically nitinol, platinum-tungsten, or cobalt-chromium constructs with catheter outer diameters ranging from 1.7 to 6 French—designed for endovascular navigation through cerebral vasculature to treat cerebrovascular pathologies. These instruments enable therapeutic intervention without craniotomy, reducing procedural morbidity and hospitalization duration. Coil-based aneurysm occlusion represents the mature revenue pool, while thrombectomy catheters constitute the fastest-growing application segment driven by expanded treatment windows and mobile stroke unit deployment. Hospital end users capture the dominant procurement volume, though ambulatory surgical centers are gaining share for elective carotid stenting procedures.
FDA breakthrough device designation and EMA centralized marketing authorization create divergent compliance pathways that shape regional product launch sequencing. The EU MDR technical documentation requirements and FDA quality system regulation enforce biocompatibility and fatigue-testing standards that filter smaller manufacturers from premium device tiers. Stakeholders must monitor how reimbursement authorities in France, Germany, and Japan calibrate procedure codes for emerging flow diverters against established coiling tariffs.
Market Dynamics
Catheter-based thrombectomy programs are expanding across United States stroke centers, compressing treatment windows and forcing hardware procurement cycles that favor integrated stroke system vendors over standalone device suppliers.
Growth Catalysts
- Expanded treatment windows:Mobile stroke unit deployment in Germany and the United States extends mechanical thrombectomy eligibility to 24 hours post-onset, driving catheter demand.
- FDA breakthrough pathways:Premarket notification acceleration for novel embolic coils shortens commercialization timelines for aneurysm occlusion devices.
- Nitinol construct advances:Shape-memory alloy engineering enables smaller French-size access catheters with improved torquability through tortuous cerebral vasculature.
Market Restraints
- Platinum-tungsten input volatility:Coil manufacturing depends on precious metal supply chains concentrated in South African mining operations.
- EU MDR recertification burden:Expanded clinical evidence requirements for flow diverters and aspiration systems filter smaller manufacturers from premium tiers.
- Microsurgical clipping persistence:Cerebrovascular surgeons at academic medical centers retain preference for open aneurysm repair in complex morphologies.
Strategic Opportunities
- Ambulatory surgical center channel:Elective carotid stenting procedures are migrating from hospital inpatient settings to ASCs in the United States, creating direct procurement relationships.
- Artificial intelligence imaging integration:Large-vessel occlusion detection algorithms are converging with mobile CT platforms to triage patients directly to thrombectomy-capable centers.
- Japan PMDA fast-track:Sakigake designation for innovative medical devices accelerates market entry for next-generation stent retrievers.
Industry Challenges
- Neurointerventionalist training pipeline:Fellowship positions in endovascular surgical neuroradiology remain insufficient to staff expanding stroke center networks.
- Biocompatibility fatigue-testing timelines:FDA quality system regulation and ISO 25539-1 compliance extend preclinical validation for cobalt-chromium constructs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurointerventional Devices Market |
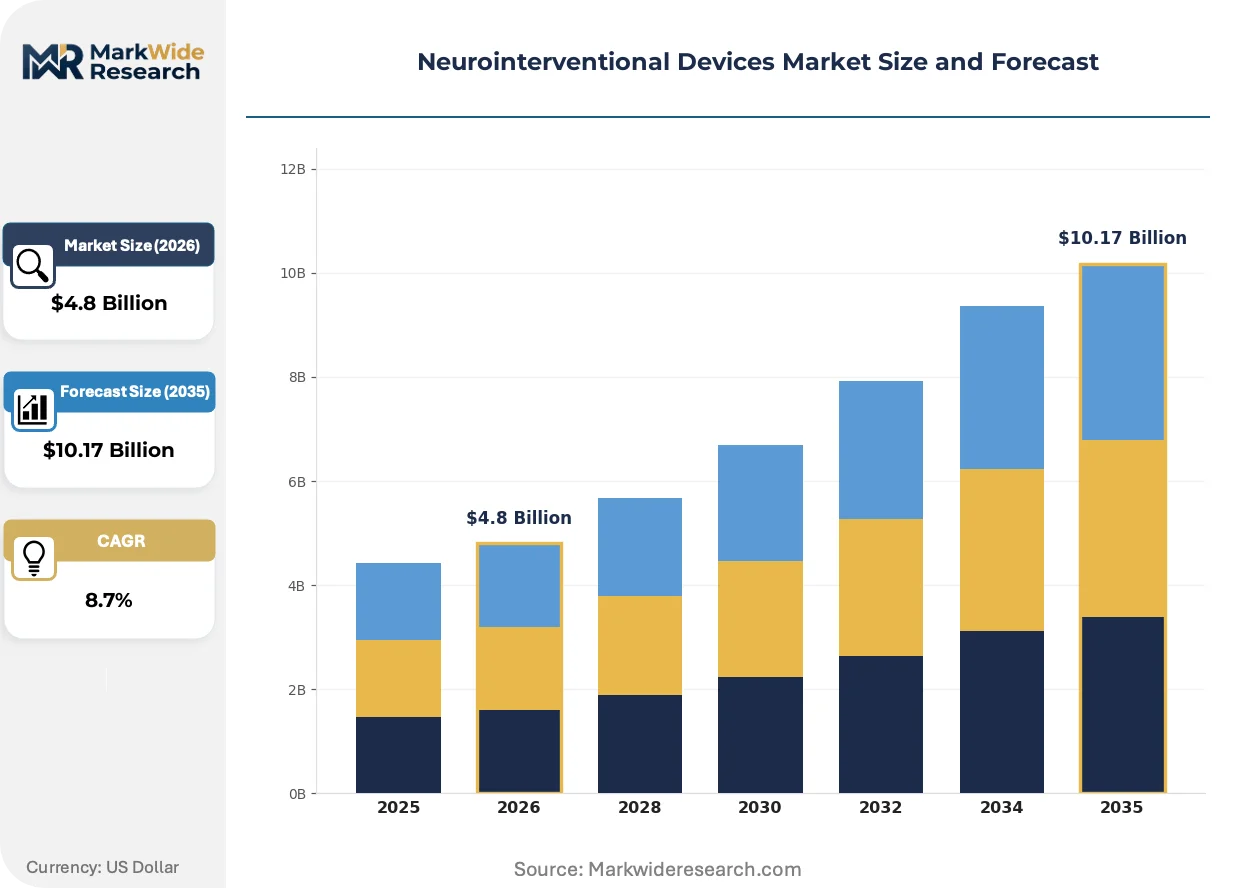
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
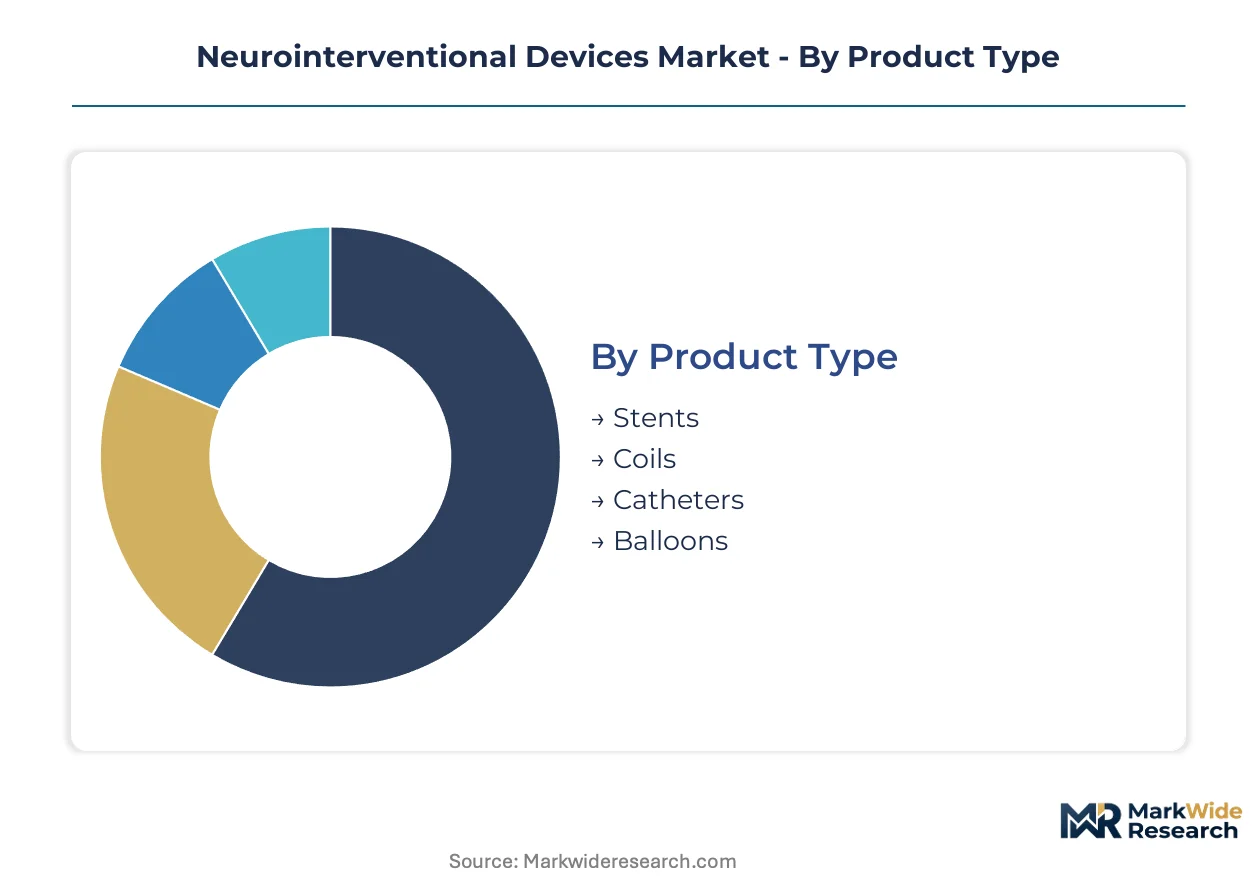
| Segmentation | Product Type: Stents, Coils, Catheters, Balloons Application: Aneurysm Repair, Thrombectomy, Vascular Malformations, Carotid Artery Stenting End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutions Delivery Mode: Direct, Intravenous, Intra-arterial, Local |
| Companies Covered | Stryker, Medtronic, Penumbra, Johnson & Johnson, Terumo Corporation, Abbott, Boston Scientific, MicroVention, Balt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurointerventional Devices Market Strategic Shifts
Device engineering is pivoting from standalone mechanical solutions toward integrated hardware-software systems that compress decision-to-treatment intervals and enable remote procedural support.
Robotic catheter navigation is converging with telemedicine infrastructure to enable real-time thrombectomy guidance from centralized specialists to geographically dispersed stroke centers. Academic medical centers in the United States are piloting these systems for after-hours coverage. The structural consequence is a compression of operator experience requirements and potential centralization of complex cases to hub institutions.
EU MDR technical documentation mandates are forcing manufacturers to rebuild quality management systems around post-market clinical follow-up obligations. Notified body capacity constraints in Germany and the Netherlands are extending recertification timelines. Flow diverter manufacturers are responding by consolidating clinical evidence generation across multiple member states to satisfy EMA centralized marketing authorization requirements.
Hospital procurement committees are unbundling stroke system contracts to evaluate thrombectomy hardware, aspiration catheters, and imaging platforms as separate line items. Integrated delivery networks in the United States are driving this fragmentation to optimize total cost of ownership. The shift is most visible in consolidated neuroradiology departments across German comprehensive stroke networks, where tender processes now separate device categories that were previously bundled.
Neurointerventional Devices Market Segmentation
Neurointerventional device procurement hinges on matching catheter specifications to lesion morphology and procedural setting. Hospitals evaluate French size, trackability, and compatibility across manufacturer ecosystems when building stroke program inventories.
Product Type:
Material composition and construct geometry determine reimbursement tiering and clinical indication breadth.
- Stents:Nitinol or cobalt-chromium tubular constructs with laser-cut cell patterns enable vessel scaffolding in carotid stenosis and flow diversion for wide-neck aneurysms. Demand concentrates in comprehensive stroke centers across Germany and the United States, driven by expanded mechanical thrombectomy eligibility windows and growing endovascular neuroradiology fellowship programs.
- Coils:Platinum-tungsten filament bundles with proprietary detachment mechanisms remain the reference therapy for saccular aneurysm occlusion. Procurement in Japanese university hospitals is accelerating under PMDA Sakigake fast-track pathways for next-generation detachable coil systems with improved packing density algorithms.
- Catheters:Aspiration and access catheters with hydrophilic coatings and variable stiffness transitions navigate tortuous cerebral vasculature.
- Balloons:Compliant and non-compliant balloon dilatation systems address intracranial stenosis and assist coil deployment in wide-neck aneurysms.
Volume sits with coils; growth tilts toward aspiration catheters competing with stent-retriever thrombectomy approaches.
Application:
Procedure code valuation and treatment window expansion reshape hardware investment priorities.
- Aneurysm Repair:Endovascular coiling and flow diversion techniques displace microsurgical clipping in anterior circulation aneurysms, though posterior circulation and giant aneurysms retain open surgical preference at academic medical centers. German neuroradiology departments are consolidating evidence generation to satisfy EU MDR post-market clinical follow-up obligations for flow diverter recertification.
- Thrombectomy:Mechanical clot retrieval via stent-retriever or direct aspiration addresses large-vessel occlusion in acute ischemic stroke. Mobile stroke unit deployment across the United States and Germany extends treatment windows to 24 hours post-onset, compressing door-to-puncture intervals and forcing catheter inventory depth at spoke hospitals.
- Vascular Malformations:Liquid embolic agents and detachable coils target arteriovenous malformations and dural arteriovenous fistulas.
- Carotid Artery Stenting:Embolic protection devices and self-expanding stents treat extracranial carotid stenosis in symptomatic patients.
Revenue concentrates in aneurysm repair; expansion accelerates fastest in thrombectomy as stroke networks proliferate.
End User:
Capital intensity and case complexity stratify purchasing authority and vendor relationship structures.
- Hospitals:Academic medical centers and comprehensive stroke centers maintain catheter laboratories with fixed angiography suites and 24/7 neurointerventionalist coverage. Integrated delivery networks in the United States are unbundling stroke system contracts to evaluate thrombectomy hardware, aspiration catheters, and imaging platforms as separate line items rather than single-vendor bundles.
- Ambulatory Surgical Centers:Freestanding facilities with limited recovery capacity are capturing elective carotid stenting cases previously performed in hospital inpatient settings. Direct procurement relationships with device manufacturers are replacing distributor intermediaries as ASCs build cardiovascular service lines.
- Specialty Clinics:Outpatient neuroradiology practices perform diagnostic angiography and minor interventions.
- Research Institutions:Academic consortia generate clinical evidence for regulatory submissions and comparative effectiveness studies.
Procurement volume remains hospital-dominated; fastest share gains are emerging in ambulatory surgical centers for elective procedures.
Delivery Mode:
Access route selection constrains device diameter, length, and torque response specifications.
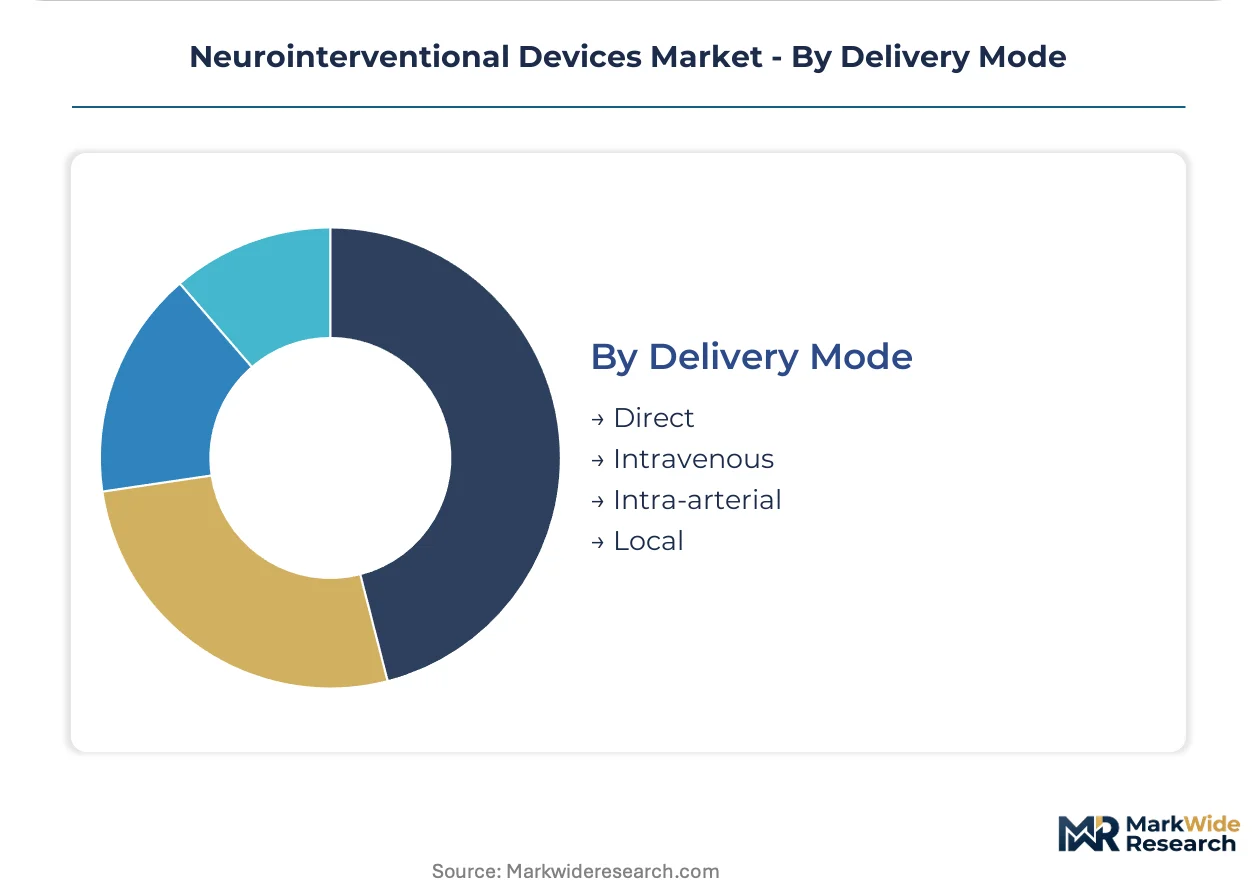
- Intra-arterial:Femoral or radial artery puncture with guiding catheter placement enables direct navigation to intracranial targets. Japanese stroke centers are adopting transradial access protocols to reduce puncture site complications and enable same-day discharge for elective aneurysm treatments.
- Direct:Surgical cutdown or percutaneous access to extracranial vessels supports complex reconstructions.
- Intravenous:Systemic thrombolytic administration precedes or accompanies mechanical thrombectomy in eligible patients.
- Local:Targeted drug infusion at the thrombus interface via microcatheter augments mechanical retrieval.
Intra-arterial access commands procedure volume; local delivery modes are gaining utilization in combined pharmacomechanical approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Ireland and Puerto Rico concentrate manufacturing tax incentives that draw neurointerventional production. These zones reduce effective tax rates and accelerate FDA premarket notification pathways for breakthrough-designated devices.
United States
Comprehensive stroke center certification drives catheter laboratory investments across academic medical centers. FDA breakthrough device designation compresses time-to-market for novel embolic coils and aspiration systems. The Texas Medical Center in Houston anchors thrombectomy training pipelines that feed expanding spoke hospital networks.
Germany
Neuroradiology departments consolidate into comprehensive stroke networks that standardize thrombectomy protocols across Bavaria and North Rhine-Westphalia. EU MDR technical documentation requirements force recertification timelines that filter smaller manufacturers from premium device tiers. Berlin-Brandenburg hosts notified body concentration that shapes regional quality management system rebuilds.
Japan
PMDA Sakigake designation accelerates market entry for next-generation stent retrievers and flow diverters. Transradial access protocols reduce puncture site complications and enable same-day discharge for elective aneurysm treatments. The Kanto region around Tokyo concentrates university hospital procurement authority for detachable coil systems.
China
NMPA innovative medical device pathways shorten registration timelines for domestic flow diverter manufacturers. National stroke center construction targets drive catheter laboratory deployment across tertiary hospitals in the Yangtze River Delta. Shanghai anchors R&D partnerships between local device startups and multinational technology licensors.
Neurointerventional Devices Market Competitive Environment
United States producers anchor the premium-tier device segment; European specialists hold regulatory compliance advantages under centralized EMA pathways. Market structure tilts toward consolidated procurement relationships with integrated stroke system vendors rather than fragmented standalone suppliers. Three archetypes dominate: diversified medtech conglomerates with stroke portfolio breadth, focused neuroradiology specialists with catheter engineering depth, and regional champions leveraging domestic regulatory fast-tracks. Competitive moves concentrate on unbundling stroke system contracts and rebuilding quality management systems around EU MDR post-market clinical follow-up obligations.
Among diversified medtech conglomerates, Stryker and Medtronic exemplify portfolio-scale positioning across thrombectomy hardware and flow diversion technology. Penumbra occupies a specialist position within aspiration catheter engineering that competes directly with stent-retriever approaches. These three entities represent distinct strategic postures: integrated stroke system dominance, R&D-intensive aneurysm therapy anchoring, and differentiated mechanical thrombectomy alternatives.
| Leading Market Players |
|---|
| Stryker |
| Medtronic |
| Penumbra |
| Johnson & Johnson |
| Terumo Corporation |
| Abbott |
| Boston Scientific |
| MicroVention |
| Balt |
| Others |
Value Chain & Pricing Dynamics
Captive sourcing of platinum-tungsten alloys from South African mining consortiums anchors both the supply security and premium pricing power of coil manufacturers serving Japanese university hospitals and German comprehensive stroke networks. This backward integration into precious metal feedstocks insulates tier-one producers from spot market volatility while forcing smaller competitors toward higher-cost distributor channels.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with hospitals paying substantial markups for emergency thrombectomy catheter availability versus scheduled elective aneurysm procedure inventory. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA breakthrough designation status and EU MDR certification tier. Pricing pressure stems from hospital procurement committees unbundling previously integrated stroke system contracts. Academic medical centers exhibit lowest price sensitivity due to fellowship training requirements, while ambulatory surgical centers drive hardest bargain for carotid stenting hardware.
Supply Chain Analysis
Freight cost escalation on temperature-controlled shipments of nitinol raw stock from Taiwanese foundries to Irish manufacturing zones compresses margins on next-generation aspiration catheters. Production gravity centers on Germany, Ireland, and Puerto Rico, with the latter two hosting FDA-registered facilities serving United States stroke centers. Component dependencies include platinum-tungsten filament, shape-memory nitinol tubing, and hydrophilic polymer coatings. Single-source vulnerability concentrates in South African precious metal refining. Distribution runs through integrated delivery network contracting offices and GPO consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR recertification burden functions as a structural moat, filtering subscale manufacturers from premium device tiers and consolidating procurement leverage among compliant incumbents with rebuilt quality management systems.
For Market Incumbents: Hedge against unbundling pressure by deepening catheter engineering differentiation in aspiration systems and flow diversion technology. Stryker and Medtronic exemplify defensive positioning through stroke portfolio breadth and R&D intensity respectively. Prioritize notified body relationship investment in Berlin-Brandenburg to compress recertification timelines. For New Entrants and Emerging Players: Begin with transradial access protocol catheters for Japanese university hospitals, where PMDA Sakigake fast-track reduces regulatory capital requirements. Ambulatory surgical center direct procurement relationships for elective carotid stenting offer lowest competitive density. Target GPO bypass strategies with freestanding cardiovascular service lines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified medtech conglomerates seeking stroke system completeness. Five-to-ten year viability hinges on EU MDR technical documentation completion and post-market clinical follow-up infrastructure. Monitor notified body capacity constraints in Germany and Netherlands as inflection signal for recertification timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Rebuild | Notified body recertification in Berlin-Brandenburg filters subscale competitors from premium tiers. |
| Stroke System Contract Unbundling | Integrated delivery networks in Texas and Germany separate hardware from imaging platform procurement. |
| Transradial Access Protocol Development | Japanese university hospitals adopting radial artery puncture reduce puncture site complications and enable same-day discharge. |
| Mobile Stroke Unit Hardware Integration | German and United States deployment extends thrombectomy eligibility to 24-hour treatment windows. |
| Post-Market Clinical Follow-Up Infrastructure | EMA centralized marketing authorization demands multi-member state evidence generation for flow diverter manufacturers. |
Study Parameters
Independent corroboration across neurointerventionalist interviews, hospital procurement committee discussions, and notified body technical documentation reviews underwrites the qualitative findings. Primary fieldwork engaged endovascular surgical neuroradiology fellowship directors, GPO contracts managers, biomedical engineers, and stroke program administrators. Secondary validation drew from FDA 510(k) filings, EMA centralized marketing authorization records, hospital procurement databases, and CMS Medicare procedure code valuations. Bottom-up catheter inventory modeling triangulated against top-down stroke center certification data.
Comparable-period anchoring to historical thrombectomy procedure volume trends and aneurysm repair migration patterns from clipping to coiling established the forecast baseline. Across the analysis window, segmentation by product type, application, end user, and delivery mode generated discrete growth trajectories. CAGRs derived from procedure code expansion rates, mobile stroke unit deployment schedules, and fellowship position growth curves. Nitinol construct adoption curves and platinum-tungsten supply constraints fed industry-specific sensitivity analyses.
Underlying measurement precision varies by segment; thrombectomy catheter demand carries tighter precision than flow diverter forecasts due to established procedure code reporting. Forecasts embed assumptions around EU MDR recertification timelines, PMDA Sakigake pathway efficiency, and mobile stroke unit reimbursement calibration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Europe Smart Bed Market
Medical Devices
North America Medical Devices Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Implantable Cardiac Rhythm Management Device Market