
 Global Confocal Microscope Market | 2026-2036
Global Confocal Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Global Confocal Microscope Market Foresight
EU MDR is rebalancing the cost-of-entry calculus for confocal microscope vendors serving European clinical research sites. ZEISS Group leverages its captive optics manufacturing in Germany to absorb compliance costs without outsourcing certification steps. Nikon Corporation anchors its competitive position through sustained R&D intensity in spectral imaging modules. Leica Microsystems specializes in multiphoton configurations for live-cell neuroscience, occupying a defensible niche against broader-platform rivals.
Confocal microscopes employ point illumination and a spatial pinhole to eliminate out-of-focus light, achieving optical sectioning with sub-micron axial resolution typically below 0.5 micrometers. This architecture enables three-dimensional reconstruction of biological specimens, semiconductor wafers, and engineered materials without physical sectioning. Laser Scanning Confocal systems dominate installed base and service revenue pools across academic core facilities. Spinning Disk variants compete on imaging speed for high-throughput pharmacology screening, where temporal resolution outweighs pure spatial precision. Multiphoton configurations represent the fastest-growing product category, driven by deep-tissue neuroscience applications that demand reduced phototoxicity at infrared excitation wavelengths.
FDA 21 CFR Part 820 quality system requirements shape design controls for instruments entering diagnostic or therapeutic development workflows, while ISO 13485 certification gates access to regulated clinical research segments. EMA and notified bodies under EU MDR enforce biocompatibility and electrical safety standards that extend validation timelines for fluorescence lifetime systems. Japan's PMDA and METI coordinate standards alignment that streamlines approval for imported optical platforms. Stakeholders must monitor evolving cross-recognition agreements between FDA and PMDA, as harmonized pathways would reshape geographic prioritization for product registration investments.
Market Dynamics
NIH funding concentration in the United States is compressing vendor pricing power while EU MDR compliance costs are forcing smaller European manufacturers toward strategic exits or captive acquisition by larger optics groups.
Growth Catalysts
- Deep-tissue neuroscience:Multiphoton excitation at infrared wavelengths reduces phototoxicity during extended live-cell imaging sessions. Academic core facilities in Germany and Japan are prioritizing these configurations for brain-mapping consortia.
- FDA 21 CFR Part 820 alignment:Harmonized quality system requirements streamline design controls for instruments entering therapeutic development workflows. This reduces duplicate validation burdens for vendors serving diagnostic applications.
- Spinning disk speed advantages:Temporal resolution requirements in high-throughput pharmacology screening are displacing slower laser-scanning architectures. Contract research organizations specify these systems for kinetic assays.
Market Restraints
- Optics supply concentration:Precision objective lens manufacturing clusters in Germany and Japan, creating vulnerability to export license delays or geopolitical friction.
- EU MDR certification timelines:Extended biocompatibility and electrical safety validation for fluorescence lifetime systems delays revenue recognition for vendors serving European clinical research segments.
- Photobleaching limitations:Organic fluorophore degradation during extended imaging sessions constrains longitudinal studies, pushing researchers toward label-free alternatives that bypass confocal architectures entirely.
Strategic Opportunities
- India academic procurement:Central university grants for life sciences infrastructure remain underpenetrated by premium confocal vendors. Local distributors with service networks hold first-mover advantage.
- AI-driven image analysis convergence:Deep learning segmentation tools trained on confocal z-stacks create bundled software-hardware value propositions. Core facilities increasingly specify integrated analysis pipelines.
- Japan PMDA-METI coordination:Streamlined approval pathways for imported optical platforms reduce registration investment for foreign vendors targeting pharmaceutical R&D customers.
Industry Challenges
- Specialized service engineer scarcity:Alignment of laser sources and galvo scanners requires technicians with combined photonics and mechatronics training. Vendor training programs struggle to match retirement rates in mature markets.
- Legacy system integration friction:Research groups with fifteen-year installed bases face workflow disruption when upgrading to spectrally unmixed detection modules. Data format incompatibility complicates longitudinal study continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Confocal Microscope Market |
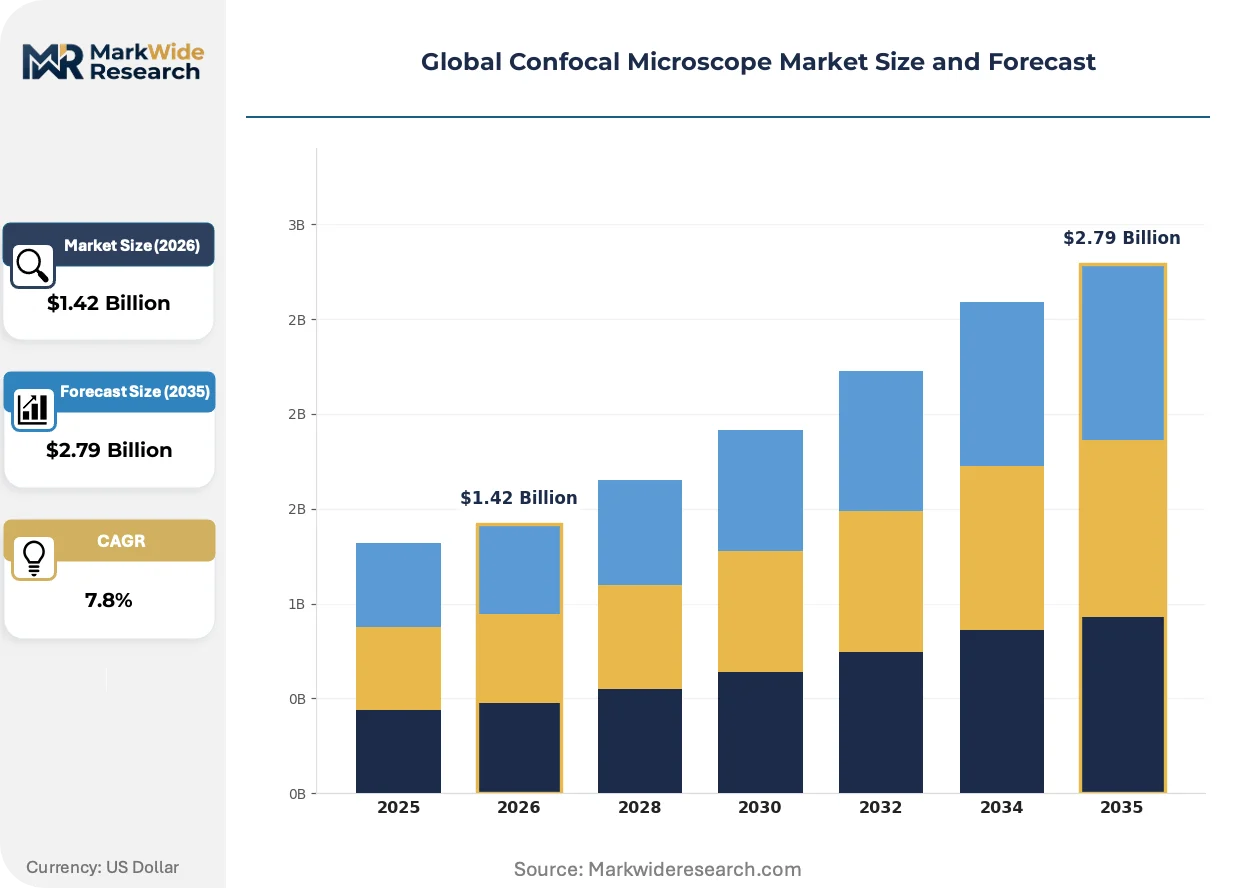
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Scanning Confocal, Spinning Disk, Programmable Array Microscopes, Multiphoton, Widefield Technology: Fluorescence Imaging, Reflectance Imaging, Fluorescence Lifetime, Spectral Imaging, 3D Reconstruction Application: Neuroscience, Material Characterization, Cell Biology, Pharmacology, Semiconductor Inspection End User: Academic Institutions, Pharmaceutical Laboratories, Research Institutes, Industrial Manufacturing, Government Agencies |
| Companies Covered | ZEISS Group, Nikon Corporation, Olympus Corporation, Leica Microsystems, Bruker Corporation, Thermo Fisher Scientific, Oxford Instruments, Thorlabs, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Confocal Microscope Market Shifts & Advancements
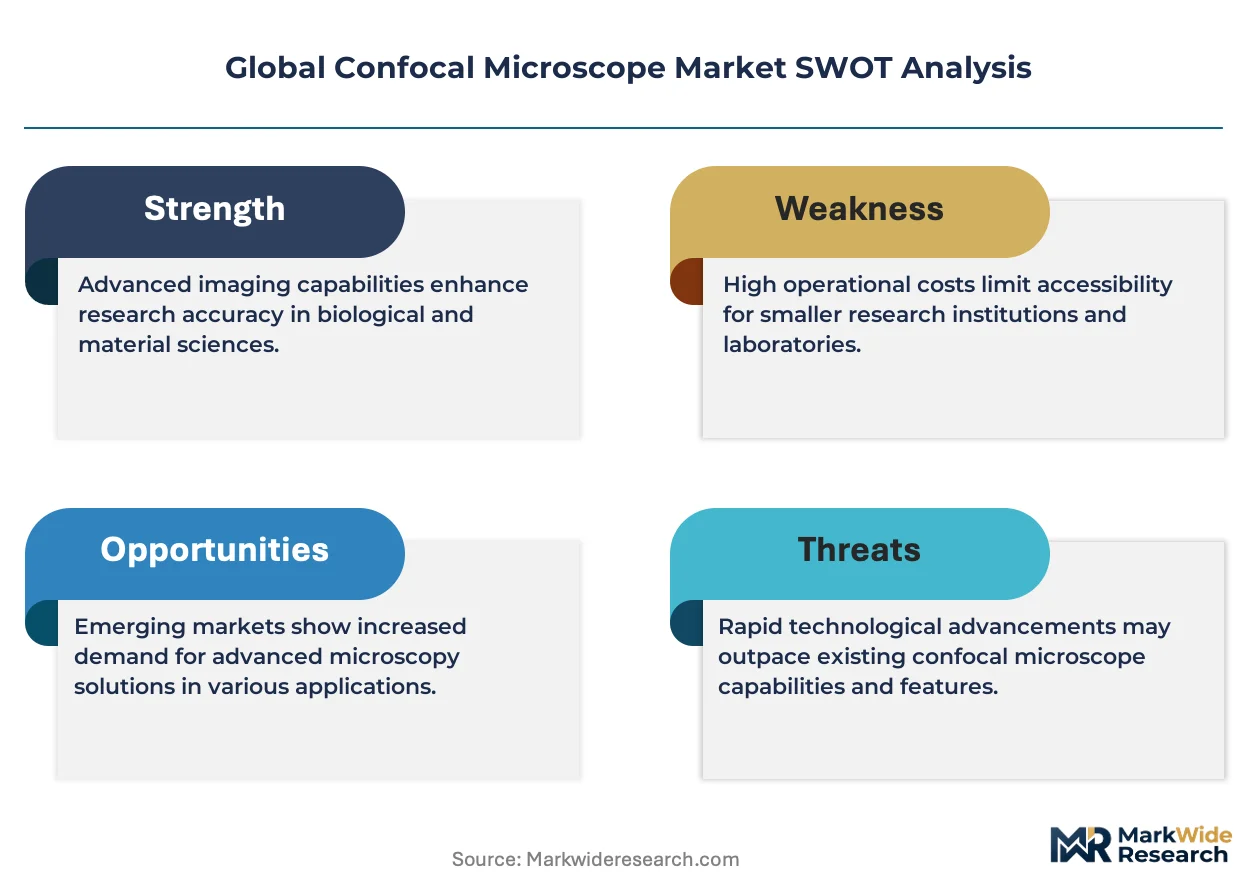
Super-resolution modalities are compressing the addressable market for conventional confocal systems while spectral detection advances and service unbundling reshape vendor economics across academic and commercial segments.
Light-sheet fluorescence microscopy is expanding into developmental biology applications previously dominated by confocal architectures. Zebrafish and organoid imaging facilities at US and German research institutes are adopting these systems for rapid volumetric acquisition. The technology is compressing demand for laser-scanning confocal units in embryology and regenerative medicine workflows.
EU MDR Article 10 technical documentation requirements are extending validation timelines for fluorescence lifetime imaging systems. Notified bodies in Germany and the Netherlands are enforcing stricter biocompatibility assessments for optical components contacting biological specimens. Vendors are responding by segregating clinical-research product lines from standard research-grade configurations to isolate compliance risk.
Core facility directors are consolidating vendor relationships around single-source service contracts that bundle preventive maintenance, laser tube replacements, and software upgrades. This behavior concentrates purchasing authority at US and UK university procurement offices. Independent service organizations are losing share as manufacturers deepen captive service penetration through multi-year institutional agreements.
Global Confocal Microscope Market Segmentation
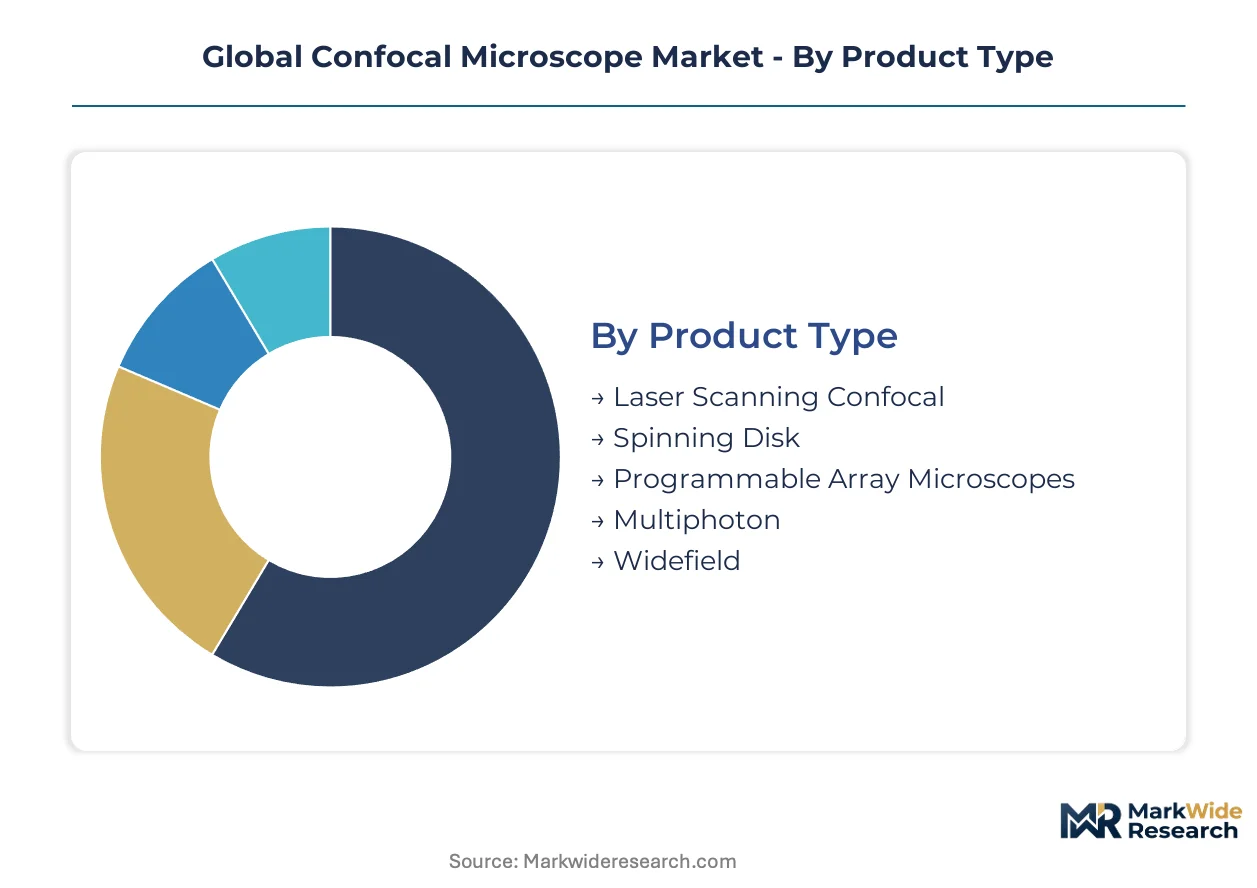
Confocal microscope procurement patterns diverge sharply across certification tiers, with clinical-research segments demanding ISO 13485 and FDA 21 CFR Part 820 compliance while standard research-grade systems face lighter regulatory burdens. Understanding these segmentation boundaries clarifies where vendor investments in validation infrastructure yield returns versus where price competition dominates.
Product Type:
FDA 21 CFR Part 820 and EU MDR compliance requirements concentrate in multiphoton and laser scanning configurations destined for therapeutic development workflows, while spinning disk and widefield variants primarily serve research-grade segments with reduced certification overhead.
- Laser Scanning Confocal:Point-scanning architecture with galvanometer mirror beam steering achieves sub-micron axial resolution through conjugate pinhole filtering. NIH-funded academic core facilities in the United States anchor installed base maintenance contracts, though photobleaching constraints push users toward faster alternatives for longitudinal studies.
- Multiphoton:Nonlinear excitation at infrared wavelengths enables deep-tissue penetration with reduced phototoxicity for live-cell neuroscience. German and Japanese brain-mapping consortia are prioritizing these systems, with METI and PMDA coordination streamlining import approvals for foreign vendors.
- Spinning Disk:Microlens-array parallelization delivers frame rates exceeding 100 fps for high-throughput pharmacology screening at contract research organizations.
- Programmable Array Microscopes:Computational optical sectioning through spatial light modulators offers software-defined flexibility without moving mechanical parts.
- Widefield:Epifluorescence architectures with deconvolution processing serve entry-level cell biology instruction and preliminary screening workflows.
Laser Scanning Confocal sits at the top of the volume ranking, with Multiphoton climbing the fastest.
Technology:
Cost tier stratification separates premium fluorescence lifetime systems requiring extended EMA validation timelines from standard fluorescence imaging configurations serving high-volume academic procurement.
- Fluorescence Imaging:Organic fluorophore excitation with spectral filtering remains the dominant signal generation modality across installed bases. German academic institutions expanding neuroscience procurement specify these systems for calcium imaging and protein localization studies.
- Spectral Imaging:Linear unmixing of emission signatures enables multi-label experiments with overlapping fluorophore spectra. Pharmaceutical R&D groups in Japan are adopting these modules for compound screening pipelines, with PMDA alignment on optical platform standards reducing registration friction.
- Fluorescence Lifetime:Time-correlated single photon counting measures excited-state decay kinetics for microenvironment sensing. EU MDR Article 10 technical documentation extends validation timelines for clinical-research deployments.
- Reflectance Imaging:Label-free contrast from refractive index variations serves semiconductor wafer inspection and materials science applications.
- 3D Reconstruction:Computational z-stack rendering enables volumetric visualization without physical sectioning for developmental biology workflows.
Fluorescence Imaging commands the largest installed base, though Spectral Imaging is gaining share fastest in premium pharmaceutical segments.
Application:
Customer type concentration varies by application maturity, with established cell biology workflows consolidating around core facility procurement while emerging neuroscience applications fragment across specialized consortia.
- Neuroscience:Deep-tissue functional imaging and connectomics mapping drive demand for infrared excitation capabilities. German Max Planck Institutes and Japanese RIKEN centers are expanding fluorescence imaging infrastructure for brain initiative programs.
- Cell Biology:Subcellular organelle dynamics and protein trafficking studies constitute the foundational application for confocal architectures. United States research universities with NIH funding support represent the core revenue pool for service contracts and laser tube replacements.
- Pharmacology:High-content screening and kinetic assay development prioritize temporal resolution over pure spatial precision. Contract research organizations specify spinning disk configurations for compound library evaluation.
- Material Characterization:Surface topography and defect analysis in engineered materials and thin films employs reflectance modalities.
- Semiconductor Inspection:Wafer-level defect detection and metrology for advanced node manufacturing requires specialized objective lenses and vibration isolation.
Cell Biology retains the highest cumulative unit volume, with Neuroscience showing the steepest expansion trajectory in multiphoton configurations.
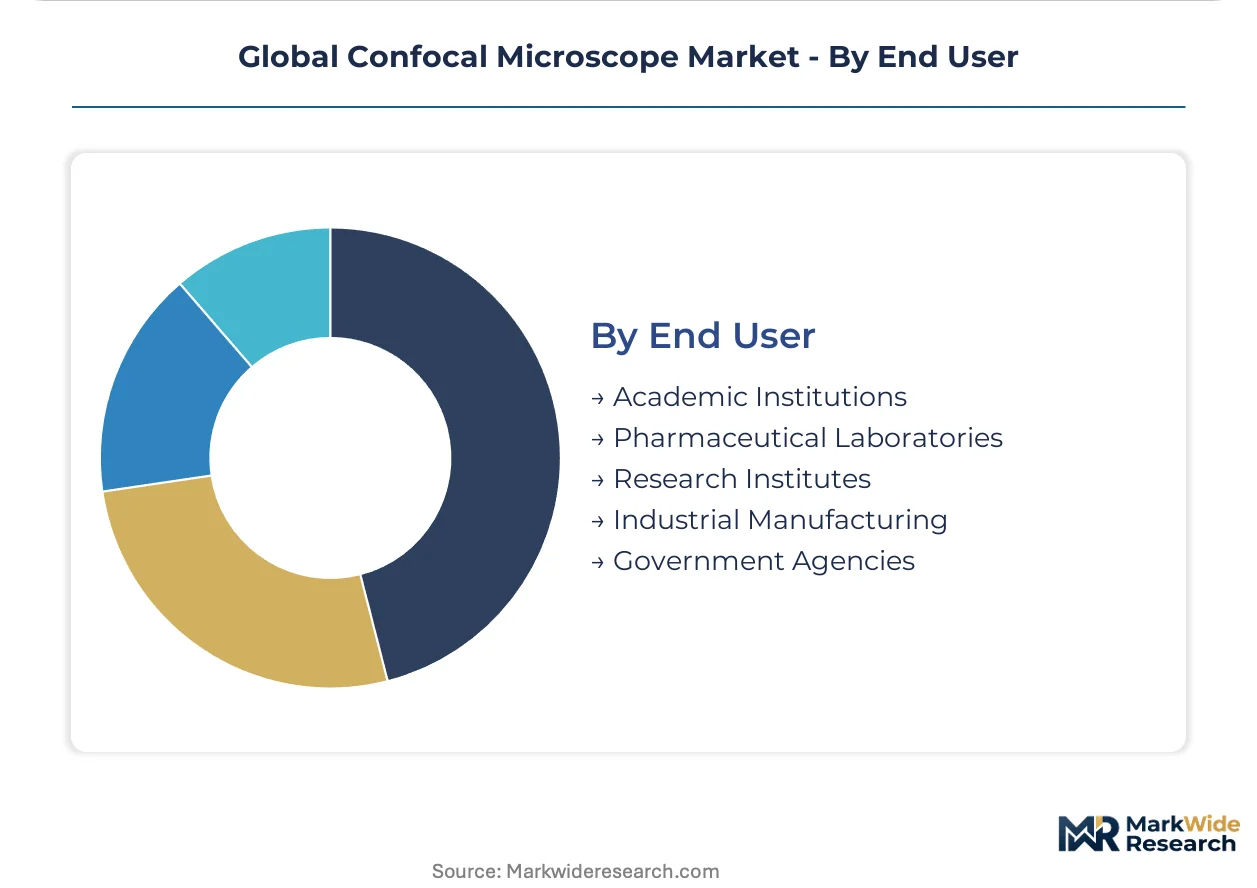
End User:
Geographic procurement concentration clusters in United States academic institutions and German research organizations, with emerging demand from Indian central university grants creating new competitive entry points.
- Academic Institutions:Core facility directors consolidate vendor relationships around bundled service contracts covering preventive maintenance and software upgrades. Procurement authority concentrates at US and UK university offices, with multi-year institutional agreements displacing independent service organizations.
- Pharmaceutical Laboratories:Therapeutic development workflows demand FDA 21 CFR Part 820 quality system alignment and ISO 13485 certification. EU MDR compliance costs are forcing strategic consolidation in vendor selection for European clinical research sites.
- Research Institutes:Government-funded neuroscience and materials science programs in Germany and Japan drive specialized multiphoton and spectral imaging procurement.
- Industrial Manufacturing:Semiconductor and advanced materials producers require reflectance imaging for quality control and failure analysis.
- Government Agencies:National laboratory and regulatory research programs support standards development and reference methodology validation.
Academic Institutions dominate cumulative shipments, with Pharmaceutical Laboratories expanding most quickly as diagnostic and therapeutic development pipelines deepen confocal integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Confocal microscopy originated from collaborative optics research in Germany during the 1950s, with the first practical laser-scanning systems commercialized through partnerships between academic laboratories and precision instrument manufacturers in Jena and Oberkochen. This German foundation established design principles and manufacturing standards that continue to shape procurement patterns across major research economies today.
United States
NIH funding channels concentrate at major research universities in Massachusetts, California, and Maryland, driving service contract consolidation and laser tube replacement revenue pools. FDA 21 CFR Part 820 quality system requirements shape design controls for instruments entering diagnostic workflows. The Boston-Cambridge corridor anchors demand for multiphoton configurations in neuroscience consortia.
Germany
Max Planck Institutes and Helmholtz Centers expand fluorescence imaging infrastructure for brain-mapping initiatives, prioritizing spectral unmixing capabilities. EU MDR Article 10 technical documentation extends validation timelines for clinical-research deployments. The Jena-Oberkochen optical cluster maintains captive manufacturing of precision objective lenses and galvo scanner assemblies.
Japan
RIKEN Brain Science Institute and university medical schools drive procurement of deep-tissue imaging systems with reduced phototoxicity specifications. METI and PMDA coordination streamlines approval pathways for imported optical platforms. The Kansai region around Osaka concentrates pharmaceutical R&D customers specifying integrated analysis pipelines.
India
Central university grants for life sciences infrastructure remain underpenetrated by premium confocal vendors, creating first-mover opportunities for distributors with service networks. The national pharmaceutical regulator maintains alignment with ISO standards for laboratory equipment. Bangalore and Hyderabad clusters show emerging demand from biotech startups and contract research organizations.
United Kingdom
Research councils channel funding toward core facility upgrades at Oxford, Cambridge, and London institutions, consolidating vendor relationships around bundled service contracts. MHRA enforcement of EU MDR transitional provisions affects fluorescence lifetime system registrations. The Cambridge-London corridor leads adoption of AI-driven image analysis convergence.
Global Confocal Microscope Market Competitive Landscape
The competitive structure tilts toward integrated optics groups with captive manufacturing capabilities. Vendor economics stratify across three tiers: multinational conglomerates with full vertical control, mid-cap specialists with regional service density, and component suppliers seeking downstream integration. Consolidation pressure intensifies as EU MDR compliance costs force smaller European manufacturers toward strategic exits or acquisition by larger groups. Dominant competitive moves include multi-year institutional service contracts displacing independent service organizations, and geographic expansion through distributor partnerships in underpenetrated academic markets.
Within the integrated optics tier, ZEISS Group and Nikon Corporation represent contrasting geographic anchors for competitive positioning. ZEISS Group exemplifies the German model of captive optics manufacturing absorbing regulatory compliance costs without outsourcing certification steps. Nikon Corporation occupies a position shaped by sustained R&D coordination between Japanese precision engineering and spectral imaging module development. Leica Microsystems sits within the specialization archetype, with multiphoton configurations for live-cell neuroscience creating defensible positioning against broader-platform rivals.
| Leading Market Players |
|---|
| ZEISS Group |
| Nikon Corporation |
| Olympus Corporation |
| Leica Microsystems |
| Bruker Corporation |
| Thermo Fisher Scientific |
| Oxford Instruments |
| Thorlabs |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Family-owned German optics houses anchor precision manufacturing clusters in Jena and Oberkochen, translating captive production of objective lenses and galvo scanners into pricing discipline that resists commoditization pressure from Asian contract manufacturers. Their ownership structure insulates long-term R&D cycles from quarterly margin compression, reinforcing premium positioning against PE-rolled competitors seeking exit multiples through service unbundling.
Pricing Analysis
Three-tier pricing structure across clinical-research, standard-research, and instructional tiers dominates vendor quotations, with FDA 21 CFR Part 820 and EU MDR certification grades creating the primary price differentiation wedge. NIH-funded academic core facilities in the United States exhibit acute price sensitivity on laser tube replacements and service contracts, while pharmaceutical laboratories purchasing multiphoton configurations for therapeutic development workflows absorb premium positioning with limited negotiation leverage. Pricing pressure stems from EU MDR compliance cost absorption by ZEISS Group and Nikon Corporation, compressing margin headroom for mid-cap specialists lacking captive certification infrastructure.
Supply Chain Analysis
ISO 13485 and FDA quality system certification gates access to clinical-research segments, concentrating qualified component supply in Germany and Japan where precision objective lens manufacturing clusters around Zeiss, Nikon, and Olympus captive facilities. German glassworks and Japanese ceramic suppliers provide specialized optical substrates and piezoelectric positioners that feed galvo scanner assembly lines. Single-source vulnerability runs through precision lens grinding capacity concentrated in Thuringia, with distribution through authorized dealer networks extending into Indian and UK academic markets where local service density determines procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 10 technical documentation requirements compound demand for validated fluorescence lifetime systems, creating sustained procurement cycles as European clinical research sites upgrade to compliant configurations. This regulatory milestone extends replacement timelines and deepens vendor-customer contractual relationships across the analysis window.
For Market Incumbents: Acquire regional service organizations with installed base relationships in underpenetrated academic markets. Nikon Corporation and ZEISS Group should consolidate independent service providers in India and the United Kingdom before mid-cap specialists establish channel control. Light-sheet fluorescence microscopy substitution in developmental biology workflows threatens laser-scanning confocal replacement demand; counter through spectral imaging module upgrades and AI-driven image analysis bundling that deepens platform stickiness. For New Entrants and Emerging Players: PMDA-METI coordination in Japan opens a window for foreign vendors targeting pharmaceutical R&D customers with streamlined import approvals. Prioritize spinning disk configurations for contract research organizations in the Kansai region, where temporal resolution requirements in high-throughput pharmacology screening outpace incumbent response times. Partner with local distributors holding central university grant relationships in India rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialists with regional service density but lacking EU MDR certification infrastructure. Long-term viability over the next decade hinges on backward integration into precision optics manufacturing or captive acquisition by conglomerates with existing compliance frameworks. Monitor cross-recognition agreement progress between FDA and PMDA as the signal indicating geographic prioritization shifts for product registration investments.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Institutional Service Contract Consolidation | Core facility directors at US and UK universities concentrate purchasing authority through bundled preventive maintenance and software upgrade agreements. |
| EU MDR Clinical-Research Product Line Segregation | Vendors isolate compliance risk by separating validated fluorescence lifetime configurations from standard research-grade systems. |
| Spectral Imaging Module R&D Expansion | Pharmaceutical R&D groups in Japan adopt linear unmixing capabilities for compound screening pipelines with PMDA-aligned registration pathways. |
| AI-Driven Image Analysis Pipeline Integration | Deep learning segmentation tools trained on confocal z-stacks create bundled software-hardware value propositions for core facility procurement. |
| Indian Distributor Partnership Development | Local service networks capture first-mover advantage in central university grants for life sciences infrastructure. |
Research Methodology
Direct dialogue with core facility directors, biomedical engineers, pharmaceutical R&D procurement managers, and GPO contracts managers grounded qualitative assessment of vendor selection criteria and service contract structures. Secondary validation drew from FDA 510(k) filings, EMA medical device registrations, NIH RePORTER funding databases, and university procurement office contract disclosures. Bottom-up and top-down triangulation reconciled unit shipment estimates with revenue pools across academic and pharmaceutical end-use segments.
Bottom-up modeling built from country-level academic funding flows and pharmaceutical R&D capex disclosures, while top-down analysis cross-checked against installed base maintenance contract values and laser tube replacement revenue pools. Segmentation dimensions spanned product type, technology tier, application workflow, and end-user procurement authority. CAGRs were derived from regression analysis of historical NIH funding trajectories, EU MDR implementation timelines, and multiphoton configuration adoption curves in brain-mapping consortia.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of FDA-PMDA harmonization acceleration or export license friction affecting German and Japanese optical component shipments. A model refresh is warranted upon material change in NIH appropriations levels or EU MDR notified body capacity constraints affecting fluorescence lifetime system validation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Global Digital Subtraction Angiography Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Australia Magnetic Resonance Imaging Market
Medical Imaging
Urology Imaging Systems Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Australia Mammography Market
Medical Imaging
AI Radiology Worklist Orchestration Market