
 Phenylacetyl Chloride Market | 2026-2036
Phenylacetyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Phenylacetyl Chloride Market Insights
REACH is hardening the cost-of-entry calculus for European phenylacetyl chloride suppliers, forcing registration dossiers and substance evaluation costs onto smaller manufacturers. CABB Group GmbH leverages its integrated chlorination infrastructure to sustain margin resilience under these compliance burdens. Tokyo Chemical Industry Co., Ltd. anchors the high-purity reagent segment through exacting quality protocols that pharmaceutical clients demand.
Phenylacetyl chloride is an acyl chloride derivative of phenylacetic acid, typically manufactured via thionyl chloride or phosgene-mediated chlorination of the parent acid, serving primarily as an acylating agent in pharmaceutical and agrochemical synthesis. Pharmaceutical Grade material commands the dominant value share due to stringent impurity ceilings mandated by pharmacopeial standards, while Industrial Grade volumes expand fastest in dye intermediate applications where specification tolerance widens. The Application dimension shows Fine Chemicals capturing deepening margin pools as custom synthesis contracts proliferate.
EPA oversight in the United States and REACH in Europe jointly constrain manufacturing discharge profiles and product purity thresholds, redirecting capital toward environmental controls and analytical verification. China's MEE enforces parallel emissions standards that reshape export eligibility for domestic producers. Stakeholders must weigh regulatory escalation trajectories against geographic sourcing diversification when committing to long-term supply arrangements.
Market Dynamics
Pharmaceutical contract manufacturing organizations are consolidating acyl chloride procurement around fewer qualified suppliers, compressing vendor lists and amplifying volume concentration among integrated chlorination specialists capable of meeting pharmacopeial impurity thresholds.
Growth Catalysts
- REACH substance evaluation:European ECHA registration requirements for acyl chlorides are filtering out marginal producers and concentrating volume among compliant manufacturers with established dossiers.
- Active pharmaceutical ingredient synthesis:Antibiotic and central nervous system drug pipelines are pulling phenylacetyl chloride demand upward as acylation chemistry remains irreplaceable for specific molecular architectures.
- Thionyl chloride process optimization:Continuous-flow chlorination systems are reducing solvent waste generation and enabling smaller footprint production facilities near pharmaceutical clusters.
Market Restraints
- Phosgene feedstock volatility:Security restrictions on phosgene transport and storage are elevating input costs and limiting new entrant capacity in regions without integrated chlor-alkali infrastructure.
- China supply concentration:Jiangsu and Shandong provinces host disproportionate phenylacetyl chloride capacity, creating geographic risk exposure for buyers dependent on single-origin sourcing.
- Alternative acylating agents:Acid anhydrides and activated esters are substituting for acyl chlorides in certain agrochemical applications where moisture sensitivity is less critical.
Strategic Opportunities
- India formulation expansion:Domestic pharmaceutical finished-dose manufacturing under PLI scheme incentives is pulling import demand for high-purity acyl chlorides upward.
- Continuous manufacturing adoption:FDA guidance on real-time release testing is expanding into acylation chemistry, rewarding suppliers with process analytical technology capabilities.
- Specialty agrochemical intermediates:Fungicide and herbicide pipelines are opening new volume channels for industrial-grade material with relaxed specification tolerances.
Industry Challenges
- Phosgene handling certification:Operator licensing requirements and emergency response infrastructure are extending commissioning timelines for new production assets by 12-18 months.
- Analytical method transfer:Pharmacopeial impurity profiling differences between USP, EP, and ChP standards are forcing duplicate validation studies for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenylacetyl Chloride Market |
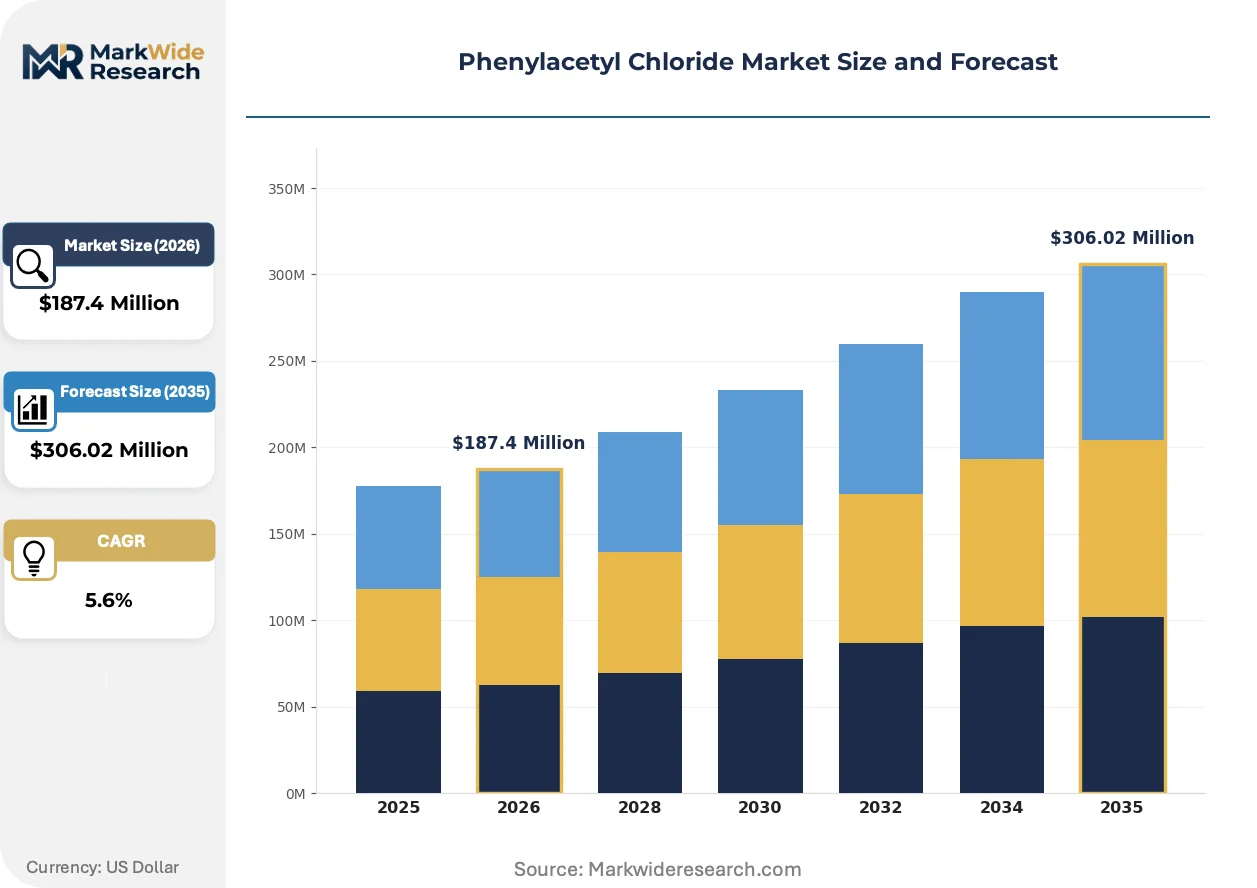
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $306.02 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Grade, Pharmaceutical Grade, Industrial Grade, Specialty Grade Application: Pharmaceuticals, Agrochemicals, Dyes, Fine Chemicals End User: Pharmacies, Chemical Manufacturers, Research Laboratories, Academic Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Tokyo Chemical Industry Co., Ltd., CABB Group GmbH, Daicel Corporation, ALTIVIA Petrochemicals Corporation, Shiva Pharmachem Ltd, Transpek Industry Limited, Triveni Chemicals, Taixing Shenlong Chemical Co., Ltd., Hefei TNJ Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenylacetyl Chloride Market Trends and Innovations
Acyl chloride manufacturing is bifurcating between pharmaceutical-grade precision and industrial-scale commodity production, with technology investments diverging accordingly. This split is reshaping supplier specialization and capital allocation patterns across the value chain.
Continuous-flow chlorination technology is expanding into phenylacetyl chloride production as manufacturers seek to contain phosgene inventory and enable real-time monitoring. Pharmaceutical contract manufacturers are prioritizing suppliers with flow chemistry capabilities for antibiotic intermediate programs. This technology is expanding into smaller-batch custom synthesis, compressing minimum order quantities and enabling just-in-time delivery models for clinical-stage drug candidates.
EPA New Chemicals Program scrutiny under TSCA Section 5 is tightening pre-manufacture notification requirements for acyl chloride derivatives with novel substituents. Industrial chemical producers are front-loading toxicological data generation to avoid review delays. Agrochemical intermediate suppliers are most affected, responding by restricting product portfolios to established chemical entities with existing SNUR determinations.
Buyer consolidation among top-ten pharmaceutical manufacturers is compressing supplier qualification cycles and unbundling technical service from material pricing. Direct procurement relationships are displacing distributor intermediaries for high-volume acyl chloride categories. This pattern is most visible in North American and European markets where merger-driven procurement integration has centralized chemical buying authority.
Phenylacetyl Chloride Market Segmentation
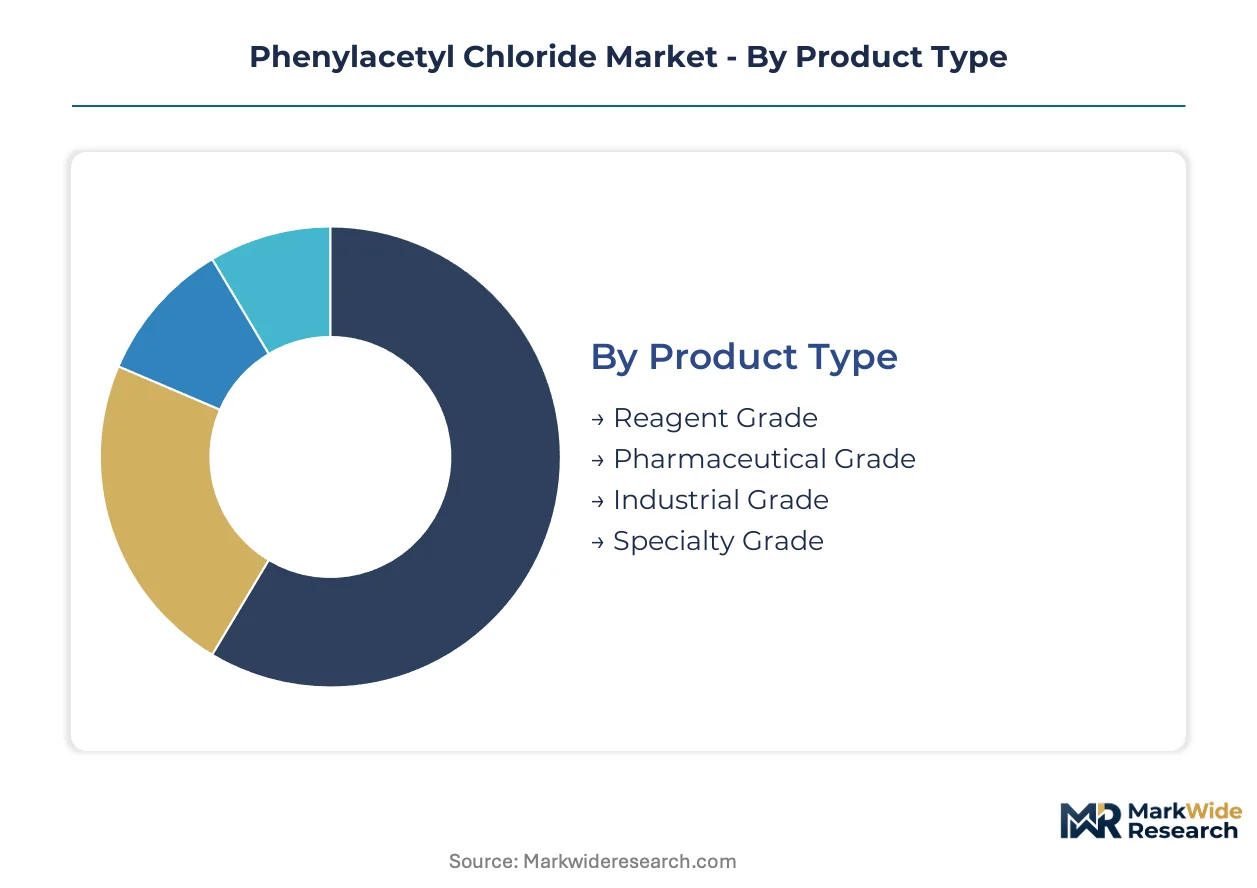
Pharmaceutical manufacturers distinguish procurement tiers through impurity thresholds and pharmacopeial compliance, while agrochemical buyers prioritize cost efficiency over specification stringency. These divergent value equations fragment supplier strategies across purity grades and application verticals.
Product Type:
Buyers in this category separate by regulatory burden tolerance and end-use liability exposure.
- Pharmaceutical Grade:Material meets USP, EP, and ChP monograph specifications with sub-ppm impurity ceilings for heavy metals and residual solvents. FDA and EMA inspections of active pharmaceutical ingredient facilities enforce batch-level certificate of analysis requirements that elevate procurement costs for antibiotic and central nervous system drug manufacturers.
- Industrial Grade:Specifications accommodate wider moisture content and acid chloride variation for dye intermediate and bulk agrochemical synthesis. Shandong and Jiangsu province producers dominate export supply, with buyers in Indian dye houses and Brazilian agrochemical formulation plants absorbing specification trade-offs for freight savings.
- Reagent Grade:Analytical purity standards for laboratory-scale acylation reactions in academic and contract research settings.
- Specialty Grade:Custom-synthesized variants with substituted phenyl rings for proprietary pharmaceutical pipelines under exclusive supply agreements.
Pharmaceutical Grade leads volumes today; Industrial Grade is gaining share fastest.
Application:
Volume concentration tracks patent cliff timing and generic drug manufacturing migration patterns.
- Pharmaceuticals:Acylation chemistry for penicillin derivatives and CNS-targeting small molecules consumes the highest-purity material. Indian formulation expansion under PLI scheme incentives is pulling import volumes upward as domestic manufacturers backward-integrate into intermediate synthesis.
- Agrochemicals:Fungicide and herbicide acylation employs lower-specification material where moisture sensitivity is manageable. Brazilian ANVISA registration pathways and EPA tolerances for pesticide intermediates are opening volume channels with relaxed analytical burdens.
- Dyes:Azo and anthraquinone intermediate synthesis absorbs commodity-grade phenylacetyl chloride from Chinese bulk producers.
- Fine Chemicals:Custom synthesis contracts for clinical-stage candidates command premium pricing through just-in-time delivery and dedicated batch protocols.
Pharmaceuticals anchors revenue concentration; Fine Chemicals shows the steepest expansion trajectory.
End User:
Procurement scale and technical service requirements stratify this category sharply.
- Chemical Manufacturers:Integrated chlor-alkali operators and acyl chloride specialists with captive phosgene infrastructure supply bulk pharmaceutical and agrochemical producers. REACH registration dossiers and EPA TSCA compliance separate qualified vendors from distributor-dependent buyers.
- Research Laboratories:Contract research organizations and custom synthesis houses purchase kilogram-scale quantities with demanding specification documentation for regulatory submission packages.
- Pharmacies:Compounding operations in regulated markets require traceable supply chains for extemporaneous preparation of specialized formulations.
- Academic Institutions:University chemistry departments source through authorized distributors with institutional pricing agreements and hazardous material handling support.
Chemical Manufacturers dominate procurement tonnage; Research Laboratories command the highest per-kilogram margins.
Distribution Channel:
Channel selection reflects buyer technical sophistication and volume scale.
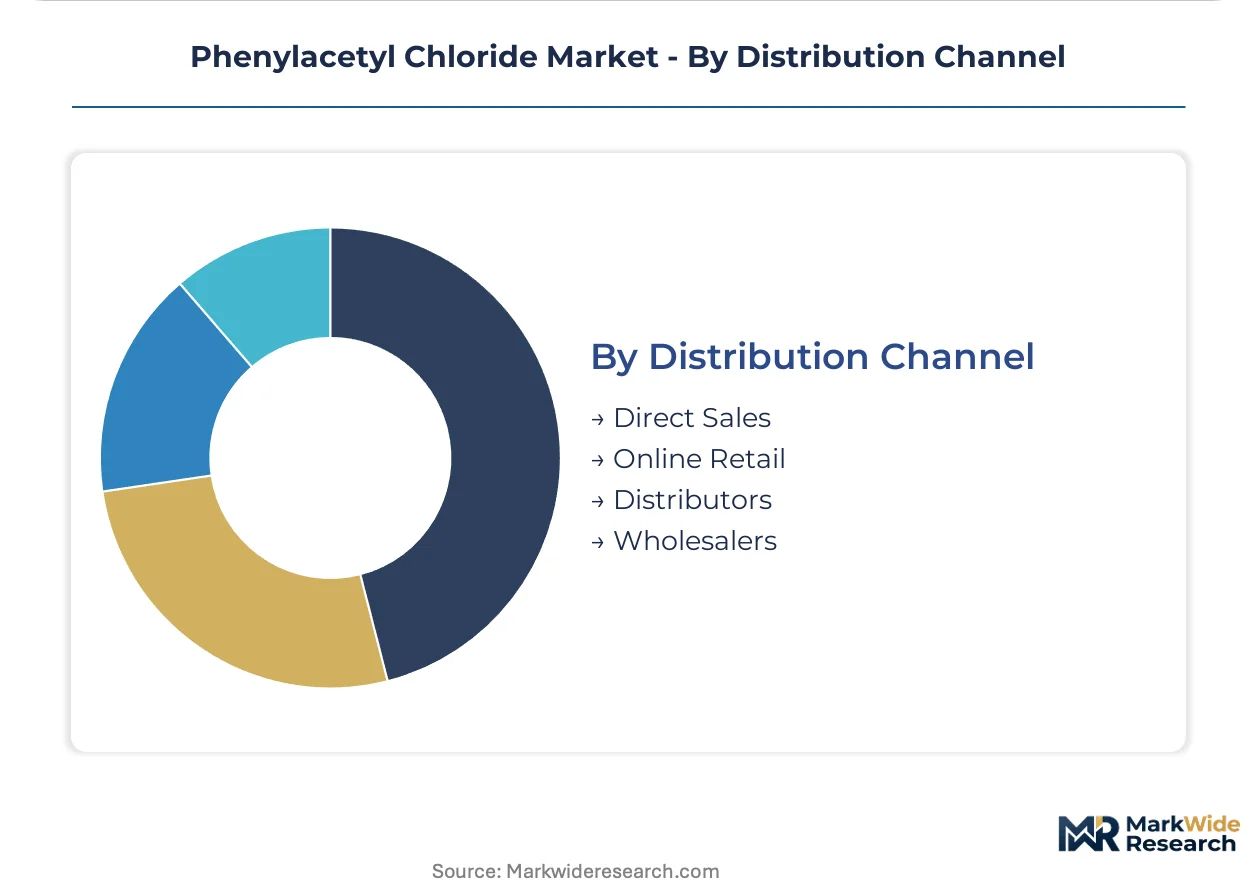
- Direct Sales:Top-ten pharmaceutical manufacturers negotiate frame contracts with integrated producers, unbundling technical service from material pricing. CABB Group and Tokyo Chemical Industry anchor this channel through qualified supplier status and process analytical technology capabilities.
- Distributors:Regional chemical distributors manage inventory and customs clearance for mid-tier buyers lacking import licensing infrastructure. Indian and Southeast Asian markets rely heavily on distributor networks for fragmented agrochemical and dye intermediate demand.
- Online Retail:E-commerce platforms serve research-scale procurement with credit card purchasing and rapid fulfillment for academic and small commercial laboratories.
- Wholesalers:Bulk commodity aggregators supply industrial-grade material to price-sensitive dye and agrochemical manufacturers with minimal technical service requirements.
Direct Sales captures the largest revenue pool; Online Retail is climbing the fastest as procurement digitization penetrates research segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemists and process engineers cluster around chlor-alkali corridors and pharmaceutical manufacturing hubs. Talent density shapes where phenylacetyl chloride production and procurement concentrate.
United States
Antibiotic intermediate demand from Tennessee and New Jersey pharmaceutical clusters pulls high-purity acyl chloride volumes upward. EPA TSCA Section 5 pre-manufacture notifications constrain novel derivative introductions. Gulf Coast chlor-alkali infrastructure near Houston supplies feedstock chlorine to acylation specialists serving CNS drug manufacturers.
Germany
Integrated chemical parks in Ludwigshafen and Leverkusen sustain captive phenylacetyl chloride production for penicillin derivative synthesis. REACH registration dossiers and ECHA substance evaluation filter marginal producers from the qualified supplier pool. CABB Group leverages Rhineland-Palatinate chlorination infrastructure to maintain margin resilience under compliance burdens.
China
Jiangsu and Shandong province dye intermediate manufacturers absorb industrial-grade volumes at specification trade-offs for freight savings. MEE emissions standards reshape export eligibility for domestic producers. Taixing Shenlong Chemical anchors supply capacity in Jiangsu near Yangtze River Delta pharmaceutical formulation clusters.
India
PLI scheme incentives for domestic pharmaceutical finished-dose manufacturing pull import demand for high-purity acyl chlorides upward. CDSCO active pharmaceutical ingredient facility inspections enforce batch-level certificate of analysis requirements. Gujarat and Maharashtra formulation plants backward-integrate into intermediate synthesis, compressing lead times for antibiotic producers.
Japan
Specialty reagent demand from Tokyo and Osaka contract research organizations commands premium pricing through exacting quality protocols. PMDA pharmaceutical manufacturing standards enforce pharmacopeial impurity profiling that separates qualified vendors. Tokyo Chemical Industry anchors the high-purity segment through dedicated batch protocols for clinical-stage candidates.
Phenylacetyl Chloride Market Competitive Landscape
The competitive structure tilts toward integrated chlorination specialists capable of sustaining pharmacopeial compliance. Three to five qualified suppliers capture disproportionate volume concentration as pharmaceutical contract manufacturing organizations compress vendor lists. Two archetypes dominate: integrated chemical conglomerates with captive phosgene infrastructure, and precision reagent specialists serving research-scale demand. Capacity expansion near pharmaceutical clusters and strategic partnerships for continuous-flow technology licensing represent the dominant competitive moves.
Among Germany-based integrated producers, CABB Group GmbH occupies a position exemplifying chlor-alkali-backed acyl chloride supply. Japanese precision chemical manufacturers, represented by Tokyo Chemical Industry Co., Ltd., anchor the high-purity reagent tier. Chinese bulk producers, with Taixing Shenlong Chemical Co., Ltd. representing the archetype, concentrate industrial-grade supply capacity. These three entities collectively illustrate the geographic and tier-based fragmentation shaping procurement strategies.
| Leading Market Players |
|---|
| Tokyo Chemical Industry Co., Ltd. |
| CABB Group GmbH |
| Daicel Corporation |
| ALTIVIA Petrochemicals Corporation |
| Shiva Pharmachem Ltd |
| Transpek Industry Limited |
| Triveni Chemicals |
| Taixing Shenlong Chemical Co., Ltd. |
| Hefei TNJ Chemical Industry Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
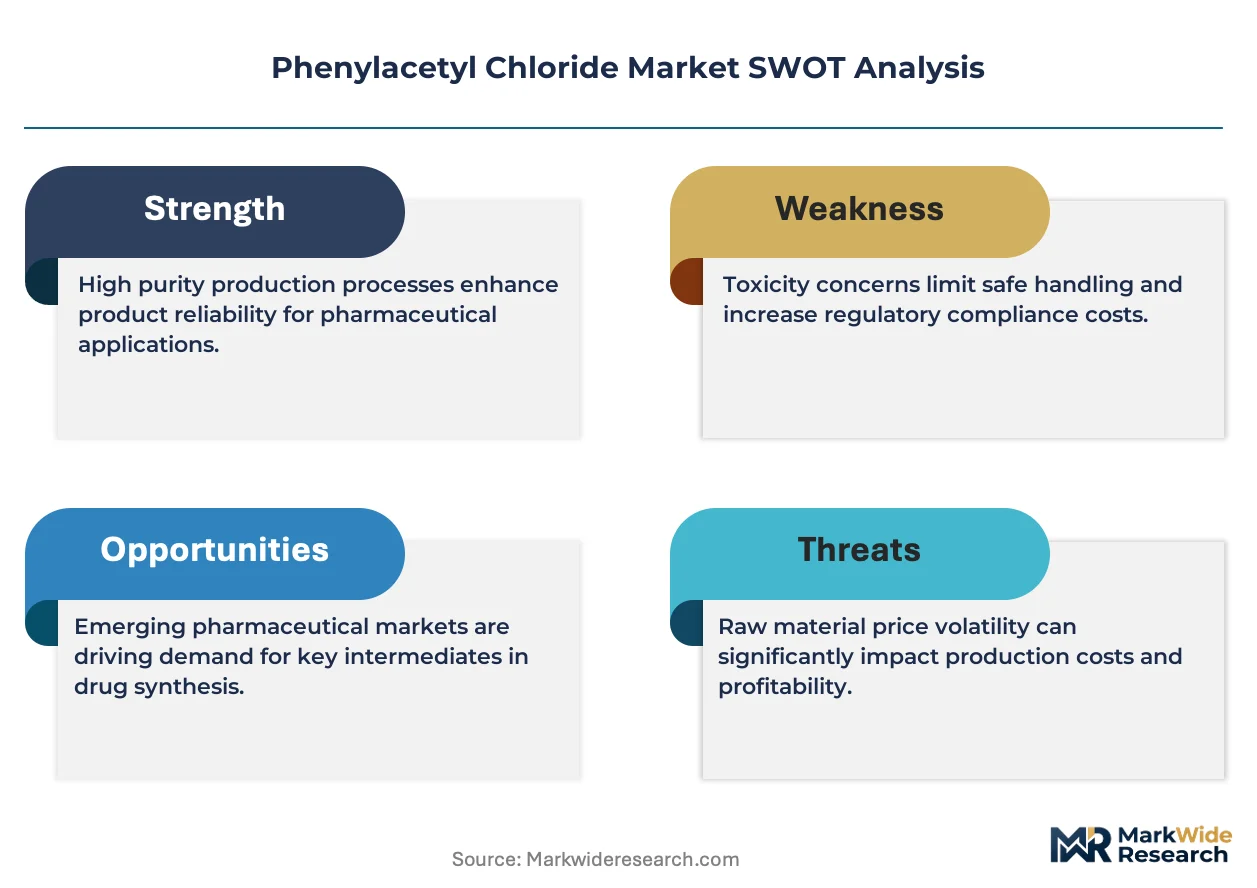
REACH substance evaluation requirements gate qualified supply access and premium-tier pricing power for European pharmaceutical-grade phenylacetyl chloride. Compliance expenditures on registration dossiers and analytical verification separate compliant integrated producers from distributor-dependent buyers absorbing specification trade-offs for freight savings.
Pricing Analysis
Bundled technical service and unbundled material pricing splits procurement relationships between top-ten pharmaceutical manufacturers and mid-tier buyers. Three-tier pricing structure across pharmaceutical, industrial, and reagent grades reflects impurity ceiling differentials and pharmacopeial certification burdens. Cost compression in industrial-grade tiers intensifies because Shandong and Jiangsu province producers compete on freight-adjusted delivered pricing. Dye intermediate and bulk agrochemical manufacturers exhibit highest price sensitivity; antibiotic and central nervous system drug manufacturers prioritize batch-level certificate of analysis compliance over unit economics.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Taixing, and Houston anchor hub-and-spoke patterns for pharmaceutical-grade material serving antibiotic intermediate clusters. Supply concentrates in China, Germany, and the United States, with Jiangsu and Shandong provinces hosting disproportionate industrial-grade capacity. Phosgene feedstock and thionyl chloride reagent dependencies tether production economics to chlor-alkali infrastructure availability. Single-source vulnerability from China supply concentration elevates geographic risk exposure for buyers lacking qualified secondary sourcing. Distribution runs through direct sales channels for high-volume pharmaceutical contracts and regional distributors for fragmented agrochemical demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phenylacetyl chloride functions as a stable compounder anchored by irreplaceable acylation chemistry in antibiotic and central nervous system drug pipelines. Active pharmaceutical ingredient synthesis demand sustains volume growth regardless of macroeconomic cyclicality.
For Market Incumbents: Extend qualified supplier status through continuous-flow chlorination technology licensing to pharmaceutical contract manufacturing organizations. Integrate backward into captive phosgene infrastructure near Gulf Coast and Rhineland-Palatinate chlor-alkali corridors to defend margin position against feedstock volatility. Prioritize process analytical technology capabilities that satisfy FDA real-time release testing guidance for antibiotic intermediate programs.
For New Entrants and Emerging Players: Enter via specialty reagent-grade supply to Tokyo and Osaka contract research organizations where exacting quality protocols command premium pricing. Target Indian formulation expansion under PLI scheme incentives as the most penetrable geography for high-purity acyl chloride import demand. Pursue exclusive supply agreements for proprietary substituted phenyl ring variants in clinical-stage candidate pipelines.
For Investors and Strategic Acquirers: Roll-up economics work for precision reagent specialists because pharmacopeial impurity profiling differences between USP, EP, and ChP standards force duplicate validation studies that marginal producers cannot sustain. The five-to-ten year viability window favors acquisition of integrated chlorination assets with established REACH dossiers. Watch ECHA substance evaluation timelines as the inflection indicator for qualified supplier pool contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Technology Licensing | Pharmaceutical contract manufacturers prioritize suppliers with flow chemistry capabilities for antibiotic programs. |
| Backward Integration into Phosgene Infrastructure | Captive chlor-alkali supply insulates margin resilience against security restrictions on transport and storage. |
| REACH Registration Dossier Investment | ECHA substance evaluation filters marginal producers and concentrates volume among compliant manufacturers. |
| India PLI Scheme Alignment | Domestic pharmaceutical finished-dose manufacturing pulls import demand for high-purity acyl chlorides upward. |
| Process Analytical Technology Deployment | FDA guidance on real-time release testing rewards suppliers with PAT capabilities in acylation chemistry. |
Research Methodology
Multiple input streams — plant manager interviews at chlor-alkali facilities, procurement lead discussions at downstream pharmaceutical manufacturers, and technical R&D director consultations — were reconciled against customs and trade data, Cefic industry reports, and SEC filings. Bottom-up volume estimates from production capacity assessments were triangulated with top-down demand aggregation across antibiotic, agrochemical, and dye intermediate applications.
Historical shipment patterns were cross-referenced against panel input from distribution channel partners to build the analytical framework across the analysis window. Segmentation dimensions modeled include grade tier, end-use industry, and regional production hub. CAGRs were derived from slope analysis of normalized volume trajectories, incorporating phosgene feedstock availability and pharmacopeial standard evolution as industry-specific forecast inputs.
Inputs from ECHA registration databases and FDA facility inspection records were available through the study window; gaps in real-time production data from Chinese provincial environmental disclosures introduce uncertainty bands around capacity utilization assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Organoclay Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Sheet Moulding Compound (SMC) Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Chromium Phosphate Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Potassium Derivatives Market