
 Opacifiers Market | 2026-2036
Opacifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Opacifiers Market Analysis
China is narrowing the cost gap between sulfate and chloride-route titanium dioxide as new chloride capacity comes online in Shandong and Sichuan provinces. Tronox Holdings plc leverages vertical integration from mineral sands to pigment to sustain margin stability across feedstock cycles. The Chemours Company anchors North American supply through chloride-process specialization at its Mississippi and Tennessee sites. KRONOS Worldwide, Inc. competes in European industrial coatings through controlled particle-size distribution technology.
Opacifiers are functional additives that scatter light through refractive index mismatch with a surrounding matrix, typically achieving hiding power measured in contrast ratio or scattering coefficients above specific thresholds depending on particle diameter and volume concentration. Titanium dioxide dominates product type volume due to its refractive index of 2.7, though barium sulfate occupies niche pharmaceutical and food-grade applications where inertness outweighs opacity efficiency. Industrial grade leads grade segmentation by tonnage, while cosmetic grade commands premium positioning as mineral sunscreen formulations displace organic UV filters under ECHA scrutiny.
EPA oversight of titanium dioxide nanoparticle classification and REACH registration requirements for nanoforms reshape product liability and customer qualification protocols in the United States and European Union. China's MEE enforces emission caps on sulfate-process acid waste that elevate environmental compliance costs for domestic producers. India's BIS certification for food-grade additives tightens import substitution pathways. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration strategies with regional formulation trends.
Market Dynamics
Chloride-route titanium dioxide capacity expansion in Shandong and Sichuan provinces is compressing sulfate-process economics and forcing legacy producers to absorb higher environmental compliance costs or exit.
Growth Catalysts
- Automotive refinish coatings:OEMs in China and India specify higher contrast ratios for metallic and pearl finishes, pulling rutile-grade TiO2 into premium formulations.
- India's BIS certification mandate:Food-grade opacifier import standards tighten, creating captive demand for domestic barium sulfate and precipitated calcium carbonate producers.
- Mineral sunscreen displacement:ECHA scrutiny of organic UV filters accelerates zinc oxide and TiO2 nanoform adoption in cosmetic-grade segments across the European Union.
Market Restraints
- Ilmenite and rutile feedstock concentration:Mineral sands supply clusters in Western Australia and South Africa expose pigment producers to freight volatility and geopolitical disruption.
- Sulfate-process acid waste liability:China's MEE emission caps on sulfuric acid effluent elevate treatment costs for 60% of domestic TiO2 capacity.
- Refractive index ceiling:No commercially viable material surpasses TiO2's 2.7 refractive index, capping opacity efficiency gains and sustaining premium pricing for chloride-route material.
Strategic Opportunities
- Indonesia and Vietnam architectural coatings:Infrastructure investment and urbanization outpace local opacifier production, opening import substitution windows for Chinese and Indian suppliers.
- Bioplastics integration:Polylactic acid and starch-based packaging require opacifiers compatible with lower-temperature processing, favoring surface-treated nano-TiO2 over conventional grades.
- EU Green Deal carbon border adjustments:Low-carbon chloride-route pigment gains preferential access versus sulfate-process imports, rewarding producers with renewable energy sourcing.
Industry Challenges
- REACH nanoform registration timelines:European Union dossier preparation for TiO2 and ZnO nanoforms extends 18-24 months, freezing product launches and locking capital in compliance.
- Particle-size distribution control:Cosmetic-grade specifications demand sub-100nm primary particles with minimal agglomeration, requiring spray-drying and micronization capex that mid-scale producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opacifiers Market |
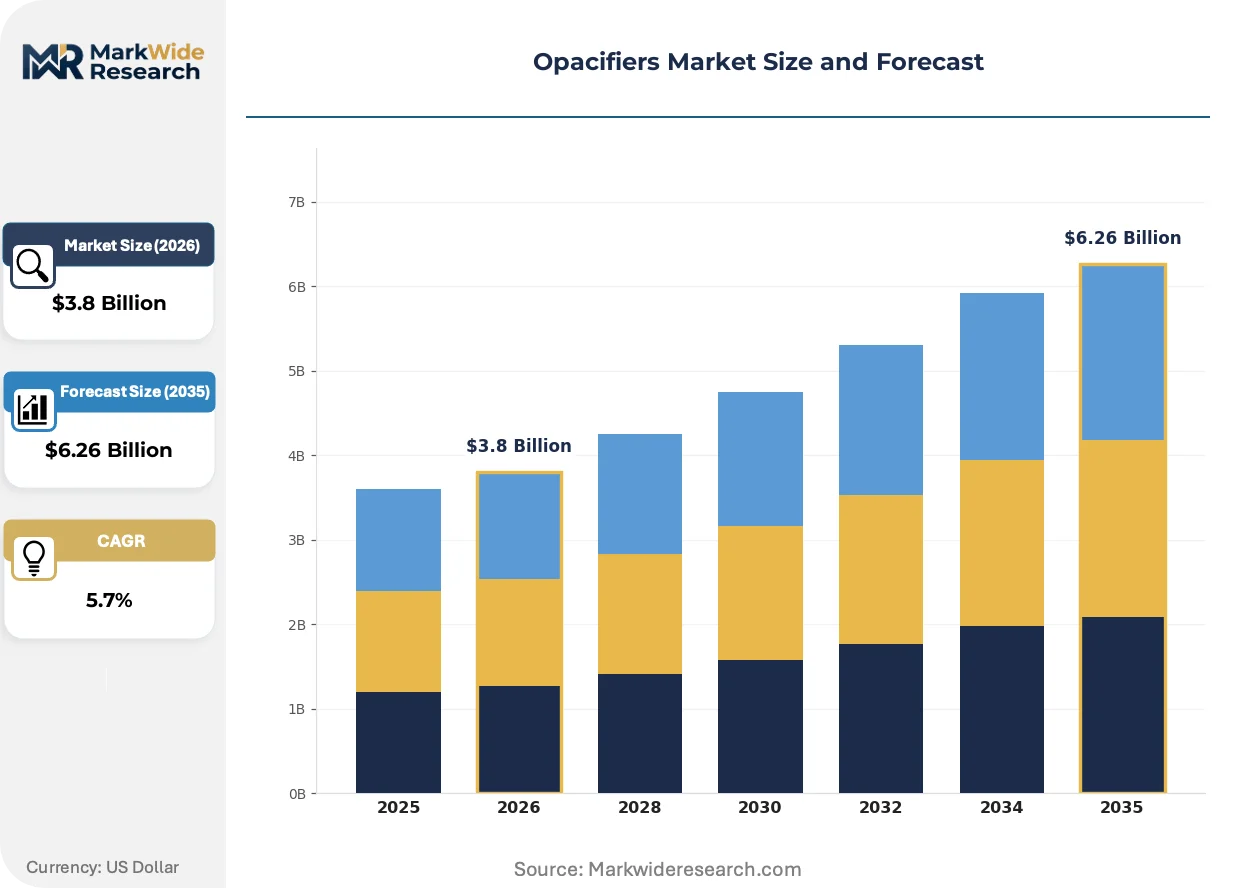
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Dioxide, Barium Sulfate, Zinc Oxide, Calcium Carbonate Industry Vertical: Paints & Coatings, Plastics, Cosmetics, Food & Beverages End User: Manufacturers, Cosmetic Companies, Food Producers, Construction Firms Grade: Industrial Grade, Food Grade, Cosmetic Grade, Pharmaceutical Grade |
| Companies Covered | Tronox Holdings plc, The Chemours Company, Dow, Indulor Chemie GmbH, Venator Materials PLC, Arkema SA, KRONOS Worldwide, Inc., BASF, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opacifiers Market Emerging Trajectories
Formulation chemistry is pivoting toward lower-VOC, waterborne systems that demand opacifiers with superior dispersibility and pH stability across alkaline and neutral binders.
Surface-treated rutile TiO2 engineered with alumina and silica encapsulation layers is migrating from solvent-borne industrial coatings into waterborne architectural paints. PPG Industries and AkzoNobel procurement teams specify these grades for zero-VOC interior formulations. The shift compresses demand for untreated anatase in premium segments while elevating technical service requirements from pigment suppliers.
REACH registration requirements for nanoforms of TiO2 and ZnO reshape product liability protocols across the European Union. ECHA's 2022 classification of TiO2 as a category 2 carcinogen by inhalation forces reformulation of powder handling systems and drives demand for granulated or liquid slurry delivery formats. Pigment producers respond with captive slurry capacity co-located at downstream paint manufacturing sites.
Coatings manufacturers consolidate qualified supplier lists from 8-12 vendors to 3-4 strategic partners with integrated slurry and technical service capabilities. This concentration transfers inventory risk upstream and compresses spot-market volumes for standard-grade TiO2. The pattern is most visible in China's eastern chemical corridor, where Jiangsu and Zhejiang paint clusters negotiate multi-year offtake agreements with Shandong-based chloride-route producers.
Opacifiers Market Segmentation
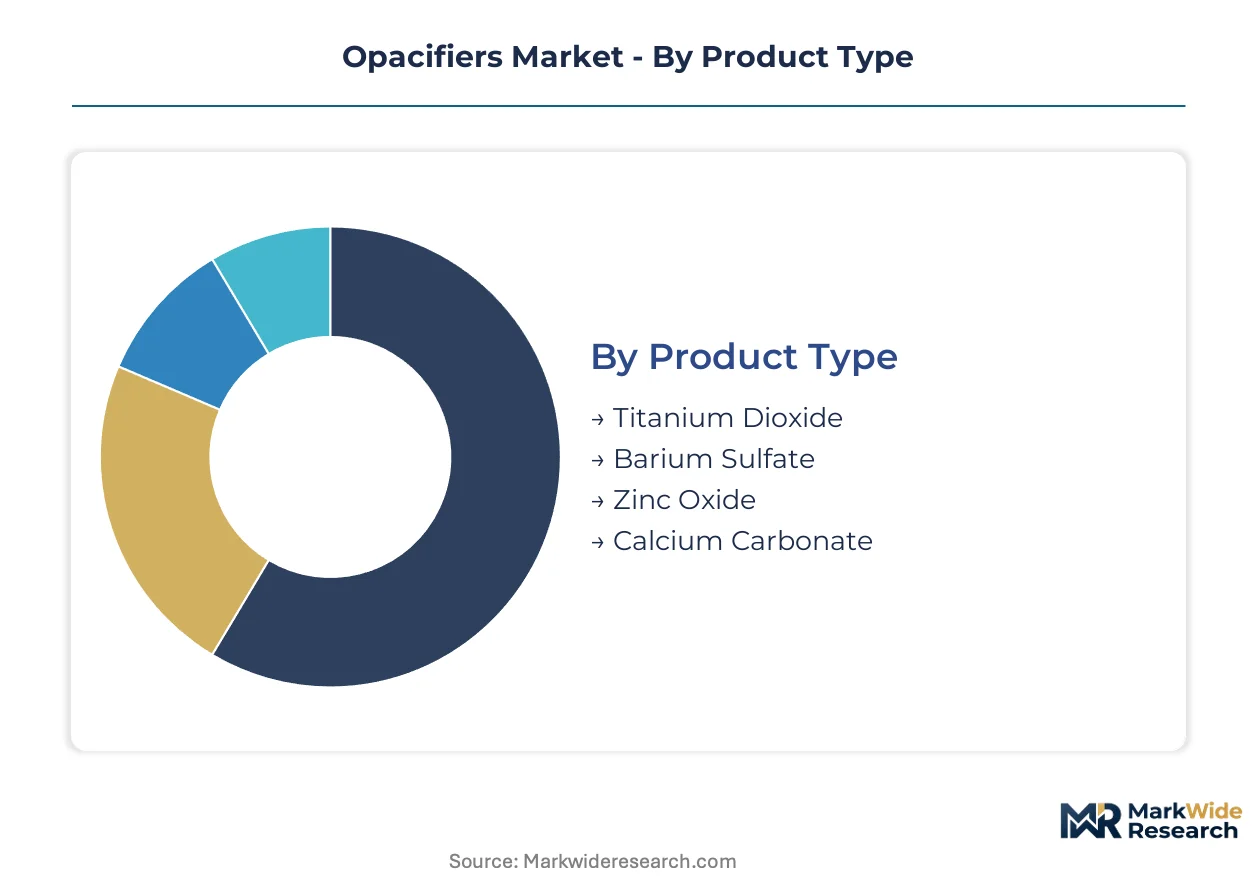
Opacifier segmentation reveals how formulation requirements diverge across end-use specifications and regulatory thresholds. Each category reflects distinct technical validation protocols that reshape supplier qualification and procurement patterns.
Product Type:
Mature commodity chemistry dominates volume positions while engineered nanoforms capture premium expansion corridors.
- Titanium Dioxide:Rutile crystal structure delivers refractive index of 2.7, the commercial maximum for scattering efficiency. Chloride-route material from Shandong and Sichuan provinces is displacing sulfate-process supply in waterborne architectural coatings as China's MEE emission caps tighten acid waste liability.
- Barium Sulfate:Inert filler with refractive index of 1.64 occupies pharmaceutical and food-grade niches where chemical neutrality outweighs opacity performance. India's BIS certification mandate for food-contact applications is redirecting import substitution toward domestic precipitated grades.
- Zinc Oxide:UV-absorbing functionality combines with moderate opacification in mineral sunscreen formulations.
- Calcium Carbonate:Ground and precipitated variants serve cost-sensitive applications with lower hiding power requirements.
Titanium Dioxide handles the majority of throughput; Zinc Oxide is climbing the fastest on share as cosmetic mineral sunscreen displacement accelerates.
Industry Vertical:
Application-specific dispersion requirements and film-forming conditions determine grade selection and surface treatment specifications.
- Paints & Coatings:Architectural and automotive refinish segments specify contrast ratios above 0.98 for metallic finishes, pulling surface-treated rutile with alumina-silica encapsulation into zero-VOC waterborne systems. Procurement consolidation from 8-12 vendors to 3-4 strategic partners concentrates inventory risk upstream.
- Plastics:Masterbatch compounding demands thermal stability above 280°C for polyolefin extrusion, favoring inorganic opacifiers over organic alternatives. Bioplastics integration into polylactic acid packaging favors surface-treated nano-TiO2 compatible with lower-temperature processing.
- Cosmetics:ECHA scrutiny of organic UV filters under REACH nanoform registration protocols is accelerating zinc oxide and TiO2 nanoform adoption.
- Food & Beverages:BIS certification requirements in India and FDA food-contact notifications in the United States enforce strict purity thresholds.
Paints & Coatings commands the dominant volume position; Cosmetics is expanding most quickly on regulatory-driven mineral sunscreen reformulation.
End User:
Scale economies and captive formulation capabilities separate integrated producers from merchant market dependence.
- Manufacturers:Paint and plastics producers with captive slurry facilities co-located at manufacturing sites transfer inventory risk upstream and compress spot-market volumes for standard-grade material.
- Cosmetic Companies:Mineral sunscreen formulators demand sub-100nm primary particles with minimal agglomeration, requiring spray-drying and micronization capital that locks mid-scale producers out of qualification.
- Food Producers:BIS certification in India and FDA compliance in the United States enforce additive purity documentation.
- Construction Firms:Direct procurement of architectural coatings specifies hiding power and weathering resistance.
Manufacturers absorb the largest share of opacifier offtake; Cosmetic Companies are gaining share fastest on premium-grade mineral sunscreen demand.
Grade:
Regulatory certification tiers separate commodity volume from premium-margin specialty positioning.
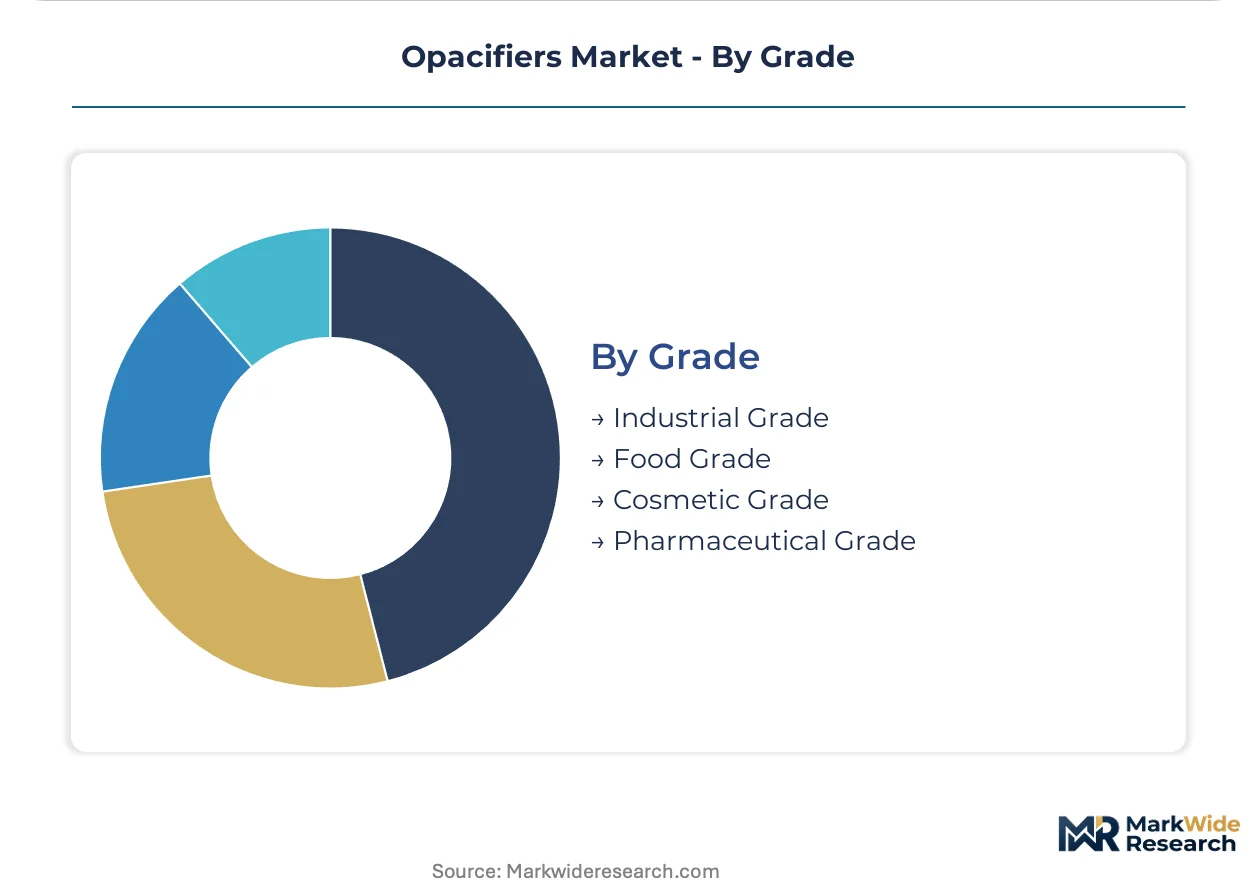
- Industrial Grade:Standard rutile and anatase TiO2 serves coatings and plastics with basic dispersion and durability requirements. Untreated anatase is losing position in premium segments as waterborne formulation chemistry advances.
- Cosmetic Grade:Sub-100nm primary particles with controlled agglomeration command premium positioning as ECHA classification of TiO2 as category 2 carcinogen by inhalation forces powder-handling system reformulation and liquid slurry delivery adoption.
- Food Grade:Barium sulfate and precipitated calcium carbonate with heavy metal limits below 10 ppm serve confectionery and pharmaceutical tablet coatings.
- Pharmaceutical Grade:USP and EP monograph compliance for excipient functionality in tablet and capsule formulations.
Industrial Grade maintains the dominant throughput position; Cosmetic Grade is expanding most quickly on regulatory-driven nanoform adoption and premium mineral sunscreen displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites Asia-Pacific chemical logistics, while Rotterdam's Maasvlakte terminals anchor European pigment distribution. These maritime gateways determine regional supply chain economics.
China
Automotive refinish coatings and architectural waterborne paints pull chloride-route titanium dioxide into premium formulations. The MEE enforces emission caps on sulfate-process acid waste that elevate compliance costs for legacy producers. Shandong and Sichuan provinces host new chloride capacity that narrows the cost gap with sulfate-route material.
United States
Zero-VOC interior paint specifications from PPG Industries and Sherwin-Williams drive surface-treated rutile adoption. EPA oversight of titanium dioxide nanoparticle classification reshapes product liability protocols. The Mississippi and Tennessee chemical corridor anchors chloride-process specialization for North American supply security.
Germany
Industrial coatings procurement concentrates qualified supplier lists from 8-12 vendors to 3-4 strategic partners. REACH registration requirements for nanoforms of TiO2 and ZnO extend dossier preparation timelines. The North Rhine-Westphalia coatings cluster negotiates multi-year offtake agreements with integrated pigment suppliers.
India
Food-grade opacifier demand accelerates as BIS certification mandates tighten import substitution pathways. The dual carbon goals of neighboring China redirect regional formulation chemistry toward low-emission systems. Gujarat's chemical manufacturing corridor expands precipitated calcium carbonate and barium sulfate capacity for domestic pharmaceutical and confectionery applications.
Opacifiers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and intermediate processing. The opacifiers sector exhibits tiered consolidation around chloride-route pigment producers, sulfate-process legacy operators, and specialty nanoform developers. Strategic archetypes include vertically integrated mineral-sands-to-pigment operators, regional merchant-market suppliers, and cosmetic-grade nanoform specialists. Capacity expansion in Shandong and Sichuan provinces and procurement consolidation by downstream coatings manufacturers represent the dominant competitive vectors.
Among North American-domiciled chemical conglomerates, The Chemours Company and Tronox Holdings plc occupy positions as archetypal integrated producers with captive mineral sands access. Venator Materials PLC represents the European merchant-market tier. These three entities exemplify how geographic feedstock positioning and process-route specialization separate premium chloride material from commodity sulfate supply.
| Leading Market Players |
|---|
| Tronox Holdings plc |
| The Chemours Company |
| Dow |
| Indulor Chemie GmbH |
| Venator Materials PLC |
| Arkema SA |
| KRONOS Worldwide, Inc. |
| BASF |
| Ashland |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Shandong and Sichuan chloride-route titanium dioxide capacity is compressing sulfate-process margins and forcing legacy producers to absorb higher environmental compliance costs or exit entirely, reshaping supplier bargaining power across coating procurement channels.
Pricing Analysis
China's MEE emission caps on sulfate-process acid waste dictate the pricing tier structure across industrial, cosmetic, and food-grade opacifiers. Three-tier pricing separates chloride-route rutile from sulfate-process material from precipitated barium sulfate fillers. Price differentiation rests on environmental compliance certification and particle-size distribution control. Cost compression in sulfate-process tiers is intensifying because legacy producers face acid waste treatment liabilities. Industrial coatings manufacturers exhibit highest price sensitivity, while cosmetic-grade nanoform buyers accept premium positioning for REACH-compliant nanoform dossiers.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian coating markets dominates supply chain risk calculus for opacifier distribution. Feedstock concentration in Western Australia and South Africa for ilmenite and rutile mineral sands, coupled with chloride-process manufacturing clustering in Shandong and Sichuan provinces, creates single-source vulnerability for premium pigment supply. Raw material dependencies span mineral sands, sulfuric acid, and chlorine gas feedstocks. Distribution runs through liquid slurry co-location agreements at downstream paint manufacturing sites, transferring inventory risk upstream from coatings producers to pigment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral sunscreen reformulation under ECHA scrutiny represents a high-growth disruption, with nanoform registration requirements creating qualification barriers that concentrate margin capture among certified suppliers.
For Market Incumbents: Build regulatory moats through captive REACH nanoform dossier preparation for TiO2 and ZnO variants. Secure multi-year offtake agreements with Jiangsu and Zhejiang paint clusters before chloride-route capacity floods merchant markets. Add spray-drying and micronization capacity to lock cosmetic-grade qualification. Threat of sulfate-process legacy exit accelerates consolidation opportunity.
For New Entrants and Emerging Players: Pursue Indonesia and Vietnam architectural coatings import substitution as Chinese chloride-route producers seek Southeast Asian offtake. Target food-grade barium sulfate and precipitated calcium carbonate in Gujarat's pharmaceutical corridor under BIS certification mandate. Lead with technical service capabilities and slurry co-location rather than commodity spot supply.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cosmetic-grade nanoform segments due to sub-100nm particle control equipment requirements. Long-term viability favors integrated mineral-sands-to-pigment operators with captive feedstock and renewable energy sourcing for EU Green Deal carbon border adjustment compliance. Watch Shandong chloride-route utilization rates as inflection signal for sulfate-process distress acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Chloride-Route Capacity Expansion | Shandong and Sichuan additions compress sulfate-process economics and force legacy environmental compliance investment. |
| Backward Integration into Mineral Sands | Captive ilmenite and rutile supply insulates margin stability across feedstock price cycles. |
| REACH Nanoform Dossier Preparation | ECHA registration timelines lock qualification advantage for early movers in cosmetic-grade segments. |
| Liquid Slurry Co-Location Agreements | PPG Industries and AkzoNobel procurement patterns transfer inventory risk upstream to pigment suppliers. |
| Bioplastics-Compatible Surface Treatment | Polylactic acid packaging demand favors lower-temperature processing nano-TiO2 development. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association reports. Interviews with chloride-route plant managers, coatings procurement leads at downstream OEMs, distribution channel partners, and cosmetic formulation R&D directors informed supply-side and demand-side validation. Secondary sources include EPA nanoform classification notices, ECHA REACH registration databases, China MEE emission cap enforcement records, and SEC 10-K pigment segment disclosures. Bottom-up capacity modeling and top-down end-use consumption estimates were cross-checked for triangulation.
Forecast inputs span grade tier, end-use industry vertical, regional production hub clustering, and nanoform certification status across the projection horizon. Segment-level CAGRs were derived from elasticity modeling against coatings production indices and plastics compounding growth. Industry-specific inputs include automotive refinish coatings specification trends and mineral sunscreen formulation shift rates under ECHA organic UV filter scrutiny.
Macroeconomic conditions sit as an overlay; deviation in construction spending indices and automotive production schedules would shift the trajectory. Forecasts reflect documented assumptions regarding chloride-route capacity ramp timing and REACH nanoform registration completion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
Dammar Gum Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Resin Capsule Market