
 Packaging Coating Additives Market | 2026-2036
Packaging Coating Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Coating Additives Market Intelligence
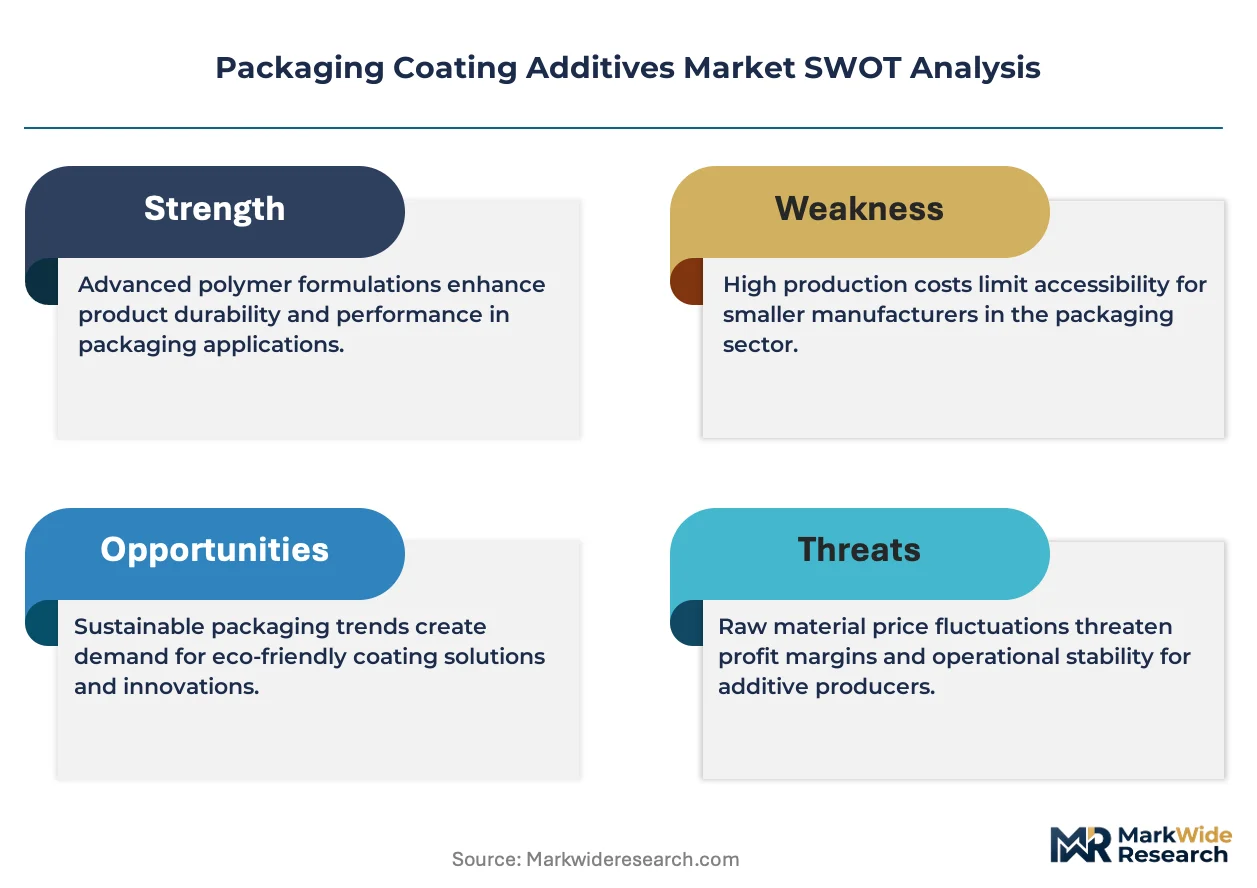
Asset-light toll manufacturing and third-party coating service agreements is fragmenting competitive boundaries among additive suppliers. BASF SE leverages its integrated epoxy and acrylic precursor chains to control input cost volatility across European coating operations. Clariant AG anchors its position through specialty wax and surface-modifier portfolios tailored to high-speed food packaging lines. Evonik Industries AG competes via siloxane and defoamer technologies that reduce coating defects in water-based systems.
Packaging coating additives are functional chemical modifiers—typically comprising slip agents, anti-blocking agents, defoamers, rheology modifiers, and wetting agents at active concentrations of 0.1% to 5% by weight—formulated into liquid or solid coating systems to enhance substrate adhesion, surface aesthetics, and process efficiency on film, paper, and metal packaging substrates. Their primary commercial purpose is to enable high-speed converting, printability, and barrier performance while minimizing material waste and re-work. Water-based technology leads volume adoption in food and beverage packaging as converters retrofit lines to meet volatile organic compound limits, while UV-curable systems command premium positioning in pharmaceutical blister packs where instant cure and low heat exposure protect thermally sensitive actives. Acrylic additives dominate flexibility and clarity demands in cosmetic container coatings, whereas polyurethane chemistry extends scratch resistance for electronics protective films.
REACH registration requirements and the EU Green Deal's packaging sustainability targets are forcing additive suppliers to document substance safety and carbon intensity across full formulation chains. FDA food contact notifications and EPA TSCA Section 5 pre-manufacture reviews govern US market entry for novel slip and anti-fog chemistries in direct-contact applications. Stakeholders must monitor how ECHA substance-of-very-high-concern candidate list expansions and state-level extended producer responsibility laws reshape permissible additive chemistries and customer qualification timelines.
Market Dynamics
Water-based coating retrofits across European converting lines are compressing qualification timelines for additive suppliers while fragmenting procurement authority between brand owners and toll manufacturers.
Growth Catalysts
- REACH SVHC expansions:ECHA's candidate list updates are accelerating substitution of legacy slip agents with bio-based alternatives in German food packaging operations.
- High-speed flexographic printing:Converters in Italy and Spain are adopting rheology modifiers that enable line speeds above 400 meters per minute on thin-gauge films.
- Barrier coating demand:Oxygen-scavenging additive chemistries are penetrating fresh protein and ready-meal segments as shelf-life extension becomes a retail priority.
Market Restraints
- Epoxy precursor volatility:Bisphenol-A supply disruptions from Asian producers are creating input cost swings that erode formulation margin stability.
- Water-based cure limitations:Slower drying kinetics versus solvent systems constrain throughput on legacy coating lines without capital-intensive infrared upgrades.
- Fluoropolymer substitution pressure:Per- and polyfluoroalkyl substance restrictions under EU F-Gas Regulation are forcing reformulation of grease-resistant coatings for fast-food packaging.
Strategic Opportunities
- Polish and Czech converter networks:Underpenetrated Central European coating capacity offers first-mover positioning for defoamer and wetting agent suppliers.
- Pharmaceutical cold-chain packaging:Anti-fog additives for temperature-controlled blister films represent an emerging specification channel with premium pricing tolerance.
- EU Green Deal packaging mandates:Recyclability targets for 2030 are creating pull for wash-off additives that enable mono-material film recovery without coating contamination.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in water-based polyurethane dispersion stabilization is concentrating among aging technical workforces in Germany and the Netherlands.
- Food contact notification timelines:FDA clearance processes for novel anti-blocking agents extend 18-24 months, delaying commercial launch in North American export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Coating Additives Market |
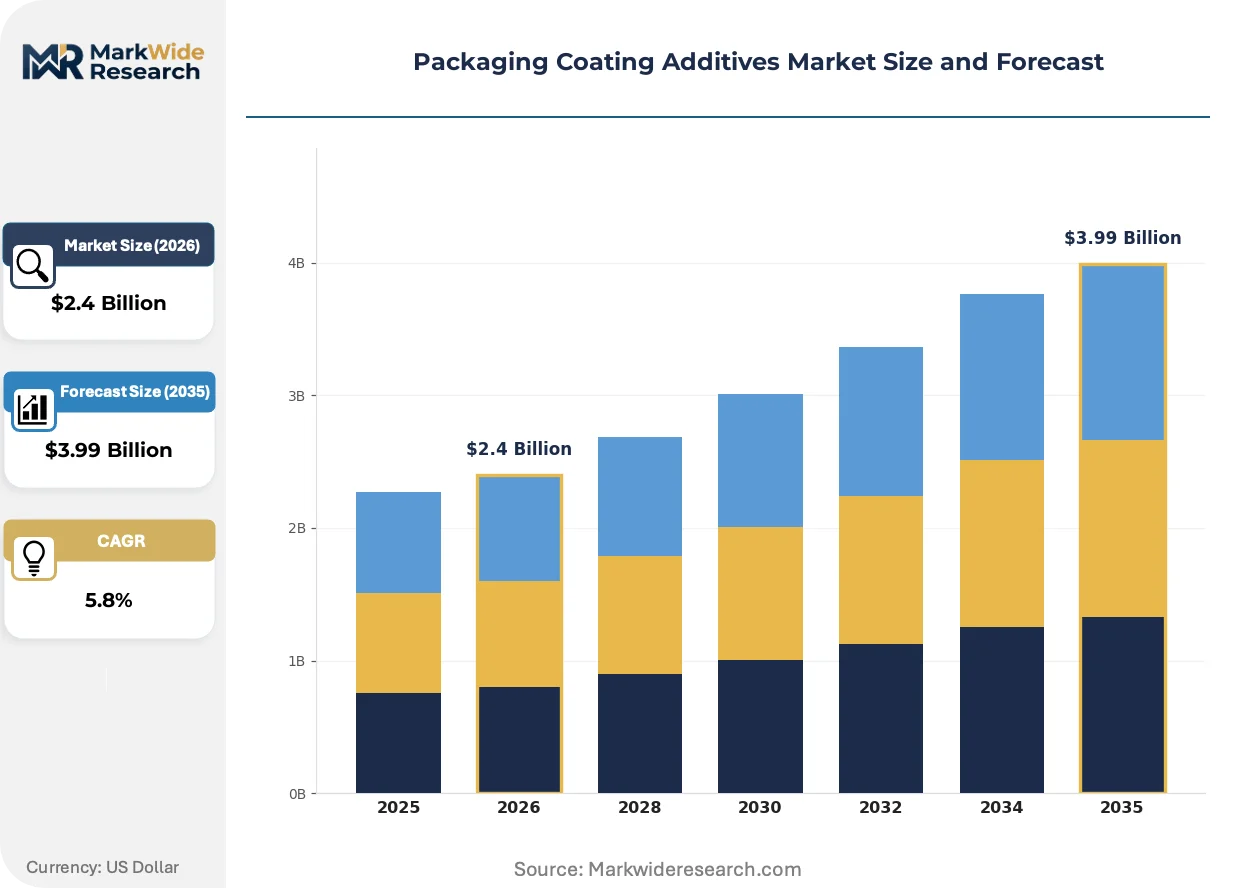
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Acrylic, Polyurethane Application: Food Packaging, Beverage Packaging, Cosmetic Containers, Pharmaceutical Packaging End User: FMCG, Healthcare, Electronics, Automotive Technology: Water-Based, Solvent-Based, UV-Curable, Hot Melt |
| Companies Covered | BASF SE, Clariant AG, Evonik Industries AG, Dow Inc., Arkema, ALTANA AG, Nouryon, Croda International Plc, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Coating Additives Market Strategic Shifts & Innovations
Digital formulation platforms are compressing R&D cycles while regulatory substance tracking is embedding transparency requirements directly into coating supply contracts.
Siloxane surface modifiers are virtualizing defect detection protocols in coating operations. Electronics protective film manufacturers in South Korea and Japan are adopting these chemistries to eliminate microscopic pinholes during high-speed roll-to-roll processing. The technology is virtualizing quality assurance workflows by enabling in-line optical inspection that replaces offline microscopy, collapsing batch release timelines from days to hours.
EU Green Deal packaging sustainability targets are mandating carbon footprint disclosure across full formulation chains. Additive suppliers must now document scope 3 emissions from raw material extraction through conversion, with penalties for incomplete data in public procurement tenders. German brand owners are responding by consolidating supplier panels to those with certified life-cycle assessment capabilities, favoring integrated chemical producers over specialized importers.
Converter procurement committees are unbundling technical service from additive supply contracts. Mid-sized Italian and Spanish packaging firms are shifting toward specification-based purchasing where formulation troubleshooting moves to third-party coating service providers. This restructuring is most visible in the flexographic segment, where brand owners now contract directly with toll coaters for barrier performance guarantees rather than delegating additive selection to ink suppliers.
Packaging Coating Additives Market Segmentation
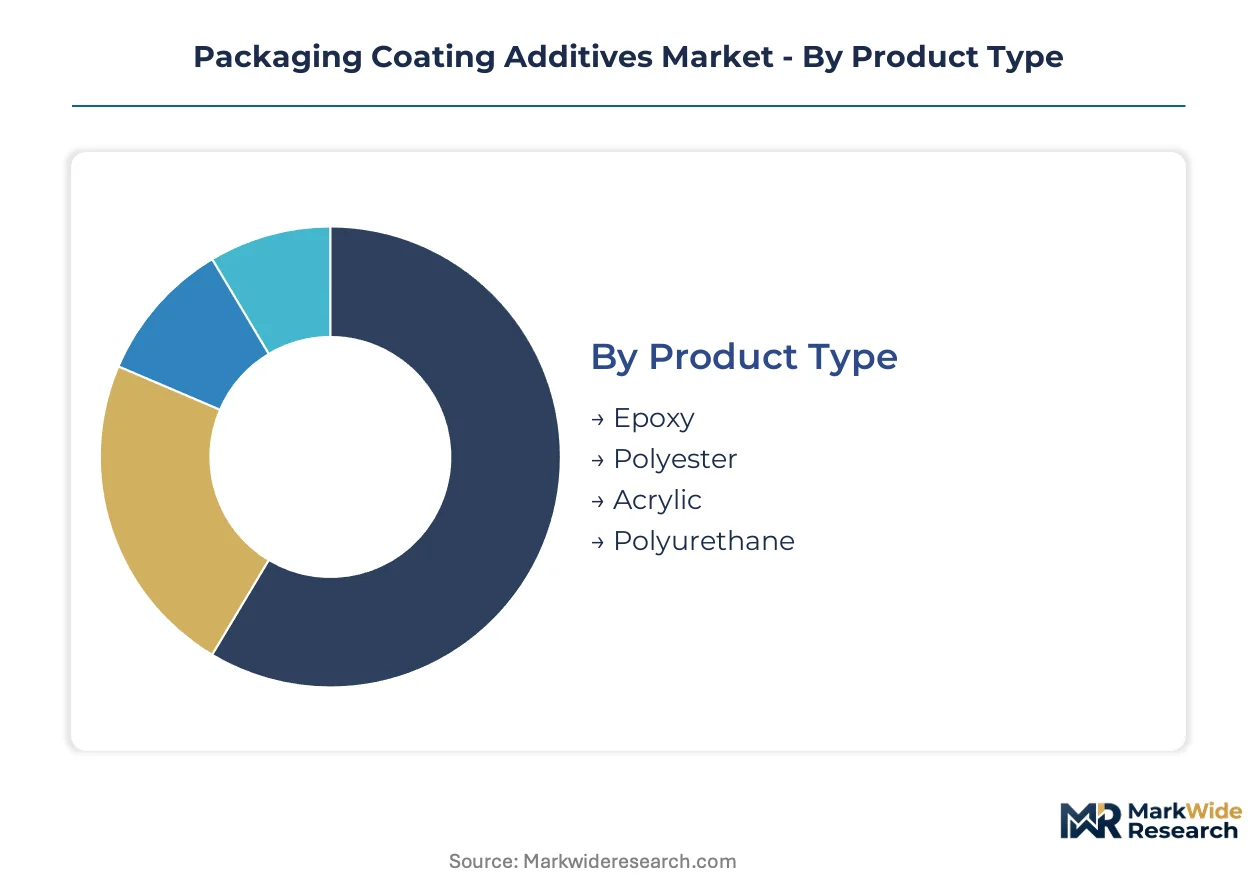
Packaging coating additives serve distinct performance requirements across substrate chemistries and converting technologies. Segment boundaries shift as brand owners consolidate supplier panels and toll manufacturers assume formulation authority.
Product Type:
Acrylic and polyurethane cycles turn fastest due to cosmetic and electronics refresh rates, while epoxy qualification timelines stretch across multi-year food packaging contracts.
- Acrylic:These additives deliver optical clarity and flexibility in cosmetic container coatings. Demand clusters in German and French beauty packaging lines where premium aesthetics command specification priority. REACH registration burdens favor established acrylic suppliers with documented substance safety dossiers.
- Polyurethane:Scratch-resistant film coatings for electronics protection dominate uptake. South Korean and Japanese manufacturers specify these chemistries for roll-to-roll processing of display films where defect tolerance approaches zero.
- Epoxy:Barrier performance in metal food cans drives steady demand despite Bisphenol-A substitution pressures under ECHA scrutiny.
- Polyester:Heat-resistant formulations serve retort pouch applications in ready-meal packaging segments.
Epoxy anchors the volume base while polyurethane gains share at the steepest rate.
Application:
Cost tier stratification separates commodity food packaging from premium pharmaceutical specifications where validation expenses dominate total cost of ownership.
- Food Packaging:Oxygen-scavenging and anti-fog additives extend shelf life for fresh protein and ready-meal formats. German retailers now mandate wash-off coating compatibility with mono-material recycling streams under EU Green Deal packaging targets.
- Pharmaceutical Packaging:Anti-fog chemistries for cold-chain blister films command premium positioning. FDA food contact notification timelines of 18-24 months restrict supplier entry to those with dedicated regulatory affairs capacity.
- Beverage Packaging:High-speed can coating lines in Italy and Spain specify rheology modifiers enabling throughput above 400 meters per minute.
- Cosmetic Containers:Clarity and UV resistance requirements favor acrylic-dominated formulation portfolios.
Food packaging absorbs the largest additive volumes while pharmaceutical applications expand most quickly on a value-per-kilogram basis.
End User:
Customer procurement maturity separates integrated FMCG giants with captive formulation expertise from fragmented electronics assemblers outsourcing coating selection.
- FMCG:Brand owners in Germany and the Netherlands co-invest in sustainable coating infrastructure, consolidating supplier relationships around life-cycle assessment capabilities. Unilever and Henkel procurement committees now specify scope 3 carbon disclosure across full formulation chains.
- Healthcare:Pharmaceutical cold-chain requirements drive anti-fog additive adoption for temperature-controlled distribution. Validation protocols extend qualification timelines versus standard food contact applications.
- Electronics:South Korean and Japanese display film manufacturers prioritize pinhole elimination through siloxane surface modifiers.
- Automotive:Protective films for interior trim components specify scratch-resistant polyurethane coatings with automotive OEM durability standards.
FMCG anchors the volume base while healthcare gains share at the steepest rate.
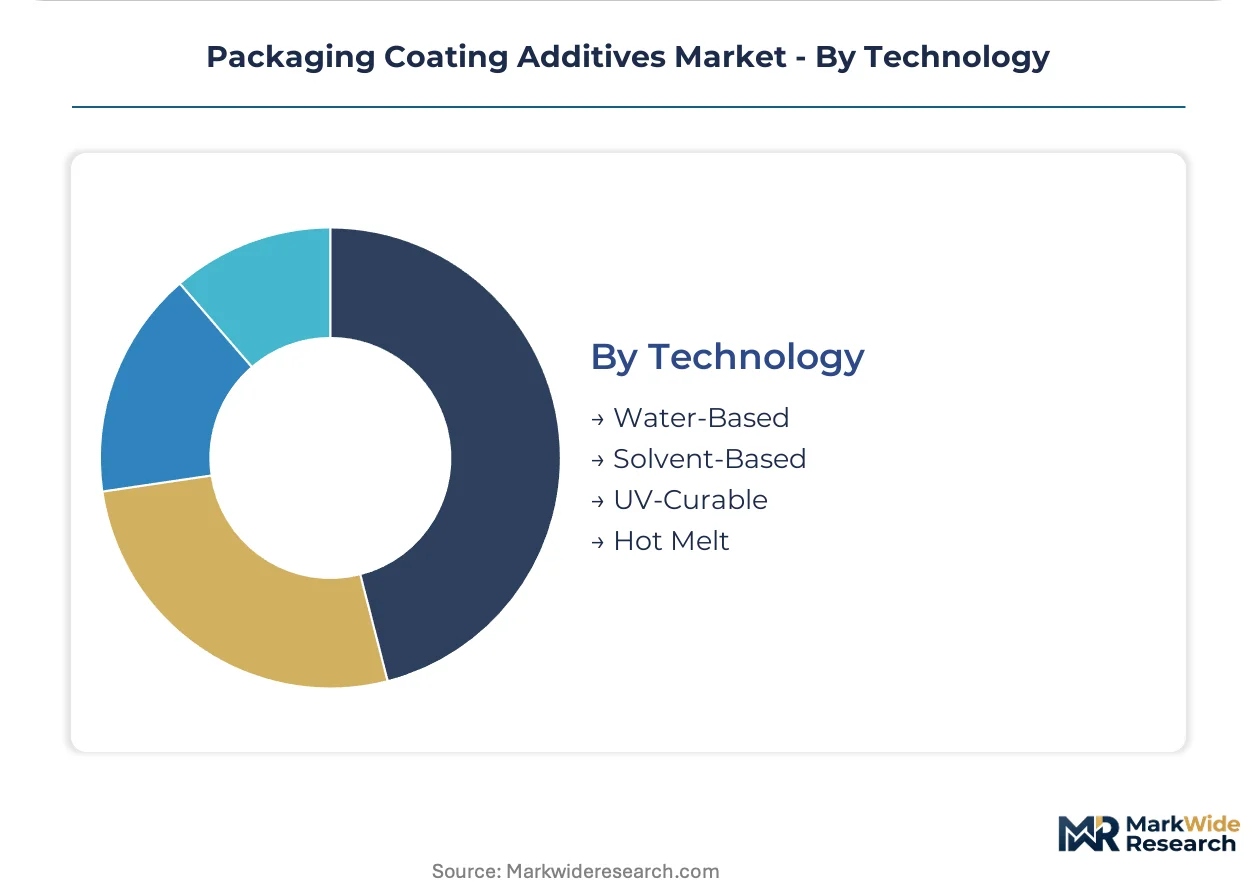
Technology:
Volume concentration favors water-based retrofits across European converting lines, while UV-curable systems occupy premium niches where instant cure protects thermally sensitive substrates.
- Water-Based:Volatile organic compound compliance drives retrofit investment across Italian and Spanish flexographic operations. Slower drying kinetics versus solvent systems constrain throughput without infrared upgrade capital deployment.
- UV-Curable:Instant cure protects thermally sensitive pharmaceutical actives in blister pack applications. Electronics protective film manufacturers specify these systems for heat-sensitive display components.
- Solvent-Based:Legacy coating lines in Eastern European converter networks maintain residual demand despite regulatory pressure.
- Hot Melt:Pressure-sensitive adhesive applications in label and tape formats favor these systems for bond strength at line speed.
Water-based technology anchors the volume base while UV-curable gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in coating additive precursors are redirecting procurement strategies toward regional supply security. Germany and the Netherlands maintain additive trade surpluses while Asian epoxy resin dependencies expose European formulators to input volatility. Converter networks in Poland and the Czech Republic are emerging as alternative coating capacity hubs.
Germany
REACH SVHC expansions are accelerating bio-based slip agent substitution in Bavarian food packaging operations. The EU Green Deal's 2030 recyclability mandates are forcing Brandenburg converters to qualify wash-off coating systems. The Rhine-Ruhr industrial corridor hosts BASF SE and Evonik Industries AG integrated precursor facilities that supply European coating formulators.
United States
FDA food contact notification timelines of 18-24 months are restricting novel anti-blocking agent launches in direct-contact applications. EPA TSCA Section 5 pre-manufacture reviews govern entry of silicone-based surface modifiers for pharmaceutical blister films. The Gulf Coast petrochemical corridor maintains residual epoxy precursor capacity serving domestic can coating lines.
China
NMPA pharmaceutical packaging standards are driving specification upgrades for barrier coating additives in cold-chain distribution. MIIT industrial policy is channeling investment into water-based coating retrofits for flexographic export operations. The Yangtze River Delta concentration of display film manufacturers specifies siloxane surface modifiers for pinhole elimination at line speeds above 400 meters per minute.
Japan
METI carbon neutrality roadmaps are pressuring electronics protective film manufacturers to disclose scope 3 emissions across coating supply chains. JIS standards for food contact materials are tightening migration limits for residual monomers in acrylic additive systems. The Kansai industrial region around Osaka maintains specialty polyurethane dispersion expertise for scratch-resistant display coatings.
South Korea
MFDS pharmaceutical packaging regulations are extending validation protocols for anti-fog additives in temperature-controlled blister films. Corporate zero-defect mandates from Samsung Display and LG Chem are specifying siloxane chemistries for roll-to-roll processing of foldable screen protective layers. The Busan-Ulsan petrochemical cluster supplies domestic epoxy and acrylic precursor requirements.
Packaging Coating Additives Market Key Industry Players
On the supply side, the industry is consolidating around integrated chemical producers with captive precursor chains and documented life-cycle assessment capabilities. Mid-sized specialty additive suppliers face procurement committee consolidation as German FMCG brand owners reduce supplier panels. Three archetypes dominate: diversified chemical conglomerates with backward integration into epoxy and acrylic feedstocks, specialty wax and surface modifier specialists serving high-speed converting lines, and siloxane technology providers targeting electronics defect elimination. Competitive moves center on M&A to secure bio-based raw material sourcing and strategic partnerships with toll coating service providers to bypass fragmented converter procurement.
Within the integrated chemical tier, BASF SE anchors European supply security through its Ludwigshafen precursor complex. Clariant AG exemplifies the specialty wax archetype with surface modifier portfolios concentrated in food packaging applications. Evonik Industries AG occupies the siloxane technology position serving electronics and water-based coating defect reduction. These three represent distinct competitive vectors rather than overlapping market contests.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Evonik Industries AG |
| Dow Inc. |
| Arkema |
| ALTANA AG |
| Nouryon |
| Croda International Plc |
| Lonza Group |
| Others |
Cost & Logistics Intelligence
Bisphenol-A supply disruptions from Asian producers determine both pricing tier spreads and supply chain shape across European coating additive markets. Epoxy precursor volatility compresses margins at the formulation level while forcing converters toward long-term offtake contracts with integrated chemical producers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across food packaging additive tiers. Price differentiation separates REACH-registered premium grades from standard commodity formulations, with certification level and volume scale as primary tiering mechanisms. Cost compression in water-based retrofits intensifies because toll manufacturers consolidate procurement authority. Mid-sized Italian and Spanish converters exhibit highest price sensitivity, while German FMCG brand owners prioritize life-cycle assessment documentation over unit cost.
Supply Chain Analysis
Upstream epoxy and acrylic feedstock production concentrates in Germany, the Netherlands, and China. European formulators draw from Asian bisphenol-A sources alongside domestic precursor capacity, with siloxane surface modifiers resting on South Korean and Japanese specialty chemical expertise. Single-source vulnerability in epoxy resin supply exposes margin stability to shipping route disruptions. Distribution runs through integrated chemical producers with captive logistics networks serving toll coating service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging mandates are accelerating a high-growth disruption as recyclability targets force wholesale reformulation roadmaps across the analysis window.
For Market Incumbents: Build regulatory dossier moats through REACH registration completion for bio-based slip agent portfolios. Secure backward integration into acrylic precursor chains to buffer Asian feedstock volatility. Consolidate supplier panel relationships with German FMCG brand owners before wash-off additive specifications harden. For New Entrants and Emerging Players: Pursue defoamer and wetting agent positioning in underpenetrated Polish and Czech converter networks. Target pharmaceutical cold-chain packaging for anti-fog additive entry, where FDA notification timelines deter established competitors. Lead with third-party coating service partnerships rather than direct converter sales. For Investors and Strategic Acquirers: ECHA substance-of-very-high-concern list expansions reshape the acquisition landscape toward bio-based formulation capabilities. Five-to-ten year viability favors integrated producers with scope 3 carbon disclosure infrastructure. Monitor EU F-Gas Regulation enforcement intensity as fluoropolymer substitution inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures precursor supply independence from Asian bisphenol-A volatility under REACH compliance. |
| Long-term Supply Agreement with Toll Coaters | Locks specification authority as brand owners bypass traditional converter procurement channels. |
| Green Manufacturing Transition | Aligns production with EU Green Deal scope 3 disclosure requirements for German FMCG tenders. |
| Joint Venture in Central European Coating Capacity | Captures first-mover positioning in Polish and Czech converter network expansion zones. |
| Acquisition of Siloxane Technology Specialist | Consolidates defect elimination expertise for South Korean and Japanese electronics protective film demand. |
Research Approach
A standing panel of coating formulators, toll manufacturing operators, FMCG procurement leads, and regulatory affairs directors provided ongoing calibration across the study period. Primary interview data combined with secondary validation from ECHA substance registrations, EU customs trade flows, SEC chemical sector filings, and Cefic industry statistics. Bottom-up volume modeling triangulated against top-down market sizing from precursor consumption patterns.
Scenario-bracketing framed projections across the modeling period, with segmentation dimensions spanning chemistry type, application end-use, technology platform, and regional production hub. CAGRs derived from fitted growth curves applied to disclosed capacity expansions and converter retrofit timelines. Water-based coating line conversion rates and pharmaceutical cold-chain packaging adoption served as industry-specific demand inputs.
Macroeconomic conditions sit as an overlay; deviation in energy costs, Asian export tariffs, or European industrial production indices would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation schedules and feedstock price stabilization. Material shifts in EU F-Gas Regulation enforcement or ECHA SVHC candidate list expansion timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Glycol Acetate Market
Additives
Battery Additives Market
Additives
Global Sizing Agents Market
Additives
China Citric Acid Market
Additives
Asia-Pacific Water Enhancer Market
Additives
Adjustive Agents Market
Additives
Global Silica-Based Matting Agents Market
Additives
Europe Fuel Additives Market
Additives
Fluoropolymer Additives Market
Additives
Sorbitan Oleate Market
Additives
Material Shrinkage-reducing Agents Market
Additives
Sorbitan Tristearate Market
Additives
Alkyl Acetates Market
Additives
Tricalcium Citrate Market
Additives
Cosmetic Grade Color Additives Market
Additives
FD and C Lakes Market