
 North America Polyphenylene Sulfide Compounds Market | 2026-2036
North America Polyphenylene Sulfide Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyphenylene Sulfide Compounds Market Intelligence
Polymer formulation around high-temperature thermoplastics is fragmenting as OEMs redesign powertrain and electronic housing architectures. Celanese Corporation leverages its captive polymerization capacity to anchor supply commitments across multiple automotive platforms. Solvay specializes in filled-grade compounds that sustain dielectric performance under thermal cycling. RTP Company competes through custom compounding services that position it between commodity resin suppliers and tier-one molders.
Polyphenylene sulfide compounds are semi-crystalline thermoplastic resins characterized by melting points near 285°C and inherent flame resistance without halogenated additives, serving primarily as metal replacements in corrosive, thermally stressed environments. Filled grades dominate volume flows as glass fiber and mineral reinforcements extend structural performance for under-hood brackets and connector housings. The automotive application segment leads absolute consumption while electronics represents the fastest-expanding margin pool as miniaturization intensifies thermal management requirements. Pellet form controls distribution logistics due to compatibility with standard injection molding feed systems.
EPA regulations under the Clean Air Act and NHTSA Corporate Average Fuel Economy standards are elevating demand for lightweight, chemically resistant polymers that enable component consolidation. The US Occupational Safety and Health Administration maintains workplace exposure thresholds that shape compounding facility investments and operational protocols. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and federal Buy America content rules that could redirect supply chain configurations across the US, Canada, and Mexico.
Market Dynamics
Automotive electrification is compressing thermal management material specifications across North American supply chains, forcing resin compounders to recalibrate glass loading ratios and dielectric stability thresholds for battery module housings and power electronics enclosures.
Growth Catalysts
- EPA Clean Air Act Amendments:Tier 3 emissions standards mandate lighter powertrain components, accelerating metal-to-polymer substitution in exhaust gas recirculation valves and charge air coolers across US vehicle platforms.
- Connector miniaturization in 5G infrastructure:Base station antenna arrays demand thermally stable dielectric housings that maintain dimensional integrity through reflow soldering cycles, pulling filled PPS grades into telecommunications supply chains.
- Southeastern US manufacturing corridor concentration:Tier-one automotive suppliers clustered in Tennessee, South Carolina, and Alabama generate localized resin demand that reduces logistics costs and enables just-in-time compounding partnerships.
Market Restraints
- Para-dichlorobenzene feedstock volatility:PPS polymerization relies on chlorinated aromatic precursors whose pricing tracks benzene and chlorine market swings, compressing compounder margins during upstream petrochemical disruptions.
- Japanese and Chinese polymer supply concentration:Captive resin production by Toray, DIC, and Chinese state-affiliated chemical groups limits North American compounders' backward integration options and creates single-source vulnerability for base polymer procurement.
- Polyetherimide and polyamide 46 substitution:Sulfone-based and high-heat aliphatic polyamides compete for connector and sensor housing applications where PPS brittleness requires impact modification that degrades dielectric performance.
Strategic Opportunities
- Mexican automotive assembly expansion:OEM capacity additions in Guanajuato and Nuevo León create geographic white space for regional compounding facilities serving USMCA-qualified component supply chains.
- Electric vehicle thermal interface materials:Gap-filling compounds between battery cells and cooling plates represent an emerging application segment where mineral-filled PPS grades can displace silicone and epoxy systems.
- US Inflation Reduction Act domestic content credits:Battery and EV assembly incentives reward North American-sourced materials, creating procurement preference structures for US and Mexican compounders over Asian resin imports.
Industry Challenges
- Specialized polymer processing expertise scarcity:Compounding high-load glass fiber grades requires extrusion operators trained in moisture control and shear management protocols that differ from commodity thermoplastics, constraining workforce scalability.
- UL 94 V-0 recertification timelines:Reformulated compounds for new automotive platforms face extended flame resistance testing cycles that delay customer qualification and lock working capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyphenylene Sulfide Compounds Market |
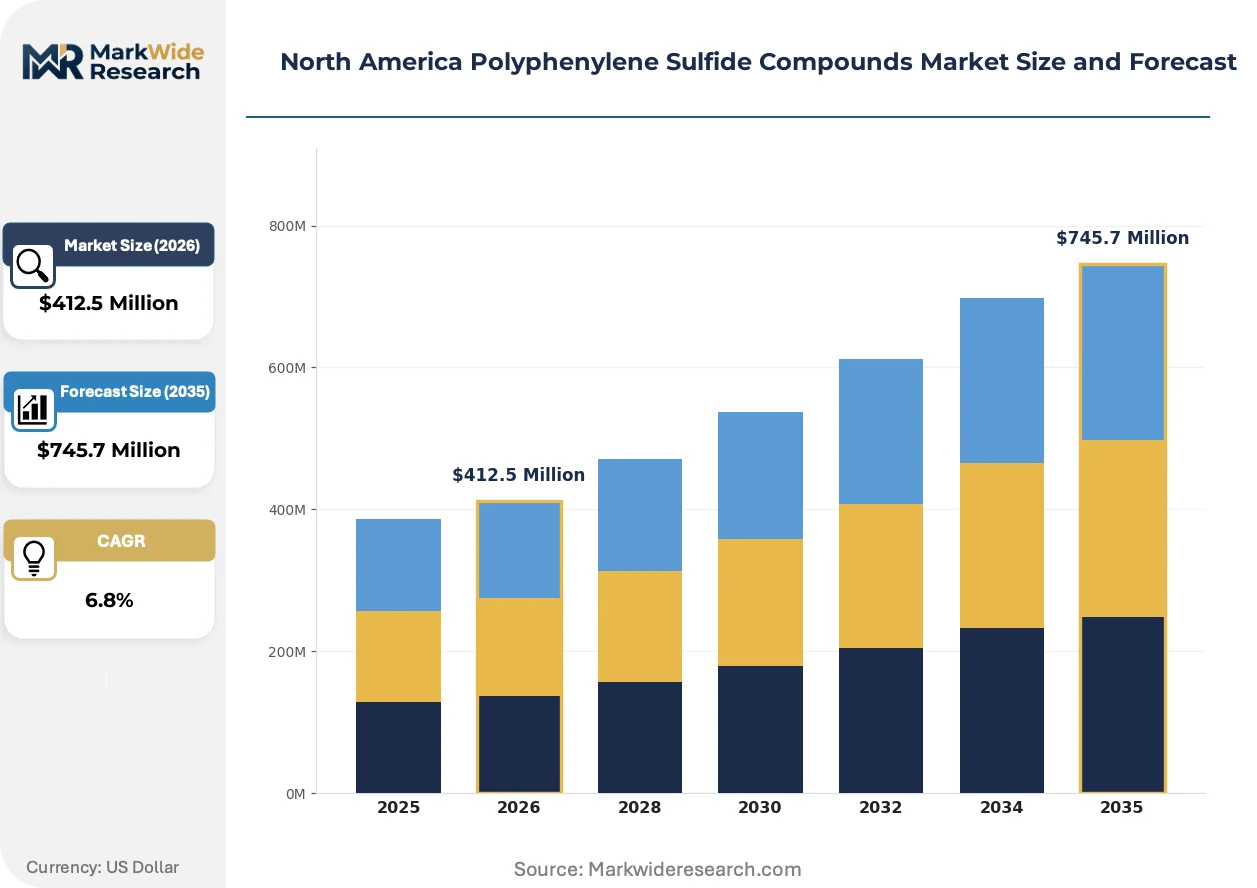
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfilled, Filled, Blends, Composites Application: Automotive, Electronics, Industrial, Aerospace End User: Manufacturers, OEMs, Retailers, Distributors Form: Pellets, Granules, Powders, Sheets |
| Companies Covered | Celanese Corporation, Toray Industries, DIC Corporation, Solvay, SABIC, Chevron Phillips Chemical, RTP Company, Tosoh Corporation, Fortron Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyphenylene Sulfide Compounds Market Strategic Shifts & Innovations
Material science convergence around electrification thermal loads is fragmenting traditional polymer selection hierarchies, with compounders now engineering for simultaneous dielectric, mechanical, and chemical resistance performance rather than optimizing single properties.
Long-fiber thermoplastic PPS composites are collapsing the performance gap between injection-molded housings and thermoset structural composites in battery tray applications. Automotive OEMs in Michigan and California are qualifying these grades for load-bearing subframes previously reserved for aluminum stampings. The technology is collapsing tier boundaries between resin suppliers and composite fabricators as compounders invest in pultrusion and direct-LFT capabilities.
NHTSA Corporate Average Fuel Economy standards are tightening material density thresholds for under-hood components, elevating glass fiber loading optimization from cost management to compliance engineering. Compounders now model fiber length distribution against creep performance to document weight reduction credits for OEM regulatory filings. The regulatory pressure is most acute in light truck platforms where engine downsizing increases thermal stress on intake manifolds and water pump housings.
Consolidated procurement by tier-one automotive suppliers is compressing compounder margins while demanding technical service co-location. Buyers in the Detroit and Stuttgart supplier ecosystems now require resin partners to maintain application engineering staff at vehicle development centers, shifting competitive advantage from formulation IP to embedded customer support. The behavioral shift is visible in southeastern US supplier parks where compounders lease satellite technical centers adjacent to major molding operations.
North America Polyphenylene Sulfide Compounds Market Segmentation
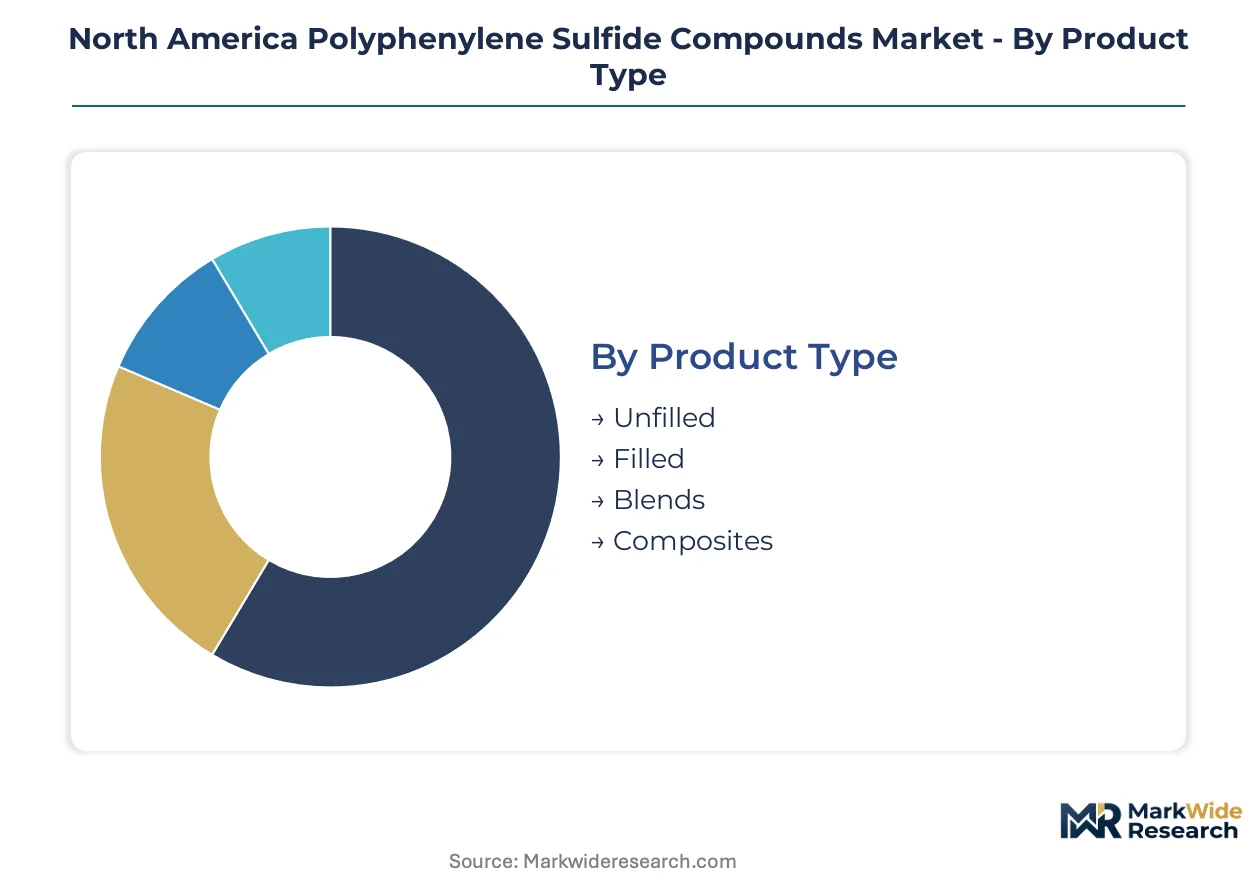
Polyphenylene sulfide compounds fragment across multiple technical dimensions that shape service intensity and formulation complexity. Each segment carries distinct thermal management requirements and regulatory exposure profiles that determine compounding economics.
Product Type:
After-sales technical service intensity escalates sharply with filler loading complexity and composite architecture sophistication.
- Filled:Glass fiber and mineral-reinforced grades dominate volume flows through extended structural performance for under-hood brackets and connector housings. Demand concentrates in the southeastern United States automotive corridor where EPA emissions standards drive metal-to-polymer substitution in charge air coolers and exhaust gas recirculation valves.
- Composites:Long-fiber thermoplastic PPS formulations are collapsing performance gaps between injection-molded housings and thermoset structural composites in battery tray applications. Michigan and California OEMs qualify these grades for load-bearing subframes previously reserved for aluminum stampings, pulling compounders into pultrusion capability investments.
- Unfilled:Virgin resin grades serve specialized dielectric applications requiring maximum purity without reinforcement-induced conductivity.
- Blends:Alloy formulations with polyphenylene oxide or liquid crystal polymers tune impact resistance and dimensional stability for hybrid component designs.
Filled grades hold the largest share; momentum sits with composites.
Application:
Cost tier stratification separates commodity under-hood components from premium electronics-grade formulations commanding formulation premiums.
- Automotive:Electrification is compressing thermal management specifications across North American supply chains, forcing recalibration of glass loading ratios and dielectric stability thresholds for battery module housings. NHTSA fuel economy rules elevate material density optimization from cost management to compliance engineering.
- Electronics:Connector miniaturization in 5G infrastructure demands thermally stable dielectric housings maintaining dimensional integrity through reflow soldering cycles. Base station antenna arrays in Texas and California pull filled PPS grades into telecommunications supply chains with accelerating specification velocity.
- Industrial:Chemical processing equipment and pump housings exploit inherent flame resistance without halogenated additives in corrosive environments.
- Aerospace:Interior compartment applications leverage low smoke toxicity profiles under FAA flammability protocols for cabin pressure environments.
Automotive commands absolute volume; electronics climbs the fastest on margin expansion.
End User:
Procurement scale and technical integration depth determine formulation partnership structures across the value chain.
- OEMs:Direct vehicle platform engineering teams specify resin grades for regulatory compliance documentation, particularly NHTSA weight reduction credits in light truck powertrain architectures.
- Manufacturers:Tier-one molding operations clustered in Tennessee and South Carolina generate localized demand enabling just-in-time compounding partnerships with embedded technical service.
- Distributors:Regional logistics networks manage pellet inventory for smaller injection molding operations lacking direct resin supplier relationships.
- Retailers:Limited presence in specialized industrial maintenance and repair segments for replacement component fabrication.
OEMs anchor specification authority; manufacturers gain share through supplier park consolidation.
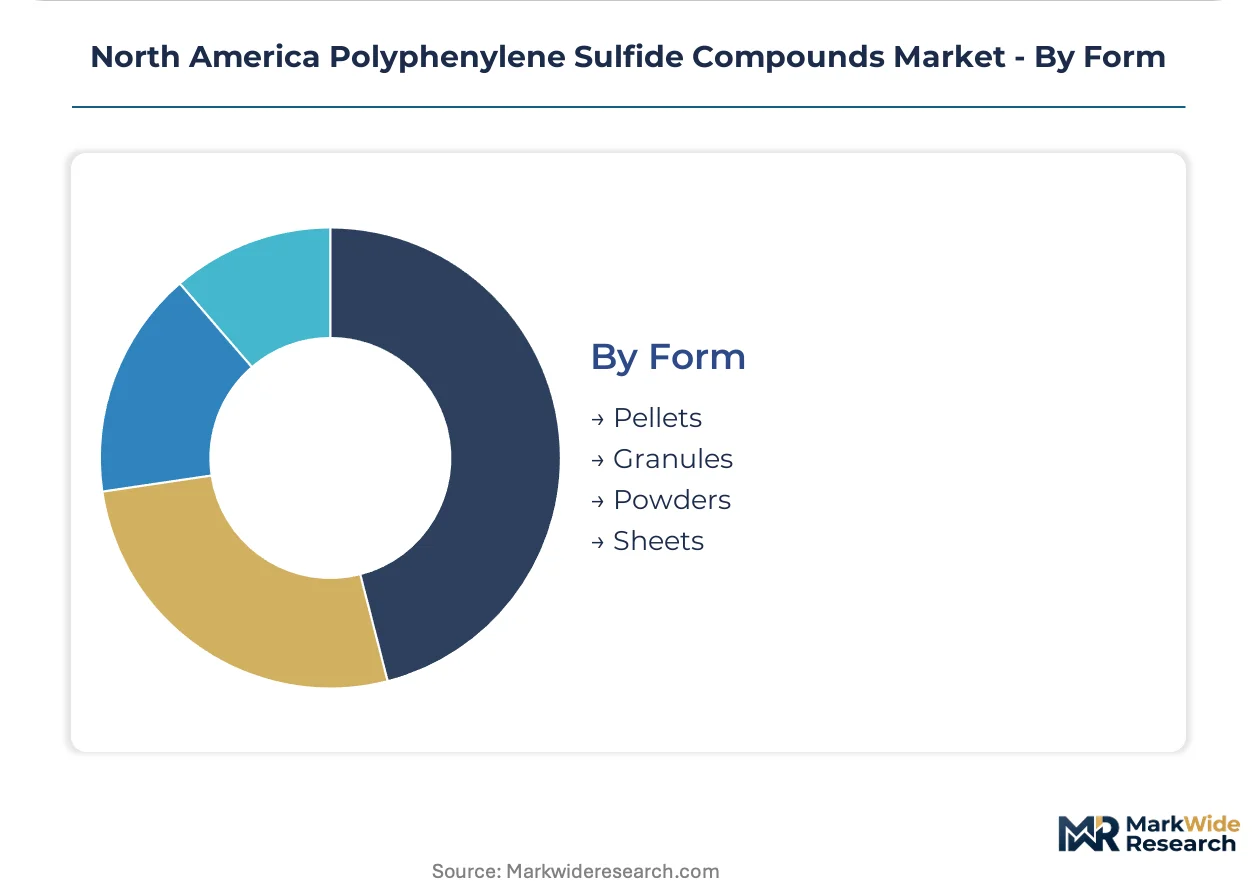
Form:
Supply chain configuration and processing equipment compatibility lock in pellet dominance despite emerging powder applications.
- Pellets:Standard cylindrical feedstock controls distribution logistics through compatibility with conventional injection molding systems across North American automotive supplier parks.
- Granules:Irregular particulate forms serve compression molding and select extrusion applications in industrial equipment fabrication.
- Powders:Fine particulate grades enable coating applications and rotational molding for complex geometric components in chemical processing infrastructure.
- Sheets:Thermoformable plate stock targets prototype development and limited-series aerospace interior panel production.
Pellets dominate logistics infrastructure; powders gain traction in coating substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian resin compounders export PPS formulations to tier-one automotive suppliers clustered in Michigan and Ohio, while Mexican assembly plants receive USMCA-qualified material flows from Tennessee and South Carolina compounding facilities.
United States
EPA Tier 3 emissions standards and NHTSA fuel economy rules compress thermal management specifications for under-hood components. The US Inflation Reduction Act domestic content credits reward North American-sourced materials for battery and EV assembly. Tennessee, South Carolina, and Alabama host concentrated tier-one supplier parks where just-in-time compounding partnerships reduce logistics costs.
Mexico
OEM capacity additions in Guanajuato and Nuevo León create geographic white space for regional compounding facilities serving USMCA-qualified supply chains. Mexican automotive assembly expansion pulls resin demand southward from traditional southeastern US manufacturing corridors. Querétaro and San Luis Potosí industrial zones attract compounder satellite operations to support German and Japanese transplant assembly networks.
Canada
Health Canada workplace exposure thresholds shape compounding facility investments and operational protocols in Ontario and Quebec chemical corridors. Canadian polymer distributors manage pellet inventory for smaller injection molding operations lacking direct resin supplier relationships. The Windsor-Toronto corridor maintains specialized logistics for automotive-grade PPS flowing to Detroit-area vehicle platforms.
North America Polyphenylene Sulfide Compounds Market Key Industry Players
Channel-controlling players compete with product-specialist players across formulation tiers. The vendor base concentrates around captive polymerization capacity and custom compounding services. Three archetypes dominate: integrated resin-compounders with backward polymerization control, independent compounders serving niche specification markets, and regional distributors managing logistics for smaller molders. Competitive moves center on geographic co-location with tier-one automotive clusters and technical service embedding at vehicle development centers.
Within the integrated-compounder tier, Celanese Corporation and Solvay exemplify archetypes anchoring supply commitments through captive production assets. RTP Company occupies a position between commodity resin suppliers and tier-one molders through custom formulation services. Toray Industries and DIC Corporation represent Japanese polymer producers whose captive resin supply shapes North American compounder procurement vulnerability.
| Leading Market Players |
|---|
| Celanese Corporation |
| Toray Industries |
| DIC Corporation |
| Solvay |
| SABIC |
| Chevron Phillips Chemical |
| RTP Company |
| Tosoh Corporation |
| Fortron Industries |
| Others |
Cost & Logistics Intelligence
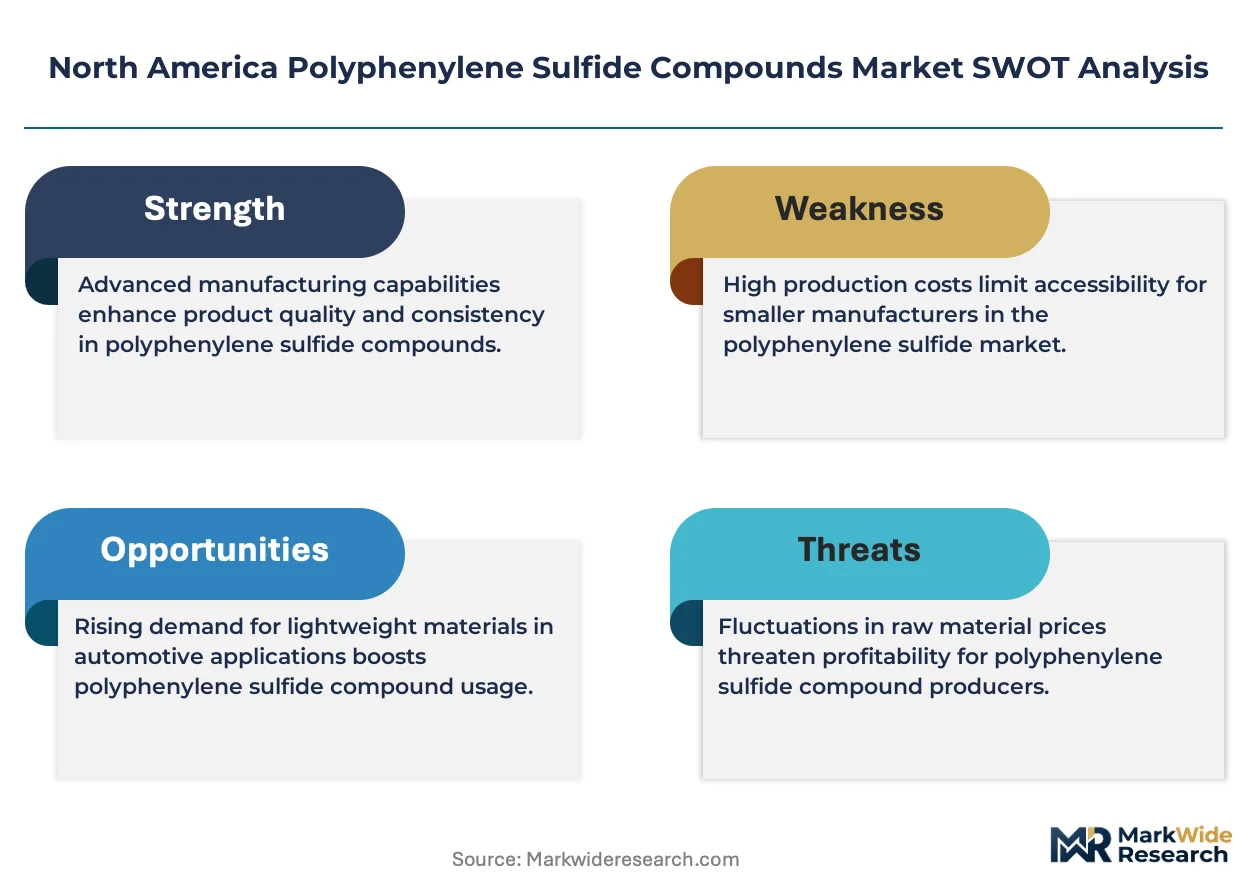
Single-source dependency on Japanese and Chinese para-dichlorobenzene polymerization capacity compresses margin recovery for North American compounders while simultaneously forcing three-tier pricing stratification across automotive, electronics, and industrial grades. This feedstock concentration amplifies tariff exposure on base resin imports and determines whether compounders absorb volatility or pass through cost escalations to tier-one molders.
Pricing Analysis
Technology-generation pricing gaps separate legacy unfilled virgin grades from next-generation long-fiber thermoplastic composites and current-generation glass-filled formulations optimized for battery thermal management. Three-tier pricing structure across premium, standard, and economy levels reflects UL 94 V-0 certification status, glass loading ratios, and embedded technical service intensity. Cost compression in standard unfilled grades intensifies because Chinese state-affiliated resin producers are expanding export volumes into Mexican automotive corridors. Tier-one automotive OEMs exhibit lowest price sensitivity due to NHTSA compliance documentation requirements, while industrial distributors serving smaller molders face acute margin pressure.
Supply Chain Analysis
Extended payment terms from Detroit-area automotive OEMs now stretch to 90-120 days, forcing compounders to utilize supply-chain finance facilities anchored by receivables from tier-one suppliers. Geographic supply concentration centers on Japan, China, and limited captive US polymerization at Celanese, with base resin flows drawing from Toray, DIC, and emerging Chinese state chemical groups. Raw material dependencies rest on para-dichlorobenzene precursors, chlorinated aromatic feedstocks, and specialized glass fiber reinforcements from Owens Corning and Johns Manville. Single-source vulnerability on polymer imports creates structural risk exposure to USMCA qualification disputes and potential tariff escalations. Distribution runs through southeastern US supplier parks where satellite compounding operations enable just-in-time pellet delivery to Tennessee and South Carolina molding facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American polyphenylene sulfide compounds sit in early-cycle expansion as electric vehicle thermal management specifications displace legacy metal stampings and silicone gap-fillers. Electrification-driven material substitution represents the primary penetration tailwind accelerating specification velocity across automotive platforms.
For Market Incumbents: Build captive polymerization moats through backward integration into para-dichlorobenzene supply or long-term offtake agreements with Japanese resin producers that lock in USMCA-qualified content for IRA credit eligibility. Celanese and Solvay should expand technical service co-location in Guanajuato supplier parks to defend against Chinese compounders establishing Mexican tolling operations. Threats include polyetherimide substitution in connector housings and Chinese state-affiliated resin producers capturing battery tray specifications through predatory pricing on long-fiber grades. For New Entrants and Emerging Players: Build out regional compounding capacity in Querétaro and San Luis Potosí to serve German and Japanese transplant assembly networks with USMCA-qualified formulations. The most penetrable white space sits in electric vehicle thermal interface materials where mineral-filled PPS grades can displace epoxy systems in cell-to-plate gap filling. Target aerospace interior applications through FAA flammability certification partnerships with tier-two fabricators seeking alternatives to thermoset phenolics. For Investors and Strategic Acquirers: The market sits at a specification-lock-in phase that favors compounders with embedded OEM technical relationships and captive resin supply. Long-term viability over the five-to-ten year window hinges on IRA domestic content credit durability and NHTSA fuel economy standard stringency. Acquisition targets should display pultrusion capability for long-fiber thermoplastic production and established supplier park presence in Tennessee or South Carolina. Monitor EPA Tier 3 enforcement consistency and Chinese resin export licensing restrictions as inflection indicators for margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymerization | Celanese captive production reduces Toray/DIC dependency and secures IRA credit eligibility. |
| Long-term Supply Agreement | Tier-one automotive suppliers lock in southeastern US compounding capacity for platform standardization. |
| Geographic Manufacturing Footprint | Querétaro satellite operations capture Guanajuato EV assembly expansion with USMCA-qualified supply. |
| Joint Venture | Pultrusion capability partnerships collapse tier boundaries between resin suppliers and composite fabricators. |
| Green Manufacturing Transition | Halogen-free flame resistance aligns with EPA Clean Air Act and California air quality regulations. |
Research Approach
The analysis maps filled grades, unfilled resins, long-fiber composites, and alloy blends, each validated through compounder technical directors, tier-one automotive procurement leads, and electronics connector OEMs. Primary interviews with plant managers at Tennessee and South Carolina supplier parks, distribution channel partners managing pellet logistics, and regulatory affairs specialists tracking EPA and NHTSA rulemaking combined with secondary validation from SEC 10-K filings, American Chemistry Council resin trade data, and customs import records. Bottom-up volume modeling triangulated against top-down OEM platform content assumptions.
Assumption sets held fixed regulatory stringency trajectories for EPA Tier 3 and NHTSA CAFE standards while varying electric vehicle penetration rates and Chinese resin export licensing scenarios across the projection horizon. Segmentation dimensions modeled include product architecture, application thermal load, end-user procurement scale, and regional production cluster. CAGRs derived from regression analysis against automotive production forecasts and electronics miniaturization indices, with cross-reference to polymer substitution elasticity in metal-to-plastic conversion applications.
Practitioners should monitor feedstock volatility in benzene-chlorine markets, IRA credit rulemaking on domestic content thresholds, and Japanese polymer producer capacity allocation decisions for early signals of margin compression or specification loss. Forecasts reflect assumptions on regulatory enforcement consistency and USMCA qualification durability. Macroeconomic deviation, regulatory rollback, or breakthrough substitution by polyetherimide or polyamide 46 would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Solketal Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Propoxylates Market
Specialty Compounds
China Collagen Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
Thionyl Chloride Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Collagen Hydrolysates Market