
 Epoxy Resin Market | 2026-2036
Epoxy Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Resin Market Intelligence
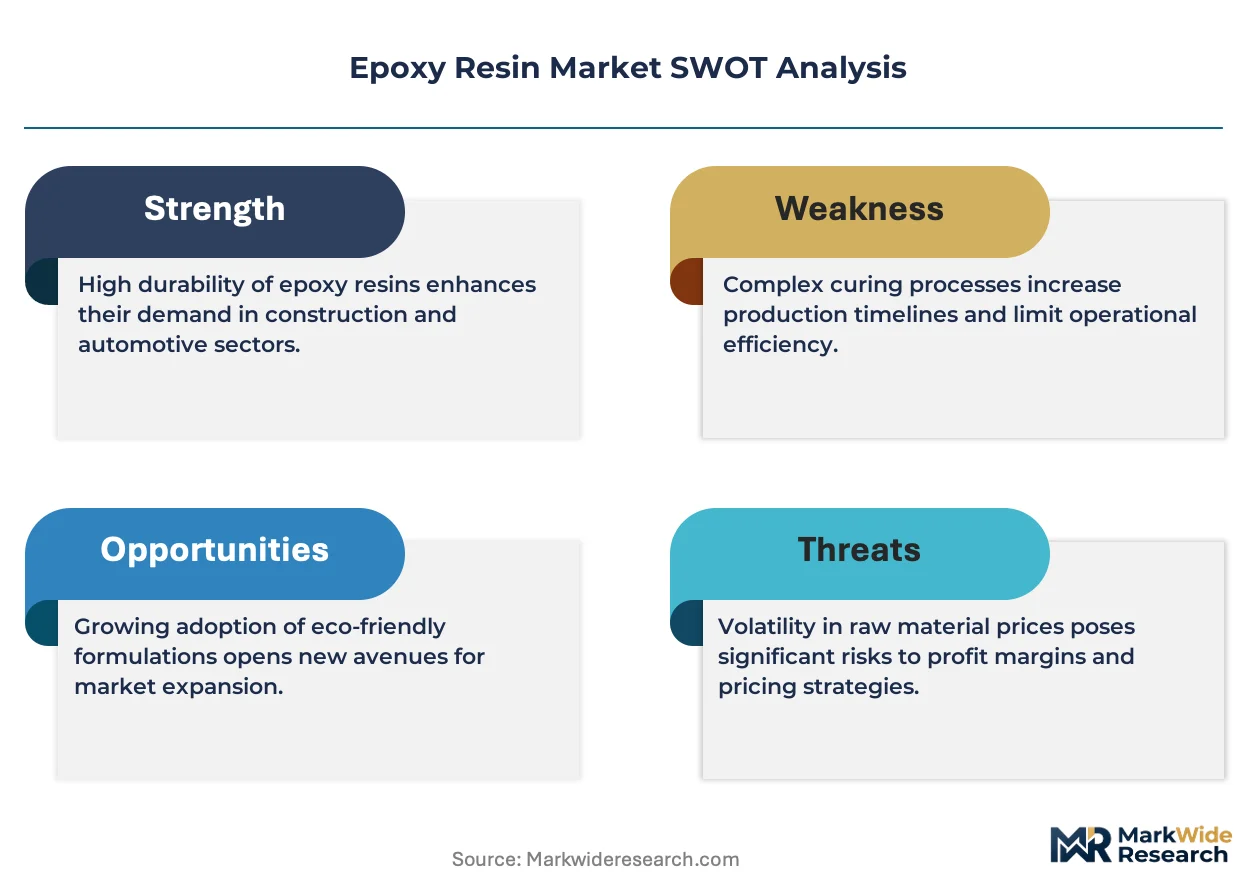
Modular formulation systems is pivoting how buyers configure epoxy purchases across industrial tiers. Huntsman Corporation leverages its specialty chemicals portfolio to anchor premium segments in aerospace-grade formulations. Kukdo Chemical competes through backward integration into epichlorohydrin production across its Korean manufacturing base. BASF SE differentiates via catalyst technology that accelerates cure cycles for automotive OEM lines.
Epoxy resin comprises thermosetting polymers formed through reaction of epichlorohydrin with bisphenol A or novolac precursors, yielding cross-linked structures with tensile strength exceeding 80 MPa and chemical resistance critical for protective coatings and structural composites. Bisphenol A grades dominate volume flows across construction and marine applications where cost-performance thresholds favor established chemistry. Liquid epoxy technology leads growth in wind energy blade infusion processes where low viscosity enables fiber wet-out across 80-meter-plus structures. Solid epoxy occupies mature coating powder segments where storage stability and handling ease offset slower cure profiles.
EPA regulates epoxy manufacturing emissions under Clean Air Act Title V permitting while OSHA enforces worker exposure limits for epichlorohydrin at 2 ppm TWA across US production facilities. REACH registration requirements in Europe mandate full toxicological dossiers for bisphenol A derivatives, pushing reformulation toward glycidyl alternatives with improved environmental profiles. China's MEE implements dual carbon goals that tighten energy intensity benchmarks for epichlorohydrin crackers serving domestic resin plants. Stakeholders must monitor feedstock cost divergence between Asian and Western bisphenol A supply chains while positioning formulation portfolios for evolving VOC thresholds.
Market Dynamics
Wind turbine blade scaling beyond 80 meters is compressing cure-cycle requirements and forcing reformulation of liquid epoxy systems for vacuum infusion processes. This dimensional pressure is reshaping supplier qualification protocols across the value chain.
Growth Catalysts
- EU Green Deal VOC thresholds:REACH-mandated volatile organic compound reductions are accelerating glycidyl-based reformulation investments across European coating producers seeking compliance headroom.
- China's dual carbon goals:MEE energy-intensity benchmarks for epichlorohydrin crackers are consolidating domestic resin capacity around integrated producers with captive feedstock.
- Blade infusion automation:Robotic fiber placement systems in wind energy manufacturing are demanding ultra-low viscosity epoxy grades that enable consistent wet-out across complex geometries.
Market Restraints
- Bisphenol A feedstock concentration:Asian supply chain dominance by Sinopec and regional petrochemical complexes creates price volatility exposure for Western formulators lacking backward integration.
- Epichlorohydrin emission controls:EPA Title V permitting and OSHA 2 ppm TWA exposure limits are constraining capacity expansion at US manufacturing facilities.
- Thermoset recyclability limitation:Cross-linked polymer structures resist mechanical or chemical breakdown, blocking circular economy participation and threatening long-term offtake from sustainability-mandated buyers.
Strategic Opportunities
- India infrastructure buildout:National highway and metro rail expansion programs are creating unserved demand for high-performance protective coatings in corrosion-intensive environments.
- Bio-based epichlorohydrin convergence:Glycerol-to-epichlorohydrin process technology is intersecting with renewable feedstock certification schemes to unlock premium positioning.
- Automotive lightweighting mandates:OEM structural composite targets are pulling thermoset adoption into chassis and battery enclosure applications previously dominated by metals.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in rheology control and cure kinetics is concentrating at legacy producers, constraining new entrant scale-up.
- Multi-regulatory dossier burden:Parallel REACH, EPA, and GB standard registration requirements are extending product launch timelines and inflating compliance fixed costs.
- Legacy coating system interoperability:Epoxy-amine cure profiles often conflict with existing shop-floor equipment calibrated for polyester or vinyl ester processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Resin Market |
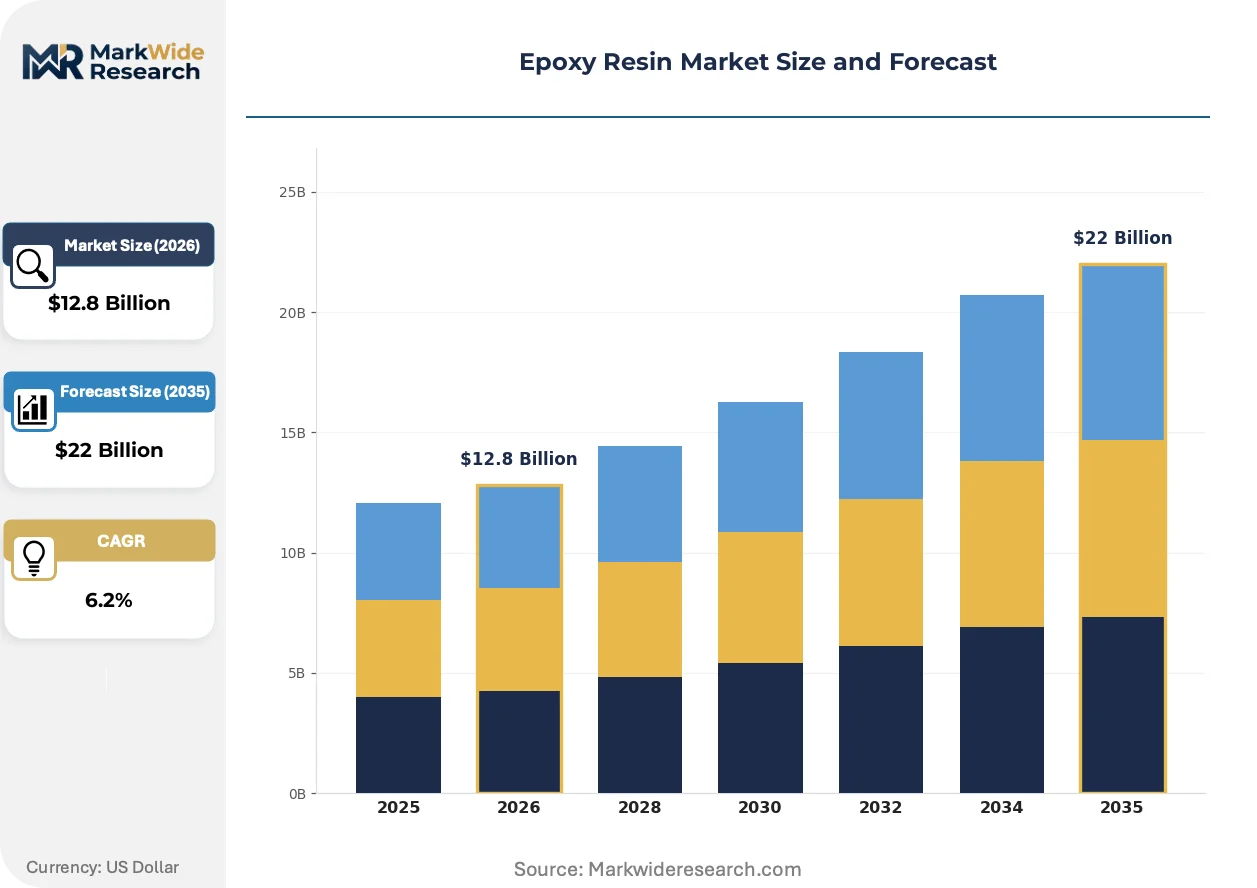
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphenol A, Novolac, Glycidyl, Others Application: Aerospace, Automotive, Electronics, Construction End User: Aerospace Manufacturers, Automotive Suppliers, Electronics Companies, Construction Firms Technology: Liquid Epoxy, Solid Epoxy, Powder Epoxy, Resin Transfer Molding |
| Companies Covered | 3M, Olin Corporation, Huntsman Corporation, Sinopec Corporation, Kukdo Chemical Co., Ltd., Nan Ya Plastics Corporation, DIC Corporation, Westlake Epoxy, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Resin Market Strategic Shifts & Innovations
Formulation science is pivoting toward modular systems that let industrial buyers customize cure speed and mechanical properties without switching base chemistries. This configurability is compressing SKU proliferation while expanding addressable application scope.
Digital formulation platforms are decentralizing technical service delivery across the epoxy value chain. Regional distributors now access cloud-based cure simulation tools previously reserved for manufacturer laboratories. Wind blade fabricators in Denmark and automotive OEMs in Germany are configuring resin systems remotely, collapsing the traditional field-support dependency that concentrated purchasing power at integrated suppliers.
REACH registration dossier requirements for bisphenol A derivatives are tightening toxicological disclosure standards across European formulations. ECHA's expanded endpoint testing mandates are pushing producers toward glycidyl novolac alternatives with more favorable environmental fate profiles. Coating applicators in France and marine yards in Italy are reformulating ahead of 2026 sunset clauses to avoid supply disruption.
Specification-driven procurement is compressing supplier switching cycles in aerospace and automotive tiers. Tier-1 composite laminators now mandate dual-source qualification for epoxy prepregs, unbundling historical sole-source relationships with established chemical suppliers. This fragmentation is most visible in Germany's automotive supply basin, where OEMs are forcing resin diversification to mitigate concentration risk.
Epoxy Resin Market Segmentation
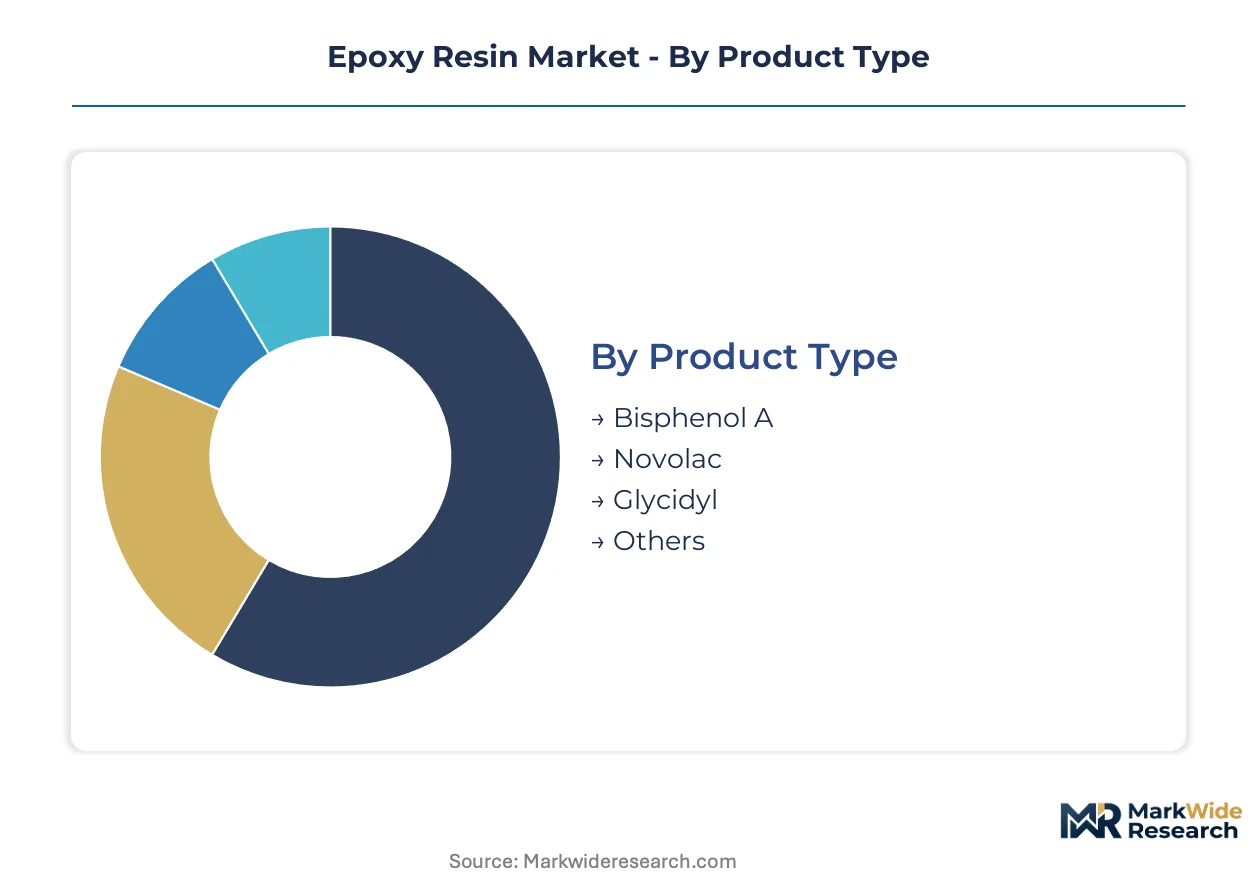
Epoxy resin purchasing decisions pivot on performance specifications that vary sharply across end-use environments. Buyers in wind energy prioritize viscosity and cure speed, while aerospace procurement emphasizes thermal stability and traceability. Understanding these segment boundaries clarifies where formulation investments concentrate and where commoditization pressures mount.
Product Type:
Cost-performance thresholds determine which chemistry dominates in each application tier, with feedstock availability and regulatory pressure reshuffling historical preferences.
- Bisphenol A:Thermosetting polymers formed through reaction of epichlorohydrin with bisphenol A precursors, yielding cross-linked structures with tensile strength exceeding 80 MPa. Construction and marine applications in China concentrate demand where Sinopec's captive feedstock supply insulates domestic formulators from import volatility.
- Novolac:Higher functionality epoxies with elevated cross-link density and superior chemical resistance against acids and solvents. Chemical processing facilities in Germany specify novolac grades for tank linings and secondary containment where regulatory exposure limits for bisphenol A drive specification shifts.
- Glycidyl:Alternatives with improved environmental fate profiles gaining traction under REACH registration pressures.
- Others:Specialty grades including aliphatic and cycloaliphatic variants for UV-stable coating applications.
Volume sits with Bisphenol A; growth tilts toward Glycidyl as ECHA sunset clauses approach.
Application:
End-use environments impose distinct certification burdens that fragment supplier qualification pathways and compress switching flexibility.
- Aerospace:Prepregs and film adhesives requiring flame-retardant ratings and full batch traceability. OEMs in Toulouse and Hamburg mandate dual-source qualification, unbundling historical sole-source relationships and forcing resin diversification onto tier-1 laminators.
- Automotive:Structural composites for chassis and battery enclosures where OEM lightweighting mandates pull thermoset adoption from metal-dominated applications. German automotive supply basins specify accelerated cure cycles that BASF's catalyst technology addresses.
- Electronics:Encapsulation and potting compounds protecting semiconductor packages from moisture and thermal cycling.
- Construction:Protective coatings and flooring systems where corrosion resistance determines specification in infrastructure buildouts.
Procurement concentration clusters in Automotive; specification complexity peaks in Aerospace.
End User:
Organizational scale and technical capability determine whether buyers access modular formulation systems or remain locked into legacy supply arrangements.
- Aerospace Manufacturers:Airbus and Boeing tier systems demand full toxicological dossiers and REACH-compliant material declarations. Qualification timelines extending 18-24 months protect incumbents with established regulatory dossiers.
- Automotive Suppliers:Tier-1 composite laminators configure resin systems remotely through digital formulation platforms, collapsing traditional field-support dependencies.
- Electronics Companies:Semiconductor packaging houses specifying low-ionics grades for flip-chip underfill applications.
- Construction Firms:Regional contractors purchasing through distributor channels with limited technical service access.
Margin capture favors Aerospace Manufacturers; volume scaling aligns with Automotive Suppliers.
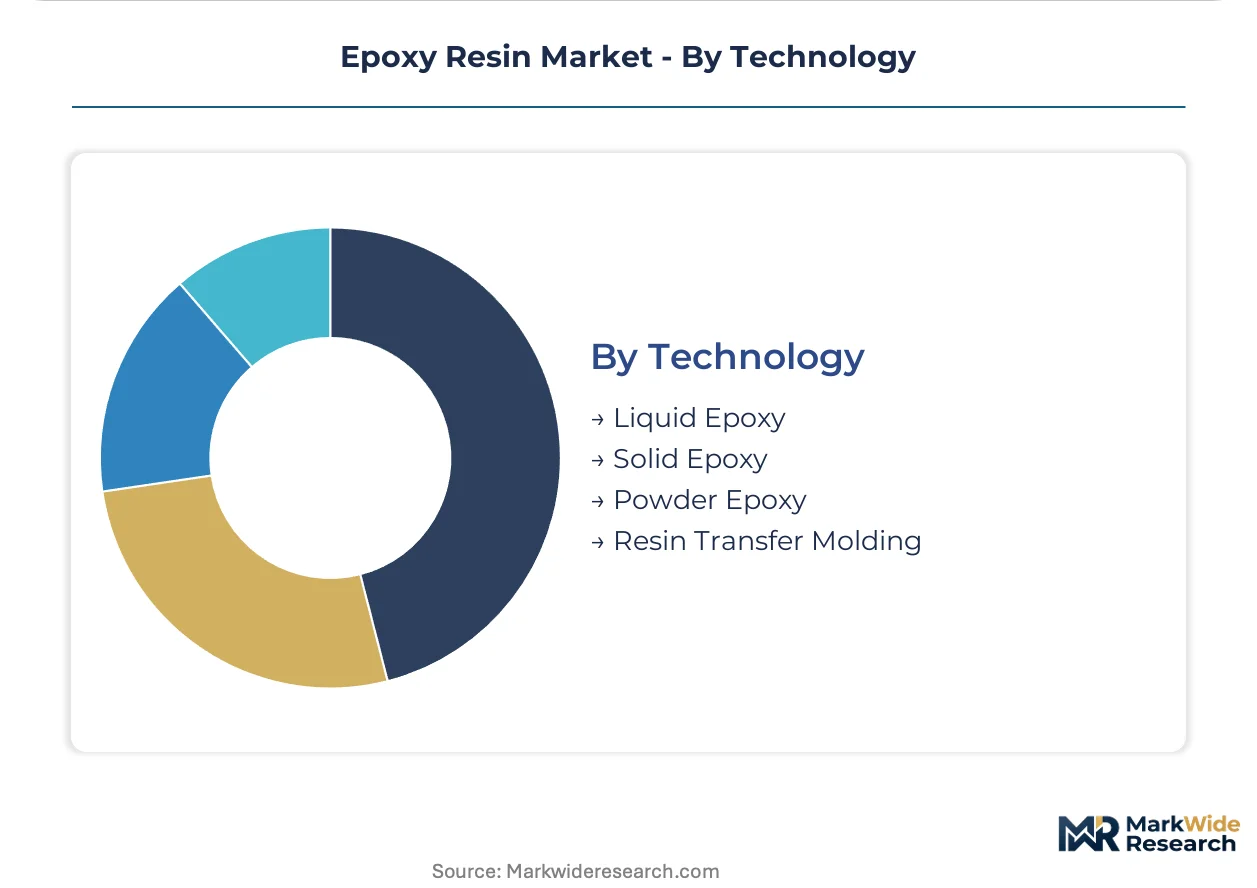
Technology:
Processing method dictates viscosity requirements, cure kinetics, and capital equipment compatibility that constrain formulation choices.
- Liquid Epoxy:Low-viscosity systems enabling fiber wet-out across 80-meter-plus wind turbine blade structures. Vacuum infusion processes in Denmark and Spain specify ultra-low viscosity grades that robotic placement systems demand for consistent wet-out across complex geometries.
- Solid Epoxy:Storage-stable forms dominating powder coating segments where handling ease offsets slower cure profiles. Mature industrial coating applications in Italy and France favor solid grades for shop-floor simplicity.
- Powder Epoxy:Zero-VOC formulations gaining share under EU Green Deal thresholds for industrial finishing.
- Resin Transfer Molding:Closed-mold processes for automotive structural components requiring precise flow control and rapid cycle times.
Application breadth is widest in Liquid Epoxy; regulatory tailwinds favor Powder Epoxy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in East Asian petrochemical corridors while consumption spreads across manufacturing clusters in Europe and North America. This geographic split creates divergent feedstock cost exposures and regulatory compliance burdens. The analysis maps five national markets where these dynamics play out distinctly.
China
Wind turbine blade fabrication and electronics encapsulation consume the majority of domestic epoxy output. MEE dual carbon goals tighten energy-intensity benchmarks for epichlorohydrin crackers serving resin plants. The Yangtze River Delta hosts Sinopec's integrated bisphenol A complexes that supply captive feedstock to downstream formulators.
Germany
Automotive OEM lightweighting mandates and chemical processing infrastructure drive specification-grade demand. ECHA REACH registration requirements mandate full toxicological dossiers for bisphenol A derivatives, accelerating glycidyl novolac adoption. The North Rhine-Westphalia chemical belt concentrates formulation R&D and automotive supplier qualification activity.
United States
Aerospace prepregs and protective coatings for infrastructure corrosion control anchor consumption. EPA Clean Air Act Title V permitting and OSHA's 2 ppm TWA exposure limits for epichlorohydrin constrain domestic capacity expansion. The Gulf Coast petrochemical corridor houses legacy epichlorohydrin production serving regional resin manufacturers.
South Korea
Electronics potting compounds and marine coatings dominate end-use profiles. Kukdo Chemical's backward integration into epichlorohydrin production exemplifies the integrated model prevalent among domestic producers. The Ulsan industrial complex clusters petrochemical feedstock production with downstream resin formulation.
India
National highway expansion and metro rail construction programs generate unserved demand for high-performance protective coatings. BIS standards for construction chemicals create certification pathways for imported and domestic formulations. The Gujarat chemical corridor attracts investment in epoxy hardener and derivative manufacturing.
Epoxy Resin Market Key Industry Players
The competitive structure tilts toward integrated petrochemical conglomerates with captive feedstock supply. Three distinct tiers operate: global diversified chemical majors with aerospace and automotive qualification dossiers; Asian national champions controlling bisphenol A and epichlorohydrin value chains; and regional formulators serving construction and industrial coating segments through distributor networks. Capacity expansion and strategic partnerships with wind blade fabricators represent the dominant competitive moves as blade scaling accelerates.
Within the integrated chemical major tier, Huntsman Corporation and BASF SE exemplify players with specialty chemicals portfolios anchoring premium aerospace and automotive segments. Among Asian national champions, Sinopec Corporation occupies a position reflecting captive feedstock dominance in the world's largest consumption market. Kukdo Chemical Co., Ltd. represents the Korean integrated model with backward control over epichlorohydrin supply. These three archetypes illustrate how feedstock access, regulatory dossier depth, and end-use qualification timelines stratify competitive position.
| Leading Market Players |
|---|
| 3M |
| Olin Corporation |
| Huntsman Corporation |
| Sinopec Corporation |
| Kukdo Chemical Co., Ltd. |
| Nan Ya Plastics Corporation |
| DIC Corporation |
| Westlake Epoxy |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Wind blade fabricators demanding ultra-low viscosity grades for 80-meter-plus structures are forcing reformulation investments that compress margins across non-integrated formulators. This specification pressure concentrates purchasing power at suppliers with captive epichlorohydrin and bisphenol A supply, amplifying price divergence between integrated majors and regional compounders.
Pricing Analysis
Cost-down pressure on aerospace-grade prepregs accelerates as tier-1 laminators mandate dual-source qualification, unbundling historical sole-source premiums. Pricing stratifies across aerospace-certified, automotive-specified, and industrial-economy tiers, with certification grade and volume scale as primary differentiation drivers. Margin tightening in construction-grade formulations reflects Sinopec's feedstock dominance in Asian supply. Automotive OEMs exhibit lowest price sensitivity due to lightweighting mandates; regional construction contractors face highest sensitivity given distributor channel economics.
Supply Chain Analysis
REACH-compliant material declarations and 18-24 month aerospace qualification timelines gate supplier access, concentrating viable supply among legacy producers with established regulatory dossiers. Manufacturing concentrates in China, Germany, and South Korea, with epichlorohydrin and bisphenol A as critical feedstock dependencies. Single-source vulnerability runs through Sinopec's Yangtze River Delta complexes. Distribution feeds from integrated petrochemical majors through regional formulators and distributor networks serving construction and marine segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock cost divergence and multi-regulatory dossier burdens are forcing consolidation among non-integrated formulators lacking backward integration or qualification depth.
For Market Incumbents: Acquire distressed formulation assets in European coating corridors to secure REACH-compliant production capacity ahead of glycidyl novolac transition deadlines. Deepen catalyst technology moats through BASF-style cure-cycle acceleration partnerships with automotive OEMs. Defend against bio-based epichlorohydrin disruptors by locking long-term offtake with glycerol-to-epichlorohydrin technology licensors. For New Entrants and Emerging Players: Cloud-based formulation platforms offer channel entry without legacy field-service infrastructure, collapsing traditional technical-service dependencies that protected incumbents. Target India's unserved protective coatings demand generated by national highway and metro rail expansion programs. Lead with modular cure-system configurability that lets mid-size contractors customize properties without switching base chemistries. For Investors and Strategic Acquirers: Re-rating potential sits with Korean and Chinese integrated producers given captive feedstock supply and MEE dual carbon consolidation tailwinds. Five-to-ten year viability favors assets with epichlorohydrin backward integration and wind blade fabricator qualification relationships. Watch for ECHA bisphenol A sunset clause acceleration as inflection signal for glycidyl novolac substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Kukdo Chemical's Ulsan complex demonstrates margin protection against feedstock volatility. |
| Green Manufacturing Transition | Glycerol-to-epichlorohydrin process technology unlocks renewable certification premiums in European coatings. |
| Long-term Supply Agreement | Wind blade fabricators in Denmark lock ultra-low viscosity grades through multi-year offtake commitments. |
| Joint Venture with Automotive OEM | BASF's catalyst technology partnerships accelerate cure cycles for German chassis composite lines. |
| Capacity Expansion in India | Gujarat chemical corridor investments capture unserved demand from national infrastructure buildout programs. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at epoxy resin manufacturers, procurement leads at wind blade fabricators, distribution channel partners in construction coatings, and technical R&D directors at formulation houses. Bottom-up volume modeling triangulated against top-down petrochemical capacity assessments from ACC and Cefic industry reports.
Data-stream reconciliation across production volume, trade flows, and end-use consumption established baseline calibration. Segmentation modeling spanned grade tier, end-use industry, cure technology, and regional production hub across the projection horizon. CAGRs derived from regression analysis against wind turbine installation forecasts, automotive lightweighting targets, and infrastructure spending programs.
Inputs from ECHA registration databases and MEE energy-intensity disclosures were available through the study window; gaps in real-time feedstock cost data from Chinese state-owned producers introduce uncertainty bands around margin compression scenarios. Forecasts reflect documented assumptions regarding blade scaling trajectories and regulatory sunset enforcement. A model refresh is warranted upon material change in REACH bisphenol A endpoint testing mandates or MEE dual carbon benchmark stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Oman PVC Products Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Saturated Polyester Resin Market
Polymers & Resins
Polyglycerol Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Global Polymeric Adsorbents Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market