
 N-Propyl Propionate Market | 2026-2036
N-Propyl Propionate Market Size, Share, and Industry Trends Forecast 2026-2036
N-Propyl Propionate Market Insights
Buyer concentration among coatings formulators is shifting as mid-sized waterborne paint producers fragment procurement across specialty ester suppliers. Eastman Chemical Company leverages its integrated oxo-alcohol platform to secure backward integration into propionate ester feedstocks. Dow Chemical Company anchors North American supply through its Gulf Coast petrochemical complex, while BASF SE competes on European regulatory compliance and tailored solvent blends for automotive OEM specifications.
N-Propyl propionate, the propyl ester of propionic acid with molecular formula C6H12O2 and boiling point approximately 122°C, serves primarily as a slow-evaporating solvent in coatings, inks, and adhesives where it balances flow properties with reduced volatile organic compound emissions. The solvent segment dominates volume consumption as architectural and industrial coatings manufacturers substitute traditional glycol ethers, while the flavoring agent category occupies narrower but higher-margin positions in food and beverage applications where purity grades command certification premiums. Liquid form concentrates procurement across drum and bulk tank packaging types, reflecting continuous-process manufacturing economics rather than discrete batch handling.
EPA volatile organic compound regulations in the United States, REACH registration requirements administered by ECHA in Europe, and China's GB standards for industrial chemical emissions collectively determine product formulation eligibility and market access conditions for N-propyl propionate suppliers. FDA food-contact substance notifications govern flavoring agent applications, creating parallel compliance tracks that separate pharmaceutical-grade from technical-grade production streams. Stakeholders must monitor regulatory divergence between jurisdictions where California's Air Resources Board imposes stricter limits than federal EPA thresholds, complicating unified product positioning across North American accounts.
Market Dynamics
Waterborne coating formulations are displacing solvent-based systems across architectural and industrial applications, forcing specialty ester suppliers to reposition N-propyl propionate within compliant solvent blends that preserve application performance while meeting tightening volatile organic compound thresholds.
Growth Catalysts
- REACH compliance deadlines:ECHA registration requirements for ester solvents with favorable toxicological profiles are pulling formulators away from glycol ethers toward propionate esters in European coatings manufacturing.
- Automotive OEM specifications:Tier-1 suppliers to German vehicle manufacturers are qualifying slow-evaporating solvents for basecoat and clearcoat systems where flow control and emission reduction must coexist.
- China's industrial chemical clusters:Specialty ester production capacity expansion in Jiangsu and Zhejiang provinces is shortening supply chains for Asian coatings formulators.
Market Restraints
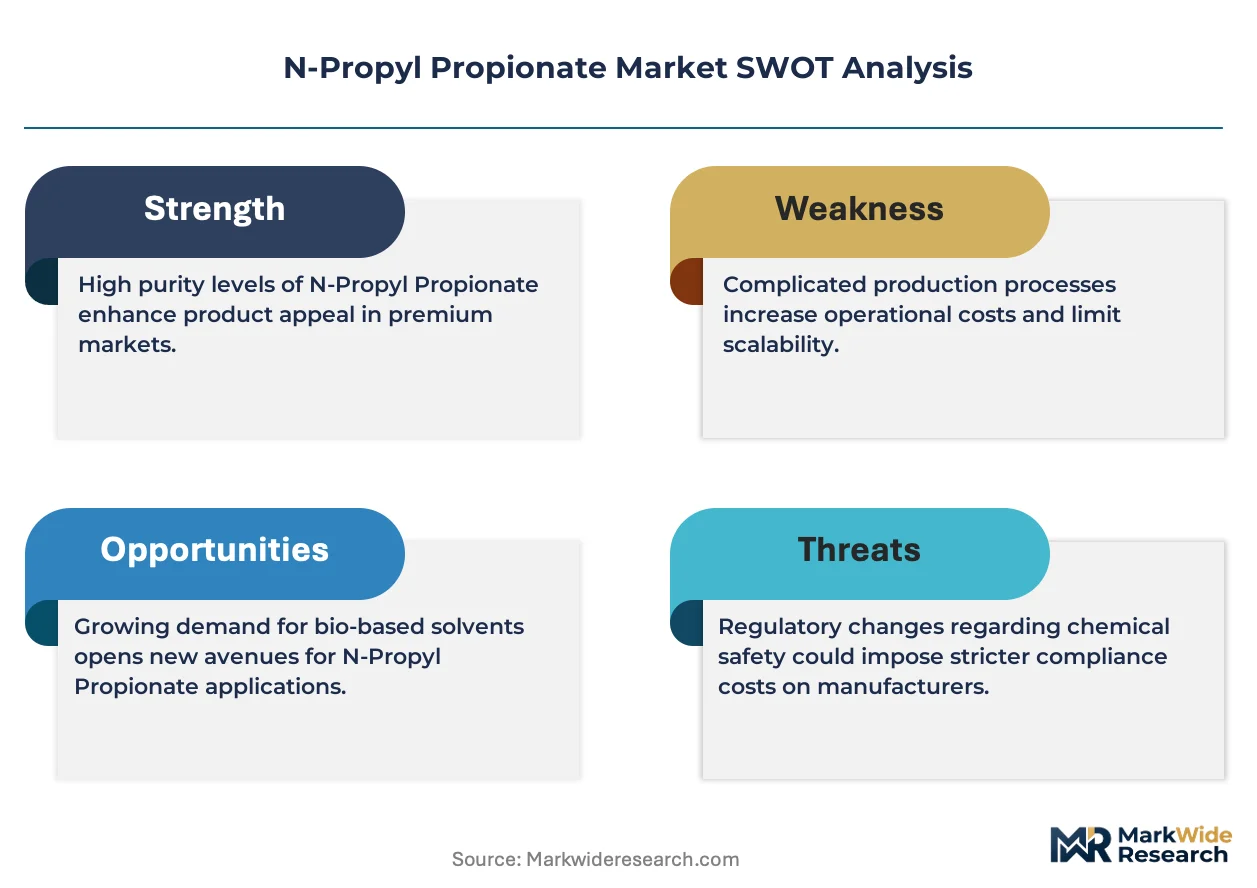
- Propionic acid feedstock volatility:N-propyl propionate production economics track ethylene and oxo-alcohol pricing swings that compress margin predictability for non-integrated producers.
- Substitution by acetate esters:N-propyl acetate and isopropyl acetate offer faster evaporation profiles at lower unit cost, constraining N-propyl propionate penetration in high-volume industrial coatings.
- EPA volatile organic compound designation:Federal exemption status uncertainty for propionate esters complicates long-term formulation commitments by US architectural coatings manufacturers.
Strategic Opportunities
- India's waterborne transition:Domestic paint producers under BIS environmental standards are seeking compliant slow solvents as solvent-based decorative coatings face phase-out timelines in metro markets.
- Food-contact certification expansion:FDA flavoring agent notifications for N-propyl propionate create parallel revenue streams in beverage and confectionery applications with certification premiums.
- Digital formulation platforms:Cloud-based solvent selection tools are enabling technical sales teams to demonstrate blend compatibility remotely, compressing customer qualification cycles.
Industry Challenges
- Specialized toxicology expertise:REACH dossier maintenance and read-across argumentation require dedicated regulatory affairs capacity that mid-sized ester producers struggle to retain.
- Multi-jurisdiction compliance synchronization:Divergent volatile organic compound definitions between California Air Resources Board and federal EPA thresholds force product variant proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Propyl Propionate Market |
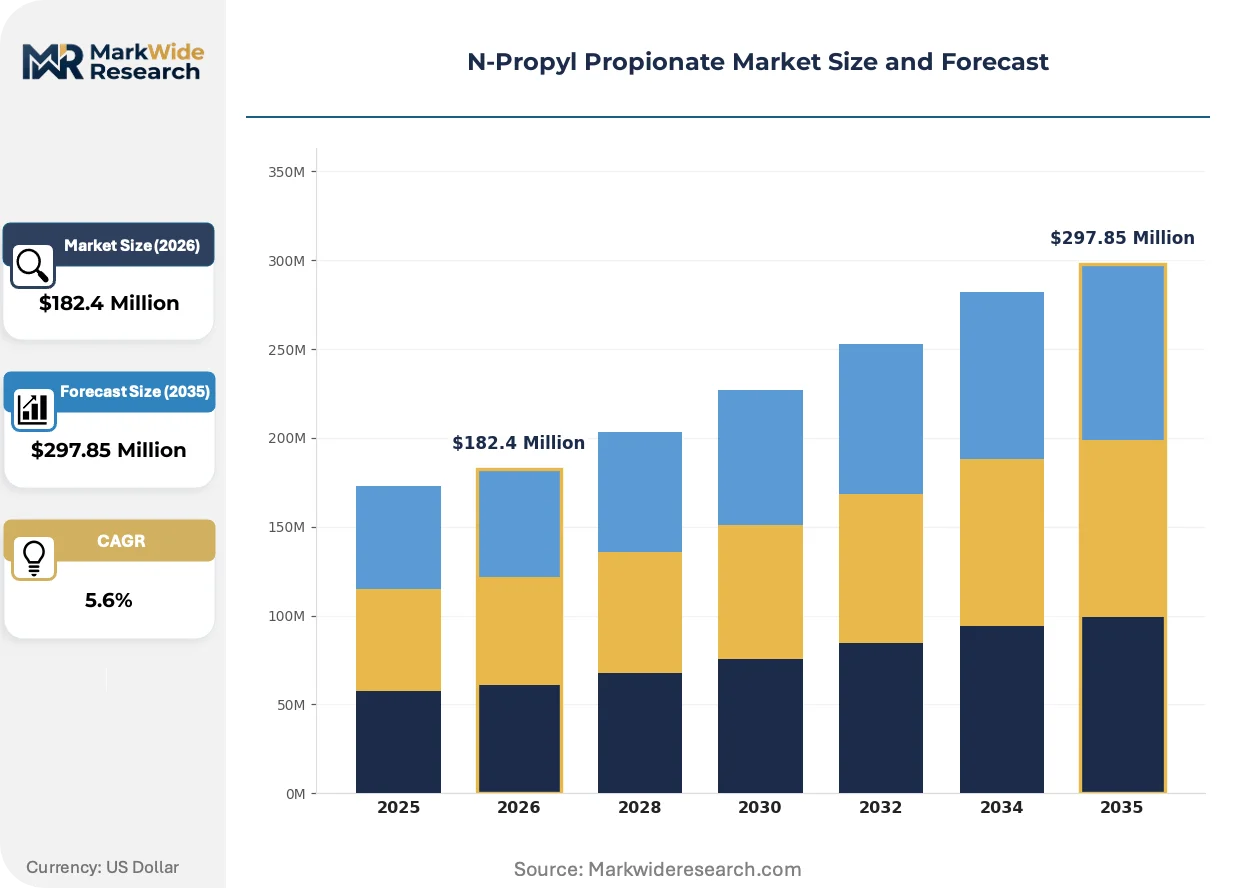
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $297.85 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Ester, Flavoring Agent, Aroma Compound End Use Industry: Food & Beverages, Personal Care, Pharmaceuticals, Coatings Form: Liquid, Powder, Concentrate, Emulsion Packaging Type: Drums, Bottles, Totes, Bulk Tanks |
| Companies Covered | Eastman Chemical Company, Dow Chemical Company, BASF SE, LyondellBasell Industries Holdings B.V., Evonik Industries AG, Celanese Corporation, INEOS Group Holdings S.A., Solvay S.A., Oxea Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Propyl Propionate Market Trends and Innovations
Reactive diluent technologies and bio-based feedstock pathways are fragmenting traditional solvent selection criteria, while digital tools compress the technical validation cycle between supplier laboratories and customer production lines.
Hybrid ester-glycol ether blends are expanding into automotive refinish and aerospace coating segments where single-solvent solutions fail to meet performance specifications. Tier-1 automotive suppliers in Germany and Japan are adopting these formulated systems for metallic basecoats requiring controlled flash-off behavior. The technology is expanding into premium architectural wood coatings where European manufacturers seek differentiated application windows.
REACH authorization procedures for Substances of Very High Concern are accelerating substitution timelines for traditional oxygenated solvents across European industrial coatings. ECHA's 2024-2025 sunset date communications for specific glycol ethers are forcing reformulation projects in metal packaging and coil coating segments. German and Benelux formulators are responding with propionate ester trials in high-solids alkyd systems.
Specification-driven procurement is consolidating technical approval authority among coatings formulator central laboratories, displacing distributed regional purchasing decisions. Bulk tank supply agreements with integrated oxo-alcohol producers are replacing drum-based spot buying in North American architectural coatings. This concentration is most visible in US Gulf Coast supply corridors where backward-integrated producers anchor long-term contracts.
N-Propyl Propionate Market Segmentation
N-Propyl propionate suppliers must align product specifications with divergent purity requirements across coatings formulators and food-contact applications. Segmentation reveals how technical-grade and pharmaceutical-grade production streams command fundamentally different pricing architectures and compliance protocols.
Product Type:
Buyers in this category differentiate primarily by evaporation profile needs and regulatory certification burdens rather than unit cost alone.
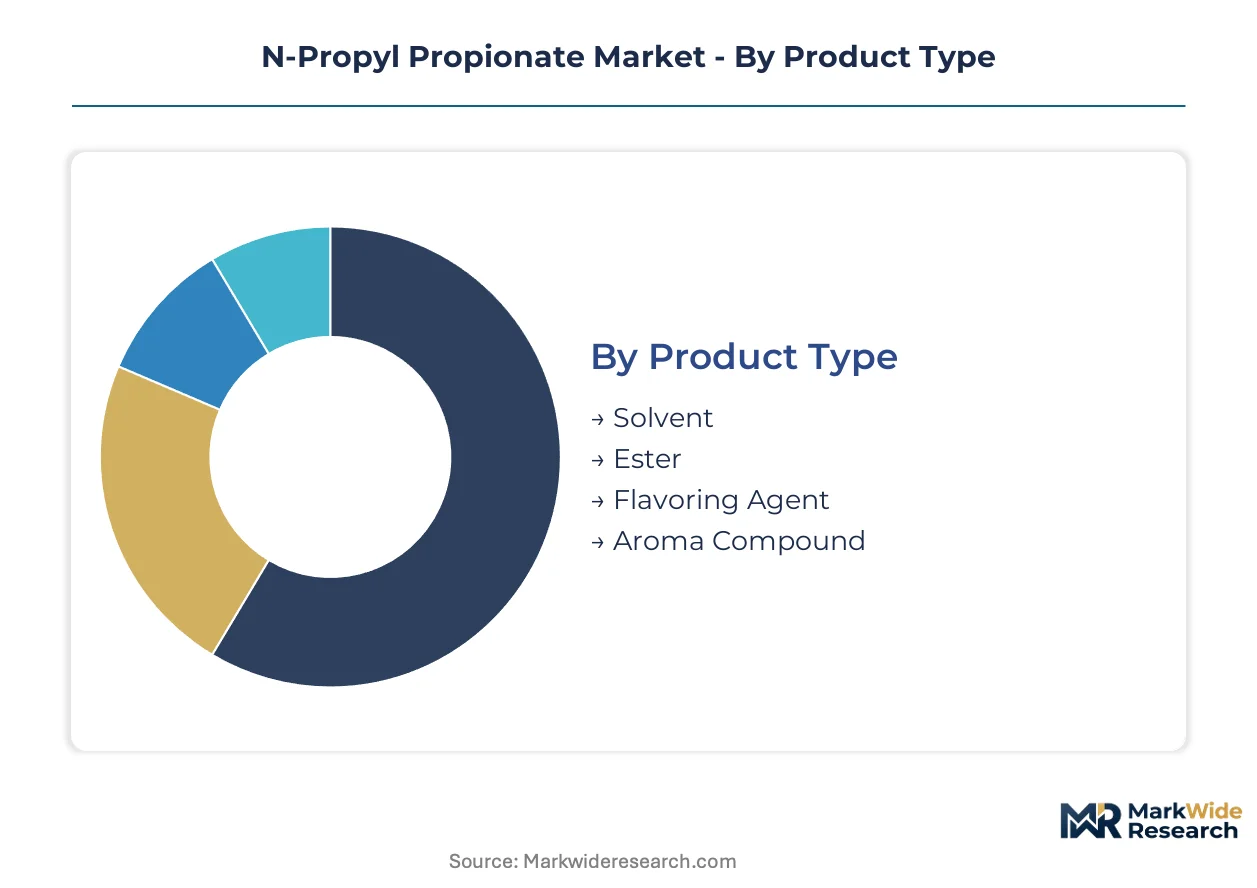
- Solvent:Slow-evaporating C6H12O2 liquid balances flow properties with reduced volatile organic compound emissions in waterborne architectural coatings. Demand concentrates among German automotive OEM suppliers qualifying basecoat systems where controlled flash-off behavior meets emission thresholds.
- Ester:Chemically identical to solvent-grade but positioned for industrial coatings requiring specific solubility parameters in high-solids alkyd formulations. Procurement from Jiangsu and Zhejiang specialty ester clusters is shortening Asian supply chains for regional formulators.
- Flavoring Agent:FDA food-contact substance notifications govern pharmaceutical-grade production with certification premiums.
- Aroma Compound:Narrower volume category serving beverage and confectionery applications.
Solvent leads volumes today; flavoring agent is gaining share fastest.
End Use Industry:
Margin structures diverge sharply between commodity coatings procurement and certified food-contact supply chains.
- Coatings:Architectural and industrial formulators drive bulk consumption as waterborne systems displace solvent-based alternatives under tightening EPA and REACH volatile organic compound thresholds. German and Benelux metal packaging producers are trialing propionate esters in coil coating reformulations.
- Food & Beverages:Purity grades require FDA notification compliance and command substantial certification premiums over technical grades. Beverage applications in North America and confectionery segments in Europe concentrate demand.
- Personal Care:Fragrance formulation applications with moderate volume scale.
- Pharmaceuticals:Excipient and processing solvent uses with stringent quality documentation requirements.
Coatings dominates current procurement; food and beverages shows steepest expansion trajectory.
Form:
Continuous-process manufacturing economics favor liquid handling over discrete batch operations.
- Liquid:Standard state for solvent and ester applications enabling drum, tote, and bulk tank logistics. Liquid form anchors procurement across all major coatings manufacturing corridors.
- Powder:Limited niche applications requiring solid-state handling.
- Concentrate:Reduced-volume shipping for remote formulation sites.
- Emulsion:Water-dispersible systems for specific coating compatibility requirements.
Liquid form captures virtually all volume; emulsion variants are climbing fastest among specialty formulators.
Packaging Type:
Procurement scale and supply chain integration determine packaging selection.
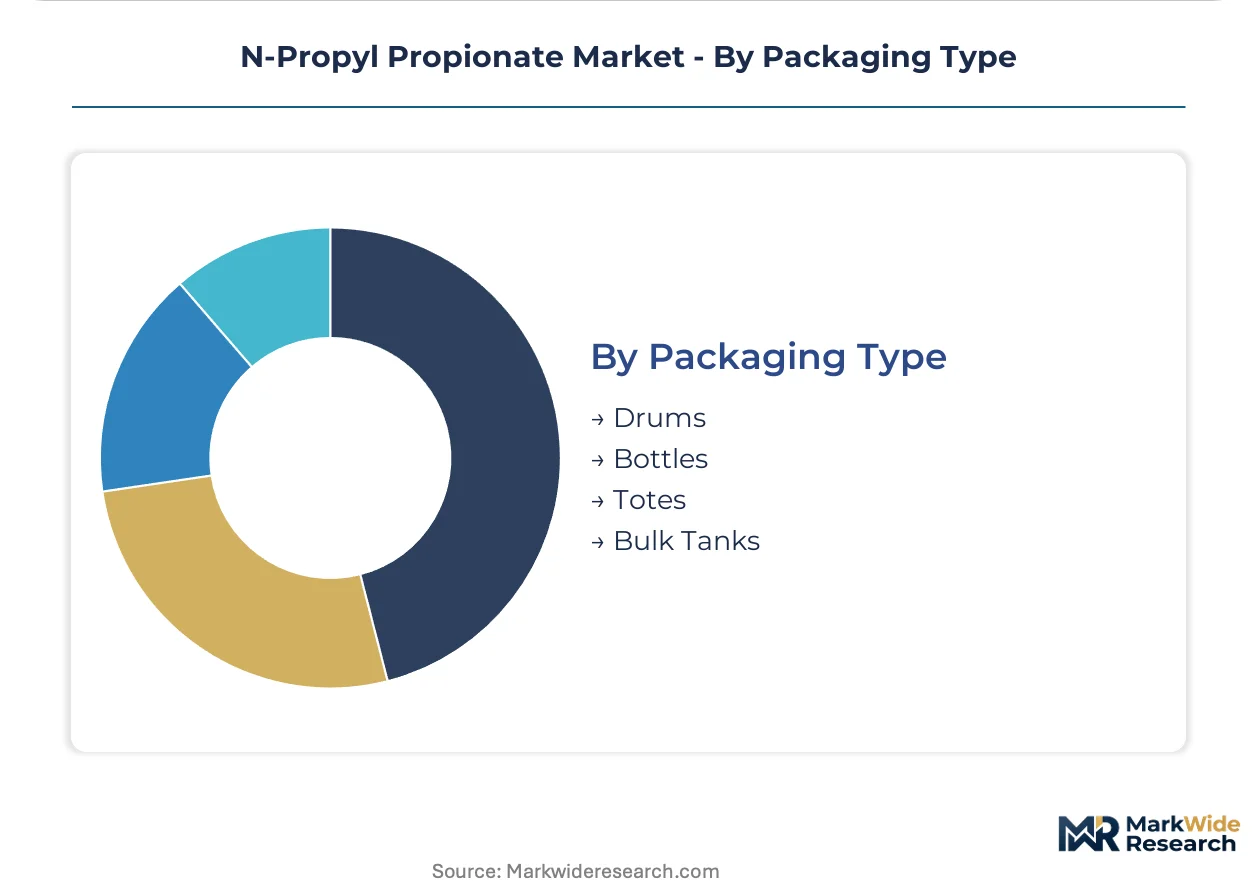
- Bulk Tanks:Integrated oxo-alcohol producers anchor long-term supply agreements with North American architectural coatings manufacturers through Gulf Coast corridors. Bulk delivery eliminates drum handling costs for high-volume continuous operations.
- Drums:Standard unit for mid-scale formulators lacking tank farm infrastructure.
- Totes:Intermediate volumes for regional coating production facilities.
- Bottles:Laboratory-scale and flavoring agent sampling quantities.
Bulk tanks lead volume throughput; totes are expanding most quickly among mid-sized waterborne paint producers fragmenting procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty ester chemists and coatings formulators concentrate in Germany, China, the United States, India, and Japan, anchoring regional demand clusters for slow-evaporating solvents.
United States
Architectural coatings manufacturers along the Gulf Coast drive bulk procurement of N-propyl propionate for waterborne reformulations. EPA volatile organic compound regulations create compliance pressure that favors exempt solvent candidates. Texas and Louisiana petrochemical corridors host backward-integrated producers supplying drum and bulk tank quantities to regional formulators.
Germany
Automotive OEM suppliers in Baden-Württemberg and Bavaria qualify propionate esters for metallic basecoat systems requiring controlled flash-off. REACH authorization timelines for glycol ethers accelerate substitution trials in high-solids alkyd formulations. The Cologne-Düsseldorf industrial belt concentrates specialty ester blending capacity for European coil coating applications.
China
Jiangsu and Zhejiang province coatings clusters expand domestic specialty ester production to serve waterborne architectural paint demand. GB standards for industrial chemical emissions tighten formulation requirements across the Yangtze River Delta. Ningbo and Taizhou chemical parks anchor regional supply chains that shorten procurement cycles for Asian formulators.
India
Domestic paint producers under BIS environmental standards seek compliant slow solvents as solvent-based decorative coatings face metro market phase-outs. Maharashtra and Gujarat industrial corridors concentrate waterborne coatings manufacturing capacity. Mumbai-Pune and Ahmedabad-Vadodara chemical zones host expanding ester solvent distribution infrastructure.
Japan
Automotive refinish and electronics coatings manufacturers in the Nagoya and Osaka industrial zones specify high-purity ester solvents for precision application requirements. METI chemical management frameworks govern substance registration and industrial emissions. Chubu and Kansai manufacturing belts maintain specialized solvent qualification protocols for tier-1 supplier integration.
N-Propyl Propionate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the N-propyl propionate supply base. The market structure tilts toward integrated oxo-alcohol producers who capture backward integration into propionic acid and propanol feedstocks. Three archetypes dominate: petrochemical majors with Gulf Coast or European petrochemical integration, Asian specialty ester producers with regional cluster proximity, and European regulatory compliance specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure long-term supply agreements with coatings formulators.
Among integrated chemical conglomerates, Eastman Chemical Company, Dow Chemical Company, and BASF SE occupy positions that exemplify divergent geographic and strategic anchoring. Eastman leverages oxo-alcohol platform integration to secure captive feedstock supply. Dow anchors North American volume through Gulf Coast petrochemical complex proximity. BASF competes on European regulatory dossier depth and tailored solvent blend capabilities for automotive OEM specifications.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Dow Chemical Company |
| BASF SE |
| LyondellBasell Industries Holdings B.V. |
| Evonik Industries AG |
| Celanese Corporation |
| INEOS Group Holdings S.A. |
| Solvay S.A. |
| Oxea Corporation |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade certification premiums diverge sharply from technical-grade commodity pricing, compressing procurement options for coatings formulators while expanding margin capture for food-contact specialists. This bifurcation concentrates supply chain investment around REACH dossier maintenance and FDA notification compliance, segmenting inventory management between bulk tank architectures and drum-based spot purchasing.
Pricing Analysis
Capacity additions in Jiangsu and Zhejiang provinces are reshaping price floors for technical-grade N-propyl propionate across Asian coatings markets. Contract-based long-term offtake agreements dominate procurement between integrated oxo-alcohol producers and Gulf Coast architectural formulators, while spot purchasing persists among mid-sized waterborne paint producers. Price differentiation stems from REACH registration completeness and FDA food-contact certification status, with certification premiums widening as ECHA authorization deadlines approach. Cost compression in technical grades is intensifying because propionic acid feedstock volatility transmits directly to non-integrated ester producers. Waterborne coatings manufacturers exhibit highest price sensitivity, while flavoring agent buyers accept substantial premiums for pharmaceutical-grade purity documentation.
Supply Chain Analysis
Direct-to-coatings-formulator channels handle hyperscale buyer demand through dedicated bulk tank agreements anchored in Texas and Louisiana petrochemical corridors. Supply concentration rests on Germany, China, and the United States, with Jiangsu province specialty ester clusters and Cologne-Düsseldorf industrial belts anchoring regional production. Raw material dependencies center on ethylene-derived oxo-alcohols, propionic acid feedstocks, and propanol intermediates. Single-source vulnerability from propionic acid supply concentration creates exposure to petrochemical pricing cycles. Distribution runs through integrated oxo-alcohol producers with backward integration into captive feedstock supply, displacing drum-based logistics for high-volume continuous operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as waterborne coating specifications tighten volatile organic compound thresholds and elevate slow-evaporating solvent premiums. German automotive OEM qualification protocols now demand REACH-compliant ester blends with documented toxicological profiles.
For Market Incumbents: Cement backward integration into oxo-alcohol feedstocks through Gulf Coast or European petrochemical complex proximity, insulating margin structures from propionic acid volatility. Deepen regulatory dossier capabilities to defend against acetate ester substitution threats in high-volume industrial coatings. Capacity expansion in Jiangsu province secures Asian formulator relationships before regional specialty ester clusters mature.
For New Entrants and Emerging Players: Launch via food-contact certification services targeting beverage and confectionery applications with FDA notification expertise as the anchor capability. India's waterborne transition under BIS environmental standards offers the most penetrable geography, with Mumbai-Pune and Ahmedabad-Vadodara chemical zones lacking established ester solvent distribution infrastructure. Technical sales teams should deploy cloud-based solvent selection tools to compress customer qualification cycles remotely.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH authorization procedures for glycol ethers accelerate substitution timelines and fragment technical approval authority among coatings formulator central laboratories. Five-to-ten-year viability favors integrated producers with captive oxo-alcohol supply and established automotive OEM qualification records. Acquisition targets should display ECHA dossier maintenance capacity and German Tier-1 supplier relationships. Watch for EPA volatile organic compound exemption status determinations as the critical inflection signal for US architectural coatings demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxo-Alcohol Feedstocks | Captive propanol supply secures margin stability against ethylene pricing volatility. |
| REACH Dossier Expansion | ECHA registration completeness qualifies suppliers for German automotive OEM basecoat specifications. |
| Food-Contact Certification Investment | FDA notification compliance unlocks beverage and confectionery premiums beyond technical grades. |
| Long-term Supply Agreements | Bulk tank contracts with Gulf Coast formulators displace spot purchasing in architectural coatings. |
| Joint Venture in Jiangsu Province | Regional production cluster proximity shortens supply chains for Yangtze River Delta formulators. |
Research Methodology
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each territory's coatings manufacturing corridors and specialty ester production clusters. Plant managers at Jiangsu and Zhejiang chemical parks, procurement leads at German automotive Tier-1 suppliers, distribution channel partners in Gulf Coast petrochemical corridors, and technical R&D directors at waterborne coatings formulators contributed primary perspectives. Secondary validation drew from ECHA REACH registration databases, US EPA volatile organic compound exemption filings, SEC 10-K disclosures from integrated chemical conglomerates, and customs trade data tracking propionate ester flows. Bottom-up volume modeling triangulated against top-down demand aggregation from end-use industry consumption patterns.
Segmentation granularity operated at grade tier, end-use industry, packaging format, and regional production hub levels throughout the projection horizon. Solvent, ester, flavoring agent, and aroma compound categories were modeled separately with purity-grade pricing architectures. Coatings, food and beverages, personal care, and pharmaceutical end-uses received distinct demand trajectories. CAGRs were derived from regression analysis against macro drivers including regulatory threshold tightening, automotive OEM specification adoption rates, and waterborne formulation penetration curves. Propionic acid feedstock pricing indices and oxo-alcohol capacity expansion schedules served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA volatile organic compound reclassification or ECHA authorization timeline acceleration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Superacids Market
Specialty Compounds
Thiocolchicoside Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Global Heat Stabilizers Market
Specialty Compounds
Conductive Plastic Compounds Market