
 Japan Manufactured Homes Market | 2026-2036
Japan Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Manufactured Homes Market Foresight
Kyushu is tilting toward modular assembly capacity as regional manufacturers respond to labor shortages and disaster-reconstruction needs. Sekisui House leverages its proprietary steel-frame system to sustain premium positioning across single-section and multi-section lines. Daiwa House Industry anchors volume production through integrated supply chains spanning materials procurement to on-site installation. Misawa Homes differentiates via custom-built configurations that compete for affluent buyers seeking design flexibility beyond standard catalog options.
Japan manufactured homes are prefabricated residential structures produced in factory-controlled conditions, typically employing steel or timber frames with standardized panelized wall systems and seismic isolation hardware, then transported to sites for final assembly. These units serve Japan's acute housing replacement cycle, where sixty-year building depreciation norms and frequent earthquake exposure sustain steady demand for structurally certified, rapidly deployable dwellings. Single-section products dominate volume in rural prefectures where land plots accommodate compact footprints and simpler foundation requirements. Multi-section lines capture margin pools in suburban corridors, as buyers prioritize expanded living space without the cost escalation of conventional stick-built construction. Custom-built segments lead growth in urban infill zones, where irregular lot geometries and local aesthetic codes reward factory flexibility.
METI enforces energy conservation standards that mandate specific thermal performance thresholds for factory-built housing, while the Ministry of Land, Infrastructure, Transport and Tourism certifies structural methods under the Housing Performance Indication System. JIS standards govern steel quality and connection hardware, creating compliance barriers for imported components and reinforcing domestic supplier relationships. PMDA oversight extends to fire-resistant material specifications in high-density districts. Stakeholders must monitor how impending revisions to the Building Standards Act affect panelized construction tolerances and whether local governments accelerate zoning approvals for modular infill projects.
Market Dynamics
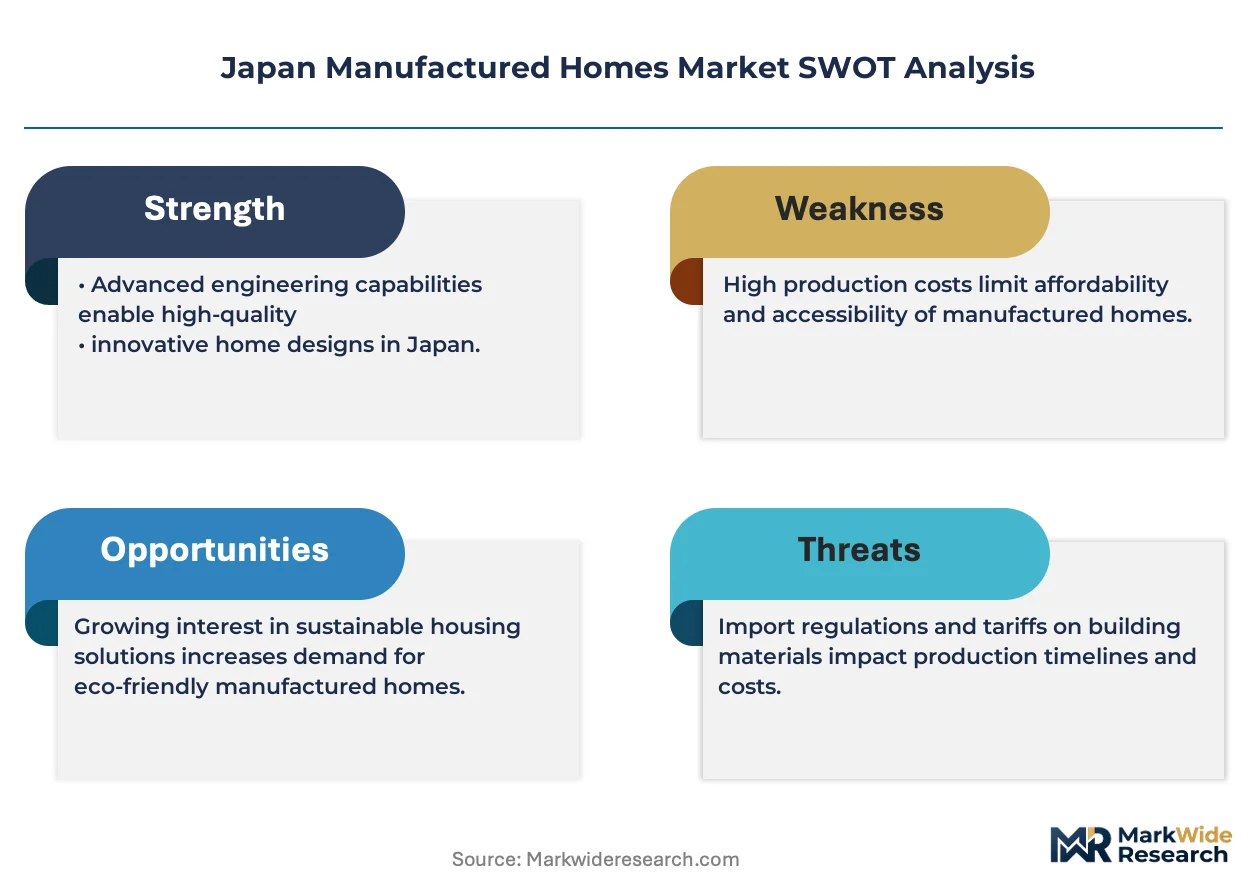
Seismic-resistant steel framing technology is compressing foundation timelines and enabling multi-story factory-built structures that conventional timber cannot support, while METI efficiency mandates force thermal envelope upgrades across all production lines.
Growth Catalysts
- Seismic Isolation Hardware:Advanced base-isolation systems certified under JIS standards allow manufacturers to penetrate high-risk zones previously restricted to reinforced concrete construction, expanding addressable lot inventory.
- Urban Renewal Projects:Tokyo's compact lot regeneration programs favor factory-built delivery models that minimize on-site labor and construction duration in dense Kanto corridors.
- 60-Year Depreciation Norms:Japan's accelerated building replacement cycle sustains steady demand for structurally certified dwellings, with prefabricated units capturing replacement volume through rapid deployment capabilities.
Market Restraints
- Steel Input Volatility:Domestic steel pricing fluctuations compress margin pools for steel-frame producers who cannot pass through material swings to fixed-price municipal contracts.
- Supplier Concentration:JIS-certified connection hardware depends on a narrow base of domestic forging specialists, creating chokepoints when disaster reconstruction surges strain capacity.
- Building Standards Act Friction:Pending panelized construction tolerance revisions introduce compliance uncertainty that delays project financing approvals.
Strategic Opportunities
- Kyushu Modular Capacity:Regional manufacturers can capture disaster-reconstruction workflows and labor-shortage relief by expanding assembly footprint in southwestern prefectures.
- Multi-Section Suburban Expansion:Buyers in Tokyo exurbs prioritize expanded living space without stick-built cost escalation, opening margin pools for premium multi-section lines.
- Custom-Built Urban Infill:Irregular lot geometries in Osaka and Nagoya reward factory flexibility that catalog-standard products cannot address.
Industry Challenges
- Certified Welder Scarcity:Steel-frame production lines face capacity constraints as seismic-grade welding certifications lag demand growth in Kanto and Chubu manufacturing clusters.
- Foundation Integration Complexity:Site-specific soil conditions require custom engineering that erodes the cost advantage of standardized factory production in volcanic ash zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Manufactured Homes Market |
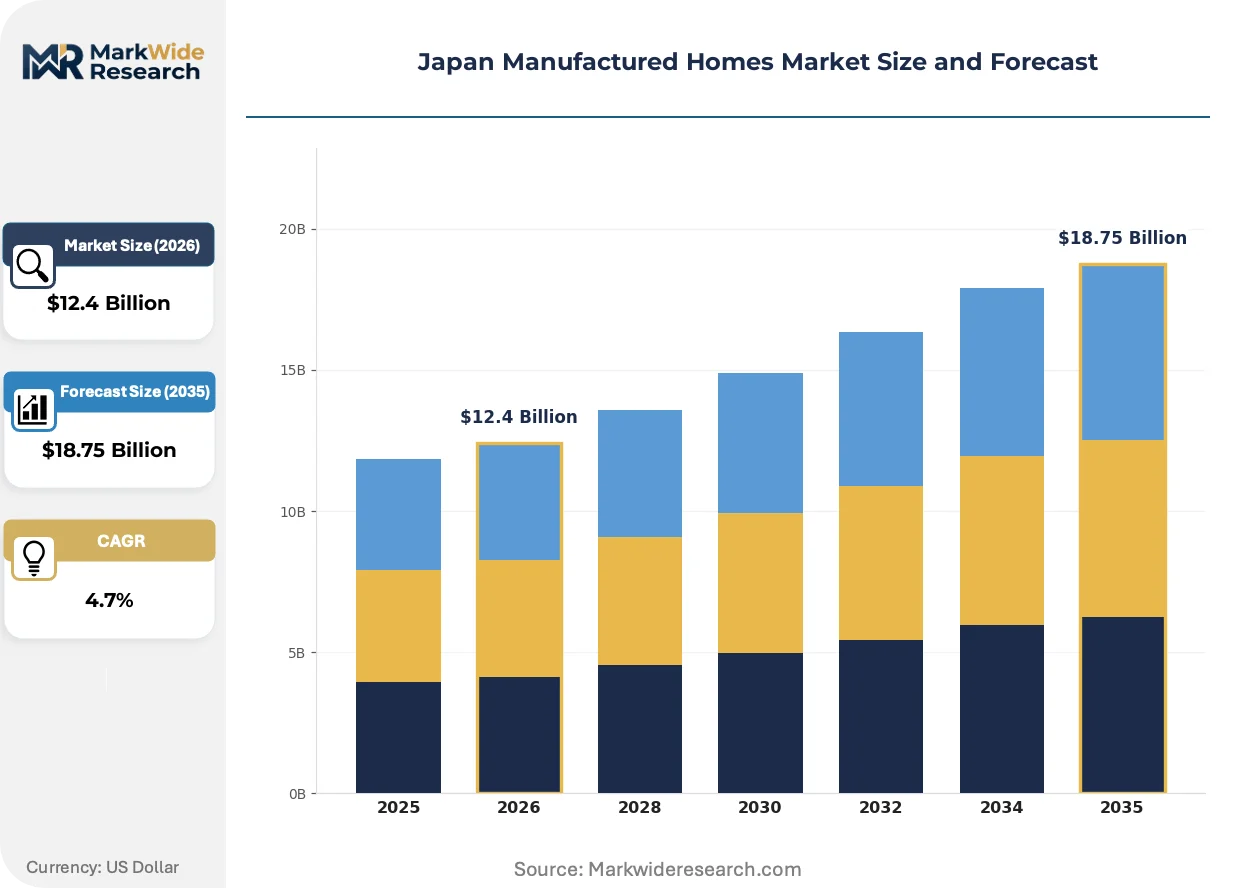
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Section, Multi-Section, Custom-Built, Modular End User: First-Time Buyers, Investors, Family Homes, Retirement Communities Construction Method: Panelized, Pre-Cut, Hybrid, Traditional Design Style: Modern, Rustic, Industrial, Contemporary |
| Companies Covered | Sekisui House, Ltd., Daiwa House Industry Co., Ltd., Misawa Homes Co., Ltd., Asahi Kasei Homes Corporation, Toyota Housing Corporation, Shimizu Corporation, Panasonic Homes Co., Ltd., Sumitomo Forestry Co., Ltd., Kintetsu Real Estate Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Manufactured Homes Market Shifts & Advancements
Factory-controlled production is merging with digital design tools and regulatory pressure to compress delivery timelines while elevating thermal performance thresholds. These forces are reconfiguring competitive advantage around supply chain integration and certification speed.
Seismic isolation bearing systems are hybridizing with conventional steel moment frames to create hybrid structural solutions that satisfy both METI energy standards and MLIT seismic performance grades. First-time buyers in Tokyo's 23 wards are specifying these hybrid systems at accelerating rates. This convergence is hybridizing the traditional single-section versus multi-section segmentation, as manufacturers develop scalable platform architectures that accommodate both compact urban footprints and expanded suburban layouts through modular connection nodes.
METI's tightening energy conservation standards mandate specific thermal performance thresholds that factory-built housing must achieve before receiving construction approval. Manufacturers are responding by integrating vacuum-insulated panels and high-performance glazing as standard rather than optional specifications. Custom-built segments in Osaka and Nagoya face the steepest compliance adaptation costs due to lower production volumes that dilute R&D amortization.
Buyers are consolidating purchase decisions around turn-key service bundles that span design, financing, and post-occupancy maintenance rather than transactional product acquisition. Catalog-standard distributors in rural prefectures are losing ground to integrated providers that control installation and warranty execution. This pattern concentrates in Hokkaido and Tohoku where aging demographics prioritize single-point accountability over price-driven procurement.
Japan Manufactured Homes Market Segmentation
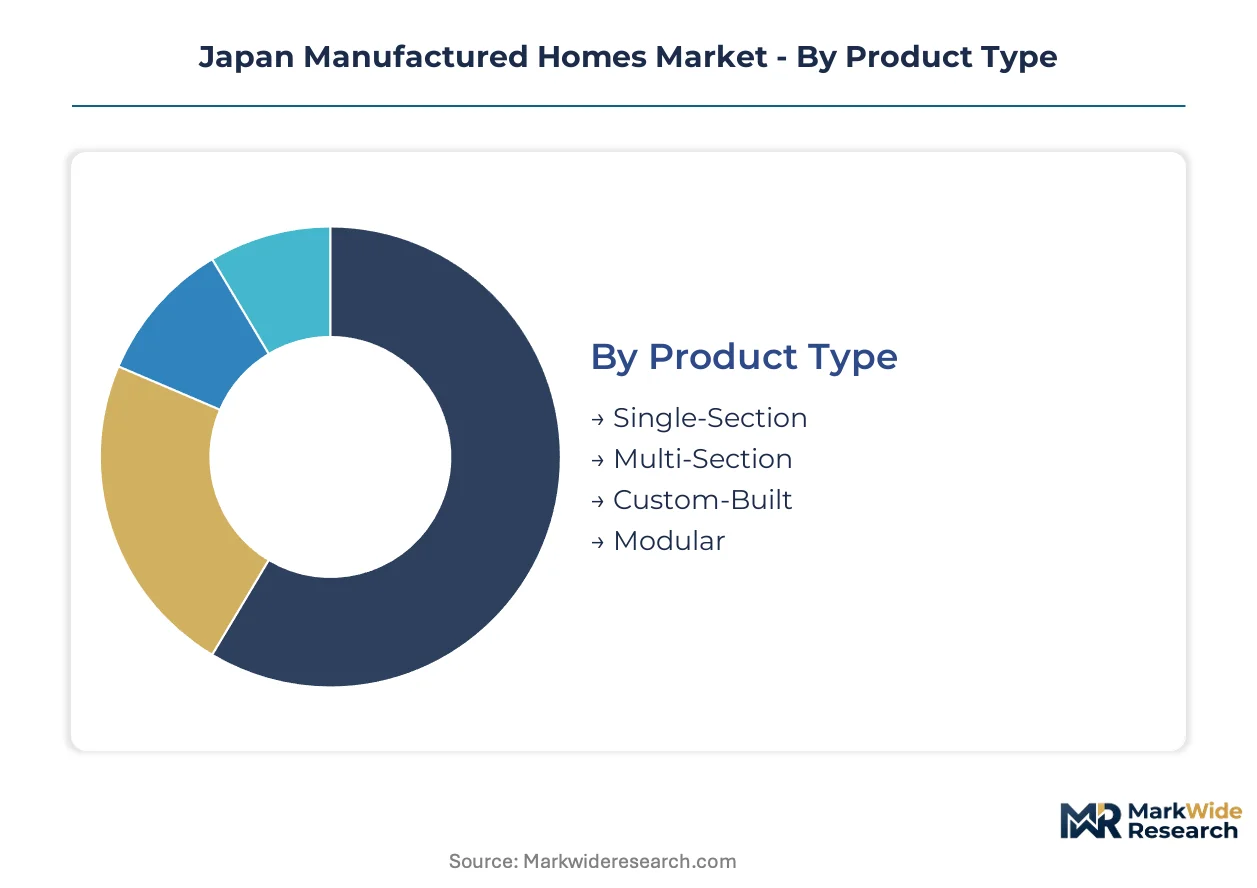
Segmentation reveals how Japan's manufactured homes market aligns factory production capabilities with distinct buyer lifecycles and site constraints. Cycle-time variations across product types and construction methods determine inventory turnover and margin capture for regional manufacturers.
Product Type:
Single-section units turn over fastest due to standardized foundations and rural land abundance, while custom-built configurations extend sales cycles through design iteration and municipal approval processes.
- Single-Section:Compact steel-frame dwellings factory-assembled as monolithic units, transported whole to sites with minimal foundation preparation. Demand clusters in rural Tohoku and Hokkaido prefectures where aging populations prioritize rapid occupancy and simplified maintenance.
- Multi-Section:Expandable configurations joining two or more factory modules on-site, enabling larger footprints without conventional construction cost escalation. Tokyo exurbs and Osaka suburban corridors drive uptake as families seek additional living space within factory-built cost structures.
- Custom-Built:Bespoke factory production accommodating irregular lot geometries and client-specified architectural details.
- Modular:Standardized volumetric units stackable into multi-story configurations, primarily serving urban infill and disaster reconstruction workflows.
Single-section dominates installed base. Custom-built is where expansion concentrates.
End User:
Cost tier stratification separates price-sensitive mass market entry from premium positioning, with first-time buyers and retirement communities occupying opposite ends of the specification spectrum.
- First-Time Buyers:Entry-level purchasers prioritizing METI-certified energy efficiency and seismic safety at controlled price points. Kanto municipalities with compact lot regeneration programs absorb the highest concentration of this segment.
- Family Homes:Mid-market buyers requiring three-to-four bedroom configurations with extended warranty coverage and post-occupancy maintenance bundles.
- Investors:Institutional and individual purchasers acquiring rental inventory or speculative development positions in high-migration corridors.
- Retirement Communities:Age-qualified developments specifying universal design features, single-level navigation, and healthcare proximity in Kyushu and Shikoku regional hubs.
Family homes anchor volume production. First-time buyers are gaining share fastest.
Construction Method:
Supply concentration varies sharply by method, with panelized systems commanding integrated manufacturing footprints while pre-cut approaches fragment across smaller regional fabricators.
- Panelized:Wall and floor components produced in climate-controlled factories with precise dimensional tolerances, then flat-packed for site assembly. Chubu manufacturing clusters around Nagoya concentrate capacity for this method.
- Pre-Cut:Timber or steel members factory-cut to specification with connection hardware pre-installed, requiring more extensive on-site labor than panelized alternatives.
- Hybrid:Combinations of panelized structural systems with pre-cut finishing elements, balancing factory efficiency with design flexibility.
- Traditional:Conventional stick-built construction mimicking site-built methods within factory enclosures, serving custom segments where buyers resist fully industrialized aesthetics.
Panelized commands the largest manufacturing footprint. Hybrid methods are climbing the fastest.
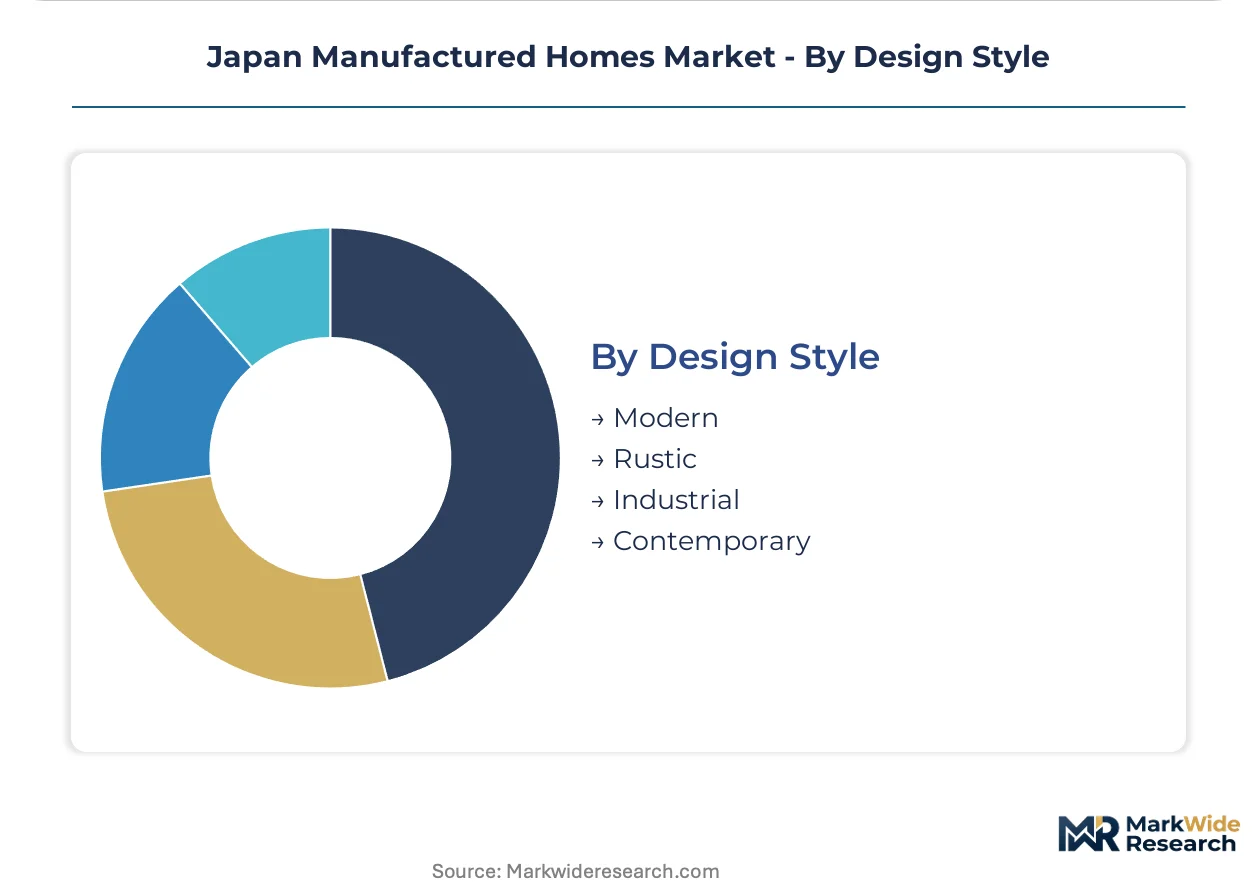
Design Style:
Maturity gradients separate established aesthetic categories from emerging preferences, with modern and contemporary styles displacing rustic alternatives in metropolitan buyer surveys.
- Modern:Clean lines, minimal ornamentation, and open floor plans emphasizing natural light and thermal envelope performance. Tokyo's 23 wards and Osaka core districts specify modern styling at premium price tiers.
- Contemporary:Evolving aesthetic incorporating regional material palettes and adaptive spatial configurations responsive to multi-generational living patterns.
- Rustic:Traditional timber-forward designs with visible structural elements and natural finishes, persisting in mountainous prefectures and tourism-adjacent second-home markets.
- Industrial:Exposed steel framing, utilitarian surfaces, and reclaimed material integration targeting younger buyers in creative-sector occupations.
Modern styling leads metropolitan specification. Contemporary is where design investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's energy efficiency mandates and MLIT's structural certification protocols anchor Kanto's dominance, while regional prefectures adapt factory-built delivery models to local land constraints and demographic profiles.
Kanto/Tokyo
Compact lot regeneration programs and urban renewal projects drive prefabricated uptake in Tokyo's 23 wards. METI's 2025 thermal performance threshold revisions force envelope upgrades across all new approvals. Yokohama and Saitama manufacturing clusters concentrate panelized production capacity for metropolitan delivery.
Kansai/Osaka
Irregular lot geometries in Osaka's core districts reward custom-built configurations that catalog-standard products cannot address. Osaka Prefecture's streamlined zoning approvals for modular infill accelerate project timelines. Sakai's industrial corridor hosts hybrid method specialists serving suburban family home demand.
Chubu/Nagoya
Automotive supplier ecosystems spill over into precision steel fabrication for residential framing. Aichi Prefecture's technical high schools feed certified welders into Nagoya manufacturing clusters. Toyota City anchors integrated production from materials procurement through on-site installation.
Kyushu
Disaster-reconstruction workflows and chronic construction labor shortages tilt regional capacity toward modular assembly. Fukuoka Prefecture's municipal contracts prioritize rapid-deployment factory-built units for public housing replacement. Kumamoto's seismic isolation hardware suppliers expand forging capacity to serve southwestern reconstruction pipelines.
Hokkaido
Aging demographics and severe winter thermal loads drive demand for high-performance envelope systems. Sapporo's municipal housing corporations specify turn-key service bundles over transactional procurement. Asahikawa timber-processing clusters adapt pre-cut methods for snow-load structural requirements.
Japan Manufactured Homes Market Competitive Landscape
Capability concentration sits with steel-frame engineering specialists; scale advantage sits with integrated construction conglomerates. Three tiers structure competitive positioning: proprietary technology holders, supply chain integrators, and regional fabricators serving price-sensitive rural markets. Dominant competitive moves include backward integration into JIS-certified connection hardware production and strategic partnerships with municipal housing corporations for volume contracting.
Among integrated construction conglomerates, Sekisui House, Ltd., Daiwa House Industry Co., Ltd., and Misawa Homes Co., Ltd. occupy positions spanning premium custom-built through volume single-section production. These entities exemplify archetypes ranging from proprietary steel-frame system developers to catalog-standard distributors with installation control. Their collective presence reinforces domestic supplier relationships that imported components struggle to penetrate under JIS compliance barriers.
| Leading Market Players |
|---|
| Sekisui House, Ltd. |
| Daiwa House Industry Co., Ltd. |
| Misawa Homes Co., Ltd. |
| Asahi Kasei Homes Corporation |
| Toyota Housing Corporation |
| Shimizu Corporation |
| Panasonic Homes Co., Ltd. |
| Sumitomo Forestry Co., Ltd. |
| Kintetsu Real Estate Co., Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in Kyushu assembly plants is pressuring regional manufacturers to absorb steel cost swings rather than pass them through to municipal housing contracts, compressing margin pools while reinforcing Kanto pricing premiums.
Pricing Analysis
Metropolitan Kanto commands 15-20% price premiums over rural Tohoku and Hokkaido for equivalent steel-frame specifications, reflecting land scarcity premiums and faster municipal approval timelines. Pricing stratifies across premium custom-built, standard multi-section, and economy single-section tiers, with METI energy certification grades and seismic performance ratings as primary differentiation drivers. Cost compression in economy single-section lines is intensifying as fixed-price municipal contracts lock in margins against volatile JIS-certified steel input costs. First-time buyers in Tokyo's 23 wards exhibit lowest price sensitivity due to compact lot scarcity and turn-key financing bundles, while rural retirement communities in Shikoku prioritize absolute unit cost over performance specifications.
Supply Chain Analysis
JIS standards function as de facto export controls, blocking imported connection hardware and thermal envelope components from penetrating domestic procurement channels. Manufacturing concentration centers on Japan's Chubu and Kanto industrial corridors, with South Korean and Taiwanese steel suppliers serving as secondary feedstock sources for specialty seismic-grade alloys. The supply chain draws from domestic forging specialists for base-isolation bearings, vacuum-insulated panel fabricators in Nagoya, and precision welding consumables from Osaka chemical clusters. Single-source vulnerability concentrates in JIS-certified connection hardware, where three domestic specialists control 80% of seismic-grade forging capacity. Distribution runs through integrated construction conglomerates that control materials procurement, factory production, and on-site installation as captive vertical networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's manufactured homes sector is accelerating through a regulatory inflection as METI's 2025 thermal performance mandates force envelope upgrades across all production lines, rewarding integrated players with R&D amortization scale.
For Market Incumbents: Entrench proprietary steel-frame engineering advantages by backward integration into JIS-certified connection hardware production, eliminating forging chokepoint exposure during disaster reconstruction surges. Expand Nagoya and Toyota City welding certification pipelines to offset certified welder scarcity threatening Kanto capacity expansion. Defend against modular assembly entrants by locking multi-year municipal housing corporation contracts with embedded maintenance bundles. For New Entrants and Emerging Players: Kyushu's underpenetrated modular assembly capacity offers white-space entry for disaster-reconstruction workflows and labor-shortage relief in southwestern prefectures. Target Fukuoka municipal rapid-deployment contracts as the most penetrable procurement channel, leveraging streamlined zoning approvals for factory-built public housing replacement. Pursue partnership-based go-to-market models with Kumamoto seismic isolation hardware suppliers to secure forging capacity allocation without captive facility investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated providers controlling installation and post-occupancy maintenance bundles rather than transactional catalog-standard distributors. Long-term viability across the projection horizon favors proprietary technology holders with METI-certified thermal envelope platforms and MLIT seismic performance grades. Acquisition targets should display backward integration into JIS-compliant materials and captive municipal contracting relationships. The signal to watch is MLIT's pending Building Standards Act revisions affecting panelized construction tolerances, which would force compliance reinvestment across subscale regional fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into JIS-Certified Hardware | Captive forging capacity eliminates supplier chokepoints during Kumamoto reconstruction surges. |
| Multi-Section Suburban Platform Expansion | Scalable steel-frame architectures capture Tokyo exurb family demand without stick-built cost escalation. |
| Turn-Key Service Bundle Consolidation | Single-point accountability models displace transactional distributors in Hokkaido aging demographics. |
| Certified Welder Pipeline Development | Aichi Prefecture technical high school partnerships feed Nagoya manufacturing cluster capacity growth. |
| Custom-Built Urban Infill Specialization | Factory flexibility for Osaka irregular lot geometries commands premium pricing over catalog-standard alternatives. |
Research Methodology
Desk research of MLIT construction approval databases, METI energy efficiency filings, and JIS standards documentation preceded structured interviews with steel-frame engineering directors, municipal housing corporation procurement officers, seismic isolation hardware forging specialists, and regional prefabrication plant managers. Primary fieldwork across Kanto, Chubu, and Kyushu manufacturing clusters was validated against secondary trade flow data, customs records for specialty steel alloy imports, and SEC filings of integrated construction conglomerates. Bottom-up unit economics modeling was triangulated with top-down market sizing from housing start permits and factory-built delivery registrations.
Forecast assumptions held METI regulatory enforcement timelines and JIS certification protocols fixed while varying steel input cost trajectories and municipal zoning approval velocities across regional prefectures. The analytical framework segmented volume and value outputs by product type, construction method, end-user archetype, and regional demand cluster across the modeling period. CAGRs were derived from regression analysis of historical factory-built housing starts against demographic replacement demand and urban renewal project pipelines, incorporating seismic risk zone migration patterns and thermal envelope upgrade adoption curves as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in domestic steel pricing volatility, Bank of Japan lending rate shifts, or municipal debt financing capacity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation consistency and JIS standards stability. Material shifts in MLIT Building Standards Act tolerance revisions or METI energy conservation threshold accelerations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
Egypt Residential Real Estate Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
Spain Residential Real Estate Market