
 North America Tiny Homes Market | 2026-2036
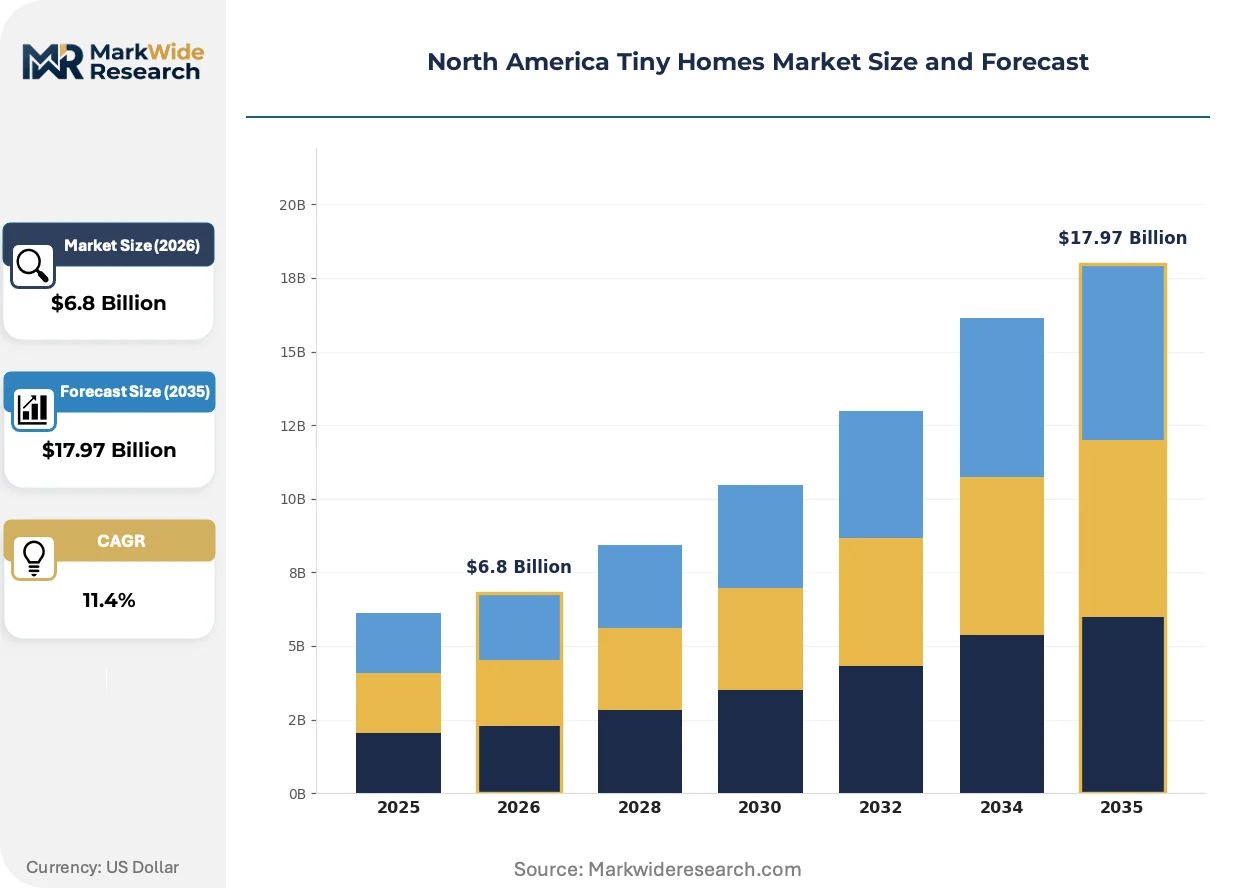
North America Tiny Homes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tiny Homes Market Analytics
Market Context
Prefabricated panel and steel-frame construction is tilting production economics toward factory-built tiny homes with tighter tolerances and shorter cycle times. Wind River Tiny Homes leverages CNC-cut timber framing to sustain premium positioning in the custom build segment. Rocky Mountain Tiny Houses anchors its operations in Colorado's Front Range, dominating regional distribution through direct-to-consumer sales channels. Tumbleweed Tiny House Company differentiates through RVIA-certified towable models that navigate interstate regulatory complexity.
Technical Definition and Segment Structure
North America tiny homes comprise dwellings typically spanning 100 to 400 square feet, constructed on permanent foundations, wheeled trailers, or repurposed shipping containers, utilizing space-efficient layouts with multi-functional built-ins and compact mechanical systems designed for full-time or seasonal occupancy. Mobile Tiny Homes and Modular Tiny Homes command the volume base, with container-based variants capturing margin pools among eco-conscious buyers seeking upcycled material credentials. Permanent Residence and Vacation Homes applications lead unit absorption, while the Rentals segment extends fastest as Airbnb operators and glamping developers scale inventory.
Regulatory Environment
The U.S. Department of Housing and Urban Development, state-level building code commissions, and local zoning boards collectively shape product standards, with IRC Appendix Q and NFPA 1192 providing baseline safety frameworks that manufacturers must satisfy for legal placement. Canadian provinces apply the National Building Code alongside municipal ADU bylaws, creating a patchwork compliance landscape that Mint Tiny House Company and Minimaliste must address through province-specific certifications. Stakeholders should monitor evolving state preemption laws that may override local tiny home prohibitions, as these legislative shifts will determine addressable market expansion faster than consumer preference alone.
Market Dynamics
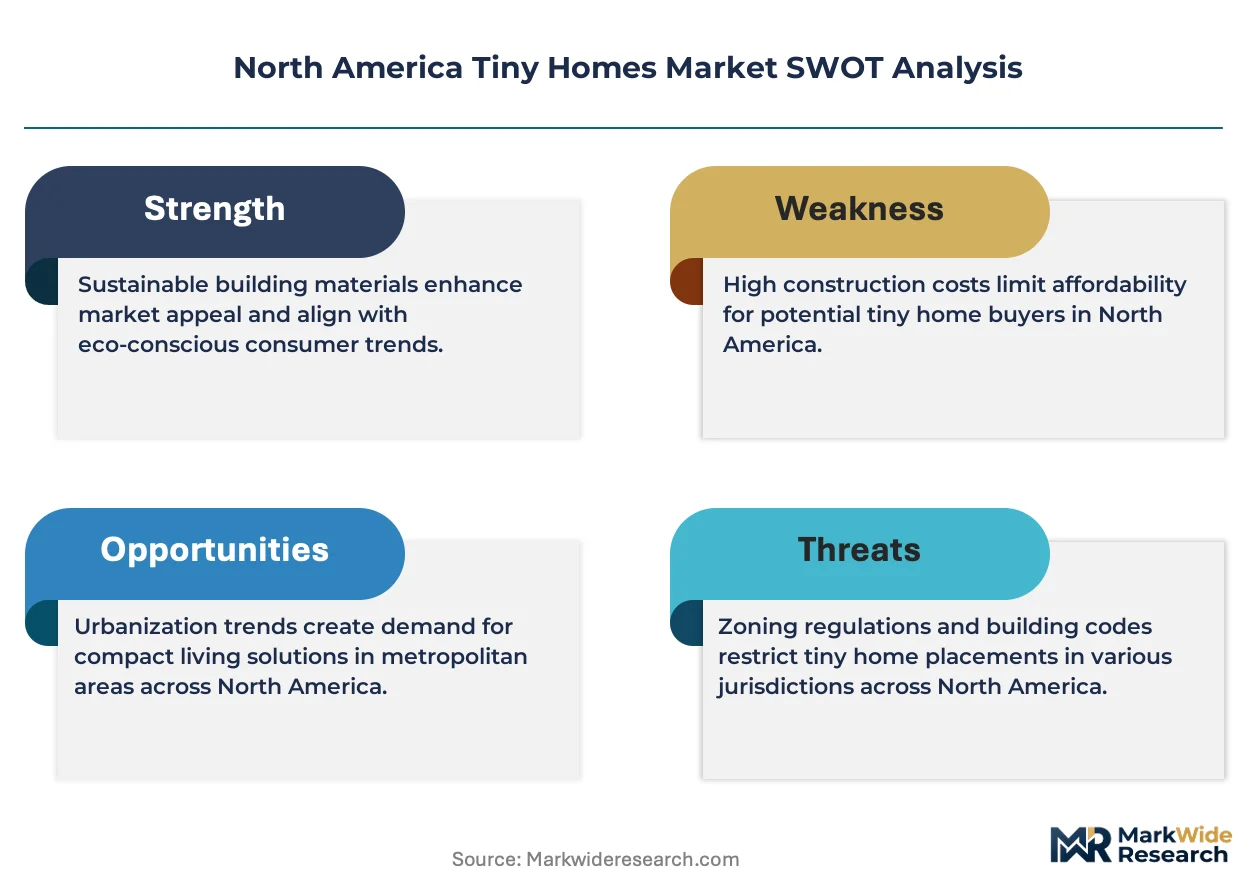
Municipal zoning preemption battles are fragmenting addressable markets, with state-level overrides of local square-footage minimums in Texas and Oregon unlocking lot placement while neighboring jurisdictions maintain prohibitions that strand manufactured inventory.
Growth Catalysts
- IRC Appendix Q adoption:The International Residential Code's tiny home appendix provides standardized safety frameworks that reduce jurisdictional variance in plan approval timelines across US states.
- Accessory dwelling unit liberalization:Colorado's statewide ADU preemption law eliminates single-family zoning barriers, permitting backyard placement on residential lots previously restricted to primary dwellings.
- Retiree downsizing migration:Aging cohorts in Arizona and Florida are liquidating suburban equity to acquire mortgage-free tiny homes, compressing average buyer age profiles.
Market Restraints
- Lumber input volatility:Softwood framing material costs swing unpredictably, squeezing gross margins on timber-intensive custom builds during supply-constrained quarters.
- Trailer chassis supply concentration:Domestic axle and steel-frame sourcing clusters in Indiana and Ohio, creating geographic vulnerability to regional manufacturing disruptions.
- Financing standardization gaps:Fannie Mae and Freddie Mac exclusion of non-permanent-foundation dwellings from conforming mortgage pools restricts buyer access to traditional credit.
Strategic Opportunities
- Canadian provincial expansion:British Columbia and Alberta municipal bylaws are relaxing minimum dwelling sizes faster than US counterparts, opening underpenetrated addressable markets for US manufacturers.
- Glamping developer channel:Airbnb Experience operators and boutique hospitality developers are procuring container-based units in volume for experiential lodging inventory.
- Solar-integrated envelope convergence:Building-integrated photovoltaics and structural insulated panel assembly are collapsing mechanical system footprint and energy connection costs simultaneously.
Industry Challenges
- RVIA certification timeline compression:Towable model manufacturers face 12-16 week inspection backlogs at Recreation Vehicle Industry Association facilities, delaying revenue recognition.
- Skilled carpentry labor scarcity:Precision timber framing and compact mechanical rough-in expertise concentrates in aging trades cohorts with limited apprenticeship pipeline replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tiny Homes Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Tiny Homes, Modular Tiny Homes, Container Homes, Customized Tiny Homes End User: Young Professionals, Retirees, Minimalists, Eco-Friendly Buyers Distribution Channel: Online Sales, Direct Sales, Retail Showrooms, Exhibitions Application: Permanent Residence, Vacation Homes, Guest Houses, Rentals |
| Companies Covered | Wind River Tiny Homes, Rocky Mountain Tiny Houses, Tumbleweed Tiny House Company, Decathlon Tiny Homes, Mint Tiny House Company, Modern Tiny Living, Tiny Mountain Houses, Tru Form Tiny, Minimaliste, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tiny Homes Market Evolving Landscape
Factory automation and modular assembly techniques are collapsing traditional site-built cost structures while compressing delivery windows from months to weeks.
CNC-cut timber framing systems are rendering obsolete conventional stick-built methods in the custom tiny home segment. Boutique builders serving high-net-worth downsizers have adopted five-axis routing equipment that machines complex joinery in controlled factory environments. The technology is rendering obsolete the premium pricing power previously attached to hand-crafted construction.
Texas Senate Bill 9 and comparable state preemption statutes are overriding municipal square-footage minimums that historically blocked legal tiny home placement. The legislation fragments regulatory compliance requirements, forcing manufacturers to maintain jurisdiction-specific product variants. Builders operating in Austin and Dallas-Fort Worth metro corridors are responding with foundation-compatible models engineered to satisfy both IRC Appendix Q and local structural wind-load amendments.
Direct-to-consumer digital configuration tools are displacing traditional dealer showroom experiences in buyer acquisition. Pacific Northwest and Mountain West purchasers now expect 3D visualization platforms that render interior layouts against actual destination topography. The channel shift is most visible in Colorado and Oregon, where remote land purchases frequently precede physical site visits.
North America Tiny Homes Market Segmentation
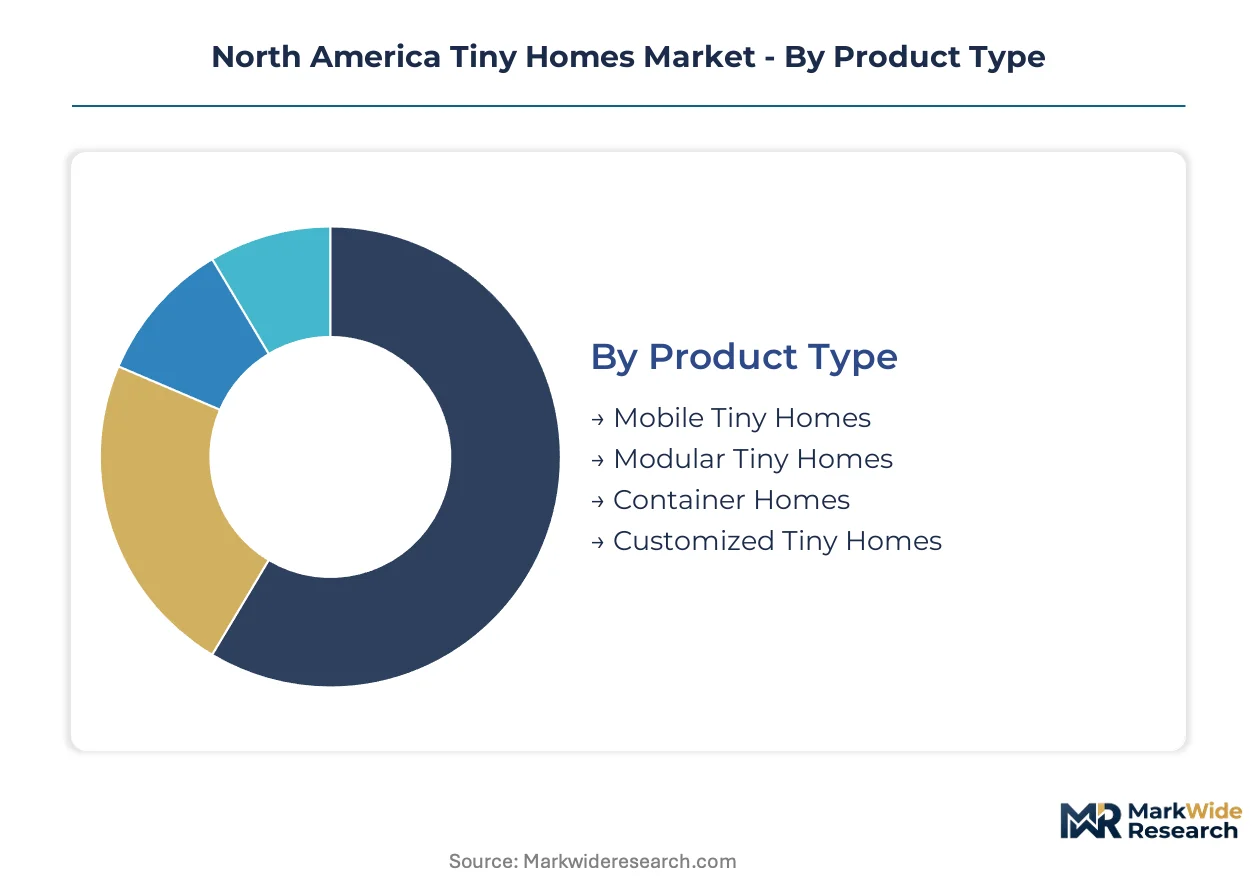
Segmentation in the North America tiny homes market reveals divergent production economics and buyer acquisition costs across structural formats. Manufacturers optimize factory layouts and material procurement differently depending on whether output targets mobile, modular, or container-based specifications.
Product Type:
Cycle times vary dramatically: mobile units complete in 4-6 weeks, while customized timber frames stretch to 16-20 weeks. This velocity spread determines working capital intensity and inventory turnover by segment.
- Mobile Tiny Homes:RVIA-certified towable structures built on steel chassis with axles rated for interstate highway speeds. Demand clusters in Texas and Florida where retirees seek snowbird mobility without permanent land commitment; chassis supply bottlenecks in Indiana periodically constrain output.
- Modular Tiny Homes:Factory-built sections transported and craned onto permanent foundations meeting IRC Appendix Q standards. Colorado's Front Range municipalities absorb volume fastest as ADU liberalization accelerates permitting timelines for foundation-compatible units.
- Container Homes:Repurposed shipping containers modified with cutouts, insulation, and mechanical systems. Eco-conscious buyers in Pacific Northwest pay premium pricing for upcycled material credentials and structural resilience.
- Customized Tiny Homes:Bespoke designs with CNC-cut joinery, premium finishes, and site-specific engineering. High-net-worth downsizers in Arizona and Oregon commission these for primary residence replacement.
Mobile Tiny Homes dominates installed base. Modular Tiny Homes is where expansion concentrates.
End User:
Buyer age and financing access split sharply across cohorts, with retirees deploying home equity while younger segments face non-conforming mortgage barriers.
- Retirees:Aging homeowners liquidating suburban properties to acquire mortgage-free dwellings with minimal maintenance obligations. Arizona and Florida absorption rates exceed national averages as equity-rich boomers downsize.
- Eco-Friendly Buyers:Environmentally motivated purchasers prioritizing embodied carbon metrics and off-grid capability. Container-based and solar-integrated models attract this segment in British Columbia and Oregon.
- Young Professionals:Remote workers seeking location flexibility and reduced housing cost burden. Financing constraints limit conversion rates as Fannie Mae exclusion of non-permanent foundations blocks traditional credit access.
- Minimalists:Lifestyle-ideology adopters pursuing intentional living with reduced possession loads. Pacific Northwest urban clusters show highest per-capita concentration of this buyer type.
Retirees command current revenue share. Eco-Friendly Buyers is climbing the fastest.
Distribution Channel:
Customer acquisition costs diverge by channel, with digital platforms collapsing geographic constraints while showrooms sustain premium-price conversion.
- Direct Sales:Manufacturer-owned channels eliminating dealer margins. Rocky Mountain builders leverage this in Colorado's Front Range with site visits to customer land parcels.
- Online Sales:Configuration tools with 3D visualization rendering interiors against destination topography. Mountain West and Pacific Northwest buyers purchase remotely before physical site visits.
- Retail Showrooms:Physical display models enabling tactile evaluation of space efficiency. Conversion rates justify higher fixed costs in Texas and Florida retirement corridors.
- Exhibitions:Trade show presence targeting aspirational buyers in early research phases. Tiny home festivals in Oregon and Colorado generate qualified lead pipelines.
Direct Sales anchors manufacturer margins. Online Sales is gaining share fastest.
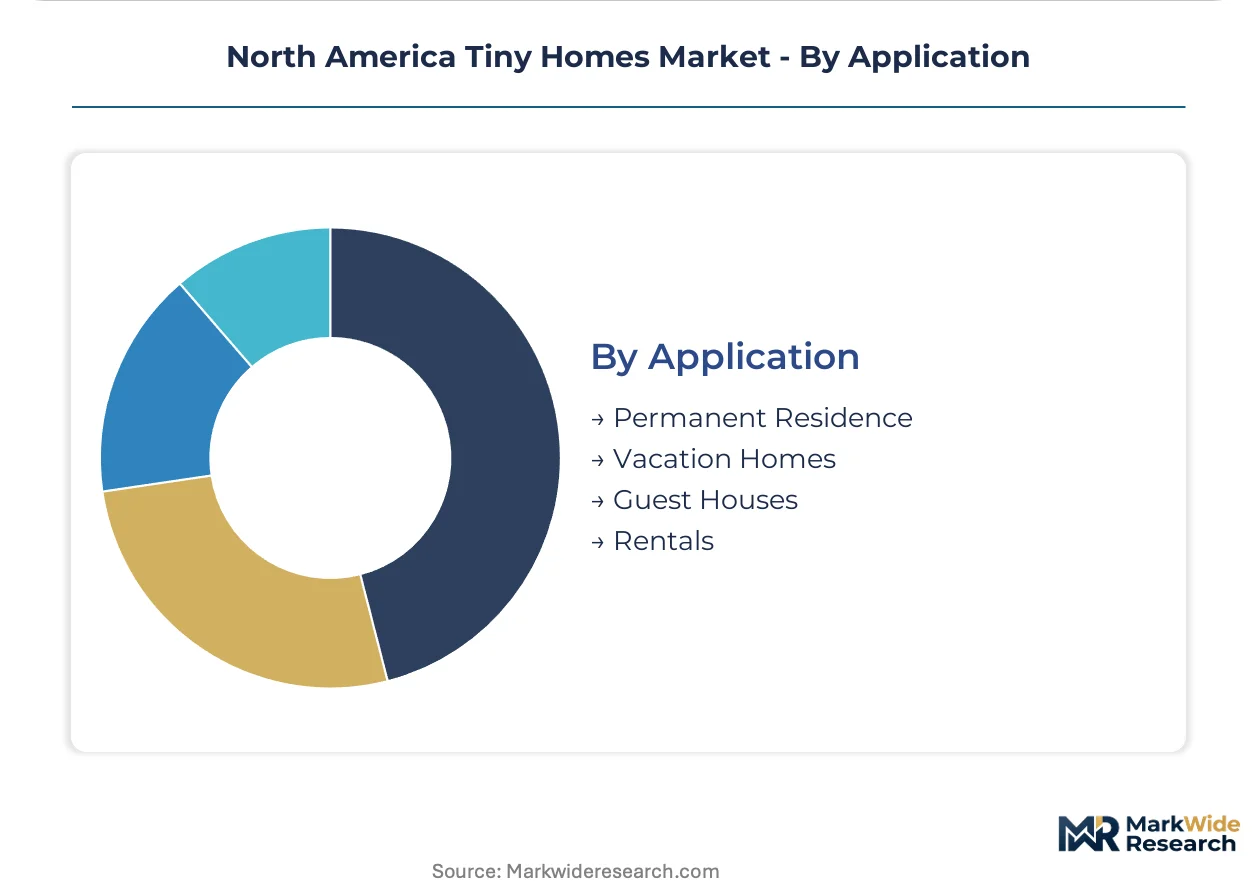
Application:
Revenue recognition timing varies: permanent residence sales close on delivery, while rental deployments generate recurring revenue streams with different capital requirements.
- Permanent Residence:Full-time occupancy dwellings requiring foundation compliance and utility connection. IRC Appendix Q adoption in Texas and Oregon accelerates permitting for this application.
- Rentals:Airbnb operators and glamping developers procuring units for experiential lodging inventory. Container-based variants scale fastest in British Columbia and Alberta.
- Vacation Homes:Seasonal-use structures on recreational land or secondary lots. Colorado mountain counties and Arizona desert regions absorb volume for weekend retreat use.
- Guest Houses:Backyard accessory dwellings on primary residential lots. California and Colorado ADU preemption laws unlock this application on previously restricted single-family zoned properties.
Permanent Residence holds current volume leadership. Rentals is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border component flows define the regional trade architecture, with Canadian timber and steel chassis from the U.S. industrial belt circulating through integrated North American supply chains. Mexico's emerging role concentrates on metal fabrication and trailer axle production for re-export.
United States
Texas and Colorado municipalities absorb the highest unit volumes as state preemption statutes override local square-footage minimums. HUD and IRC Appendix Q provide baseline safety frameworks that manufacturers satisfy for legal placement. Austin and Denver metro corridors anchor factory-built production clusters where ADU liberalization accelerates permitting timelines.
Canada
British Columbia and Alberta municipal bylaws relax minimum dwelling sizes faster than U.S. counterparts, opening underpenetrated addressable markets. Health Canada applies the National Building Code alongside provincial ADU regulations, creating patchwork compliance requirements. Vancouver and Calgary clusters concentrate container-based fabrication serving eco-conscious buyer segments.
Mexico
Northern border states supply steel trailer chassis and axle assemblies to U.S. manufacturers, leveraging maquiladora cost structures. Mexican federal housing programs and state-level construction codes shape informal market development. Nuevo León and Chihuahua industrial zones concentrate metal fabrication capacity for cross-border re-export.
Pacific Northwest
Oregon and Washington state building codes align progressive zoning with tiny home viability, attracting container-based and timber-framed production. State-level energy efficiency mandates and seismic requirements influence envelope specifications. Portland and Seattle metro areas cluster boutique builders serving minimalist and eco-friendly buyer cohorts.
Mountain West
Colorado's Front Range dominates regional distribution through direct-to-consumer channels as ADU preemption eliminates single-family zoning barriers. Arizona retirement corridors absorb vacation-home and permanent-residence deployments from equity-rich downsizers. Denver and Phoenix anchor competing production hubs with diverging buyer age profiles.
North America Tiny Homes Market Competitive Landscape
On the supply side, the industry is fragmented across geographic micro-clusters with limited national-scale consolidation, as zoning variance forces jurisdiction-specific product variants. Three strategic archetypes dominate: custom timber-frame boutiques serving high-net-worth downsizers, RVIA-certified towable manufacturers navigating interstate regulatory complexity, and container-based fabricators capturing eco-conscious premium pricing. Competitive moves center on geographic expansion into Canadian provinces and direct-to-consumer digital channel buildout.
Among U.S.-based fabricators, Wind River Tiny Homes and Tumbleweed Tiny House Company exemplify divergent positioning archetypes. Rocky Mountain Tiny Houses anchors regional concentration in Colorado's Front Range. These three occupy distinct competitive vectors—custom timber precision, certified towable mobility, and regional distribution density—rather than competing head-to-head for identical buyer segments.
| Leading Market Players |
|---|
| Wind River Tiny Homes |
| Rocky Mountain Tiny Houses |
| Tumbleweed Tiny House Company |
| Decathlon Tiny Homes |
| Mint Tiny House Company |
| Modern Tiny Living |
| Tiny Mountain Houses |
| Tru Form Tiny |
| Minimaliste |
| Others |
Value Network & Pricing Analysis
Single-source chassis dependency in Indiana and Ohio determines both three-tier pricing spreads across premium custom timber, standard modular, and economy mobile segments and the geographic clustering of final assembly operations near Great Lakes steel fabrication corridors.
Pricing Analysis
Retirees liquidating suburban equity anchor pricing stratification across premium, standard, and economy tiers, with CNC-cut custom builds commanding spreads over factory modular units based on joinery precision and RVIA certification grade. Price differentiation stems from foundation compliance requirements and after-sales service bundling. Cost compression in the economy mobile tier intensifies because lumber input volatility squeezes timber-intensive custom builders during supply-constrained quarters. Young professionals face the highest price sensitivity due to non-conforming mortgage barriers, while high-net-worth downsizers exhibit minimal sensitivity.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates cross-border timber and steel component flows that feed assembly operations in Texas and Colorado. Domestic supply draws from Canadian softwood, Indiana steel chassis, and Ohio axle assemblies. Single-source vulnerability concentrates in trailer chassis fabrication clusters. Distribution runs through direct-to-consumer digital platforms displacing traditional dealer showrooms in the Mountain West and Pacific Northwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through IRC Appendix Q adoption and municipal ADU preemption statutes creates defendable moats for early movers who secure jurisdiction-specific certifications ahead of state-level zoning liberalization waves.
For Market Incumbents: Pre-empt emerging container-based competitors by securing province-specific certifications in British Columbia and Alberta faster than cross-border rivals can replicate compliance infrastructure. Backward integration into CNC timber fabrication equipment locks in premium-tier positioning as five-axis routing becomes table stakes for high-net-worth downsizer segments. For New Entrants and Emerging Players: Build out digital configuration platforms targeting remote land purchasers in Colorado and Oregon who complete transactions before physical site visits. The glamping developer channel in British Columbia represents the most penetrable white-space target, with container-based units procured in volume for experiential lodging inventory. For Investors and Strategic Acquirers: Texas Senate Bill 9 and comparable state preemption statutes reshapes the acquisition landscape by fragmenting regulatory compliance requirements that favor multi-jurisdictional certification holders. Long-term viability hinges on builders capable of maintaining state-specific product variants without margin erosion. Monitor state-level preemption law passage rates as the primary inflection signal for addressable market expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| RVIA Certification Investment | Unlocks interstate towable sales for retirees seeking snowbird mobility across Texas and Florida corridors. |
| Canadian Provincial Expansion | Captures underpenetrated British Columbia and Alberta markets where municipal bylaws relax faster than U.S. counterparts. |
| Solar-Integrated Envelope Development | Collapses mechanical footprint and energy connection costs for off-grid eco-conscious buyers in Oregon. |
| Direct-to-Consumer Platform Buildout | Displaces dealer margins and enables 3D visualization against destination topography for Mountain West purchasers. |
| Foundation-Compatible Model Engineering | Satisfies both IRC Appendix Q and local wind-load amendments in Austin and Dallas-Fort Worth metro areas. |
Research Methodology
A standing panel of tiny home builders, municipal zoning officers, RVIA certification inspectors, and glamping developers provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from HUD regulatory filings, state building code commission records, municipal ADU ordinance databases, and Canadian National Building Code amendments. Bottom-up unit shipment tallies and top-down construction permit flows were triangulated to anchor volume estimates.
Scenario bracketing around lumber cost volatility, chassis supply disruption, and zoning preemption velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user cohort, distribution channel, and application use case. CAGRs were derived from regression analysis against housing affordability indices, retirement migration patterns, and ADU permitting velocity. Industry-specific inputs incorporated IRC Appendix Q adoption timelines and RVIA inspection backlog durations.
Stress conditions across softwood lumber pricing, trailer chassis availability, and state preemption legislative passage were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory liberalization pace and retiree equity liquidation rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
Europe Residential Real Estate Market