
 Canada E-House Market | 2026-2036
Canada E-House Market Size, Share, and Industry Trends Forecast 2026-2036
Canada E-House Market Outlook
Market Context
Canadian switchgear fabricators and electrical contractors is restructuring project delivery models around factory-built, transportable substation enclosures. Siemens AG leverages its Calgary engineering footprint to anchor western Canadian utility contracts with integrated automation packages. ABB Ltd. competes through its Burlington, Ontario facility, where it sustains a fabrication pipeline optimized for Arctic-rated enclosures. Schneider Electric SE differentiates via its Montreal-based microgrid controls division, which specializes in coupling E-House units with distributed generation architectures for remote industrial sites.
Technical Definition and Segment Structure
An E-House is a prefabricated, transportable metal enclosure housing medium-voltage switchgear, transformers, protection relays, and control systems, typically engineered to IP54 or NEMA 3R standards and delivered as a fully tested plug-and-play power distribution node. These structures serve mining camps, oil sands processing facilities, and renewable energy interconnection points where conventional brick-and-mortar substations face prohibitive construction timelines or permafrost constraints. Modular E-House configurations now dominate Canadian utility procurement because they compress commissioning schedules and permit seasonal installation windows in northern latitudes. Portable E-House units are gaining share in fly-in mining operations across Nunavut and the Northwest Territories, where equipment must relocate between extraction phases without permanent civil foundations. Fixed E-House demand remains concentrated in oil sands steam-assisted gravity drainage facilities around Fort McMurray, where decades-long production horizons justify permanent installations with 40-year design lifecycles.
Regulatory Framework and Outlook
Health Canada and provincial electrical safety authorities enforce CSA C22.2 and IEEE C37 series standards that govern arc-flash containment, seismic bracing, and fire-resistance ratings for enclosed switchgear assemblies. The Canadian Environmental Protection Act and provincial greenhouse gas regulations are pushing energy providers toward E-House configurations that integrate energy storage and smart grid interfaces to defer transmission upgrades. Alberta's Utilities Commission interconnection rules and British Columbia's CleanBC building codes collectively shape procurement specifications, particularly for renewable energy developers seeking streamlined grid access. Stakeholders must monitor evolving provincial carbon compliance deadlines and federal clean electricity regulations that will determine whether E-House procurement prioritizes fossil-fuel backup integration or pure battery-buffered designs.
Market Dynamics
Alberta's Utilities Commission interconnection timelines and British Columbia's CleanBC building codes are compressing procurement cycles, forcing utilities and industrial developers toward factory-built substation enclosures that bypass seasonal construction windows and permafrost engineering constraints.
Growth Catalysts
- Oil sands steam-assisted gravity drainage expansion:Decades-long production horizons around Fort McMurray justify permanent E-House installations with 40-year design lifecycles, sustaining factory order books.
- CSA C22.2 arc-flash containment mandates:Health Canada's tightening electrical safety requirements accelerate replacement of aging open-air switchgear with enclosed, pre-certified modular assemblies.
- Fly-in mining corridor electrification:Portable E-House units enable rapid power relocation across Nunavut and Northwest Territories extraction phases without permanent civil foundations.
Market Restraints
- Arctic-rated insulation material volatility:Cold-weather transformer fluids and composite enclosure materials face supply concentration from limited North American specialty chemical producers.
- Seismic bracing engineering bottlenecks:IEEE C37 series compliance for western Canadian fault zones requires scarce structural engineering capacity, extending design timelines.
- Brick-and-mortar substation substitution:Long-horizon municipal utilities in southern Ontario retain preference for conventional construction despite longer commissioning schedules.
Strategic Opportunities
- Yukon and northern Quebec mining frontiers:Underpenetrated territories lack established electrical contractor networks, creating first-mover advantage for integrated E-House suppliers with logistics capabilities.
- Battery-buffered microgrid convergence:Coupling E-House switchgear with distributed energy storage addresses federal clean electricity regulations while deferring transmission upgrades.
- Integrated automation package bundling:Factory-embedded protection relays and SCADA systems capture margin from electrical contractors who previously performed field integration.
Industry Challenges
- Arc-flash commissioning engineer scarcity:CSA-certified field technicians capable of live testing medium-voltage assemblies are concentrated in Calgary and Edmonton, creating mobilization bottlenecks for remote deployments.
- Legacy utility procurement system integration:Provincial crown corporations operate rigid capital budgeting cycles misaligned with factory fabrication lead times, forcing working capital strain on fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada E-House Market |
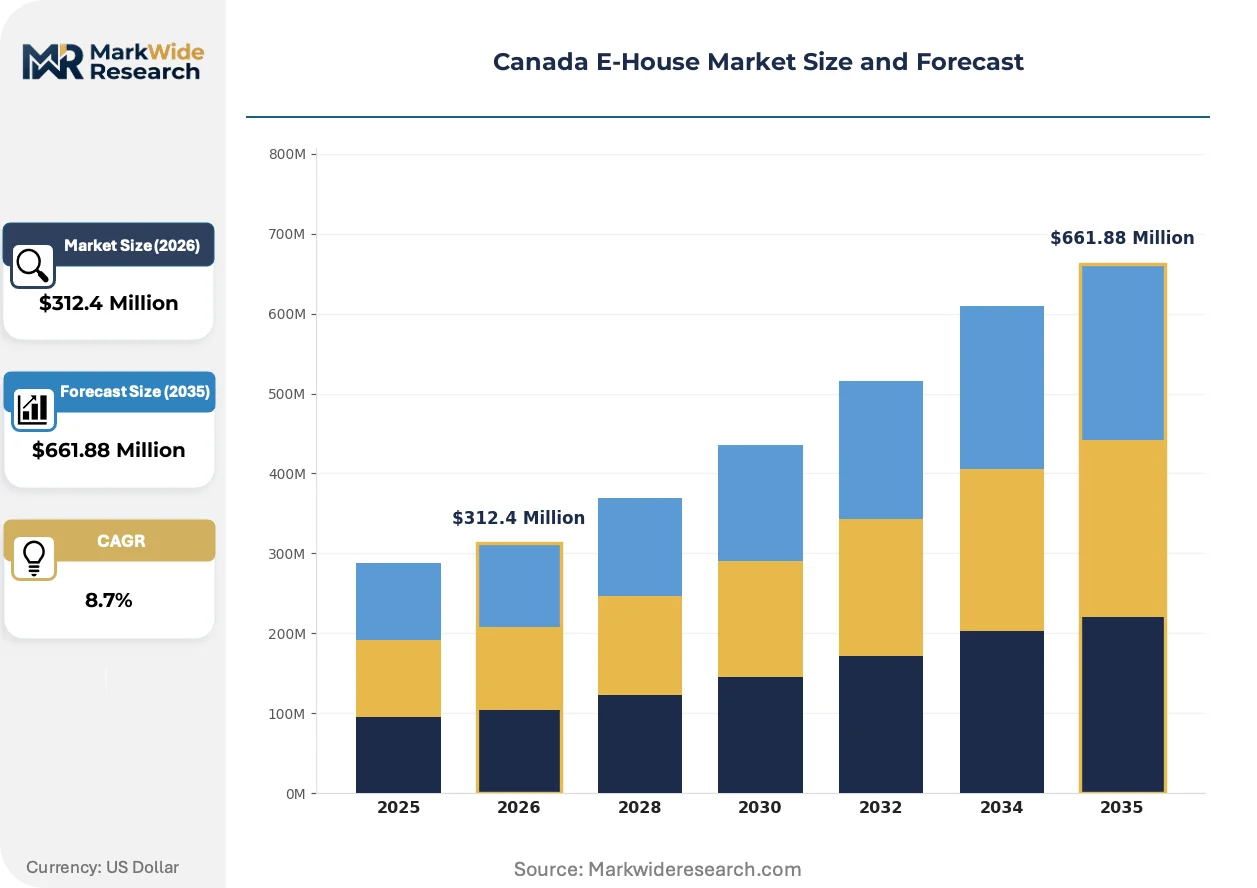
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular E-House, Portable E-House, Fixed E-House, Custom E-House Application: Mining, Renewable Energy, Oil & Gas, Utilities End User: Energy Providers, Construction Firms, Industrial Manufacturers, Mining Companies Technology: Distributed Generation, Energy Storage, Smart Grids, Microgrid Solutions |
| Companies Covered | Siemens AG, ABB Ltd., Schneider Electric SE, General Electric, Eaton Electric Ltd, Powell Industries, WEG S.A, Sonic Enclosures Ltd, Bird Construction Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada E-House Market Strategic Shifts
Digital twin modeling and predictive thermal monitoring are reshaping how E-House fabricators validate enclosure performance before site delivery, compressing commissioning risk and extending equipment lifecycle visibility for remote industrial operators.
Gas-insulated switchgear (GIS) technology is unifying medium-voltage protection and control functions within compact, sealed enclosures rated for Arctic temperature swings. Mining operators across Nunavut are specifying GIS-integrated E-House units to eliminate SF6 handling complexity in fly-in camps. This unifying architecture reduces footprint by sixty percent versus air-insulated alternatives, enabling helicopter transport to ridge-line exploration sites previously unreachable with conventional substation equipment.
Health Canada's proposed updates to CSA C22.2 No. 31 switchgear enclosures standards will mandate enhanced arc-venting and fire-resistance ratings for oil sands facilities. Fabricators in Alberta are pre-engineering blast-resistant wall assemblies and forced-ventilation interlocks to preempt compliance deadlines. Oil sands operators around Fort McMurray are accelerating procurement to lock in legacy specifications before stricter testing protocols take effect.
Engineer-procure-construct contractors are consolidating vendor relationships around single-source E-House suppliers who deliver fully commissioned power nodes rather than equipment-only packages. This disintermediation of field electrical work compresses project timelines but shifts liability exposure to fabricators for on-site performance guarantees. The pattern is most visible in British Columbia renewable energy interconnections, where developers face CleanBC-mandated carbon accounting that penalizes construction-phase emissions from extended site crews.
Canada E-House Market Segmentation
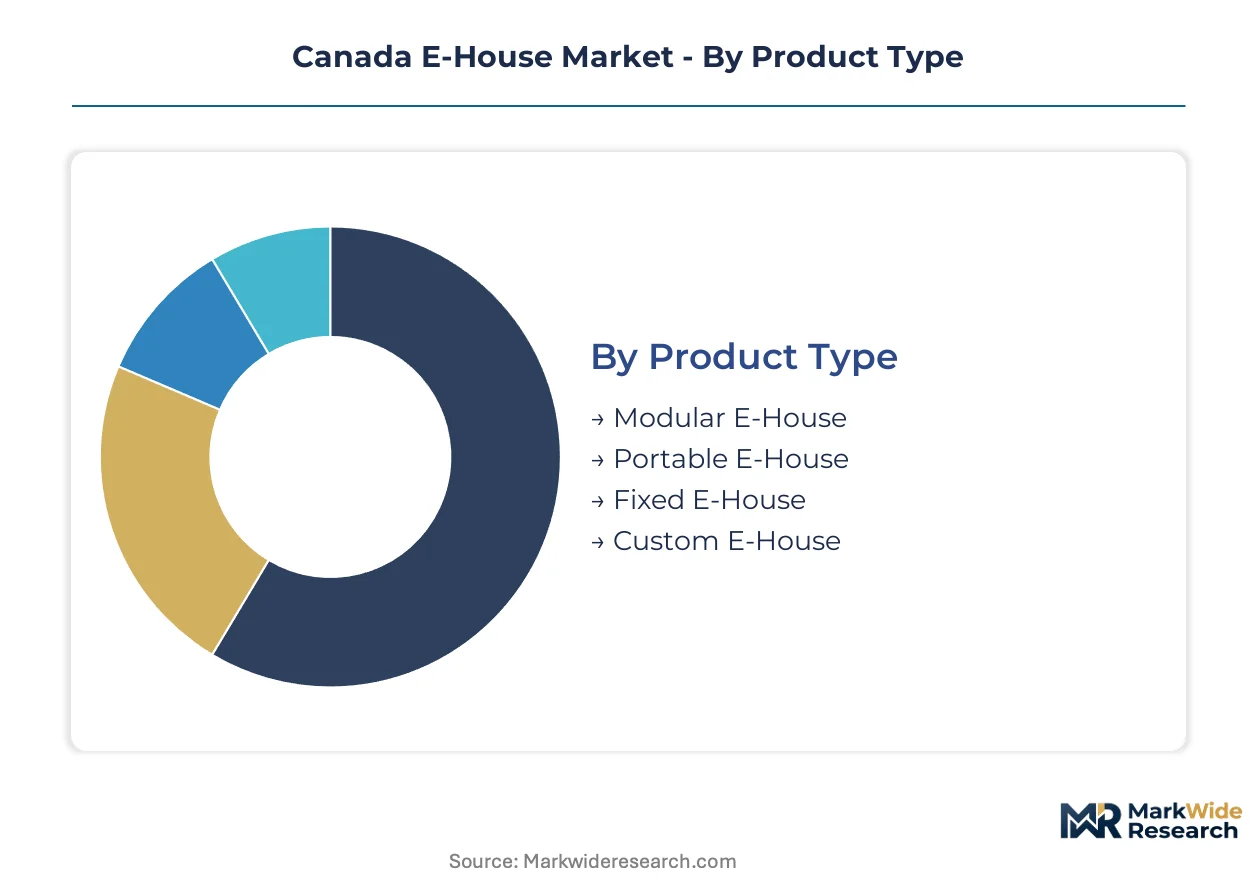
E-House procurement patterns across Canada diverge sharply by deployment permanence, industrial application, and grid integration architecture. Fabricators must align factory capacity with these structural fault lines to capture utility-scale contracts versus remote mining logistics.
Product Type:
Replacement cycles for aging brick-and-mortar substations are accelerating factory-built enclosure orders as Health Canada's CSA C22.2 mandates tighten arc-flash containment requirements.
- Modular E-House:Factory-assembled switchgear enclosures with standardized dimensions enable rapid site installation and future capacity expansion. Alberta utilities and British Columbia renewable developers dominate procurement, driven by interconnection deadline compression and seasonal construction windows.
- Portable E-House:Skid-mounted or trailer-based configurations deploy without permanent civil foundations. Fly-in mining camps across Nunavut and the Northwest Territories represent the core demand cluster, where equipment must relocate between extraction phases.
- Fixed E-House:Permanent installations with 40-year design lifecycles anchor oil sands steam-assisted gravity drainage facilities around Fort McMurray.
- Custom E-House:Bespoke enclosures accommodate non-standard switchgear configurations or extreme environmental ratings.
Volume placements concentrate in Modular E-House; the faster expansion belongs to Portable E-House.
Application:
Cost-tier differentiation separates megaproject-scale oil sands deployments from fragmented mining camp electrification.
- Mining:Remote extraction operations in northern territories require helicopter-transportable power infrastructure. Arc-flash commissioning engineer scarcity in Calgary and Edmonton creates mobilization bottlenecks for these deployments.
- Renewable Energy:British Columbia wind and solar interconnection projects prioritize factory-built enclosures to meet CleanBC carbon accounting mandates that penalize extended site crews.
- Oil & Gas:Decades-long production horizons justify premium fixed installations with integrated automation packages.
- Utilities:Provincial crown corporations operate rigid capital budgeting cycles that strain fabricator working capital.
Revenue concentration sits with Oil & Gas; Renewable Energy climbs the fastest.
End User:
Customer-type segmentation reveals divergent procurement sophistication between integrated energy majors and fragmented construction contractors.
- Energy Providers:Provincial utilities and independent power producers specify fully commissioned power nodes rather than equipment-only packages.
- Construction Firms:Engineer-procure-construct contractors consolidate vendor relationships around single-source suppliers to compress project timelines.
- Industrial Manufacturers:Processing facilities in southern Ontario retain preference for conventional substation construction despite longer commissioning schedules.
- Mining Companies:Operators across Yukon and northern Quebec mining frontiers lack established electrical contractor networks, creating first-mover opportunities.
Contract flow concentrates with Energy Providers; Mining Companies represent the steepest expansion trajectory.
Technology:
Supply concentration in Arctic-rated insulation materials shapes which grid integration architectures achieve scale.
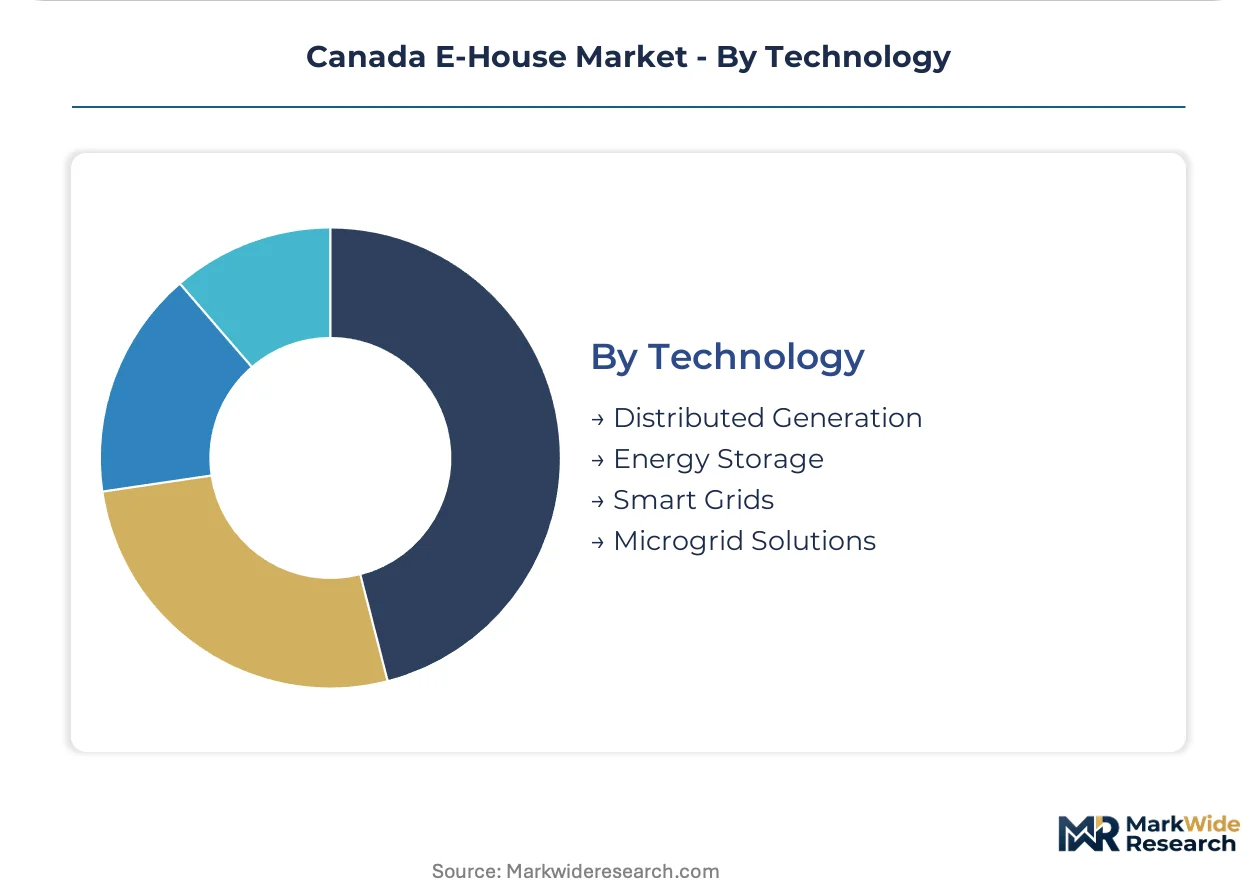
- Distributed Generation:On-site power production coupled with E-House switchgear addresses federal clean electricity regulations while deferring transmission upgrades.
- Energy Storage:Battery-buffered configurations integrate lithium-ion systems within enclosure assemblies to provide ride-through capability and peak shaving.
- Smart Grids:Digital twin modeling and predictive thermal monitoring validate enclosure performance before site delivery.
- Microgrid Solutions:Schneider Electric's Montreal-based controls division specializes in coupling E-House units with island-capable architectures for remote industrial sites.
Deployment scale favors Distributed Generation; Microgrid Solutions gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fort McMurray's oil sands deposits anchor Alberta's E-House procurement volume, while permafrost engineering constraints across northern territories concentrate portable unit demand in fly-in mining corridors.
Alberta
Oil sands steam-assisted gravity drainage facilities and utility interconnection deadlines drive factory-built enclosure orders. Alberta's Utilities Commission mandates compressed grid connection timelines that favor modular substation delivery. Fort McMurray industrial clusters sustain permanent E-House installations with 40-year design lifecycles.
British Columbia
Renewable energy developers and CleanBC carbon accounting requirements accelerate factory-built procurement. The province's building codes penalize construction-phase emissions from extended site crews. Vancouver and interior wind interconnection points concentrate modular E-House deployments.
Ontario
Municipal utilities and southern industrial manufacturers retain conventional substation preferences despite longer commissioning schedules. Provincial crown corporations operate rigid capital budgeting cycles misaligned with factory fabrication lead times. Greater Toronto Area electrical contractors face working capital strain from procurement system friction.
Quebec
Northern mining frontiers and underpenetrated electrical contractor networks create first-mover opportunities for integrated suppliers. Provincial interconnection standards and Health Canada safety mandates govern enclosure specifications. Montreal-based controls specialists couple E-House units with microgrid architectures for remote sites.
Northern Territories
Fly-in mining camps across Nunavut and the Northwest Territories require helicopter-transportable power infrastructure without permanent civil foundations. Arctic-rated insulation materials and seismic bracing requirements concentrate demand for portable configurations. Ridge-line exploration sites specify compact GIS-integrated units for equipment relocation between extraction phases.
Canada E-House Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue battery-buffered microgrid convergence and integrated automation bundling. The vendor base stratifies across three archetypes: integrated automation packagers capturing margin from field electrical work, Arctic-rated enclosure specialists, and engineer-procure-construct consolidators. Competitive positioning sharpens around factory-embedded commissioning capabilities and logistics reach into underpenetrated northern territories. Dominant moves include vendor relationship consolidation by EPC contractors and pre-engineering of blast-resistant assemblies ahead of CSA C22.2 updates.
Among Germany-based industrial conglomerates, Siemens AG exemplifies the integrated automation tier through western Canadian utility anchoring. Swiss-domiciled ABB Ltd. occupies a position within Arctic-rated fabrication, while French-headquartered Schneider Electric SE represents the microgrid convergence archetype through Montreal-based controls specialization. These three entities collectively illustrate how geographic engineering footprints align with provincial procurement clusters.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Schneider Electric SE |
| General Electric |
| Eaton Electric Ltd |
| Powell Industries |
| WEG S.A |
| Sonic Enclosures Ltd |
| Bird Construction Corp |
| Others |
Value Chain & Pricing Dynamics
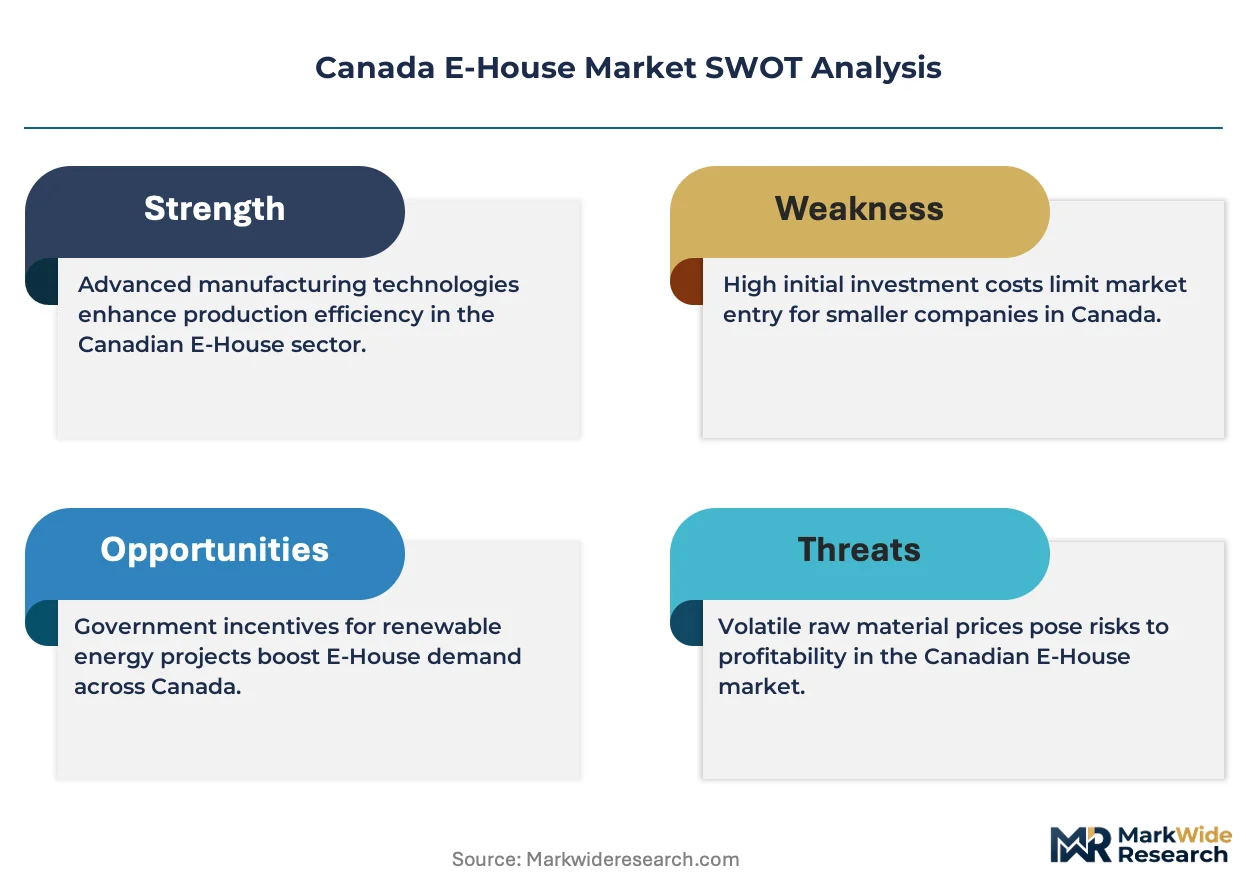
Arctic-rated transformer fluids and cold-weather composite enclosure materials flow from limited North American specialty chemical producers through three distinct pricing tiers downstream. Factory-embedded commissioning capabilities and logistics reach into underpenetrated northern territories separate premium fabricators from standard-tier competitors facing margin compression.
Pricing Analysis
Warranty and factory-embedded commissioning bundling distinguishes premium E-House suppliers from equipment-only vendors competing on base enclosure cost. Three-tier pricing structure across premium, standard, and economy levels reflects arc-flash certification grade, seismic bracing complexity, and automation integration depth. Pricing pressure stems from provincial crown corporations' rigid capital budgeting cycles misaligned with factory fabrication lead times, forcing working capital strain on fabricators. Municipal utilities in southern Ontario exhibit highest price sensitivity due to brick-and-mortar substation substitution preferences, while oil sands operators around Fort McMurray prioritize 40-year lifecycle reliability over upfront cost.
Supply Chain Analysis
CSA-certified structural engineers and arc-flash commissioning technicians concentrate in Calgary and Edmonton, creating mobilization bottlenecks for remote deployments. Manufacturing capacity clusters in Burlington, Ontario, Montreal, Quebec, and Calgary, Alberta, with raw material dependencies on cold-weather insulation compounds, seismic-rated steel alloys, and gas-insulated switchgear components. Single-source vulnerability runs through Arctic-rated specialty chemical producers for transformer fluids and composite materials. Distribution runs through engineer-procure-construct contractors consolidating vendor relationships around single-source suppliers capable of delivering fully commissioned power nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as fabricators capture margin previously earned by field electrical contractors through factory-embedded protection relays and SCADA systems. Control over upstream commissioning capabilities and downstream logistics reach determines competitive positioning.
For Market Incumbents: Hedge against margin erosion by deepening captive supply of CSA-certified arc-flash commissioning engineers and pre-engineering blast-resistant wall assemblies ahead of Health Canada's proposed CSA C22.2 No. 31 updates. Lock in multi-year service contracts with Alberta Utilities Commission-interconnected utilities to offset working capital strain from provincial crown corporation procurement cycles. Secure exclusive relationships with Arctic-rated insulation material suppliers to defend against specialty chemical producer supply concentration. For New Entrants and Emerging Players: Battery-buffered microgrid convergence offers a technology-first wedge into underpenetrated Yukon and northern Quebec mining frontiers lacking established electrical contractor networks. Target fly-in mining camps across Nunavut and the Northwest Territories with helicopter-transportable GIS-integrated portable E-House units. Partner with Montreal-based controls specialists for microgrid architecture integration to bypass incumbent automation package advantages. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated E-House suppliers with captive logistics capabilities in Alberta and British Columbia during provincial utility procurement slowdowns. Long-term viability hinges on factory-embedded commissioning scale and Arctic-rated enclosure certification depth. Watch Alberta Utilities Commission interconnection timeline compression and Health Canada CSA C22.2 compliance deadline acceleration as inflection indicators for premium-tier fabricator margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Commissioning Engineering | Captive CSA-certified technician capacity in Calgary and Edmonton secures remote deployment mobilization advantage. |
| Arctic-Rated Material Supply Agreements | Long-term contracts with North American specialty chemical producers hedge cold-weather insulation volatility. |
| Battery-Buffered Microgrid Convergence | Coupling E-House switchgear with distributed energy storage addresses federal clean electricity regulations. |
| Blast-Resistant Pre-Engineering | Preemptive CSA C22.2 No. 31 compliance investment captures oil sands procurement acceleration ahead of mandate deadlines. |
| Northern Territory Logistics Buildout | Helicopter-transportable unit staging in Yellowknife and Iqaluit unlocks Yukon and Nunavut mining frontier penetration. |
Study Parameters
Health Canada electrical safety filings, Alberta Utilities Commission interconnection records, and provincial crown corporation procurement databases formed the secondary backbone for market sizing and regulatory timeline mapping. Primary interviews with utility planning officers, EPC contractor procurement leads, E-House fabricator engineering directors, and arc-flash commissioning technicians validated factory capacity utilization and seasonal installation window constraints. Bottom-up triangulation across product type, application, and regional deployment patterns reconciled with top-down utility capital expenditure tracking.
Bottom-up modeling segmented volume and value across modular, portable, fixed, and custom E-House configurations, then cross-referenced against oil sands production horizon data and renewable energy interconnection queues. Top-down validation drew from provincial utility integrated resource plans and CleanBC carbon accounting mandate implementation schedules. CAGRs were derived from regression analysis of historical factory order books against interconnection deadline compression trends and CSA certification requirement phase-ins. Forecast inputs incorporated Arctic-rated material supply constraints and seismic bracing engineering capacity scarcity.
Several conditions sit outside the modeled scope, including federal clean electricity regulation finalization timing, provincial carbon compliance deadline adjustments, and specialty chemical producer capacity expansion decisions. Forecasts reflect assumptions about Health Canada CSA C22.2 enforcement consistency and Alberta Utilities Commission interconnection timeline adherence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Egypt Residential Real Estate Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
Spain Residential Real Estate Market