
 Indonesia Residential Real Estate Market | 2026-2036
Indonesia Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Residential Real Estate Market Insights
Buyer concentration among first-time purchasers in Greater Jakarta is realigning developer priorities toward affordable and mid-range inventory. Agung Podomoro Group leverages its integrated township model to capture this demographic across multiple price tiers. Sinar Mas Land anchors its position through large-scale master-planned communities in Tangerang and BSD City. Ciputra Development differentiates via mixed-use concepts that blend residential units with retail and education facilities.
Indonesia residential real estate encompasses completed and under-construction dwelling units intended for owner occupation or rental income, typically involving reinforced concrete frame construction with masonry infill and minimum floor-area ratios set by local zoning codes. The primary commercial purpose centers on delivering habitable space that satisfies household shelter demand while generating capital appreciation and rental yield for investors. Apartments and condominiums dominate transaction volumes in Jakarta and Surabaya where land scarcity pushes vertical development, whereas townhouses and villas command premium pricing in suburban corridors with lower density allowances. Luxury and mid-range segments attract institutional capital and affluent domestic buyers, but affordable housing draws the deepest buyer pool supported by government mortgage subsidy programs.
Indonesia's Ministry of Public Works and Public Housing sets building codes and spatial planning standards that determine permissible density and infrastructure obligations, while Bank Indonesia regulates mortgage loan-to-value ratios to manage systemic credit risk in property lending. Local governments issue location permits and building approval documents that directly gate project commencement timelines. Stakeholders must monitor regulatory shifts in foreign ownership rules and subsidized lending programs that alter accessible buyer segments.
Market Dynamics
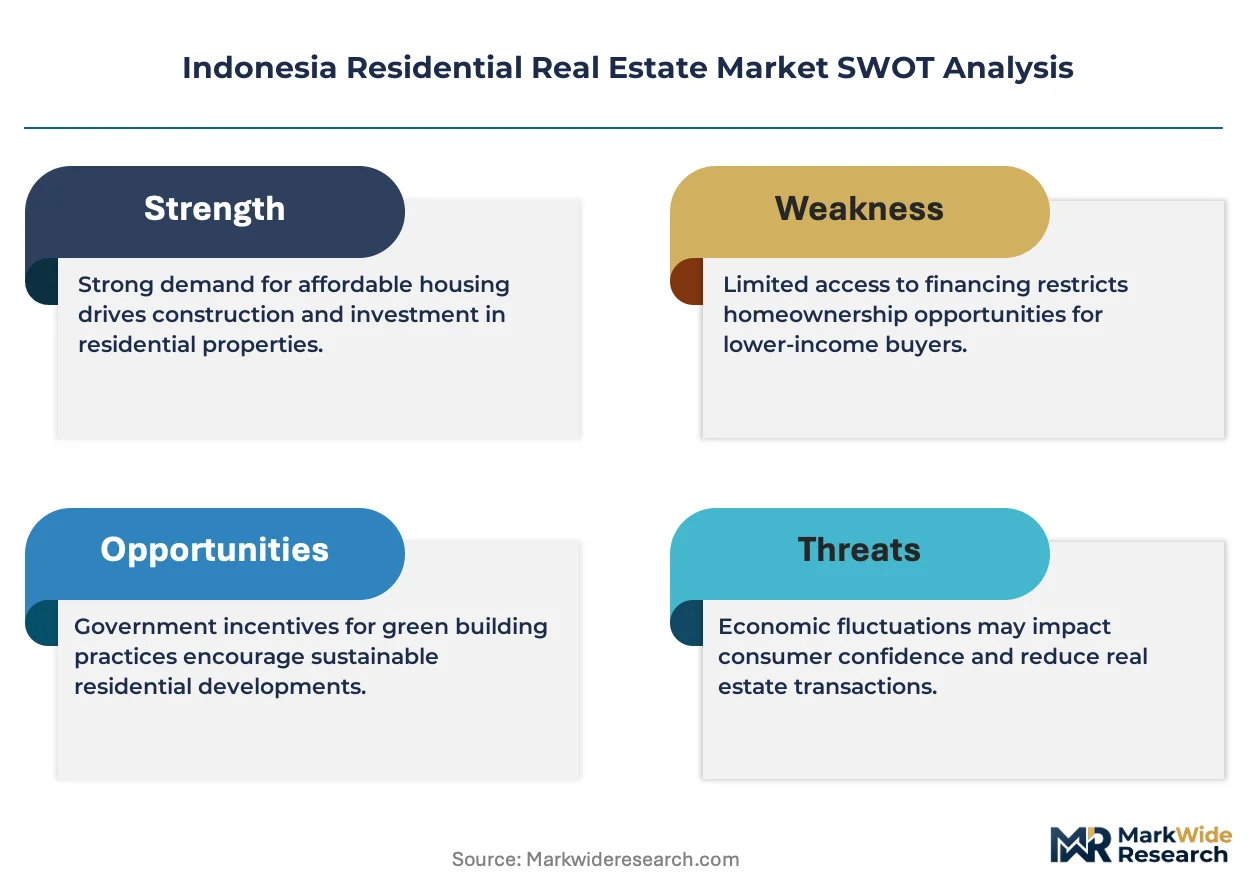
Indonesia's residential real estate sector faces intensifying pressure from mortgage subsidy program expansion and satellite city infrastructure buildout, which is compressing developer margins while accelerating transaction velocity in Greater Jakarta's peripheral corridors.
Growth Catalysts
- Subsidy Program Extension:Indonesia's Ministry of Public Works and Public Housing maintains mortgage interest rate subsidies through the FLPP scheme, expanding accessible buyer pools in the affordable segment. This mechanism channels credit to first-time purchasers who dominate transaction volumes.
- Spatial Planning Liberalization:Revised Perda RTRW regulations streamline building permit issuance timelines, reducing project gestation periods for developers operating in Tangerang and Bekasi satellite zones. Permit acceleration unlocks inventory faster than historical baselines.
- Vertical Development Technology:Precast concrete panel systems and modular construction methods reduce high-rise completion cycles. These techniques enable developers to deliver apartment inventory ahead of demand surges in land-scarce Jakarta core districts.
Market Restraints
- Land Banking Concentration:Developable land in Greater Jakarta concentrates among legacy holders with decades-old permits, creating artificial scarcity that inflates raw land costs for new entrants. This structural bottleneck limits competitive supply response.
- Rebar and Cement Price Volatility:Input costs for reinforced concrete frame construction fluctuate with domestic steel mill output and clinker import dependencies. Margin compression intensifies when commodity cycles spike during project execution phases.
- Foreign Ownership Caps:Presidential Regulation No. 103/2015 restricts foreign nationals to leasehold structures and designated price floors, excluding offshore capital from mass-market segments. This regulatory friction segments investable inventory.
Strategic Opportunities
- Secondary City Penetration:Surabaya and Medan exhibit undersupplied mid-range inventory relative to household formation rates. Developers with township replication capabilities can transplant proven Jakarta satellite models into these demographically expanding hubs.
- Integrated Utility Convergence:Smart metering infrastructure and distributed solar generation are converging with residential development specifications. Early adopters capturing this technology pairing differentiate projects through operational cost transparency.
- Sharia Financing Channel:KPR Syariah products via Bank Indonesia's regulatory framework unlock religiously observant buyer segments previously excluded from conventional mortgage structures. This channel innovation expands addressable market breadth.
Industry Challenges
- Licensed Quantity Surveyor Scarcity:Project cost control and certification documentation face bottlenecks from limited professional surveyor supply. This talent gap extends pre-construction timelines and inflates third-party verification expenses.
- Legacy Title Clearance Complexity:Land banking acquisitions require navigating overlapping customary (adat) claims and colonial-era registration gaps. Due diligence intensity consumes capital deployment cycles before physical construction commences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Residential Real Estate Market |
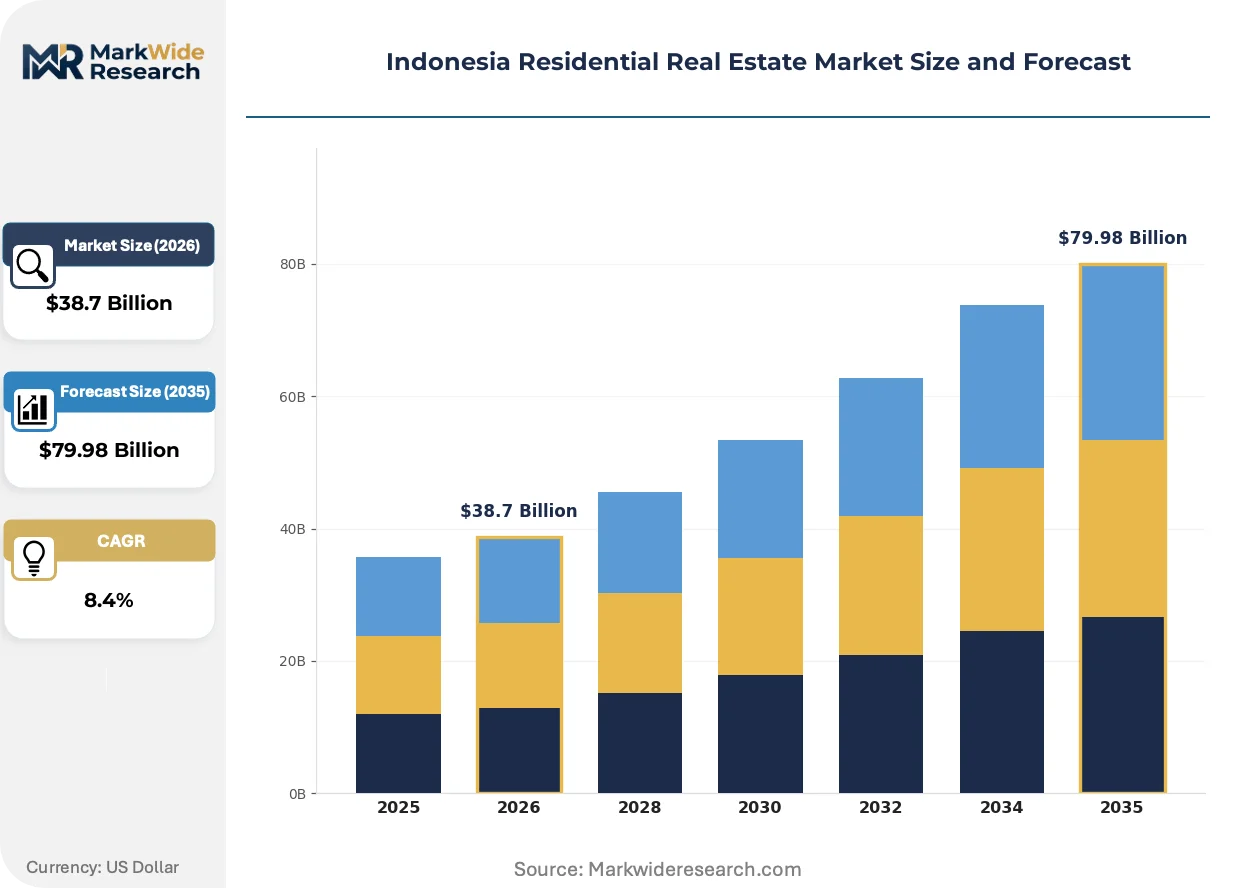
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Condominium, Apartment, Townhouse, Villa Price Tier: Luxury, Mid-Range, Affordable, Budget Buyer Type: First-Time Buyers, Real Estate Investors, Locals, Expats Sale Method: Direct Sales, Auctions, Off-Plan, Resale |
| Companies Covered | Agung Podomoro Group, PT Pakuwon Jati, Sinar Mas Land, PT Wijaya Karya (Persero) Tbk, PT PP (Persero) Tbk, Ciputra Development, PT Bumi Serpong Damai, PT Summarecon Agung, Lippo Karawaci, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Residential Real Estate Market Trends and Innovations
Digital transaction platforms and sustainable building specifications are reconfiguring how Indonesian residential inventory reaches buyers, with technology intermediation and environmental compliance emerging as parallel vectors of competitive differentiation.
Building Information Modeling (BIM) software is expanding into developer pre-sales and construction sequencing workflows. Mid-scale developers in BSD City and Alam Sutera clusters adopt BIM for clash detection and material takeoff precision. This technology compression reduces change-order frequency and accelerates handover timelines.
Bank Indonesia's macroprudential policy on loan-to-value ratios tightens speculative purchase leverage while preserving first-home buyer access. The industrial consequence channels credit toward owner-occupier segments and away from pure investment acquisitions. Jakarta's condominium pre-sale market responds with smaller unit footprints to maintain entry price accessibility under tighter lending ceilings.
Buyer research behavior has shifted toward virtual reality walkthroughs and drone-captured site progress documentation. Developer marketing teams in Tangerang satellite projects now deploy these tools to replace physical showhouse visits. This channel disintermediation compresses sales cycles for out-of-province purchasers evaluating Greater Jakarta inventory remotely.
Indonesia Residential Real Estate Market Segmentation
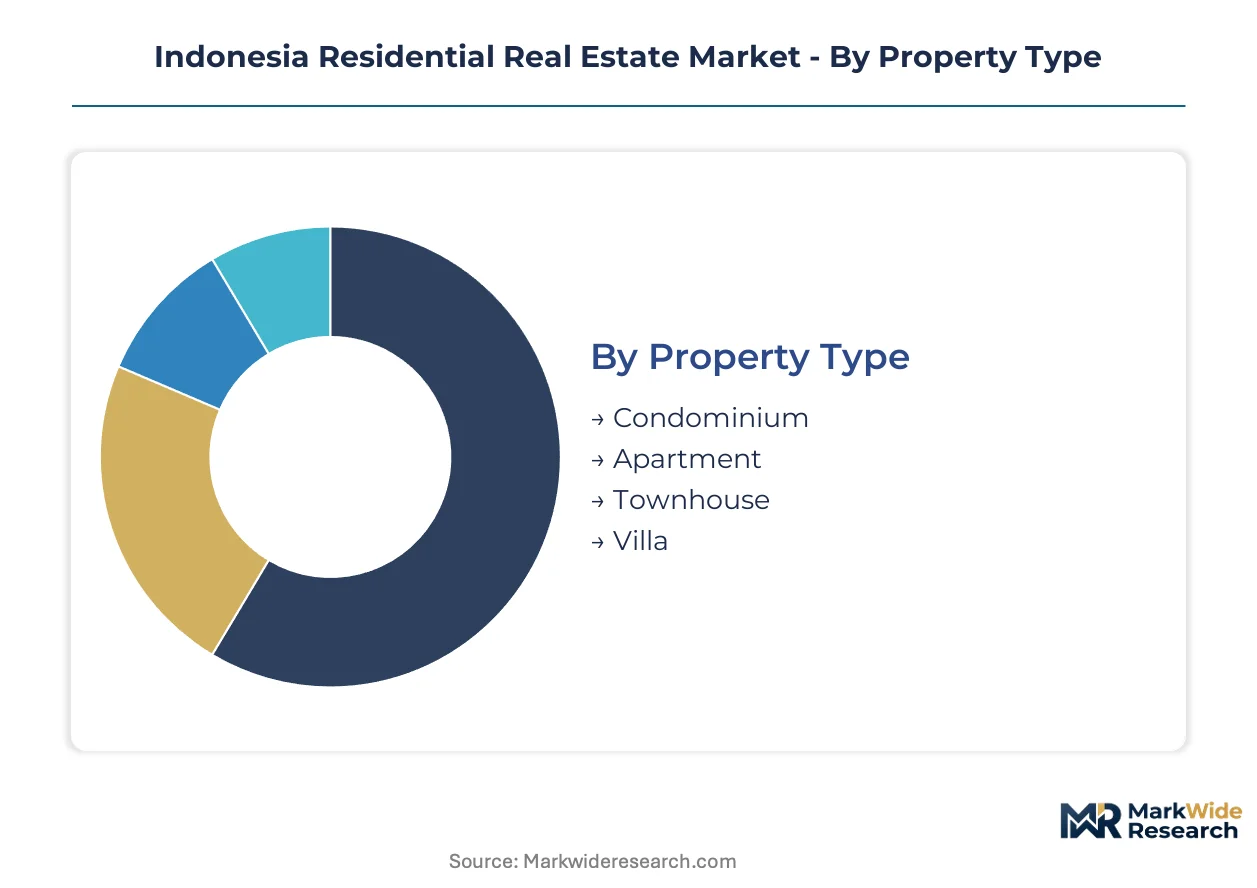
Segmentation in Indonesia's residential real estate market reveals how construction methods, buyer demographics, and transaction mechanics fragment addressable demand. Developers align product specifications with distinct financing channels and regulatory constraints across each axis.
Property Type:
Structural design choices determine density permissions, construction timelines, and capital intensity across Indonesia's urban corridors.
- Condominium:Strata-titled vertical units with shared common areas and management bodies. Demand concentrates in Jakarta's CBD and Surabaya's central districts where Perda RTRW permits high-rise density and land scarcity pushes developers skyward.
- Apartment:Rental-oriented vertical dwellings with simpler ownership structures than condominiums. Peripheral zones in Tangerang and Bekasi absorb this inventory as first-time buyers leverage FLPP subsidies for entry-level vertical living.
- Townhouse:Attached low-rise units with private ground-level access. BSD City and Alam Sutera clusters favor this format for mid-range buyers seeking space without villa-level land costs.
- Villa:Detached single-family residences on dedicated plots. Premium coastal and hillside locations in Bali and Lombok attract expat and luxury domestic purchasers.
Mature deployment sits with apartments in Greater Jakarta's satellite cities. Newer deployment is concentrated in condominiums as vertical development technology compresses high-rise completion cycles.
Price Tier:
Cost positioning governs accessible buyer pools, subsidy eligibility, and margin structures across Indonesia's mortgage-financed market.
- Luxury:Units exceeding established price floors with premium finishes and amenity packages. Jakarta's Sudirman-Thamrin corridor and Bali's Seminyak district anchor this segment for high-net-worth domestic and expatriate purchasers.
- Mid-Range:Products targeting creditworthy professionals with conventional KPR financing. Surabaya and Medan exhibit undersupply relative to household formation rates, creating expansion opportunities for township replicators.
- Affordable:FLPP-subsidized inventory with price ceilings and interest rate support. Ministry of Public Works and Public Housing program parameters dictate specifications and eligible buyer income brackets.
- Budget:Informal and formal low-cost housing outside subsidy frameworks. Secondary city peripheries absorb this segment where land costs permit minimal infrastructure investment.
Volume leadership belongs to affordable tier units in Greater Jakarta. The steepest expansion trajectory runs through mid-range inventory as satellite city infrastructure matures.
Buyer Type:
Purchaser profiles determine financing instrument selection, unit size preferences, and holding period expectations.
- First-Time Buyers:FLPP-eligible owner-occupiers dominating transaction volumes in Tangerang and Bekasi. Bank Indonesia LTV regulations preserve their credit access while constraining speculative leverage.
- Real Estate Investors:Yield-focused purchasers seeking rental income and capital appreciation. Condominium pre-sales in Jakarta's CBD attract this group despite foreign ownership caps limiting offshore participation.
- Locals:Domestic purchasers across all price tiers with conventional KPR or KPR Syariah financing. Sharia-compliant products unlock religiously observant segments previously excluded from conventional mortgage structures.
- Expats:Foreign nationals restricted to leasehold structures and designated price floors under Presidential Regulation No. 103/2015. Bali and Jakarta's premium corridors concentrate this limited-demand pool.
Transaction velocity concentrates with first-time buyers leveraging subsidized credit. Investor participation is compressing under tighter macroprudential policy.
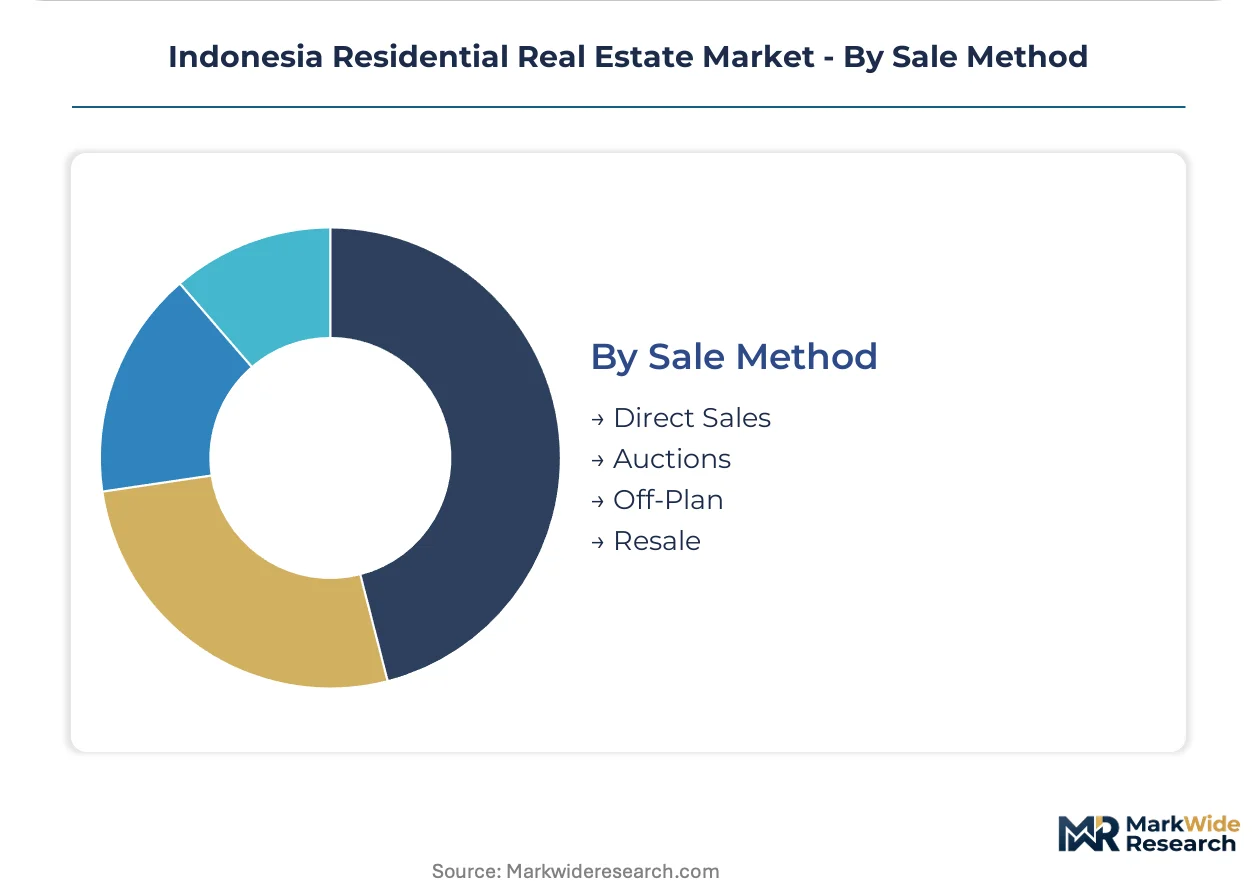
Sale Method:
Transaction mechanics determine developer cash flow timing, buyer risk exposure, and regulatory compliance intensity.
- Direct Sales:Immediate ownership transfer upon completion with standard mortgage processing. Established developers in BSD City rely on this method for inventory with clear title and finished construction.
- Auctions:Price-discovery mechanisms for distressed or unique assets. Foreclosed properties and estate sales in Jakarta's secondary market utilize this channel.
- Off-Plan:Pre-construction sales with staged payment schedules tied to construction milestones. Vertical projects in land-scarce districts depend on this mechanism to fund construction progression.
- Resale:Secondary market transactions between existing owners and new purchasers. Satellite city maturation is expanding this channel as initial owner-occupiers upgrade or relocate.
Primary market dominance rests with off-plan sales for vertical developments. Resale channel expansion is accelerating in Tangerang and Bekasi as early township phases reach maturity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
First-time buyers in Greater Jakarta dominate transaction volumes, concentrating demand across Indonesia's most liquid residential corridor. Satellite city infrastructure buildout in Tangerang and Bekasi channels this buyer pool outward from the capital core. Ministry of Public Works and Public Housing permit streamlining accelerates inventory delivery in these peripheral zones.
Greater Jakarta
Jakarta's satellite cities of Tangerang and Bekasi absorb the deepest buyer pool through FLPP-subsidized mortgage access. Perda RTRW spatial planning revisions compress building permit timelines for developers operating in these corridors. BSD City and Alam Sutera anchor master-planned community deployment across multiple price tiers.
Surabaya
Household formation rates in East Java's capital outpace mid-range inventory supply, creating absorption capacity for township replication models. Bank Indonesia's macroprudential LTV regulations preserve first-home buyer credit access in this secondary hub. Rungkut and Benowo industrial zones drive employment migration that feeds residential demand.
Medan
North Sumatra's demographic expansion supports formal housing penetration beyond informal settlement patterns. Ministry of Public Works and Public Housing affordable housing programs extend subsidy eligibility to this underserved northern corridor. Deli Serdang regency concentrates developer land banking for future township phases.
Bali
Expatriate and luxury domestic purchasers sustain premium villa demand despite foreign ownership restrictions under Presidential Regulation No. 103/2015. Leasehold structures dominate transaction mechanics for offshore capital deployment. Seminyak and Canggu sub-markets anchor high-end inventory absorption.
Bandung
West Java's tertiary education concentration generates rental demand from student and young professional segments. Cimahi and Gedebage corridors absorb vertical development as land scarcity intensifies in the central city. Local government location permit issuance governs project commencement velocity.
Indonesia Residential Real Estate Market Competitive Landscape
Jakarta-based developers anchor the premium tier; satellite city specialists hold volume leadership through township scale. Market structure concentrates around integrated township operators with legacy land positions and state-linked constructors with public project pipelines. Three archetypes dominate: master-planned community developers, vertical construction specialists, and hybrid state-private consortiums. Competitive dynamics center on land banking velocity and permit acquisition timelines rather than price competition.
Among integrated township developers, Agung Podomoro Group, Sinar Mas Land, and Ciputra Development occupy distinct positioning archetypes. Agung Podomoro represents the multi-tier inventory model spanning affordable through luxury segments within single developments. Sinar Mas Land anchors large-scale satellite city deployment with infrastructure bundling capabilities. Ciputra Development exemplifies mixed-use convergence strategies that blend residential delivery with retail and education facility integration.
| Leading Market Players |
|---|
| Agung Podomoro Group |
| PT Pakuwon Jati |
| Sinar Mas Land |
| PT Wijaya Karya (Persero) Tbk |
| PT PP (Persero) Tbk |
| Ciputra Development |
| PT Bumi Serpong Damai |
| PT Summarecon Agung |
| Lippo Karawaci |
| Others |
Pricing and Supply Chain Analysis
Precast concrete panel systems and modular construction methods are compressing high-rise completion cycles while simultaneously redistributing cost economics toward off-site manufacturing clusters. This production-method transition concentrates supply leverage among developers with captive precast facilities in Greater Jakarta's satellite corridors, compressing margins for competitors dependent on spot-market concrete sourcing.
Pricing Analysis
Volume leadership concentrates in affordable tier units where FLPP subsidies cap developer pricing power, while margin protection runs through mid-range inventory in maturing satellite cities. Three-tier pricing structure across premium, standard, and economy levels separates luxury villas in Bali from BSD City townhouses and Tangerang apartments. Pricing pressure stems from rebar and cement input volatility, with Bank Indonesia LTV regulations intensifying buyer price sensitivity among first-time purchasers in the affordable segment.
Supply Chain Analysis
Freight cost escalation from Java's northern port corridors to Bekasi and Tangerang construction sites is amplifying landed material expenses for developers without backward-integrated logistics. Domestic supply draws from Indonesia's domestic steel mills and clinker import dependencies, with raw material feeds resting on rebar, cement, and masonry infill components. Single-source vulnerability concentrates in legacy land banking holders with decades-old permits. Distribution runs through direct developer-to-buyer channels for off-plan vertical projects and established brokerage networks for resale inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's residential real estate sector sits in a technology-transition phase where Building Information Modeling workflows are displacing legacy 2D drafting and manual quantity surveying. This shift rewards early adopters with compressed change-order frequency and accelerated handover timelines.
For Market Incumbents: Acquire licensed quantity surveyor capacity and BIM implementation expertise to offset talent scarcity bottlenecks. Consolidate land banking positions in Deli Serdang and Rungkut corridors before spatial planning liberalization triggers permit competition. Defensive positioning against modular construction specialists requires backward integration into precast panel production. For New Entrants and Emerging Players: Mortgage brokers and Sharia financing intermediaries represent the most accessible channel partnership archetype for market entry. White-space targets concentrate in Surabaya's undersupplied mid-range segment and Medan's formal housing transition zone. Go-to-market positioning through KPR Syariah products unlocks religiously observant buyer pools previously excluded from conventional mortgage structures. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated township operators seeking satellite city replication capabilities. Long-term viability favors developers with mixed-use convergence competencies blending residential delivery with retail and education facility integration. The signal to watch is FLPP subsidy program continuity as an inflection indicator for affordable segment demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Township Development | Captures first-time buyer volume through FLPP-subsidized mortgage access in Tangerang and Bekasi corridors. |
| Modular Construction Adoption | Compresses high-rise completion cycles using precast concrete panel systems in land-scarce Jakarta districts. |
| Sharia Financing Channel Buildout | Expands addressable market breadth via KPR Syariah products compliant with Bank Indonesia regulatory frameworks. |
| Secondary City Replication | Transports proven satellite city models into Surabaya and Medan where household formation outpaces inventory supply. |
| Smart Utility Convergence | Differentiates projects through operational cost transparency from smart metering and distributed solar integration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with property development executives, mortgage lending officers, spatial planning officials, and construction procurement managers combined with secondary validation from Bank Indonesia macroprudential disclosures, Ministry of Public Works and Public Housing permit databases, and regional trade association construction material price indices. Bottom-up project pipeline enumeration and top-down household formation modeling enabled cross-verification.
Granularity-level modeling deployed property type, price tier, buyer segment, and sale method dimensions at the metropolitan zone level across the projection horizon. CAGRs derived from cohort-specific absorption rate trajectories and inventory completion schedules. Forecast inputs incorporated FLPP subsidy program parameters, Perda RTRW spatial planning revision timelines, and macroprudential LTV regulation scenarios.
Caveats apply where subsidy program discontinuation, commodity price spikes, or regulatory reversals on foreign ownership could materially shift the outlook. Forecasts reflect documented assumptions about infrastructure buildout velocity and mortgage credit availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
Egypt Residential Real Estate Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
North America Real Estate Brokerage Market
Residential Real Estate Market
South Africa Residential Real Estate Market