
 ASEAN Condominiums and Apartments Market | 2026-2036
ASEAN Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Condominiums and Apartments Market Outlook
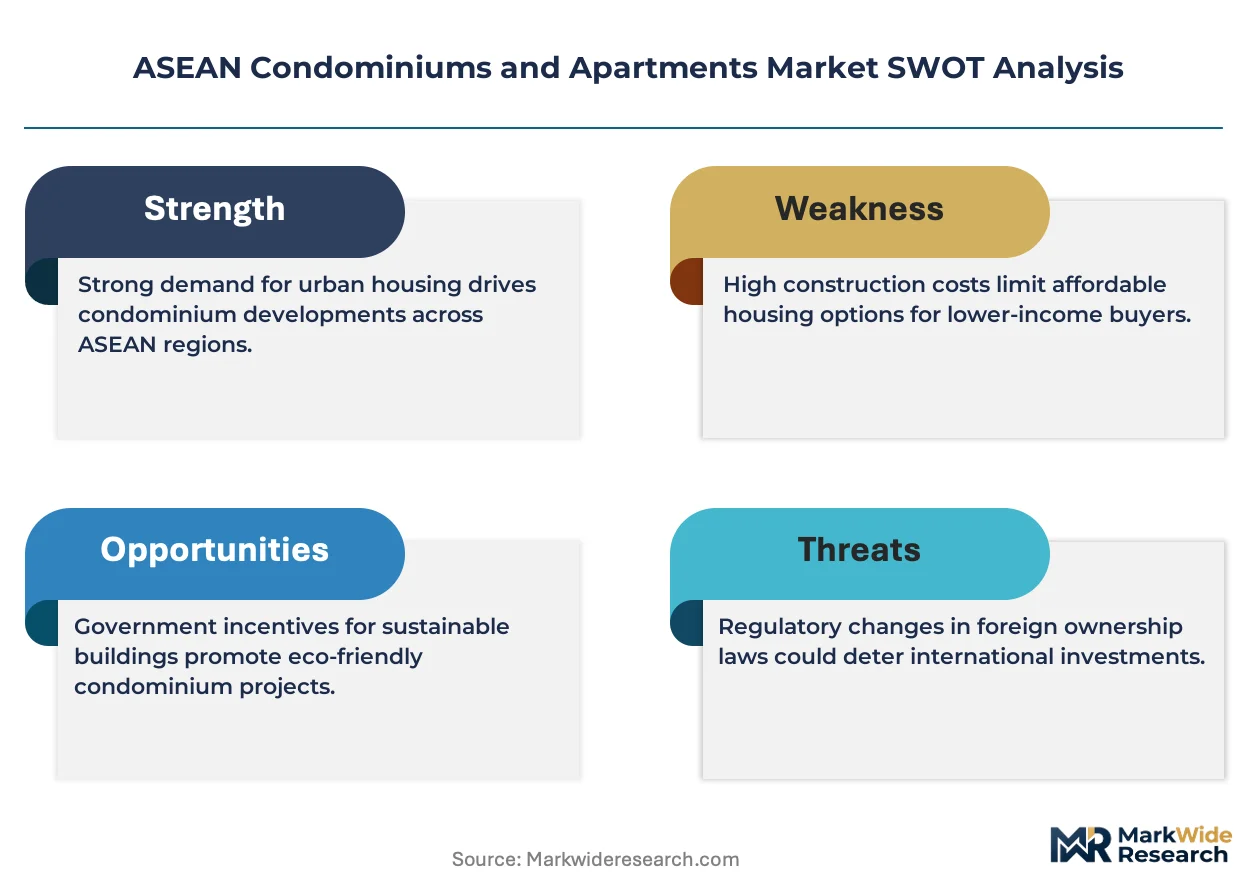
Premium-tier specifications is reorganizing the ASEAN residential development landscape. CapitaLand Limited leverages its integrated development model across Singapore and Vietnam to sustain competitive positioning. Ayala Land Inc. anchors its portfolio in Metro Manila's mixed-use precincts, while Sansiri Public Company Limited specializes in Bangkok's transit-oriented luxury segments.
ASEAN condominiums and apartments comprise multi-unit residential structures with reinforced concrete frames, fire-rated compartmentation, and centralized utility distribution systems designed for vertical urban density. These assets serve commercial purposes through strata-titled ownership, rental yield generation, and capital appreciation in supply-constrained metropolitan cores. Luxury apartments and penthouse suites command disproportionate margin pools across the price tier spectrum, while studio apartments and small units attract the fastest-growing end-user base of young professionals seeking transit-proximate housing. The size segmentation reveals medium units as the mature volume anchor, with extra-large units and ultra-premium pricing concentrating developer returns in selective gateway cities.
Thailand's Condominium Act B.E. 2522 and its amendments, Singapore's Building and Construction Authority codes, and the Philippines' Housing and Land Use Regulatory Board standards collectively shape product specifications, foreign ownership quotas, and market access conditions across the region. These frameworks influence unit mix decisions, completion timelines, and cross-border investment flows. Stakeholders must monitor evolving foreign buyer restrictions and green building mandates as determinants of project viability and capital deployment sequencing.
Market Dynamics
Smart building technology integration is compressing development timelines and reshaping capital allocation priorities across ASEAN metropolitan residential construction. Developers now sequence technology procurement ahead of structural completion to capture premium pricing tiers.
Growth Catalysts
- Transit-oriented development mandates:Bangkok's Metropolitan Rapid Transit expansions and Ho Chi Minh City's Metro Line 1 are concentrating condominium approvals within 500-meter radii of station nodes.
- Thailand's Condominium Act B.E. 2522 amendments:Foreign ownership quota relaxations in designated investment zones are unlocking cross-border capital flows into secondary city centers.
- Cross-laminated timber hybrid systems:Malaysian and Indonesian developers are piloting engineered wood-concrete composites to reduce embodied carbon in mid-rise structures.
Market Restraints
- Reinforced steel price volatility:ASEAN's dependence on imported billet from Chinese state-owned mills exposes project margins to exchange-rate and tariff fluctuations.
- Geographic supply concentration:Elevator and escalator systems consolidate around Japanese and European OEMs with limited regional manufacturing footprint.
- Philippines' HLURB foreign ownership ceilings:The 40% equity cap in condominium corporations constrains institutional capital deployment in Metro Manila's premium segments.
Strategic Opportunities
- Vietnam's secondary city corridor:Da Nang and Can Tho exhibit undersupplied luxury inventory relative to inbound foreign direct investment flows.
- Singapore's Green Mark certification acceleration:Mandatory super-low energy building standards from 2030 are creating first-mover advantage for integrated design-build operators.
- PropTech-embedded sales channels:Virtual reality unit customization and blockchain-based strata-title registries are shortening pre-sale conversion cycles.
Industry Challenges
- Building information modeling expertise scarcity:ASEAN engineering consultancies face talent gaps in 5D BIM cost integration and digital twin deployment.
- Fire-rated facade system certification delays:Testing backlog at Singapore's Building and Construction Authority laboratories extends product approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Condominiums and Apartments Market |
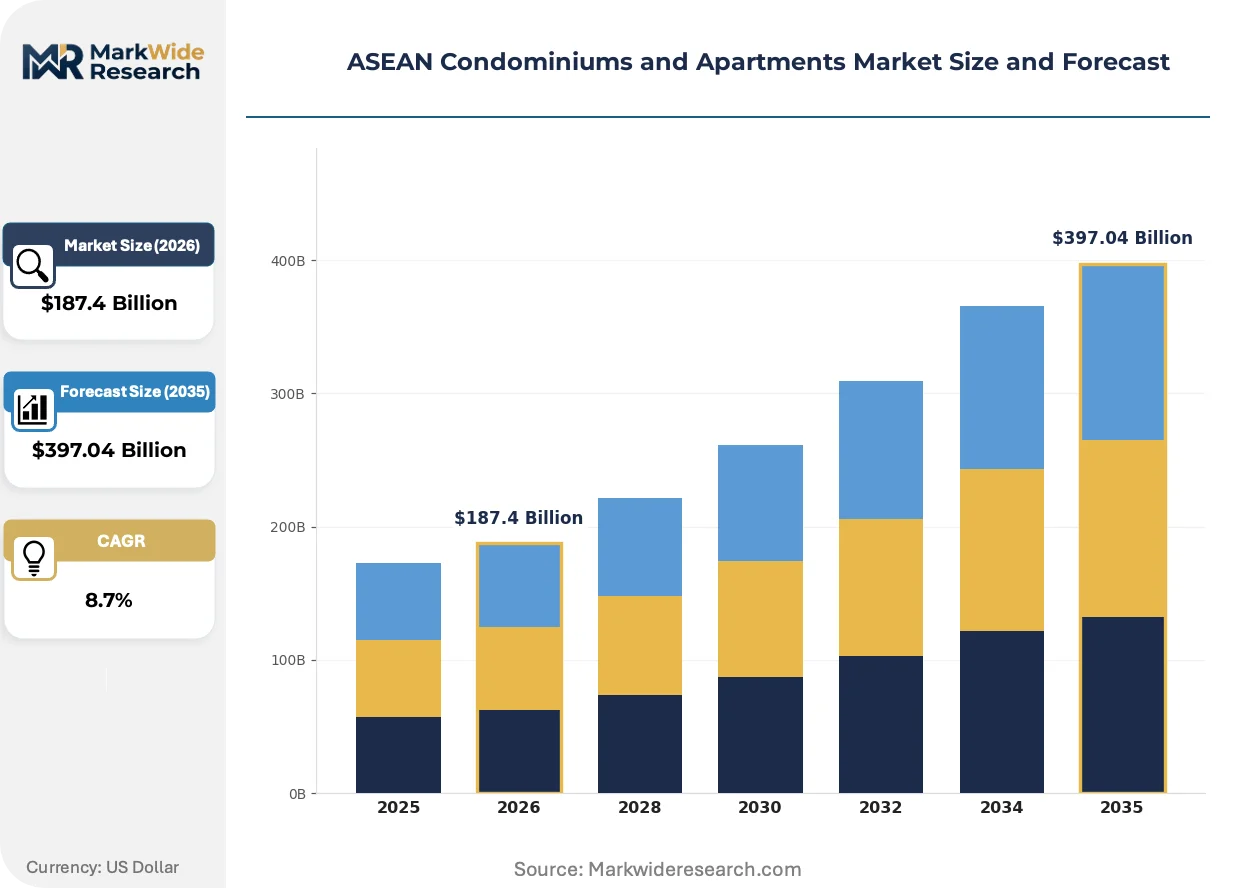
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Apartments, Studio Apartments, Duplexes, Penthouse Suites End User: Young Professionals, Families, Retirees, Foreign Investors Size: Small Units, Medium Units, Large Units, Extra-Large Units Price Tier: Affordable, Mid-range, Premium, Ultra-Premium |
| Companies Covered | CapitaLand Limited, Ayala Land Inc., SM Development Corporation, Frasers Property Limited, UOL Group Limited, Sansiri Public Company Limited, Megaworld Corporation, SP Setia Bhd, City Developments Limited, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Condominiums and Apartments Market Strategic Shifts
Digital twin construction workflows and modular prefabrication are compressing traditional development cycles across ASEAN gateway cities. These shifts are redistributing value capture from general contractors to technology-integrated asset managers.
Integrated building automation platforms combining IoT sensors, predictive maintenance algorithms, and tenant-facing mobile applications are supplanting legacy mechanical-electrical systems in premium-tier developments. Bangkok and Singapore developers now mandate platform interoperability as a procurement condition. This technology compression is enabling remote facility management at portfolio scale, reducing on-site staffing requirements by half.
Singapore's Building Control Act amendments mandating super-low energy building standards from 2030 are accelerating deep retrofit specifications in existing stock. Developers must now model whole-life carbon performance at planning submission stage. The premium condominium segment bears the steepest compliance cost escalation, passing efficiency investments through to per-square-meter pricing.
Young professional households are consolidating housing search and financing origination through integrated PropTech platforms rather than traditional brokerage channels. Vietnam and Indonesia markets exhibit the fastest channel migration, with digital-native buyers expecting virtual staging and mortgage pre-approval within single-session transactions. This behavior shift is compressing developer marketing spend toward platform partnerships and away from physical show galleries.
ASEAN Condominiums and Apartments Market Segmentation
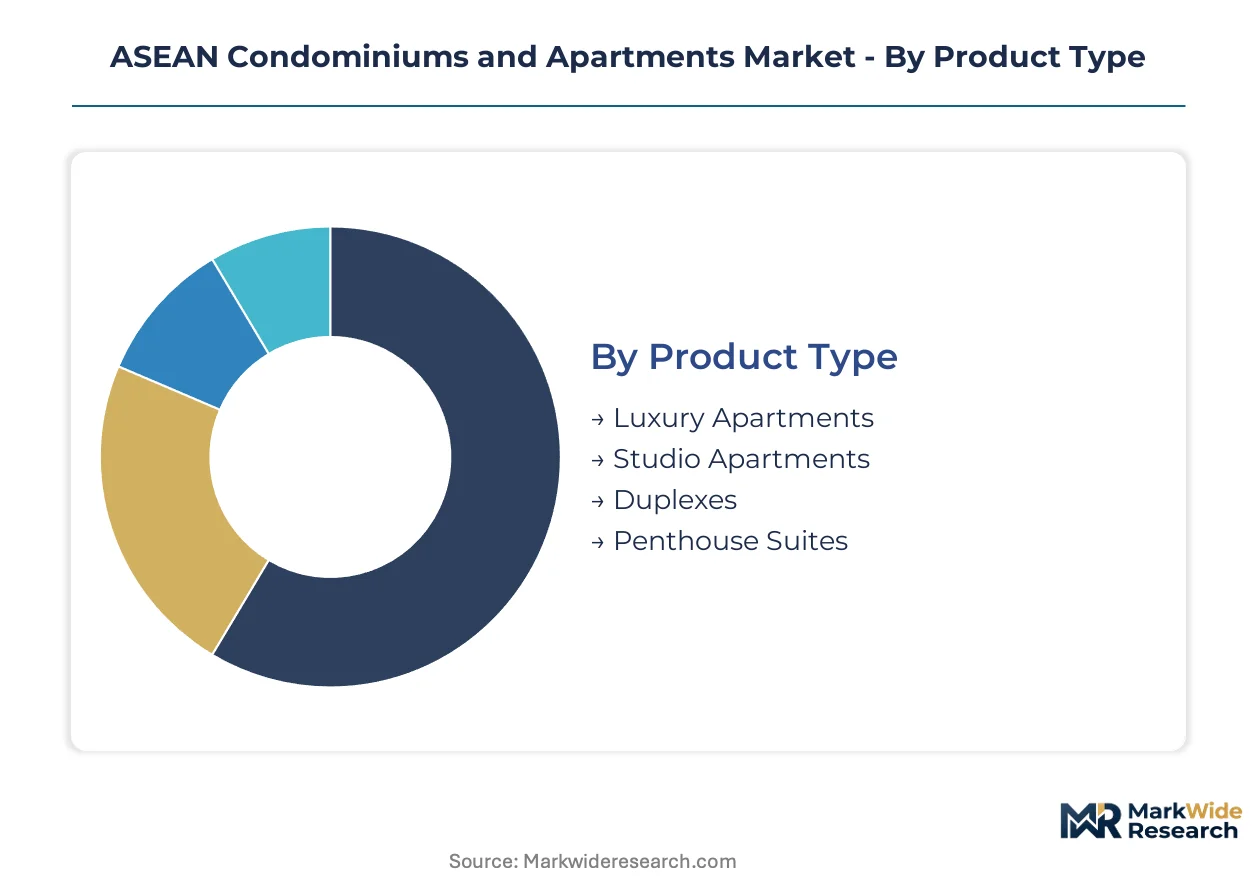
Developer unit mix decisions across Bangkok, Singapore, and Metro Manila hinge on precise alignment between product specifications and buyer liquidity profiles. Segmentation discipline determines absorption rates in supply-constrained submarkets and shapes capital deployment sequencing across project pipelines.
Product Type:
Domestic owner-occupier demand anchors studio and duplex supply in Bangkok's fringe transit zones, while foreign capital concentrates in luxury apartments and penthouse suites across Singapore and Vietnam's gateway cities. Export-led absorption in premium tiers outpaces local purchasing power in several metropolitan cores.
- Luxury Apartments:Reinforced concrete frame structures with centralized MEP systems and concierge-grade amenities. Demand clusters in Singapore's Core Central Region and Bangkok's Sukhumvit corridor, driven by cross-border wealth preservation mandates and quota-constrained foreign ownership.
- Studio Apartments:Compact single-chamber units optimized for rental yield generation and transit proximity. Young professional households in Ho Chi Minh City and Jakarta's CBD fringe drive the fastest inventory turnover, with pre-sale conversion cycles compressing through PropTech channels.
- Duplexes:Two-level vertical configurations with internal staircases and enhanced ceiling heights. Family-oriented demand in Metro Manila's Ortigas and Makati fringe sustains developer interest despite higher per-unit construction complexity.
- Penthouse Suites:Crown-floor configurations with private terrace access and customized fit-out specifications. Ultra-high-net-worth acquisition in Singapore's Marina Bay and Bangkok's riverside precincts commands disproportionate margin capture per square meter.
Studio apartments command the established base. The steepest expansion runs through penthouse suites.
End User:
Cost tier stratification separates mass-market absorption from institutional-grade yield plays, with financing availability and foreign ownership quotas segmenting accessible buyer pools across metropolitan markets.
- Young Professionals:First-time purchasers prioritizing transit proximity and digital-native sales channels. Bangkok's Metropolitan Rapid Transit expansion corridors and Ho Chi Minh City's Metro Line 1 station radii concentrate this segment's search behavior.
- Families:Multi-bedroom unit demand anchored in school district proximity and recreational amenity access. Metro Manila's mixed-use precincts and Singapore's suburban new towns sustain this segment's purchasing power.
- Retirees:Downsizing households seeking single-level accessibility and healthcare proximity. Thailand's secondary cities and Malaysia's Penang corridor attract cross-border retirement migration from North Asian source markets.
- Foreign Investors:Yield-focused capital subject to ownership quota constraints and repatriation regulations. Singapore's stamp duty regime and Thailand's Condominium Act B.E. 2522 amendments shape deployment timing across this segment.
Young professionals anchor volume throughput. Foreign investors deliver the highest margin capture per transaction.
Size:
Application-driven specifications differentiate investor-grade compact units from owner-occupier spacious configurations, with buildable floor area ratios constraining feasible unit counts per land parcel.
- Small Units:Sub-45 square meter configurations optimized for rental yield and entry-level affordability. Bangkok's developer pipeline and Ho Chi Minh City's District 2 concentrate this format's supply concentration.
- Medium Units:45-90 square meter two-bedroom configurations serving family transition housing. Singapore's Housing and Development Board upgraders and Metro Manila's emerging middle class sustain this segment's maturity.
- Large Units:90-150 square meter three-bedroom configurations with dedicated utility and storage zones. Premium district scarcity in Bangkok's central business district and Singapore's prime districts supports pricing power.
- Extra-Large Units:Super-150 square meter configurations with maid quarters and multi-generational flexibility. Ultra-premium developments in Singapore's Sentosa Cove and Bangkok's riverside luxury towers concentrate this segment's limited inventory.
Medium units represent the volume anchor. Small units are gaining share fastest through investor channel migration.
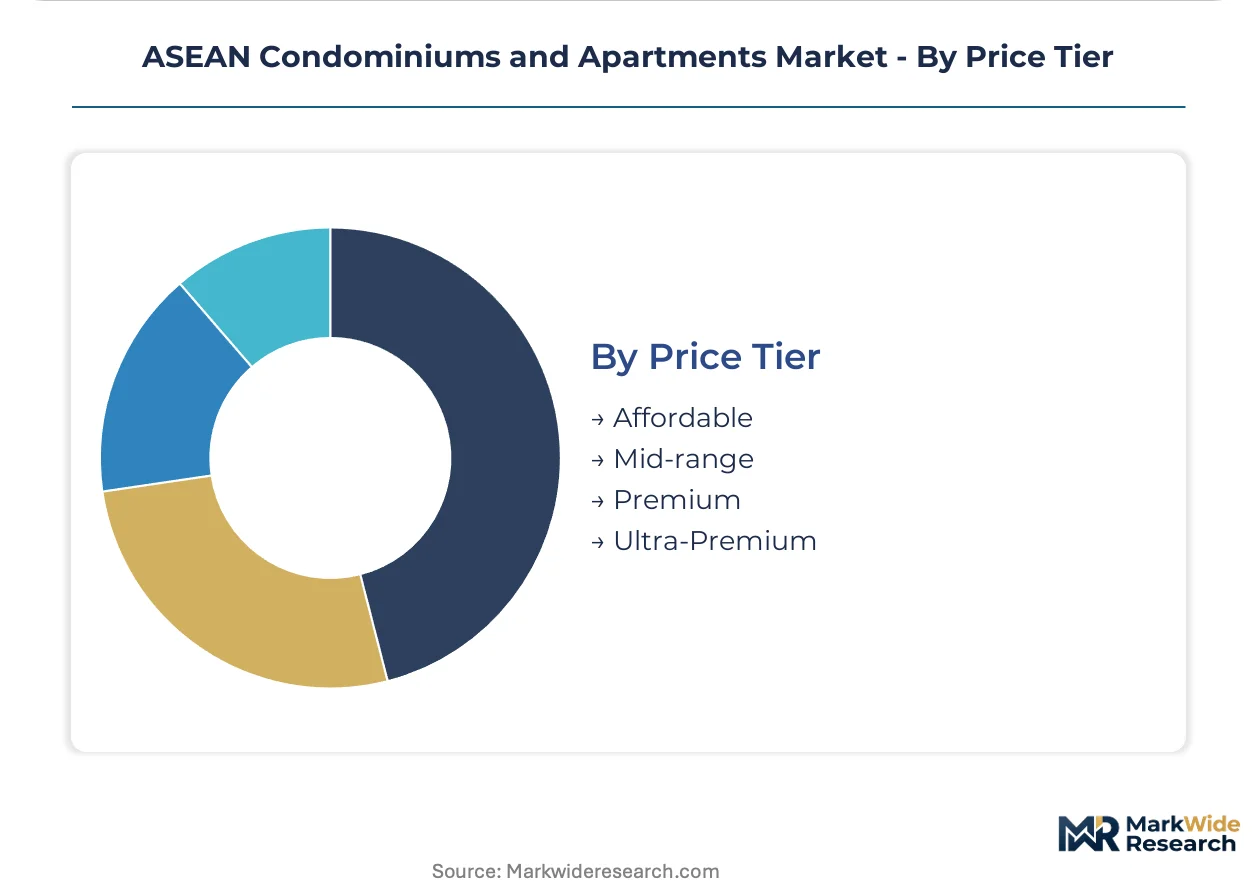
Price Tier:
Margin concentration stratifies across certification grades and location premiums, with green building mandates and transit proximity creating pricing differentiation within each tier.
- Affordable:Sub-median pricing aligned with government housing eligibility thresholds and mortgage subsidy programs. Philippines' Pag-IBIG Fund participation and Thailand's Government Housing Bank schemes shape this segment's financing accessibility.
- Mid-range:Median-to-75th percentile pricing capturing mass-market upgraders and investor yield requirements. Bangkok's fringe transit zones and Ho Chi Minh City's District 7 exhibit this tier's deepest inventory.
- Premium:75th-to-95th percentile pricing with branded developer provenance and enhanced amenity packages. Singapore's Outside Central Region and Metro Manila's Bonifacio Global City sustain this tier's absorption velocity.
- Ultra-Premium:Top-decile pricing with bespoke architectural involvement and concierge-grade service layering. Singapore's Core Central Region and Bangkok's ultra-luxury enclaves concentrate this tier's limited transaction flow.
Mid-range pricing commands the established base. Premium tier inventory is climbing the fastest through green certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development pipelines cluster around metropolitan transit corridors and foreign investment zones across Southeast Asia. Bangkok's Metropolitan Rapid Transit expansion and Singapore's urban densification mandates concentrate capital deployment. Regulatory frameworks in each member state shape foreign ownership access and green building compliance timelines.
Singapore
Ultra-high-net-worth capital preservation demand sustains premium absorption in the Core Central Region. The Building and Construction Authority's super-low energy building standards from 2030 accelerate deep retrofit specifications. Marina Bay and Orchard Road precincts concentrate luxury inventory with integrated commercial components.
Thailand
Young professional households drive studio and small-unit absorption along Bangkok's expanding transit network. Amendments to the Condominium Act B.E. 2522 relax foreign ownership quotas in designated investment zones. Sukhumvit corridor and riverside luxury towers anchor developer margin capture.
Philippines
Family-oriented demand in Metro Manila's mixed-use precincts sustains medium-unit supply volumes. The Housing and Land Use Regulatory Board's 40% foreign ownership ceiling constrains institutional capital in premium segments. Bonifacio Global City and Ortigas Center concentrate branded developer activity.
Vietnam
Inbound foreign direct investment flows outpace luxury inventory supply in secondary city corridors. National construction standards and provincial land use plans shape project approval timelines. Ho Chi Minh City's Metro Line 1 station radii and Da Nang's coastal zone concentrate pre-sale activity.
Malaysia
Cross-border retirement migration from North Asian source markets supports Penang corridor demand. The country's green building rating tool and strata title regulations influence developer specifications. Kuala Lumpur's transit-oriented development zones and Iskandar Malaysia anchor pipeline concentration.
ASEAN Condominiums and Apartments Market Competitive Environment
Concentration sits with integrated property conglomerates and specialized residential developers across tiered market positions. Singapore-based and Thai-listed players dominate premium-tier positioning through transit-linked land banks. Strategic archetypes include integrated mixed-use operators, luxury residential specialists, and mass-market volume builders. Competitive moves center on land bank accumulation near transit nodes and PropTech-enabled sales channel integration.
Among Singapore-based integrated developers, CapitaLand Limited and City Developments Limited exemplify the mixed-use conglomerate archetype with regional portfolio scale. Thai-listed specialists Sansiri Public Company Limited and Frasers Property Limited occupy positions within the luxury residential tier, anchoring Bangkok's transit-oriented and riverside segments. Philippine conglomerate Ayala Land Inc. represents the emerging market integrated operator model across Metro Manila's mixed-use precincts.
| Leading Market Players |
|---|
| CapitaLand Limited |
| Ayala Land Inc. |
| SM Development Corporation |
| Frasers Property Limited |
| UOL Group Limited |
| Sansiri Public Company Limited |
| Megaworld Corporation |
| SP Setia Bhd |
| City Developments Limited |
| Others |
Value Chain & Pricing Dynamics
Ninety-day elevator system lead times from Japanese and European OEMs compress developer procurement windows and amplify pricing power for premium-tier installations in Bangkok and Singapore. This inventory constraint cascades through reinforced concrete frame sourcing and MEP component bundling, forcing developers to sequence technology procurement ahead of structural completion to lock in cost certainty.
Pricing Analysis
Thailand's Condominium Act B.E. 2522 dictates the pricing tier structure through foreign ownership quota allocations and designated investment zone classifications. Pricing stratifies across ultra-premium, premium, mid-range, and affordable tiers, with green building certification premiums and transit proximity creating differentiation within each band. Cost compression in mid-range inventory is intensifying because imported billet price volatility from Chinese state-owned mills feeds through to reinforced steel framing costs. Young professional households exhibit highest price sensitivity in studio and small-unit segments, while ultra-high-net-worth buyers in Singapore's Core Central Region demonstrate lowest sensitivity to per-square-meter premiums.
Supply Chain Analysis
Port congestion at Singapore's PSA terminals and container availability constraints on intra-ASEAN trade lanes elevate inbound logistics costs for facade systems and elevator components. Manufacturing concentration rests on China for structural steel, Japan and Germany for vertical transportation systems, and Thailand for ready-mix concrete and precast elements. Raw material dependencies span imported billet, fire-rated aluminum composite panels, and cross-laminated timber hybrids from Malaysian and Indonesian pilot facilities. Single-source vulnerability concentrates around Japanese and European elevator OEMs with limited regional manufacturing footprint. Distribution runs through developer-direct procurement with technology-integrated asset managers capturing value from traditional general contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as young professional demand splinters across transit-proximate micro-locations and PropTech-enabled purchase channels. Developer scale advantages dilute when absorption velocity depends on hyperlocal amenity matching rather than brand equity alone.
For Market Incumbents: Fortify land bank positions within 500-meter radii of confirmed transit nodes in Bangkok's Metropolitan Rapid Transit expansion corridors and Ho Chi Minh City's Metro Line 1 station zones. Integrate backward into cross-laminated timber hybrid system supply through Malaysian and Indonesian joint ventures to offset embodied carbon compliance costs. Channel control through proprietary PropTech platforms reduces customer acquisition cost erosion from third-party brokerage migration. For New Entrants and Emerging Players: Anchor in Vietnam's secondary city corridor where Da Nang and Can Tho exhibit undersupplied luxury inventory relative to inbound foreign direct investment flows. Target family-oriented medium-unit demand in Metro Manila's Ortigas fringe where branded developer concentration remains below Bonifacio Global City and Makati levels. Deploy virtual reality unit customization and blockchain-based strata-title registries as differentiated sales channel infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates with underoptimized residential development subsidiaries lacking integrated PropTech capabilities or green building certification pipelines. Long-term viability favors operators with captive land banks in transit-oriented development zones and in-house building information modeling expertise. Monitor Singapore's Building and Construction Authority super-low energy building standard compliance timelines as inflection indicator for retrofit specification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Transit-Linked Land Bank Accumulation | Secures development rights within 500-meter radii of Bangkok MRT and Ho Chi Minh City Metro Line 1 stations ahead of zoning premium recognition. |
| PropTech Platform Integration | Compresses pre-sale conversion cycles through virtual reality staging and single-session mortgage origination for young professional buyers. |
| Cross-Laminated Timber Hybrid Adoption | Reduces embodied carbon in mid-rise structures to meet Singapore's 2030 super-low energy building mandates and Thailand's green certification premiums. |
| Backward Integration into MEP Systems | Mitigates single-source vulnerability from Japanese and European elevator OEMs through regional manufacturing partnerships or captive supply arrangements. |
| Green Mark Certification Acceleration | Creates first-mover advantage in Singapore's premium condominium segment as mandatory standards escalate compliance cost pass-through to buyers. |
Study Parameters
Desk research of national construction standards, strata title regulations, and foreign ownership quota frameworks preceded structured interviews with residential development executives, transit authority planning officers, green building certification consultants, and PropTech platform operators. Secondary validation drew from Thailand's Condominium Act amendments, Singapore's Building Control Act disclosures, Philippines HLURB filings, Vietnam provincial land use plans, and customs data on structural steel and elevator system imports. Bottom-up unit absorption modeling triangulated against top-down metropolitan GDP and demographic projections.
Variance decomposition across product type, end-user archetype, unit size, and price tier dimensions shaped analytical framework construction over the projection horizon. CAGRs derived from historical completion data, pre-sale velocity trends, and regulatory timeline assumptions. Forecast inputs incorporated foreign direct investment flow trajectories into Vietnamese secondary cities and retirement migration patterns toward Malaysia's Penang corridor.
Material uncertainties — reinforced steel price volatility from Chinese state-owned mill output, fire-rated facade system certification delays at Singapore's Building and Construction Authority laboratories, and foreign ownership quota amendment timing across ASEAN member states — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding transit construction completion schedules and green building mandate enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Condom Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market