
 Bahrain Senior Living Market | 2026-2036
Bahrain Senior Living Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Senior Living Market Outlook
Bahrain's National Health Regulatory Authority licensing framework is restructuring entry requirements for senior care operators, raising capital thresholds and mandating clinical staffing ratios that favor established providers. Alsalama Healthcare leverages its hospital-affiliated model to sustain full-time nursing coverage across its residential properties. Royal Bahrain Hospital anchors the high-acuity segment with on-site specialist access and rehabilitation infrastructure. Home Care Middle East competes through flexible outpatient contracts that extend nursing support into private residences.
Senior living encompasses licensed residential and non-residential services designed to support older adults with daily activities, medical monitoring, and social engagement through purpose-built facilities or home-based care delivery. Facilities typically integrate 24-hour emergency response systems, medication management protocols, and accessibility modifications to maintain resident safety and autonomy. Assisted living and memory care command premium positioning due to specialized staffing requirements and higher regulatory compliance costs, while home care service models are expanding fastest as families prefer aging-in-place alternatives. Private pay arrangements dominate revenue pools, though government assistance segments are gaining traction as Bahrain expands social welfare eligibility for elderly citizens.
The National Health Regulatory Authority and Ministry of Labour and Social Development jointly oversee facility licensing, staff credentialing, and resident welfare standards, creating compliance barriers that filter out undercapitalized entrants. Bahrain's building codes, administered by the Works Ministry, mandate fire suppression, elevator access, and infection control infrastructure that shape facility design and renovation economics. Stakeholders must monitor evolving reimbursement policies and workforce visa regulations that will determine whether supply expansion keeps pace with demographic transition.
Market Dynamics
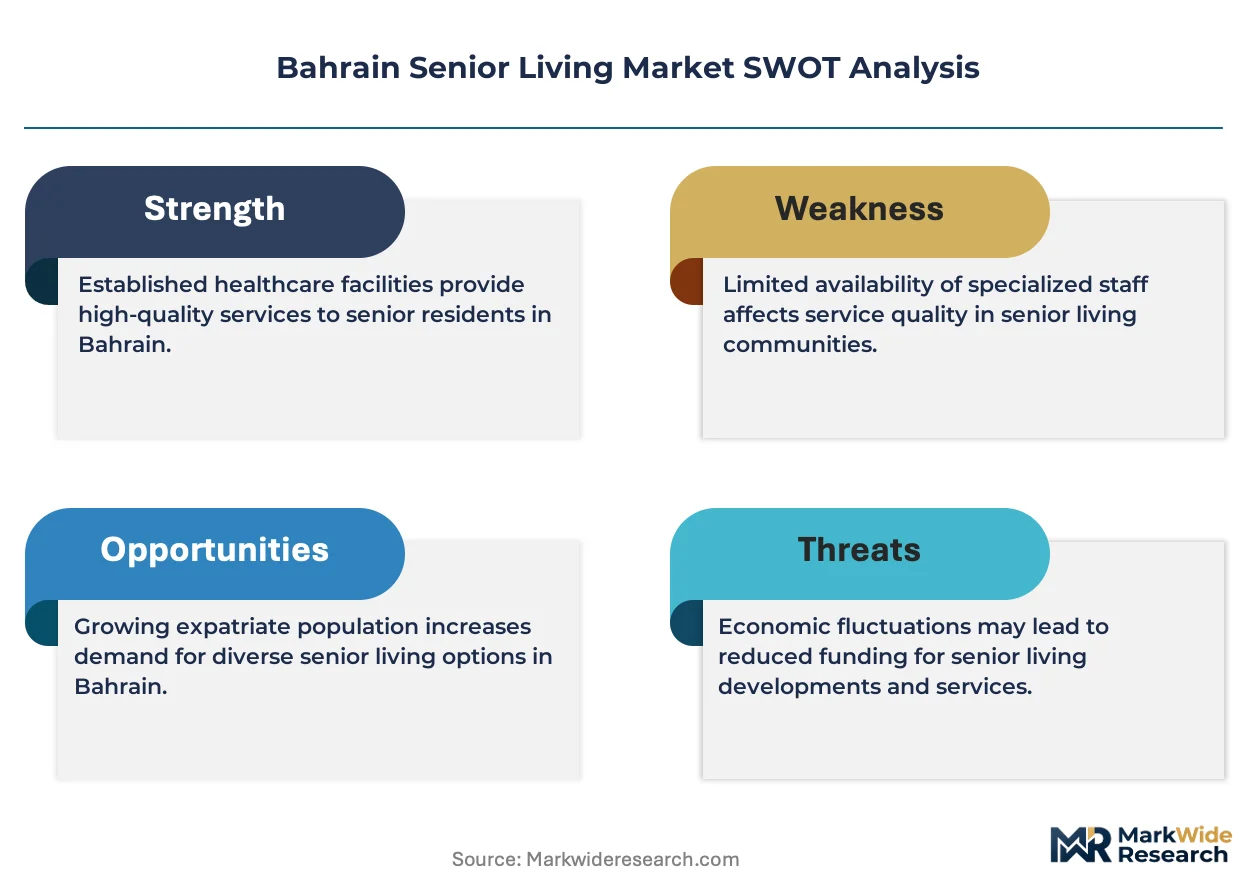
Bahrain's National Health Regulatory Authority licensing overhaul is consolidating the senior living landscape by elevating capital requirements and clinical staffing mandates that favor hospital-affiliated operators over independent entrants.
Growth Catalysts
- Expatriate Retirement Influx:GCC nationals and European retirees are selecting Bahrain for its licensed residential care infrastructure and relative cost positioning against Dubai and Riyadh alternatives.
- NHRA Quality Mandates:The National Health Regulatory Authority's tightened facility standards are filtering out substandard operators and redirecting demand toward compliant, purpose-built communities.
- Integrated Care Models:Hospital-affiliated senior living properties are capturing preference through guaranteed specialist access and seamless acute-to-residential care transitions.
Market Restraints
- Clinical Workforce Scarcity:Bahrain's Ministry of Labour and Social Development visa quotas for Filipino and Indian nursing staff constrain facility expansion timelines.
- Land Cost Concentration:Manama and Northern Governorate development plots command premiums that inflate project breakeven thresholds beyond independent operator capacity.
- Regulatory Compliance Burden:Dual oversight from NHRA and the Works Ministry creates overlapping fire safety, infection control, and building code requirements that extend permitting cycles.
Strategic Opportunities
- Home Care Extension:Outpatient nursing contracts for private residences represent underdeveloped white space as families seek aging-in-place alternatives to facility relocation.
- Memory Care Specialization:Dementia-specific units with secured environments and behavioral health staffing are undersupplied relative to diagnosed prevalence among Bahraini nationals over 75.
- Government Reimbursement Expansion:Social welfare eligibility broadening for elderly citizens is creating a funded segment distinct from historical private-pay dominance.
Industry Challenges
- Specialized Care Certification:NHRA dementia care and palliative care endorsements require documented training hours and supervisor credentials that strain existing staffing pools.
- Technology Integration Complexity:Emergency response systems and electronic health records must interface with Ministry of Health hospital networks, creating interoperability requirements that delay facility commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Senior Living Market |
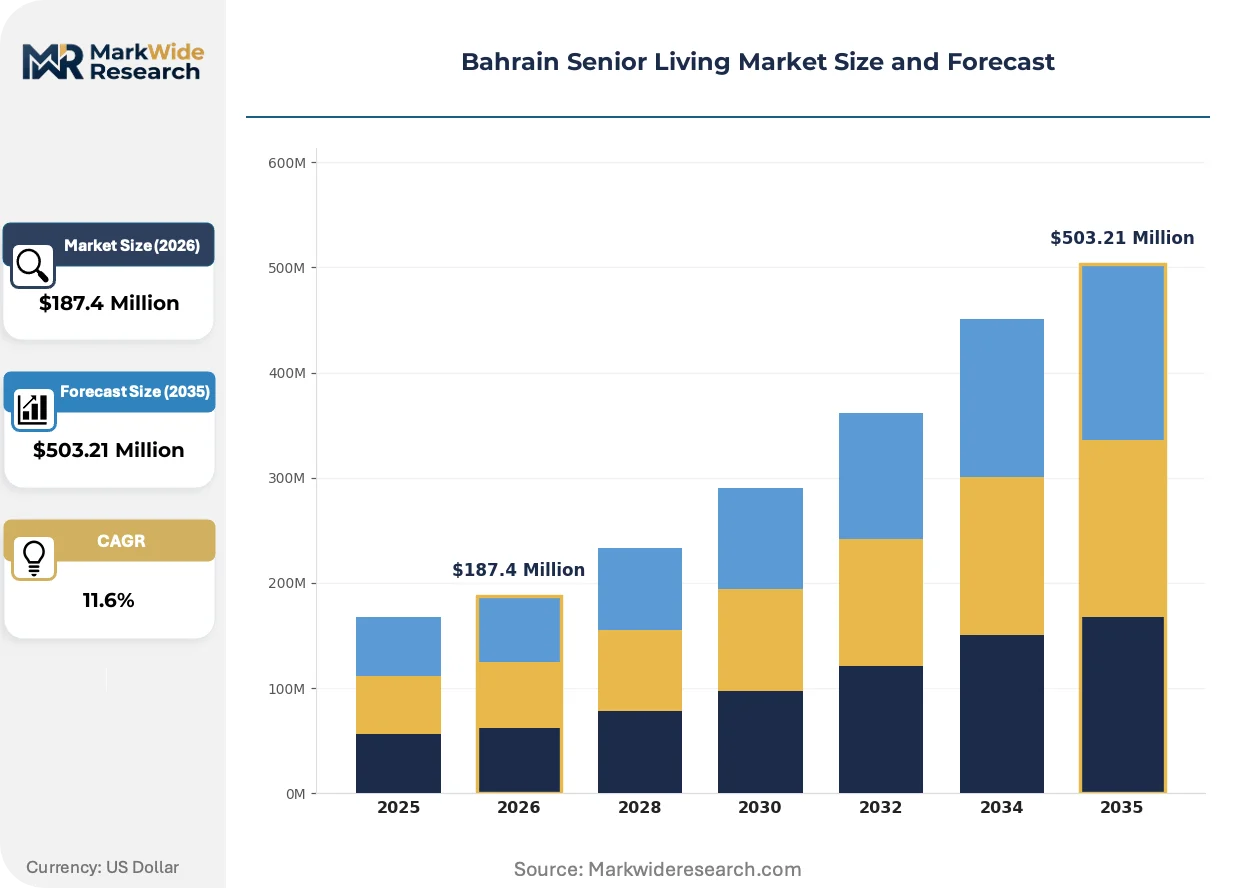
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Care Type: Assisted Living, Independent Living, Memory Care, Nursing Care Service Model: Residential, Outpatient, Day Care, Home Care Facility Size: Small Scale, Medium Scale, Large Scale, Luxury Payment Model: Private Pay, Long-Term Care Insurance, Government Assistance, Others |
| Companies Covered | Aecom, Home Health Care Centre, Alsalama Healthcare, KIMS Health at Home, Home Care Middle East, Royal Bahrain Hospital, Al-Hikma Society, Basha Medical Group, Venta Health Homecare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Senior Living Market Strategic Shifts
Technology-enabled care delivery and regulatory tightening are converging to reshape how senior living services are structured, staffed, and consumed across Bahrain's governorates.
Telehealth-integrated monitoring systems are expanding into residential care protocols by enabling remote specialist consultations and real-time vital sign transmission to affiliated hospitals. Assisted living operators in Manama are deploying these platforms to reduce emergency transfer frequency and maintain resident stability. The structural consequence is compressing the traditional boundary between residential care and acute medical oversight, allowing facilities to retain higher-acuity residents.
The National Health Regulatory Authority's 2024 facility licensing framework is mandating minimum nurse-to-resident ratios and continuous clinical supervision that previous guidelines treated as aspirational. This regulatory tightening is accelerating capital deployment toward hospital-affiliated properties with existing clinical infrastructure. Memory care and high-acuity assisted living segments face the steepest compliance cost increases, favoring operators with scale to absorb staffing overhead.
Family-driven procurement of modular home care packages is displacing traditional facility-first decision patterns among Bahraini nationals with adequate residential space. Adult children are contracting nursing visits, medication management, and physiotherapy sessions as discrete services rather than bundled residential admissions. This behavioral shift is most visible in the Northern Governorate, where multigenerational housing remains culturally normative and private villa stock supports in-place service delivery.
Bahrain Senior Living Market Segmentation
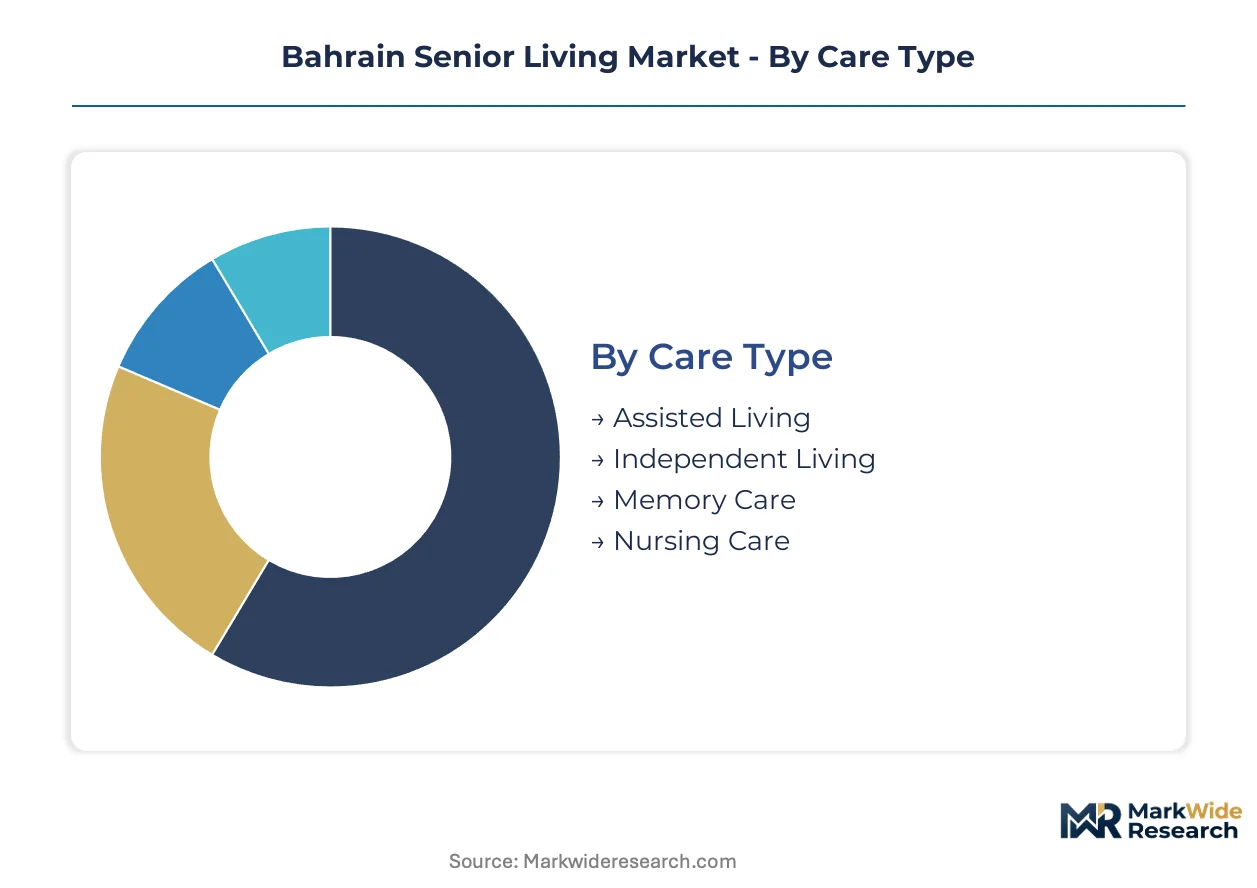
Bahrain's senior living market fragments across care intensity, service delivery mode, facility scale, and payment source. Each dimension shapes capital deployment, staffing requirements, and regulatory exposure for operators competing within the National Health Regulatory Authority framework.
Care Type:
Buyer selection hinges on clinical dependency level and family willingness to manage care coordination.
- Assisted Living:Supervised residential environments with medication management and daily activity support. Demand concentrates in Manama among expatriate retirees seeking licensed alternatives to Dubai's higher cost structure, with NHRA staffing mandates favoring hospital-affiliated operators.
- Memory Care:Secured units with behavioral health specialization for dementia residents. Northern Governorate development pipelines show the steepest capacity additions, driven by diagnosed prevalence among Bahraini nationals over 75 and limited existing supply.
- Independent Living:Age-restricted housing without clinical services, emphasizing community amenities and accessibility features.
- Nursing Care:Skilled nursing facilities with 24-hour registered nurse coverage and rehabilitation infrastructure.
Volume sits with Assisted Living; growth tilts toward Memory Care.
Service Model:
Distribution economics favor models with lower fixed asset intensity and faster regulatory commissioning.
- Home Care:Discrete nursing visits, physiotherapy, and medication management delivered in private residences. Northern Governorate families with multigenerational villas are driving the steepest expansion trajectory, displacing facility-first decisions among adult children.
- Residential:Purpose-built facilities with integrated emergency systems and continuous staffing. Manama's land cost premiums constrain new entrants, consolidating share among established hospital-affiliated properties.
- Outpatient:Clinic-based services without overnight accommodation, including specialist consultations and rehabilitation.
- Day Care:Structured daytime programming with transportation, meals, and social activities for community-dwelling seniors.
Residential commands current revenue concentration; Home Care gains share fastest.
Facility Size:
Capital availability and land access determine feasible scale for new market entrants.
- Large Scale:Communities exceeding 100 units with diversified care levels and on-site amenities. Manama development plots support this format for hospital-affiliated operators absorbing NHRA compliance overhead across greater resident volume.
- Luxury:Premium-positioned properties with concierge services, larger unit footprints, and specialist access guarantees. Expatriate retirees from GCC and European markets concentrate demand here, prioritizing licensed infrastructure over cost minimization.
- Medium Scale:40-100 unit properties balancing operational efficiency with personalized service delivery.
- Small Scale:Under 40 units, often villa conversions serving localized catchments with lower capital barriers.
Large Scale absorbs institutional investment; Luxury captures margin expansion.
Payment Model:
Reimbursement source shapes resident acquisition strategy and pricing power.
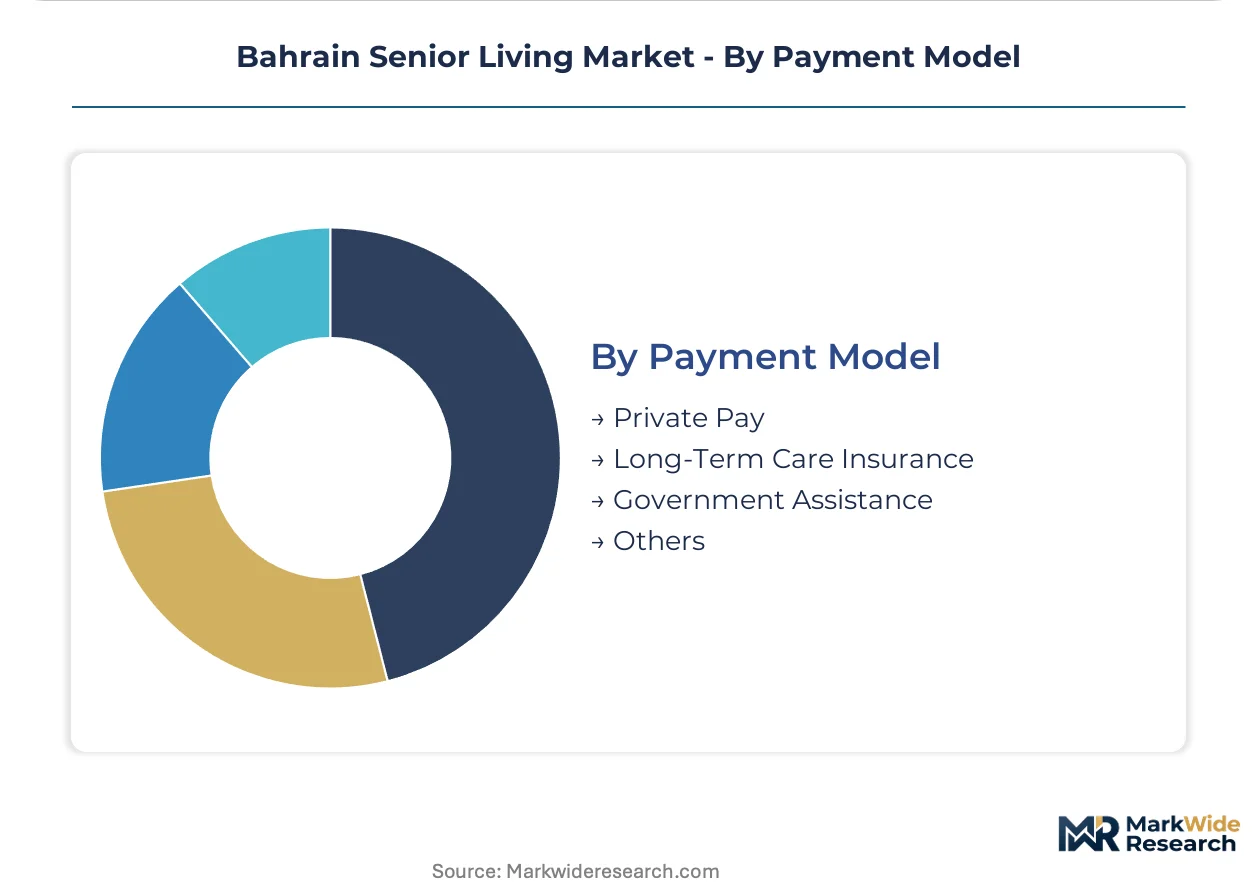
- Private Pay:Direct resident or family payment without third-party reimbursement. This segment dominates current revenue pools across all facility types, particularly among expatriate retirees and affluent Bahraini families.
- Government Assistance:Social welfare subsidies for eligible elderly citizens. Ministry of Labour and Social Development eligibility expansion is creating a funded segment distinct from historical private-pay dominance, with operators adapting intake processes for verification requirements.
- Long-Term Care Insurance:Policy-based coverage for residential and home care services, still nascent in Bahrain but emerging among corporate benefit packages.
- Others:Employer-sponsored arrangements, charitable support, and hybrid financing structures.
Private Pay anchors current operations; Government Assistance drives volume accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manama anchors Bahrain's senior living infrastructure through its concentration of hospital-affiliated residential properties and NHRA-licensed facilities serving expatriate retirees from GCC and European markets.
Manama Capital Governorate
Expatriate retirees from Saudi Arabia and Kuwait drive assisted living demand in Manama's licensed residential communities. The National Health Regulatory Authority enforces clinical staffing ratios that favor hospital-affiliated operators with existing nursing infrastructure. Seef and Juffair districts host the majority of large-scale integrated retirement developments under active construction.
Northern Governorate
Bahraini nationals over 75 with dementia diagnoses concentrate demand for memory care units in this governorate. Ministry of Labour and Social Development welfare eligibility expansion is creating funded demand segments beyond traditional private-pay arrangements. Muharraq and Riffa clusters see active villa conversion projects targeting multigenerational families seeking aging-in-place alternatives.
Southern Governorate
Land cost advantages attract medium-scale independent living developments targeting middle-income Bahraini retirees. The Works Ministry building code compliance costs remain lower here than in northern districts, enabling faster project commissioning. Askar and Awali sub-regions host emerging retirement community proposals linked to healthcare zone expansions.
Central Governorate
Home care service providers extend nursing visits and physiotherapy contracts across dispersed villa communities in this governorate. Families with adequate residential space prefer modular outpatient packages over facility relocation. Isa Town and Hamad Town serve as logistics hubs for mobile care teams covering southern catchments.
Western Coastal Corridor
Luxury-positioned retirement properties target European retirees seeking licensed infrastructure at cost positioning below Dubai alternatives. Durrat Al Bahrain and Amwaj Islands developments integrate concierge services and specialist access guarantees. NHRA licensing requirements for these properties mandate continuous clinical supervision that filters out undercapitalized entrants.
Bahrain Senior Living Market Competitive Environment
Premium-margin players sit above commodity-margin players across clinical staffing density and NHRA compliance infrastructure. Hospital-affiliated operators capture preference through guaranteed specialist access and seamless acute-to-residential transitions, while independent entrants struggle with overlapping Works Ministry and NHRA permitting cycles. Three archetypes dominate: integrated hospital-affiliated properties, standalone assisted living specialists, and home care extension platforms. Competitive moves concentrate on capacity expansion in Northern Governorate memory care and strategic partnerships for technology-enabled monitoring systems.
Within the hospital-affiliated tier, Royal Bahrain Hospital and Alsalama Healthcare anchor premium positioning through full-time nursing coverage and rehabilitation infrastructure. Home Care Middle East occupies the outpatient extension archetype, competing through flexible contracts that deliver nursing support into private residences. These three entities exemplify how regulatory compliance scale and clinical staffing density separate sustainable operators from filtered entrants under NHRA's tightened framework.
| Leading Market Players |
|---|
| Aecom |
| Home Health Care Centre |
| Alsalama Healthcare |
| KIMS Health at Home |
| Home Care Middle East |
| Royal Bahrain Hospital |
| Al-Hikma Society |
| Basha Medical Group |
| Venta Health Homecare |
| Others |
Value Chain & Pricing Dynamics
NHRA staffing ratio mandates are forcing operators to absorb higher clinical labor costs, compressing margins and pushing pricing stratification toward hospital-affiliated properties with captive nursing pools.
Pricing Analysis
Value-based pricing anchored to clinical outcome guarantees dominates the hospital-affiliated tier, where Royal Bahrain Hospital and Alsalama Healthcare bundle specialist access into residential fees. Price differentiation separates licensed memory care units with behavioral health certification from standard assisted living, with premium positioning justified by NHRA dementia care endorsements. Pricing pressure intensifies in the home care segment as Filipino and Indian nursing visa quotas constrain supply expansion. Expatriate retirees from GCC markets show lowest price sensitivity, prioritizing licensed infrastructure over cost minimization.
Supply Chain Analysis
Regional distribution centers for medical equipment and pharmaceuticals cluster in Manama's Seef district, feeding supplies to Northern Governorate facilities through hub-and-spoke logistics. Equipment sourcing draws from Germany, the United States, and the United Arab Emirates for diagnostic and monitoring devices. Clinical workforce recruitment rests on Philippines and India as primary nursing labor markets. Single-source vulnerability concentrates in specialized dementia care pharmaceuticals and mobility equipment. Distribution runs through hospital-affiliated procurement networks that leverage existing supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed bed capacity trails demand acceleration, with NHRA commissioning timelines creating a structural bottleneck that sustains pricing power for compliant operators.
For Market Incumbents: Extend memory care footprints in Northern Governorate corridors where diagnosed dementia prevalence exceeds existing unit supply. Deepen backward integration into nursing workforce pipelines by sponsoring visa quotas through Ministry of Labour and Social Development channels. Counter home care displacement by embedding outpatient contracts within residential admission packages. For New Entrants and Emerging Players: Telehealth-integrated monitoring platforms offer the lowest regulatory barrier for technology-enabled market entry, bypassing NHRA facility licensing requirements. Target Central Governorate home care contracts where multigenerational villa stock supports aging-in-place service delivery. Lead with modular nursing visit packages priced below residential admission thresholds. For Investors and Strategic Acquirers: The window for entry favors hospital-affiliated operators with existing clinical infrastructure and NHRA compliance track records. Long-term viability hinges on scale to absorb staffing overhead across diversified care levels. Monitor Ministry of Labour and Social Development visa quota expansions as the inflection signal for supply-constraint easing.| Strategic Initiative | Industry Significance |
|---|---|
| NHRA Licensing Compliance Investment | Hospital-affiliated operators leverage existing clinical infrastructure to accelerate facility commissioning timelines. |
| Memory Care Unit Expansion | Northern Governorate developments address diagnosed dementia prevalence among Bahraini nationals over 75. |
| Home Care Platform Integration | Telehealth-enabled monitoring reduces emergency transfer frequency and extends residential resident stability. |
| Nursing Workforce Pipeline Sponsorship | Ministry of Labour visa quota allocation determines facility expansion capacity across all operator tiers. |
| Government Reimbursement Intake Adaptation | Social welfare eligibility expansion creates funded demand segments beyond historical private-pay dominance. |
Study Parameters
Document review covered NHRA facility licensing frameworks, Ministry of Labour and Social Development welfare eligibility criteria, and Works Ministry building code requirements, complemented by interviews with senior living operators, hospital system administrators, and clinical staffing agencies. Primary fieldwork engaged facility directors, nursing workforce recruiters, and expatriate retiree relocation consultants. Secondary validation drew from healthcare regulatory filings, construction permitting databases, and demographic transition projections. Bottom-up unit capacity modeling triangulated against top-down expenditure flow analysis.
Market size and growth trajectory outputs reflect segmentation across care type, service model, facility scale, and payment source dimensions. The analytical framework incorporated assisted living, memory care, independent living, and nursing care intensity tiers alongside home care, residential, outpatient, and day care delivery modes. CAGRs were derived from demand elasticity modeling against supply constraint scenarios. Forecast inputs included NHRA staffing mandate implementation timelines and Ministry of Labour visa quota allocation patterns.
The model holds under stable regulatory enforcement and demographic transition assumptions; deviation in visa policy liberalization or accelerated welfare eligibility expansion would shift capacity-constraint severity. Forecasts reflect documented base conditions without contingency weighting. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
United Arab Emirates Residential Real Estate Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
Vietnam Residential Real Estate Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Spain Manufactured Homes Market