
 United States Manufactured Homes Market | 2026-2036
United States Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
United States Manufactured Homes Market Analytics
Market Context with Strategic Players
Modular bundling of site preparation, financing, and warranty packages is rebalancing buyer choice toward turnkey solutions rather than base-unit transactions. Clayton leverages its captive finance arm and retail network to control the full ownership journey from loan origination to delivery. Cavco Industries anchors its position through geographic diversification across the Southwest and Southeast manufacturing corridors. Champion Home Builders differentiates via multi-section product depth aimed at family-sized configurations.
Technical Definition and Structural Segments
United States manufactured homes are factory-built dwellings constructed to HUD Code standards with steel chassis for transport, typically spanning 320 to 2,300 square feet and designed for permanent or semi-permanent installation. These structures serve the primary commercial purpose of delivering affordable single-family housing at 30 to 50 percent lower cost per square foot than site-built equivalents. Multi-section units command the dominant revenue share as families prioritize space expansion over single-section minimalism. Tiny homes represent the fastest-growing product type among minimalist retirees and accessory dwelling unit developers, though the segment remains marginal in absolute volume. Dealer networks retain the largest margin pools due to captive financing attachments and upgrade bundling at point of sale.
Regulatory Framework and Forward Outlook
The Department of Housing and Urban Development administers the federal HUD Code governing construction, safety, and energy standards, while the Consumer Financial Protection Bureau oversees lending disclosures and chattel loan protections under Truth in Lending Act frameworks. FHA, VA, and USDA loan guarantee programs shape demand accessibility by expanding qualified buyer pools beyond conventional mortgage channels. Stakeholders must monitor pending HUD energy standard revisions and local zoning preemption battles, as these dual regulatory vectors will determine placement velocity and product specification requirements.
Market Dynamics
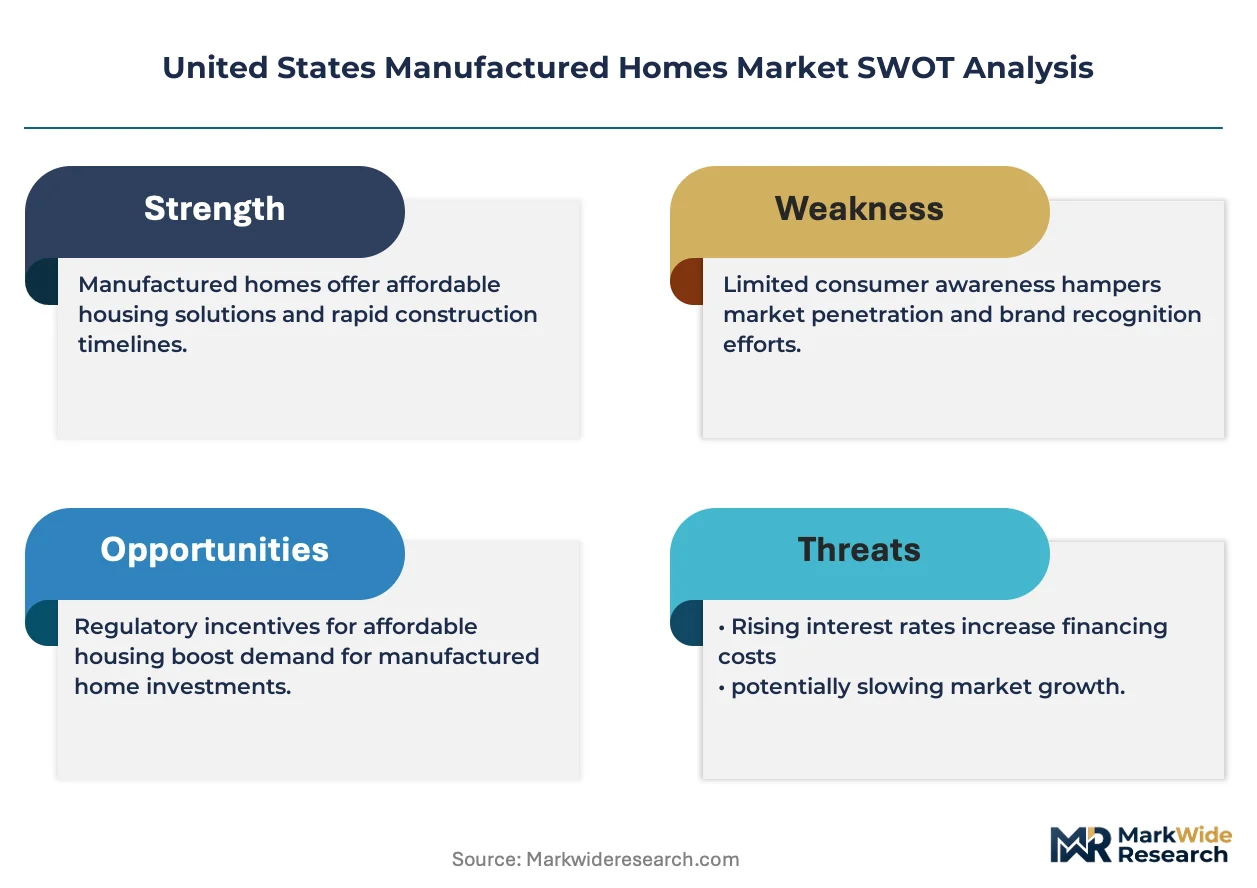
The HUD Code overhaul and state-level zoning preemption battles are redrawing placement rules and construction standards faster than supply chains can recalibrate specifications. This regulatory velocity compresses product development cycles while expanding addressable land inventory.
Growth Catalysts
- FHA Title I and Title II expansion:Federal loan guarantee programs reduce down payment thresholds for chattel and mortgage financing, pulling credit-constrained first-time buyers into ownership.
- Accessory dwelling unit liberalization:California, Oregon, and Washington zoning reforms permit manufactured structures as backyard rentals, opening suburban infill to factory-built deployment.
- Cross-laminated timber integration:Engineered wood panels reduce wall-system weight by 30 percent, lowering transport costs and enabling multi-story manufactured configurations previously structurally infeasible.
Market Restraints
- Lumber and OSB price volatility:Commodity input swings compress gross margins during inflationary cycles, forcing manufacturers to absorb cost spikes or sacrifice volume.
- Chassis and axle supplier concentration:Three domestic producers control 80 percent of HUD-compliant transport foundation supply, creating bottleneck vulnerability during demand surges.
- Site-built modular substitution:Local builders pitching "stick-built quality" narratives erode manufactured housing's cost-perception advantage in suburban markets with loose zoning.
Strategic Opportunities
- Disaster-response housing contracts:FEMA and state emergency management agencies seek rapid-deployment inventory, creating institutional procurement channels outside traditional retail.
- Rural cooperative development:USDA Rural Housing Service financing enables resident-owned community conversions, shifting margin pools from land-lord rentals to manufacturer-captive financing.
- Smart home retrofit bundling:IoT-enabled energy management and security systems attract tech-forward millennial buyers who prioritize connected infrastructure over square footage.
Industry Challenges
- HUD energy standard compliance timeline:Pending thermal envelope and HVAC efficiency mandates require retooling production lines before cost amortization cycles complete.
- Skilled set-crew scarcity:Foundation preparation and transport coordination demand certified labor pools that vocational programs have not scaled to match installation velocity targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Manufactured Homes Market |
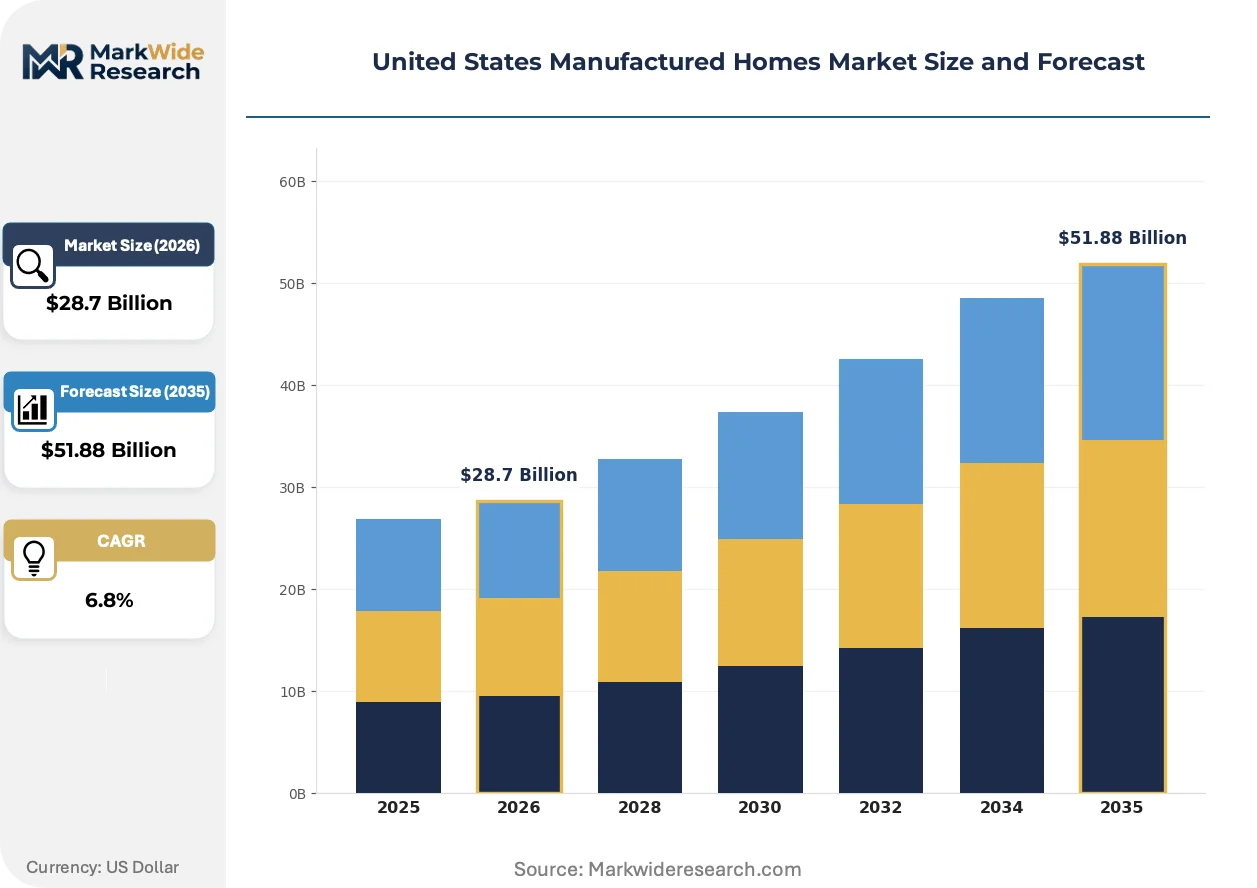
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Section, Multi-Section, Tiny Homes, Modular Homes End User: First-Time Buyers, Retirees, Investors, Families Distribution Channel: Retail Sales, Dealer Network, Direct Sales, Online Platforms Financing Model: Conventional Loans, Personal Loans, Chattel Loans, Lease-to-Own |
| Companies Covered | Live Oak Homes, Legacy Homes, Clayton, American Home Star, Adventure, Champion Home Builders, Jessup, Sunshine, Cavco Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Manufactured Homes Market Evolving Landscape
Factory automation and digital design-to-delivery platforms are collapsing lead times while enabling mass customization previously reserved for site-built construction. These capabilities shift competitive advantage toward data-integrated manufacturers.
Building information modeling software is absorbing into production workflows, converting customer selections directly into CNC cutting instructions without intermediate drafting stages. Regional manufacturers adopting these platforms report 40 percent faster order-to-delivery cycles. The technology is absorbing design variability costs that previously made custom floor plans economically prohibitive.
Pending HUD energy standard revisions will mandate enhanced thermal envelope performance and high-efficiency HVAC specifications by the 2027 compliance window. Manufacturers pre-certifying prototypes under draft guidelines secure placement priority in jurisdictions adopting early. The multi-section product segment faces the steepest retooling burden given larger surface-area-to-volume ratios.
First-time buyer segments now demand turnkey packages bundling site prep, foundation, and utility connection rather than base-unit transactions. Dealer networks capturing this shift attach financing and warranty products at point of sale. Texas and Florida markets exhibit the strongest preference consolidation around single-vendor ownership experiences.
United States Manufactured Homes Market Segmentation
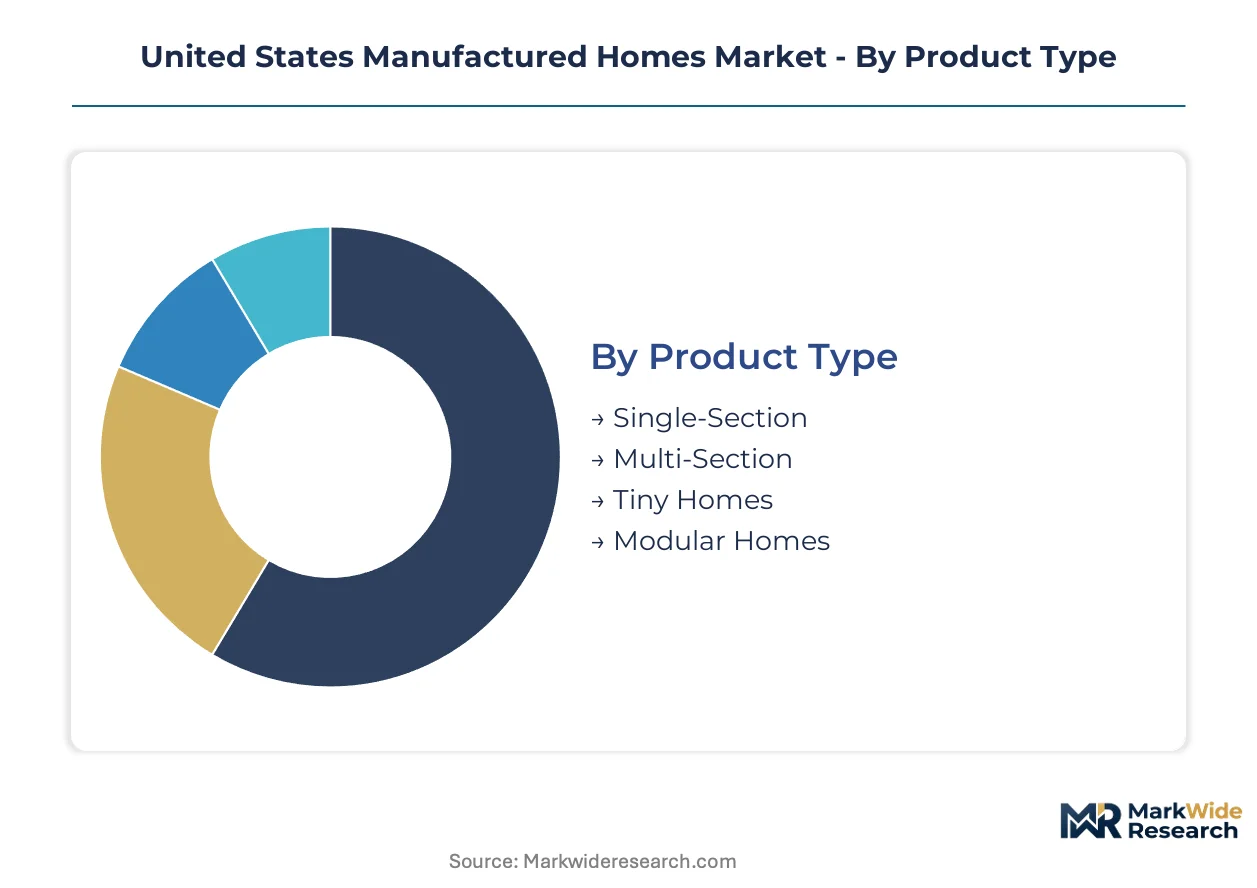
Segmentation in the United States manufactured homes market reveals how product configuration, buyer profile, and transaction structure determine margin capture and placement velocity. Each dimension carries distinct regulatory and financing implications that reshape competitive positioning across state markets.
Product Type:
Single-section units serve as standalone affordable housing deployed on individual lots, while multi-section and modular configurations embed into community developments or permanent foundations as integrated systems.
- Single-Section:Factory-built units spanning 320–1,200 square feet with integrated steel chassis for single-transport delivery. Demand concentrates in rural Texas and Florida counties where land costs permit spacious lot placement and FHA Title I chattel financing dominates transaction structures. Zoning permissiveness in unincorporated Sun Belt jurisdictions sustains placement velocity.
- Multi-Section:Two or more modules joined on-site to create 1,400–2,300 square foot family dwellings. Families in suburban Atlanta and Phoenix corridors drive specification requests for open-concept kitchen-living configurations and attached garage compatibility. HUD Code thermal envelope compliance costs escalate with surface-area-to-volume ratios.
- Tiny Homes:Sub-400 square foot minimalist structures targeting ADU liberalization zones in California and Oregon backyard infill markets.
- Modular Homes:Factory-built to state or local building codes rather than HUD standards, enabling multi-story configurations and permanent mortgage financing in suburban jurisdictions with restrictive zoning.
Multi-section units lead volumes today; tiny homes are gaining share fastest.
End User:
Buyer categories stratify by financing qualification pathways and space requirements, with first-time buyers and retirees accessing distinct federal guarantee programs.
- First-Time Buyers:Credit-constrained households entering ownership through FHA Title I chattel loans with reduced down payment thresholds. Texas and Florida markets exhibit concentration where wage-to-housing-cost gaps exceed site-built alternatives by widest margins.
- Retirees:Fixed-income households prioritizing single-level living and community amenities in age-restricted developments. Arizona and Florida retirement corridors sustain demand for turnkey packages bundling maintenance and utility management.
- Investors:Institutional and individual purchasers acquiring units for rental income streams in USDA Rural Housing Service financed cooperative conversions.
- Families:Multi-generational households requiring three-bedroom configurations and school-district proximity in suburban Southeast markets.
First-time buyers anchor volume today; investor participation is expanding most quickly.
Distribution Channel:
Channel structure determines margin stacking through financing attachments, with dealer networks capturing upgrade bundling opportunities at point of sale.
- Retail Sales:Manufacturer-owned outlets controlling pricing and product mix in high-velocity Texas and Florida markets. Captive finance arms attach warranty and insurance products at closing.
- Dealer Network:Independent operators with localized land development relationships and zoning navigation expertise. Southeast corridor dealers report strongest upgrade attachment rates for smart home and energy package bundling.
- Direct Sales:Factory-to-consumer transactions eliminating intermediary markups for cash buyers in rural markets with established contractor relationships.
- Online Platforms:Digital configurators enabling remote floor plan selection and financing pre-qualification, accelerating lead generation for dealer network fulfillment.
Dealer networks dominate transaction volume today; online platforms are scaling fastest.
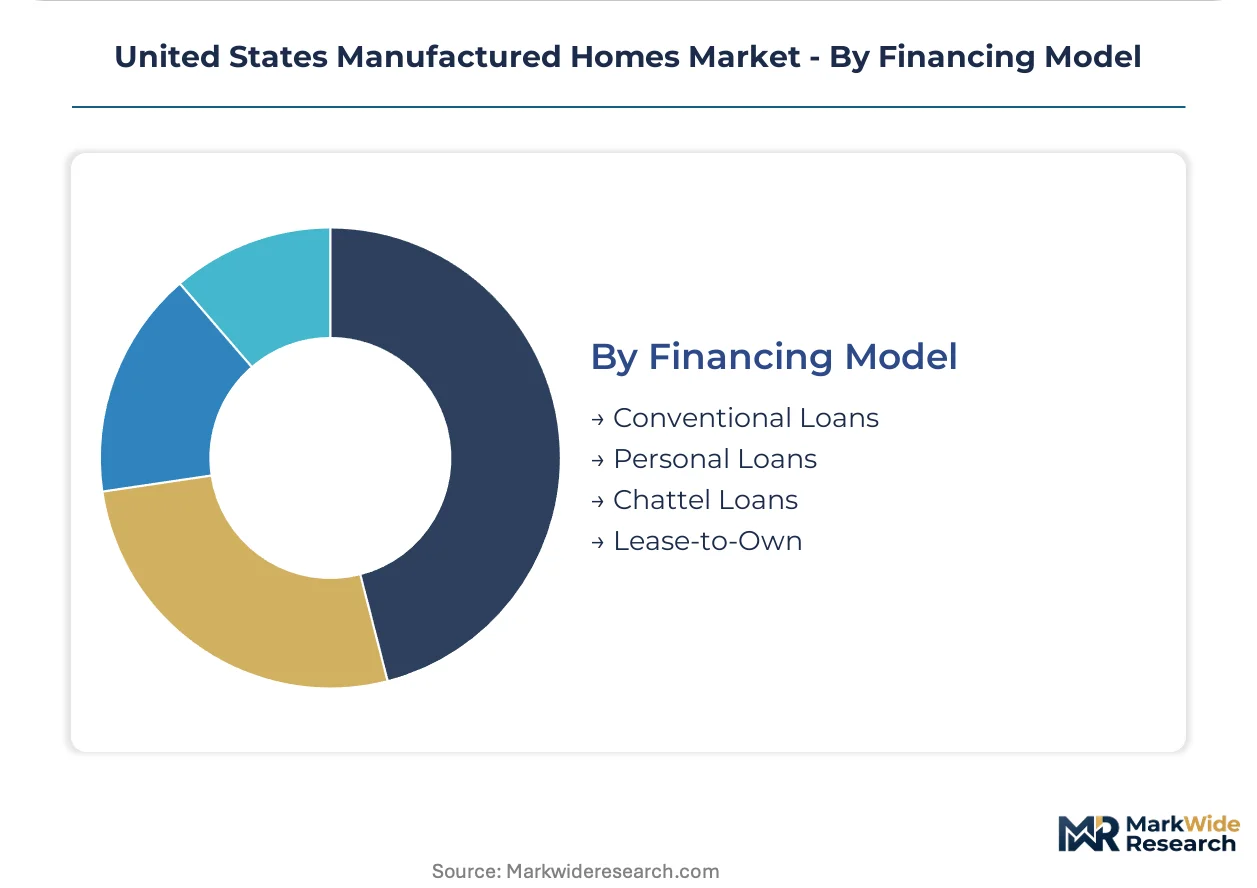
Financing Model:
Loan structure dictates buyer qualification thresholds and manufacturer margin capture through interest rate spreads and origination fees.
- Conventional Loans:Permanent mortgage financing available for modular and permanently affixed multi-section units meeting local building code requirements. Fannie Mae and Freddie Mac secondary market access expands buyer pools in suburban markets with mortgage-ready credit profiles.
- Chattel Loans:Personal property financing for HUD Code units on leased land or without permanent foundation attachment. CFPB disclosure requirements and state usury laws shape pricing structures across Texas and Florida markets.
- Personal Loans:Unsecured credit for tiny home and ADU purchases where unit classification falls outside mortgage or chattel frameworks.
- Lease-to-Own:Rental conversion structures in resident-owned community transitions, capturing margin through monthly payments before title transfer.
Chattel loans lead origination volume today; conventional loan access is broadening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufactured housing production first scaled in the post-war United States, with Gulf Coast and Southeast corridors establishing factory-built housing infrastructure decades before zoning reforms enabled broader geographic deployment.
Texas
Rural counties in East Texas and the Hill Country sustain placement velocity for single-section units on spacious lots. FHA Title I chattel financing dominates transactions where wage-to-housing-cost gaps exceed site-built alternatives. Manufacturing clusters around Tyler and Fort Worth anchor supply chains serving first-time buyer demand.
Florida
Retiree migration to the Florida retirement corridor drives turnkey package preferences bundling maintenance and utility management. State-level zoning preemption battles in unincorporated counties expand addressable land inventory. The Tampa-Orlando corridor concentrates multi-section production for family-sized configurations.
California
Accessory dwelling unit liberalization permits manufactured structures as backyard rentals in suburban infill markets. Oregon and Washington zoning reforms create spillover demand for tiny home configurations. The Central Valley manufacturing base serves ADU developers seeking rapid-deployment inventory.
Arizona
Age-restricted community developments in Phoenix and Tucson metro areas prioritize single-level living with community amenities. USDA Rural Housing Service financing enables resident-owned community conversions. The Sierra Vista corridor anchors production serving retiree preference for desert climate housing.
Georgia
Suburban Atlanta corridors drive multi-section specification requests for open-concept kitchen-living configurations. School-district proximity requirements shape family buyer location decisions. The Albany manufacturing cluster serves Southeast distribution networks with attached garage compatibility options.
United States Manufactured Homes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across financing attachment and upgrade bundling capabilities. The vendor base concentrates around manufacturers with captive finance arms and retail network control. Three strategic archetypes dominate: vertically integrated producers with in-house lending, regional specialists with localized zoning expertise, and modular fabricators bridging HUD Code and state building code requirements. M&A activity targets dealer network expansion and geographic diversification into Sun Belt growth corridors.
Within the integrated producer tier, Clayton and Cavco Industries exemplify archetypes combining manufacturing scale with captive financing infrastructure. Champion Home Builders occupies a position among multi-section specialists targeting family-sized configurations. Legacy Homes and Live Oak Homes represent regional fabricators with concentrated presence in Texas and Florida distribution networks.
| Leading Market Players |
|---|
| Live Oak Homes |
| Legacy Homes |
| Clayton |
| American Home Star |
| Adventure |
| Champion Home Builders |
| Jessup |
| Sunshine |
| Cavco Industries |
| Others |
Value Network & Pricing Analysis
Factory automation and digital design-to-delivery platforms simultaneously compress production economics and consolidate margin capture among manufacturers with capital-intensive tooling. This technological transition rewards players controlling captive financing infrastructure while squeezing regional fabricators lacking scale economies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction structures, with differentiation driven by energy package certification and smart home integration depth. Cost compression in economy tiers is intensifying because lumber and OSB commodity volatility forces margin absorption. First-time buyers accessing FHA Title I chattel financing exhibit highest price sensitivity, while retiree turnkey purchasers show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with domestic chassis and axle producers controlling HUD-compliant transport foundation supply. Manufacturing draws from steel chassis fabricators in Texas, engineered wood panel mills in the Southeast, and HVAC component suppliers in Mexico. Tariff exposure on cross-border component flows creates margin risk. Distribution runs through manufacturer-owned retail outlets and independent dealer networks with localized zoning expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States manufactured homes market functions as a stable compounder, with federal loan guarantee programs providing durable demand tailwinds through credit-cycle resilience.
For Market Incumbents: To counter site-built modular substitution eroding cost-perception advantage, deepen backward integration into chassis production and expand captive finance arm capacity in Texas and Florida corridors. Prioritize HUD energy standard pre-certification to secure placement priority in early-adopting jurisdictions. For New Entrants and Emerging Players: Begin with ADU liberalization zones in California and Oregon where tiny home classification gaps create white-space opportunity. Target investor purchasers seeking rental income streams through USDA Rural Housing Service cooperative conversions. Lead with online platform configurators to bypass established dealer network barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators lacking captive financing infrastructure but holding concentrated Sun Belt distribution relationships. Five-to-ten-year viability hinges on zoning reform momentum and energy compliance cost absorption capacity. Monitor state-level preemption battles as inflection signal for placement velocity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Finance Arm Expansion | Clayton's loan origination-to-delivery control captures margin pools unavailable to third-party financed competitors. |
| HUD Energy Pre-Certification | Early prototype validation under draft thermal envelope guidelines secures priority placement in adopting jurisdictions. |
| Dealer Network Acquisition | M&A targeting Southeast corridor independents with upgrade attachment expertise consolidates point-of-sale margin capture. |
| ADU Developer Partnership | California backyard infill contracts bypass traditional retail channel economics for rapid-deployment inventory. |
| Smart Home Retrofit Bundling | IoT energy management packages attract tech-forward millennial buyers prioritizing connected infrastructure. |
Research Methodology
Coverage spans Texas, Florida, California, Arizona, and Georgia, with primary inputs from each manufacturing corridor combining interviews with plant operations directors, dealer network principals, FHA lending officers, and HUD compliance consultants. Secondary validation draws from HUD Code revision dockets, FHA Title I and Title II origination reports, state zoning preemption legislative tracking, and manufactured housing community development databases. Bottom-up unit shipment data triangulates against top-down construction spending flows.
Rate-of-change decomposition separates volume drivers from price realization across product type, end-user financing pathway, distribution channel structure, and regional regulatory cluster dimensions over the projection horizon. CAGRs derive from segment-level unit economics modeling incorporating input cost elasticity and placement velocity sensitivity. Forecast inputs include FHA loan guarantee program participation rates and state-level zoning reform adoption curves.
Several conditions sit outside the modeled scope, including extreme commodity price spikes exceeding historical volatility bands and federal loan program legislative suspension. Forecasts reflect documented assumptions about regulatory timeline adherence and labor pool scaling. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
India Residential Real Estate Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
North America Real Estate Brokerage Market