
 Malaysia Real Estate Market | 2026-2036
Malaysia Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Real Estate Market Outlook
Property management and facility operations revenue is tilting from basic maintenance toward integrated smart-building services. Eco World Development Group Berhad leverages its digital infrastructure platform to capture recurring income streams beyond unit sales. Mah Sing Group Berhad anchors its competitive position through rapid project turnover cycles in the affordable residential band. S P Setia Berhad differentiates via township-scale master planning that bundles retail, education, and healthcare amenities within single developments.
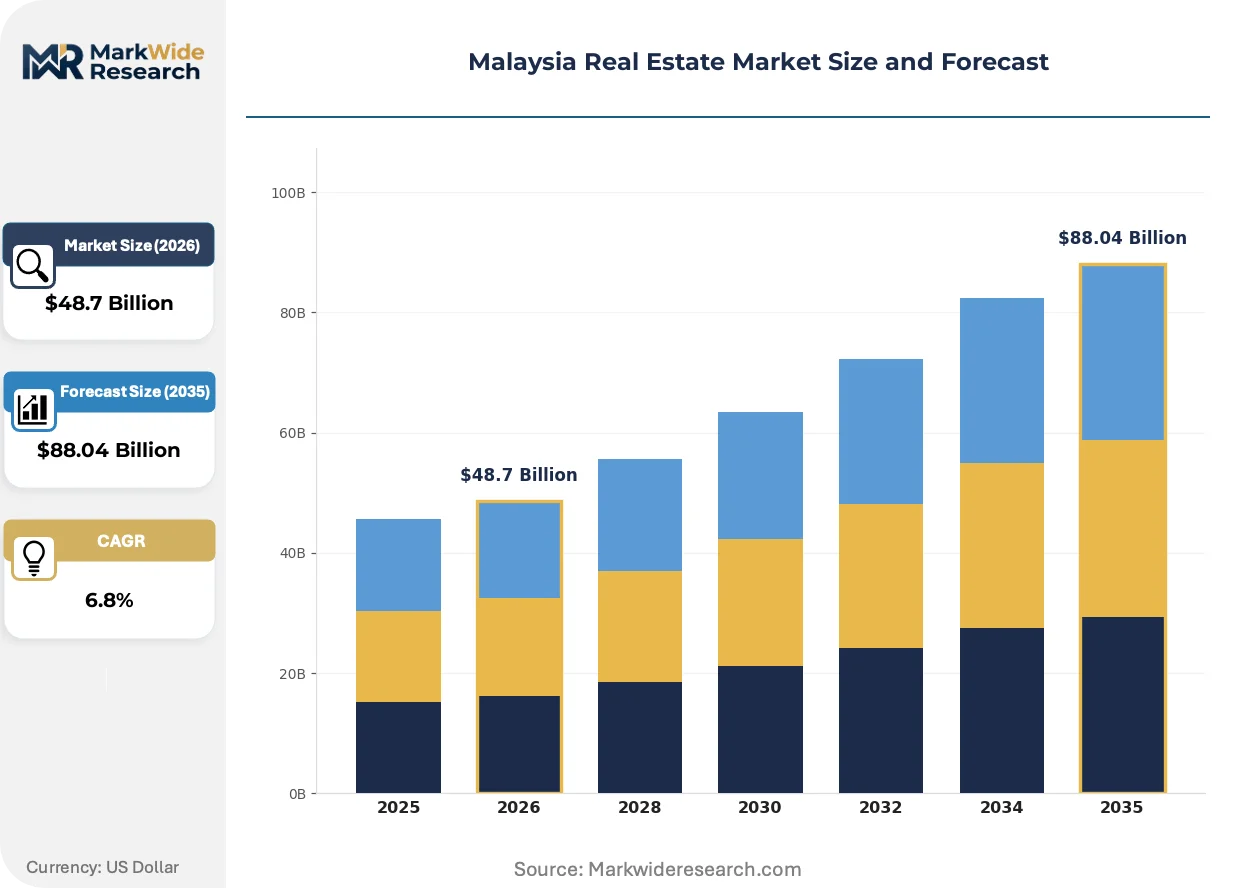
Malaysia real estate encompasses land and permanent structures traded for residential occupation, commercial activity, industrial production, or agricultural use, with developments typically specified by gross floor area, plot ratio, and tenure type spanning freehold to leasehold up to 99 years. The primary commercial purpose centers on generating rental yield, capital appreciation, or operational utility for end-users across a $48.7 billion property stock. Residential property retains the largest transaction volume share, though industrial segments command superior per-square-foot pricing in logistics corridors. Commercial real estate faces structural repricing as hybrid work patterns reshape office absorption rates in Greater Kuala Lumpur.
Bank Negara Malaysia's lending guidelines and the Ministry of Housing and Local Government's affordable housing quotas shape developer project feasibility and buyer financing access. Iskandar Regional Development Authority zoning overlays and Johor state conversion premiums influence land-use intensity and cross-border investment flows. Stakeholders must monitor central bank interest rate trajectories and state-level conversion approval backlogs as these determine launch timing and inventory clearing velocity.
Market Dynamics
Cross-border capital flows from Singapore into Johor Bahru are compressing development timelines and accelerating land-use conversion approvals. This capital pressure is forcing domestic developers to reposition project portfolios toward higher-yielding industrial and data center segments.
Growth Catalysts
- Iskandar Malaysia zoning overlays:The Iskandar Regional Development Authority streamlines conversion premiums and density bonuses for mixed-use developments. Foreign investors exploit these overlays to secure long-dated leasehold positions.
- E-commerce fulfillment warehousing:Port of Tanjung Pelepas corridor operators demand cold-chain and last-mile facilities. Logistics developers are speculatively building grade-A warehouse stock ahead of tenant commitments.
- BIS-equivalent building energy codes:Green certification mandates from the Ministry of Housing tighten material specifications. Certified developments command rental premiums and expedited planning approvals.
Market Restraints
- Interest rate sensitivity:Bank Negara Malaysia's overnight policy rate trajectory directly constrains mortgage affordability. First-time buyer loan eligibility thresholds suppress transaction velocity in the primary residential market.
- Conversion approval backlogs:Johor state land offices face processing delays for agricultural-to-residential title conversions. Developers carry holding costs on land banks awaiting development order issuance.
- Office absorption compression:Hybrid work patterns have structurally reduced net effective rents in Greater Kuala Lumpur Grade-A stock. Landlords face capex demands to retrofit obsolete floor plates.
Strategic Opportunities
- Data center co-location demand:Singapore-crossing hyperscalers seek Johor sites for campus-scale deployments. Power substation proximity and submarine cable landing points determine site selection.
- Integrated township master planning:Bundled retail, education, and healthcare amenities within single developments reduce buyer switching. Township operators capture recurring service revenue beyond unit handover.
- Smart-building service layering:Property management revenue tilts from basic maintenance toward IoT-enabled facility optimization. Digital infrastructure platforms generate subscription income from building systems.
Industry Challenges
- Green certification compliance timelines:BIS-equivalent energy code audits require specialized assessor capacity. Project launches slip when certification documentation lags construction milestones.
- Construction labor availability:Foreign worker quota restrictions constrain site manpower during peak activity phases. Developers absorb wage inflation to maintain project schedules.
- Legacy building system integration:Retrofit projects face interoperability failures when connecting new IoT sensors to existing BMS infrastructure. Technical debt inflates smart-building upgrade costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Real Estate Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Residential, Commercial, Industrial, Agricultural Customer Type: First-Time Buyers, Investors, Developers, Tenants Transaction Type: Buy, Sell, Lease, Rent Facility Type: High-Rise, Low-Rise, Bungalows, Condominiums |
| Companies Covered | Eco World Development Group Berhad, Mah Sing Group Berhad, S P Setia Berhad, Gamuda Land, IOI Properties Group Berhad, Sime Darby Property Berhad, UEM Sunrise Berhad, Tropicana Corporation Berhad, Sunway Property, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Real Estate Market Strategic Shifts
Digital infrastructure and sustainability mandates are reconfiguring how Malaysian real estate generates returns. Developers now compete on operational technology integration rather than unit specifications alone.
Building management systems are migrating from on-premise server architectures to cloud-native platforms with edge computing nodes. Grade-A office landlords in Kuala Lumpur are deploying these systems to optimize HVAC energy consumption in real time. The shift compresses facilities management headcount while improving tenant comfort scorecards.
Bank Negara Malaysia's responsible financing guidelines now embed climate risk assessments into commercial property lending decisions. Lenders demand energy efficiency audits before approving construction loans for large-scale developments. Industrial warehouse sponsors in Selangor are pre-emptively installing solar arrays to satisfy these underwriting requirements.
Institutional investors are consolidating direct property holdings through single-asset and portfolio-level transactions rather than development partnerships. Pension funds and sovereign wealth vehicles from Singapore favor stabilized income-producing assets over construction-risk exposure. This rotation concentrates ownership of prime logistics and office stock in fewer hands across the Klang Valley corridor.
Malaysia Real Estate Market Segmentation
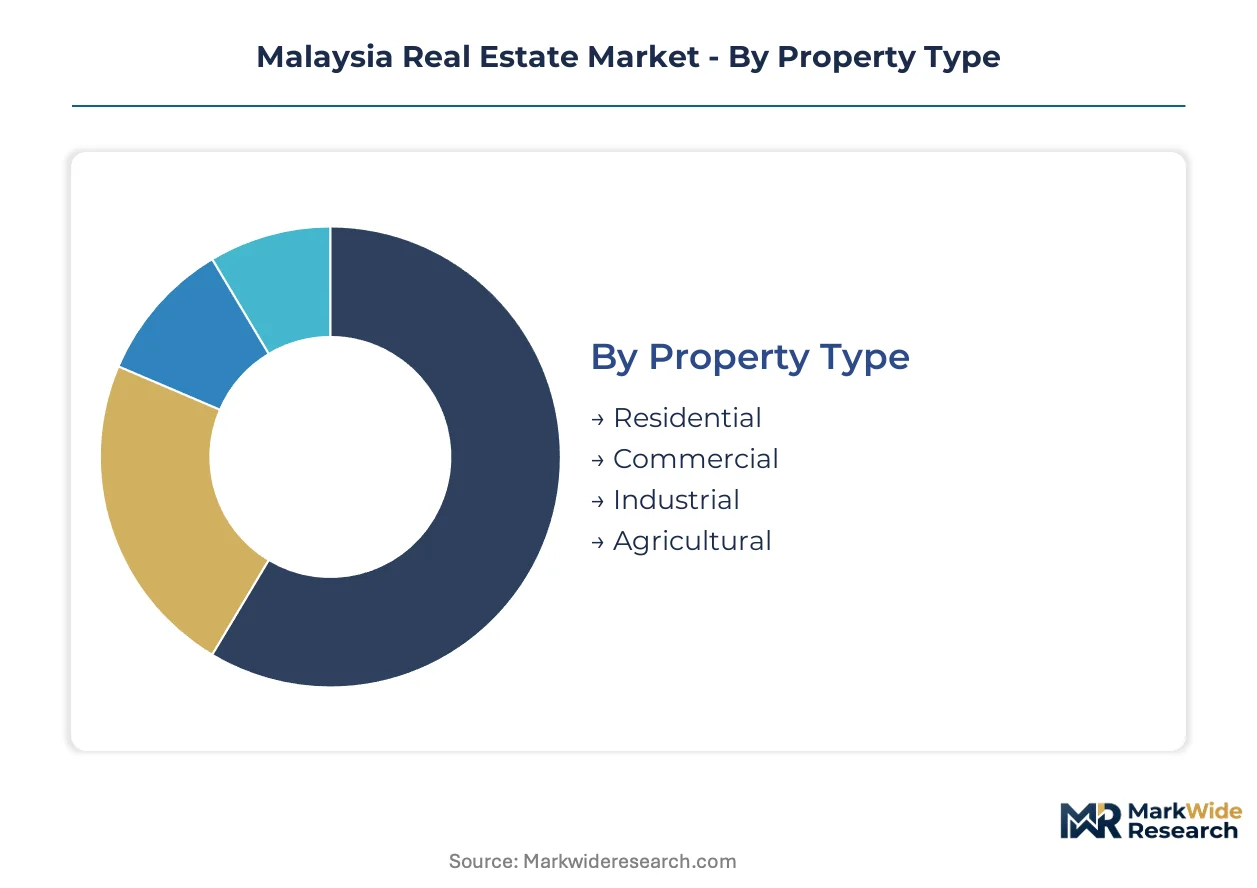
Malaysian real estate segmentation reveals divergent investment horizons across property classes. Residential and industrial assets attract fundamentally different capital pools with distinct yield expectations and regulatory exposures.
Property Type:
Mature segments anchor institutional portfolios while emerging categories capture speculative capital seeking structural repricing.
- Residential:Freehold and leasehold units ranging from terraced houses to high-rise apartments dominate transaction volumes. First-time buyers in Selangor and Johor drive absorption in the affordable band below RM500,000, though Bank Negara Malaysia lending thresholds constrain mortgage eligibility for younger cohorts.
- Commercial:Grade-A office stock in Kuala Lumpur's Golden Triangle and retail podium space in integrated townships generate rental yield streams. Hybrid work patterns have compressed net effective rents, forcing landlords to fund floor-plate retrofits to maintain occupancy.
- Industrial:Logistics warehousing and manufacturing facilities command premium per-square-foot pricing in Selangor and Johor corridor locations. E-commerce fulfillment operators pre-commit to cold-chain and last-mile facilities near Port of Tanjung Pelepas.
- Agricultural:Plantation land and smallholdings trade primarily for conversion speculation into residential or industrial titles. Johor state conversion approval backlogs extend holding periods and inflate carrying costs for land banks.
Residential retains volume leadership; industrial holds the steepest expansion curve.
Customer Type:
Transaction motivation splits between utility-driven occupation and financial return optimization.
- First-Time Buyers:Young households targeting entry-level apartments face deposit requirements and debt-service-ratio limits under responsible financing guidelines. Skim and second-hand markets compete for this constrained demand pool.
- Investors:Domestic and Singapore-crossing purchasers acquire rental-yield assets in Iskandar Malaysia and Greater Kuala Lumpur. Capital appreciation expectations hinge on infrastructure completion timelines and township maturity.
- Developers:Listed property companies and joint-venture sponsors control land banks and construction pipelines. Rapid project turnover specialists compete against township-scale master planners with bundled amenity offerings.
- Tenants:Corporate occupiers and residential renters seek flexible lease terms amid economic uncertainty. Commercial tenants negotiate shorter tenures with renewal options to preserve strategic relocation capacity.
First-time buyers anchor transaction velocity; investors command pricing power in prime submarkets.
Transaction Type:
Liquidity preferences determine whether capital deploys into ownership structures or operating leases.
- Buy:Primary market purchases from developers involve progressive payment schedules tied to construction milestones. Secondary market acquisitions require title verification and outstanding charge clearance.
- Sell:Disposals trigger real property gains tax liabilities scaled to holding period duration. Foreign owners face additional compliance layers under state-level consent requirements.
- Lease:Long-term commercial tenancies with built-in escalation clauses attract institutional capital seeking yield stability. Industrial triple-net leases transfer operating cost burdens to tenant operators.
- Rent:Short-term residential rentals in urban cores serve transient employment populations. Furnished serviced apartments compete with purpose-built rental housing from emerging institutional landlords.
Buy transactions dominate absolute volume; lease structures concentrate institutional capital deployment.
Facility Type:
Built-form density reflects land-value gradients and planning authority zoning incentives.
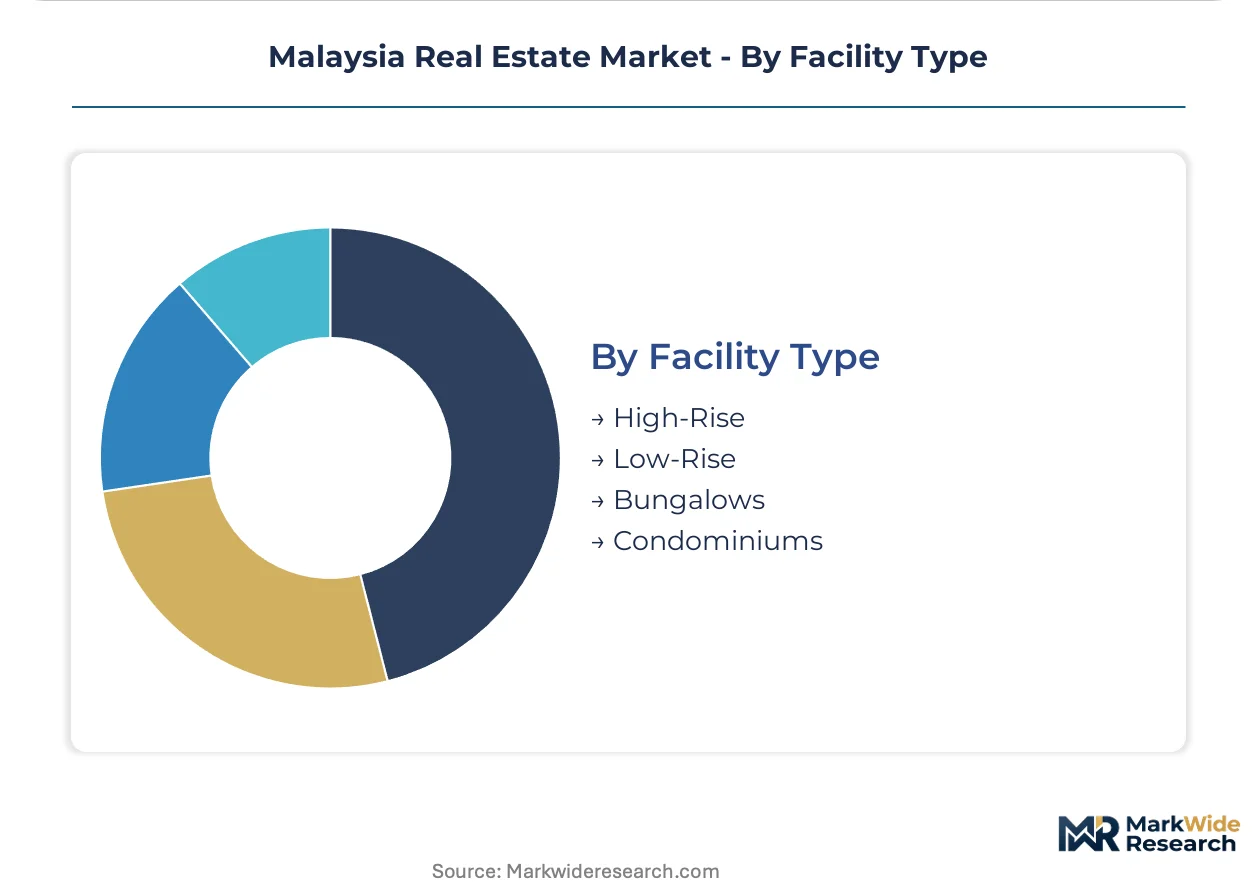
- High-Rise:Condominium and serviced apartment towers maximize plot ratio extraction in transit-oriented development zones. Elevated maintenance fees and sinking fund obligations affect long-term affordability.
- Low-Rise:Walk-up apartments and shop-offices serve price-sensitive segments in secondary locations. Aging stock in Kuala Lumpur's established neighborhoods faces obsolescence pressure.
- Bungalows:Detached landed housing in gated communities commands scarcity premiums in mature suburbs. Foreign acquisition restrictions limit demand pool depth for premium segments.
- Condominiums:Stratified title properties with shared common facilities dominate new supply in urban centers. Joint management bodies grapple with maintenance cost allocation disputes.
High-rise captures supply volume; bungalows maintain pricing elevation in constrained submarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johor Bahru exhibits the highest price elasticity among first-time buyers, while Kuala Lumpur's prime submarkets absorb Singapore-crossing capital with minimal sensitivity to mortgage rate shifts.
Selangor
Petaling Jaya and Shah Alam corridor developers target young households with sub-RM500,000 apartments. Bank Negara Malaysia's debt-service-ratio thresholds constrain loan approvals for this cohort. Cyberjaya's data center cluster draws hyperscaler co-location demand from Singapore operators seeking power substation proximity.
Johor
Iskandar Malaysia zoning overlays compress conversion timelines for mixed-use developments. The Iskandar Regional Development Authority streamlines density bonuses for foreign investors securing leasehold positions. Pasir Gudang industrial zone anchors cold-chain warehousing demand from Port of Tanjung Pelepas fulfillment operators.
Kuala Lumpur
Grade-A office landlords in the Golden Triangle face net effective rent compression from hybrid work patterns. The Ministry of Housing's BIS-equivalent energy codes mandate green certification for new commercial stock. Mont'Kiara and Bangsar South submarkets concentrate township-scale master planning with bundled retail and healthcare amenities.
Penang
Bayan Lepas industrial zone attracts electronics manufacturing facility expansions. Penang Island's limited land supply elevates per-square-foot pricing for residential developments. George Town's UNESCO heritage buffer restricts high-rise density, preserving scarcity premiums for restored shophouse stock.
Sabah
Kota Kinabalu's tourism-dependent rental market serves transient employment populations in hospitality and logistics. State-level conversion approval backlogs extend agricultural-to-residential title timelines. Likas Bay corridor concentrates mid-rise condominium supply targeting domestic investors seeking rental yield exposure.
Malaysia Real Estate Market Competitive Environment
Capability concentration sits with township-scale master planners; scale advantage sits with rapid-turnover affordable housing specialists. The vendor base organizes around three strategic archetypes: integrated township operators capturing recurring service revenue, industrial-logistics developers pre-committing speculative warehouse stock, and smart-building platform providers monetizing IoT-enabled facility optimization. Dominant competitive moves include portfolio diversification into data center co-location and strategic partnerships with Singapore-crossing institutional capital.
Within the township-scale tier, Eco World Development Group Berhad, S P Setia Berhad, and Gamuda Land exemplify bundled-amenity master planning that reduces buyer switching costs. These Berhad-structured developers anchor recurring income streams beyond unit handover through retail, education, and healthcare service layering. Mah Sing Group Berhad occupies a distinct position on the rapid-turnover vector, compressing project cycles in the affordable residential band. The competitive dynamic between these archetypes intensifies as cross-border capital from Singapore forces domestic repositioning toward higher-yielding industrial segments.
| Leading Market Players |
|---|
| Eco World Development Group Berhad |
| Mah Sing Group Berhad |
| S P Setia Berhad |
| Gamuda Land |
| IOI Properties Group Berhad |
| Sime Darby Property Berhad |
| UEM Sunrise Berhad |
| Tropicana Corporation Berhad |
| Sunway Property |
| Others |
Value Chain & Pricing Dynamics
Port of Tanjung Pelepas corridor warehousing capacity dynamics directly shape downstream pricing power for logistics developers in Johor. Grade-A cold-chain facilities command rental premiums when speculative stock pre-commits to e-commerce fulfillment operators ahead of tenant contracts.
Pricing Analysis
Long-term offtake agreements anchor industrial warehouse pricing, while residential transactions run on progressive payment schedules tied to construction milestones. Price differentiation separates green-certified developments with BIS-equivalent energy compliance from standard stock without certification. Pricing pressure stems from Bank Negara Malaysia lending thresholds constraining first-time buyer mortgage eligibility in the affordable residential band. First-time buyers below RM500,000 exhibit highest price sensitivity; Singapore-crossing institutional investors in Iskandar Malaysia show lowest sensitivity to financing cost shifts.
Supply Chain Analysis
Upstream feedstock for construction materials draws from China, Indonesia, and Thailand for steel, cement, and aluminum systems. Green certification mandates from the Ministry of Housing tighten material specifications, forcing specification upgrades in glazing, insulation, and MEP components. Single-source vulnerability concentrates in specialized assessor capacity for energy code audits, causing project launch delays when certification documentation lags construction milestones. Distribution runs through developer-direct sales galleries for primary residential stock and institutional broker networks for commercial and industrial assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
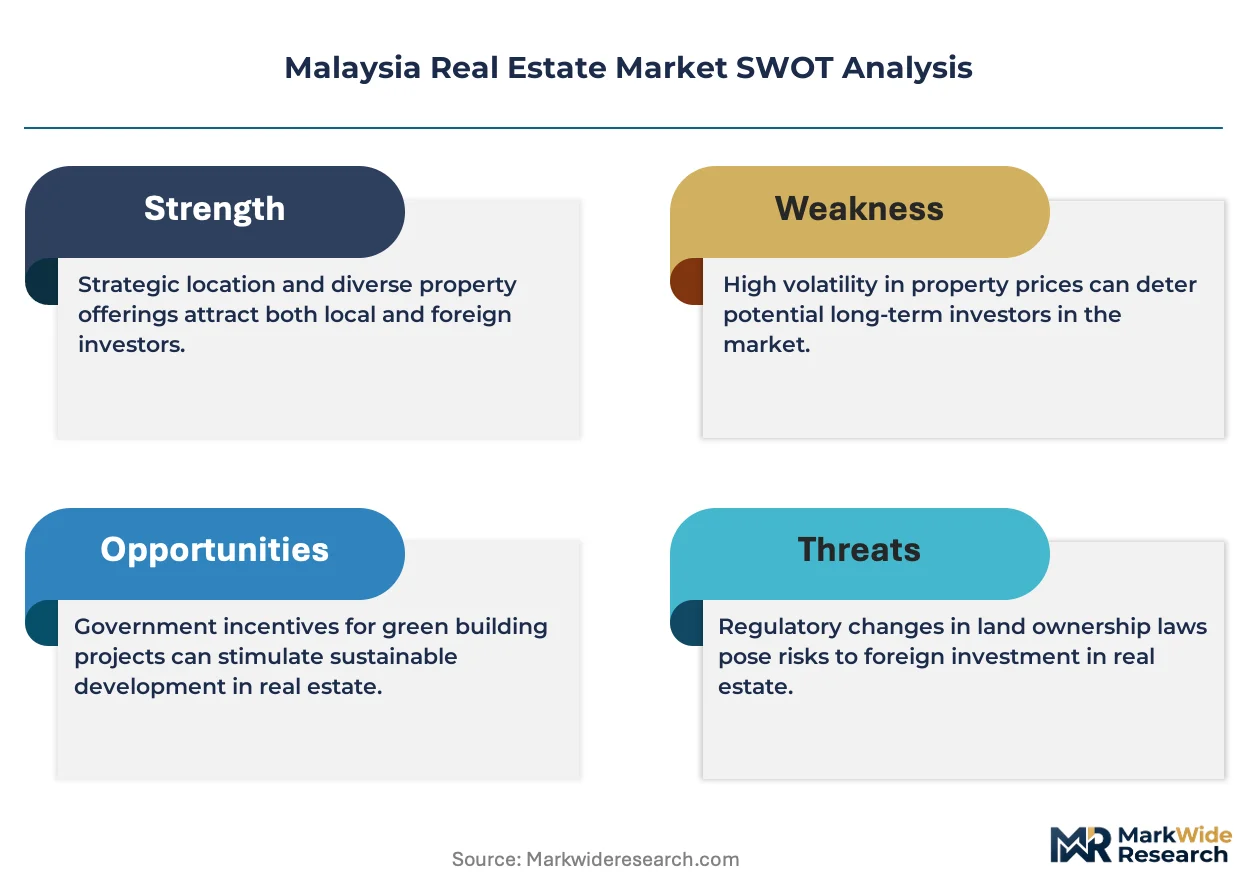
Malaysia real estate sits in early-cycle expansion as data center co-location demand from Singapore hyperscalers accelerates land absorption in Johor corridor submarkets.
For Market Incumbents: Harden township-scale master planning advantages by deepening bundled retail, education, and healthcare service layers that reduce buyer switching costs. Fortify against rapid-turnover specialists through vertical integration into property management platforms generating recurring subscription income from IoT-enabled building systems. For New Entrants and Emerging Players: Sabah's agricultural-to-residential conversion backlog creates white-space opportunity for developers willing to absorb extended holding periods on land banks awaiting title approvals. Target Kota Kinabalu's tourism-dependent rental market with furnished serviced apartments serving transient hospitality and logistics employment populations. Partner with state-level land offices to streamline conversion premium negotiations. For Investors and Strategic Acquirers: Long-term, this sits as a yield-compression play because institutional capital rotation from Singapore concentrates ownership of stabilized logistics and office stock in fewer hands. Acquisition targets should emphasize industrial-logistics developers with pre-committed warehouse stock near Port of Tanjung Pelepas. Watch Bank Negara Malaysia overnight policy rate trajectory as the inflection signal determining residential transaction velocity recovery timing.| Strategic Initiative | Industry Significance |
|---|---|
| Data Center Co-location Partnership | Johor sites with power substation proximity attract Singapore hyperscaler campus-scale deployments. |
| Green Certification Pre-Investment | BIS-equivalent energy code compliance expedites planning approvals and commands rental premiums. |
| Smart-Building Platform Integration | Cloud-native building management systems generate recurring subscription revenue beyond unit handover. |
| Integrated Township Master Planning | Bundled amenities within single developments reduce buyer switching and capture service income. |
| Cross-Border Capital Syndication | Singapore institutional partnerships provide construction-risk capital for industrial segment repositioning. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with property development executives, facilities management directors, and institutional investment officers; and secondary validation against Bank Negara Malaysia lending guideline circulars, Iskandar Regional Development Authority zoning overlays, and Ministry of Housing energy code directives. Bottom-up project pipeline tracking across Selangor, Johor, and Kuala Lumpur submarkets triangulated against top-down capital flow estimates from Singapore-crossing transaction reporting.
Forecast inputs considered property type segmentation by residential, commercial, industrial, and agricultural classes; customer type splits between first-time buyers, investors, developers, and tenants; and facility type differentiation across high-rise, low-rise, bungalow, and condominium stock. CAGRs were derived from absorption rate modeling tied to mortgage eligibility thresholds and infrastructure completion timelines. Data center power demand curves and e-commerce fulfillment floor plate specifications anchored industrial segment projections.
The forecast holds incumbent behavior within observed patterns; aggressive land bank accumulation by Singapore-crossing sovereign wealth vehicles would shift outcomes beyond modeled ranges. Cross-checking against Bank Negara Malaysia quarterly household debt service ratio publications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
Egypt Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
Vietnam Residential Real Estate Market
Residential Real Estate Market
South Korea Residential Real Estate Market