
 South Africa Residential Real Estate Market | 2026-2036
South Africa Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Residential Real Estate Market Analytics
Energy-efficient green certification is collapsing the price gap between premium sustainable homes and conventional builds across South Africa's major metros. Pam Golding Properties leverages its coastal and golf estate portfolio to dominate the luxury segment in KwaZulu-Natal and the Western Cape. Seeff Property Group anchors its competitive position through deep franchise penetration in Cape Town's Atlantic Seaboard and Southern Suburbs. Balwin Properties specializes in large-scale sectional title developments with integrated lifestyle amenities in Gauteng's urban corridors.
South Africa residential real estate encompasses the buying, selling, and leasing of dwellings intended for non-commercial habitation, with stock quality measured by title deed clarity, sectional plan registration under the Sectional Titles Act, and compliance with National Building Regulations SANS 10400 standards for structural safety and energy usage. The primary commercial purpose centers on wealth preservation through bricks-and-mortar assets in a market where mortgage finance availability directly governs transaction velocity. Affordable housing and middle-income housing are absorbing the bulk of new supply as developers respond to Finance Linked Individual Subsidy Programme incentives and gap housing demand from formally employed households excluded from fully subsidized programmes. Luxury homes retain the deepest margin pools but face constrained volume growth due to transfer duty thresholds and emigration-driven seller pressure in prime Johannesburg nodes.
South Africa's National Home Builders Registration Council enforces warranty protections and structural competency standards that shape developer construction decisions and buyer recourse pathways. The Department of Human Settlements coordinates the Finance Linked Individual Subsidy Programme and Breaking New Ground policy framework, directing public-private partnership investment toward serviced land release and affordable unit delivery. Municipal rate base pressures and ongoing electricity reliability challenges from Eskom will force stakeholders to weigh location risk against infrastructure-backed value appreciation in site selection and portfolio allocation decisions.
Market Dynamics
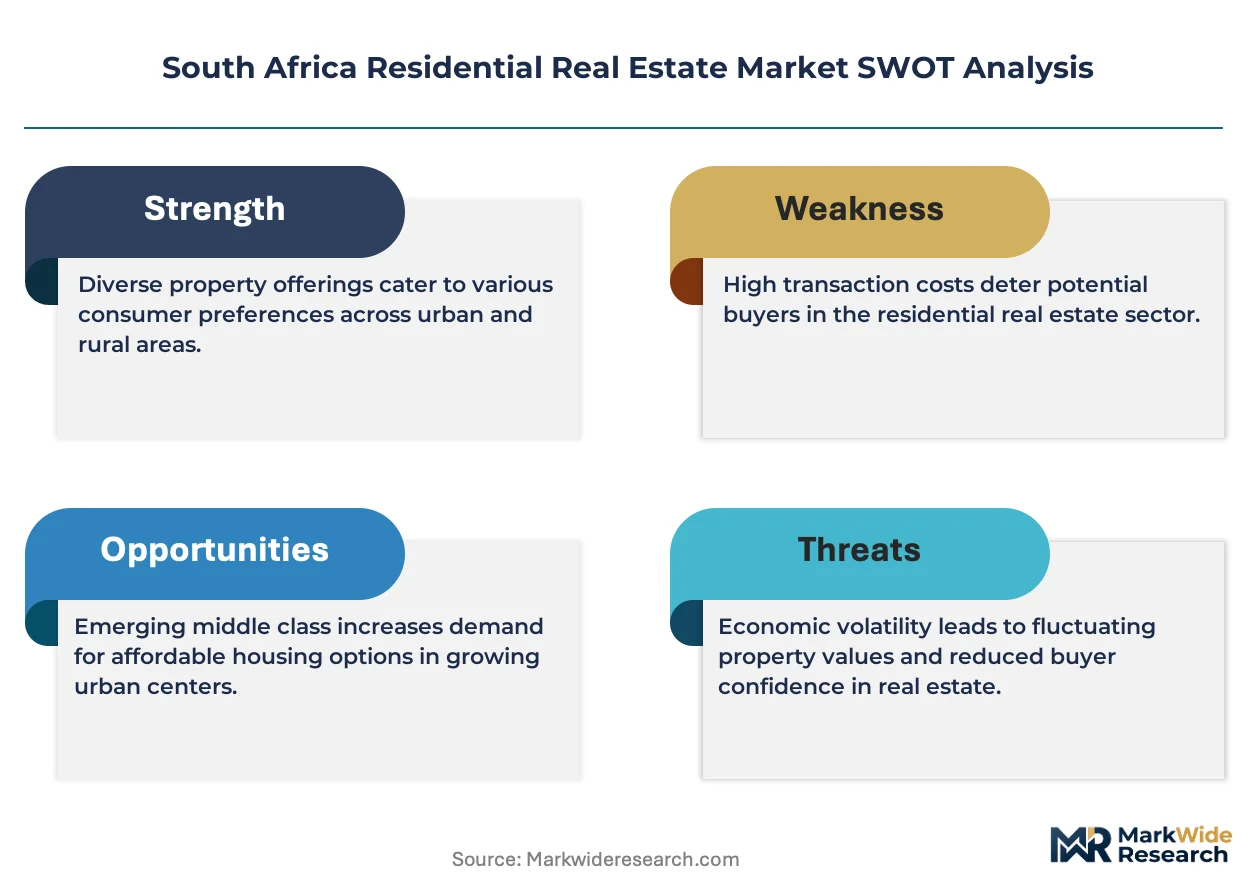
The Finance Linked Individual Subsidy Programme is redirecting developer capital toward affordable housing stock, compressing margins in the mid-market while amplifying transaction velocity in Gauteng's urban corridors.
Growth Catalysts
- FLISP subsidy channeling:South Africa's Department of Human Settlements directs formally employed households excluded from fully subsidized programmes into gap housing developments, expanding the addressable buyer base in Johannesburg and Pretoria corridors.
- Secure estate preference clustering:Detached houses in access-controlled developments near Cape Town and Durban are capturing sustained buyer interest as crime-sensitive households prioritize perimeter security over standalone suburban plots.
- Eskom reliability arbitrage:Load-shedding frequency is accelerating demand for solar-integrated new builds, with energy autonomy becoming a decisive site-selection criterion for premium buyers.
Market Restraints
- Transfer duty threshold compression:South Africa's sliding transfer duty structure imposes steep marginal rates on transactions above ZAR 2.5 million, constraining volume growth in Johannesburg's prime northern suburbs where emigration-driven seller pressure already softens pricing power.
- Municipal rate base erosion:Eskom debt restructuring and distribution maintenance backlogs in eThekwini and Johannesburg metros are degrading infrastructure-backed value appreciation assumptions in peripheral locations.
- Mortgage availability cyclicality:South African Reserve Bank policy rate transmission directly governs transaction velocity, with prime-linked lending rates compressing first-time buyer qualification ratios during tightening cycles.
Strategic Opportunities
- Western Cape coastal corridor extension:Garden Route towns between George and Plettenberg Bay remain underpenetrated by institutional developers, offering land-banking positions ahead of remote-work migration patterns.
- Green certification premium capture:Energy-efficient building standards under SANS 10400-XA are creating pricing stratification, with certified builds commanding measurable premiums in Cape Town's Atlantic Seaboard resale market.
- Sectional title lifestyle bundling:Integrated amenities—co-working spaces, concierge services, wellness facilities—within large-scale sectional title developments are displacing standalone housing preference among Gauteng's young professional cohort.
Industry Challenges
- NHBRC warranty compliance timelines:National Home Builders Registration Council structural competency assessments and defect liability period administration are extending project handover schedules, compressing developer cash conversion cycles.
- Skilled construction labor scarcity:Artisan availability for specialized energy-system installation and green building certification compliance is constraining rollout velocity in high-growth nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Residential Real Estate Market |
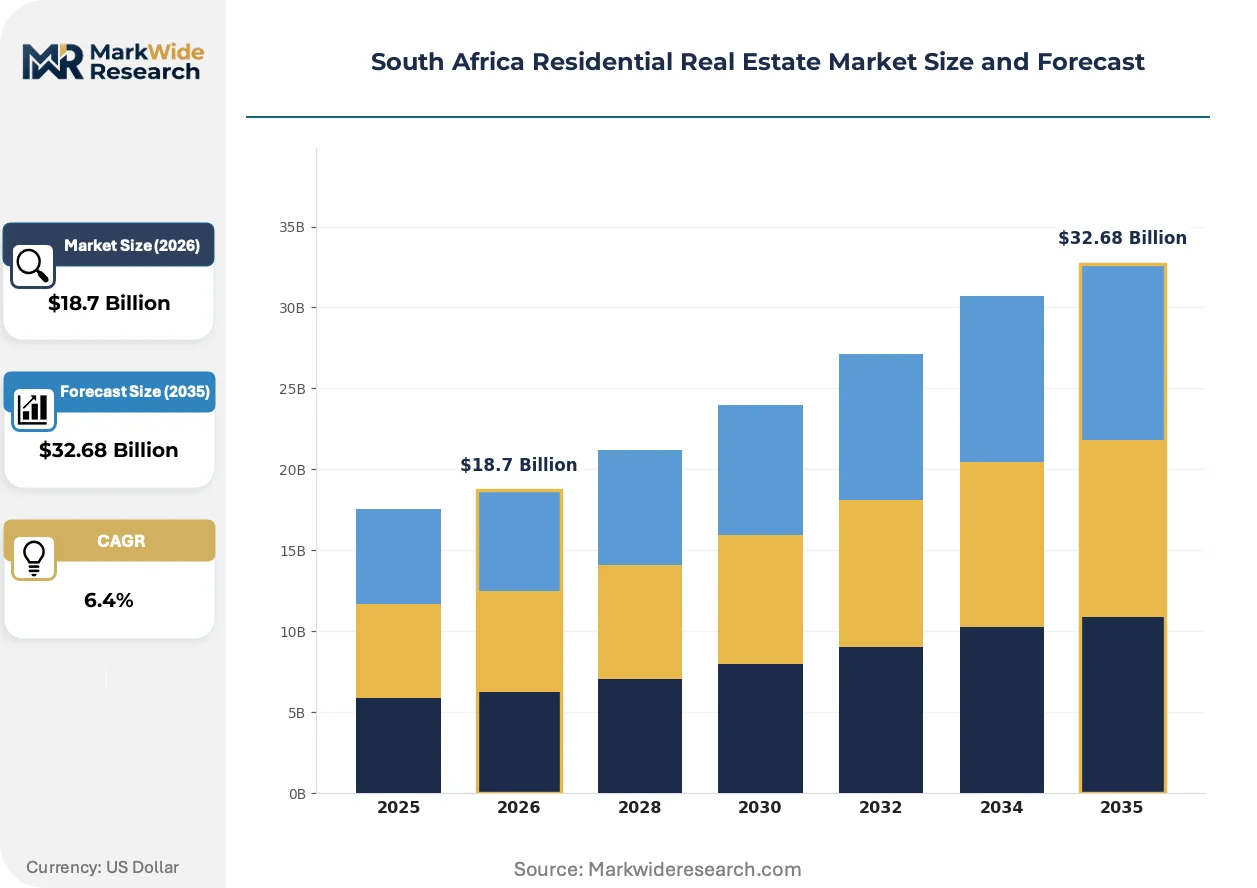
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Detached Houses, Townhouses, Apartments, Bungalows Market Segment: Luxury Homes, Affordable Housing, Middle-Income Housing, Social Housing Buyer Type: First-Time Buyers, Investors, Retirees, Foreign Buyers Sales Channel: Direct Sales, Real Estate Agents, Online Listings, Auctions |
| Companies Covered | Pam Golding Properties, Seeff Property Group, RE/MAX of Southern Africa, Rawson Property Group, Chas Everitt International, Balwin Properties, Calgro M3, Jawitz Properties, Growthpoint Properties, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Residential Real Estate Market Evolving Landscape
Digital transaction platforms and embedded energy systems are restructuring how South African buyers discover, finance, and occupy residential assets across price tiers.
Solar PV and battery storage integration is displacing grid-dependent construction as the default specification in new estate developments. Premium buyers in Cape Town's Southern Suburbs and Johannesburg's northern corridor now treat energy autonomy as non-negotiable. This technology shift is compressing resale values of unretrofitted stock built before 2020.
South Africa's Breaking New Ground policy framework is mandating serviced land release through public-private partnerships, redirecting municipal planning capacity toward affordable unit delivery. The industrial consequence is densification pressure on urban peripheries previously zoned for low-rise expansion. Gauteng municipalities are responding with accelerated sectional title approval processes to absorb channelled demand.
Remote-work permanence is rotating demand toward secondary cities and coastal towns outside traditional commuting radii. Estate agents in the Western Cape report buyer origination shifts from Johannesburg-based relocations to local telecommuter households. This pattern is most visible in Hermanus and Mossel Bay, where transaction volumes now outpace pre-2020 Cape Town metro growth rates.
South Africa Residential Real Estate Market Segmentation
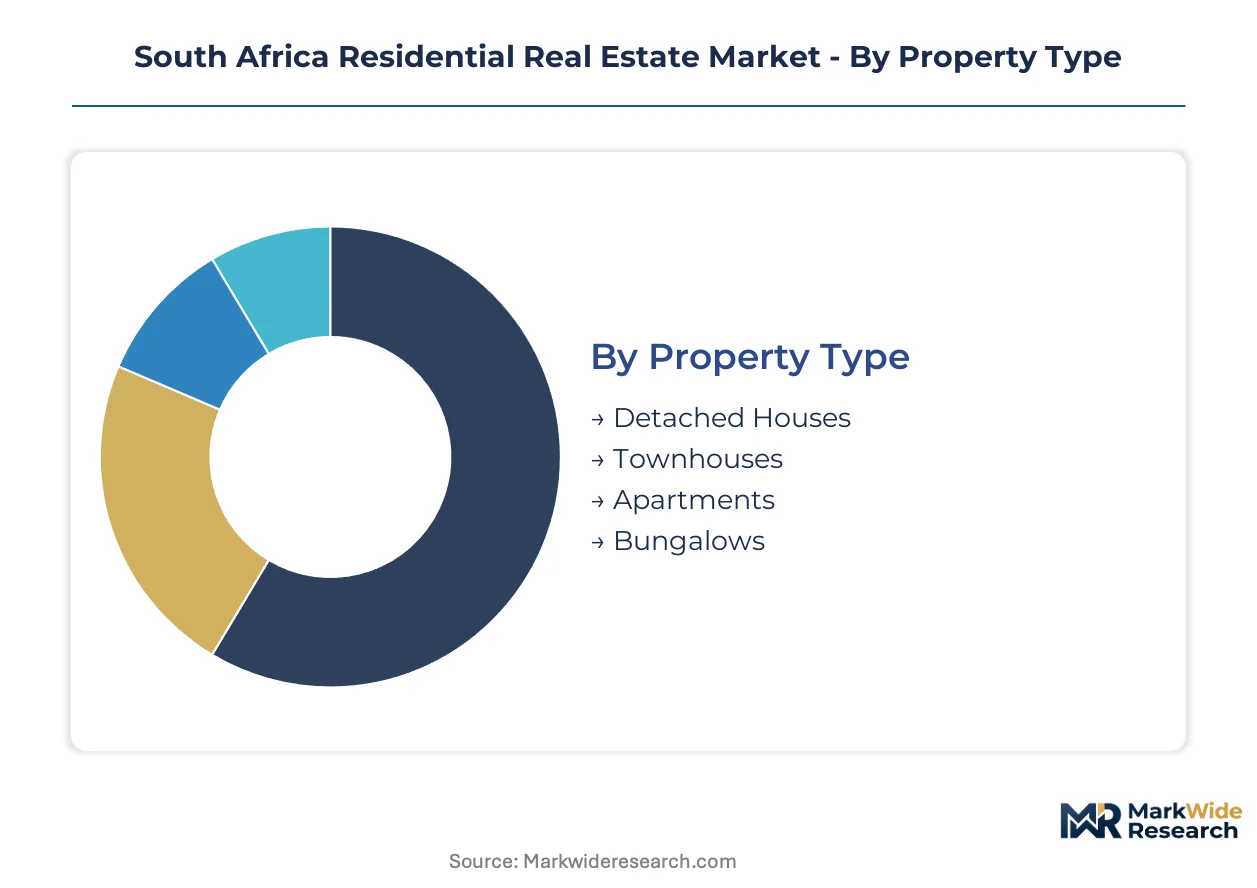
South Africa's residential market fragments across four distinct dimensions that govern capital allocation, construction specifications, and transaction velocity. Each segmentation layer reveals how subsidy programmes, security preferences, and mortgage accessibility reshape competitive positioning across Gauteng, Western Cape, and KwaZulu-Natal.
Property Type:
Substitution pressure runs strongest against standalone suburban plots as sectional title formats capture Gauteng's young professional cohort and Western Cape's remote-work migrants.
- Detached Houses:Free-standing dwellings on individual erf titles remain the default aspiration for family households, particularly in secure estates near Johannesburg's northern corridor and Cape Town's Atlantic Seaboard where perimeter security commands premium pricing. Estate agents report sustained buyer interest for access-controlled developments with solar integration and backup power systems as load-shedding frequency degrades grid-dependent stock values.
- Townhouses:Multi-unit row housing with shared walls and sectional title governance dominates middle-income supply in Pretoria's eastern nodes and Durban's northern suburbs. Developers leverage Breaking New Ground policy incentives to accelerate sectional plan registration, compressing approval timelines for densification projects targeting gap housing demand.
- Apartments:High-rise and mid-rise flats concentrate in Cape Town's CBD and Sandton's commercial core, serving investor buyers seeking rental yield from young professional tenants.
- Bungalows:Single-storey detached formats retain preference among retiree buyers in coastal Garden Route towns and KwaZulu-Natal's North Coast.
Detached houses anchor the volume base while apartments gain share at the steepest rate in Cape Town's urban core.
Market Segment:
Cost tier stratification determines margin pools, with transfer duty thresholds creating pricing cliffs that reshape developer product mix decisions.
- Affordable Housing:Units priced below FLISP programme ceilings absorb the bulk of public-private partnership investment, with the Department of Human Settlements channeling formally employed households into gap housing stock across Johannesburg and Tshwane corridors. Serviced land release mandates under Breaking New Ground accelerate delivery timelines for this segment.
- Middle-Income Housing:Stock priced between subsidised thresholds and luxury transfer duty bands faces compressed margins as mortgage availability cyclicality constrains first-time buyer qualification ratios during South African Reserve Bank tightening cycles.
- Luxury Homes:Premium stock above ZAR 2.5 million faces volume constraints from steep marginal transfer duty rates and emigration-driven seller pressure in prime Johannesburg nodes.
- Social Housing:Fully subsidised rental units fall outside commercial transaction flows, though institutional investors participate through regulated rental stock portfolios.
Affordable housing commands the deepest public capital commitment while middle-income stock faces the sharpest demand volatility.
Buyer Type:
Customer composition shifts reflect generational wealth transfer patterns and currency-driven foreign acquisition windows.
- First-Time Buyers:Formally employed households excluded from fully subsidised programmes leverage FLISP subsidies to enter Gauteng's urban corridors, with mortgage pre-approval rates governing transaction velocity in Pretoria and Johannesburg.
- Investors:Buy-to-let purchasers concentrate in Cape Town's Atlantic Seaboard and Sandton's rental nodes, targeting yield from young professional tenants in sectional title developments with integrated amenities.
- Retirees:Downsizing buyers rotate capital toward Western Cape coastal towns and KwaZulu-Natal's North Coast, driving transaction volume growth in Hermanus and Ballito.
- Foreign Buyers:Non-resident purchasers face exchange control constraints and transfer duty surcharges, limiting participation to prime Cape Town and Johannesburg nodes during rand depreciation windows.
First-time buyers supply the transaction base while retirees rotate capital fastest into coastal secondary markets.
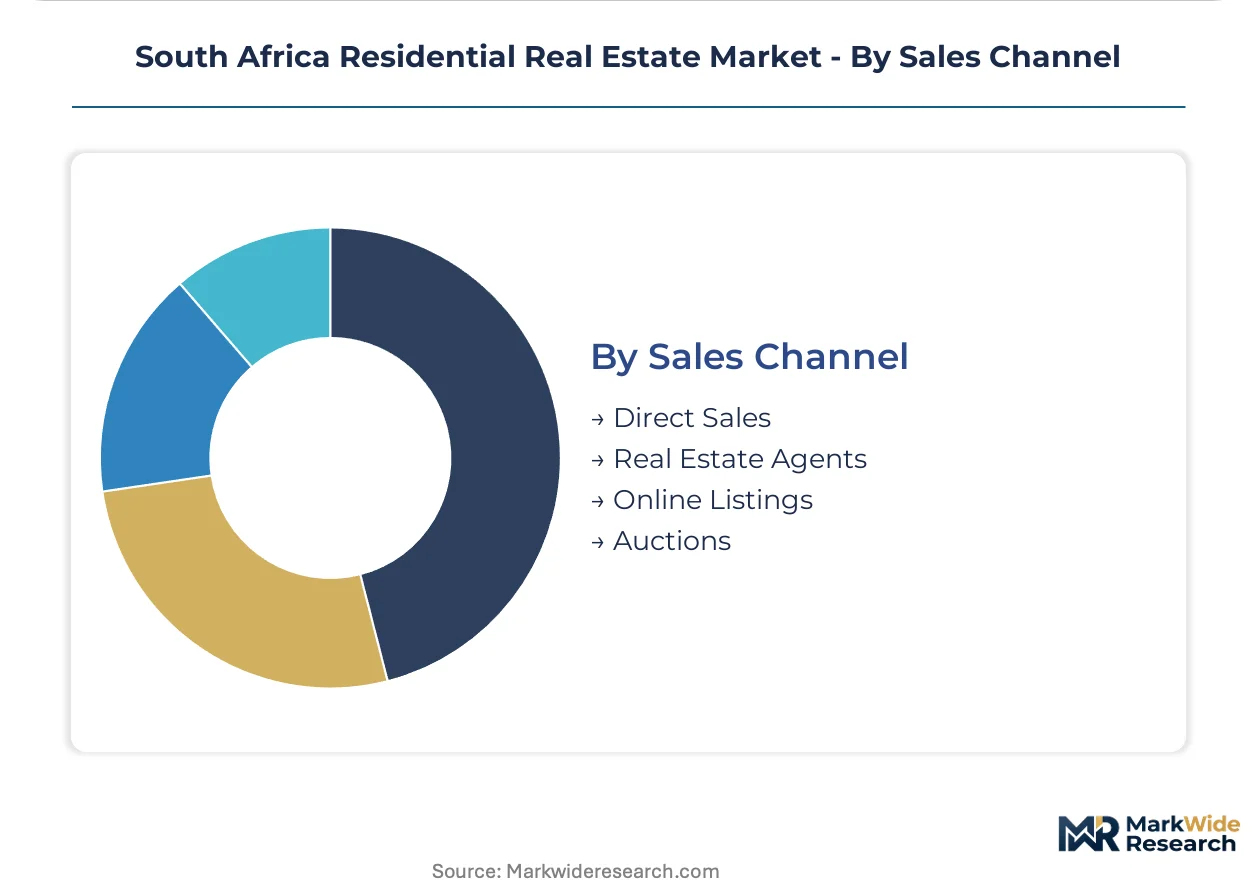
Sales Channel:
Channel mix evolution tracks digital platform penetration and high-value transaction complexity requirements.
- Real Estate Agents:Franchise networks dominate Cape Town's Atlantic Seaboard and Southern Suburbs, with commission-based intermediaries capturing luxury segment transactions requiring valuation complexity and buyer qualification support.
- Online Listings:Property portals displace print classifieds for initial discovery, though conversion still requires physical inspection given South Africa's title deed clarity risks and NHBRC warranty verification needs.
- Direct Sales:Developer-led sales offices control new build transactions in large-scale sectional title projects, capturing margin that would otherwise flow to intermediaries.
- Auctions:Distressed and estate stock clears through court-ordered and voluntary auction processes, concentrated in Johannesburg's northern suburbs where emigration-driven seller pressure elevates distressed supply.
Agent-mediated sales retain the value concentration while online channels capture the steepest share expansion in initial buyer discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developer capital clusters in Gauteng's urban corridors and Western Cape coastal nodes, with provincial planning authorities accelerating sectional title approvals to absorb channelled demand from subsidy programmes and remote-work migration.
Gauteng
First-time buyers leverage FLISP subsidies to enter Johannesburg and Tshwane corridors, where the Department of Human Settlements channels formally employed households into gap housing stock. The Breaking New Ground policy framework accelerates serviced land release in peripheral municipalities. Pretoria's eastern nodes and Sandton's commercial core concentrate mid-rise sectional title developments targeting young professional tenants.
Western Cape
Remote-work permanence rotates demand toward Atlantic Seaboard estates and Garden Route towns between George and Plettenberg Bay. The provincial planning department fast-tracks green building certifications under SANS 10400-XA standards. Hermanus and Mossel Bay transaction volumes now outpace pre-2020 Cape Town metro growth rates as telecommuter households displace Johannesburg relocations.
KwaZulu-Natal
Secure estate developments near Durban capture crime-sensitive household preferences for perimeter security over standalone suburban plots. Municipal rate base pressures from Eskom debt restructuring degrade infrastructure-backed value appreciation in peripheral eThekwini locations. Ballito and the North Coast concentrate retiree downsizing demand from Gauteng capital rotation.
Eastern Cape
Affordable housing developers exploit land cost arbitrage relative to Gauteng metros, targeting FLISP-eligible buyers priced out of Johannesburg corridors. The provincial human settlements department coordinates public-private partnership investment toward serviced land release in Gqeberha and East London. Transaction velocity remains constrained by mortgage availability cyclicality and distant commercial employment nodes.
South Africa Residential Real Estate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across South Africa's residential real estate market. Franchise networks dominate high-value transaction intermediation in coastal premium nodes, while integrated developers control margin capture in large-scale sectional title rollouts. Three archetypes define competitive positioning: heritage-brand estate agencies with coastal portfolio depth, volume-driven sectional title specialists, and diversified property conglomerates with rental yield exposure. Dominant competitive moves include geographic portfolio diversification into secondary cities and backward integration into land banking ahead of infrastructure extension.
Among heritage-brand intermediaries, Pam Golding Properties and Seeff Property Group exemplify coastal and metropolitan corridor concentration respectively. Pam Golding Properties occupies a position within the luxury segment anchored by golf estate and Atlantic Seaboard exposure. Seeff Property Group sits within the franchise-network tier with deep penetration in Cape Town's Southern Suburbs. Balwin Properties represents the integrated developer archetype, specializing in large-scale sectional title developments with bundled lifestyle amenities across Gauteng's urban corridors.
| Leading Market Players |
|---|
| Pam Golding Properties |
| Seeff Property Group |
| RE/MAX of Southern Africa |
| Rawson Property Group |
| Chas Everitt International |
| Balwin Properties |
| Calgro M3 |
| Jawitz Properties |
| Growthpoint Properties |
| Others |
Value Network & Pricing Analysis
Ninety-day construction material lead times in Gauteng's urban corridors compress developer cash conversion cycles while amplifying pricing power for suppliers with secured inventory positions. This inventory scarcity dynamic concentrates margin capture upstream in cement, steel, and solar component distribution networks, forcing developers to absorb cost volatility or pass through to pre-qualified buyers.
Pricing Analysis
South Africa's Sectional Titles Act dictates the pricing tier structure across the residential market, with registration compliance costs creating measurable stratification between premium estate developments and conventional suburban stock. Three-tier pricing structure across premium, standard, and economy levels separates Atlantic Seaboard luxury estates from mid-market sectional title units and FLISP-subsidised affordable housing. Cost compression in the middle-income tier is intensifying because mortgage availability cyclicality from South African Reserve Bank tightening constrains buyer qualification ratios. First-time buyers accessing FLISP subsidies exhibit the highest price sensitivity, while luxury segment purchasers in Cape Town's coastal nodes demonstrate the least.
Supply Chain Analysis
Inventory holding periods for solar PV and battery storage systems have compressed to six-to-eight weeks as load-shedding frequency accelerates specification defaults in new developments. Supply concentrates in China for photovoltaic modules, South Africa for cement and aggregates, and Germany for high-efficiency inverter technology. Raw material dependencies rest on imported lithium-ion cells, locally quarried limestone, and steel reinforcement from ArcelorMittal South Africa. Single-source vulnerability runs through Eskom grid connection timelines, which govern project energisation schedules. Distribution runs through developer-direct procurement for large-scale sectional title rollouts and merchant builders' merchants for standalone suburban construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Property management and energy service contracts are expanding faster than bricks-and-mortar transaction margins, creating a service-attach opportunity for stakeholders who bundle ongoing operational control with initial unit sales.
For Market Incumbents: Consolidate land-banking positions in Western Cape Garden Route corridors ahead of remote-work migration saturation, while deepening backward integration into solar installation and battery maintenance capabilities to capture recurring revenue from energy-autonomous estates. The threat of emigration-driven seller pressure in prime Johannesburg nodes demands defensive positioning in coastal secondary markets where inbound Gauteng capital rotation persists. For New Entrants and Emerging Players: Lead with sectional title lifestyle bundling in Pretoria's eastern nodes, where Breaking New Ground policy incentives accelerate approval timelines and young professional tenant demand outpaces institutional developer supply. The most penetrable white space sits in integrated co-working and wellness amenity provision within large-scale residential developments, with a direct-to-buyer digital sales platform as the go-to-market angle to displace traditional agent intermediation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across affordable housing public-private partnerships as serviced land release mandates compress site preparation timelines. Long-term viability over the coming decade hinges on exposure to rental yield portfolios in Western Cape coastal towns and Gauteng's urban corridors. Acquisition targets should concentrate on developers with NHBRC warranty compliance track records and established municipal planning relationships. The signal to watch is FLISP subsidy allocation volumes from the Department of Human Settlements as demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Land Banking in Secondary Corridors | Positions developers ahead of remote-work migration into Garden Route towns between George and Plettenberg Bay. |
| Green Certification Compliance | SANS 10400-XA energy efficiency standards command measurable resale premiums in Cape Town's Atlantic Seaboard market. |
| Integrated Amenity Bundling | Co-working spaces and wellness facilities within sectional title developments displace standalone housing preference among young professionals. |
| Solar-Plus-Storage Specification Default | Energy autonomy becomes non-negotiable site-selection criterion as load-shedding frequency degrades grid-dependent stock values. |
| FLISP Channel Partnership | Formal collaboration with the Department of Human Settlements secures priority allocation of gap housing demand from formally employed households. |
Research Methodology
The analysis maps affordable housing, middle-income housing, luxury homes, and sectional title developments, each validated through developer executives, municipal planning officers, mortgage originators, and estate agency franchise heads. Primary interviews with these stakeholders combined with secondary validation from National Home Builders Registration Council warranty filings, South African Reserve Bank credit extension data, Deeds Office transaction records, and municipal sectional title approval databases. Bottom-up unit count aggregation and top-down value estimation triangulate market size outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation across property type, market segment, buyer type, and sales channel, with provincial geographic disaggregation and green certification status as cross-cutting dimensions. CAGRs derive from trend extrapolation of transaction velocity, mortgage approval rates, and subsidy programme allocation trajectories. Key forecast inputs include Eskom load-shedding frequency projections and Breaking New Ground policy implementation pace.
Forecasts assume regulatory continuity in South Africa's National Building Regulations and Breaking New Ground policy framework; material policy shifts would require re-modeling. Specific risks that could revise projections include NHBRC warranty compliance timeline extensions, municipal rate base erosion from Eskom debt restructuring, and South African Reserve Bank policy rate volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
South Korea Residential Real Estate Market