
 South Korea Residential Real Estate Market | 2026-2036
South Korea Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Residential Real Estate Market Insights
Project financing through asset-backed securitization is reconfiguring capital access for mid-tier developers. Samsung C&T leverages its integrated construction-finance platform to anchor large-scale apartment complexes in Seoul's satellite cities. DL E&C competes through specialized engineering capabilities in high-rise residential towers. Korea Land & Housing Corporation dominates public-sector supply with direct government funding for affordable housing stock.
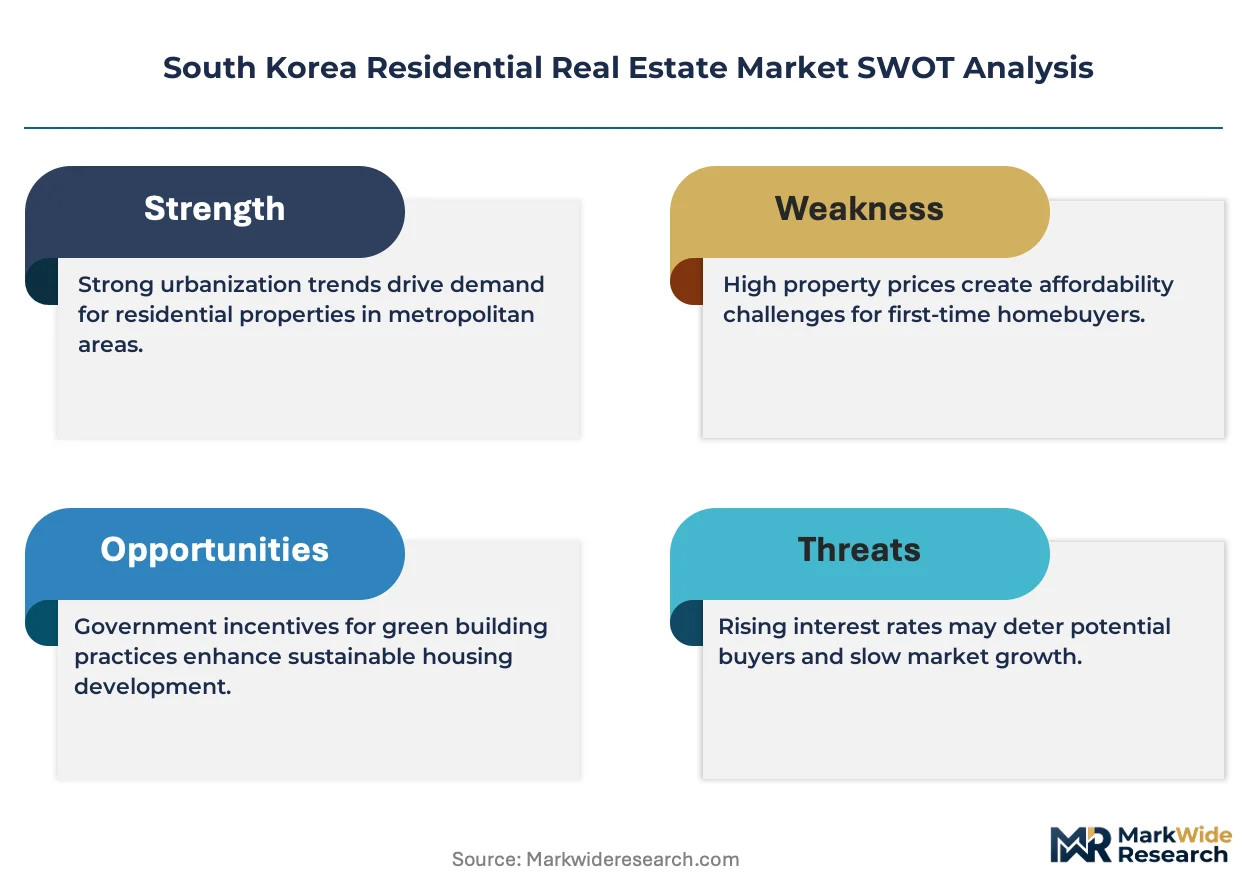
South Korea residential real estate encompasses privately and publicly developed housing units intended for permanent or long-term occupancy, typically constructed with reinforced concrete frame systems and standardized floor-area ratios mandated by municipal zoning codes. The primary commercial purpose centers on delivering shelter assets to owner-occupiers and rental-income seekers within one of Asia's most urbanized populations. Apartment property types lead transaction volumes and price benchmarks nationwide, while student housing segments within the buyer profile dimension attract rising institutional capital seeking yield compression. Luxury market segments command premium pricing in Seoul's core districts, whereas affordable categories face persistent supply constraints despite policy intervention.
MFDS building material standards, Ministry of Land Infrastructure and Transport zoning enforcement, and Kookmin Bank mortgage regulation collectively shape construction quality thresholds, development density limits, and household leverage capacity. The country's national housing regulator periodically adjusts price-ceiling rules for designated speculation zones, directly cooling or stimulating demand in overheated districts. Stakeholders must monitor whether Seoul's expanded greenbelt release plans and Busan's special district designation alter site acquisition economics for private developers.
Market Dynamics
Project financing through asset-backed securitization is reconfiguring capital access for mid-tier developers across South Korea's residential construction sector. This structural shift is compressing development timelines while concentrating risk exposure among institutional underwriters.
Growth Catalysts
- Ministry of Land Infrastructure and Transport zoning enforcement:Relaxed floor-area ratio limits in designated new town zones accelerate site feasibility for private developers targeting young family demand.
- Seoul satellite city clusters:Gyeonggi Province's infrastructure corridors concentrate population inflows from capital region workers seeking affordable unit entry points.
- Reinforced concrete frame systems:Standardized construction methodologies reduce per-unit development costs while enabling rapid vertical assembly in high-density districts.
Market Restraints
- Greenbelt release constraints:Seoul's urban containment boundary limits developable land supply, inflating site acquisition premiums beyond mid-tier developer reach.
- Household leverage ceilings:Kookmin Bank mortgage regulation caps debt-service ratios, constraining purchasing power for price-tier migration.
- Speculation zone price ceilings:National housing regulator cooling measures suppress developer margin recovery in overheated Gangnam corridor districts.
Strategic Opportunities
- Busan special district designation:Regulatory tailwinds for Korea's second metropolitan zone attract capital seeking yield compression outside Seoul's saturated core.
- Student housing yield compression:Institutional capital deployment targets purpose-built rental assets serving university corridor demand in Daejeon and Daegu.
- Integrated construction-finance platforms:Technology convergence between development execution and capital structuring creates captive funding advantages for scale operators.
Industry Challenges
- MFDS building material certification timelines:Extended approval cycles for novel insulation and facade systems delay project launches and compress developer working capital cycles.
- Legacy zoning code fragmentation:Municipal-level density variation across Gyeonggi Province jurisdictions complicates portfolio-standardized development approaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Residential Real Estate Market |
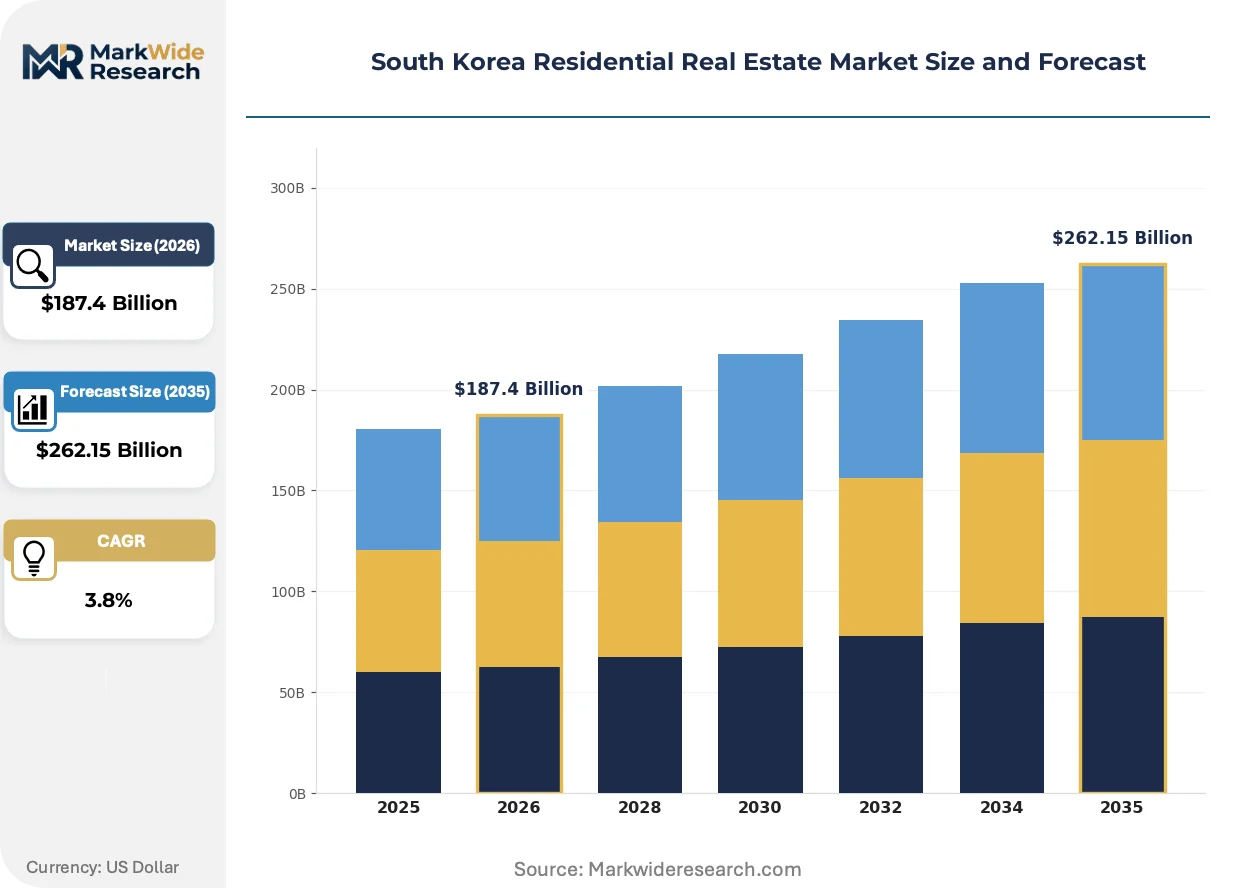
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $262.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Apartment, Detached House, Townhouse, Condominium Market Segment: Luxury, Mid-Range, Affordable, Student Housing Buyer Profile: First-Time Buyers, Investors, Families, Retirees Sales Channel: Real Estate Agents, Online Portals, Auctions, Direct Sales |
| Companies Covered | Lotte Engineering & Construction, DL E&C, Hyundai Development Company, Posco E&C, Daewoo Engineering & Construction, Samsung C&T, Booyoung Group, Korea Land & Housing Corporation, GS Engineering & Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Residential Real Estate Market Trends and Innovations
Smart building integration and modular construction methods are compressing development cycles while reshaping buyer expectations across South Korea's residential sector. These shifts are redistributing competitive advantage toward technology-capable developers.
Prefabricated bathroom pods and kitchen modules are migrating from niche luxury applications to mainstream apartment construction. Mid-scale developers in Suwon and Seongnam are adopting these systems to accelerate unit turnover. The technology is migrating from premium-tier demonstration projects to volume-standard deployment, compressing skilled-labor dependency and reducing on-site construction waste.
MFDS building material standards now mandate enhanced fire-resistance ratings for high-rise residential towers above twenty stories. This regulatory tightening accelerates substitution toward non-combustible facade cladding systems. Premium segment developers in Seoul's Yeouido and Gangnam districts are absorbing certification costs through unit pricing power, while affordable segment projects face margin compression from mandatory material upgrades.
Digital mortgage pre-approval platforms are displacing branch-based application processes for first-time buyer segments. Korea Land & Housing Corporation's integrated portal channels direct subsidized loan access to eligible households. This channel shift concentrates transaction velocity in government-backed financing vehicles, reducing private lender origination share in entry-level price brackets across Gyeonggi Province new town zones.
South Korea Residential Real Estate Market Segmentation
Segmentation in South Korea's residential real estate reveals how construction standards, financing access, and demographic targeting fragment demand across distinct buyer ecosystems. Understanding these divides clarifies where government subsidies concentrate purchasing power and where private developers capture margin premiums.
Property Type:
The use-case spectrum spans permanent family settlement to rental-income instruments, with each property type commanding different construction methodologies and zoning permissions.
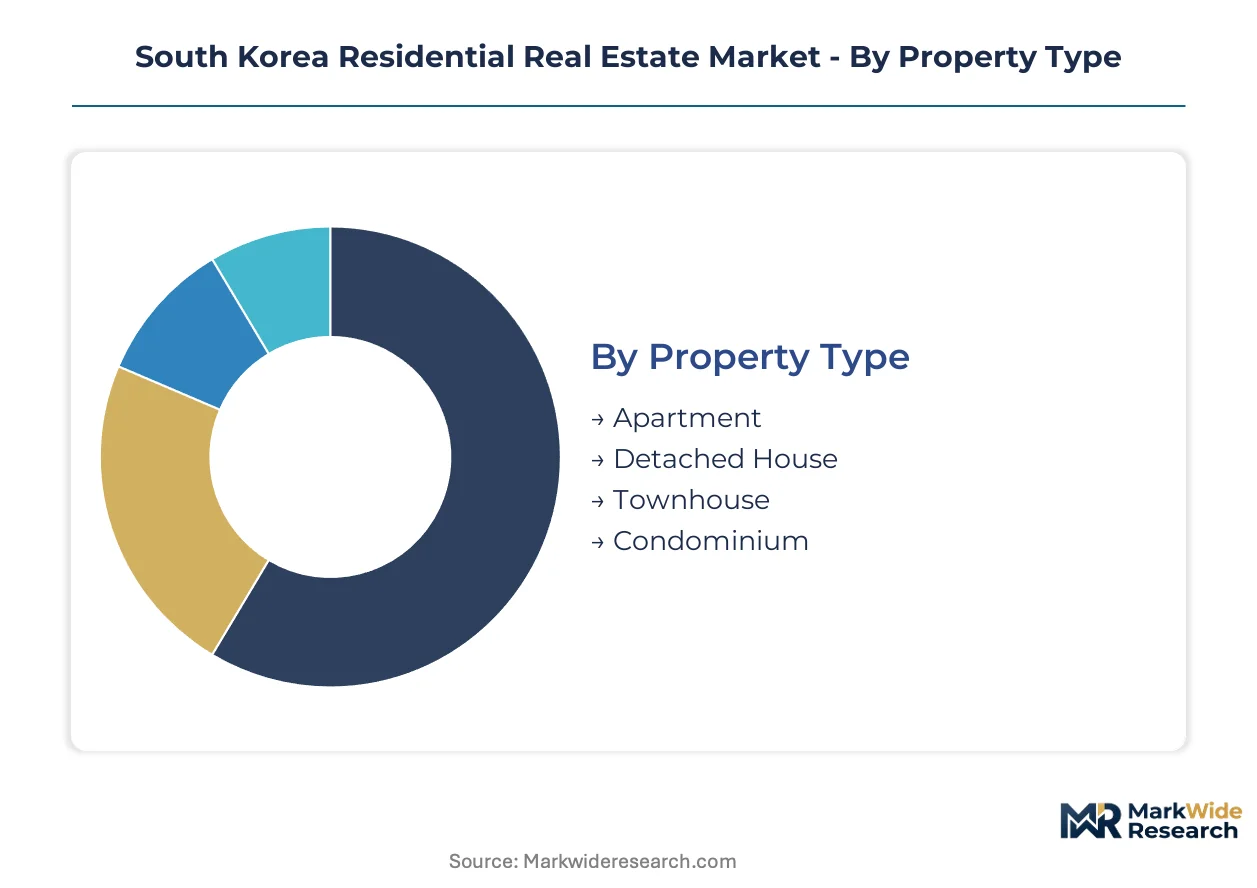
- Apartment:Reinforced concrete frame systems enable standardized vertical assembly above twenty stories, concentrating transaction volumes in Seoul's Gangnam corridor and Gyeonggi Province new town zones where young families cluster for transit access. MFDS fire-resistance mandates for high-rise towers accelerate non-combustible facade adoption, compressing margins for affordable-tier developers.
- Detached House:Low-density construction on greenbelt-adjacent parcels attracts retiree demand seeking privacy outside Seoul's urban containment boundary. Site acquisition premiums and restrictive zoning limit developer participation to luxury-focused operators with patient capital structures.
- Townhouse:Medium-density row housing in Suwon and Seongnam satellite cities bridges apartment efficiency with detached privacy for multi-child families. Modular bathroom pod integration accelerates construction timelines for mid-tier developers.
- Condominium:Strata-titled units in Busan's special district designation attract yield-seeking investors outside Seoul's saturated core. Individual ownership structures complicate maintenance fee enforcement compared to apartment association governance.
The dominant share belongs to Apartment, while Condominium is closing the gap fastest in secondary metropolitan zones.
Market Segment:
Cost tier stratification reflects how household leverage ceilings and price-ceiling regulations partition accessible inventory from premium assets.
- Luxury:Premium positioning in Seoul's Yeouido and Gangnam districts absorbs MFDS certification costs through unit pricing power. Foreign investor quotas and speculation zone cooling measures constrain transaction velocity despite persistent demand from high-net-worth domestic buyers.
- Mid-Range:Volume-standard construction targets price-tier migration for capital region workers in Gyeonggi Province infrastructure corridors. Digital mortgage pre-approval platforms channel Korea Land & Housing Corporation subsidized loans to eligible households, accelerating transaction velocity.
- Affordable:Public-sector supply dominates through Korea Land & Housing Corporation direct government funding, though persistent constraints outpace policy intervention in overheated districts. Greenbelt release limitations inflate land costs beyond mid-tier developer reach.
- Student Housing:Purpose-built rental assets in Daejeon and Daegu university corridors attract institutional capital seeking yield compression outside Seoul's core. Asset-backed securitization reconfigures capital access for specialized operators.
Mid-Range commands absolute transaction volume, though Student Housing is expanding most quickly as institutional deployment accelerates.
Buyer Profile:
Customer type distribution maps directly onto financing vehicle eligibility and household lifecycle positioning.
- First-Time Buyers:Government mortgage subsidies lower entry barriers, driving transaction volumes across Gyeonggi Province new town zones. Digital portal concentration reduces private lender origination share in entry-level price brackets.
- Investors:Yield compression strategies target Busan special districts and student housing corridors, with asset-backed securitization enabling portfolio-scale deployment. Speculation zone price ceilings suppress margin recovery in Gangnam corridor districts.
- Families:Young household demand concentrates in Seoul satellite city clusters seeking affordable unit entry points with transit connectivity. Floor-area ratio relaxations in designated new town zones accelerate site feasibility for developers.
- Retirees:Downsizing demand migrates toward low-density detached housing on greenbelt peripheries, constrained by limited developable land supply and extended MFDS material certification timelines.
First-Time Buyers anchor current transaction velocity, while Investors are gaining share fastest through securitization-enabled capital deployment.
Sales Channel:
Channel configuration reflects how technology convergence and regulatory transparency reshape transaction economics.
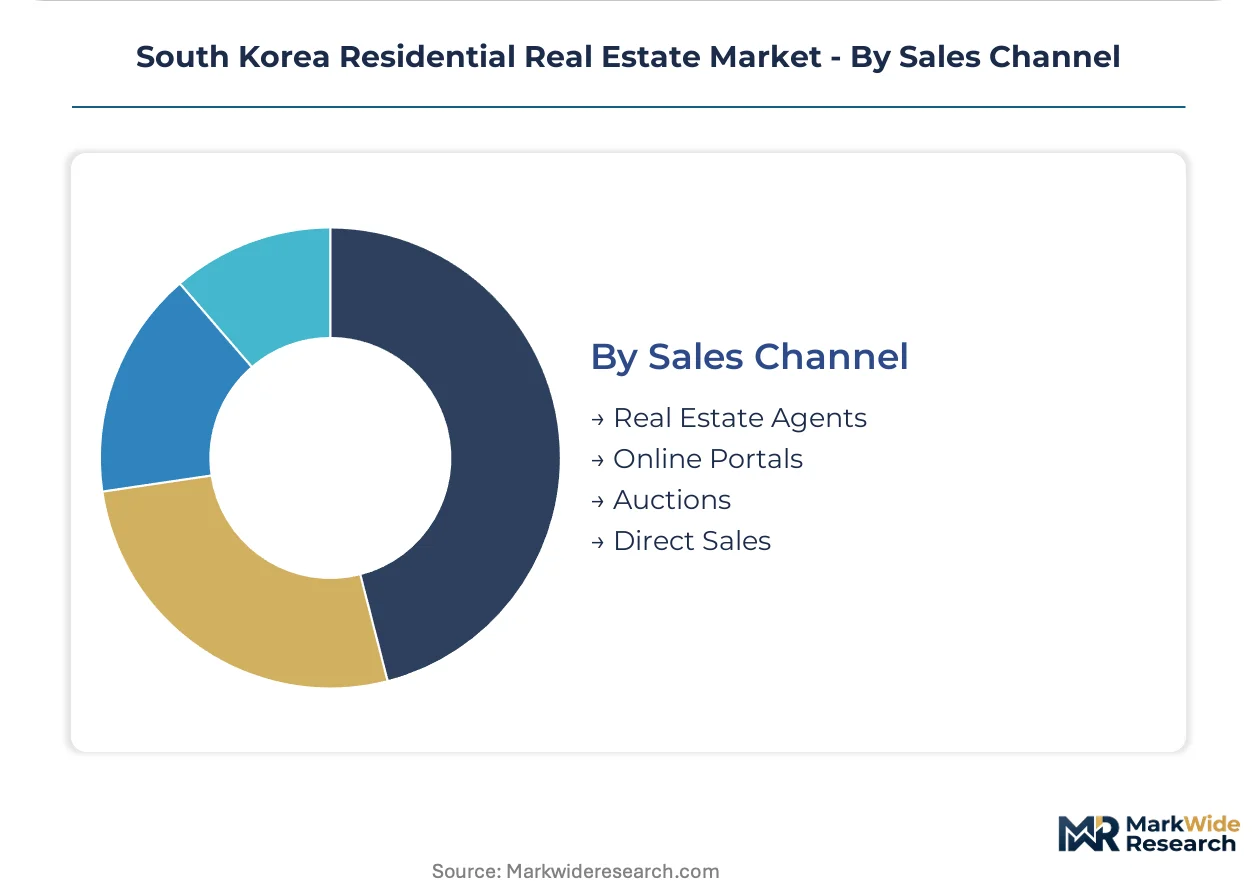
- Real Estate Agents:Traditional brokerage retains dominance in luxury segments requiring negotiation complexity and off-market inventory access. Commission structures compress as online portals displace intermediary functions in standardized transactions.
- Online Portals:Digital platforms aggregate inventory transparency across Gyeonggi Province new town zones, concentrating first-time buyer traffic. Korea Land & Housing Corporation's integrated portal channels direct subsidized loan access, reducing private lender engagement.
- Auctions:Judicial and distressed sales attract investor segments seeking below-market acquisition in overheated districts. Regulatory disclosure requirements limit information asymmetry advantages.
- Direct Sales:Developer-to-buyer transactions in pre-construction apartment projects bypass intermediary costs, with integrated construction-finance platforms enabling captive funding advantages for scale operators like Samsung C&T.
Real Estate Agents still handle the largest transaction value, yet Online Portals are climbing the fastest as digital mortgage pre-approval displaces branch-based processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS building material standards and Ministry of Land Infrastructure and Transport zoning enforcement channel development capital toward specific metropolitan corridors. These regulatory frameworks concentrate transaction velocity in government-designated growth zones while constraining supply in containment areas.
Seoul Capital Area
Gangnam corridor luxury demand and Gyeonggi Province new town zones attract young family inflows seeking transit-connected affordability. Speculation zone price ceilings suppress developer margins in overheated districts. Suwon and Seongnam satellite cities concentrate modular construction adoption for accelerated unit turnover.
Busan-Ulsan
Special district designation draws yield-seeking institutional capital outside Seoul's saturated core. Port-city industrial heritage supports workforce housing demand from manufacturing clusters. Haeundae and Centum City sub-markets attract condominium investors seeking strata-titled rental assets.
Daegu-Gyeongbuk
University corridor demand anchors purpose-built student housing deployment from institutional operators. Asset-backed securitization enables portfolio-scale capital access for specialized developers. Kookmin Bank mortgage regulation caps local household leverage, compressing price-tier migration capacity.
Daejeon-Sejong
Administrative capital relocation sustains public-sector employment housing demand. Korea Land & Housing Corporation direct funding dominates affordable supply in this corridor. Government complex proximity supports mid-range apartment pricing power against national trend lines.
Gwangju-Honam
Greenbelt release limitations constrain developable land supply across this southwestern zone. Legacy agricultural zoning fragments municipal density permissions. Smaller-scale developers compete through townhouse construction for multi-child families seeking space-cost balance.
South Korea Residential Real Estate Market Competitive Landscape
On the supply side, the industry is tiered between integrated construction-finance platforms, specialized engineering operators, and public-sector suppliers with direct government funding. Chaebol-affiliated developers leverage captive capital advantages for large-scale apartment complexes. Mid-tier specialists compete through modular construction adoption and regional market focus. Dominant competitive moves include integrated construction-finance platform expansion and asset-backed securitization structuring for institutional capital deployment.
Within the chaebol-affiliated tier, Samsung C&T and Hyundai Development Company exemplify scale-driven operators with integrated execution capabilities. DL E&C occupies a position among specialized engineering-focused developers competing through high-rise residential tower expertise. Korea Land & Housing Corporation anchors the public-sector supply archetype with direct government funding for affordable housing stock. These three represent distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Lotte Engineering & Construction |
| DL E&C |
| Hyundai Development Company |
| Posco E&C |
| Daewoo Engineering & Construction |
| Samsung C&T |
| Booyoung Group |
| Korea Land & Housing Corporation |
| GS Engineering & Construction |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Seoul's greenbelt-adjacent parcels drives site acquisition premiums beyond mid-tier developer reach, compressing margins while concentrating pricing power among chaebol-affiliated operators with captive capital structures. This utilization dynamic forces smaller developers toward Gyeonggi Province new town zones where floor-area ratio relaxations improve feasibility economics.
Pricing Analysis
MFDS fire-resistance certification tiers create the primary spread between luxury and affordable segments, with Yeouido and Gangnam developers absorbing compliance costs through unit pricing power while mid-range projects face margin compression from mandatory material upgrades. Three-tier pricing structure across premium, standard, and economy levels reflects household leverage ceilings imposed by Kookmin Bank mortgage regulation. Cost compression in affordable tiers is intensifying because greenbelt release limitations inflate land costs beyond developer reach. First-time buyers in Gyeonggi Province exhibit highest price sensitivity, while luxury segment purchasers demonstrate lowest elasticity due to foreign investor quotas and speculation zone cooling measures.
Supply Chain Analysis
Reinforced concrete feedstock supply draws from domestic cement producers and imported steel reinforcement, with prefabricated bathroom pod manufacturing clustering in Suwon and Seongnam industrial corridors. Standardized facade cladding systems and modular kitchen units represent critical component dependencies for accelerated construction timelines. Single-source vulnerability concentrates in MFDS-certified insulation material suppliers, where extended approval cycles delay project launches. Distribution runs through Korea Land & Housing Corporation's integrated portal for subsidized loan segments, while private developers rely on direct sales channels for pre-construction apartment projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's residential real estate market sits in early-cycle expansion as first-time buyer transaction volumes accelerate through government mortgage subsidies, with institutional capital deployment into student housing segments indicating yield compression opportunities ahead of broader market penetration.
For Market Incumbents: Harden market position through backward integration into prefabricated component manufacturing, securing captive supply of MFDS-certified facade systems against certification timeline delays. Expand capacity in Busan's special district designation ahead of regulatory tailwinds attracting yield-seeking capital, while consolidating channel control through integrated construction-finance platforms that reduce working capital pressure from extended material approval cycles. For New Entrants and Emerging Players: Build out specialized engineering capabilities in high-rise residential towers, targeting Daejeon and Daegu university corridors where purpose-built student housing demand outpaces institutional supply. Focus white-space capture on modular bathroom pod integration for mid-scale townhouse developments in Suwon and Seongnam satellite cities, leveraging direct sales channels to bypass established brokerage networks in standardized transactions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across asset-backed securitization structures as institutional underwriters concentrate risk exposure in student housing portfolios. Long-term viability over the next decade rests on identifying developers with patient capital structures capable of absorbing MFDS certification cost inflation in high-rise segments. Monitor Korea Land & Housing Corporation subsidy allocation shifts as the primary inflection signal for entry-level price bracket velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Construction-Finance Platform Expansion | Samsung C&T's captive funding advantages accelerate large-scale apartment complex delivery in Seoul satellite cities. |
| Modular Construction Adoption | Prefabricated bathroom pod integration compresses skilled-labor dependency for mid-tier developers in Gyeonggi Province. |
| Asset-Backed Securitization Structuring | Institutional capital deployment into student housing corridors enables portfolio-scale yield compression outside Seoul's core. |
| Busan Special District Development | Regulatory tailwinds attract condominium investment seeking strata-titled rental assets in Korea's second metropolitan zone. |
| Digital Mortgage Portal Integration | Korea Land & Housing Corporation's subsidized loan channel concentrates first-time buyer transaction velocity in government-backed vehicles. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with development executives at chaebol-affiliated and mid-tier construction firms, regulatory affairs specialists at the Ministry of Land Infrastructure and Transport, mortgage underwriting officers at Kookmin Bank, and institutional investment managers targeting residential yield compression; alongside secondary validation through MFDS building material certification databases, Korea Land & Housing Corporation subsidy allocation records, and municipal zoning enforcement filings across Seoul and Gyeonggi Province jurisdictions. Bottom-up unit economics triangulated against top-down capital flow estimates anchored the market sizing framework.
Forecast inputs spanning property type, market segment, buyer profile, and sales channel dimensions were modeled across the projection horizon, with CAGRs derived from regression analysis against household formation rates, mortgage origination velocity, and greenbelt release policy trajectories. Construction cost inflation indices and institutional capital deployment patterns into asset-backed securitization vehicles provided industry-specific forecast anchors for the residential development pipeline.
Stress conditions across MFDS certification timeline extensions, Kookmin Bank debt-service ratio adjustments, and greenbelt release policy reversals were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subsidy continuation and regulatory enforcement intensity, with speculative zone cooling measure expansion representing a specific risk factor that could revise trajectory. Cross-checking against Korea Appraisal Board transaction price benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
North America Real Estate Brokerage Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
France Condominiums and Apartments Market