
 Qatar Condominium and Apartment Market | 2026-2036
Qatar Condominium and Apartment Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Condominium and Apartment Market Analytics
Multi-source contractor engagement is rebalancing toward consolidated partnerships with pre-qualified developers as Qatar's residential pipeline matures. Qatari Diar Real Estate Company leverages its sovereign-linked project portfolio to dominate master-planned community delivery across Doha and Lusail. Mazaya Qatar sustains competitive positioning through mid-market product specialization that targets young professional households. Ezdan Holding Group anchors volume supply in affordable and mid-range inventory, operating one of the largest rental and sale portfolios in the country.
Qatar condominiums and apartments comprise individually owned residential units within multi-unit structures, typically constructed with reinforced concrete frames, thermal insulation systems, and smart building management interfaces serving owner-occupiers and rental investors. Luxury condominiums and executive suites command premium pricing in West Bay and The Pearl-Qatar, where scarcity of sea-view inventory protects margin pools. Studio apartments and affordable-tier units absorb the fastest turnover among expatriate arrivals and single-income professionals entering Qatar's services economy.
Qatar's Ministry of Municipality enforces building codes and green construction standards that elevate material specifications and energy performance thresholds for new residential approvals. The Qatar Central Bank regulates mortgage finance ratios and foreign ownership frameworks that shape investor eligibility and leverage capacity in the condominium segment. Stakeholders must monitor policy adjustments to expatriate residency permits and ownership zones, as these mechanisms determine addressable buyer pools and project feasibility timelines.
Market Dynamics
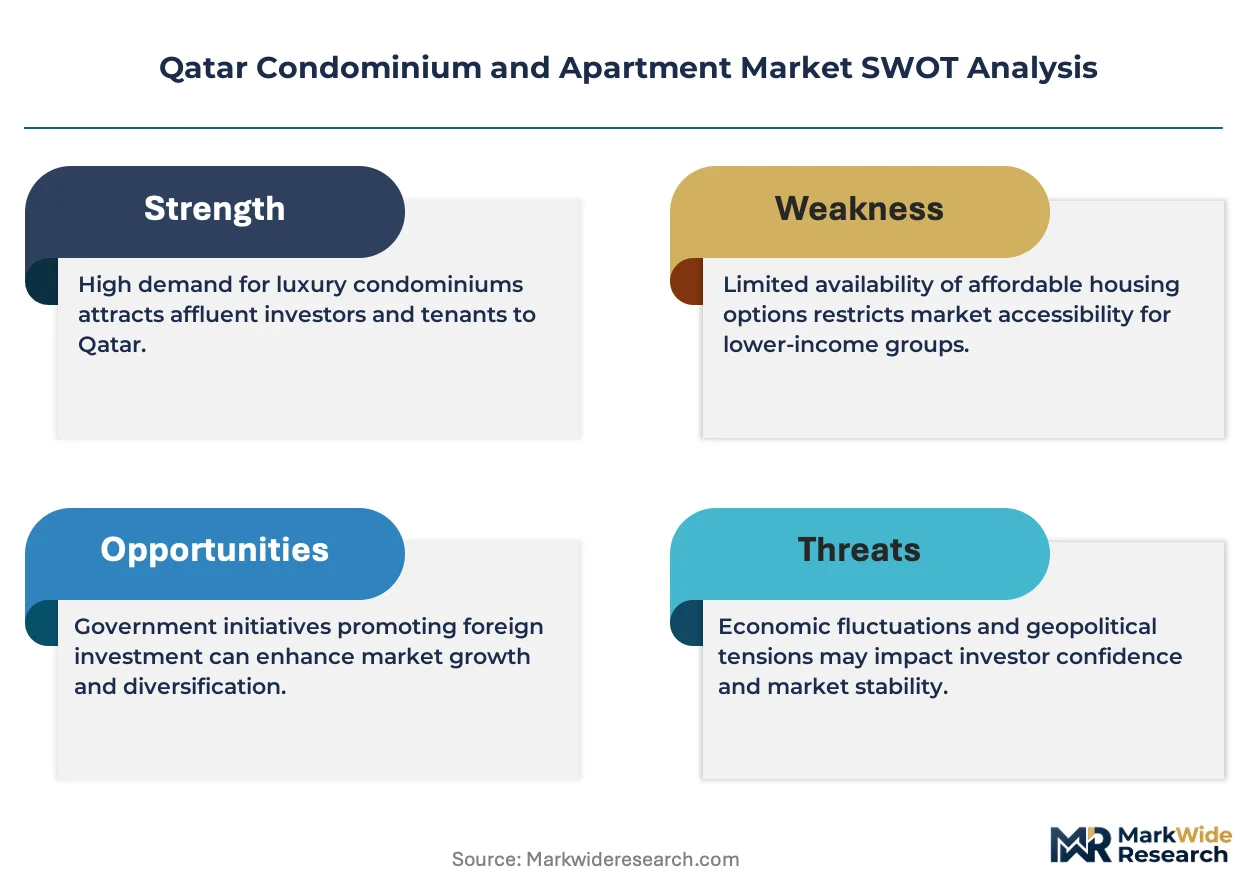
Qatar's Ministry of Municipality green certification mandates are compressing project approval timelines while elevating construction material specifications, forcing developers to pre-qualify suppliers and redesign thermal envelope systems before breaking ground.
Growth Catalysts
- Building Energy Code Enforcement:The Ministry of Municipality's updated thermal performance standards mandate double-glazed facades and high-efficiency HVAC systems, creating specification pull for advanced insulation materials and smart building management interfaces.
- Lusail City Infrastructure Completion:Waterfront district utilities and transit connectivity reaching operational status are unlocking absorption velocity for master-planned residential towers targeting institutional capital deployment.
- Expatriate Professional Inflows:Services sector expansion in Doha's West Bay corridor sustains studio and one-bedroom absorption rates among single-income households seeking proximity to employment clusters.
Market Restraints
- Construction Input Cost Volatility:Reinforced steel and aluminum facade system prices fluctuate with Gulf Cooperation Council import tariff adjustments, compressing developer margin projections on fixed-price contracts.
- Foreign Ownership Zone Restrictions:Qatar Central Bank eligibility frameworks limit condominium purchase rights to designated investment zones, constraining addressable buyer pools outside The Pearl-Qatar and Lusail City.
- Skilled Labor Supply Concentration:Specialist MEP contractors and certified energy auditors cluster with established master developers, leaving mid-tier projects facing procurement bottlenecks and timeline extensions.
Strategic Opportunities
- Integrated Lifestyle Service Layering:Developers embedding concierge platforms, co-working infrastructure, and wellness amenities within residential towers capture premium positioning against commodity apartment stock.
- Retrofit Certification Pathways:Existing building stock in Doha's older districts presents conversion potential as the Ministry of Municipality expands green building incentive programs to renovation permits.
- Institutional Rental Platform Structuring:Build-to-rent vehicles targeting sovereign wealth and pension fund capital are aggregating mid-market inventory for professionalized property management and yield optimization.
Industry Challenges
- Green Building Certification Timeline Compression:GSAS certification requirements add 4-6 months to design development phases, forcing developers to front-load consultant engagement and risk construction delays.
- Smart System Integration Complexity:IoT infrastructure, access control, and energy management platforms from disparate vendors create interoperability failures requiring costly mid-construction specification changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Condominium and Apartment Market |
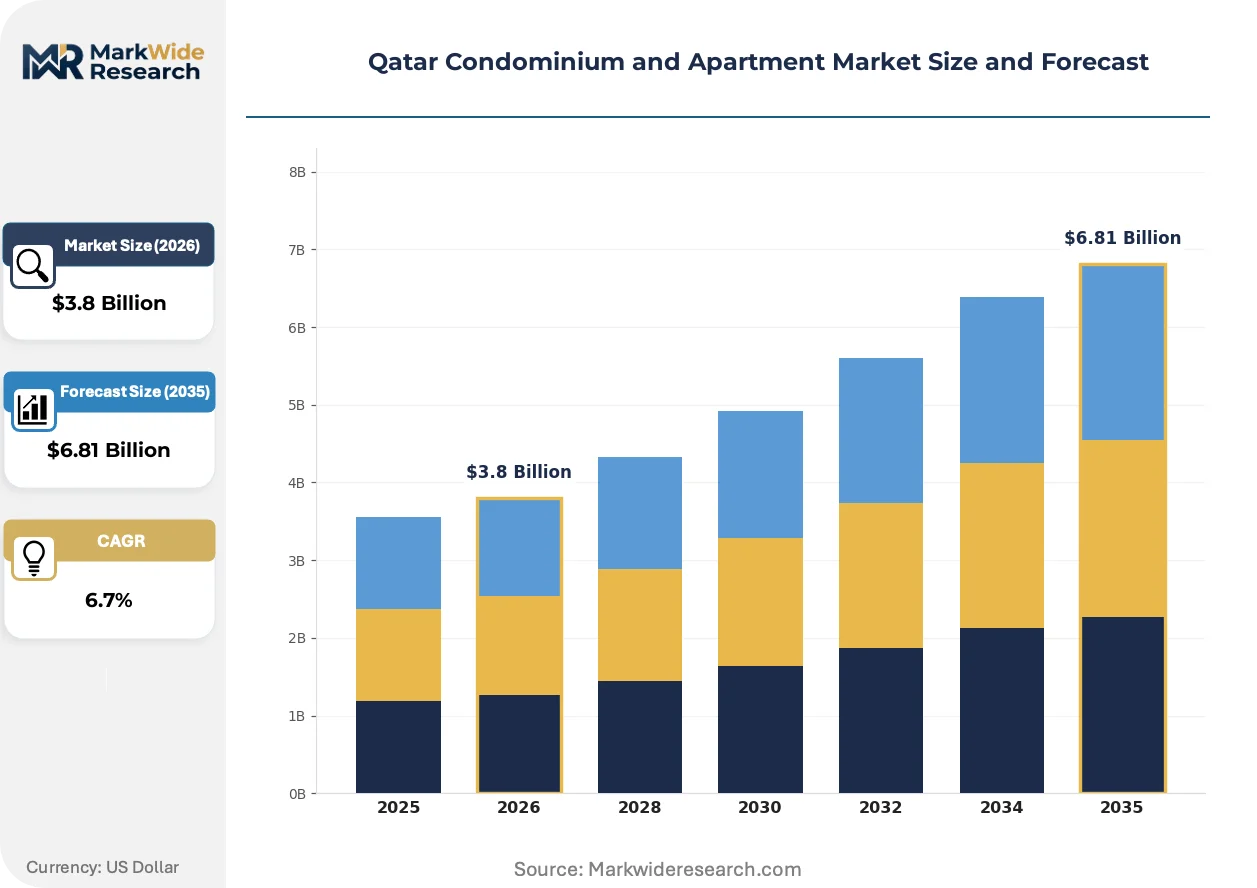
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Condominiums, Studio Apartments, Executive Suites, Serviced Apartments End User: Expatriates, Young Professionals, Families, Investors Distribution Channel: Direct Sales, Real Estate Agencies, Online Platforms, Auctions Price Tier: Affordable, Mid-Range, Premium, High-End |
| Companies Covered | Qatari Diar Real Estate Company, Mazaya Qatar, Ezdan Holding Group, Al Asmakh Real Estate Development, First Qatar, Barwa Real Estate, Al Mana Real Estate, Ansar Group of Companies, United Development Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Condominium and Apartment Market Evolving Landscape
Prefabrication and digital construction methods are compressing delivery schedules for Qatar's residential pipeline while elevating quality consistency. These shifts intersect with regulatory mandates and buyer preference evolution to reshape competitive positioning.
Cross-laminated timber and prefabricated bathroom pods are modularizing construction sequences for mid-rise residential towers. Developers targeting young professional segments in Lusail City are adopting these systems to accelerate envelope closure and reduce on-site labor dependency. The approach is modularizing traditional cast-in-place concrete workflows, compressing project timelines by 15-20 percent while standardizing finish quality across repetitive unit types.
Qatar Central Bank mortgage finance ratio adjustments are tightening leverage availability for foreign investors, redirecting capital toward cash-heavy institutional buyers. The policy shift favors sovereign-linked developers with balance sheet capacity to self-finance construction phases. Luxury inventory in West Bay and The Pearl-Qatar faces elongated absorption cycles as individual investor participation thins.
Buyer preference is rotating toward service-embedded rental contracts that bundle utilities, maintenance, and amenity access into single monthly payments. Young professional households in Doha's West Bay corridor are displacing traditional lease structures in favor of managed apartment operators offering flexibility and predictable cost exposure. This pattern concentrates in employment-proximate districts where turnover velocity supports operational scale.
Qatar Condominium and Apartment Market Segmentation
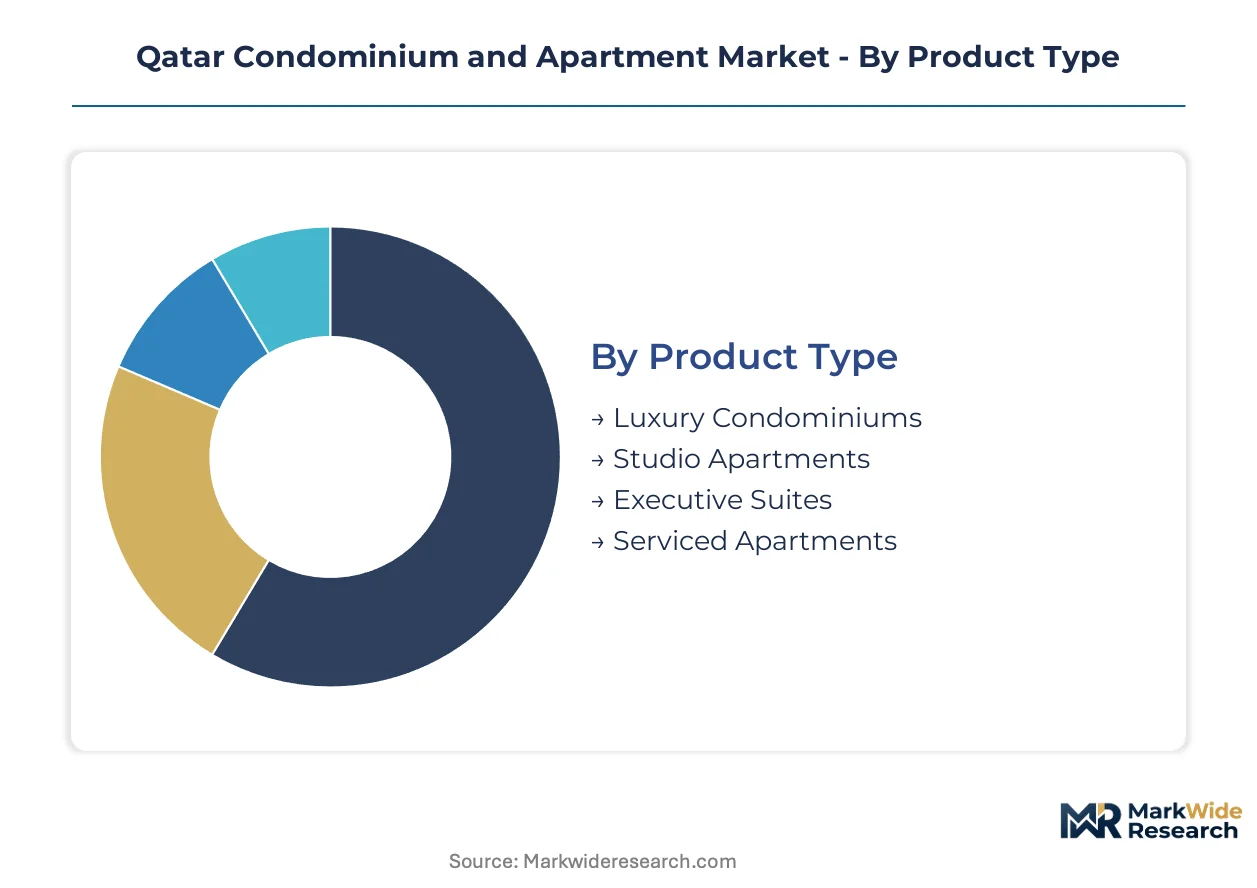
Segmentation in Qatar's residential market reveals how capital allocation, buyer eligibility, and distribution economics fragment addressable demand across distinct product tiers and customer profiles. Developers calibrate specifications, financing structures, and amenity bundles to match the purchasing constraints and lifestyle preferences of each identified pool.
Product Type:
Capital intensity escalates sharply with unit scale and finish grade, driving divergent financing strategies and partnership structures across the product spectrum.
- Luxury Condominiums:These units feature reinforced concrete superstructures with curtain-wall facades, smart home infrastructure, and GSAS-certified thermal systems. Demand clusters in West Bay and The Pearl-Qatar, where scarcity of sea-view inventory protects developer margins despite extended absorption timelines.
- Studio Apartments:Compact single-room layouts with integrated kitchenettes and space-efficient storage systems dominate entry-level supply. Expatriate arrivals in Doha's services economy absorb these units fastest, prioritizing employment proximity over living space.
- Executive Suites:Larger one-bedroom configurations with dedicated work zones and premium finishes target mid-level management assignees. Corporate relocation packages often subsidize lease rates in Lusail City's waterfront districts.
- Serviced Apartments:Fully managed units bundling housekeeping, concierge, and utility services into monthly contracts. Institutional operators are scaling this inventory to capture young professional preference for predictable cost exposure.
Studio apartments absorb the bulk of installed capacity; luxury condominiums are expanding most quickly as sovereign-linked developers front-load premium pipeline in Lusail City.
End User:
Buyer eligibility rules and residency permit frameworks segment demand into pools with radically different financing access and ownership rights.
- Expatriates:Non-Qatari residents face foreign ownership zone restrictions limiting purchase rights to The Pearl-Qatar and designated Lusail City districts. Rental absorption dominates this pool, with studio and one-bedroom units turning fastest.
- Young Professionals:Single-income households in Doha's West Bay corridor prioritize employment proximity and service-embedded rental contracts over ownership. This segment is displacing traditional lease structures in favor of managed apartment operators.
- Families:Multi-bedroom demand concentrates in master-planned communities with school access and recreational amenities. Qatari Diar's integrated developments capture this pool through bundled lifestyle offerings.
- Investors:Institutional capital from sovereign wealth and pension funds is aggregating mid-market inventory for build-to-rent platforms. Individual investor participation is thinning due to Qatar Central Bank mortgage ratio tightening.
Expatriate renters command the largest transaction volume; institutional investors are climbing the fastest as capital structures professionalize.
Distribution Channel:
Channel economics vary with buyer sophistication, transaction scale, and the regulatory burden of foreign ownership documentation.
- Direct Sales:Developer-led marketing through on-site showrooms and dedicated sales teams captures premium buyers seeking customization options. Sovereign-linked developers leverage direct channels to control pricing and buyer qualification.
- Real Estate Agencies:Broker networks dominate secondary market transactions and rental placements, earning commission spreads on lease renewals and resale activity. Established agencies cluster with master-planned community developers for exclusive listing rights.
- Online Platforms:Digital listing aggregators are gaining traction among young professional renters comparing inventory across employment-proximate districts. Virtual tour capabilities reduce physical viewing requirements for expatriate arrivals.
- Auctions:Distressed inventory and developer close-out units clear through auction channels, typically attracting cash-heavy local buyers circumventing mortgage finance constraints.
Real estate agencies handle the bulk of transaction flow; online platforms are gaining share fastest among digitally native buyer cohorts.
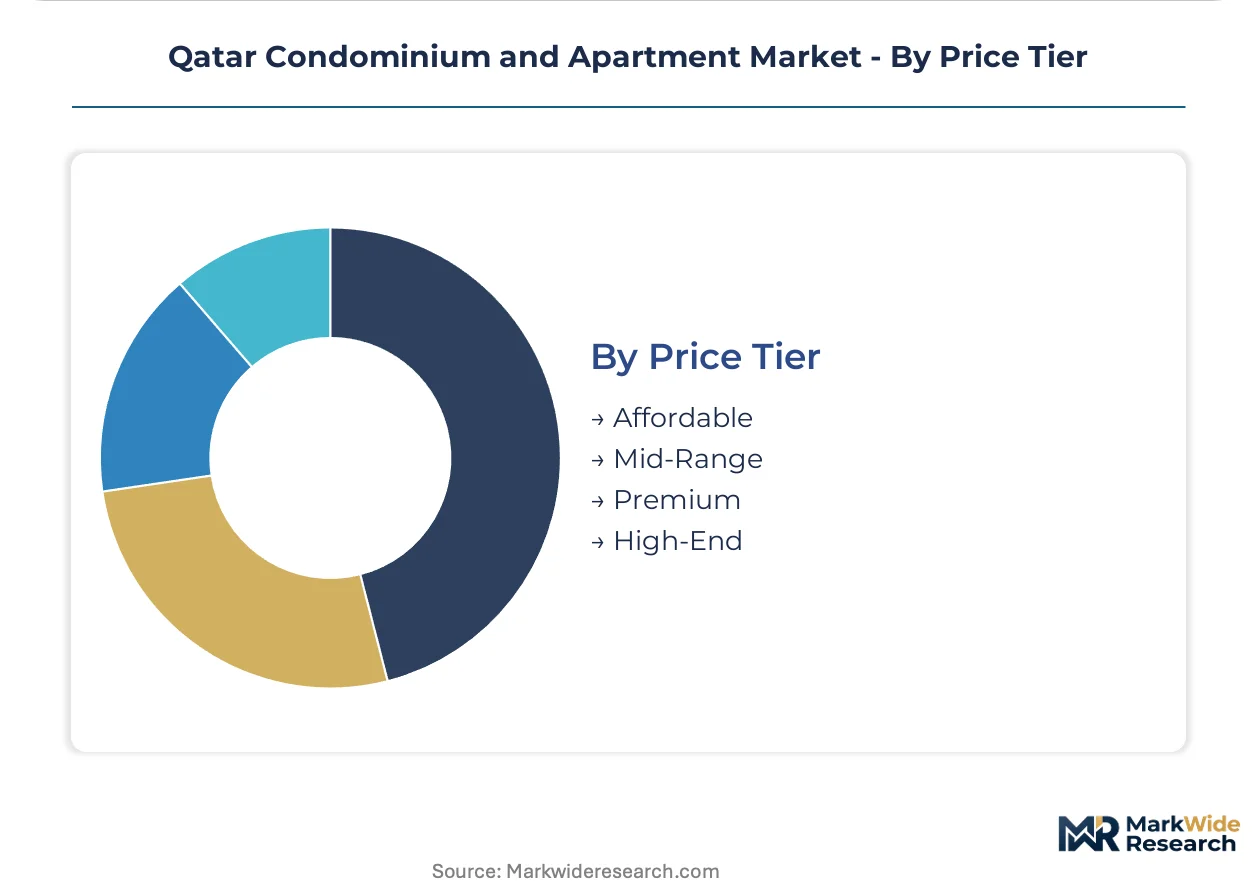
Price Tier:
Margin structure and construction specification intensity separate tiers with limited overlap in buyer pools or competitive positioning.
- Affordable:Basic reinforced concrete construction with standardized finishes and minimal amenity provision. Ezdan Holding Group anchors volume supply in this tier, operating rental portfolios targeting single-income households.
- Mid-Range:Enhanced thermal insulation, fitted kitchens, and limited smart building interfaces. Mazaya Qatar specializes here, capturing young professional households with location-efficient product in emerging districts.
- Premium:Double-glazed facades, integrated HVAC efficiency systems, and shared amenity access including fitness and co-working infrastructure. Lusail City's waterfront towers concentrate this inventory.
- High-End:Customizable layouts, concierge platforms, and GSAS Gold or Platinum certification. West Bay and The Pearl-Qatar scarcity dynamics protect pricing power despite elongated sales cycles.
Mid-range inventory absorbs the bulk of development pipeline; high-end units are climbing the fastest as green certification mandates elevate baseline specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Doha's West Bay corridor and Lusail City's waterfront districts, where expatriate professionals and institutional investors drive absorption. The Ministry of Municipality's green certification mandates are reshaping construction standards across all sub-regions. Master-planned communities anchor supply deployment in emerging districts.
West Bay
Expatriate professionals in financial services and energy sectors drive studio and one-bedroom absorption. The Ministry of Municipality enforces updated thermal performance standards for all new approvals. Luxury towers along the Corniche concentrate premium inventory with sea-view scarcity protecting developer margins.
Lusail City
Master-planned waterfront districts attract institutional capital and high-net-worth buyers seeking integrated lifestyle offerings. Green certification mandates from the Ministry of Municipality compress project timelines while elevating material specifications. The Marina and Entertainment City clusters concentrate high-end residential pipeline.
The Pearl-Qatar
Foreign ownership zone status enables non-Qatari purchase rights unavailable elsewhere. Qatar Central Bank mortgage frameworks shape investor eligibility and leverage capacity. Porto Arabia and Qanat Quartier sub-districts anchor luxury supply with scarcity dynamics supporting pricing power.
Al Wakrah
Affordable and mid-range inventory absorbs young professional households priced out of Doha core. Ezdan Holding Group anchors volume supply through rental portfolios targeting single-income residents. The municipality's infrastructure investments are unlocking absorption velocity in this emerging corridor.
Al Khor
Industrial zone proximity drives demand from energy sector workers seeking employment-proximate housing. Limited luxury supply creates pricing premiums for quality inventory. Barwa Real Estate maintains presence through workforce housing developments serving northern industrial clusters.
Qatar Condominium and Apartment Market Competitive Landscape
Consolidated partnerships with pre-qualified developers dominate the current landscape as Qatar's residential pipeline matures. Sovereign-linked entities leverage balance sheet capacity to self-finance construction phases, while mid-tier specialists target niche buyer segments. Three archetypes prevail: sovereign-backed master developers, mid-market product specialists, and volume-scale affordable providers. Strategic portfolio diversification and green certification pre-qualification constitute the dominant competitive moves.
Among sovereign-linked developers, Qatari Diar Real Estate Company exemplifies the master-planned community archetype through its integrated project portfolio across Doha and Lusail. Mazaya Qatar occupies a position within the mid-market specialization tier, targeting young professional households with location-efficient product. Ezdan Holding Group anchors the volume-scale affordable segment, operating one of the country's largest rental and sale portfolios.
| Leading Market Players |
|---|
| Qatari Diar Real Estate Company |
| Mazaya Qatar |
| Ezdan Holding Group |
| Al Asmakh Real Estate Development |
| First Qatar |
| Barwa Real Estate |
| Al Mana Real Estate |
| Ansar Group of Companies |
| United Development Company |
| Others |
Value Network & Pricing Analysis
Reinforced steel and aluminum facade system costs cascade through Qatar's residential construction tiers, with Gulf Cooperation Council import tariff adjustments compressing developer margins on fixed-price contracts while elevating baseline specifications for green-certified inventory. The Ministry of Municipality's thermal performance mandates force pre-qualification of premium material suppliers, concentrating procurement power with sovereign-linked developers who self-finance construction phases.
Pricing Analysis
Volume-scale affordable inventory absorbs the bulk of transaction flow while high-end units command extended absorption cycles with protected margins. Three-tier pricing structure across premium, mid-range, and affordable levels stratifies by GSAS certification grade and sea-view scarcity, with West Bay and The Pearl-Qatar inventory pricing off architectural differentiation. Cost compression in mid-range tiers is intensifying because Mazaya Qatar and similar specialists compete on location efficiency. Expatriate renters in studio and one-bedroom units exhibit highest price sensitivity; institutional investors deploying build-to-rent capital show lowest sensitivity, prioritizing yield stability over entry pricing.
Supply Chain Analysis
Specialist MEP contractors and certified energy auditors concentrate with established master developers in Qatar, leaving mid-tier projects facing procurement bottlenecks and timeline extensions. Raw material inputs draw from UAE for aluminum facade systems, Saudi Arabia for cement and aggregates, and East Asia for smart building management interfaces. Single-source vulnerability runs through GSAS-certified insulation material suppliers pre-qualified by the Ministry of Municipality. Distribution runs through consolidated partnerships with pre-qualified developers as the residential pipeline matures, with direct sales channels capturing premium buyer customization demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's condominium market is becoming a vertical-integration race as developers pursue captive control over GSAS-certified material supply chains to defend margin pools against input cost volatility. Sovereign-linked players are extending upstream into pre-qualified supplier networks to compress procurement timelines.
For Market Incumbents: Acquire GSAS-certified insulation and smart building interface suppliers to secure priority allocation during material shortages. Sovereign-linked developers like Qatari Diar should consolidate exclusive partnerships with thermal envelope specialists to preempt mid-tier competitors from accessing certified inputs. This defensive positioning counters the threat of procurement bottlenecks that delay project approvals under Ministry of Municipality timelines.
For New Entrants and Emerging Players: Young professional households seeking service-embedded rental contracts represent the most penetrable buyer archetype currently underserved by traditional lease structures. New entrants should target Lusail City's emerging districts outside the Marina cluster, where land costs permit competitive positioning against established master-planned communities. A build-to-rent platform bundling utilities, maintenance, and amenity access into single monthly payments offers the strongest go-to-market angle.
For Investors and Strategic Acquirers: Qatar Central Bank mortgage ratio adjustments tightening foreign investor leverage is the leading indicator that institutional capital will dominate future absorption. Long-term viability over a multi-year window rests on exposure to sovereign-linked developers with balance sheet capacity to self-finance construction phases. Acquisition targets should feature build-to-rent vehicles with professionalized property management infrastructure. The signal to monitor is Ministry of Municipality expansion of green building incentive programs to renovation permits, which would unlock conversion value in Doha's older districts.
| Strategic Initiative | Industry Significance |
|---|---|
| GSAS Certification Pre-Qualification | Ministry of Municipality mandates compress approval timelines, privileging developers with established consultant relationships. |
| Backward Integration into Certified Materials | Captive supply of thermal insulation and smart interfaces defends margins against GCC import tariff volatility. |
| Build-to-Rent Platform Structuring | Sovereign wealth and pension fund capital aggregation professionalizes yield optimization in mid-market inventory. |
| Service-Embedded Contract Layering | Concierge platforms and co-working infrastructure capture young professional preference for predictable cost exposure. |
| Retrofit Certification Pathway Development | Green building incentive program expansion to renovation permits unlocks conversion potential in Doha's older districts. |
Research Methodology
Multi-period observation of construction permit approvals, GSAS certification timelines, and expatriate residency permit frameworks anchored the trend analysis, supplemented by interviews with project development executives at sovereign-linked developers, procurement leads at mid-tier construction firms, Ministry of Municipality regulatory affairs officers, and portfolio managers at institutional real estate investment vehicles. Secondary validation drew from Qatar Central Bank mortgage finance circulars, Ministry of Municipality building code amendments, Lusail City infrastructure completion disclosures, and customs data on GCC construction material imports. Bottom-up unit absorption tracking across West Bay, Lusail City, and The Pearl-Qatar sub-regions was triangulated against top-down pipeline value estimates.
Segment-weighting across product type, end user, distribution channel, and price tier dimensions shaped the analytical framework, with luxury condominium, studio apartment, executive suite, and serviced apartment categories modeled separately. Expatriate, young professional, family, and investor end-user pools were assigned differential absorption velocities based on Qatar Central Bank eligibility frameworks and employment sector expansion patterns. CAGRs were derived from trend extrapolation of permit approval volumes and institutional capital deployment flows, with cross-validation against master-planned community completion schedules and green certification timeline benchmarks.
Revisions become necessary when Ministry of Municipality adjusts thermal performance standards, Qatar Central Bank modifies foreign ownership zone frameworks, or GCC import tariff structures shift materially. Forecasts reflect assumptions about continued expatriate professional inflows and Lusail City infrastructure completion trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market