
 Indonesia Real Estate Market | 2026-2036
Indonesia Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Real Estate Market Insights
Modular township bundling—where residential clusters integrate retail, logistics, and co-working nodes in single master plans—is hardening as the dominant product configuration across Indonesian urban developments. Sinar Mas Land leverages its integrated township model in BSD City to sustain recurring revenue streams from commercial tenants. PT Ciputra Development Tbk anchors its competitive position through specialized healthcare-education precincts that differentiate it from conventional residential developers.
Indonesia real estate encompasses land and permanent structures developed for residential habitation, commercial activity, or industrial operations, typically engineered with seismic-resistant reinforced concrete frames and tropical climate ventilation systems to ensure structural integrity and occupant comfort across the archipelago's high-humidity, earthquake-prone environment. Residential property leads transaction volume nationally, while industrial logistics parks represent the fastest-growing margin pool as e-commerce fulfillment demand reshapes warehousing specifications. REITs remain underdeveloped relative to regional peers, though regulatory easing signals expansion potential for institutional capital participation.
Indonesia's Ministry of Public Works and Housing enforces building codes through SNI standards, while the Financial Services Authority regulates REIT frameworks and developer financing disclosures to protect retail investors. The Omnibus Law on Job Creation streamlined land acquisition permits, accelerating project timelines for developers navigating previously fragmented provincial approval chains. Stakeholders must monitor Nusantara capital relocation timelines and subsequent infrastructure commitment levels to calibrate portfolio exposure between established Jakarta-Surabaya corridors and emerging eastern Indonesian demand centers.
Market Dynamics
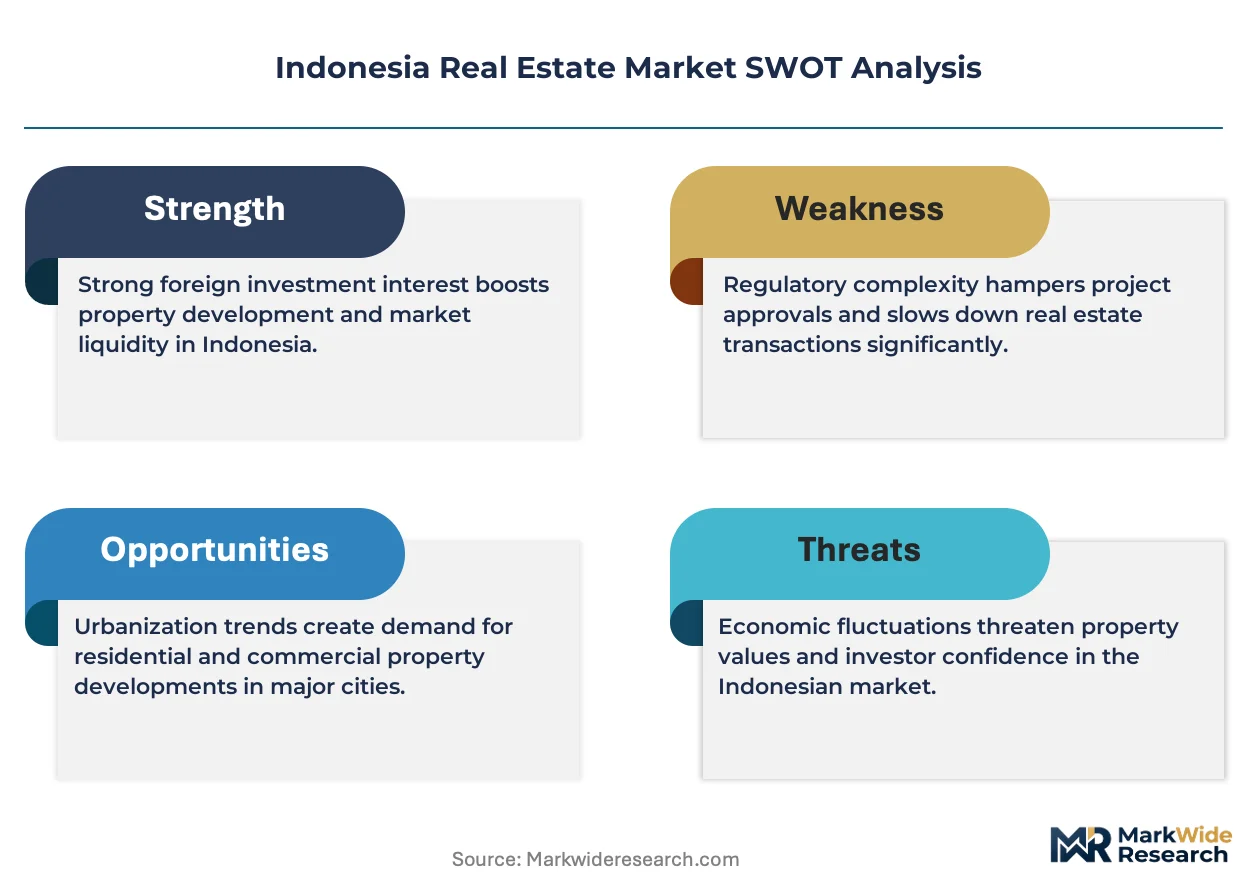
The Indonesia Real Estate Market is undergoing structural compression as the Ministry of Public Works and Housing tightens SNI energy efficiency mandates while e-commerce fulfillment demand reshapes industrial land use priorities. Developers now face simultaneous pressure to decarbonize existing stock and reposition portfolios toward logistics-capable assets.
Growth Catalysts
- Omnibus Law on Job Creation:Streamlined land acquisition permits collapsed approval timelines from fragmented provincial chains into centralized processes. Developers report faster project mobilization across Java and Sumatra.
- E-commerce fulfillment infrastructure:Last-mile warehousing specifications now dominate industrial park design. Logistics operators demand higher ceiling clearances and automated loading docks.
- Nusantara capital relocation:Government infrastructure commitments are pulling residential and commercial pipelines eastward. Eastern Kalimantan land values respond to administrative demand signals.
Market Restraints
- Reinforced concrete input volatility:Seismic-grade steel and cement prices fluctuate with energy costs. Construction margins compress when commodity cycles spike.
- Land banking concentration:Legacy holdings cluster in Jakarta-Surabaya corridors. Developers lacking eastern exposure face pipeline gaps as demand rotates.
- REIT regulatory immaturity:Financial Services Authority frameworks lag regional peers. Institutional capital participation remains structurally capped.
Strategic Opportunities
- Smart building technology convergence:IoT sensors and building management systems merge with solar PV installations. Ministry mandates create compliance-driven retrofit demand.
- Healthcare-education precincts:Specialized mixed-use configurations attract stable tenant bases. Demographic aging and middle-class expansion support recurring revenue models.
- Modular township bundling:Residential clusters integrating retail, logistics, and co-working nodes reduce tenant leakage. Master-planned environments capture spending within walled ecosystems.
Industry Challenges
- Green building certification timelines:SNI compliance documentation delays project launches. Developers struggle to synchronize construction schedules with verification cycles.
- Seismic engineering talent scarcity:Specialized structural designers command premium compensation. Firms compete for limited expertise in tropical climate ventilation and earthquake-resistant framing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Real Estate Market |
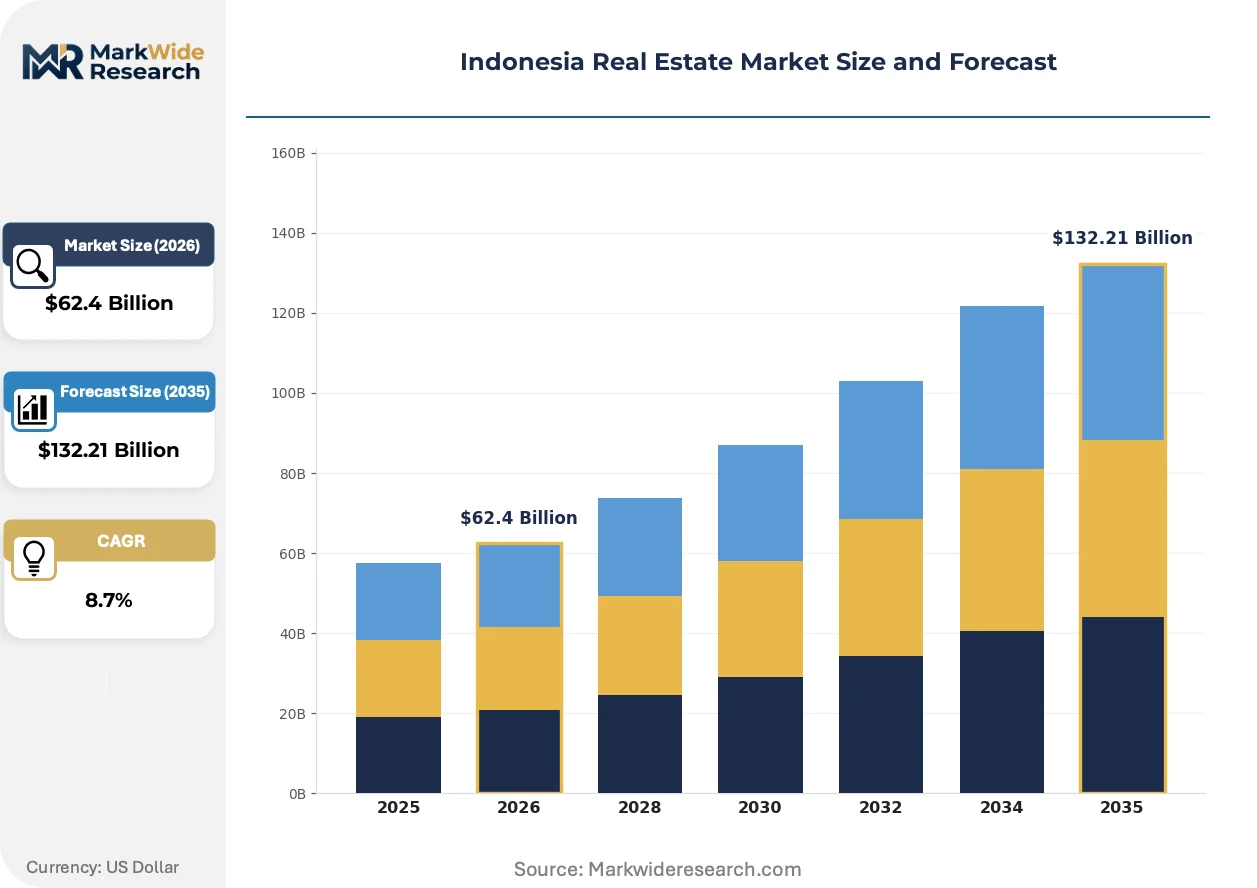
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Residential, Commercial, Industrial, Mixed-Use Investment Type: Direct Ownership, REITs, Crowdfunding, Joint Ventures Target Customer: First-Time Buyers, Investors, Corporates, Developers Sales Channel: Online Platforms, Real Estate Agents, Auctions, Direct Sales |
| Companies Covered | Sinar Mas Land, PT Lippo Karawaci Tbk, PT Ciputra Development Tbk, PT Agung Podomoro Land Tbk, PT Pakuwon Jati Tbk, PT Summarecon Agung Tbk, PT Alam Sutera Realty Tbk, PT Intiland Development Tbk, PT Jababeka Tbk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Real Estate Market Trends and Innovations
Digital infrastructure and regulatory pressure are converging to redefine asset specifications across Indonesian property development. Three distinct vectors are compressing traditional development cycles and altering competitive positioning.
Prefabricated structural components are modularizing construction workflows for mid-rise residential and commercial projects. Large developers now specify factory-cast floor plates and wall panels to compress on-site assembly duration. This shift is modularizing project delivery timelines from 24-month cycles toward 16-month completions.
The Ministry of Public Works and Housing is enforcing SNI 03-6389-2011 energy efficiency standards through mandatory building envelope performance audits. New commercial permits require documented thermal resistance values and mechanical system efficiency ratings. Industrial logistics facilities face the tightest compliance windows as warehousing energy loads trigger intensive HVAC scrutiny.
Corporate tenants now bundle lease negotiations with sustainability performance guarantees rather than accepting standard gross rent structures. Facility managers demand real-time energy dashboards and carbon reporting infrastructure as contract inclusions. This preference shift concentrates in Jakarta CBD towers where multinational occupiers anchor Class A absorption.
Indonesia Real Estate Market Segmentation
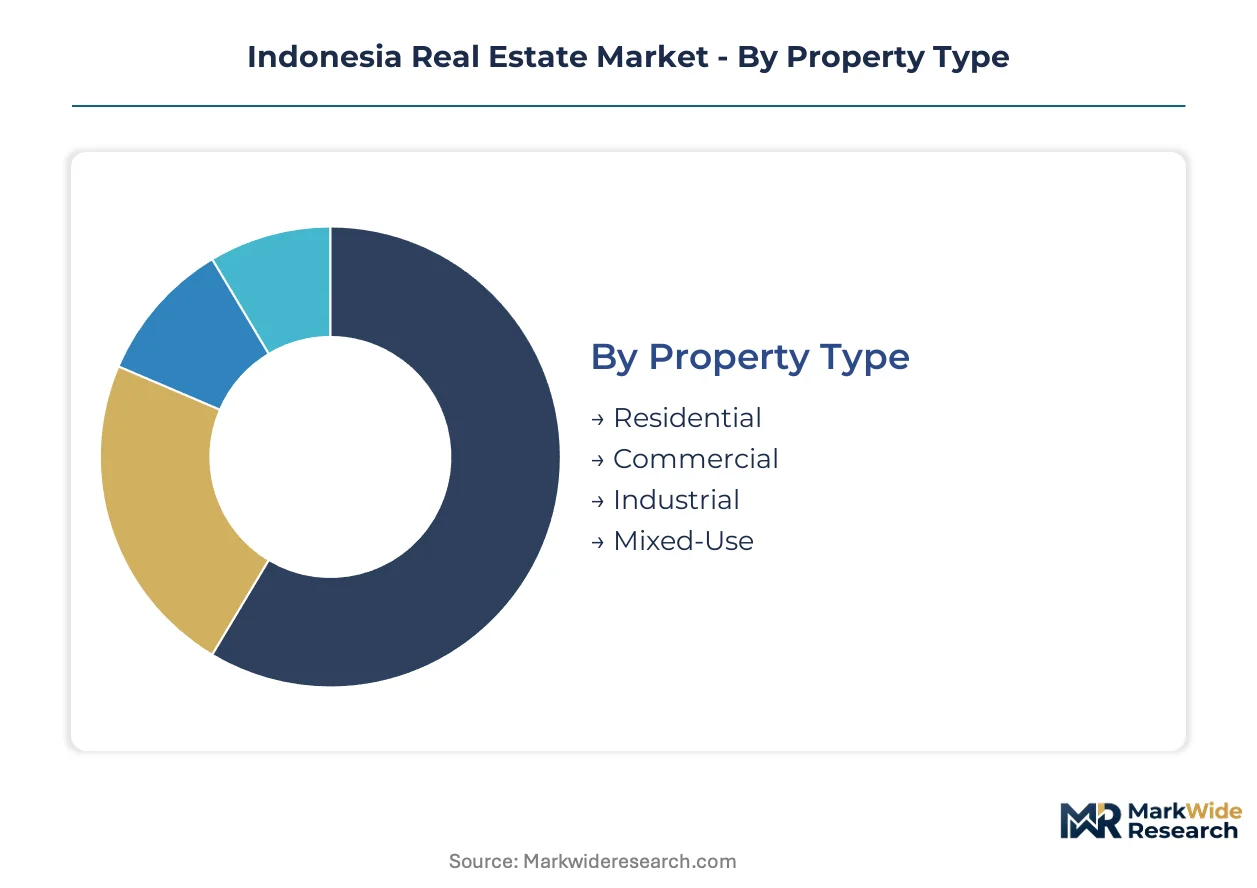
Indonesian real estate buyers fragment sharply by capital deployment horizons and risk tolerance. Developers calibrate product specifications, financing structures, and sales channel intensity to match these divergent buyer profiles across Jakarta-Surabaya corridors and emerging eastern markets.
Property Type:
Cost tiers separate buyers in this category, with entry thresholds and operating expense burdens determining portfolio allocation strategies.
- Residential:Seismic-resistant reinforced concrete frames with tropical ventilation systems dominate construction specifications. First-time buyers in Greater Jakarta and Surabaya drive transaction volume, though land banking scarcity in established corridors constrains affordable supply pipelines.
- Industrial:Logistics-capable assets with higher ceiling clearances and automated loading docks capture e-commerce fulfillment demand. Eastern Kalimantan land values respond to Nusantara infrastructure commitments as operators reposition toward government administrative demand centers.
- Commercial:Class A towers in Jakarta CBD integrate real-time energy dashboards and carbon reporting infrastructure to satisfy multinational tenant sustainability requirements. Ministry of Public Works and Housing SNI energy efficiency mandates tighten building envelope performance standards.
- Mixed-Use:Master-planned environments bundling residential clusters with retail, logistics, and co-working nodes reduce tenant leakage. BSD City and comparable township developments capture recurring revenue from commercial tenants within walled ecosystems.
Volume sits with Residential; growth tilts toward Industrial.
Investment Type:
Capital source maturity distinguishes participants, from retail investors seeking fractional exposure to institutional funds demanding governance infrastructure.
- Direct Ownership:Individual and family office capital deploys through outright land or building acquisition. High-net-worth investors concentrate in Jakarta-Surabaya premium residential and commercial assets, absorbing title transfer complexity in exchange for control.
- REITs:Financial Services Authority regulatory frameworks lag regional peers, capping institutional participation. Regulatory easing signals expansion potential for retail investor access to diversified property portfolios with professional management.
- Joint Ventures:Developer-landowner partnerships split construction expertise against land contribution, accelerating project mobilization under Omnibus Law streamlined permitting. Structure dominates greenfield township developments where legacy landholders lack development capability.
- Crowdfunding:Digital platforms fractionalize residential and commercial exposure for retail capital pools below direct ownership thresholds. Regulatory clarity remains incomplete as the Financial Services Authority evaluates investor protection frameworks.
Direct Ownership commands current capital deployment; Joint Ventures are expanding most quickly as developers secure eastern land positions.
Target Customer:
Decision velocity and information access separate buyers, from lengthy mortgage-approval cycles to rapid corporate facility decisions.
- First-Time Buyers:Price-sensitive entrants navigate subsidized mortgage schemes and developer payment plans. Concentration in Greater Jakarta peripheral zones where land costs permit entry-level product pricing.
- Corporates:Multinational occupiers anchor Class A absorption with bundled lease negotiations incorporating sustainability performance guarantees. Facility managers demand documented thermal resistance values and mechanical system efficiency ratings as contract inclusions.
- Investors:Yield-focused buyers evaluate rental income stability against capital appreciation in secondary locations. Healthcare-education precincts attract this segment for tenant base stability amid demographic aging.
- Developers:Professional capital recycles through project-specific vehicles, with Sinar Mas Land and PT Ciputra Development Tbk leveraging integrated township models to sustain recurring revenue streams.
Corporates dominate Jakarta CBD absorption; First-Time Buyers are gaining share fastest in peripheral corridors.
Sales Channel:
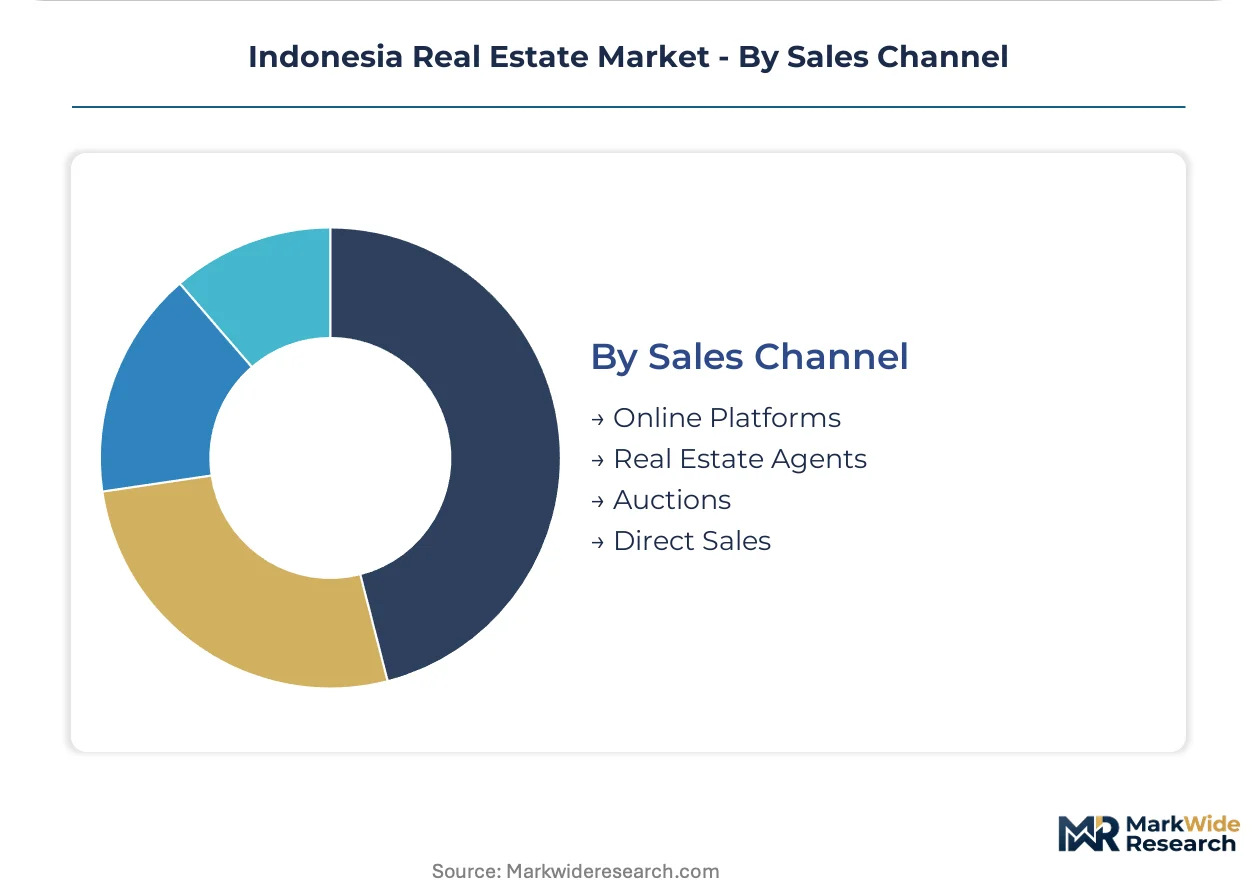
Transaction size and buyer sophistication determine channel selection, from algorithmic property matching to relationship-driven institutional negotiations.
- Real Estate Agents:Commission-based intermediaries dominate residential transactions, providing neighborhood expertise and mortgage facilitation. Networks concentrate in established Jakarta-Surabaya submarkets with liquid resale activity.
- Online Platforms:Digital listing aggregators compress search costs for standardized residential inventory. E-commerce fulfillment infrastructure demand is pulling platform development toward industrial logistics property databases.
- Direct Sales:Developer-controlled channels capture margin on pre-construction residential and commercial inventory. Marketing investment concentrates in integrated township launches where master-plan visualization drives commitment.
- Auctions:Distressed and foreclosure inventory clears through court-supervised processes, attracting investor buyers with liquidity and legal tolerance. Volume remains thin relative to negotiated transactions.
Real Estate Agents transact the most units; Online Platforms show the steepest expansion trajectory as logistics property data demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kawasan Ekonomi Khusus (KEK) incentives are concentrating industrial real estate development in designated zones across Java and Sumatra. The Ministry of Public Works and Housing channels infrastructure investment toward these corridors. Developers calibrate land banking strategies between established demand centers and emerging eastern growth poles.
Greater Jakarta
Corporate occupiers and first-time buyers dominate absorption in the capital region. The Ministry of Public Works and Housing enforces SNI energy efficiency standards through mandatory building envelope audits. Tangerang and Bekasi submarkets concentrate logistics-capable industrial parks serving e-commerce fulfillment networks.
Surabaya
East Java's manufacturing base sustains demand for integrated township developments with industrial components. The Omnibus Law on Job Creation accelerated land acquisition permits in surrounding Sidoarjo and Gresik regencies. Surabaya's port infrastructure anchors warehousing clusters targeting domestic distribution and export-oriented manufacturing.
Eastern Kalimantan
Nusantara capital relocation is pulling administrative and residential demand eastward. Government infrastructure commitments include transport corridors linking the new capital zone to Balikpapan and Samarinda. Land values in the Nusantara periphery respond to speculative positioning ahead of civil service migration timelines.
Medan
North Sumatra's position as a gateway to the Malacca Strait sustains industrial logistics interest. The Financial Services Authority regulates developer financing disclosures affecting project-scale capital formation. Deli Serdang regency concentrates new warehousing specifications targeting cross-border trade facilitation.
Makassar
Eastern Indonesia's largest metro anchors commercial and residential pipelines serving Sulawesi and Papua hinterlands. Provincial approval chains under the Omnibus Law streamlined permits for mixed-use developments. The Tanjung Bunga corridor concentrates premium residential projects targeting returning diaspora capital.
Indonesia Real Estate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Indonesia's real estate sector. The market structure tilts toward integrated township developers with captive land banks and recurring commercial revenue streams. Three archetypes dominate: diversified conglomerates with multi-sector holdings, pure-play residential specialists, and industrial logistics operators. Competitive moves concentrate on land banking expansion in eastern growth corridors and smart building technology integration to meet tightening SNI compliance windows.
Within the integrated township tier, Sinar Mas Land exemplifies the diversified conglomerate model through its BSD City development, while PT Ciputra Development Tbk occupies a position emphasizing specialized healthcare-education precincts. PT Lippo Karawaci Tbk represents the scale-driven approach to master-planned community development. These developers anchor competitive positioning through differentiated product configurations rather than commodity residential offerings.
| Leading Market Players |
|---|
| Sinar Mas Land |
| PT Lippo Karawaci Tbk |
| PT Ciputra Development Tbk |
| PT Agung Podomoro Land Tbk |
| PT Pakuwon Jati Tbk |
| PT Summarecon Agung Tbk |
| PT Alam Sutera Realty Tbk |
| PT Intiland Development Tbk |
| PT Jababeka Tbk |
| Others |
Pricing and Supply Chain Analysis
Smart building certification tiers split the commercial market into three performance bands that command divergent rental premiums and require distinct procurement strategies. Premium-grade assets with integrated IoT sensors and solar PV arrays source specialized components through limited supplier channels, while standard-grade stock competes on construction cost minimization through bulk material aggregation.
Pricing Analysis
Short lead-time premiums dominate Jakarta CBD Class A towers where multinational tenants demand immediate occupancy with sustainability performance guarantees. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and energy dashboard inclusion. Price differentiation stems from SNI compliance documentation completeness and mechanical system efficiency ratings. Cost compression in economy-tier peripheral residential is intensifying because first-time buyers negotiate aggressively on pre-construction payment plans.
Supply Chain Analysis
Freight costs from China, South Korea, and Japan determine landed prices for seismic-grade steel and automated loading dock systems. Raw material dependencies center on cement clinker, reinforced concrete additives, and HVAC control modules. Single-source vulnerability concentrates in specialized seismic engineering components where Japanese suppliers dominate. Distribution runs through developer-controlled procurement divisions that aggregate volume across multiple township projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesian real estate is transitioning from conventional reinforced concrete construction to prefabricated modular systems that compress project delivery timelines. Smart building management platforms are displacing legacy manual controls as Ministry of Public Works and Housing mandates tighten.
For Market Incumbents: Deepen captive land banking in Eastern Kalimantan ahead of Nusantara infrastructure commitment acceleration. Secure backward integration into prefabricated component manufacturing to defend margins against commodity steel price volatility. Incumbent township developers face displacement risk from modular construction specialists with faster assembly cycles. For New Entrants and Emerging Players: First-time buyers in Greater Jakarta peripheral zones present the most penetrable entry point given land cost advantages and subsidized mortgage scheme access. White-space opportunities sit in healthcare-education precincts where specialized mixed-use configurations attract stable tenant bases. Go-to-market positioning should emphasize Omnibus Law permitting expertise to accelerate project mobilization against legacy developers. For Investors and Strategic Acquirers: Re-rating potential sits with industrial logistics operators given e-commerce fulfillment infrastructure demand reshaping warehousing specifications. Long-term viability favors assets with Nusantara corridor exposure and SNI pre-certification documentation. Watch Nusantara civil service migration timelines as the inflection indicator for eastern land value appreciation.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building Technology Integration | IoT sensor deployment satisfies Ministry SNI energy efficiency audit requirements for commercial permits. |
| Eastern Land Banking Expansion | Nusantara corridor positioning captures administrative demand from government capital relocation. |
| Prefabricated Component Manufacturing | Factory-cast floor plates compress on-site assembly duration from 24-month toward 16-month cycles. |
| Healthcare-Education Precinct Development | Specialized mixed-use configurations attract stable tenant bases amid demographic aging trends. |
| Logistics-Capable Industrial Park Buildout | Higher ceiling clearances and automated loading docks capture e-commerce fulfillment demand. |
Research Methodology
Document review covered Ministry of Public Works and Housing SNI standards, Financial Services Authority REIT frameworks, and Omnibus Law regulatory filings, complemented by interviews with property development executives, logistics facility managers, and construction procurement leads. Secondary validation drew from customs trade data, provincial permit issuance records, and developer financing disclosures. Bottom-up project pipeline aggregation and top-down macroeconomic indicators were triangulated.
Historical absorption patterns were cross-referenced against panel input from institutional investors and tenant facility managers. Segmentation modeling incorporated property type, investment vehicle structure, target customer archetype, and regional regulatory cluster across the analysis window. CAGRs were derived from unit completion forecasts and rental rate trajectory assumptions. Forecast inputs included Nusantara infrastructure commitment schedules and e-commerce fulfillment square footage demand curves.
Revisions become necessary when Ministry energy efficiency mandates accelerate, seismic-grade steel commodity cycles spike, or Nusantara administrative migration timelines shift. Forecasts reflect documented assumptions about permitting velocity and construction cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
E House Market