
 Germany Residential Real Estate Market | 2026-2036
Germany Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Residential Real Estate Market Foresight
Institutional project financing is narrowing the field of viable competitors in German residential development. Vonovia SE leverages its scale to secure favorable bond terms for portfolio expansion across tier-one cities. Patrizia SE anchors its position through specialized fund structures targeting core-plus residential assets. Deutsche Wohnen SE sustains development pipelines via joint-venture equity partnerships that limit balance-sheet exposure.
Germany residential real estate encompasses privately owned or leased dwellings—detached houses, condominiums, townhouses, multi-family buildings, and duplexes—typically constructed with reinforced concrete frames or timber hybrid systems and regulated by the Energy Efficiency Ordinance (EnEV) successor standards. Its primary purpose is to provide habitable space for households while functioning as a store of wealth and inflation hedge in a low-interest-rate environment. Condominium stock leads transaction volume in urban cores where land scarcity elevates per-unit values. Multi-family buildings capture the deepest margin pools for institutional investors through operational efficiencies at scale. First-time homebuyers represent the most contested buyer profile as lenders compete for long-term mortgage relationships.
The Federal Financial Supervisory Authority (BaFin) governs mortgage lending standards, while the German Building Energy Act (GEG) and KfW promotional bank programs shape construction quality and retrofit incentives. BaFin's macroprudential rules constrain loan-to-value ratios, filtering speculative demand and protecting portfolio quality for regulated lenders. Stakeholders must monitor how KfW subsidy recalibrations and municipal zoning accelerations interact to determine which price tiers and property types clear feasibility hurdles in the next development cycle.
Market Dynamics
The German Building Energy Act (GEG) is compressing development timelines by mandating near-zero-energy standards for all new construction, forcing developers to front-load capital into envelope systems and heat-pump infrastructure before foundation work begins.
Growth Catalysts
- KfW Promotional Bank Subsidies:Low-interest construction loans and renovation grants channel private capital into efficiency upgrades, expanding the addressable market for certified low-energy housing stock across metropolitan zones.
- First-Time Homebuyer Cohort:Mortgage accessibility improvements at German retail banks are unlocking pent-down-payment capacity among younger households, creating demand velocity in entry-level condominiums.
- Urban In-Migration Patterns:Sustained population flows into Berlin, Munich, and Hamburg generate structural supply deficits that support absorption rates for new multi-family units.
Market Restraints
- Construction Input Cost Volatility:Reinforced concrete and timber hybrid material costs fluctuate with energy-intensive production cycles, squeezing project feasibility margins before sales contracts close.
- Land Scarcity in Tier-One Cities:Municipal zoning restrictions and brownfield remediation requirements concentrate developable parcels in the hands of incumbent holders, limiting new entrant pipeline access.
- BaFin Macroprudential Credit Limits:Loan-to-value ratio caps filter speculative demand but simultaneously constrain leverage-dependent buyer segments, compressing transaction velocity at price thresholds.
Strategic Opportunities
- Deep Energy Retrofit Stock:Pre-1990 multi-family buildings in eastern German states present concentrated renovation demand as GEG compliance deadlines approach, creating specialized contractor opportunities.
- Heat Pump and PV Integration Mandates:The GEG's fossil-fuel heating ban from 2024 onward creates captive demand for building-systems contractors capable of integrated envelope-and-plant design.
- Institutional Build-to-Retain Models:Pension funds and insurance balance sheets seek long-duration yield assets, opening equity partnerships for developers willing to retain operational control post-completion.
Industry Challenges
- Certified Craftsman Shortage:Specialized trades for passive-house construction and heat-pump installation face training pipeline gaps, extending project timelines and inflating labor cost contingencies.
- GEG Compliance Documentation Burden:Energy performance verification requirements demand specialized consultancy inputs, adding soft-cost layers that erode developer returns on smaller-scale projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Residential Real Estate Market |
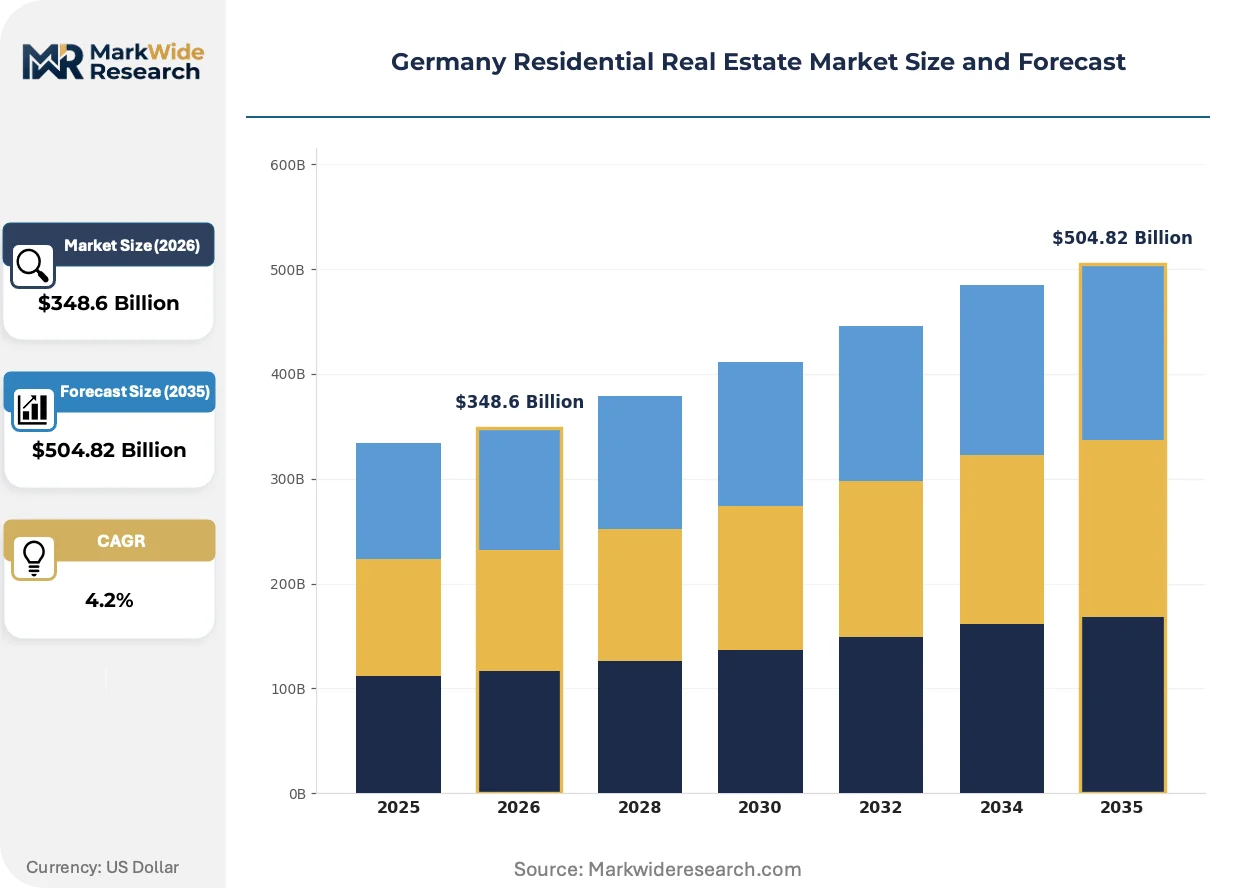
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $504.82 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Detached House, Condominium, Townhouse, Multi-family Building, Duplex Buyer Profile: First-time Homebuyers, Property Investors, Retirees, Relocating Families, Renovators Sales Channel: Real Estate Agents, Online Portals, Auction Houses, Private Sellers, Property Developers Price Tier: Economy, Mid-Range, Premium, Luxury, Ultra Prime |
| Companies Covered | TAG Immobilien AG, Patrizia SE, Vonovia SE, Heimstaden Germany GmbH, ABG Frankfurt Holding, Deutsche Wohnen SE, Vivawest GmbH, Consus Real Estate, LEG Immobilien SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Residential Real Estate Market Shifts & Advancements
Building technology and financing structures are converging to reshape how German residential assets are delivered, operated, and held on institutional balance sheets.
Timber hybrid structural systems are migrating from niche ecological projects to mid-rise multi-family developments in Munich and Hamburg. Institutional developers adopt these systems to accelerate construction schedules and meet carbon-accounting requirements for green bond eligibility. The shift compresses traditional concrete-frame contractor relationships while elevating specialized timber engineering firms into prime vendor status.
The German Building Energy Act (GEG) and its EnEV successor standards now mandate heat-pump-ready infrastructure and maximum primary energy thresholds for all new permits. Developers must integrate envelope performance, ventilation heat recovery, and renewable generation into schematic design phases rather than treating them as fit-out options. Multi-family projects in Berlin face the steepest compliance gradients, driving consolidation toward developers with in-house energy modeling capabilities.
Institutional landlords are unbundling property management from development execution, creating standalone service platforms that compete for third-party fee income. Vonovia and Patrizia now operate captive management arms that bid against independent operators for external mandates. This restructuring concentrates operational data and tenant relationship ownership with asset holders, compressing margins for traditional third-party property managers in tier-one cities.
Germany Residential Real Estate Market Segmentation
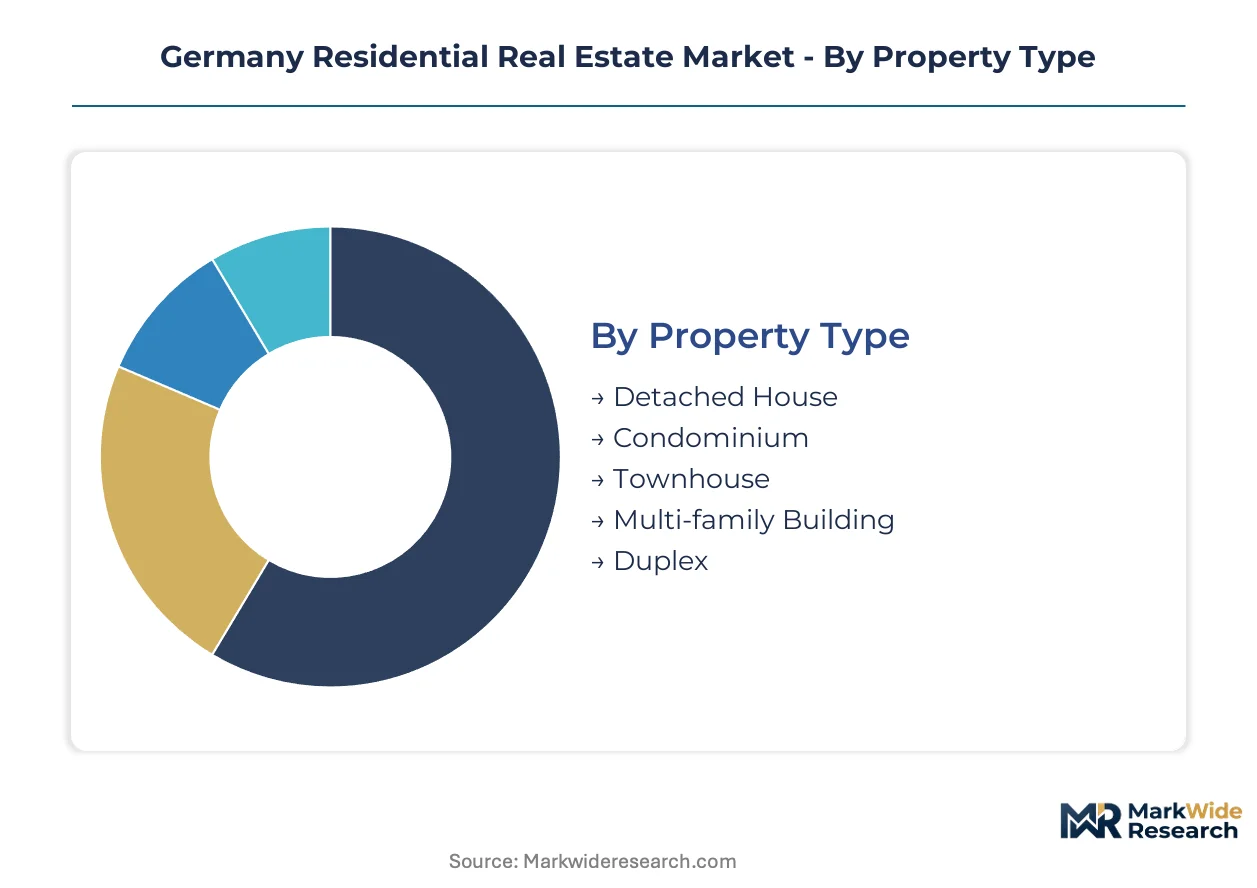
Segmentation in German residential real estate reveals how regulatory pressure, financing access, and urbanization patterns concentrate value across distinct property categories and buyer cohorts. Understanding these divisions exposes where capital flows meet constraint points in development pipelines and transaction velocity.
Property Type:
Mature structural categories dominate transaction volume while emerging hybrid formats gain regulatory preference under GEG efficiency mandates.
- Detached House:Single-family dwellings on dedicated land parcels, typically constructed with reinforced concrete frames or timber hybrid systems. Demand concentrates in suburban rings around Munich and Hamburg where remote-work flexibility sustains premium pricing despite longer commutes.
- Condominium:Individual ownership units within multi-story buildings, regulated by the German Condominium Act (WEG). Berlin's housing supply deficit drives absorption velocity for entry-level units as first-time buyers compete for limited stock in gentrifying districts.
- Townhouse:Attached or semi-detached dwellings sharing party walls, offering intermediate density between apartments and detached homes. Stuttgart and Frankfurt corridors show rising developer interest for family-oriented configurations.
- Multi-family Building:Purpose-built rental or owner-occupied structures with five or more units, capturing institutional capital through operational scale efficiencies. Eastern German cities present concentrated renovation demand as GEG compliance deadlines approach.
- Duplex:Two-unit structures permitting owner-occupancy with rental income offset, popular among small-scale investors in secondary cities where land costs permit feasibility.
Multi-family buildings handle the majority of throughput; condominiums are climbing the fastest on share as urban land scarcity intensifies.
Buyer Profile:
Customer segmentation tracks life-cycle stage and capital source, revealing divergent sensitivity to BaFin lending constraints and KfW subsidy eligibility.
- First-time Homebuyers:Households entering ownership without prior property equity, typically targeting entry-level condominiums. Mortgage accessibility improvements at German retail banks unlock pent-down-payment capacity among younger cohorts in Berlin and Hamburg.
- Property Investors:Private or institutional capital seeking yield through rental income or appreciation. Tax-advantaged depreciation schedules and negative interest rate environments sustain demand for core-plus assets in tier-one cities.
- Retirees:Empty-nest households downsizing from suburban family homes to urban condominiums or senior-accessible townhouses. Proximity to healthcare infrastructure and public transit determines location preference.
- Relocating Families:Corporate transferees and intra-German migrants seeking immediate occupancy solutions. Munich's labor market dynamism generates consistent demand for furnished mid-range rentals.
- Renovators:Owner-occupants or developers acquiring pre-1990 stock for GEG-compliant energy retrofits. KfW promotional bank subsidies channel private capital into efficiency upgrades across eastern German states.
Property investors anchor transaction volume; first-time homebuyers represent the steepest expansion trajectory as lender competition intensifies.
Sales Channel:
Distribution architecture spans traditional intermediaries and digital platforms, with regulatory licensing requirements filtering participant quality.
- Real Estate Agents:Licensed intermediaries governed by the Estate Agent Act (MaBV), commanding commission structures of 3-7 percent depending on regional convention. Bavaria and Baden-Württemberg maintain higher fee tolerance than eastern states.
- Online Portals:Digital listing aggregators enabling direct buyer-seller contact, compressing information asymmetry and traditional agent relevance. Market leaders integrate mortgage pre-qualification tools to capture transaction funnel data.
- Auction Houses:Specialized venues for distressed or unique properties, including forced sales and estate liquidations. Judicial auction procedures under the German Code of Civil Procedure (ZPO) create transparency advantages for cash-ready buyers.
- Private Sellers:Direct transactions bypassing intermediaries, typically occurring in tight-knit communities or among repeat transactors with established valuation confidence.
- Property Developers:Vertical integration of construction and sales functions, common in new-build condominiums. GEG compliance documentation burdens favor developers with in-house energy modeling capabilities.
Real estate agents still process the majority of throughput; online portals are gaining share fastest as digital-native cohorts enter prime home-buying age.
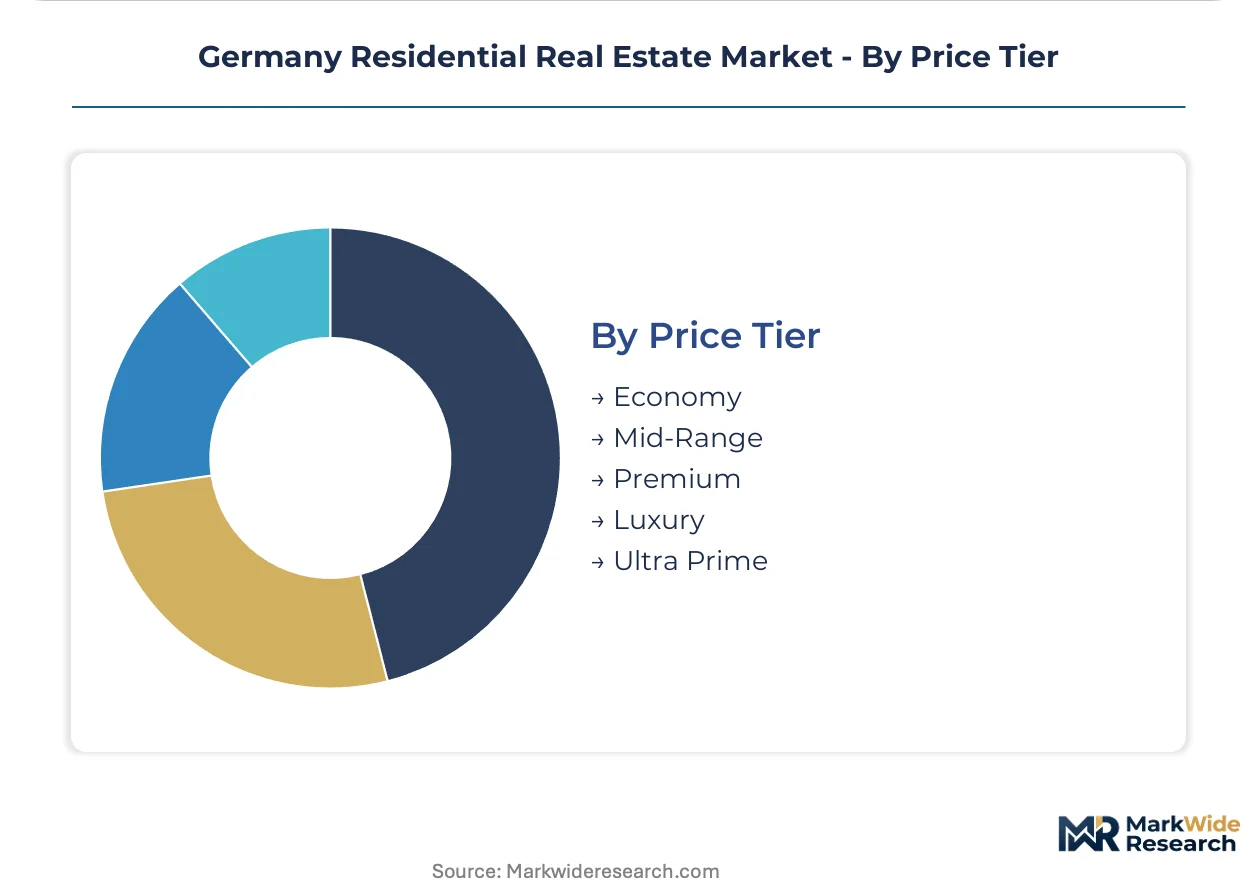
Price Tier:
Stratification reflects land scarcity gradients, construction cost differentials, and amenity premiums across metropolitan hierarchies.
- Economy:Entry-level housing stock in secondary cities or peripheral districts, often requiring renovation to meet GEG standards. Eastern German markets and post-industrial Ruhr regions concentrate supply.
- Mid-Range:Standard-quality construction in established neighborhoods with transit access, representing the median transaction volume across German metropolitan areas.
- Premium:Above-average specifications in prime urban locations or desirable suburban enclaves. Munich's constrained supply elevates per-unit values disproportionately.
- Luxury:High-end finishes, architectural distinction, and exclusive addresses in tier-one city centers. Berlin-Mitte and Hamburg-HafenCity anchor this segment.
- Ultra Prime:Exceptional properties with unique locational or historical attributes, transacting through private networks rather than public listings. Lakefront Bavarian estates and preserved Gründerzeit villas in Berlin command this tier.
Mid-range properties handle the majority of throughput; premium tier is expanding most quickly as international capital seeks inflation-hedge assets in stable jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German Building Energy Act (GEG) and KfW promotional bank programs create divergent investment climates across federal states, with efficiency mandates and subsidy access determining where developers concentrate capital deployment.
Bavaria
Munich's persistent housing supply deficit attracts institutional capital seeking inflation-hedge assets in a supply-constrained environment. The Bavarian building code supplements federal GEG standards with additional thermal bridge requirements. The Munich metropolitan corridor concentrates timber-hybrid construction expertise as developers race to meet near-zero-energy mandates.
North Rhine-Westphalia
Post-industrial Ruhr cities present concentrated renovation demand as pre-1990 multi-family stock faces GEG compliance deadlines. KfW low-interest renovation loans channel private capital into efficiency upgrades across Dortmund and Essen. The Rhine-Ruhr polycentric urban region supports mid-range pricing tiers where land scarcity pressures remain muted relative to southern metros.
Baden-Württemberg
Stuttgart's automotive sector payrolls sustain premium housing demand despite longer commutes from suburban rings. State-level passive-house construction incentives stack with federal KfW programs. The Stuttgart-Heilbronn corridor shows rising developer interest for family-oriented townhouse configurations.
Berlin-Brandenburg
Sustained in-migration from domestic and international sources generates structural supply deficits that support absorption rates for new multi-family units. Federal rent regulation frameworks interact with municipal zoning accelerations to determine project feasibility. Berlin's housing supply deficit drives absorption velocity for entry-level condominiums as first-time buyers compete for limited stock.
Hamburg
Port-city economic dynamism generates consistent demand for furnished mid-range rentals among corporate transferees. The Hamburg Building Energy Act implementation timeline runs parallel to federal GEG mandates. The HafenCity redevelopment zone anchors luxury-tier transactions as international capital seeks stable-jurisdiction assets.
Germany Residential Real Estate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Scale-driven institutional landlords dominate portfolio holdings in tier-one cities, while regional developers retain footholds in secondary markets through localized land-bank relationships. Two strategic archetypes prevail: vertically integrated platform operators bundling development, management, and financing functions; and specialized fund managers deploying capital through joint-venture structures. Competitive intensity concentrates around land-bank accumulation in supply-constrained metros and operational efficiency in multi-family asset management.
Within the scale-driven tier, Vonovia SE and Deutsche Wohnen SE exemplify platform operators with captive management capabilities, while Patrizia SE occupies a position among specialized fund structures targeting core-plus residential assets. TAG Immobilien AG represents regional consolidation archetypes with eastern German concentration. These entities illustrate how institutional capital concentration narrows viable competitor fields as bond-market access and KfW subsidy eligibility filter participation.
| Leading Market Players |
|---|
| TAG Immobilien AG |
| Patrizia SE |
| Vonovia SE |
| Heimstaden Germany GmbH |
| ABG Frankfurt Holding |
| Deutsche Wohnen SE |
| Vivawest GmbH |
| Consus Real Estate |
| LEG Immobilien SE |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine Corridor freight costs transmit energy price volatility directly into reinforced concrete and timber hybrid material expenses, concentrating pricing power among developers with captive logistics contracts while forcing tiered price differentiation between GEG-compliant new builds and legacy stock.
Pricing Analysis
Energy performance certification under GEG standards creates the primary spread between premium and economy tiers. Pricing stratifies across near-zero-energy new construction, retrofit-compliant existing stock, and pre-GEG legacy assets facing obsolescence risk. Cost compression in mid-range condominiums is intensifying because construction input volatility outpaces pre-sale price escalation. First-time homebuyers exhibit highest price sensitivity, while institutional build-to-retain investors absorb premium tier premiums for long-duration yield stability.
Supply Chain Analysis
Dual-use building technology export controls from EU member states limit heat-pump and smart-grid component flows, constraining supply for GEG-mandated installations. Manufacturing concentrates in Germany, Austria, and Poland for timber hybrid systems, with reinforced concrete sourcing from domestic and Benelux producers. Supply chain risk centers on single-source vulnerability for certified passive-house craftsmen. Distribution runs through developer-integrated procurement platforms and regional building-material cooperatives serving smaller contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German residential real estate fragmentation creates niche entry points as GEG compliance deadlines splinter demand across retrofit specialists, new-build platform operators, and regional land-bank holders.
For Market Incumbents: Insulate portfolio quality through backward integration into certified craftsman training pipelines, locking in labor capacity ahead of GEG enforcement waves. Secure long-term land options in Berlin-Brandenburg and Munich corridors before municipal zoning accelerations expire. Threat of margin compression from construction cost volatility demands captive procurement relationships with timber hybrid suppliers. For New Entrants and Emerging Players: Pre-1990 multi-family buildings in eastern German states represent the most penetrable entry point, with KfW renovation subsidies de-risking capital deployment. Specialized heat-pump and envelope-system contracting offers lower capital intensity than full development execution. Go-to-market angle: partner with Patrizia SE or TAG Immobilien AG fund structures for pipeline access without balance-sheet exposure. For Investors and Strategic Acquirers: Regional developers with concentrated eastern German land banks and established municipal relationships offer acquisition profiles with embedded GEG retrofit optionality. Long-term viability rests on regulatory enforcement consistency and KfW subsidy continuity. Signal to watch: BaFin macroprudential recalibration of loan-to-value caps, which would unlock leveraged buyer segments and accelerate transaction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GEG Compliance Integration | Captive energy modeling capabilities separate viable developers from obsolete competitors under EnEV successor standards. |
| Timber Hybrid Manufacturing Scale-Up | Domestic production expansion reduces exposure to cross-border freight volatility and secures green bond eligibility. |
| Certified Craftsman Pipeline Development | In-house training programs lock in specialized labor capacity ahead of GEG enforcement deadlines. |
| Joint-Venture Equity Structuring | Partnerships with pension funds and insurance balance sheets limit developer balance-sheet exposure while retaining operational control. |
| Municipal Zoning Acceleration Capture | Early land-bank accumulation in Berlin, Munich, and Hamburg corridors secures developable parcels before supply constraints intensify. |
Research Methodology
Cross-validation between primary interviews with property developers, KfW program officers, municipal zoning administrators, and institutional fund managers anchors the qualitative findings against secondary sources including BaFin regulatory filings, federal building permit databases, and KfW promotional bank disbursement records. Bottom-up project pipeline enumeration triangulates with top-down macroeconomic absorption modeling.
Calibration against historical construction cost indices and mortgage origination velocity informs the analytical framework across the analysis window. Segmentation dimensions include property type, buyer profile, sales channel, price tier, and federal state regulatory cluster. CAGRs derive from supply-demand gap projections and GEG compliance timeline phasing, with inputs from in-migration patterns and KfW subsidy recalibration scenarios.
Practitioners should monitor KfW interest rate adjustments, BaFin macroprudential rule changes, and GEG enforcement variance across federal states for early signals of forecast deviation. Material shifts in construction input cost trajectories or federal coalition policy toward rent regulation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Europe Residential Real Estate Market