
 China Residential Real Estate Market | 2026-2036
China Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
China Residential Real Estate Market Analysis
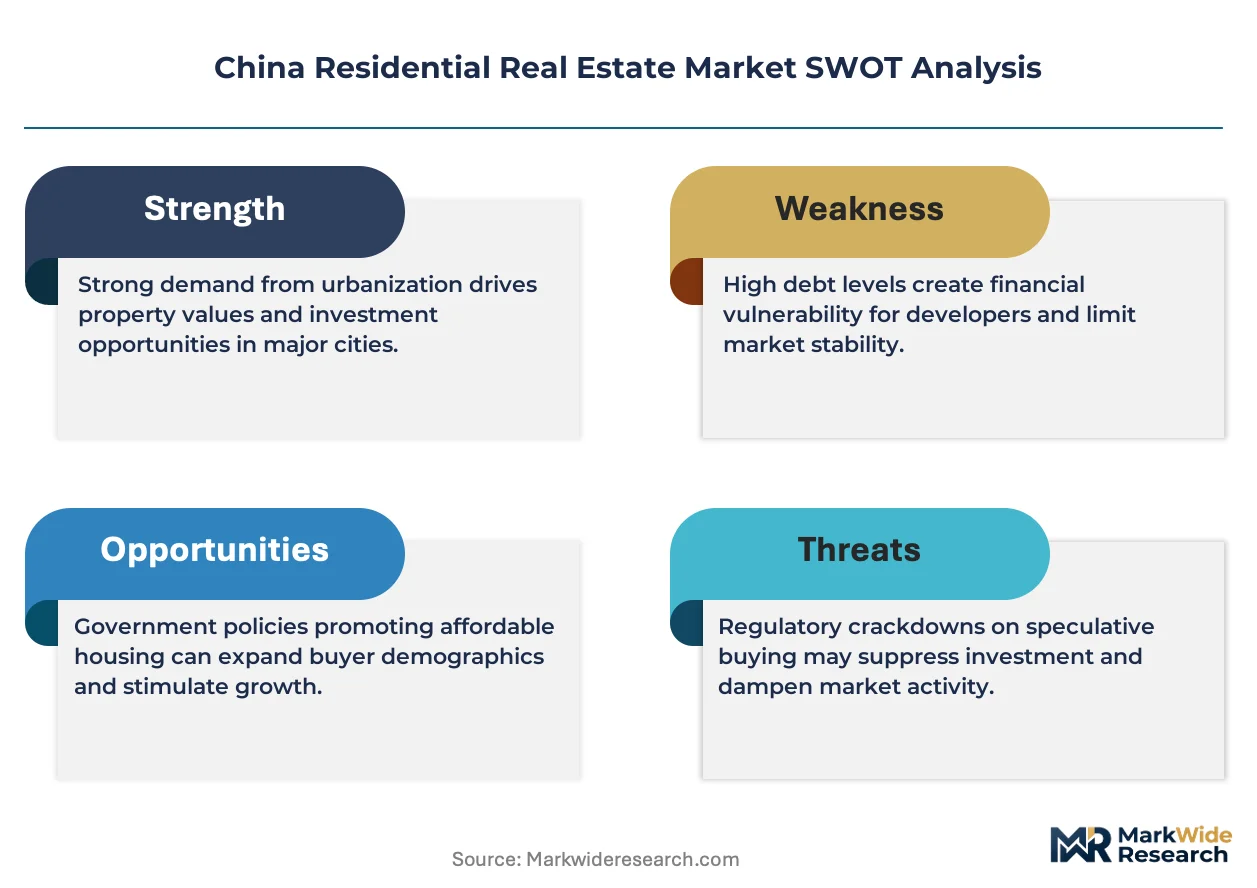
Property management and after-sales service revenue is reconfiguring profit pools away from pure development sales across the China residential sector. China Vanke leverages its nationwide property services platform to capture recurring income streams beyond unit delivery. Country Garden Holdings anchors its competitiveness through extensive lower-tier city coverage and standardized construction methods. Longfor Group differentiates via premium retail-integrated residential complexes in core urban zones.
China residential real estate encompasses purpose-built dwelling units ranging from reinforced concrete high-rise apartments to steel-frame villas, designed for permanent occupancy with specified floor-area ratios, seismic ratings, and utility connectivity standards. The primary commercial purpose centers on monetizing land-use rights through construction and transfer of habitable units to individual or institutional owners. Apartments dominate transaction volumes across all price tiers, while the luxury segment captures disproportionate margin concentration in first-tier cities. First-time buyers represent the most policy-sensitive demand cohort, with mortgage easing directives from the central bank directly stimulating their entry.
The Ministry of Housing and Urban-Rural Development enforces green building standards that mandate energy-efficiency certifications for new residential projects, reshaping material procurement and design specifications. The PBOC and CBIRC jointly calibrate mortgage lending rules and down-payment ratios to modulate speculative demand and safeguard financial stability. Local land-bureau auction mechanisms determine supply timing and floor prices, constraining developer margin flexibility. Stakeholders must monitor whether smart-city infrastructure mandates from MIIT accelerate embedded technology requirements in new residential stock.
Market Dynamics
Property management revenue streams are reconfiguring profit pools away from pure development sales as developers pivot toward recurring income models. The MIIT smart-city infrastructure mandates and Ministry of Housing and Urban-Rural Development green building codes are redirecting capital allocation toward energy-efficient construction and embedded technology requirements.
Growth Catalysts
- MIIT Smart-City Mandates:Embedded IoT infrastructure requirements in new residential stock are accelerating technology integration across tier-one and tier-two developments.
- Mortgage Easing Directives:PBOC down-payment ratio adjustments are stimulating first-time buyer entry in tier-two cities where transaction volumes concentrate.
- Yangtze River Delta Cluster Demand:Shanghai-Suzhou-Hangzhou corridor absorption rates are sustaining developer cash flow visibility amid national inventory pressures.
Market Restraints
- Land-Bureau Auction Mechanisms:Local government floor-price setting constrains developer margin flexibility and compresses return thresholds on new projects.
- Reinforced Concrete Input Volatility:Steel and cement price swings disrupt construction cost forecasting and erode fixed-price contract profitability.
- Financial Stability Safeguards:CBIRC speculative-demand controls limit leverage availability for multiple-property purchasers and investor segments.
Strategic Opportunities
- Tier-Three City Underpenetration:Standardized construction methods enable scalable entry into lower-tier markets where coverage gaps persist.
- Green Building Certification Premiums:Ministry of Housing and Urban-Rural Development energy-efficiency standards create pricing differentiation for certified developments.
- Retail-Residential Convergence:Mixed-use zoning liberalization in core urban zones permits premium revenue stacking from integrated commercial assets.
Industry Challenges
- Seismic Rating Compliance Timelines:GB standard certification delays for high-rise structural designs extend pre-construction approval cycles.
- Smart-System Integration Complexity:Legacy building management infrastructure requires costly retrofitting to achieve MIIT connectivity mandates.
- Skilled Project Manager Scarcity:Energy-efficient construction expertise gaps constrain developer execution capacity for green-certified developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Residential Real Estate Market |
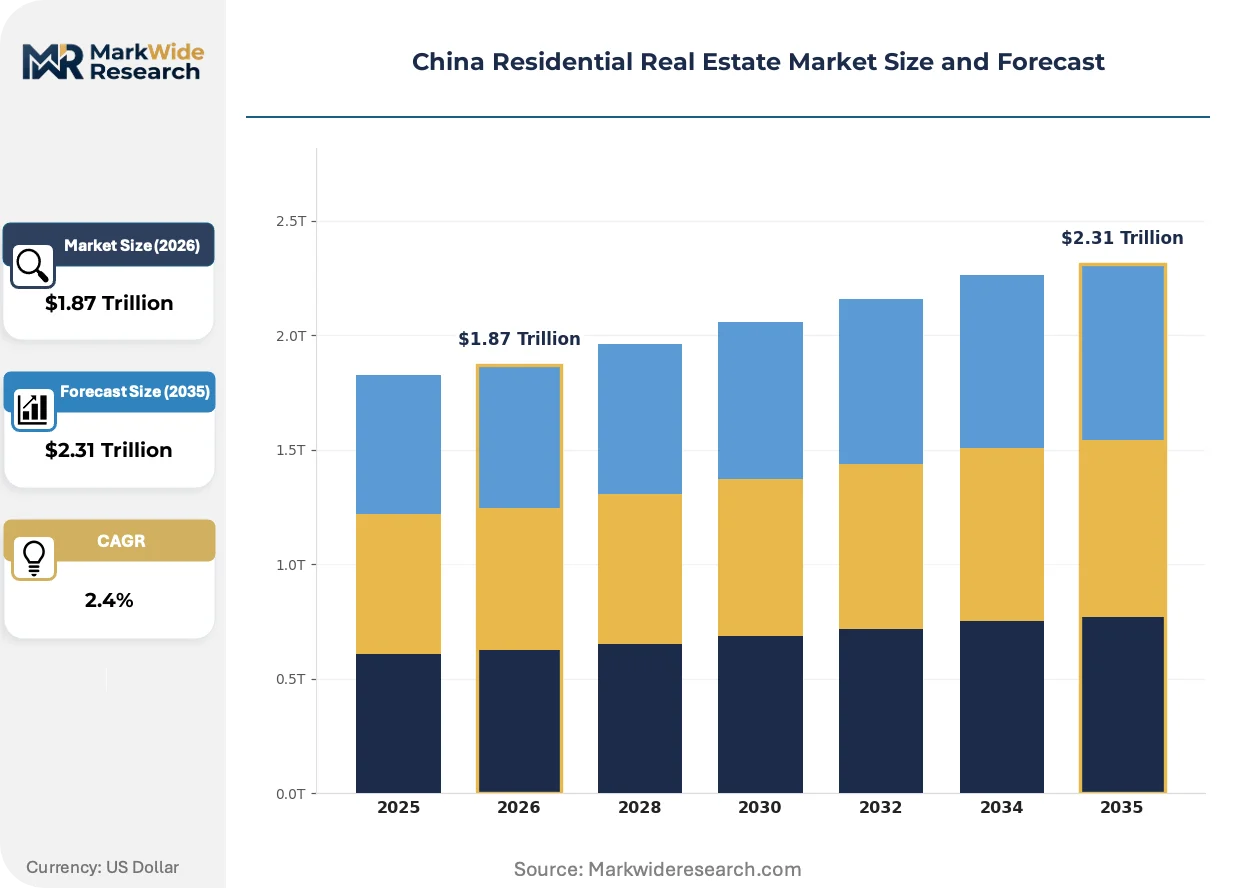
| Market Size in 2026 | $1.87 Trillion |
| Market Size in 2035 | $2.31 Trillion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Apartments, Villas, Townhouses, Bungalows Price Tier: Luxury, Mid-range, Affordable, Budget Development Stage: Pre-construction, Under Construction, Completed, Renovated Buyer Type: First-time Buyers, Investors, Renters, Retirees |
| Companies Covered | China Vanke Co., Ltd, China State Construction Engineering Corporation, Country Garden Holdings Company Limited, China Resources Land Limited, Sunac China Holdings Limited, Longfor Group Holdings Limited, China Overseas Land & Investment Limited, Greenland Group, Shimao Group Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Residential Real Estate Market Emerging Trajectories
Digital building management platforms and prefabricated construction methods are compressing development timelines while elevating quality consistency. Regulatory pressure on carbon intensity and buyer preference for technology-enabled living are converging to reshape competitive positioning.
Building-integrated photovoltaics and smart glass facade systems are rendering obsolete conventional curtain-wall construction in premium residential towers. Shanghai and Hangzhou developers are mandating these specifications for new luxury inventory. The technology shift is compressing mechanical system footprints and reducing operational energy loads.
Dual carbon goals enforcement through MEE provincial targets is tightening embodied carbon limits on steel and cement procurement. Developers must now source low-carbon materials or absorb compliance penalties. The Yangtze River Delta cluster faces the strictest interim benchmarks given its concentration of construction activity.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into discrete subscription tiers. Tier-two city buyers are selecting à-la-carte property management modules over comprehensive packages. Longfor Group and comparable operators are restructuring revenue recognition around recurring service streams rather than upfront delivery margins.
China Residential Real Estate Market Segmentation
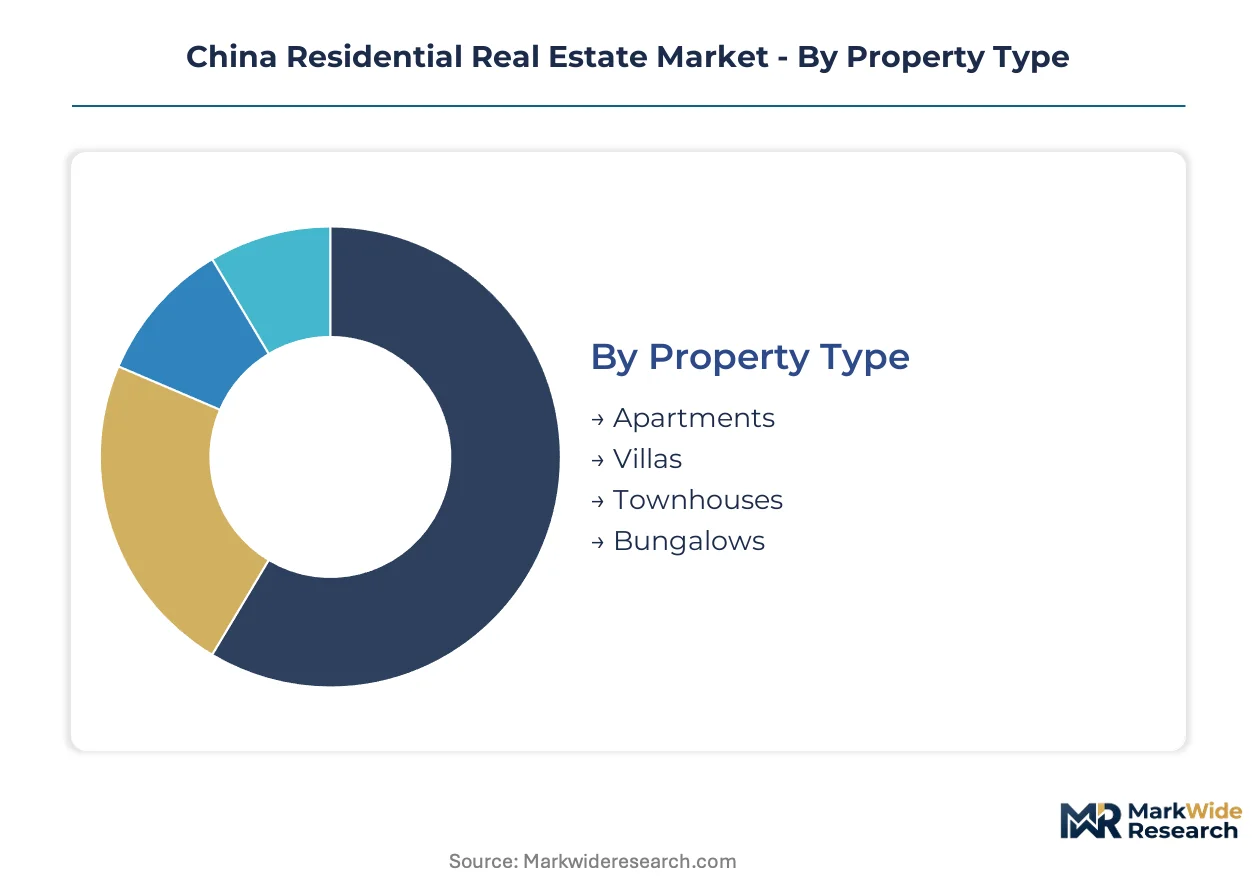
Segmentation in China's residential real estate market reveals how capital cycles, policy sensitivity, and buyer demographics create distinct risk-return profiles across product categories. Developers calibrate land acquisition and construction pacing differently for each segment, with inventory turnover varying dramatically between speculative pre-sales and completed stock.
Property Type:
Apartments turn inventory fastest through standardized pre-sale models, while villas and townhouses operate on extended capital commitment timelines stretching across multiple development cycles.
- Apartments:Reinforced concrete high-rise structures dominate transaction volumes across all price tiers. Demand concentrates in the Yangtze River Delta cluster around Shanghai, Suzhou, and Hangzhou, where MIIT smart-city mandates accelerate embedded IoT infrastructure requirements in new developments.
- Villas:Steel-frame detached dwellings with premium floor-area ratios and seismic ratings command extended sales cycles. Supply concentrates in first-tier city peripheries where green building certification premiums from Ministry of Housing and Urban-Rural Development standards create pricing differentiation.
- Townhouses:Medium-density attached units balance space efficiency with land-use intensity.
- Bungalows:Low-rise single-story construction remains limited to specific zoning allowances in tier-three cities.
Apartments dominate installed base. Villas is where expansion concentrates for margin extraction.
Price Tier:
Cost stratification determines financing structure, with luxury developments relying on institutional capital and affordable segments depending on PBOC mortgage easing directives.
- Luxury:Premium positioning in core urban zones with building-integrated photovoltaics and smart glass facade systems. Shanghai and Hangzhou developers mandate these specifications, with dual carbon goals enforcement through MEE provincial targets tightening embodied carbon limits on steel and cement procurement.
- Mid-range:Standardized construction methods enable scalable deployment across tier-two cities. First-time buyer demand responds directly to central bank down-payment ratio adjustments, making this cohort the most policy-sensitive in transaction volume terms.
- Affordable:Government-subsidized pricing bands with constrained developer margins.
- Budget:Entry-level inventory in lower-tier markets where coverage gaps persist.
Mid-range commands transaction volume. Luxury captures margin concentration.
Development Stage:
Capital lock-up duration varies dramatically, with pre-construction land banking consuming years of carrying costs versus immediate revenue recognition on renovated stock.
- Pre-construction:Land-use rights acquisition and approval cycles subject to local land-bureau auction mechanisms. GB standard certification delays for high-rise structural designs extend timelines, particularly for seismic rating compliance in high-rise residential towers.
- Under Construction:Prefabricated construction methods compress development timelines while elevating quality consistency. Steel and cement price volatility disrupts cost forecasting for fixed-price contracts.
- Completed:Ready-for-occupancy inventory with immediate revenue recognition.
- Renovated:Legacy stock retrofitting to achieve MIIT connectivity mandates and energy-efficiency certifications.
Under Construction absorbs majority capital deployment. Renovated is climbing the fastest as retrofit demand accelerates.
Buyer Type:
Customer segmentation determines sales channel strategy, with institutional investors negotiating bulk terms while individual purchasers respond to mortgage availability signals.
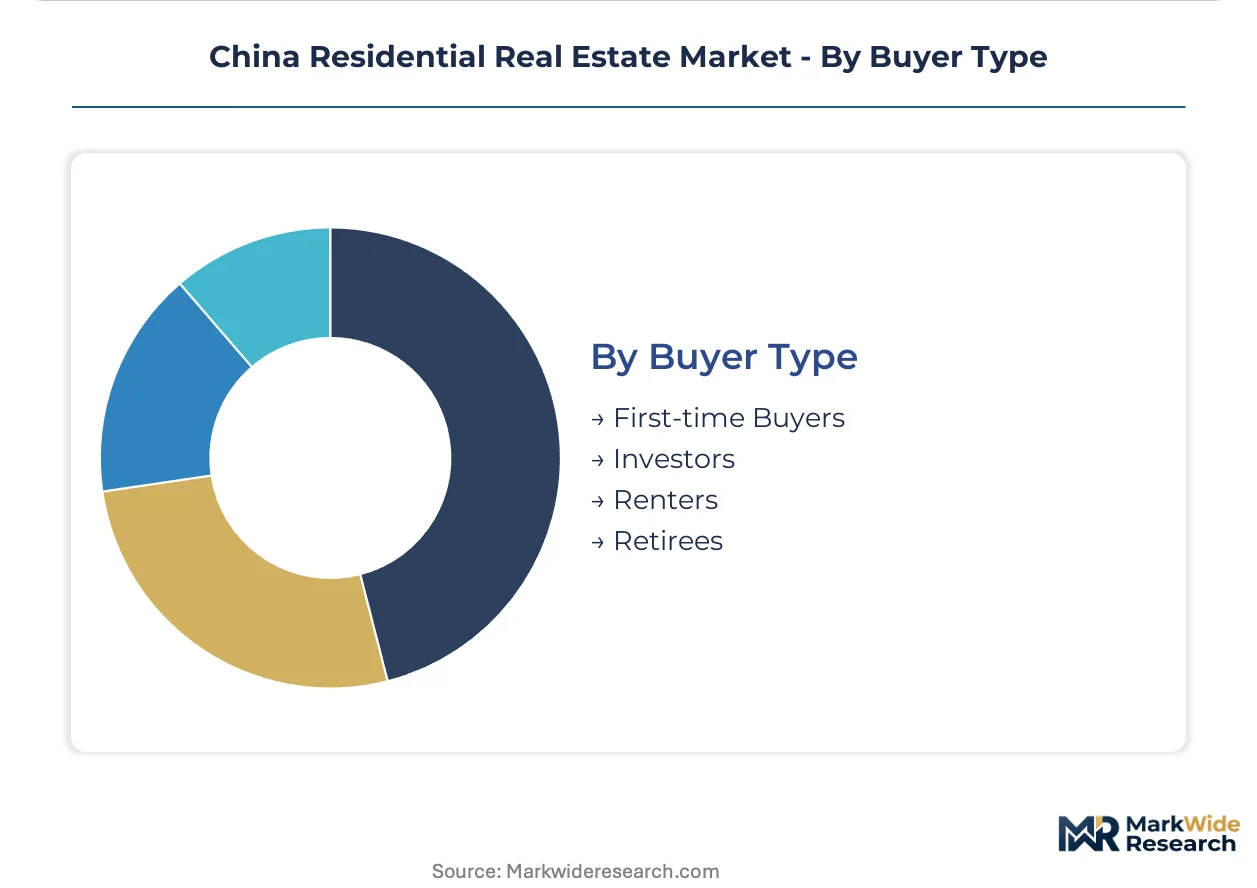
- First-time Buyers:Policy-sensitive entry cohort concentrated in tier-two cities. PBOC and CBIRC mortgage lending rules directly stimulate or constrain their market participation, with down-payment ratio adjustments serving as the primary demand modulation tool.
- Investors:Multiple-property purchasers facing CBIRC speculative-demand controls and leverage limitations. Financial stability safeguards restrict availability for this segment regardless of price tier.
- Renters:Price-sensitive demand for leasehold arrangements in urban employment centers.
- Retirees:Downsizing purchasers prioritizing property management and after-sales service quality.
First-time Buyers dominate transaction flow. Investors face strictest regulatory constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
First-time buyers in tier-two cities exhibit the highest price elasticity, responding immediately to mortgage easing directives, while luxury purchasers in first-tier cores show demand inelasticity regardless of policy shifts. This divergence shapes regional development priorities and capital allocation patterns across China's residential markets.
Yangtze River Delta
Shanghai, Suzhou, and Hangzhou concentrate transaction volumes for both apartments and premium villas. MIIT smart-city mandates accelerate embedded IoT infrastructure requirements in new developments. The cluster faces strictest MEE dual carbon interim benchmarks, tightening embodied carbon limits on steel and cement procurement.
Pearl River Delta
Shenzhen and Guangzhou drive demand for mid-range inventory among technology sector employees. PBOC down-payment ratio adjustments directly stimulate first-time buyer entry in Dongguan and Foshan peripheral markets. Green building certification premiums from Ministry of Housing and Urban-Rural Development standards create pricing differentiation for certified developments.
Beijing-Tianjin-Hebei
Capital region buyers prioritize property management quality and after-sales service over pure price considerations. CBIRC speculative-demand controls limit leverage availability for multiple-property purchasers regardless of price tier. Prefabricated construction methods compress development timelines in Tianjin while elevating quality consistency.
Sichuan-Chongqing
Chengdu and Chongqing absorb scalable deployment of standardized construction methods across mid-range segments. Local land-bureau auction mechanisms constrain developer margin flexibility through floor-price setting. Seismic rating compliance timelines for GB standard certification extend pre-construction approval cycles for high-rise residential towers.
Shandong Peninsula
Qingdao and Jinan markets exhibit coverage gaps in tier-three city penetration where standardized methods enable scalable entry. Steel and cement price volatility disrupts construction cost forecasting for fixed-price contracts. Skilled project manager scarcity for energy-efficient construction expertise constrains developer execution capacity.
China Residential Real Estate Market Vendor Landscape
State-affiliated developers and private-sector operators split the market along capital access and operational agility lines. The structure consolidates around tier-one landbank scale rather than national fragmentation. Three archetypes dominate: nationwide property services platforms, lower-tier coverage specialists, and premium retail-integrated complex developers. Competitive moves center on recurring income model pivots and mixed-use zoning exploitation.
Among the private-sector cohort, China Vanke Co., Ltd exemplifies the property services platform archetype through its nationwide footprint. Country Garden Holdings Company Limited occupies a position representing extensive lower-tier market coverage capabilities. Longfor Group Holdings Limited anchors the premium retail-integrated residential complex segment in core urban zones.
| Leading Market Players |
|---|
| China Vanke Co., Ltd |
| China State Construction Engineering Corporation |
| Country Garden Holdings Company Limited |
| China Resources Land Limited |
| Sunac China Holdings Limited |
| Longfor Group Holdings Limited |
| China Overseas Land & Investment Limited |
| Greenland Group |
| Shimao Group Holdings Limited |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor carries reinforced concrete and steel inputs from northern mills to Shanghai-Suzhou-Hangzhou construction sites, with logistics cost volatility amplifying developer margin compression in premium segments while enabling price discrimination across tier-one and tier-two delivery zones.
Pricing Analysis
Property management subscription tiers now drive lifetime value beyond unit delivery, with three-tier pricing structure across premium, standard, and economy service levels capturing recurring revenue from retirees and first-time buyers alike. Price differentiation rests on green building certification grade and embedded smart-system density, with MIIT-compliant developments commanding premiums. Pricing pressure stems from local land-bureau floor-price mechanisms constraining developer flexibility. First-time buyers in tier-two cities exhibit highest price sensitivity, while luxury purchasers in Shanghai cores show demand inelasticity.
Supply Chain Analysis
Prefabricated component manufacturing concentrates in Hebei, Jiangsu, and Guangdong provinces, where state-affiliated construction groups and private developers source standardized wall panels and floor systems. Raw material flows draw from domestic steel mills, cement clinker producers, and low-carbon glass fabricators. Supply chain risk centers on single-source vulnerability for building-integrated photovoltaics imported from specialized foundries. Distribution runs through regional logistics hubs serving tier-one clusters before radiating to lower-tier markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Property management and after-sales service layers are expanding faster than development sales, transforming residential real estate into a service-attach business where recurring revenue streams reconfigure stakeholder returns.
For Market Incumbents: Build switching-cost moats through captive property services platforms that lock in residents across multiple development cycles. Deepen backward integration into prefabricated component manufacturing to secure cost advantages against steel price volatility. Anchor competitiveness through green certification pipelines that anticipate MEE dual carbon enforcement tightening. For New Entrants and Emerging Players: Build out tier-three city coverage networks where standardized construction methods enable scalable entry against established coverage gaps. Target mid-range apartment segments in Sichuan-Chongqing and Shandong Peninsula where first-time buyer concentration responds to PBOC mortgage easing. Deploy digital building management platforms as differentiation wedge against legacy operators. For Investors and Strategic Acquirers: Carve-out targets emerge from state-affiliated developers divesting non-core property services units to private operators with platform integration capabilities. Five-to-ten year viability hinges on recurring revenue ratio expansion exceeding development sales dependency. Monitor MIIT smart-city mandate acceleration as inflection signal for technology-enabled inventory premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Property Services Platform Integration | Captures recurring revenue streams beyond unit delivery for China Vanke and comparable operators. |
| Green Building Certification Pipeline | Anticipates MEE dual carbon enforcement tightening embodied carbon limits on steel procurement. |
| Prefabricated Construction Scale-Up | Compresses development timelines while elevating quality consistency across tier-two city deployments. |
| Tier-Three City Coverage Expansion | Exploits underpenetrated markets where Country Garden standardized methods enable scalable entry. |
| Smart-System Technology Licensing | Addresses MIIT embedded IoT mandates accelerating connectivity requirements in new residential stock. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with property development executives, construction procurement leads, land-bureau officials, and property services operators; and secondary validation through MIIT infrastructure mandates, Ministry of Housing and Urban-Rural Development green building filings, PBOC mortgage policy circulars, and local land auction records. Bottom-up project pipeline assessments triangulated against top-down regional absorption rate benchmarks.
Forecast inputs span property type segmentation, price tier stratification, development stage capital cycles, and buyer archetype policy sensitivity across the projection horizon. CAGRs derive from historical transaction volume trajectories, land supply auction schedules, and mortgage availability elasticities. Modeled variables include prefabrication penetration rates, green certification adoption curves, and smart-system embedded technology diffusion patterns.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by state-affiliated developers or sudden PBOC mortgage tightening would shift outcomes beyond modeled ranges. Quarterly review of land-bureau auction clearing rates, steel futures pricing, and MIIT smart-city mandate implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market