
 Singapore Real Estate Market | 2026-2036
Singapore Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Real Estate Market Outlook
Mass engineered timber is hardening as a structural alternative to conventional steel and concrete in mid-rise commercial developments, compressing construction timelines and carbon footprints. City Developments Limited leverages its integrated development model to control costs across design, construction, and asset management phases. CapitaLand Investment Limited anchors its portfolio through REIT platforms that recycle capital into new acquisitions. Frasers Property competes on build-to-rent and business park formats that cater to flexible occupier requirements.
Singapore real estate comprises land and built assets traded, leased, or managed for residential occupation, commercial enterprise, industrial production, and retail distribution, governed by strata title systems and leasehold tenures ranging from 99 to 999 years. Residential and commercial property types absorb the majority of institutional capital flows, with industrial segments gaining traction from logistics and data centre demand. REITs as an investment vehicle dominate liquidity provision for retail investors, while direct ownership and private equity structures concentrate among ultra-high-net-worth individuals and sovereign-linked entities. The HDB market segment maintains structural depth through public housing policy, though luxury and mid-range private condominiums capture disproportionate margin pools.
Singapore's Urban Redevelopment Authority zoning instruments and the Building and Construction Authority Green Mark standards shape permissible density, sustainability benchmarks, and redevelopment timelines across all submarkets. The Monetary Authority of Singapore macroprudential rules on loan-to-value ratios and stamp duties directly filter speculative demand and foreign participation eligibility. Stakeholders must monitor land release schedules from the Government Land Sales programme and assess cooling measure adjustments before committing development capital or acquisition leverage.
Market Dynamics
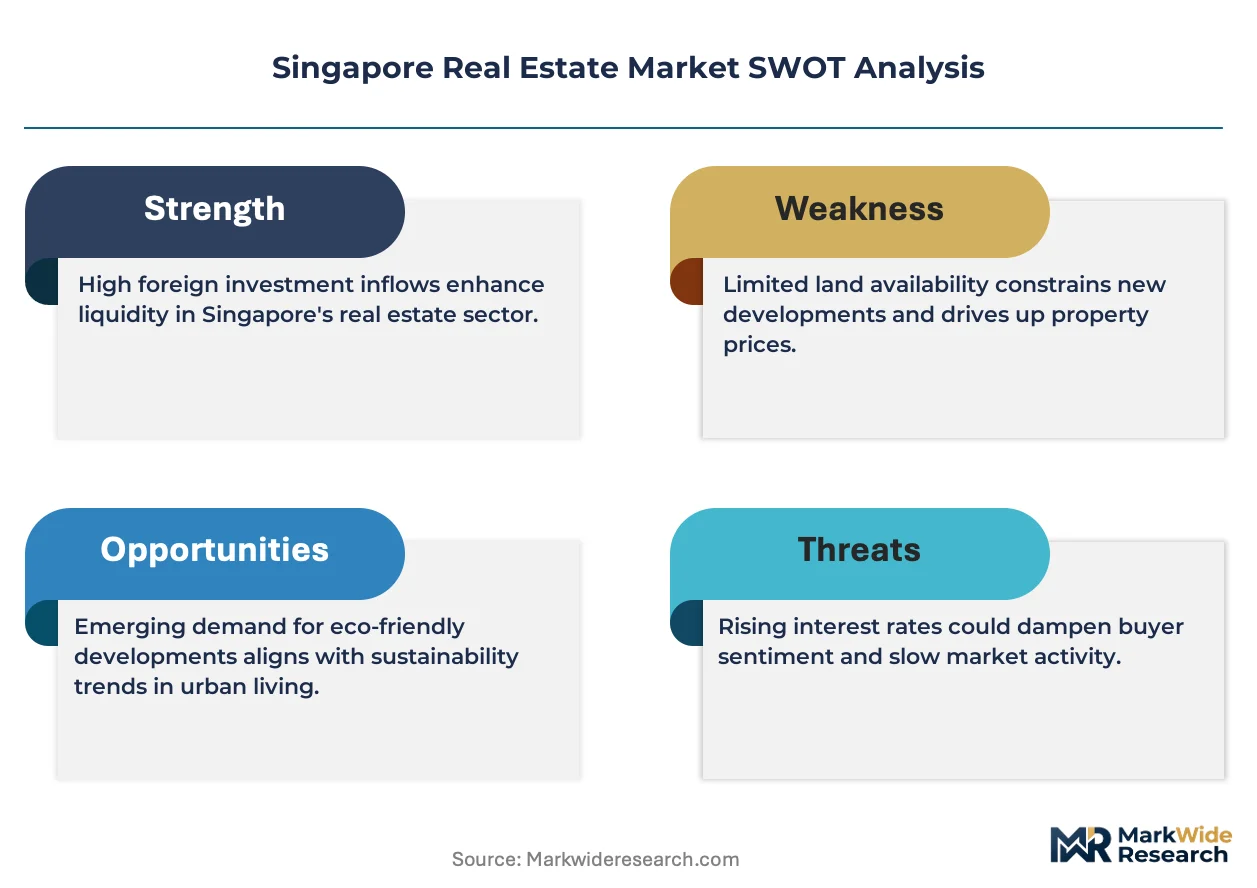
The Urban Redevelopment Authority's cooling measures are recalibrating speculative investment patterns while technology firms intensify Grade A office demand in the Central Business District.
Growth Catalysts
- Technology Sector Expansion:Regional headquarters mandates from data centre and fintech operators are compressing vacancy rates in premium commercial precincts.
- Greater Southern Waterfront Redevelopment:Port land releases under the Government Land Sales programme are triggering mixed-use regeneration with integrated transport nodes.
- Building and Construction Authority Green Mark:Mandatory sustainability benchmarks are accelerating retrofit demand and premium pricing for certified assets.
Market Restraints
- Additional Buyer's Stamp Duty Structure:Foreign investor participation eligibility filters are constraining liquidity in luxury residential segments.
- Construction Input Concentration:Steel and concrete supply dependencies on regional manufacturing clusters expose project timelines to shipping volatility.
- Loan-to-Value Macroprudential Caps:Monetary Authority of Singapore leverage restrictions are compressing acquisition capacity for speculative purchasers.
Strategic Opportunities
- Mass Engineered Timber Adoption:Structural timber systems are opening mid-rise commercial development categories previously dominated by conventional materials.
- Build-to-Rent Formats:Flexible tenure models are capturing expatriate and young professional segments underserved by traditional strata ownership.
- Data Centre Zoning Liberalisation:Industrial land reclassification is enabling hyperscale facility development in western corridor precincts.
Industry Challenges
- Green Mark Certification Timelines:BCA assessment backlogs are delaying project marketing and occupancy commencement.
- Integrated Development Complexity:Mixed-use schemes combining retail, residential and office components require coordination across disparate operational teams.
- Strata Management Fragmentation:Multi-owner commercial buildings face governance friction in executing sustainability retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Real Estate Market |
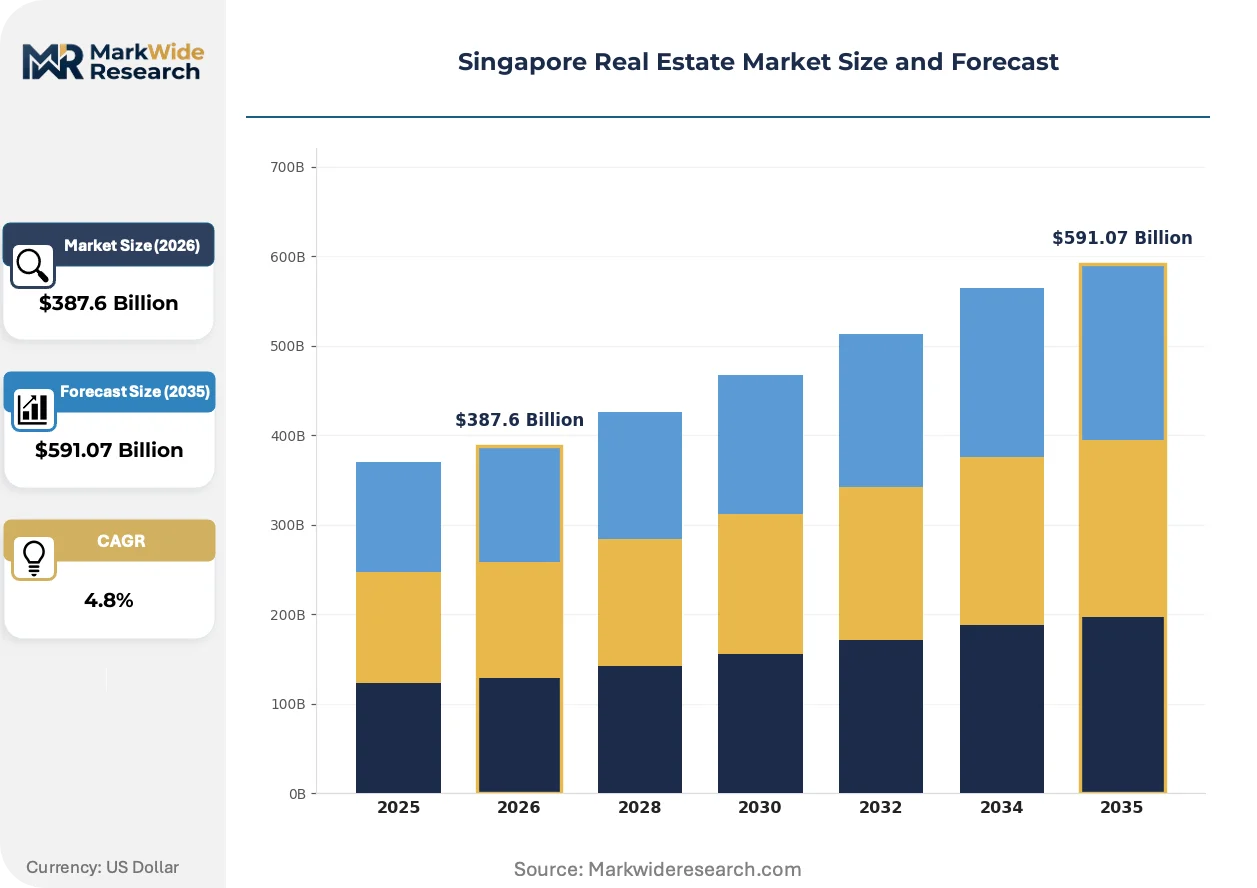
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Residential, Commercial, Industrial, Retail Investment Type: Direct Ownership, REITs, Private Equity, Crowdfunding Buyer Profile: Investors, Homebuyers, Foreign Buyers, Developers Market Segment: Luxury, Mid-range, Affordable, HDB |
| Companies Covered | City Developments Limited, UOL Group, PropNex Realty, 99 Group, Huttons Asia, ERA Realty Network, Frasers Property, OrangeTee & Tie, CapitaLand Investment Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Real Estate Market Strategic Shifts
Digital twin platforms and generative design tools are compressing development cycles while sustainability mandates reshape asset valuation methodologies across all property classes.
Mass engineered timber is overtaking conventional steel and concrete as the structural system of choice for mid-rise commercial developments. City Developments Limited and Frasers Property are specifying cross-laminated timber for six-to-twelve storey office buildings. Construction timelines compress by thirty percent while embodied carbon metrics satisfy institutional investor ESG screening requirements.
Singapore's Urban Redevelopment Authority zoning instruments now mandate minimum greenery replacement ratios for redevelopment sites exceeding five thousand square metres. Developers must integrate sky gardens, vertical planting systems or podium-level landscaping. The policy most affects Orchard Road and Marina Bay precincts where land values previously discouraged non-revenue-generating space allocation.
Tenants are consolidating footprints and prioritising flight-to-quality migration over expansion. Technology and financial services occupiers are surrendering secondary space in ageing buildings to concentrate headcount in Grade A assets with wellness certifications and hybrid-work infrastructure. This behaviour is most visible in the Central Business District where net effective rents for premium stock diverge sharply from secondary grades.
Singapore Real Estate Market Segmentation
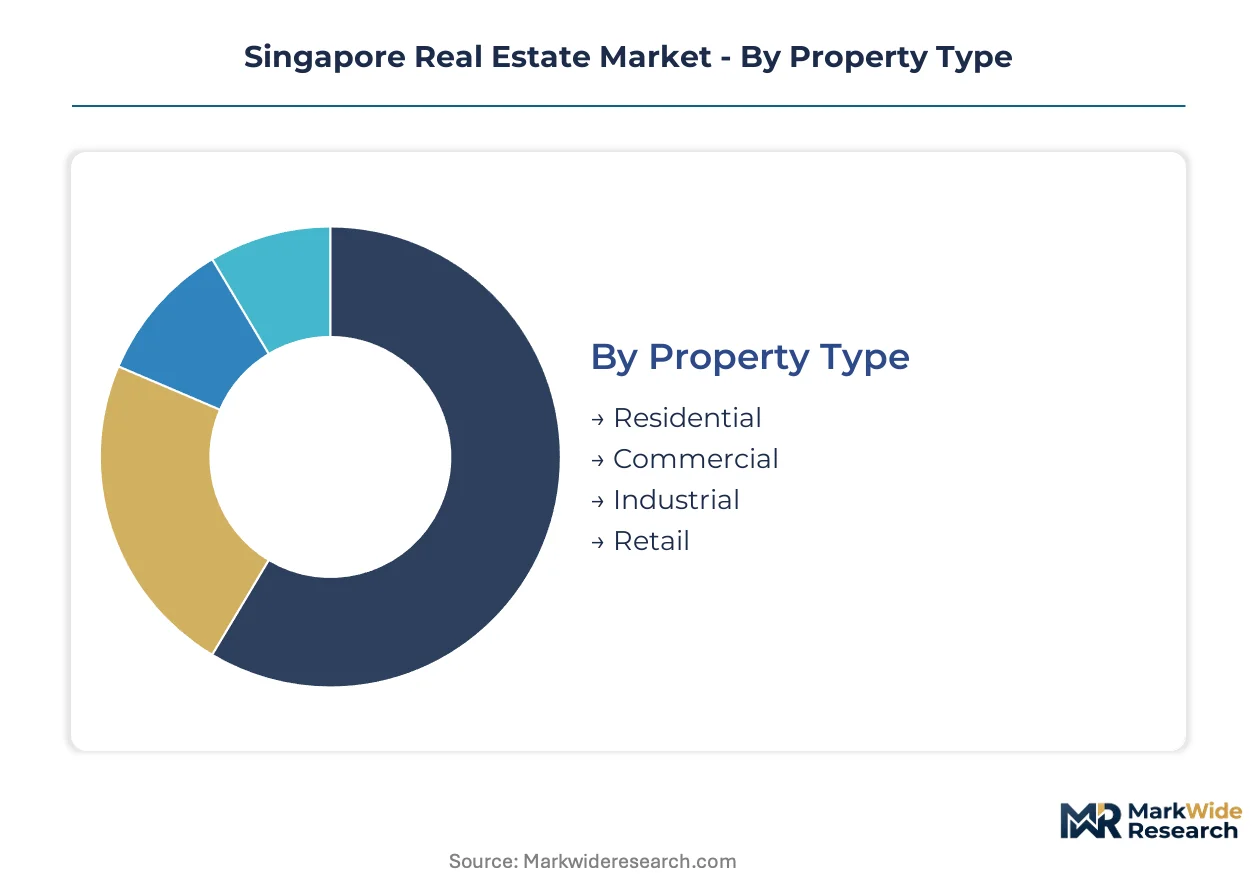
Singapore's real estate market fragments across property function, capital structure, buyer motivation, and price tier. Each segmentation axis reveals distinct liquidity patterns and regulatory exposure. Developers and investors configure strategies around the intersection of these dimensions.
Property Type:
Capital deployment intensity varies sharply by asset function, with lease tenure and planning permission complexity driving risk-adjusted return thresholds.
- Residential:Strata-titled condominiums and landed housing dominate transaction volumes. Private residential stock concentrates in the Core Central Region where cooling measures filter speculative participation.
- Commercial:Grade A office assets in the Central Business District absorb technology sector regional headquarters demand. Flight-to-quality behaviour compresses vacancy spreads between premium and secondary stock.
- Industrial:Logistics facilities and data centres drive absorption in western corridor precincts. Government Land Sales programme releases are reclassifying land use to accommodate hyperscale facility requirements.
- Retail:Orchard Road and suburban mall formats face divergent trajectories. Experiential and F&B tenancy mixes are displacing traditional apparel anchors.
Volume sits with Residential; growth tilts toward Industrial.
Investment Type:
Liquidity horizons and governance burdens separate institutional vehicles from direct holding structures.
- Direct Ownership:Ultra-high-net-worth individuals and family offices hold trophy assets for generational wealth preservation. Stamp duty exposure and loan-to-value caps constrain leverage capacity.
- REITs:CapitaLand Investment and Frasers Centrepoint Trust platforms recycle capital through stapled security structures. Retail investor access provides depth absent in private markets.
- Private Equity:Sovereign-linked entities and pension funds pursue value-add repositioning of ageing commercial stock. Closed-end fund tenures align with redevelopment timelines.
- Crowdfunding:Fractional platforms democratise access to premium residential and commercial slices. Monetary Authority of Singapore licensing requirements filter platform operators.
REITs command liquidity depth; private equity captures illiquidity premiums.
Buyer Profile:
Regulatory eligibility and financing access stratify purchasing power across participant types.
- Investors:Yield-focused purchasers target rental income from established residential and commercial stock. Additional Buyer's Stamp Duty tiers compress net returns on multiple-property holdings.
- Homebuyers:Owner-occupiers access preferential loan-to-value ratios and lower stamp duty rates. HDB upgraders form the pipeline for private condominium entry.
- Foreign Buyers:Non-resident purchasers face elevated stamp duty surcharges and restricted eligibility for landed housing. Mainland Chinese and Indonesian nationals concentrate in luxury condominium segments.
- Developers:Government Land Sales programme participants bid on sites with prescribed gross floor area and use mix. City Developments Limited and Frasers Property compete on integrated development execution.
Homebuyers anchor transaction volumes; foreign buyers concentrate margin pools.
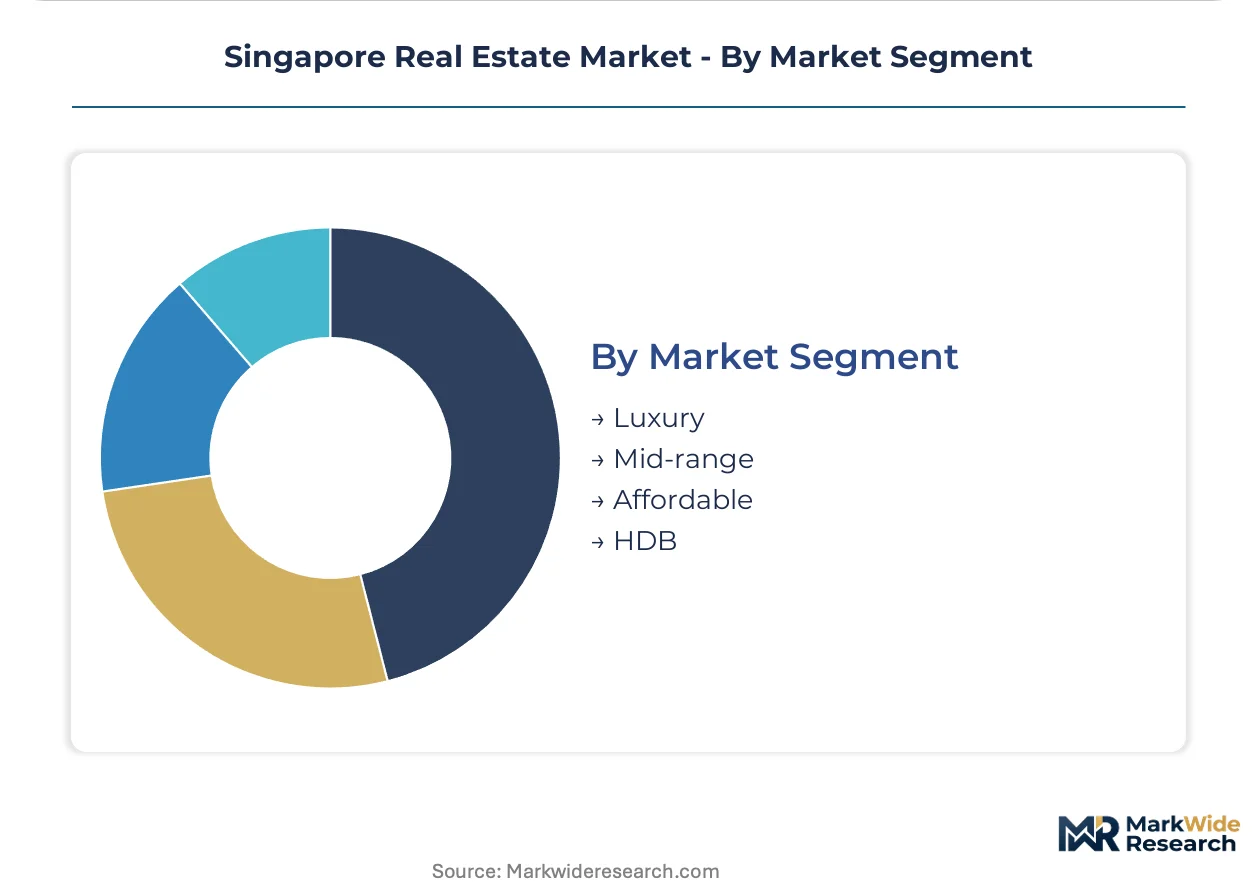
Market Segment:
Price tier alignment with household income distribution and policy intervention intensity shapes absorption velocity.
- Luxury:Core Central Region condominiums above specified price thresholds attract wealth preservation capital. Cooling measure adjustments most immediately affect this segment's liquidity.
- Mid-range:Rest of Central Region and Outside Central Region private housing serves HDB upgraders and young professionals. Mass engineered timber construction is compressing delivery timelines in this category.
- Affordable:Executive condominiums bridge public and private tenure with resale restrictions. CPF housing grants enhance accessibility for qualifying households.
- HDB:Public housing maintains structural market depth through Build-To-Order and resale flat programmes. Mature estate premiums reflect locational scarcity and amenity concentration.
HDB contains volume scale; mid-range private captures upgrade flow acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology sector regional headquarters mandates and port land redevelopment are concentrating demand in Singapore's Central Business District and Greater Southern Waterfront precincts.
Core Central Region
Grade A office absorption from fintech and data centre operators is compressing vacancy rates in Marina Bay and Raffles Place. The Urban Redevelopment Authority zoning instruments mandate minimum greenery replacement ratios for sites exceeding five thousand square metres. Tanjong Pagar and Downtown Core sub-precincts are witnessing flight-to-quality migration as tenants consolidate footprints.
Rest of Central Region
Mid-range private residential development serves HDB upgraders and young professionals seeking proximity to employment nodes. Monetary Authority of Singapore loan-to-value macroprudential caps filter speculative leverage capacity while preserving owner-occupier access. Mass engineered timber construction is compressing delivery timelines in Queenstown and Tiong Bahru regeneration zones.
Outside Central Region
Executive condominiums bridge public and private tenure with resale restrictions and CPF housing grant enhancement. Government Land Sales programme releases in Tampines and Jurong West are accommodating build-to-rent formats for expatriate segments. Industrial land reclassification is enabling logistics facility development along the western corridor.
Greater Southern Waterfront
Port land releases under the Government Land Sales programme are triggering mixed-use regeneration with integrated transport nodes. Building and Construction Authority Green Mark standards shape permissible density and sustainability benchmarks across redevelopment timelines. Keppel and Tanjong Pagar terminal precincts are converting to residential, commercial and recreational uses.
Western Industrial Corridor
Data centre zoning liberalisation is enabling hyperscale facility development in Tuas and Jurong Innovation District. The Urban Redevelopment Authority cooling measures recalibrate speculative investment patterns while preserving institutional capital flows. Jurong Rock Caverns and adjacent precincts are attracting logistics and advanced manufacturing operations.
Singapore Real Estate Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated developers commanding premium positioning in mixed-use schemes while pure-play agencies compete on transaction velocity. The market structure concentrates around five dominant archetypes: diversified property conglomerates with REIT platforms, integrated developers controlling design-to-asset-management value chains, transaction-focused agency networks, technology-enabled marketplace operators, and sovereign-linked entities preserving trophy assets. Strategic moves center on mass engineered timber adoption for carbon footprint compression and build-to-reent format expansion for flexible tenure capture.
Within the integrated development tier, City Developments Limited exemplifies cost control across design, construction and asset management phases, while CapitaLand Investment Limited anchors portfolio stability through REIT-based capital recycling. Frasers Property occupies a position competing on build-to-rent and business park formats that address evolving occupier requirements for hybrid-work infrastructure.
| Leading Market Players |
|---|
| City Developments Limited |
| UOL Group |
| PropNex Realty |
| 99 Group |
| Huttons Asia |
| ERA Realty Network |
| Frasers Property |
| OrangeTee & Tie |
| CapitaLand Investment Limited |
| Others |
Value Chain & Pricing Dynamics
Mass engineered timber adoption is compressing construction cost curves while concentrating procurement relationships with certified suppliers in Malaysia and Indonesia. This structural shift simultaneously reduces embodied carbon exposure for developers and tightens supplier qualification requirements, embedding pricing power with early-movers who secured cross-laminated timber offtake agreements.
Pricing Analysis
Volume concentrates in HDB and mid-range private residential where thin margins reward construction efficiency; premium margins sit with Core Central Region luxury stock where brand premiums and scarcity rents dominate. Three-tier pricing structure across premium, standard, and economy levels reflects Green Mark certification tiers, locational amenity density, and developer track record. Cost compression in mid-rise commercial segments is intensifying because mass timber fabrication shortens on-site assembly duration. Foreign buyers in luxury condominiums exhibit lowest price sensitivity; HDB upgraders in executive condominiums face highest sensitivity to mortgage rate movements.
Supply Chain Analysis
Direct-to-project procurement channels handle hyperscale developer demand for structural timber systems and prefabricated modules. Malaysia, Indonesia, and Vietnam anchor regional supply for engineered timber and construction-grade steel. Project timelines hinge on shipping volatility through the Strait of Malacca and port clearance efficiency at Tuas Mega Port. Distribution runs through vertically integrated developers who control design-to-delivery workflows, reducing subcontractor fragmentation exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore real estate is consolidating around developers with integrated execution capabilities as cooling measures and sustainability mandates filter speculative capital. The Monetary Authority of Singapore leverage restrictions are accelerating exits by undercapitalized land bankers.
For Market Incumbents: Cement defensible positioning through captive supply agreements for mass engineered timber and cross-laminated timber fabrication capacity in Johor Bahru. Control distribution channels by acquiring strata management platforms that govern retrofit execution in ageing commercial stock. Green Mark certification backlogs at the Building and Construction Authority threaten project marketing timelines; preemptive submission staffing reduces regulatory friction. For New Entrants and Emerging Players: Build-to-rent operators represent the most penetrable segment, with expatriate demand in Tampines and Jurong West outpacing institutional supply. Target Government Land Sales programme sites zoned for flexible tenure models where CapitaLand Investment and Frasers Property have limited build-to-rent exposure. Partner with co-living platform operators to secure pre-leasing velocity before construction completion. For Investors and Strategic Acquirers: Exit pathways concentrate in REIT stapled security structures and sovereign-linked entity portfolio rotations. Long-term viability favors developers with integrated design-construction-asset management capabilities and established timber supply chains. Monitor Building and Construction Authority Green Mark assessment queue lengths as an inflection indicator for project marketing delays and occupancy commencement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Engineered Timber Integration | Cross-laminated timber adoption compresses construction timelines thirty percent while satisfying institutional ESG screening. |
| Build-to-Rent Format Expansion | Flexible tenure models capture expatriate segments underserved by traditional strata ownership structures. |
| Green Mark Certification Pre-Submission | Early BCA engagement reduces assessment backlogs that delay project marketing and occupancy commencement. |
| Greater Southern Waterfront Site Acquisition | Port land releases under Government Land Sales trigger mixed-use regeneration with integrated transport nodes. |
| REIT Platform Capital Recycling | Stapled security structures provide retail investor liquidity depth absent in private direct ownership markets. |
Study Parameters
Urban Redevelopment Authority land release schedules, Building and Construction Authority Green Mark certification databases, and Monetary Authority of Singapore macroprudential policy circulars formed the secondary backbone. Primary interviews with property development executives, REIT portfolio managers, construction procurement leads, and strata management operators validated demand assumptions. Bottom-up site-level absorption data and top-down institutional capital flow estimates were triangulated to anchor market sizing.
Bottom-up modeling tracked individual Government Land Sales site transactions, construction commencement permits, and occupancy certificate issuance across the projection horizon. Segmentation dimensions included property type, investment vehicle structure, buyer profile eligibility, and price tier alignment. CAGRs were derived from rolling average absorption rates adjusted for cooling measure elasticity and technology sector employment growth. Forecast inputs incorporated mass engineered timber adoption curves and data centre zoning liberalization timelines.
Caveats apply where Monetary Authority of Singapore loan-to-value adjustments or Urban Redevelopment Authority cooling measure recalibrations could materially shift the outlook. Forecasts reflect assumptions regarding technology sector regional headquarters mandates and port land release schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market