
 Remote Sensing Technology Market | 2026-2036
Remote Sensing Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Sensing Technology Market Intelligence
The ISO 19115 metadata standard is collapsing the barriers between disparate geospatial datasets, enabling greater interoperability. Hexagon AB leverages its comprehensive software and sensor portfolio to serve multiple end-user segments. Maxar Technologies, Inc. differentiates through its high-resolution satellite constellation and advanced analytics capabilities. Planet Labs, Inc. operates a large fleet of Earth-imaging satellites, providing daily global coverage.
Remote sensing technology involves acquiring information about an object without physical contact, typically from satellites or aircraft. These systems use sensors to detect electromagnetic radiation reflected or emitted from the Earth's surface at specific wavelengths. Satellite-based deployment commands the largest share, but the UAV segment is expanding rapidly due to lower operational costs. Among technologies, LIDAR and Hyperspectral Imaging are increasingly preferred over RADAR for precision-focused applications like forestry.
The US Federal Aviation Administration (FAA) governs commercial UAV operations, impacting airborne data collection. In parallel, the EU Green Deal and China's dual carbon goals create significant demand for environmental monitoring services. National data sovereignty laws increasingly dictate how satellite imagery is stored and processed across borders. Stakeholders must navigate this evolving regulatory landscape to maintain market access and operational continuity.
Market Dynamics
The convergence of sensor miniaturization with the expansion of cloud-based analytics is the central force shaping the remote sensing technology market. This dynamic enables the deployment of sophisticated sensors like hyperspectral imagers on cost-effective platforms, broadening access to actionable geospatial intelligence.
Growth Catalysts
- Policy-Driven Environmental Monitoring:The EU Green Deal and China's dual carbon goals create regulatory mandates for monitoring emissions, land use change, and ecosystem health, directly stimulating demand for satellite and airborne observation services.
- Sensor Technology Advancement:The miniaturization of hyperspectral and LIDAR sensors allows for their integration onto smaller, more agile UAVs, lowering operational costs and opening new applications in precision agriculture and infrastructure inspection.
- Agricultural Modernization in Brazil:Concentrated demand from Brazil's large-scale agribusiness sector for precision agriculture applications, including crop health monitoring and yield optimization, provides a significant and focused growth engine.
Market Restraints
- Data Sovereignty Regulations:Increasingly stringent national laws governing the cross-border transfer and storage of geospatial data create significant compliance burdens and operational complexity for global satellite operators.
- High Satellite Constellation Costs:The substantial capital investment required to build, launch, and maintain constellations of high-resolution imaging satellites presents a formidable barrier to entry for new competitors.
- Atmospheric and Weather Limitations:Optical and hyperspectral sensors are constrained by cloud cover, smoke, and other atmospheric conditions, limiting their reliability for time-sensitive monitoring applications in certain climates.
Strategic Opportunities
- Insurance and Risk Modeling:Applying remote sensing data for automated post-disaster damage assessment and parametric insurance products represents a significant, underpenetrated commercial application.
- Fusion of LIDAR and Hyperspectral Data:Combining 3D structural data from LIDAR with the material identification capabilities of hyperspectral imaging can create advanced analytics for forestry management, urban planning, and mineral exploration. *Coastal and Maritime Surveillance: Southeast Asian nations offer a key opportunity for monitoring illegal fishing, piracy, and marine pollution, applications where wide-area satellite surveillance provides unique value.
Industry Challenges
- Data Processing and Storage Bottlenecks:The sheer volume and velocity of data generated by modern satellite fleets present a major challenge, requiring massive investment in scalable ground infrastructure and automated processing pipelines.
- Geospatial Analytics Talent Gap:A persistent shortage of data scientists and analysts with the specialized skills to interpret complex, multi-source remote sensing data limits the ability of end-users to extract full value.
- Integration with Enterprise Systems:End-users face difficulties integrating diverse geospatial data formats, despite the ISO 19115 standard, into existing enterprise resource planning (ERP) and business intelligence (BI) workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Sensing Technology Market |
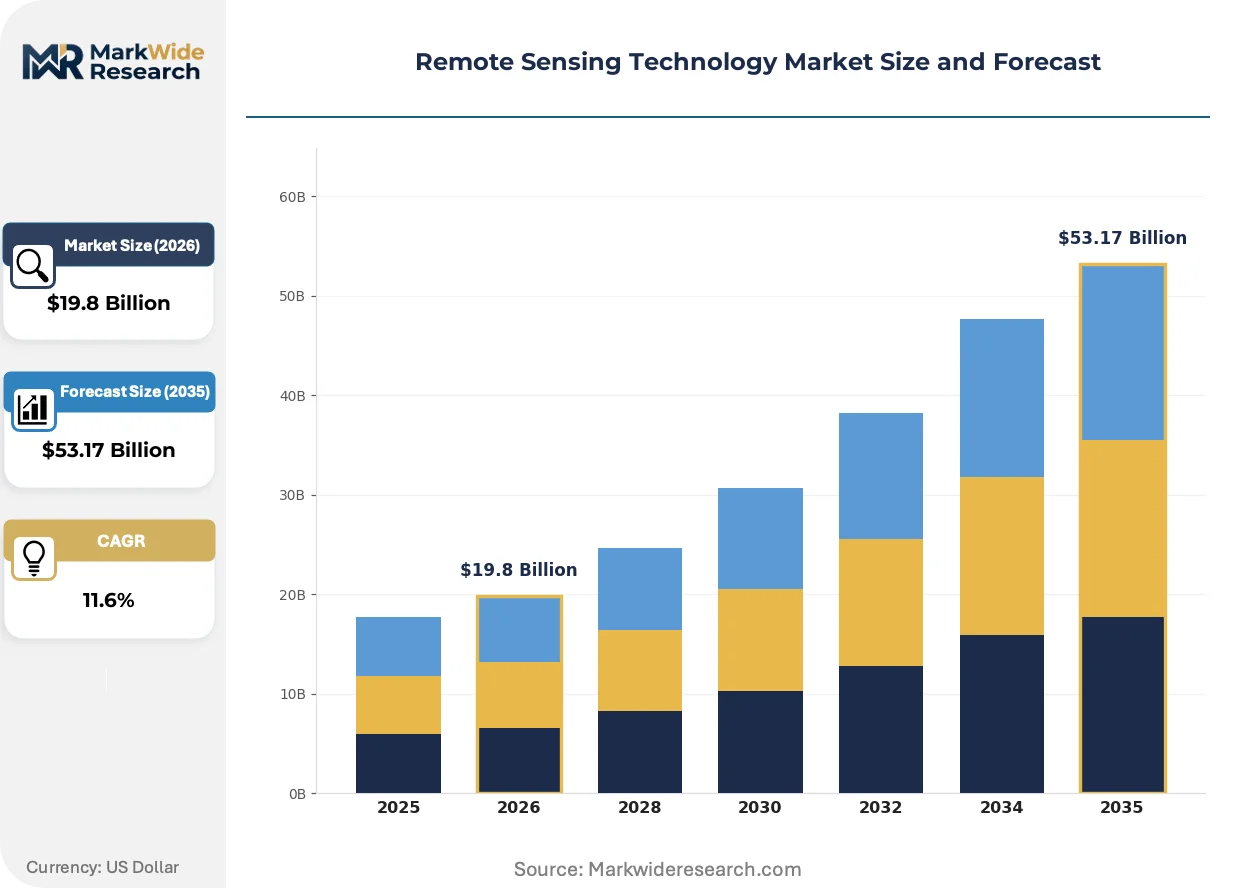
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $53.17 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LIDAR, RADAR, Hyperspectral Imaging, Multispectral Imaging, Thermal Imaging, Ultrasonic Sensors Application: Environmental Monitoring, Disaster Management, Resource Exploration, Precision Agriculture, Urban Planning, Archaeology Deployment: Satellite, Airborne, Ground-Based, UAV, Balloon, High-Altitude Platform End User: Government Agencies, Research Institutions, Energy Companies, Construction Firms, Defense Organizations, Conservation Groups |
| Companies Covered | Northrop Grumman Corporation, Planet Labs, Inc., Honeywell International, Inc., Hexagon AB, Thales Group S.A., Lockheed Martin Corporation, Maxar Technologies, Inc., Teledyne Technologies, Inc., General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Sensing Technology Market Strategic Shifts & Innovations
The market's primary evolution is from the sale of raw imagery toward the delivery of integrated, subscription-based analytical insights. This shift places a premium on software capabilities, AI-driven data fusion, and platform-based delivery models that embed geospatial intelligence directly into customer workflows.
AI-powered sensor fusion combines inputs from disparate sources like RADAR, LIDAR, and optical imagery into a single, cohesive intelligence product. Sectors such as defense and large-scale agriculture are adopting this technology to gain a more complete operational picture. This trend is decomposing the siloed nature of remote sensing data, forcing a move toward unified, multi-modal information platforms rather than discrete imagery files.
New rules from regulators like the US Federal Aviation Administration (FAA) governing Beyond Visual Line of Sight (BVLOS) flights are a critical enabler. This regulatory evolution significantly expands the geographic area and economic viability of using UAVs for applications like pipeline, powerline, and railway monitoring. The airborne data collection segment, particularly service providers focused on linear infrastructure, is positioned to benefit directly from these expanded operational freedoms.
A definitive behavioral change is the move away from transactional, project-based imagery acquisition toward subscription-based Data-as-a-Service (DaaS) models. This disrupts the traditional sales cycle by providing customers with continuous access to updated imagery and analytics via APIs. The shift is most pronounced in the environmental monitoring and financial services industries, where access to timely, ongoing data streams is paramount for decision-making.
Remote Sensing Technology Market Segmentation
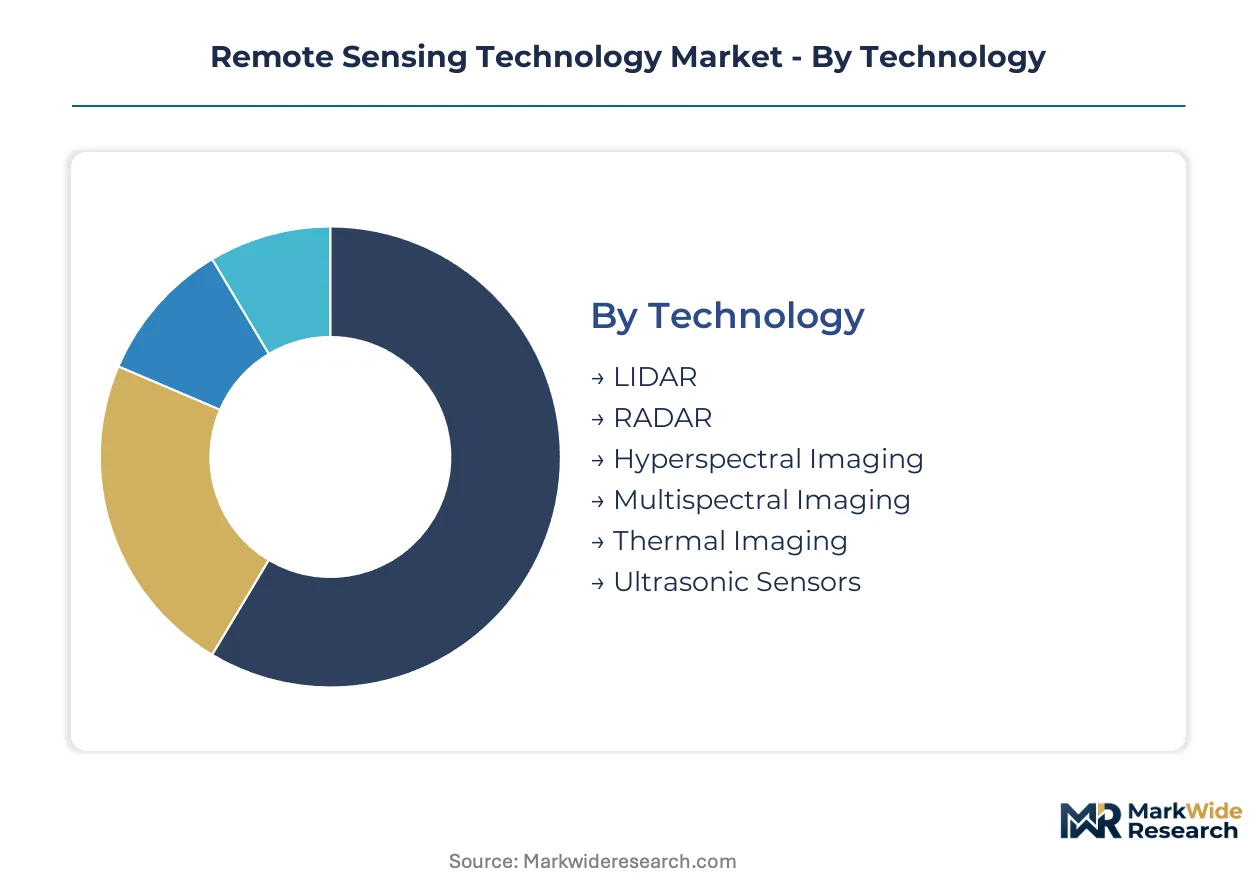
The remote sensing technology market exhibits diverse characteristics across its operational and functional segments. Understanding these distinctions allows stakeholders to identify specific value propositions and target emerging demand clusters. This granular view reveals where technological advancements are driving new applications and where established methods retain market dominance.
Technology:
The selection of remote sensing technology often dictates the data acquisition channel, influencing platform choice and analytical workflow. Different sensor types are optimized for specific environmental conditions and data requirements, shaping the overall solution architecture.
- LIDAR:This active remote sensing technology emits laser pulses to measure distance and create highly accurate 3D representations of terrain and objects. Demand concentrates in forestry management and urban planning, where precise elevation models are critical for infrastructure development and resource assessment.
- Hyperspectral Imaging:These sensors capture continuous spectral information across hundreds of narrow bands, enabling detailed material identification and compositional analysis. Miniaturization allows deployment on smaller UAVs, broadening accessibility for precision agriculture applications like crop health monitoring.
- RADAR:An active sensing system using radio waves for all-weather, day-and-night imaging, crucial for defense and maritime surveillance.
- Multispectral Imaging:Captures data across discrete spectral bands, offering cost-effective solutions for broad-area environmental monitoring and land-use mapping.
- Thermal Imaging:Detects infrared radiation for temperature mapping, heat loss detection, and monitoring volcanic activity.
- Ultrasonic Sensors:Employ sound waves for short-range distance measurement and object detection in ground-based industrial inspection.
By volume, RADAR leads due to its long-standing defense applications. By growth pace, Hyperspectral Imaging is ahead, driven by sensor miniaturization and new analytical capabilities.
Application:
The cost structure of remote sensing solutions varies significantly by application, depending on the required data resolution, revisit rates, and analytical complexity. High-precision applications often command premium pricing for specialized data products.
- Environmental Monitoring:This application involves tracking changes in ecosystems, climate, and pollution levels using satellite and airborne sensors. Policy mandates like the EU Green Deal and China's dual carbon goals create significant demand for continuous, large-scale observation services.
- Precision Agriculture:Remote sensing data guides optimized resource use in farming, including variable rate fertilization, irrigation, and pest detection. Brazil's large-scale agribusiness sector represents a concentrated growth engine, leveraging satellite and UAV imagery for yield optimization.
- Disaster Management:Utilizes rapid-response imagery for damage assessment, emergency planning, and post-event recovery efforts following natural catastrophes.
- Resource Exploration:Employs geological mapping and analysis to identify potential deposits of minerals, oil, and gas, reducing exploratory drilling costs.
- Urban Planning:Provides geospatial data for infrastructure development, population density analysis, and monitoring urban sprawl in rapidly expanding cities.
- Archaeology:Leverages LIDAR and other sensors to discover and map ancient structures and landscapes hidden beneath vegetation or soil, aiding cultural preservation.
Environmental Monitoring contributes the largest value, driven by regulatory compliance. Precision Agriculture shows the strongest volume expansion, particularly in emerging markets.
Deployment:
The choice of deployment platform is often dictated by the end-user's operational requirements, budget constraints, and the specific geographic scope of data collection. Each platform offers distinct advantages in terms of coverage, resolution, and revisit frequency.
- Satellite:Orbiting Earth, satellites provide wide-area coverage and frequent revisits, making them ideal for large-scale environmental monitoring and global intelligence gathering. Maxar Technologies and Planet Labs operate extensive constellations, serving diverse government and commercial clients with high-resolution imagery.
- UAV:Unmanned Aerial Vehicles offer high-resolution, on-demand data collection over smaller areas with lower operational costs compared to traditional aircraft. Regulatory evolution from the US FAA regarding BVLOS flights significantly expands their economic viability for linear infrastructure inspection.
- Airborne:Manned aircraft carry specialized sensors for high-resolution surveys, often used for detailed mapping projects and infrastructure inspection over specific regions.
- Ground-Based:Fixed or mobile sensors collect highly localized data, frequently employed for structural health monitoring, industrial inspection, and localized environmental assessments.
- Balloon:High-altitude balloons provide cost-effective, persistent surveillance over regional areas, often used for atmospheric research and temporary communication relays.
- High-Altitude Platform:These near-space vehicles offer persistent, quasi-stationary observation capabilities, bridging the gap between satellite and airborne systems for regional needs.
Satellite deployment represents the most mature segment, providing foundational data infrastructure. UAV deployment demonstrates significant innovation, continuously expanding its operational envelope and application scope.
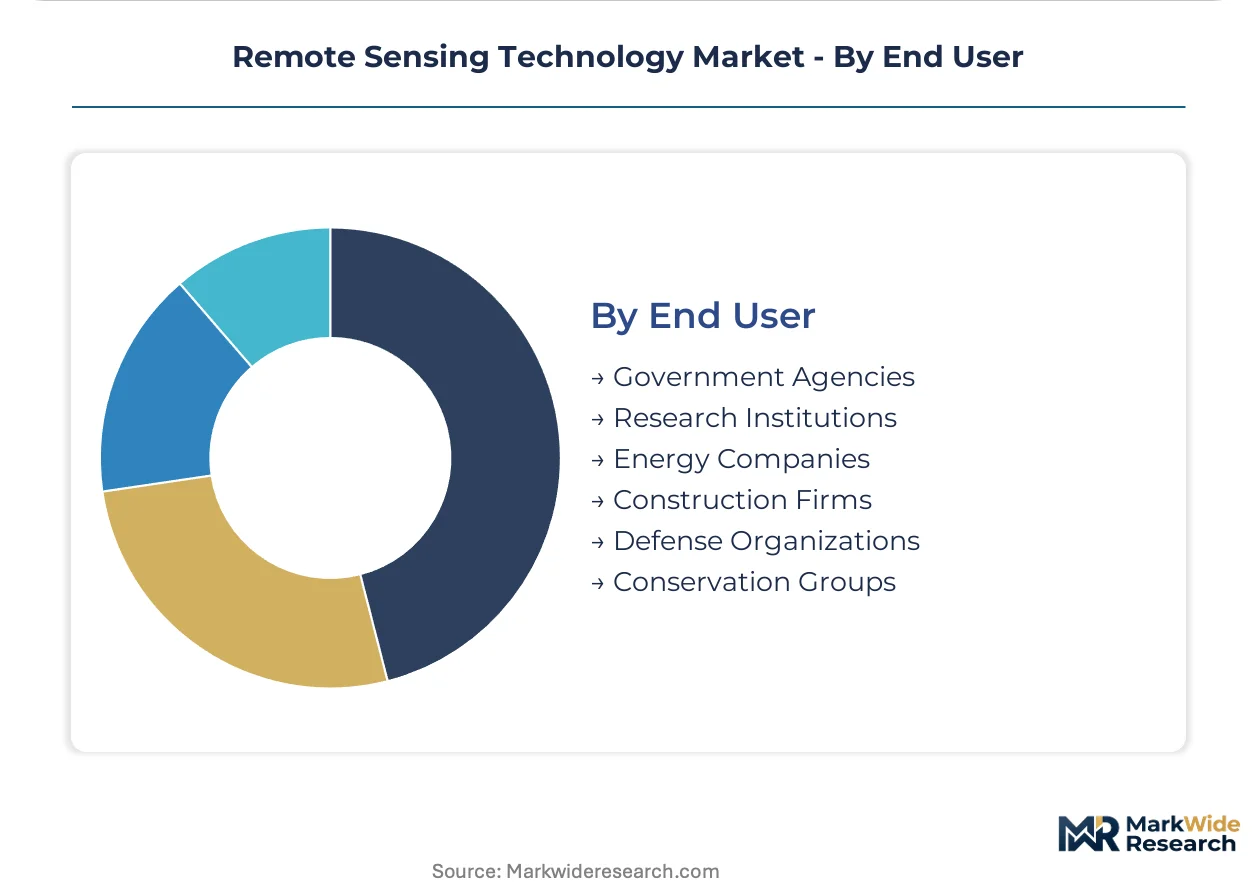
End User:
Supply of remote sensing data and analytics often concentrates around specific end-user requirements, with specialized providers tailoring solutions for distinct industry verticals. This specialization addresses unique data formats, security needs, and regulatory compliance within each sector.
- Government Agencies:These entities are major consumers of remote sensing data for national security, land management, disaster response, and environmental regulation. National data sovereignty laws increasingly dictate how satellite imagery is stored and processed for these critical public sector applications.
- Research Institutions:Universities and scientific organizations utilize remote sensing for climate modeling, ecological studies, and geological research, often driving advancements in sensor technology and analytical methodologies. The ISO 19115 standard facilitates data sharing among these academic bodies.
- Energy Companies:Employ remote sensing for pipeline monitoring, site selection for renewable energy projects, and environmental impact assessments in oil and gas operations.
- Construction Firms:Utilize geospatial data for site surveying, progress monitoring, and volumetric calculations on large-scale infrastructure projects, improving project efficiency.
- Defense Organizations:Rely on satellite and airborne intelligence for surveillance, reconnaissance, and target identification, crucial for strategic and tactical operations.
- Conservation Groups:Apply remote sensing to monitor deforestation, track wildlife, and assess biodiversity, supporting efforts in environmental protection and habitat preservation.
Demand from Government Agencies is globally distributed, reflecting national security and environmental mandates. Conservation Groups exhibit a strong focus on biodiversity hotspots in Southeast Asia and the Amazon basin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for remote sensing technology is evident in regions driving large-scale precision agriculture and environmental monitoring. These areas demand continuous, high-resolution data for informed decision-making. Policy mandates further stimulate market expansion across diverse geographies.
Brazil
Brazil's large-scale agribusiness drives significant demand for precision agriculture, including crop health monitoring and yield optimization. National environmental policies mandate extensive monitoring of deforestation and land use change. The agricultural heartland of Mato Grosso deploys satellite and UAV imagery for optimized resource management.
United States
The United States exhibits strong demand for remote sensing in defense, infrastructure inspection, and land management. The US Federal Aviation Administration (FAA) governs commercial UAV operations, expanding airborne data collection. Technology hubs like Silicon Valley foster innovation in sensor development and analytics platforms.
China
China's stringent dual carbon goals create substantial demand for environmental monitoring to track emissions and ecosystem health. Extensive urban planning and resource exploration projects also rely on geospatial data. Major industrial centers in the Yangtze River Delta utilize remote sensing for infrastructure development and pollution control.
Germany
Germany's commitment to the EU Green Deal drives demand for detailed environmental monitoring and sustainable land management. Precision forestry and urban planning require highly accurate 3D data from LIDAR systems. High-tech regions like Bavaria develop advanced remote sensing solutions for smart city initiatives and agricultural optimization.
India
India's vast agricultural sector and rapid infrastructure development fuel demand for remote sensing in crop health assessment and construction project monitoring. National disaster management agencies utilize satellite imagery for rapid damage assessment. Technology centers in Bengaluru and Hyderabad are hubs for geospatial data processing and analytics.
Remote Sensing Technology Market Key Industry Players
Player mix skews toward integrated solution providers and specialized data analytics firms rather than purely hardware manufacturers. The market structure is evolving from fragmented sensor sales to more consolidated platform-based offerings. Key strategic archetypes include satellite constellation operators, advanced sensor developers, and geospatial intelligence platforms. Companies are increasingly pursuing portfolio diversification and strategic partnerships to offer end-to-end solutions.
Specialists in Earth observation data and analytics include Planet Labs, Inc., which operates a large fleet of Earth-imaging satellites providing daily global coverage. This company exemplifies the data-as-a-service model, offering continuous access to updated imagery. Maxar Technologies, Inc. also occupies a significant position, known for its high-resolution satellite constellation and advanced analytics capabilities, representing a key player in critical intelligence provision. Hexagon AB, a Swedish multinational, exemplifies an integrated provider, leveraging its comprehensive software and sensor portfolio across multiple end-user segments, from geospatial to industrial applications.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Planet Labs, Inc. |
| Honeywell International, Inc. |
| Hexagon AB |
| Thales Group S.A. |
| Lockheed Martin Corporation |
| Maxar Technologies, Inc. |
| Teledyne Technologies, Inc. |
| General Dynamics Corporation |
| Others |
Cost & Logistics Intelligence
The ISO 19115 metadata standard gates both data supply qualification and price differentiation across geospatial datasets. This standardization reduces friction in data exchange, yet specialized data products command premium pricing.
Pricing Analysis
Cost-plus contract patterns, often indexed to satellite launch costs, define pricing for bespoke remote sensing projects. Price differentiation stems from data resolution and the complexity of analytics required. Pricing softness reflects increasing satellite capacity and the commoditization of raw imagery. Government agencies are generally less price-sensitive for critical intelligence, while conservation groups exhibit higher price sensitivity for environmental monitoring.
Supply Chain Analysis
Access to specialized sensor components, particularly high-performance optics, creates a chokepoint in the remote sensing supply chain. Supply concentration for advanced sensors lies primarily in the United States, with some manufacturing in Europe and Asia. Raw material dependencies include rare earth elements for sensor fabrication and specialized alloys for satellite structures. Single-source vulnerability for critical components poses a structural risk. Distribution runs through direct sales to large enterprise clients and API-based delivery for Data-as-a-Service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The remote sensing market offers a defensive moat, underpinned by the high switching costs associated with integrating complex geospatial data into enterprise workflows.
For Market Incumbents:Shield core satellite imagery contracts by investing heavily in AI-powered analytics platforms that embed geospatial intelligence directly into customer workflows. This strategy counters the threat of raw imagery commoditization. Leverage R&D in sensor fusion to offer comprehensive, multi-modal data products, solidifying market leadership against emerging competitors.
For New Entrants and Emerging Players:Anchor in niche, high-value applications like parametric insurance modeling, where underpenetration is significant and specialized analytics can command premium pricing. Target coastal and maritime surveillance in Southeast Asian nations, offering bespoke solutions for illegal fishing detection. A subscription-based Data-as-a-Service model for specific use cases provides a viable go-to-market angle.
For Investors and Strategic Acquirers:The US Federal Aviation Administration's (FAA) regulatory evolution regarding Beyond Visual Line of Sight (BVLOS) flights reshapes the acquisition landscape for UAV-centric data providers. Long-term viability rests on sustained demand from environmental monitoring and precision agriculture. Seek acquisition targets with strong AI-driven analytics capabilities and established platforms for sensor fusion. The signal to watch is further relaxation of BVLOS regulations in other key geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-powered Sensor Fusion Platforms | This initiative integrates disparate data sources, providing comprehensive intelligence for defense and agriculture. |
| Expand Subscription-Based Data-as-a-Service (DaaS) Offerings | Shifting to DaaS models provides continuous revenue streams and embeds intelligence into customer workflows. |
| Invest in Miniaturized Hyperspectral Sensor R&D | Smaller sensors enable broader deployment on UAVs, opening new precision agriculture applications. |
| Forge Strategic Partnerships with Cloud Analytics Providers | These partnerships address data processing bottlenecks and enhance scalability for geospatial intelligence. |
| Target Emerging Markets for Precision Agriculture Solutions | Brazil's agribusiness sector offers concentrated demand for yield optimization and crop health monitoring. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market reports anchors the qualitative findings of this analysis. This includes insights from satellite operators, sensor manufacturers, geospatial data scientists, and agricultural technology developers. Secondary data sources encompass governmental reports from the FAA and the EU, academic journals, company financial filings, and remote sensing technology whitepapers, all triangulated with bottom-up market sizing and top-down validation.
Sensitivity analysis informed the forecast framework, projecting market evolution across the analysis window. The model incorporates segmentation dimensions including technology, application, deployment, end-user, and regional policy mandates. Compound annual growth rates were derived from historical growth trends and anticipated technological advancements. Key industry-specific forecast inputs include satellite launch schedules and UAV regulatory changes.
Material uncertainties — including unforeseen geopolitical shifts or rapid sensor commoditization — sit outside the modeled envelope, influencing market trajectory. Forecasts reflect assumptions regarding regulatory stability and sustained investment in space infrastructure. Practitioners should keep alternative scenarios live as global environmental policy and technological innovation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Eye Tracking Market
Sensors
Facial Tracking Solution Market
Sensors
Industrial Barcode Scanners Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Connected Smart Thermostats Market
Sensors
APAC Wireless Sensors Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Smart Barcode Readers Market
Sensors
Voice Sounders Market
Sensors
Europe Lidar Market
Sensors
Machine Health Monitoring Market
Sensors
Alcohol Sensor Market
Sensors
Automated Weather Observation System Market
Sensors
Barcode Scanner Market
Sensors
Digital Direction Finder Market
Sensors
Bluetooth Photo Capture Device Market