
 Machine Health Monitoring Market | 2026-2036
Machine Health Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Health Monitoring Market Analysis
Mid-sized manufacturing plants is rotating toward subscription-based predictive maintenance platforms, displacing traditional reactive service contracts. SKF AB leverages its bearing diagnostics heritage to anchor condition monitoring sensor deployments across European automotive lines. Honeywell International Inc. competes through integrated software platforms that unify vibration data with building management systems. Rockwell Automation Inc. dominates North American factory floors by extending its control-system footprint into edge analytics hardware.
Machine health monitoring encompasses the continuous acquisition and analysis of mechanical, thermal, and lubricant condition indicators to preempt equipment failure. Systems typically sample vibration at 10 kHz or higher, process spectral signatures through FFT algorithms, and trigger maintenance workflows when ISO 10816 velocity thresholds breach programmable limits. Vibration analysis leads installed technology bases due to decades of standardized transducer availability and interpretive maturity. Oil analysis represents the fastest-growing diagnostic category as particle spectroscopy costs decline and hydraulic system criticality rises in wind turbine and mining applications. Predictive maintenance solutions capture disproportionate margin pools because they bundle recurring software licenses with proprietary failure-mode libraries.
OSHA machinery safety directives and EPA emissions enforcement both elevate the cost of unplanned downtime, tightening compliance linkages to monitoring infrastructure. ISO 17359 condition monitoring standards shape product certification requirements and cross-border procurement specifications. FDA quality system regulations for pharmaceutical manufacturing equipment further specify validated monitoring protocols. Stakeholders must weigh captive sensor development against platform partnerships as data ownership clauses become the decisive contract term.
Market Dynamics
Industrial IoT sensor networks and cloud-native analytics platforms are compressing the interval between data acquisition and maintenance action, forcing incumbent vendors to re-architect hardware-software bundles around subscription economics.
Growth Catalysts
- OSHA machinery safety enforcement:Rising penalties for unplanned equipment failures in US manufacturing plants are accelerating capital allocation toward continuous vibration monitoring systems.
- Wind turbine hydraulic criticality:Offshore wind installations in the North Sea are expanding oil analysis programs as particle spectroscopy costs decline and gearbox reliability becomes a revenue-critical variable.
- Edge computing hardware:On-premise FFT processing at 10 kHz sampling rates is eliminating latency bottlenecks that previously forced maintenance decisions into batch workflows.
Market Restraints
- MEMS accelerometer supply concentration:Taiwan-based foundry capacity constraints are creating 12-16 week lead times for vibration transducers rated above 100°C operating temperature.
- ISO 17359 certification complexity:Cross-border procurement specifications require redundant testing protocols that extend product validation cycles by 8-14 months for non-European suppliers.
- Manual inspection persistence:Smaller metal fabrication shops continue to rely on scheduled walk-around programs rather than automated monitoring due to upfront sensor installation costs.
Strategic Opportunities
- India PLI scheme for capital goods:Domestic manufacturing incentives are creating localized demand for condition monitoring systems as automotive and textile clusters expand capacity.
- Digital twin convergence:Physics-based equipment models fused with real-time sensor streams are enabling prescriptive maintenance that extends asset life beyond traditional predictive thresholds.
- Pharmaceutical FDA validation protocols:Quality system regulations for aseptic processing equipment are mandating documented monitoring trails that favor integrated platform vendors over point-solution providers.
Industry Challenges
- Vibration analyst skill scarcity:Interpreting spectral signatures against ISO 10816 velocity thresholds requires specialized training that outpaces vocational program output in Midwestern US manufacturing hubs.
- Legacy control system integration:Brownfield installations running proprietary PLC protocols demand costly gateway hardware to normalize data streams for cloud analytics ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Health Monitoring Market |
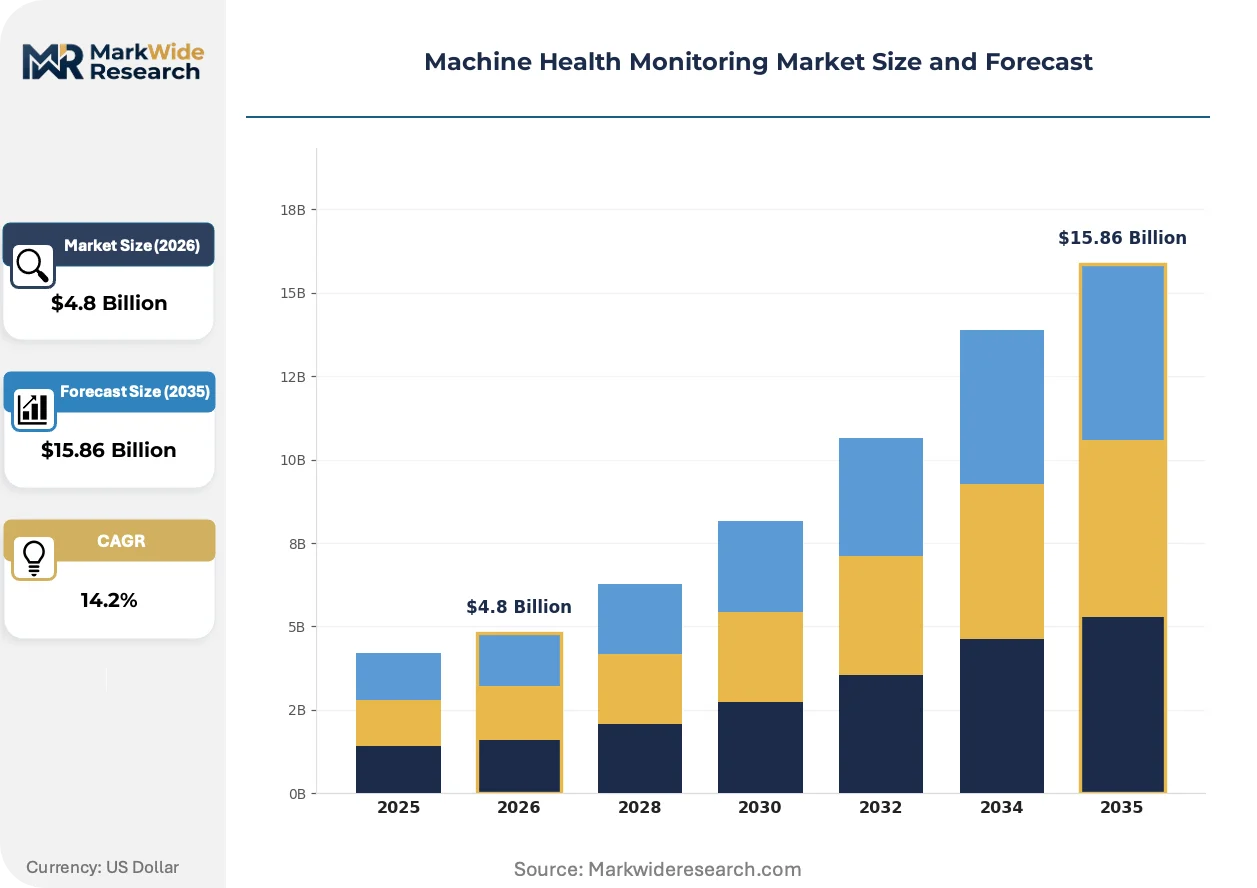
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vibration Analysis, Thermography, Ultrasonic Testing, Oil Analysis Product Type: Condition Monitoring Sensors, Predictive Maintenance Solutions, Software Platforms, Cloud Services End User: Manufacturing Plants, Oil & Gas Industry, Aerospace Sector, Power Generation Facilities Installation: On-Premise, Cloud-Based, Hybrid Solutions, Remote Monitoring |
| Companies Covered | Emerson Electric Co., Honeywell International Inc., SKF AB, General Electric, Siemens AG, ABB Ltd., Rockwell Automation Inc., National Instruments, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Health Monitoring Market Emerging Trajectories
Machine health monitoring architectures are splitting between high-frequency edge processing for safety-critical assets and low-cost cloud telemetry for non-rotating equipment, creating divergent vendor specialization paths.
Wireless vibration sensors operating on LoRaWAN and private 5G networks are bifurcating the installed base. Food and beverage processors with washdown requirements are adopting IP69K-rated battery-powered units at triple the pace of general manufacturing. This shift is compressing the addressable market for traditional wired accelerometer suppliers while expanding the serviceable market for industrial connectivity specialists.
EU CSRD sustainability disclosure mandates are forcing asset-intensive manufacturers to document equipment efficiency and failure rates as Scope 3 emissions inputs. German automotive suppliers are responding by embedding energy consumption metrics alongside traditional mechanical condition indicators in their monitoring dashboards. The regulation is accelerating consolidation around platforms that can correlate vibration data with kilowatt-hour telemetry.
Maintenance procurement in North American discrete manufacturing is fragmenting from bundled OEM service contracts toward unbundled software subscriptions. Tier-two automotive stampers are purchasing vibration analytics licenses separately from sensor hardware, then sourcing installation from regional system integrators. This pattern is most pronounced in Michigan and Ohio, where supplier diversity requirements and cost transparency pressures are dismantling traditional single-source relationships.
Machine Health Monitoring Market Segmentation
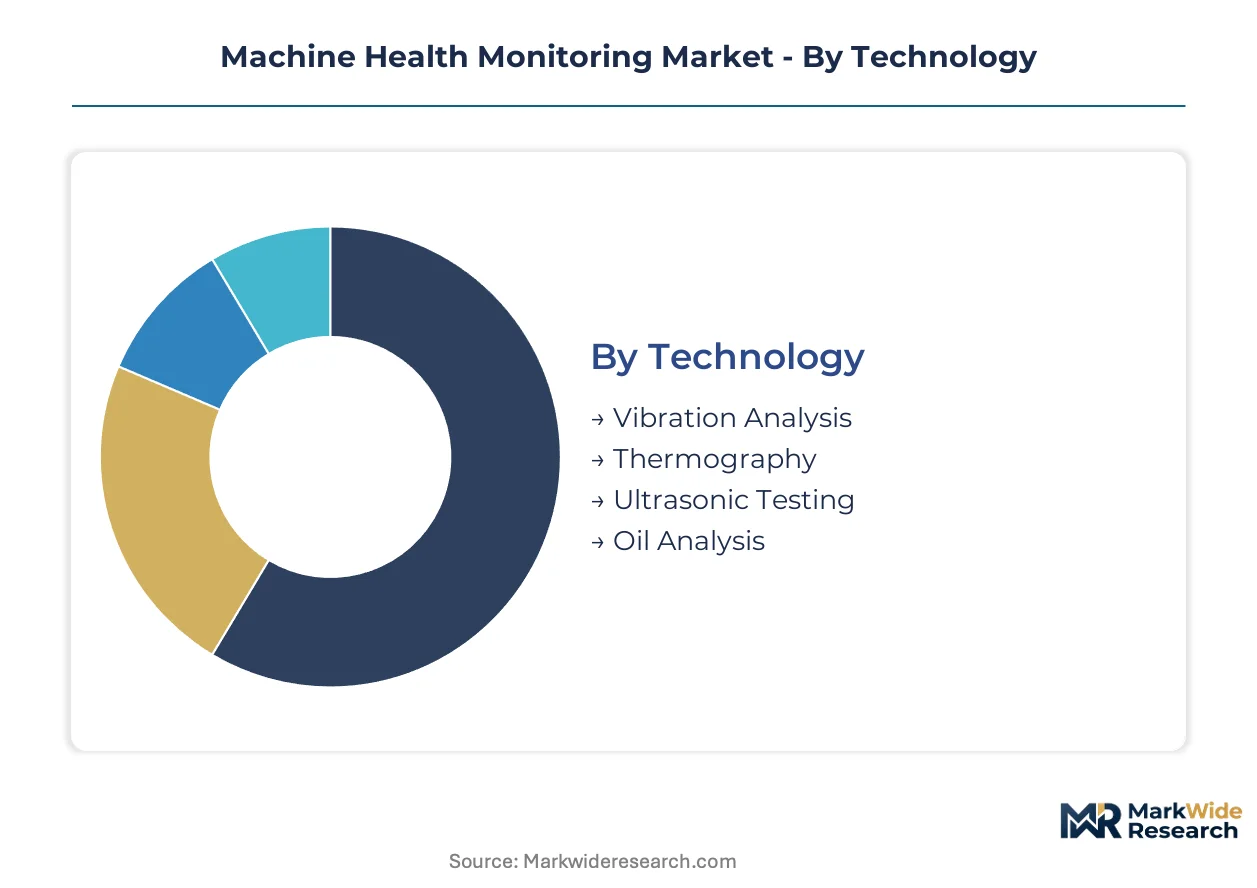
Machine health monitoring systems fragment across technology maturity, deployment economics, and regulatory compliance requirements. Understanding these divisions reveals where capital concentrates and where subscription models displace capital expenditure.
Technology:
Regulatory differentiation separates proven methods with ISO certification from emerging diagnostics still seeking standardization.
- Vibration Analysis:FFT-based spectral processing at 10 kHz sampling rates dominates installed bases due to decades of transducer standardization and ISO 10816 velocity threshold interpretation. Manufacturing plants in Germany and the United States anchor demand as OSHA machinery safety enforcement tightens and automotive lines prioritize bearing reliability.
- Oil Analysis:Particle spectroscopy and lubricant degradation monitoring are climbing the fastest as hydraulic system criticality rises in offshore wind turbines and mining haul trucks. North Sea wind installations drive adoption where gearbox failures carry severe revenue penalties.
- Thermography:Infrared thermal imaging detects electrical connection degradation and bearing friction anomalies through non-contact temperature mapping.
- Ultrasonic Testing:High-frequency acoustic emission monitoring identifies early-stage crack propagation and leak detection in pressurized systems.
Established volume favors Vibration Analysis; emerging adoption favors Oil Analysis.
Product Type:
Customer procurement patterns now split between hardware ownership and recurring software licenses.
- Predictive Maintenance Solutions:Bundled offerings combining sensor hardware with proprietary failure-mode libraries and cloud analytics capture disproportionate margin pools through recurring revenue structures. Mid-sized manufacturing plants in Michigan and Ohio are unbundling these from traditional OEM service contracts.
- Condition Monitoring Sensors:Wired accelerometers, temperature probes, and oil debris sensors constitute the physical data acquisition layer with standardized 4-20mA and digital outputs.
- Software Platforms:Analytics engines normalizing multi-sensor streams into maintenance workflows compete on integration depth with building management and ERP systems.
- Cloud Services:Scalable data storage and compute resources enable smaller facilities to access enterprise-grade diagnostics without on-premise infrastructure investment.
Hardware ownership concentrates in Condition Monitoring Sensors; recurring revenue expansion centers on Predictive Maintenance Solutions.
End User:
Asset criticality and downtime cost structures determine monitoring sophistication and deployment urgency.
- Manufacturing Plants:Discrete and process manufacturing facilities deploy the broadest sensor arrays as predictive maintenance replaces scheduled downtime protocols. Automotive stamping lines and food processing washdown environments drive divergent form-factor requirements.
- Power Generation Facilities:Combined-cycle gas turbines and hydroelectric generators demand continuous monitoring to maintain grid reliability commitments and avoid regulatory penalties.
- Oil & Gas Industry:Upstream drilling equipment and downstream refining assets operate in hazardous classification zones requiring explosion-proof sensor housings.
- Aerospace Sector:Engine test cells and airframe assembly lines apply monitoring to tooling and ground support equipment rather than flight-certified components.
Deployment breadth favors Manufacturing Plants; specification stringency favors Power Generation Facilities.
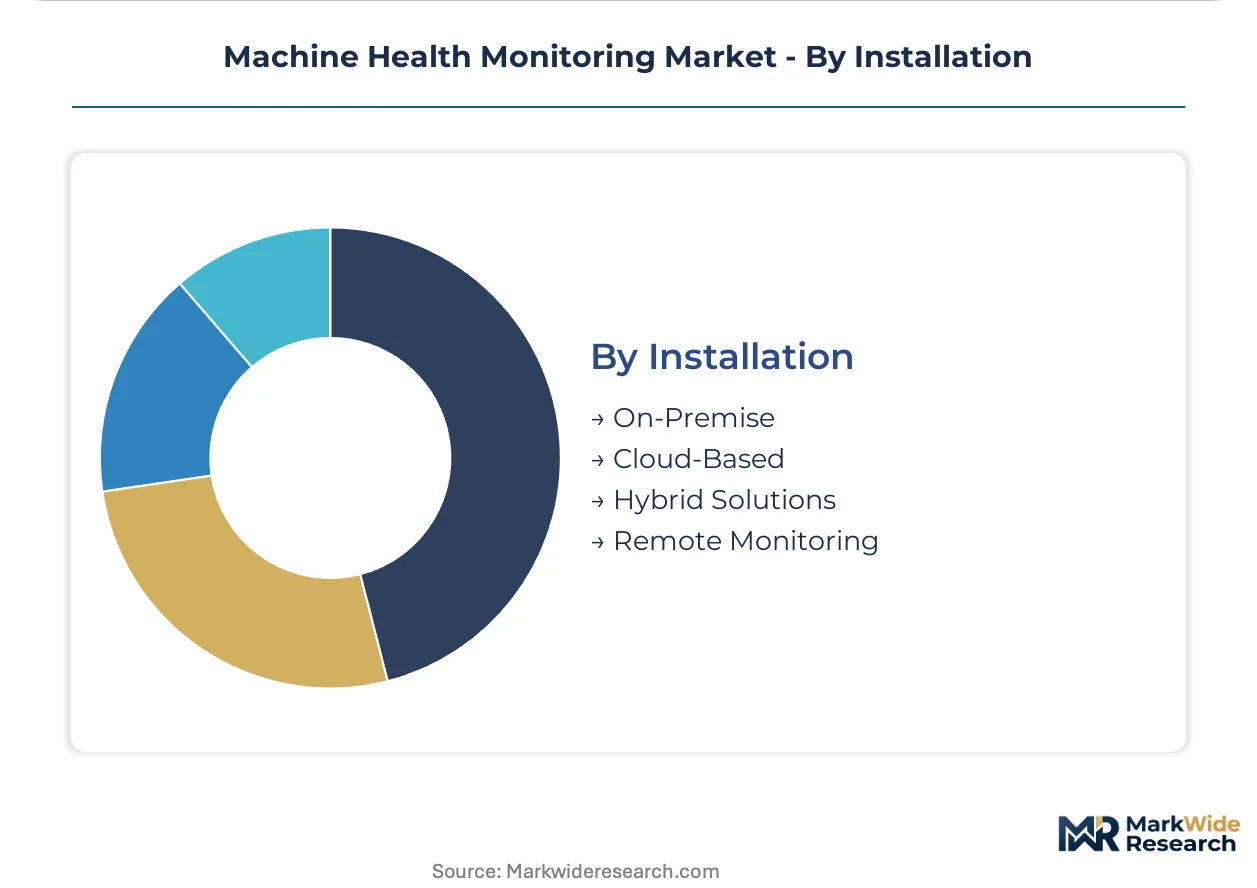
Installation:
Latency requirements and data sovereignty concerns shape architecture selection between edge and cloud processing.
- On-Premise:Local FFT processing and historian databases serve safety-critical assets where sub-second response times trigger automated shutdown sequences. Edge computing hardware eliminates cloud latency for vibration thresholds.
- Cloud-Based:Centralized analytics platforms aggregate data across distributed asset fleets, enabling cross-site benchmarking and machine learning model training.
- Hybrid Solutions:Tiered architectures process high-frequency safety data locally while streaming aggregated metrics to cloud dashboards for maintenance planning.
- Remote Monitoring:Third-party service providers assume operational responsibility for sensor health and alert triage, common in wind turbine and pipeline applications.
Control-system integration favors On-Premise; fleet-scale optimization favors Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sensor manufacturers export predictive maintenance hardware to automotive clusters in the United States and China, establishing the primary trade-flow corridor for vibration analysis systems. Factory automation intensity in these buyer markets drives equipment reliability investments. Regulatory enforcement across multiple jurisdictions tightens compliance linkages to monitoring infrastructure.
United States
OSHA machinery safety enforcement is accelerating capital allocation toward continuous vibration monitoring in Midwestern automotive stamping plants. The EPA emissions enforcement framework elevates unplanned downtime costs for power generation facilities. Michigan and Ohio supplier diversity requirements are dismantling traditional single-source maintenance contracts.
Germany
EU CSRD sustainability disclosure mandates force asset-intensive manufacturers to document equipment efficiency as Scope 3 emissions inputs. The CE marking framework and ISO 17359 condition monitoring standards shape product certification requirements. Bavarian automotive suppliers embed energy consumption metrics alongside mechanical condition indicators in monitoring dashboards.
China
MIIT industrial internet policies accelerate cloud-native analytics platform deployment across Yangtze River Delta manufacturing bases. GB standards and dual carbon goals tighten energy efficiency monitoring requirements for heavy industry. Shenzhen and Shanghai factory automation intensity drives sensor-to-decision timeline compression.
India
PLI scheme incentives for capital goods create localized demand as automotive and textile clusters expand capacity. BIS certification requirements and CEA power sector regulations elevate monitoring infrastructure for grid-connected industrial assets. Gujarat and Maharashtra manufacturing plants rotate toward subscription-based predictive maintenance platforms.
Japan
METI smart factory initiatives promote edge computing hardware adoption for sub-second safety-critical response times. JIS standards and PMDA quality system regulations for pharmaceutical manufacturing specify validated monitoring protocols. Kansai region semiconductor fabrication facilities deploy the broadest sensor arrays for predictive maintenance replacement of scheduled downtime.
Machine Health Monitoring Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with control-system heritage, creating a tiered structure where bearing specialists and automation vendors compete through overlapping capability sets. Strategic archetypes include heritage diagnostic firms leveraging decades of transducer standardization, integrated platform vendors unifying multi-sensor streams with ERP systems, and edge hardware specialists compressing latency for safety-critical assets. Dominant competitive moves center on portfolio diversification into software subscriptions and strategic partnerships for cloud analytics integration.
Within the heritage diagnostic tier, SKF AB and Fluke Corporation exemplify archetypes built on physical measurement expertise and field-service relationships. Honeywell International Inc. and Rockwell Automation Inc. occupy positions as integrated platform anchors, competing through software-hardware bundles that extend control-system footprints into analytics layers. Siemens AG and ABB Ltd. represent European conglomerate archetypes with cross-sector industrial automation portfolios. Emerson Electric Co. and General Electric anchor the North American diversified industrial tier, while National Instruments exemplifies the test-and-measurement specialist archetype migrating toward industrial IoT applications.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Honeywell International Inc. |
| SKF AB |
| General Electric |
| Siemens AG |
| ABB Ltd. |
| Rockwell Automation Inc. |
| National Instruments |
| Fluke Corporation |
| Others |
Supply Flow & Price Mechanics
Foundry-scale economies in MEMS accelerometer production anchor price floors for vibration transducers while compressing margins for smaller sensor suppliers unable to secure Taiwan Semiconductor Manufacturing Company capacity allocations. This concentration dynamic simultaneously elevates procurement leverage for tier-one automation vendors and forces mid-tier competitors toward software-centric pricing models that decouple recurring license revenue from hardware bill-of-materials exposure.
Pricing Analysis
Next-generation wireless vibration sensors with LoRaWAN connectivity command substantial premiums over legacy wired 4-20mA accelerometers, while cloud-native predictive maintenance platforms undercut on-premise historian systems through subscription economics. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical monitoring suites from general manufacturing vibration analytics and basic threshold-alert sensors. Pricing pressure stems from automotive OEMs unbundling software licenses from sensor hardware in Michigan and Ohio supplier diversity programs. Tier-two metal fabrication shops exhibit highest price sensitivity due to upfront installation cost barriers, while offshore wind operators demonstrate lowest sensitivity given revenue-critical gearbox reliability requirements.
Supply Chain Analysis
Strategic stockpiling of high-temperature-rated MEMS accelerometers has displaced just-in-time procurement as Taiwan foundry capacity constraints extend component lead times and force buffer inventory accumulation among tier-one automation vendors. Component sourcing concentrates on Taiwan for vibration transducers, Germany for precision bearing assemblies, and China for edge computing hardware enclosures. Raw material dependencies span silicon wafers for MEMS fabrication, rare earth elements for magnetic sensors, and specialized polymers for IP69K-rated washdown housings. Single-source vulnerability around Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through authorized system integrator networks in industrial clusters rather than direct OEM-to-plant sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent predictive maintenance platforms face substitution pressure from open-source analytics frameworks and hyperscaler cloud services that commoditize failure-mode detection algorithms. Defense requires compounding proprietary data network effects before horizontal technology platforms capture industrial IoT market share.
For Market Incumbents: Compound sensor deployment footprints through backward integration into edge computing hardware production, securing captive supply chains that insulate against Taiwan foundry bottlenecks while creating switching costs for manufacturing plant customers. Prioritize certification investment in FDA-validated monitoring protocols for pharmaceutical applications, establishing regulatory moats that open-source alternatives cannot replicate without multi-year validation timelines. Defensive positioning must anticipate hyperscaler cloud platforms unbundling analytics from hardware.
For New Entrants and Emerging Players: Differentiate on wireless sensor form-factor specialization for food and beverage washdown environments, where IP69K-rated battery-powered units are penetrating at triple general manufacturing rates. Target India's PLI scheme capital goods incentives as the most penetrable geography, where automotive and textile cluster expansion creates localized demand without entrenched incumbent relationships. Pursue regional system integrator partnerships as the primary go-to-market angle, bypassing direct competition with Rockwell Automation and Honeywell International distribution networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among predictive maintenance solution providers bundling proprietary failure-mode libraries with cloud analytics subscriptions, offering superior cash flow visibility against hardware-centric sensor manufacturers. Long-term viability across the analysis window favors platform vendors with demonstrated FDA validation capabilities and cross-ERP integration depth. Acquisition target archetype: mid-size oil analysis specialists with particle spectroscopy expertise applicable to offshore wind turbine gearbox monitoring. Watch for inflection when unbundled software subscription penetration in North American discrete manufacturing crosses critical mass thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Integration | On-premise FFT processing eliminates cloud latency for ISO 10816 velocity threshold breaches. |
| Wireless Sensor Form-Factor Development | IP69K-rated battery-powered units capture food and beverage washdown specification requirements. |
| FDA Validation Protocol Investment | Documented monitoring trails for pharmaceutical aseptic processing equipment create regulatory moats. |
| Regional System Integrator Partnership | Localized installation capabilities bypass direct competition with established automation vendor networks. |
| Cloud-Native Analytics Platform Launch | Subscription economics displace capital expenditure barriers for mid-sized manufacturing plant adoption. |
Methodological Framework
Initial hypotheses were tested against primary input from maintenance directors at automotive stamping plants, vibration analysts at Midwestern US manufacturing hubs, procurement leads at European bearing manufacturers, and aftermarket service heads at industrial automation OEMs, then refined through secondary validation against SEC 10-K filings, ISO 17359 certification registries, OSHA enforcement databases, and customs trade data for vibration sensor imports. Bottom-up sensor deployment estimates triangulated against top-down predictive maintenance software license revenue analysis.
Variance decomposition across technology segments, product type procurement patterns, end-user asset criticality tiers, and installation architecture preferences shaped the analytical framework throughout the projection horizon. CAGRs derived from regression analysis of historical adoption curves against regulatory enforcement intensity and factory automation investment cycles. Industry-specific forecast inputs incorporated MEMS accelerometer supply elasticity and cloud infrastructure capex disclosure trends from hyperscaler platforms.
Material uncertainties — Taiwan foundry capacity allocation shifts, FDA validation timeline extensions, and PLI scheme incentive modifications — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained OSHA machinery safety enforcement and continued offshore wind turbine installation growth. Revision becomes warranted when unbundled software subscription penetration in North American discrete manufacturing accelerates beyond modeled substitution rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Facial Tracking Solution Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
2D Barcode Reader Market
Sensors
Ultrasonic Technologies Market
Sensors
Global Position Tracking System Market
Sensors
Europe Lidar Market
Sensors
Global RFID Market
Sensors
Asset Tracking Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
Asset Tags Market
Sensors
Micro Location Technology Market
Sensors
Transport Monitoring System Market
Sensors
Asia Pacific Container Monitoring Market