
 Canada Geospatial Analytics Market | 2026-2036
Canada Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Geospatial Analytics Market Insights
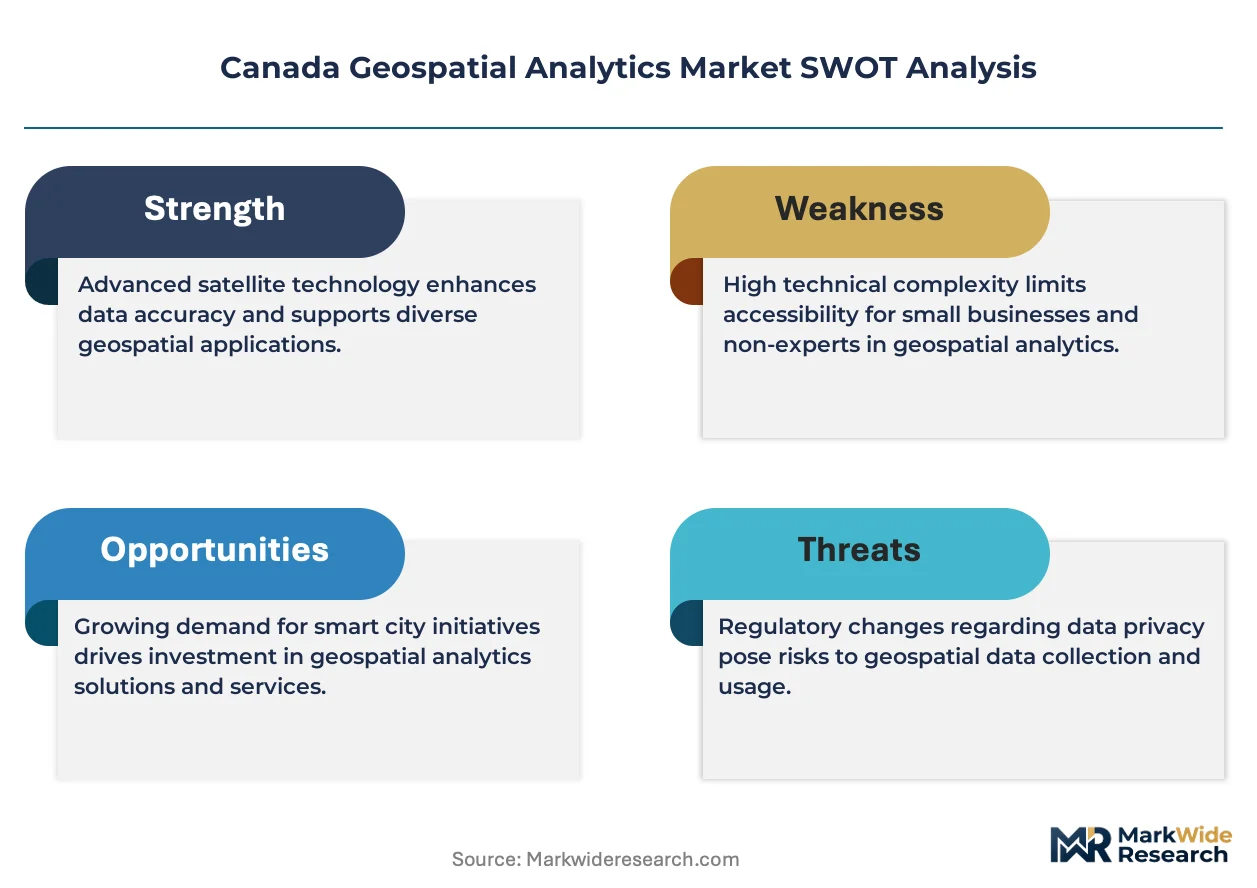
ISO 19115 geospatial metadata compliance is redrawing competitive access in federal procurement. Esri Canada leverages its entrenched position across Crown land management systems. Hexagon AB anchors precision agriculture and surveying verticals with integrated sensor-to-software workflows. Trimble Inc. competes through specialized GNSS hardware paired with analytics subscriptions for construction and utilities.
Geospatial analytics encompasses the computational processing of location-referenced data through coordinate-based algorithms, spatial statistics, and remote sensing pipelines to generate actionable intelligence for resource allocation and risk assessment. The technology stack processes satellite imagery, LiDAR point clouds, and cadastral vectors at sub-meter resolution for infrastructure and environmental decision-making. GIS and remote sensing technologies dominate current government spending on natural resource monitoring, while cloud-based and SaaS deployment models capture the fastest expansion as municipalities abandon legacy server farms. Urban planning and environmental monitoring applications sit at the center of provincial procurement cycles, with disaster management emerging as a priority segment driven by flood and wildfire exposure across the Prairie Provinces.
Health Canada and PMRA reference geospatial frameworks for environmental health exposure mapping, while Natural Resources Canada mandates open data standards that shape vendor interoperability requirements. The Treasury Board Secretariat's Directive on Automated Decision-Making imposes algorithmic transparency obligations on AI-enhanced spatial analysis tools sold to federal agencies. Stakeholders must weigh compliance investments against the contracting advantages of holding recognized federal certifications as procurement rules tighten around explainable analytics.
Market Dynamics
Natural Resources Canada's open data mandate is compressing vendor switching costs and forcing interoperability investments across federal procurement channels. Provincial forestry departments in British Columbia and Alberta are accelerating satellite-based timber inventory modernization, redirecting platform spending toward cloud-native architectures.
Growth Catalysts
- ISO 19115 Compliance Mandate:Federal procurement rules now require standardized geospatial metadata, creating contracting advantages for certified vendors across Crown land management systems.
- Cloud Migration Wave:Municipal infrastructure planners in the Greater Toronto Area are abandoning legacy server farms for SaaS deployment models, expanding addressable platform markets.
- Wildfire Risk Modeling:Prairie Provinces disaster management agencies are prioritizing flood and wildfire exposure analytics, driving demand for real-time remote sensing pipelines.
Market Restraints
- LiDAR Hardware Cost Concentration:Precision sensor supply chains remain concentrated among specialized manufacturers, limiting price competition for integrated survey workflows.
- Algorithmic Transparency Requirements:The Treasury Board Secretariat's Directive on Automated Decision-Making imposes explainability obligations on AI-enhanced spatial tools, extending federal sales cycles.
- Legacy System Entrenchment:Decades of Esri platform deployment across provincial natural resource departments creates switching friction for alternative vendors.
Strategic Opportunities
- Precision Agriculture Expansion:Alberta and Saskatchewan farm operations are adopting sensor-to-software workflows for variable-rate input management, opening underpenetrated rural analytics markets.
- Health-Environment Convergence:Health Canada and PMRA are referencing geospatial frameworks for environmental health exposure mapping, creating new cross-agency procurement channels.
- Interoperability Certification:Vendors holding recognized federal certifications gain preferential access to tightening procurement rules around explainable analytics.
Industry Challenges
- Geospatial Data Science Talent Scarcity:Federal agencies and provincial departments face acute shortages of analysts capable of integrating remote sensing pipelines with cadastral vector systems.
- Legacy Integration Complexity:Municipal customers struggle to connect cloud-native platforms with decades-old property tax and infrastructure databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Geospatial Analytics Market |
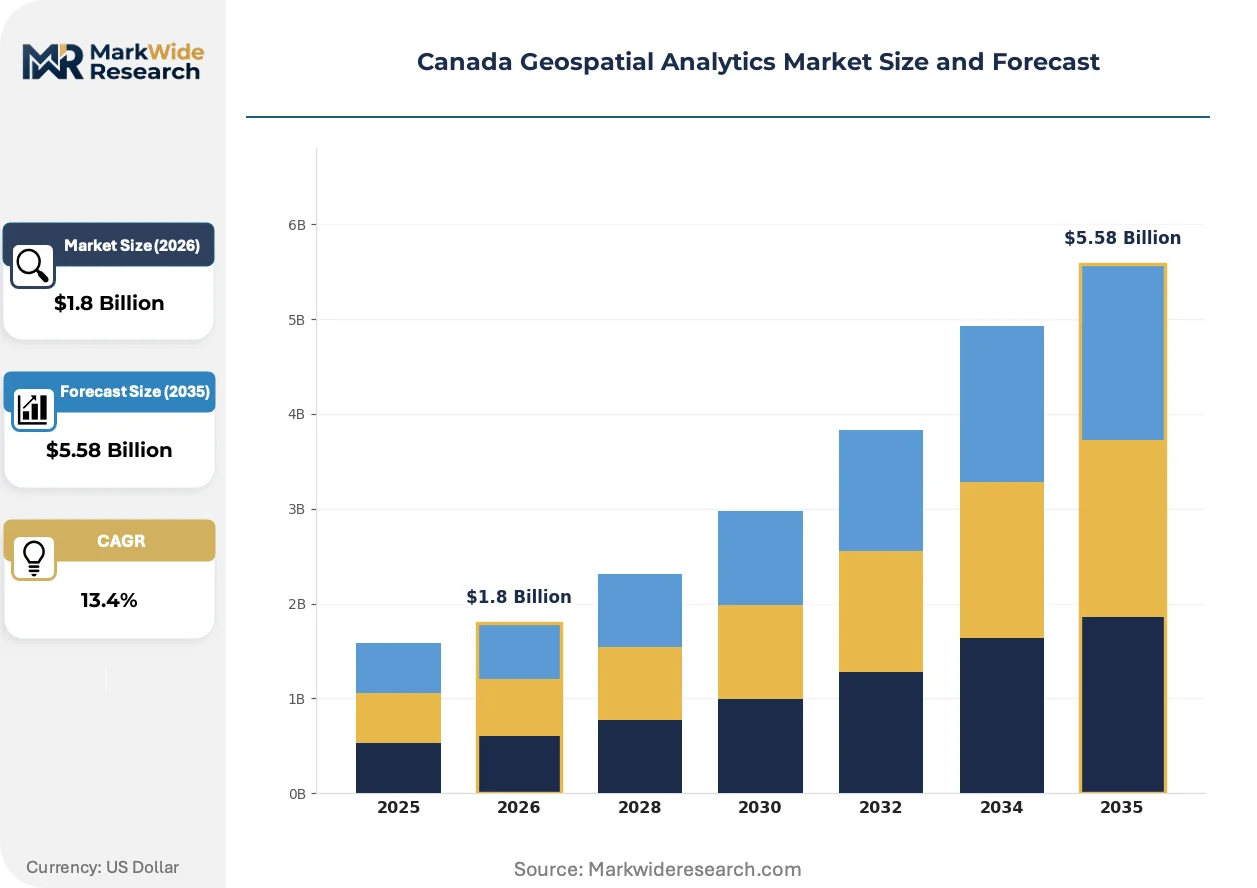
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.58 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GIS, Remote Sensing, Mapping Software, Spatial Data Infrastructure Application: Urban Planning, Environmental Monitoring, Disaster Management, Asset Management End User: Government Agencies, Research Institutions, Private Sector, NGOs Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Esri Canada, Hexagon AB, Trimble Inc., IBM, Bentley Systems, Maxar Technologies, Harris Corporation, Intermap Technologies, Autodesk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Geospatial Analytics Market Trends and Innovations
Cloud-native geospatial processing architectures are compressing deployment timelines and enabling real-time analytics for emergency response applications. Federal and provincial buyers are reorienting procurement criteria around interoperability rather than single-vendor stack depth.
AI-enhanced change detection algorithms are supplanting manual photogrammetry interpretation in forestry and infrastructure monitoring workflows. Alberta's provincial forestry division has adopted automated crown cover assessment tools, cutting inventory update cycles from annual to quarterly intervals. This compression is forcing traditional survey firms to retrain field crews for validation rather than measurement roles.
Health Canada's PMRA is mandating geospatial exposure mapping for pesticide registration reviews, extending spatial analytics requirements into environmental health regulatory processes. Agricultural chemical manufacturers must now submit location-referenced drift and runoff models. This obligation is pulling precision agriculture vendors into toxicology data services.
Municipal infrastructure buyers are unbundling software subscriptions from professional services, treating geospatial platforms as operational utilities rather than capital projects. Toronto-area cities are piloting usage-based pricing for planning department cloud access. This shift is compressing vendor margins while extending contract durations through embedded renewal clauses.
Canada Geospatial Analytics Market Segmentation
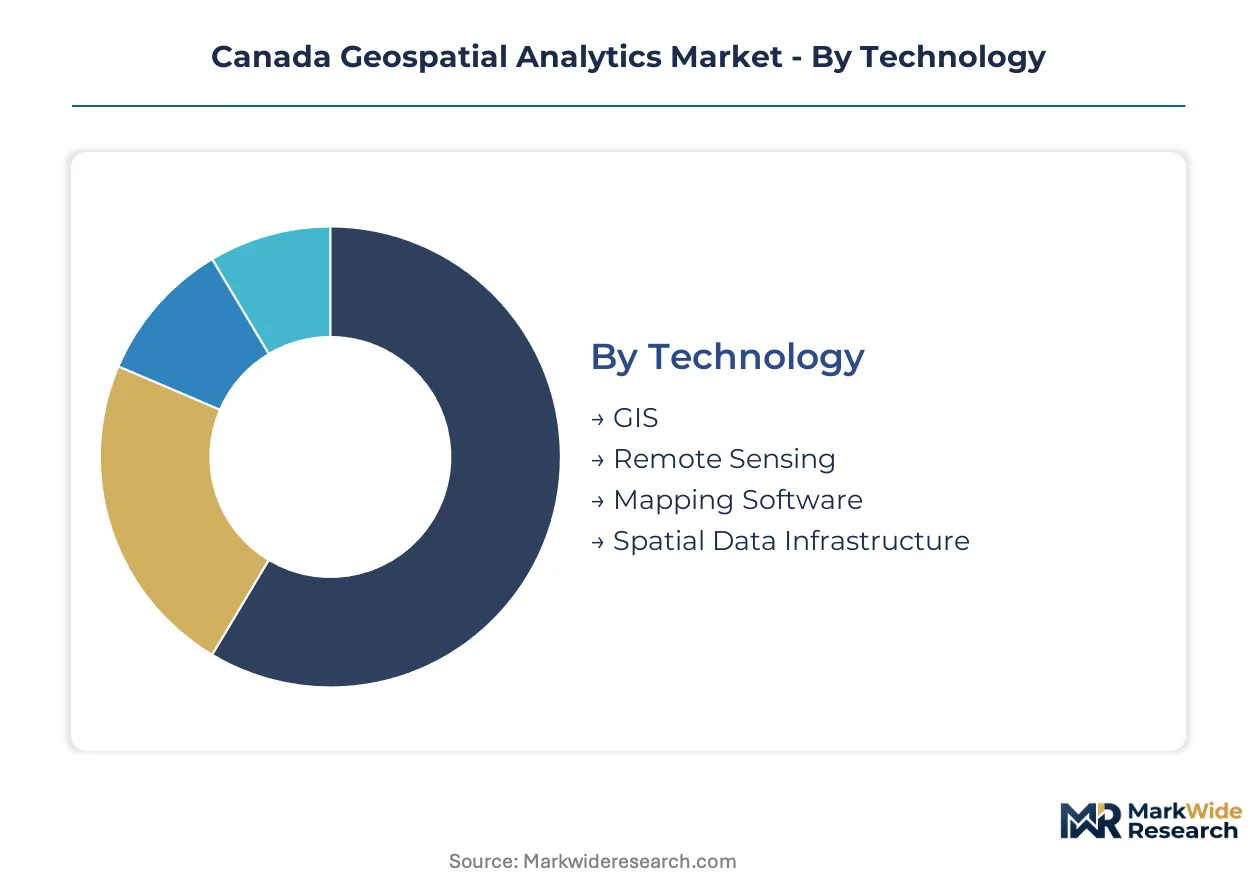
Segmentation in the Canada Geospatial Analytics Market reveals distinct procurement patterns across federal, provincial, and municipal tiers. Channel strategies diverge sharply between legacy infrastructure upgrades and cloud-native deployments, with vendor positioning calibrated to specific buyer technical maturity and budget cycles.
Technology:
Channel flow splits between hardware-integrated sales through surveying firms and software-led procurement via systems integrators serving government accounts.
- GIS:Core platform technology integrates cartographic visualization with attribute databases for land registry and infrastructure asset management. British Columbia and Alberta forestry departments concentrate demand here, driven by Crown land tenure tracking mandates and annual cut-block planning cycles.
- Remote Sensing:Satellite and aerial imagery pipelines process multispectral and synthetic aperture radar data for change detection at sub-meter resolution. Prairie Provinces disaster management agencies are accelerating procurement for wildfire perimeter mapping and flood extent assessment.
- Mapping Software:Desktop and field-mobile applications for data collection, editing, and cartographic production.
- Spatial Data Infrastructure:Federated catalog services and metadata registries enabling cross-jurisdictional data discovery under Natural Resources Canada open data standards.
By volume, GIS leads procurement across federal and provincial channels. By growth pace, Remote Sensing is expanding most quickly as satellite revisit frequencies improve and analytics automate.
Application:
Cost tiering separates capital-intensive enterprise deployments from subscription-based departmental tools, with price-to-function ratios determining municipal versus federal adoption patterns.
- Urban Planning:Zoning analysis, growth scenario modeling, and development impact assessment for municipal planning departments. The Greater Toronto Area concentrates demand as municipalities abandon legacy server farms for cloud-native platforms serving concurrent growth management and infrastructure deficit planning.
- Environmental Monitoring:Ecosystem health assessment, pollution source tracking, and biodiversity corridor mapping. Health Canada and PMRA are mandating geospatial exposure frameworks for pesticide registration reviews, pulling precision agriculture vendors into toxicology data services.
- Disaster Management:Real-time situational awareness and predictive risk modeling for emergency operations centers.
- Asset Management:Linear infrastructure condition assessment and lifecycle costing for utilities and transportation departments.
Urban Planning commands the largest absolute spend through multi-year municipal capital budgets. Environmental Monitoring is climbing the fastest as regulatory compliance obligations expand across federal agencies.
End User:
Customer type determines contract structure, with government buyers favoring multi-vendor framework agreements and private sector procurement emphasizing integrated sensor-to-software workflows.
- Government Agencies:Federal departments, provincial natural resource ministries, and municipal planning authorities. Natural Resources Canada mandates ISO 19115 metadata compliance, creating contracting advantages for certified vendors across Crown land management systems.
- Research Institutions:Universities and federal science agencies conducting spatial analysis for climate adaptation and resource economics.
- Private Sector:Forestry operators, agricultural producers, and engineering consultancies purchasing analytics for operational decision-making.
- NGOs:Conservation organizations and Indigenous land management entities accessing open data for stewardship planning.
Government Agencies dominate procurement volume through consolidated federal and provincial spending. Private Sector adoption is gaining share fastest as precision agriculture workflows penetrate Alberta and Saskatchewan farm operations.
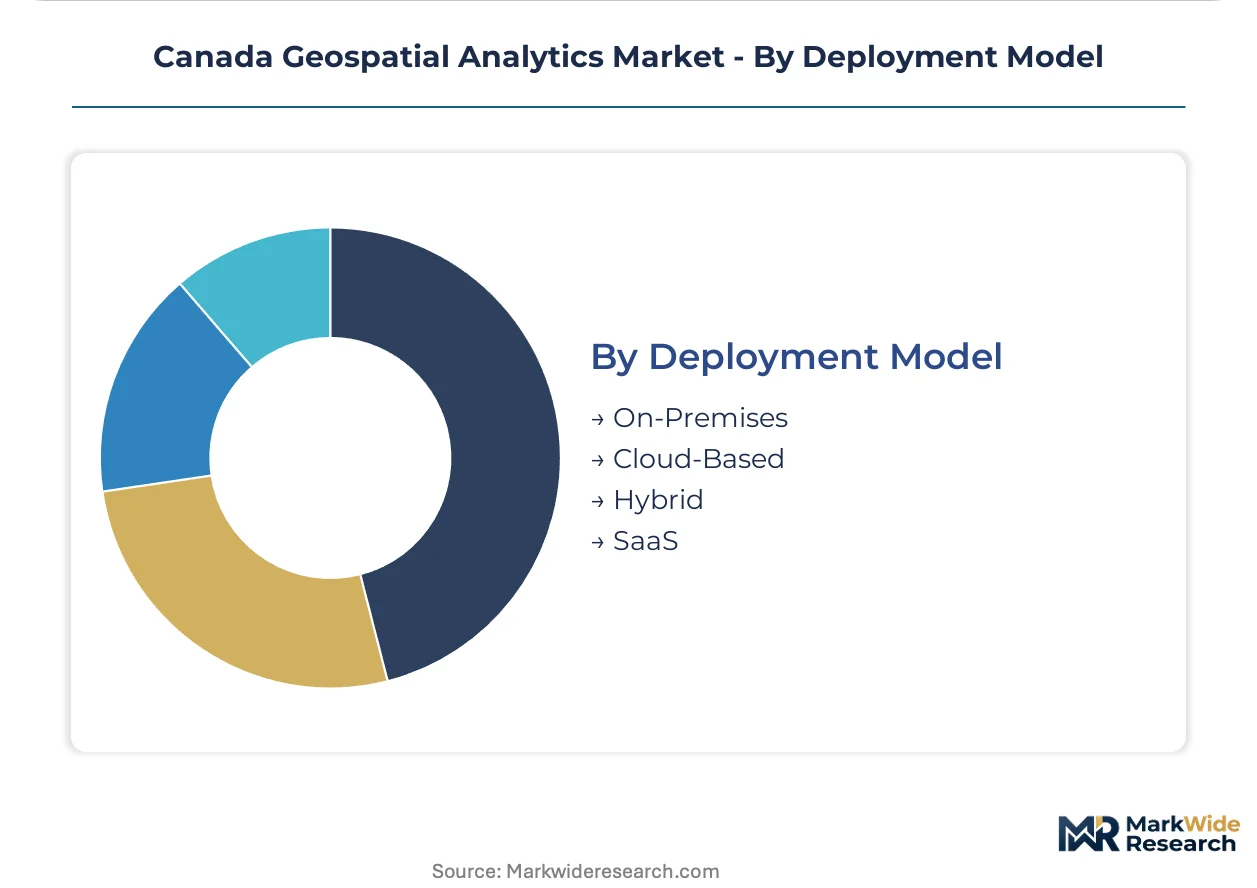
Deployment Model:
Maturity gradients separate established on-premises installations from emerging cloud architectures, with hybrid configurations bridging legacy system entrenchment and SaaS flexibility demands.
- On-Premises:Dedicated server infrastructure behind government firewalls for classified or sensitive spatial data. Legacy Esri deployments across provincial natural resource departments create switching friction that preserves incumbent positions despite higher total cost of ownership.
- Cloud-Based:Scalable compute and storage resources enabling real-time analytics without capital infrastructure commitment. Toronto-area cities are piloting usage-based pricing for planning department access, compressing vendor margins while extending contract durations through embedded renewal clauses.
- Hybrid:Split architectures retaining sensitive data on-premises while leveraging cloud processing for non-critical analytics workloads.
- SaaS:Subscription-accessible platforms with embedded maintenance, updates, and support services.
On-Premises retains the largest installed base across federal security-classified environments. Cloud-Based deployment is expanding most quickly as municipal infrastructure planners abandon legacy server farms and Treasury Board procurement rules tighten around interoperability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans Mountain Pipeline expansion and Pacific rail corridors anchor British Columbia's geospatial intensity. Federal open data mandates and provincial timber inventory programs are redrawing procurement patterns across Canadian sub-regions.
Ontario
Municipal infrastructure planners in the Greater Toronto Area are abandoning legacy server farms for cloud-native platforms. Natural Resources Canada's ISO 19115 metadata compliance requirements shape vendor certification priorities. Toronto-area cities pilot usage-based pricing for planning department cloud access.
British Columbia
Provincial forestry departments accelerate satellite-based timber inventory modernization under Crown land tenure tracking mandates. The BC Wildfire Service drives demand for real-time remote sensing pipelines and automated change detection. Vancouver serves as the western hub for geospatial systems integrators serving Pacific resource sectors.
Alberta
Farm operations across the Prairie Provinces adopt sensor-to-software workflows for variable-rate input management. Alberta's provincial forestry division deploys automated crown cover assessment tools, compressing inventory update cycles. Calgary anchors precision agriculture vendor activity and energy sector spatial analytics demand.
Quebec
Natural resource ministries prioritize environmental monitoring for biodiversity corridor mapping and ecosystem health assessment. The province's hydropower infrastructure drives linear asset management procurement for transmission corridor monitoring. Montreal clusters remote sensing research institutions and federal science agency operations.
Canada Geospatial Analytics Market Competitive Landscape
Listed leaders compete with private specialists across platform interoperability and Crown land management system entrenchment. The vendor base splits between entrenched incumbents with decades of provincial deployment and cloud-native challengers exploiting federal open data mandates. Two strategic archetypes dominate: full-stack platform providers with hardware-software integration, and modular SaaS vendors unbundling professional services from software subscriptions. Competitive moves concentrate on interoperability certification investments and municipal cloud migration capture.
Within the full-stack tier, Esri Canada and Hexagon AB exemplify contrasting approaches to federal procurement access. Esri Canada occupies a position shaped by historical platform deployment across provincial natural resource departments. Hexagon AB sits within the precision measurement archetype, with integrated sensor-to-software workflows serving agriculture and surveying verticals. Trimble Inc. represents the specialized hardware-plus-subscription model competing for construction and utilities analytics demand.
| Leading Market Players |
|---|
| Esri Canada |
| Hexagon AB |
| Trimble Inc. |
| IBM |
| Bentley Systems |
| Maxar Technologies |
| Harris Corporation |
| Intermap Technologies |
| Autodesk |
| Others |
Pricing and Supply Chain Analysis
Ninety-to-120-day sensor procurement lead times for LiDAR hardware concentrate pricing power among specialized manufacturers serving Canadian forestry and surveying verticals. This elongated procurement cycle reinforces cost pass-through to municipal buyers while compressing margins for systems integrators caught between fixed-price contracts and component volatility.
Pricing Analysis
Volume-discount tiering structures separate enterprise Crown land management deployments from municipal departmental subscriptions. Three-tier pricing stratifies across federal certification-holding vendors, provincial framework agreement participants, and unaccredited SaaS challengers. Pricing pressure stems from Toronto-area municipalities piloting usage-based cloud access models that unbundle professional services from software licenses. Federal agencies exhibit lowest price sensitivity due to security-classified procurement requirements, while cash-constrained municipal planning departments drive hardest bargain negotiations.
Supply Chain Analysis
Inbound logistics costs through Vancouver and Prince Rupert ports constrain hardware-integrated vendor margins as container availability fluctuates on transpacific trade lanes. Component sourcing concentrates in the United States for GNSS chipsets, Germany for precision optics, and China for drone airframe assemblies. LiDAR sensor supply chains rest on single-source dependencies with manufacturers in California and Sweden. Tariff exposure on Chinese-manufactured unmanned aerial vehicles creates procurement risk for remote sensing service providers. Distribution runs through systems integrators serving provincial natural resource ministries and direct SaaS channels targeting municipal infrastructure planners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada Geospatial Analytics Market sits in early-cycle expansion as federal open data mandates and cloud migration tailwinds accelerate platform replacement across municipal infrastructure planning.
For Market Incumbents: Fortify interoperability certification positions under Natural Resources Canada ISO 19115 mandates to preserve Crown land management system entrenchment against cloud-native challengers. Deepen backward integration into precision sensor distribution to offset LiDAR hardware cost concentration and secure supply allocation during procurement crunches. For New Entrants and Emerging Players: Lead with SaaS-native deployment models targeting Alberta and Saskatchewan precision agriculture operations where sensor-to-software workflow penetration remains underdeveloped. Capture municipal cloud migration demand in the Greater Toronto Area through usage-based pricing structures that bypass incumbent professional services bundling. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-sized surveying firms possessing provincial forestry department relationships but lacking cloud platform capabilities. Long-term viability hinges on federal certification durability and interoperability compliance rather than single-vendor stack depth. The signal to watch is Treasury Board Secretariat procurement rule tightening around explainable AI analytics obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Investment | Natural Resources Canada ISO 19115 compliance creates preferential federal contracting access for certified vendors. |
| Cloud-Native Platform Migration | Toronto-area municipal infrastructure planners abandon legacy server farms for scalable SaaS deployment models. |
| Precision Agriculture Workflow Expansion | Alberta and Saskatchewan farm operations adopt sensor-to-software variable-rate input management systems. |
| AI-Enhanced Change Detection Development | Automated crown cover assessment tools compress British Columbia forestry inventory update cycles from annual to quarterly. |
| Health-Environment Data Service Integration | Health Canada PMRA pesticide registration mandates pull precision agriculture vendors into toxicology exposure mapping. |
Research Methodology
Operator-level perspectives from provincial forestry department procurement officers, municipal infrastructure planning directors, federal geospatial data stewards, and precision agriculture systems integrators anchored the qualitative base. Primary interview findings triangulated against Natural Resources Canada open data policy documents, Treasury Board Secretariat procurement directives, provincial timber inventory program disclosures, and municipal cloud migration tender records. Bottom-up deployment model sizing and top-down federal spending allocation analysis cross-validated market estimates.
Sensitivity analysis tested forecast outputs against alternative cloud adoption velocity assumptions and LiDAR hardware cost trajectories across the projection horizon. Segmentation modeling incorporated technology stack, application vertical, end-user tier, and deployment architecture dimensions. CAGRs derived from year-over-year platform spending patterns by government tier and private sector penetration rates in agriculture and forestry operations.
The analysis sits within stated boundaries; outcomes outside sustained federal open data mandate enforcement or accelerated municipal cloud procurement timelines would require recalibration. Forecasts reflect assumptions regarding Treasury Board algorithmic transparency rule implementation and provincial timber inventory modernization funding continuity. Recalibration cycles align with material shifts in Health Canada PMRA geospatial exposure mapping obligations and Prairie Provinces disaster management agency remote sensing procurement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
South Korea Geospatial Analytics Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market