
 Robotic Drilling Market | 2026-2036
Robotic Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Drilling Market Analysis
API Q2 and ISO 9001 certification cycles is redrawing competitive access in robotic drilling equipment supply. Nabors Industries Ltd leverages its integrated rig manufacturing footprint to sustain automation R&D intensity across North American land markets. NOV Inc anchors its position through controls hardware that dominates offshore drillship retrofits. Schlumberger Limited differentiates via AI-driven well construction software layered across third-party rig platforms.
Robotic drilling encompasses autonomous and remotely operated systems that execute tripping, connection-making, and wellbore steering through closed-loop control architectures achieving sub-millimeter depth accuracy and real-time torque management. These systems eliminate human exposure to derrick hazards while sustaining consistent rate-of-penetration across extended-reach laterals. Autonomous drillers command the largest installed base among product types, though hybrid drilling systems are expanding fastest as operators phase automation onto existing mechanical rigs. AI Solutions within the technology dimension capture disproportionate development investment, while oil and gas exploration remains the dominant application by capital commitment despite geothermal drilling posting higher growth velocity.
FAA guidelines for unmanned systems and OSHA fall-protection mandates shape land-based robotic rig deployment timelines in the United States, while BSEE well control regulations govern offshore automation acceptance criteria. The EU Machinery Directive and ATEX certification requirements constrain European market entry for non-compliant control systems. Stakeholders must monitor evolving cybersecurity standards for connected drilling assets, as regulatory bodies in multiple jurisdictions draft protocols for remote-operated critical infrastructure.
Market Dynamics
Autonomous drilling systems are restructuring capital allocation across oilfield services as operators prioritize crew safety and well consistency over legacy mechanical rig economics. API Q2 certification requirements are compressing supplier qualification timelines and favoring integrated manufacturers with captive controls development.
Growth Catalysts
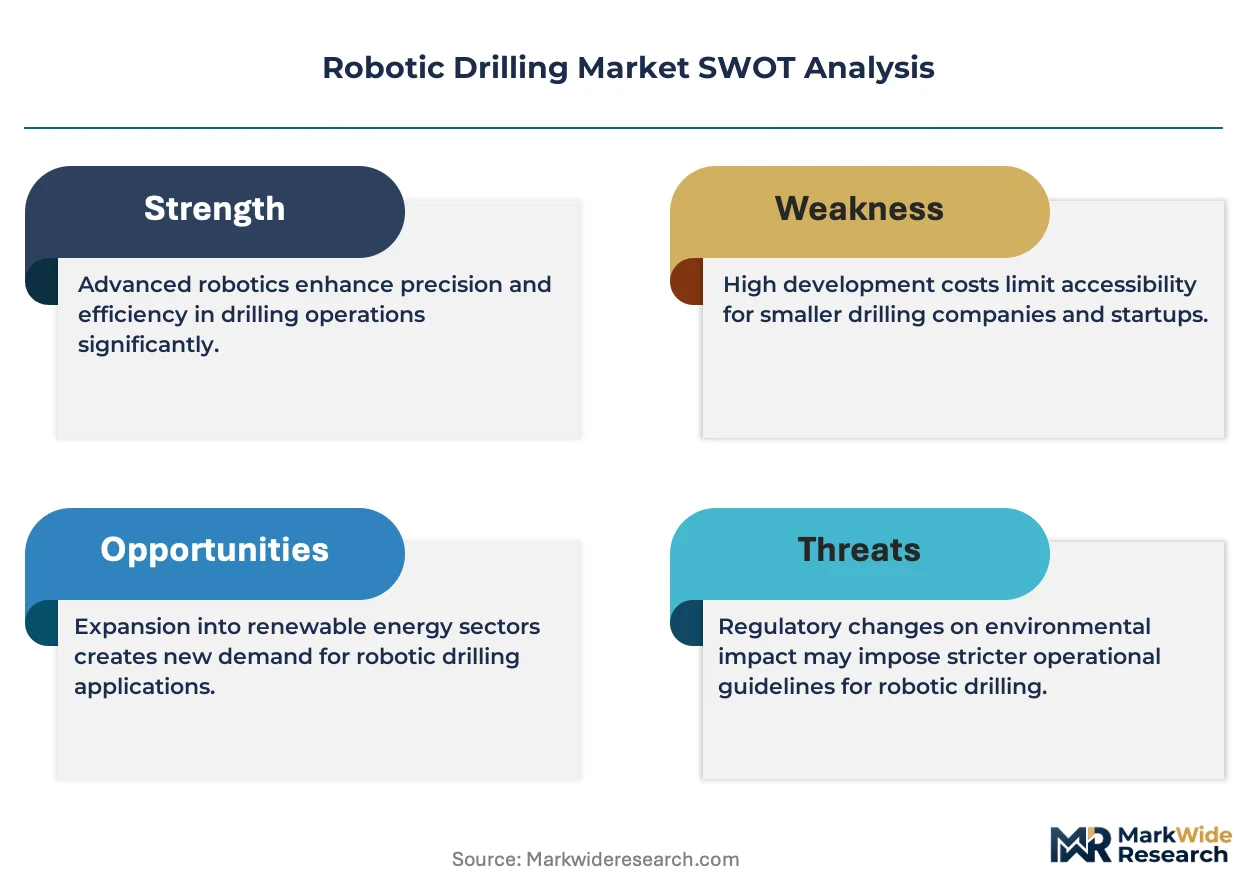
- OSHA Fall-Protection Mandates:United States land operators face escalating compliance costs for manual derrick work, accelerating retrofit demand for robotic pipe-handling systems that eliminate human exposure at height.
- Extended-Reach Laterals:Permian Basin and Bakken producers are drilling longer horizontal sections that exceed human consistency limits, requiring closed-loop torque management to sustain rate-of-penetration across 15,000-foot laterals.
- BSEE Well Control Regulations:Offshore drillship operators in the Gulf of Mexico must demonstrate sub-second kick detection response, a capability only autonomous systems reliably deliver under high-pressure conditions.
Market Restraints
- High-Grade Steel Input Volatility:Drillstring components and rig superstructures depend on specialized alloy supply concentrated in Chinese and Indian mills, exposing automation retrofits to raw material price swings.
- Control System Vendor Concentration:Proprietary drilling software architectures from a narrow supplier base in Houston and Aberdeen create integration lock-in and limit operator bargaining leverage.
- Legacy Rig Mechanical Constraints:Pre-2010 land rigs lack the structural sensor density and hydraulic bandwidth required for full automation, forcing costly mid-life upgrades or premature retirement.
Strategic Opportunities
- Geothermal Energy Expansion:United States Department of Energy funding for enhanced geothermal systems is creating demand for drilling automation adapted to hard-rock crystalline formations beneath the Great Basin.
- Remote Operations Centers:Real-time drilling command from onshore facilities is supplanting offshore crew rotations, reducing helicopter logistics costs for North Sea and Gulf of Mexico assets.
- EU Machinery Directive Convergence:ATEX certification alignment with IECEx standards is opening a pathway for North American automation vendors to access Norwegian and UK offshore markets without duplicate testing.
Industry Challenges
- Cyber-Physical Security Integration:Connected drilling assets face escalating ransomware exposure, requiring OT-security engineering talent scarce in traditional oilfield services hiring pools.
- Multi-Vendor Control Harmonization:Operators running mixed fleets of NOV, Schlumberger, and proprietary rig systems struggle to unify data architectures for fleet-wide performance analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Drilling Market |
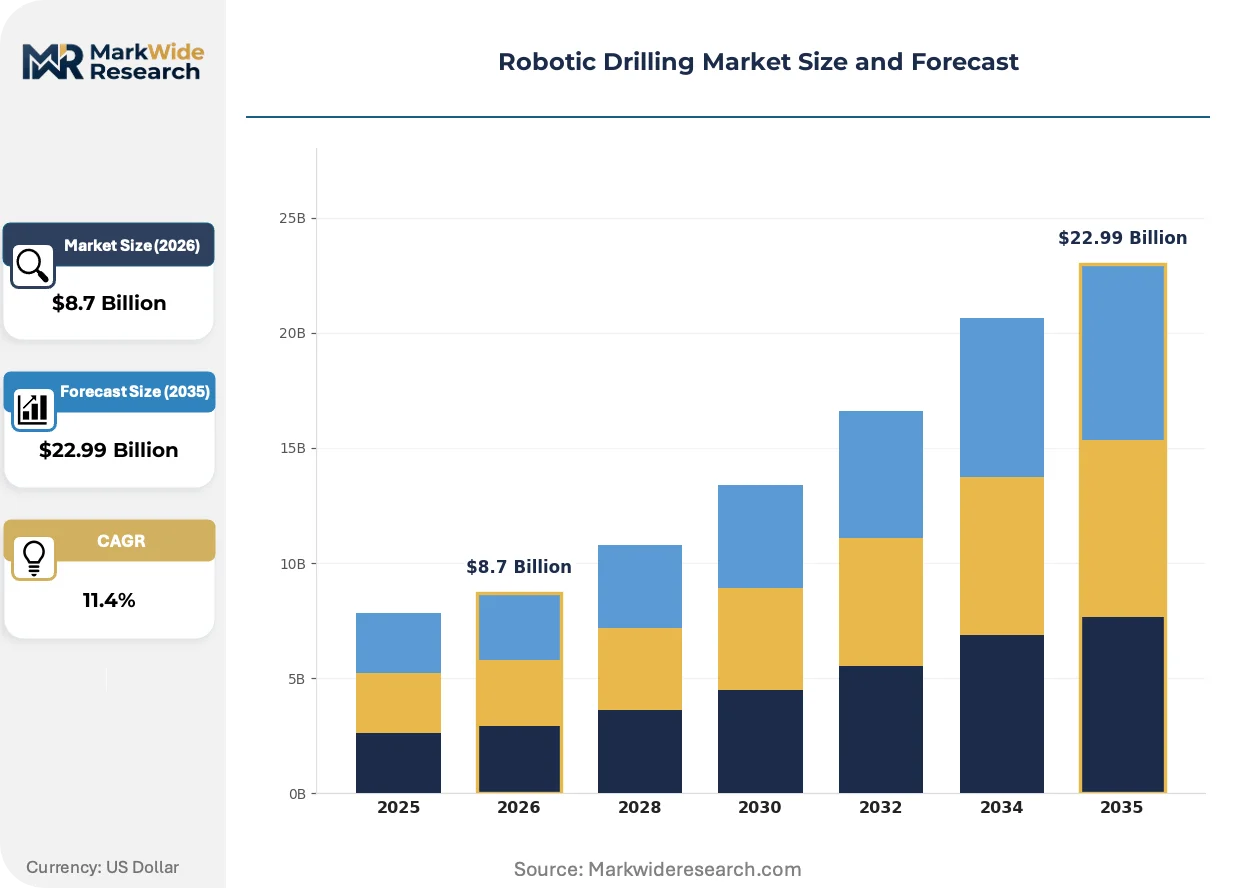
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Drillers, Remote-Controlled Drillers, Hybrid Drilling Systems, Conventional Drilling Rigs Technology: AI Solutions, Sensor Technologies, Robotics, Automation Software Application: Mining Operations, Oil & Gas Exploration, Geothermal Drilling, Construction Projects End User: Energy Companies, Mining Firms, Construction Contractors, Engineering Services |
| Companies Covered | Nabors Industries Ltd, NOV Inc, Schlumberger Limited, Precision Drilling Corporation, Huisman Equipment B.V., Weatherford International, Ensign Energy Services, Drillmec, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Drilling Market Emerging Trajectories
Artificial intelligence is penetrating well construction workflows at the control layer, compressing the loop between downhole measurement and surface actuation from minutes to milliseconds. This shift is redrawing competitive advantage toward software-anchored suppliers and away from pure hardware manufacturers.
AI-driven wellbore steering algorithms are supplanting directional driller judgment in real-time geosteering decisions. Permian Basin operators with substantial lateral inventories are deploying these systems across 40% of new spuds within eighteen months of pilot completion. The technology is compressing the premium commanded by experienced directional drilling crews and flattening regional day-rate dispersion.
The BSEE Well Control Rule amendments are mandating redundant blowout preventer control systems with automated shear activation triggers. Gulf of Mexico drillship contractors are reconfiguring subsea control pods to accommodate these requirements ahead of the compliance deadline. Deepwater projects with 2026 sanctioning decisions are embedding these specifications into rig construction contracts.
Performance-based drilling contracts are displacing day-rate structures in United States land markets. E&P companies in the Delaware Basin are tying contractor compensation to drilling speed and wellbore quality metrics rather than time-on-location. This shift concentrates automation investment among the dozen contractors with sufficient balance sheet depth to absorb outcome volatility.
Robotic Drilling Market Segmentation
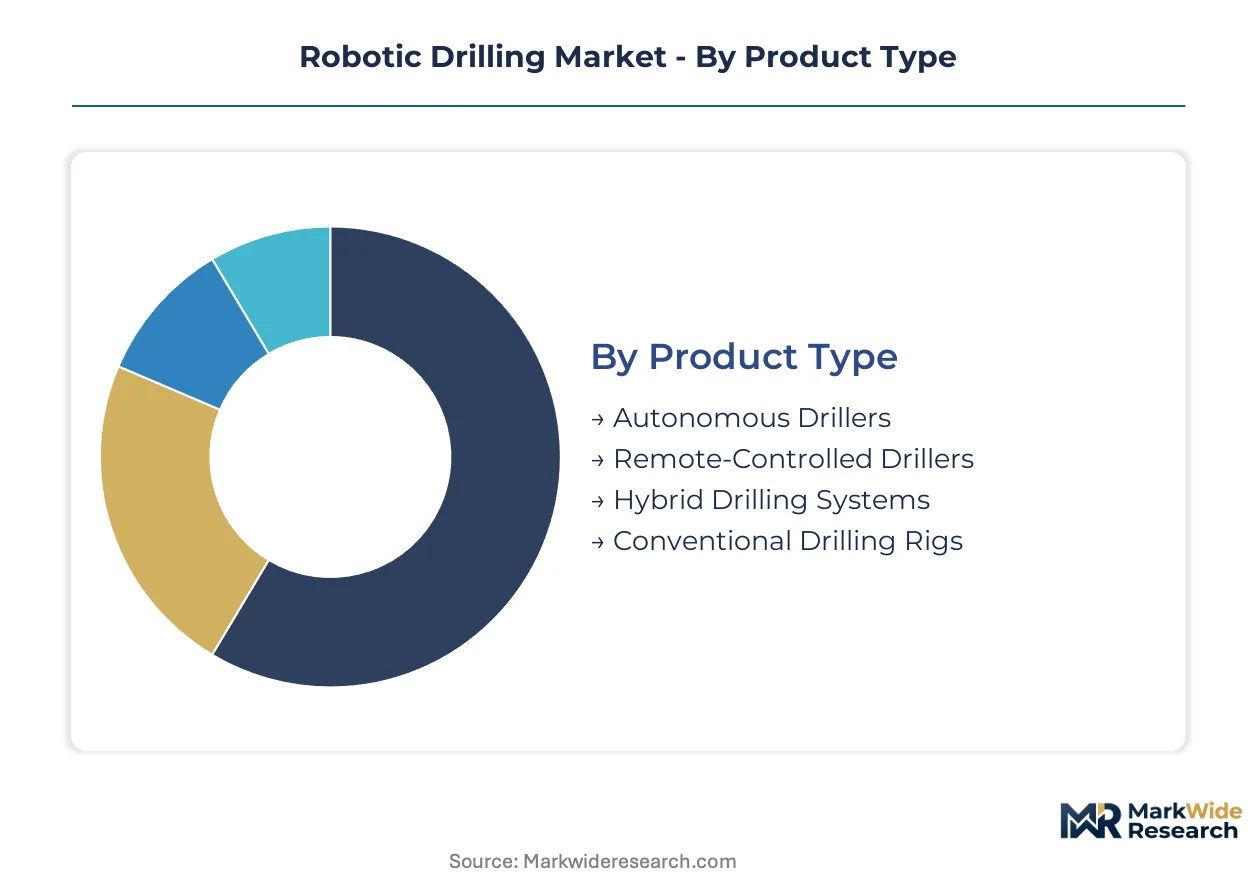
Segmentation in robotic drilling reveals how regulatory pressure and operational risk tolerance fragment equipment procurement. Buyers select automation tiers based on crew exposure limits, well complexity, and certification requirements rather than capital cost alone.
Product Type:
API Q2 and ISO 9001 certification cycles create tiered market access, with fully autonomous systems facing the longest qualification timelines but commanding premium positioning in offshore environments.
- Autonomous Drillers:Closed-loop systems execute tripping, connection-making, and wellbore steering without human intervention in the derrick. Demand concentrates in United States Gulf Coast offshore drillships where BSEE well control regulations mandate sub-second kick detection response that only autonomous architectures reliably deliver.
- Hybrid Drilling Systems:Phased automation retrofits onto existing mechanical rigs blend robotic pipe-handling with retained manual oversight. Permian Basin operators favor this tier for pre-2010 land rig fleets lacking structural sensor density for full conversion, accepting incremental crew reduction while avoiding premature asset retirement.
- Remote-Controlled Drillers:Surface-operated systems maintain human decision loops while removing personnel from height hazards.
- Conventional Drilling Rigs:Legacy mechanical platforms without automation integration serve marginal acreage and international markets with limited regulatory enforcement.
Established volume favors Autonomous Drillers; emerging adoption favors Hybrid Drilling Systems.
Technology:
Development investment clusters where software layers can deploy across heterogeneous rig fleets, reducing operator dependence on single-vendor hardware lock-in.
- AI Solutions:Machine learning algorithms compress surface-to-downhole control loops from minutes to milliseconds. United States land markets deploy these systems across new spuds within eighteen months of pilot completion, flattening directional driller day-rate dispersion.
- Robotics:Articulated manipulators and autonomous pipe-handling mechanisms execute physical tripping operations. Mining Operations in hard-rock formations beneath the Great Basin drive specialized adaptations for crystalline geology.
- Sensor Technologies:Downhole measurement-while-drilling and surface load sensing enable closed-loop torque management.
- Automation Software:Control architectures harmonizing multi-vendor rig systems struggle with data standardization across mixed fleets.
Capital deployment heaviest in AI Solutions; steepest expansion trajectory in Sensor Technologies as legacy rig retrofits demand sensing infrastructure.
Application:
End-use risk profiles determine automation urgency, with high-pressure hydrocarbon environments outpacing geothermal and construction in specification stringency.
- Oil & Gas Exploration:Extended-reach laterals exceeding 15,000 feet require consistent rate-of-penetration that human crews cannot sustain. United States Gulf Coast and Permian Basin operators anchor capital commitment despite price volatility.
- Geothermal Drilling:Hard-rock crystalline formations demand specialized bit dynamics and thermal management. United States Department of Energy funding for enhanced geothermal systems is climbing the fastest among applications.
- Mining Operations:Autonomous blasthole drilling reduces personnel exposure in open-pit and underground environments.
- Construction Projects:Foundation drilling and tunnel boring apply robotic precision to civil infrastructure with lower regulatory pressure than energy applications.
Revenue concentration remains with Oil & Gas Exploration; policy tailwinds favor Geothermal Drilling.
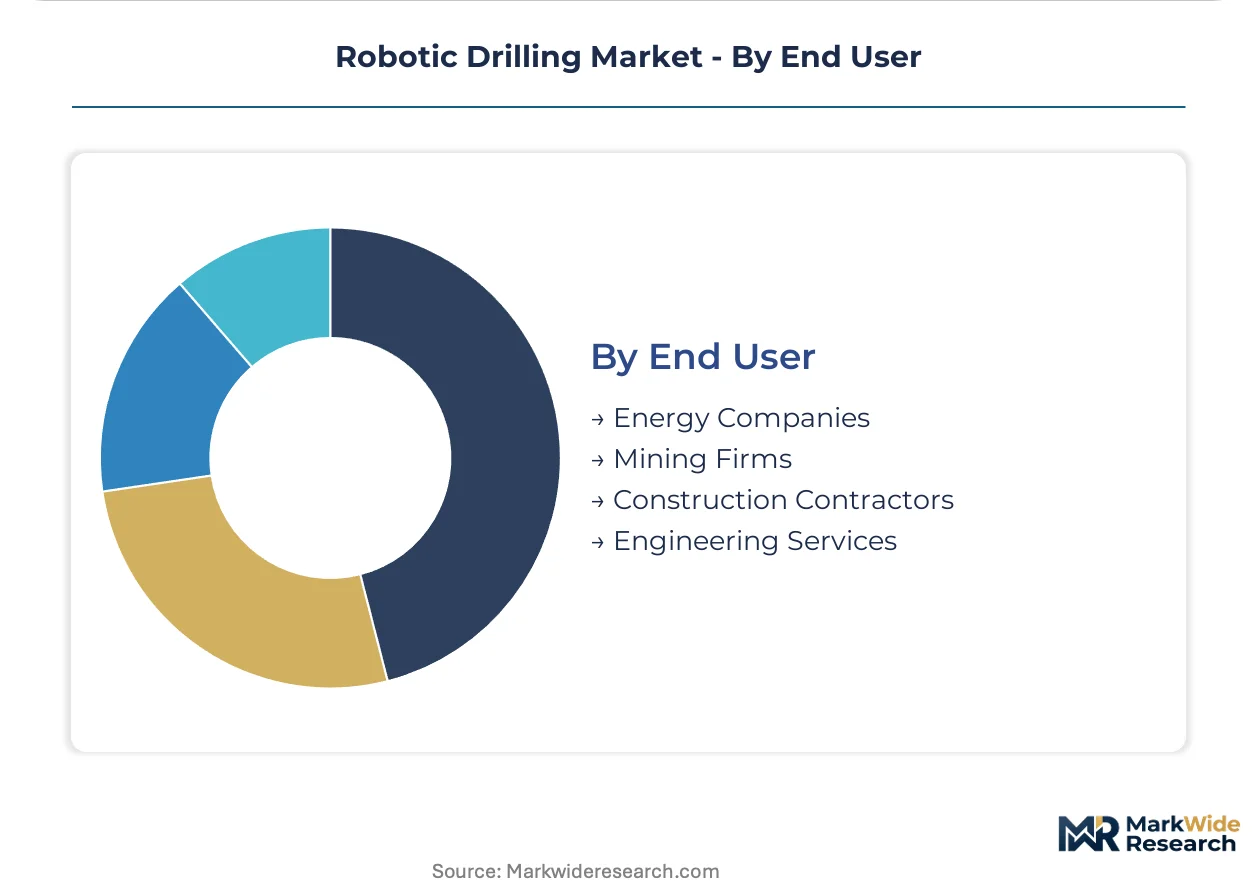
End User:
Procurement authority and balance sheet depth separate buyers capable of absorbing outcome-based contract volatility from those locked in day-rate structures.
- Energy Companies:Integrated majors and large independents specify automation in rig construction contracts and retrofit programs. Delaware Basin producers tie contractor compensation to drilling speed and wellbore quality metrics rather than time-on-location.
- Mining Firms:Diversified resource companies automate blasthole fleets to reduce workforce exposure in remote jurisdictions with escalating safety liability.
- Construction Contractors:Project-based procurement limits automation investment to specialized foundation and tunneling applications.
- Engineering Services:Third-party drilling management firms lack capital for fleet ownership but influence technology selection through consulting mandates.
Contract innovation concentrates among Energy Companies; standardization pressure rises for Engineering Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors North American robotic drilling supply chains, connecting Gulf Coast fabrication yards to Permian Basin operators. Norwegian North Sea infrastructure underwrites European offshore automation demand. East Asian port networks sustain Chinese and South Korean rig component exports.
United States
OSHA fall-protection mandates drive retrofit demand across pre-2010 land rigs in the Permian Basin and Bakken formations. BSEE well control regulations mandate sub-second kick detection for Gulf of Mexico drillships. Houston-Galveston corridor fabrication yards concentrate autonomous system integration for both offshore and onshore deployment.
Norway
North Sea decommissioning timelines and mature field automation sustain demand for remote-operated drilling systems. The EU Machinery Directive and ATEX certification requirements filter market access for non-compliant control vendors. Stavanger and Bergen host engineering clusters specializing in subsea robotics integration for harsh-environment platforms.
China
Domestic shale development in Sichuan and Xinjiang provinces accelerates land rig automation procurement. MIIT industrial equipment standards and GB certification protocols govern control system qualification for state-owned operator fleets. Shanghai and Tianjin port infrastructure supports drillstring component manufacturing for export markets.
Saudi Arabia
Aramco rig fleet modernization programs prioritize automation for gas field development in the Empty Quarter. Saudi Standards, Metrology and Quality Organization (SASO) technical regulations align with API Q2 for equipment import approval. Dhahran-Ras Tanura industrial corridor concentrates rig manufacturing joint ventures with Western technology licensors.
Brazil
Pre-salt deepwater development drives autonomous drilling system demand for floating production units. ANP regulatory requirements for well integrity management mandate closed-loop control architectures. Macaé and Rio de Janeiro serve as integration hubs for offshore automation retrofit programs.
Robotic Drilling Market Vendor Landscape
Listed leaders compete with private specialists across capital access and technology licensing dimensions. The supplier base concentrates around integrated rig manufacturers with captive controls development, while independent software vendors carve positions through AI-driven well construction platforms. Two archetypes dominate: full-stack automation providers and modular component specialists. Competitive moves center on strategic partnerships for fleet-wide data harmonization and selective backward integration into sensor hardware.
Within the integrated manufacturer tier, Nabors Industries Ltd and NOV Inc occupy positions anchored by rig manufacturing footprints and offshore retrofit dominance respectively. Schlumberger Limited exemplifies the software-anchored archetype, layering AI capabilities across heterogeneous rig platforms without hardware ownership. These three entities represent the structural fault lines between hardware-captive and software-agnostic competitive strategies.
| Leading Market Players |
|---|
| Nabors Industries Ltd |
| NOV Inc |
| Schlumberger Limited |
| Precision Drilling Corporation |
| Huisman Equipment B.V. |
| Weatherford International |
| Ensign Energy Services |
| Drillmec |
| Halliburton Company |
| Others |
Supply Flow & Price Mechanics
API Q2 and ISO 9001 certification cycles gate both supplier qualification and price differentiation simultaneously, with compliant autonomous systems commanding substantial premiums over uncertified alternatives while excluding non-compliant vendors from offshore procurement.
Pricing Analysis
Volume-discount tiering structures stratify across premium autonomous systems, standard hybrid retrofits, and economy-grade remote-controlled units. Certification level—specifically API Q2 and ATEX tier—drives the widest price spreads, followed by after-sales service bundling. Cost compression in the hybrid tier is intensifying because pre-2010 land rig operators demand phased automation without full replacement. Mining firms show highest price sensitivity due to project-based procurement cycles, while Gulf of Mexico drillship contractors demonstrate lowest sensitivity given regulatory non-compliance costs.
Supply Chain Analysis
Port congestion along the Houston-Galveston corridor and container availability on Asia-Pacific trade lanes elevate inbound logistics costs for control system hardware. Manufacturing concentrates in the United States, China, and Norway. High-grade alloy drillstring components and subsea control pods rest on specialized steel supply from Chinese and Indian mills. Single-source vulnerability concentrates in proprietary drilling software architectures from Houston and Aberdeen. Distribution runs through rig manufacturing joint ventures and direct OEM channels to operator fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage as multi-vendor data harmonization becomes the primary interoperability battleground, with AI-driven control layers displacing hardware-centric value capture.
For Market Incumbents: Compound captive controls development with selective sensor hardware acquisition to defend against modular software entrants. Nabors Industries Ltd and NOV Inc must accelerate backward integration into downhole measurement systems before independent AI vendors capture the control-to-actuation loop. Certification investment in ATEX and IECEx alignment opens Norwegian and UK offshore markets without duplicate testing overhead. For New Entrants and Emerging Players: Differentiate on geothermal hard-rock automation adapted to crystalline formations beneath the Great Basin, where United States Department of Energy funding outpaces supply-side capability. The most penetrable segment sits in pre-2010 land rig hybrid retrofits across the Permian Basin, where operators seek incremental crew reduction without full asset retirement. A go-to-market angle through engineering services consulting mandates bypasses capital barriers to fleet ownership. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rig manufacturing specialists holding captive automation R&D but lacking software-anchored valuation multiples. Long-term viability hinges on 5-10 year conversion of day-rate contracts to performance-based structures in United States land markets. The signal to watch is Delaware Basin operator willingness to tie contractor compensation to drilling speed and wellbore quality metrics rather than time-on-location.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Vendor Data Harmonization Platform | Unified control architectures reduce operator dependence on single-vendor lock-in across mixed NOV, Schlumberger, and proprietary rig fleets. |
| Geothermal Hard-Rock Automation Development | Specialized bit dynamics and thermal management capture United States Department of Energy funding for enhanced geothermal systems. |
| Remote Operations Center Buildout | Real-time drilling command from onshore facilities reduces helicopter logistics costs for North Sea and Gulf of Mexico assets. |
| Cyber-Physical Security Engineering Investment | OT-security talent acquisition addresses ransomware exposure on connected drilling assets facing regulatory scrutiny. |
| Performance-Based Contract Structure Transition | Outcome-based compensation ties contractor payment to drilling speed and wellbore quality metrics in Delaware Basin deployments. |
Methodological Framework
Initial hypotheses were tested against primary input from rig automation engineers, offshore drilling contractors, E&P procurement directors, and control system software architects and refined through secondary validation against BSEE regulatory filings, API certification databases, OSHA enforcement records, and rig construction contract disclosures. Bottom-up triangulation across equipment shipment data and top-down reconciliation with operator capital expenditure announcements anchored volume estimates.
Variance decomposition across product type, technology layer, application risk profile, and end-user procurement authority structured the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated BSEE Well Control Rule compliance timelines and United States Department of Energy geothermal funding trajectories.
Decision-makers should treat outputs as directional under sustained oil price bands and regulatory enforcement intensity; material deviation would warrant model refresh. Specific risk factors include raw material price volatility in high-grade alloy supply and cybersecurity incident frequency on connected drilling assets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Automated Guided Vehicle (AGV) Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
SCARA Robots Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
Marine Robots Market
Robotics and Automation
Self-Driving Floor Scrubbers Market
Robotics and Automation
Servo Gripper Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Smart Sweeper Market