
 Europe Lidar Market | 2026-2036
Europe Lidar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lidar Market Foresight
Multi-source procurement for photonics components is hardening across European lidar supply chains. RIEGL Laser Measurement Systems GmbH anchors Austrian production of long-range laser scanners for surveying and defense applications. Hexagon AB leverages its Leica Geosystems subsidiary to dominate precision measurement workflows across Nordic infrastructure projects. SICK AG specializes in industrial safety lidar, competing aggressively for warehouse automation contracts in Germany and the Netherlands.
Europe Lidar denotes light detection and ranging systems that emit pulsed or continuous-wave laser radiation—typically at 905 nm or 1550 nm wavelengths—and measure return time or frequency shift to generate dense three-dimensional point clouds for spatial mapping and object detection. Solid-state lidar is displacing mechanical rotating assemblies in automotive qualification programs, driven by shock resistance and packaging constraints. 3D lidar captures the dominant share of mapping and navigation applications, while multibeam configurations are gaining traction in environmental monitoring deployments across Alpine and coastal zones.
The EU AI Act imposes conformity requirements on autonomous decision-making systems, directly affecting lidar validation protocols for automotive and security end users. CE marking under the Machinery Directive and EASA's evolving unmanned aircraft standards shape product access across industrial and aerospace segments. Stakeholders must monitor how ECHA's restricted substance lists interact with laser diode metallization and gallium arsenide wafer supply chains.
Market Dynamics
Solid-state lidar architectures are compressing mechanical component counts across European automotive qualification pipelines, forcing supply chain reconfiguration around semiconductor-grade manufacturing protocols.
Growth Catalysts
- EU AI Act compliance mandates:Conformity requirements for autonomous decision-making systems are accelerating validation investments in spatial perception hardware across German and French OEM programs.
- Alpine environmental monitoring:Multibeam lidar deployments for glacial mapping and avalanche prediction are expanding procurement from research consortia in Austria, Switzerland, and Italy.
- 1550 nm wavelength adoption:Eye-safe laser sources are enabling longer-range detection thresholds for highway-speed autonomous platforms without pedestrian exposure restrictions.
Market Restraints
- Gallium arsenide wafer concentration:European lidar manufacturers remain dependent on Asian substrate suppliers for high-electron-mobility transistor fabrication.
- ECHA substance restrictions:Candidate list updates targeting heavy metals in laser diode packaging are complicating metallization processes for 905 nm emitter assemblies.
- Mechanical lidar residual demand:360-degree rotating units retain cost advantages in surveying applications, delaying full solid-state transition timelines.
Strategic Opportunities
- Polish industrial automation corridor:Warehouse robotics deployments in Silesian logistics hubs remain underserved by incumbent German safety lidar suppliers.
- Photonics convergence with quantum sensing:Gravity gradiometry integration with lidar point clouds is opening defense and geodesy applications previously closed to standalone optical systems.
- CE marking streamlining:Machinery Directive harmonization for collaborative robots is reducing certification duplication for lidar-based human-machine interface modules.
Industry Challenges
- Optomechanical assembly talent scarcity:Precision alignment specialists for MEMS mirror integration are concentrated in Dutch and German photonics clusters, creating recruitment bottlenecks.
- Automotive SPICE compliance timelines:Software process maturity requirements for Level 3+ driving systems are extending development cycles by 18-24 months for lidar perception stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lidar Market |
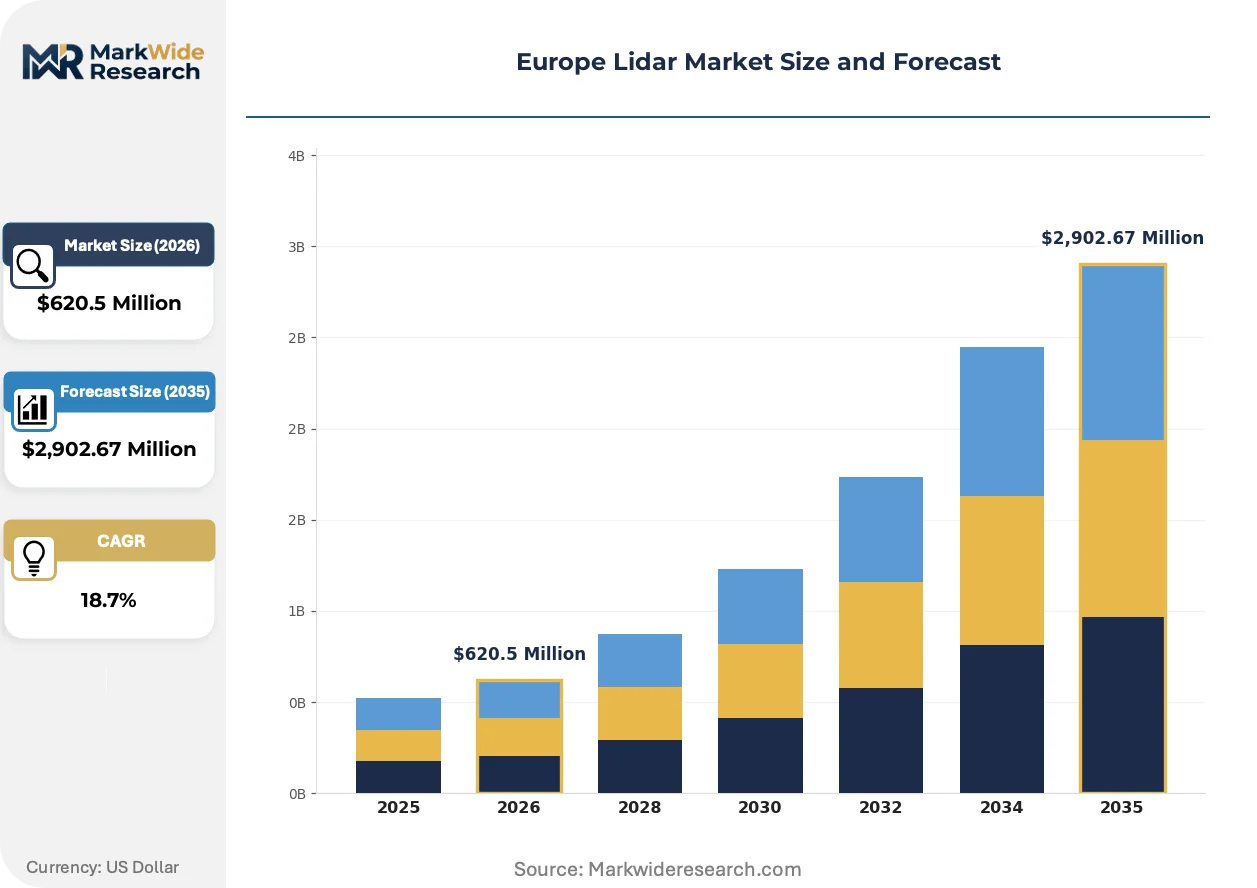
| Market Size in 2026 | $620.5 Million |
| Market Size in 2035 | $2,902.67 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Lidar, Mechanical Lidar, Frequency Modulated Continuous Wave Lidar, Flash Lidar End User: Automotive, Aerospace, Agriculture, Infrastructure Technology: 2D Lidar, 3D Lidar, Multibeam Lidar, Velocimeter Lidar Application: Mapping, Navigation, Environmental Monitoring, Security |
| Companies Covered | Leica Geosystems AG, Hexagon AB, RIEGL Laser Measurement Systems GmbH, Trimble Inc., Topcon Corporation, FARO Technologies Inc., Teledyne Technologies Inc., YellowScan, SICK AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lidar Market Shifts & Advancements
European lidar development is pivoting from hardware performance metrics toward perception software integration, with validation protocols increasingly dominating competitive differentiation.
Frequency-modulated continuous-wave lidar is integrating coherent detection principles to enable direct velocity measurement alongside ranging. German Tier 1 suppliers are embedding FMCW modules into highway pilot systems for 2026 platform launches. This architecture is integrating Doppler capability without separate radar sensor provisioning, compressing sensor fusion complexity and unit economics for Level 4 vehicle programs.
REACH substance screening is tightening disclosure requirements for laser diode substrate materials across the entire supply chain. Manufacturers must now document gallium, indium, and arsenic content through smelter and refiner verification. Automotive lidar producers with German final assembly are restructuring supplier qualification to pre-empt authorization sunset risks for critical III-V semiconductor inputs.
Performance-based validation contracts are displacing component-centric procurement in Nordic infrastructure mapping. Swedish and Norwegian transport agencies now specify point cloud accuracy guarantees rather than hardware specifications, transferring integration risk to lidar system vendors. Dutch water management authorities have adopted similar outcome frameworks for coastal erosion monitoring tenders, compressing traditional equipment sales cycles into multi-year service agreements.
Europe Lidar Market Segmentation
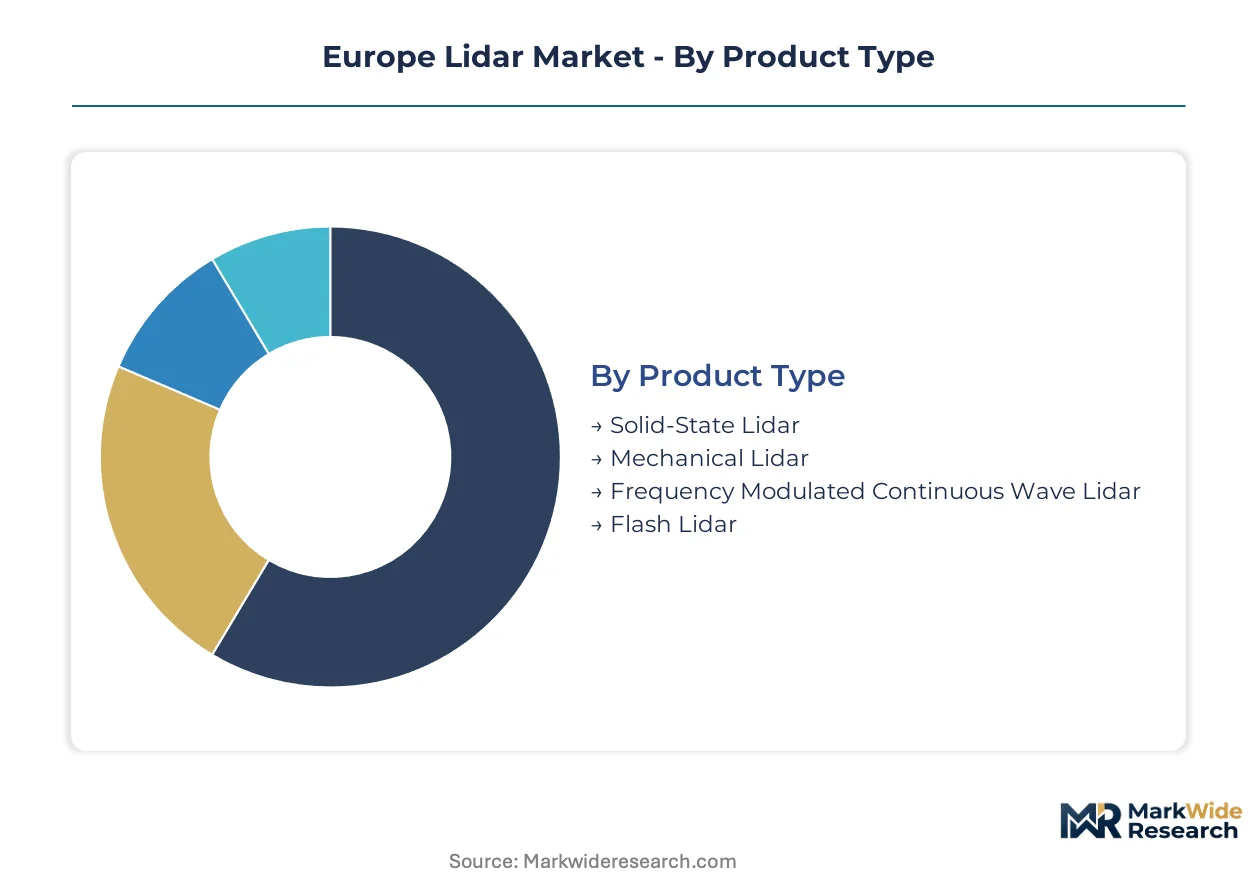
European lidar procurement patterns diverge sharply between embedded automotive systems and standalone surveying instruments. Understanding these integration-depth distinctions clarifies why solid-state architectures command premium valuations while mechanical units retain residual utility in geospatial workflows.
Product Type:
Standalone lidar systems dominate geospatial and defense contracting, whereas embedded automotive modules require semiconductor-grade manufacturing protocols and automotive SPICE compliance.
- Solid-State Lidar:MEMS mirrors and optical phased arrays eliminate rotating assemblies, delivering shock resistance for automotive qualification pipelines. German OEMs at BMW and Mercedes-Benz are embedding these units into Level 3 highway pilot systems, with validation cycles extending 18-24 months under EU AI Act conformity requirements.
- Mechanical Lidar:Motorized rotating heads generate 360-degree point clouds with proven field reliability. Surveying applications across Alpine corridors in Austria and Switzerland retain preference for these units due to cost advantages in terrestrial mapping workflows where packaging constraints are secondary.
- Frequency Modulated Continuous Wave Lidar:Coherent detection enables simultaneous ranging and velocity measurement through Doppler processing.
- Flash Lidar:Single-pulse illumination captures entire scenes without scanning mechanics, suited for short-range industrial safety applications.
Volume placements concentrate in Mechanical Lidar for geospatial contracting; the faster expansion belongs to Solid-State Lidar.
End User:
Cost-tier stratification separates million-unit automotive programs from thousand-unit infrastructure deployments, with aerospace and agriculture occupying intermediate volume positions.
- Automotive:Level 3 and Level 4 autonomous platforms integrate lidar as primary spatial perception sensors. Procurement concentrates in Germany's automotive corridor, where KBA type-approval processes and EU AI Act mandates are accelerating validation investments for highway-speed detection systems.
- Aerospace:EASA unmanned aircraft standards and emerging detect-and-avoid requirements are shaping product specifications for drone-mounted mapping systems. Leica Geosystems and RIEGL supply long-range units for aerial survey consortia.
- Agriculture:Precision farming applications leverage terrain mapping for variable-rate input application across Nordic and French arable regions.
- Infrastructure:Swedish and Norwegian transport agencies specify point-cloud accuracy guarantees rather than hardware specifications, compressing equipment sales into multi-year service agreements for coastal erosion and glacial monitoring.
Revenue concentration sits with Automotive; Infrastructure is climbing the fastest as performance-based contracting displaces component-centric procurement.
Technology:
Dimensionality and beam configuration determine integration complexity, with 3D architectures dominating navigation while multibeam systems gain traction in environmental monitoring.
- 3D Lidar:Dense point-cloud generation enables object classification and scene reconstruction for autonomous navigation. Deployment concentrates in German automotive qualification programs and Dutch warehouse robotics, where SICK AG competes for safety-lidar contracts.
- Multibeam Lidar:Simultaneous multiple-angle illumination captures complex topography without platform motion. Austrian and Swiss research consortia deploy these systems for Alpine glacial mapping and avalanche prediction networks.
- 2D Lidar:Single-plane scanning suffices for planar obstacle detection in constrained industrial environments.
- Velocimeter Lidar:Doppler-shift measurement targets wind-field characterization and traffic-flow monitoring applications.
3D Lidar captures dominant placement volumes; Multibeam Lidar is gaining share fastest in environmental monitoring tenders.
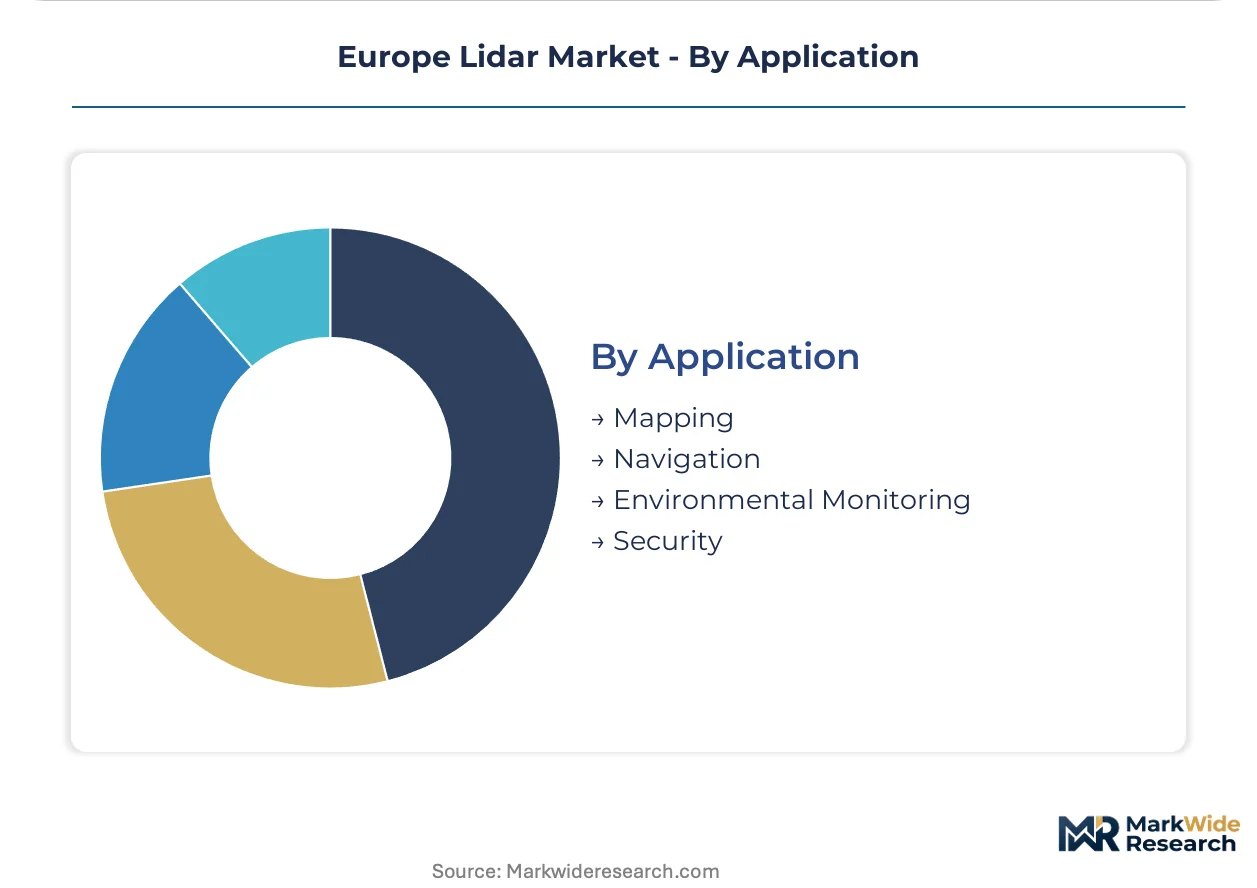
Application:
Customer-type differentiation separates government-funded environmental programs from commercial security and navigation deployments, with mapping serving dual constituencies.
- Mapping:Topographic survey, urban modeling, and heritage documentation drive demand across Nordic infrastructure agencies and Central European engineering consultancies. Hexagon AB's Leica Geosystems subsidiary dominates precision measurement workflows through established distribution channels.
- Navigation:Real-time localization and path planning for autonomous systems require sub-centimeter accuracy at highway speeds. German Tier 1 suppliers are embedding FMCW modules into 2026 platform launches to compress sensor-fusion complexity.
- Environmental Monitoring:Dutch water management authorities and Italian coastal protection agencies specify outcome-based contracts for erosion and flood-risk assessment.
- Security:Perimeter surveillance and critical infrastructure protection deploy eye-safe 1550 nm sources for extended-range detection without pedestrian exposure restrictions.
Mapping retains the largest installed base; Navigation is expanding most quickly as automotive SPICE-compliant stacks reach production maturity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for lidar procurement clusters in Germany's automotive corridor, where BMW and Mercedes-Benz Level 3 programs are accelerating sensor validation timelines under EU AI Act mandates.
Germany
KBA type-approval processes and automotive SPICE compliance requirements are extending development cycles for highway-speed detection systems. The EU AI Act imposes conformity obligations on autonomous decision-making systems, directly affecting lidar validation protocols. Bavaria's Munich-Stuttgart industrial axis anchors embedded automotive lidar production for 2026 platform launches.
France
Autonomous vehicle testing programs in the Paris-Saclay cluster are driving procurement for environmental monitoring and navigation applications. ANSM and CNIL guidance on AI system transparency shapes product development for security end users. The Île-de-France region concentrates R&D investment for solid-state architectures targeting Level 4 driving platforms.
Austria
Alpine glacial mapping and avalanche prediction networks are expanding multibeam lidar deployments from research consortia. EASA unmanned aircraft standards influence product specifications for drone-mounted survey systems. Tyrol and Salzburg host specialized production of long-range laser scanners for defense and geodesy applications.
Netherlands
Dutch water management authorities specify outcome-based contracts for coastal erosion monitoring, compressing equipment sales into multi-year service agreements. REACH substance screening tightens disclosure requirements for laser diode materials across supply chains. The Randstad logistics corridor drives warehouse robotics demand for industrial safety lidar from SICK AG and competitors.
Sweden
Swedish transport agencies specify point-cloud accuracy guarantees rather than hardware specifications, transferring integration risk to system vendors. CE marking under the Machinery Directive shapes product access for collaborative robot applications. Stockholm and Gothenburg anchor Nordic infrastructure mapping workflows dominated by precision measurement specialists.
Europe Lidar Market Competitive Landscape
Portfolio diversification dominates the current landscape as vendors restructure around semiconductor-grade manufacturing protocols and perception software integration. The vendor base spans three distinct tiers: automotive-embedded specialists, geospatial instrument incumbents, and industrial safety providers. Two strategic archetypes have emerged: full-stack system vendors capturing outcome-based service contracts, and component suppliers feeding Tier 1 automotive integrators. M&A activity and technology licensing agreements represent the dominant competitive vectors as firms address optomechanical assembly talent scarcity.
Among precision measurement specialists, Leica Geosystems AG and Hexagon AB exemplify the geospatial instrument archetype through established distribution channels across Nordic infrastructure projects. RIEGL Laser Measurement Systems GmbH anchors the defense-surveying intersection with Austrian-based production of long-range units. These three entities occupy positions spanning standalone terrestrial mapping, aerial survey consortia, and emerging autonomous platform integration.
| Leading Market Players |
|---|
| Leica Geosystems AG |
| Hexagon AB |
| RIEGL Laser Measurement Systems GmbH |
| Trimble Inc. |
| Topcon Corporation |
| FARO Technologies Inc. |
| Teledyne Technologies Inc. |
| YellowScan |
| SICK AG |
| Others |
Supply & Pricing Matrix
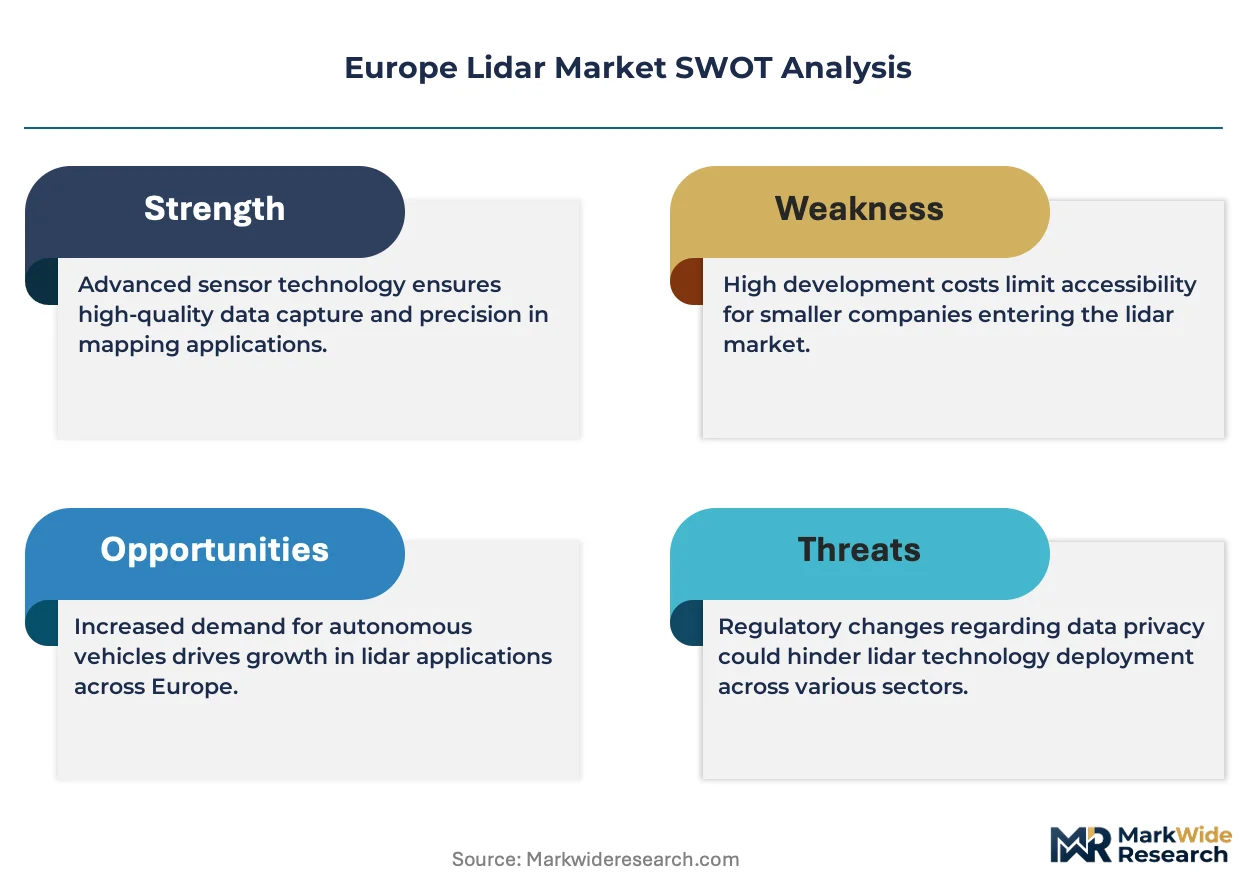
Automotive-grade certification tiers split European lidar procurement into sharply divergent cost structures, with CE-marked highway-speed units commanding multiples over industrial safety variants while supply chains reorganize around semiconductor-grade cleanroom protocols versus mechanical assembly workflows.
Pricing Analysis
Volume-vs-margin splits separate million-unit automotive programs from thousand-unit geospatial contracts. Three-tier pricing structure across automotive-grade, industrial-certified, and survey-economy levels reflects EU AI Act validation burdens and KBA type-approval costs. Pricing pressure stems from gallium arsenide wafer scarcity forcing substitution toward silicon photonics. Automotive OEMs exhibit lowest price sensitivity; Nordic infrastructure agencies negotiate hardest on outcome-based service terms.
Supply Chain Analysis
Precision optomechanical assembly talent scarcity concentrates in Dutch and German photonics clusters, constraining MEMS mirror integration capacity. European lidar production draws from Asian gallium arsenide substrate suppliers, German laser diode packaging facilities, and Austrian long-range scanner assembly. Single-source vulnerability in III-V semiconductor inputs threatens authorization sunset exposure under ECHA candidate list updates. Distribution runs through Tier 1 automotive integrators in Bavaria and precision measurement distributors across Nordic engineering consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races are intensifying as vendors pursue captive control over gallium arsenide wafer supply to preempt ECHA authorization risks and secure automotive SPICE-compliant production pipelines.
For Market Incumbents: Anchor defensive positioning through backward integration into laser diode metallization and gallium arsenide substrate sourcing. Incumbent RIEGL and Hexagon AB must preempt ECHA substance restrictions by restructuring supplier qualification protocols. Capacity addition in Austrian and German photonics clusters secures optomechanical assembly talent pools against recruitment bottlenecks.
For New Entrants and Emerging Players: Enter via Polish Silesian logistics hubs where warehouse robotics demand outpaces German safety lidar incumbent coverage. The most penetrable segment sits in flash lidar for short-range industrial safety applications underserved by SICK AG's multibeam focus. Go-to-market leverage rests on CE marking streamlining under Machinery Directive harmonization for collaborative robots.
For Investors and Strategic Acquirers: Re-rating potential sits with FMCW module specialists given German Tier 1 highway pilot integration timelines. Long-term viability favors vendors bridging semiconductor-grade manufacturing with perception software stacks. Acquisition target archetype: Austrian or Swiss multibeam developers with Alpine environmental monitoring installed base. Watch EASA unmanned aircraft standard finalization as inflection signal for drone-mounted mapping system procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into III-V Semiconductor Supply | ECHA authorization sunset risks force captive gallium arsenide wafer sourcing for German automotive lidar producers. |
| FMCW Module Platform Integration | Coherent detection architectures compress sensor fusion complexity for BMW and Mercedes-Benz Level 4 programs. |
| Outcome-Based Service Contract Conversion | Swedish and Norwegian transport agencies now specify point cloud accuracy guarantees rather than hardware specifications. |
| CE Marking Streamlining Investment | Machinery Directive harmonization reduces certification duplication for lidar-based collaborative robot modules. |
| Photonics-Quantum Sensing Convergence | Gravity gradiometry integration opens defense and geodesy applications previously closed to standalone optical systems. |
Research Methodology
Independent corroboration across Tier 1 supplier procurement officers, OEM platform engineers, and precision measurement distribution heads underwrites the qualitative findings. Primary interviews with automotive SPICE compliance leads, EASA unmanned aircraft certification specialists, and Nordic infrastructure agency procurement managers combined with secondary validation from KBA type-approval databases, ECHA restricted substance filings, and EU AI Act conformity documentation. Bottom-up segment sizing and top-down macroeconomic cross-checks triangulate volume and value estimates.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product architecture, end-user industry, technology dimensionality, and application type, with additional granularity on automotive autonomy level and infrastructure contracting mode. CAGRs derive from fitted growth curves benchmarked against historical semiconductor component penetration patterns and automotive sensor adoption cycles. Industry-specific forecast inputs incorporate EU AI Act implementation timelines and EASA unmanned aircraft standard evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA substance list acceleration or automotive SPICE compliance timeline extensions. Forecasts reflect documented assumptions on regulatory implementation pacing and semiconductor supply chain normalization. Material deviation in gallium arsenide wafer authorization status or German automotive platform launch schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Wireless Synchronized Clocks Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Traffic Sensor Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Vision Positioning System Market
Sensors
Eye Tracking Market
Sensors
Weigh-In-Motion System Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Refrigeration Monitoring Market
Sensors
India Asset Tracking Market
Sensors
Personal Navigation Devices Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Global RFID Market
Sensors
Temperature Data Loggers Market
Sensors
Global Load Monitoring System (LMS) Market