
 Alcohol Sensor Market | 2026-2036
Alcohol Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Sensor Market Intelligence
The performance gap between high-precision electrochemical sensors for law enforcement and lower-cost semiconductor units for personal use is expanding. Drägerwerk AG & Co. KGaA specializes in certified devices for police and medical applications, sustaining its position through rigorous quality control. Lifeloc Technologies, Inc. competes on the accuracy and reliability of its fuel cell-based breathalyzers for professional markets. In contrast, other firms target the consumer segment with less stringent performance requirements and lower price points.
An alcohol sensor is an analytical device designed to measure the concentration of ethanol in a gaseous sample, typically human breath. Most professional-grade units employ an electrochemical fuel cell that oxidizes alcohol to produce a measurable electrical current proportional to the breath alcohol content. Electrochemical sensors dominate the product landscape due to their superior accuracy and stability over time. While law enforcement remains a core application, automotive safety systems are a rapidly advancing area for new sensor integration.
Product standards are shaped by directives from bodies like the NHTSA in the United States and requirements for CE marking in Europe. These regulations dictate sensor accuracy, calibration frequency, and reliability for use in ignition interlock devices and evidentiary breathalyzers. Sensor manufacturers must therefore align product development and certification with evolving regional mandates for passive alcohol detection in vehicles to ensure market access and compliance.
Market Dynamics
The central force shaping the alcohol sensor market is intensifying regulatory pressure for vehicle safety integration. Mandates advanced by bodies like the NHTSA in the United States are compelling automotive manufacturers to incorporate passive alcohol detection, shifting the market's center of gravity.
Growth Catalysts
- Automotive Safety Mandates:Forthcoming regulations in North America, particularly from the NHTSA, require passive alcohol detection systems in new vehicles, creating a substantial, long-term demand channel for automotive-grade sensors.
- Electrochemical Sensor Precision:Law enforcement and medical sectors continue to drive demand for high-accuracy electrochemical fuel cell sensors due to their evidentiary-grade reliability and stability for breath alcohol measurement.
- Workplace Safety Policies:Expansion of zero-tolerance policies in industrial, logistics, and mining sectors across Europe and Australia is increasing the requirement for routine employee alcohol screening with certified devices.
Market Restraints
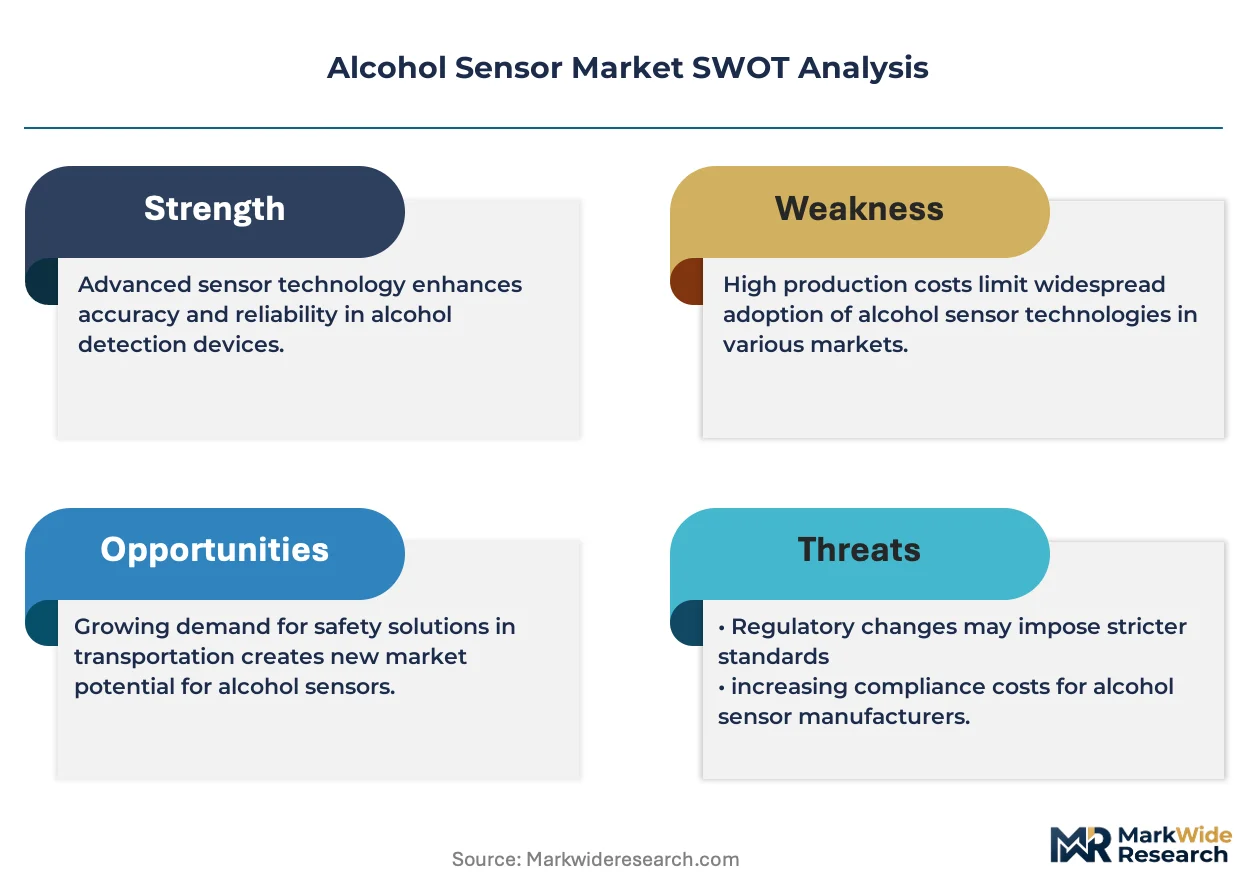
- High Input Material Costs:The price of platinum, a critical catalyst in high-performance electrochemical fuel cells, introduces significant cost volatility and margin pressure for manufacturers of professional-grade sensors.
- Semiconductor Sensor Limitations:Lower-cost semiconductor-based sensors exhibit cross-sensitivity to substances other than ethanol and suffer from sensor drift, limiting their application in legally binding or medical contexts.
- Divergent Certification Standards:Navigating disparate and lengthy certification processes, such as NHTSA approval in the US and CE marking for ignition interlocks in Europe, complicates global product launches and increases development costs.
Strategic Opportunities
- Smart Device Integration:Embedding miniaturized sensors into consumer electronics like smartphones or smart home systems presents a new frontier for personal wellness monitoring and parental control applications.
- Expansion in Asia-Pacific:As countries like India and Australia tighten road safety laws and drunk-driving enforcement, significant white space exists for both personal breathalyzers and vehicle ignition interlock devices.
- Biometric Sensor Fusion:Combining alcohol detection with biometric identifiers such as fingerprint or facial recognition can enhance the security and reliability of ignition interlock systems, preventing circumvention.
Industry Challenges
- Automotive Certification Timelines:The extensive testing and validation required to meet automotive-grade reliability and obtain NHTSA certification for in-vehicle passive sensors represents a multi-year, capital-intensive barrier for suppliers.
- False Positive Mitigation:Integrating passive sensors into vehicle cabins requires sophisticated software and hardware solutions to distinguish between driver breath and ambient alcohol sources, preventing erroneous vehicle lockouts.
- Calibration Standardization:The lack of a universal standard for the required frequency and procedure for sensor calibration creates operational inconsistencies for law enforcement agencies and commercial fleets operating across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Sensor Market |
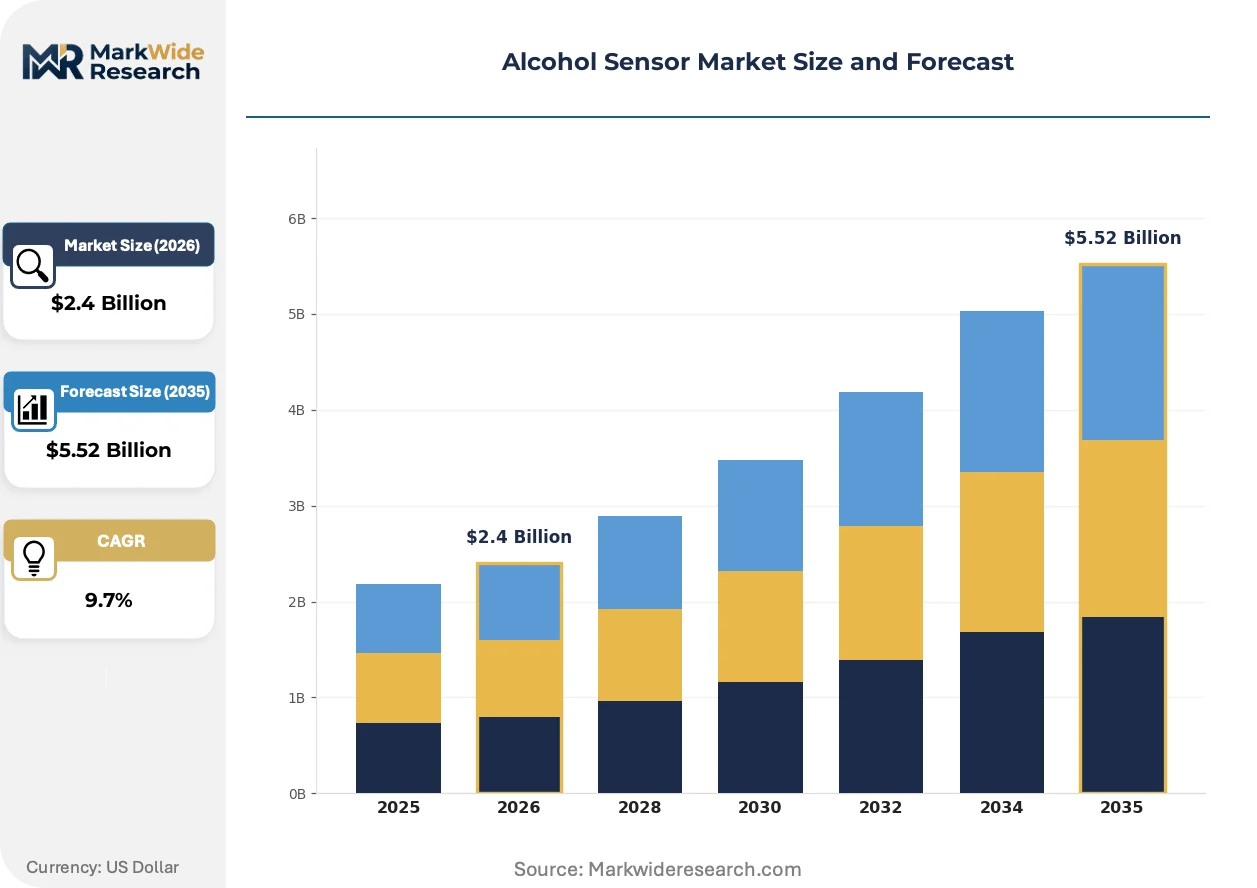
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical, Semiconductor, Infrared Optical, Fuel Cell, Photoionization Detector Application: Breathalyzers, Workplace Safety, Medical Diagnostics, Law Enforcement, Automotive Safety Systems Technology: Gas Sensing, Optical Sensing, Chemical Sensing, Nanotechnology, Wireless Communication End User: Transportation Operators, Manufacturing Facilities, Healthcare Providers, Public Safety Agencies, Research Laboratories |
| Companies Covered | Drägerwerk AG & Co. KGaA, Lifeloc Technologies, Inc., Intoximeters, Inc., Alcohol Countermeasure Systems Corporation, AlcoPro, Inc., Abbott, Honeywell International Inc., Asahi Kasei Corporation, Quest Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Sensor Market Strategic Shifts & Innovations
The market's evolution is defined by a dual trajectory: the pursuit of higher precision for professional applications and the drive toward miniaturization for seamless integration into vehicles and personal devices. This technological push is occurring alongside a significant shift in regulatory frameworks and commercial models.
Miniaturized electrochemical sensors based on micro-electro-mechanical systems (MEMS) technology are reducing the physical footprint of detection units. Automotive Tier-1 suppliers and wearable device manufacturers are leading the adoption of these smaller, more power-efficient components. This development is converging with IoT connectivity to enable real-time, cloud-based monitoring for applications like commercial fleet management and remote parolee supervision, creating new service-based revenue streams.
European Union directives, including the updated General Safety Regulation (GSR), are creating a strong pull for advanced driver-assistance systems. The regulation encourages technologies that monitor for driver impairment, including alcohol detection, compelling automakers to integrate compliant sensor systems to access the EU market. This affects Tier-1 automotive suppliers most directly, who must now align their product roadmaps and secure CE marking to serve European vehicle platforms.
A notable shift from one-time hardware sales to subscription-based monitoring services is altering commercial models, especially in judicial and fleet management segments. This disrupts the traditional model of selling breathalyzers or interlocks as standalone products, with service providers now offering bundled packages that include calibration, data reporting, and compliance management. The trend is most pronounced in North America, where court-mandated ignition interlock programs are widely established.
Alcohol Sensor Market Segmentation
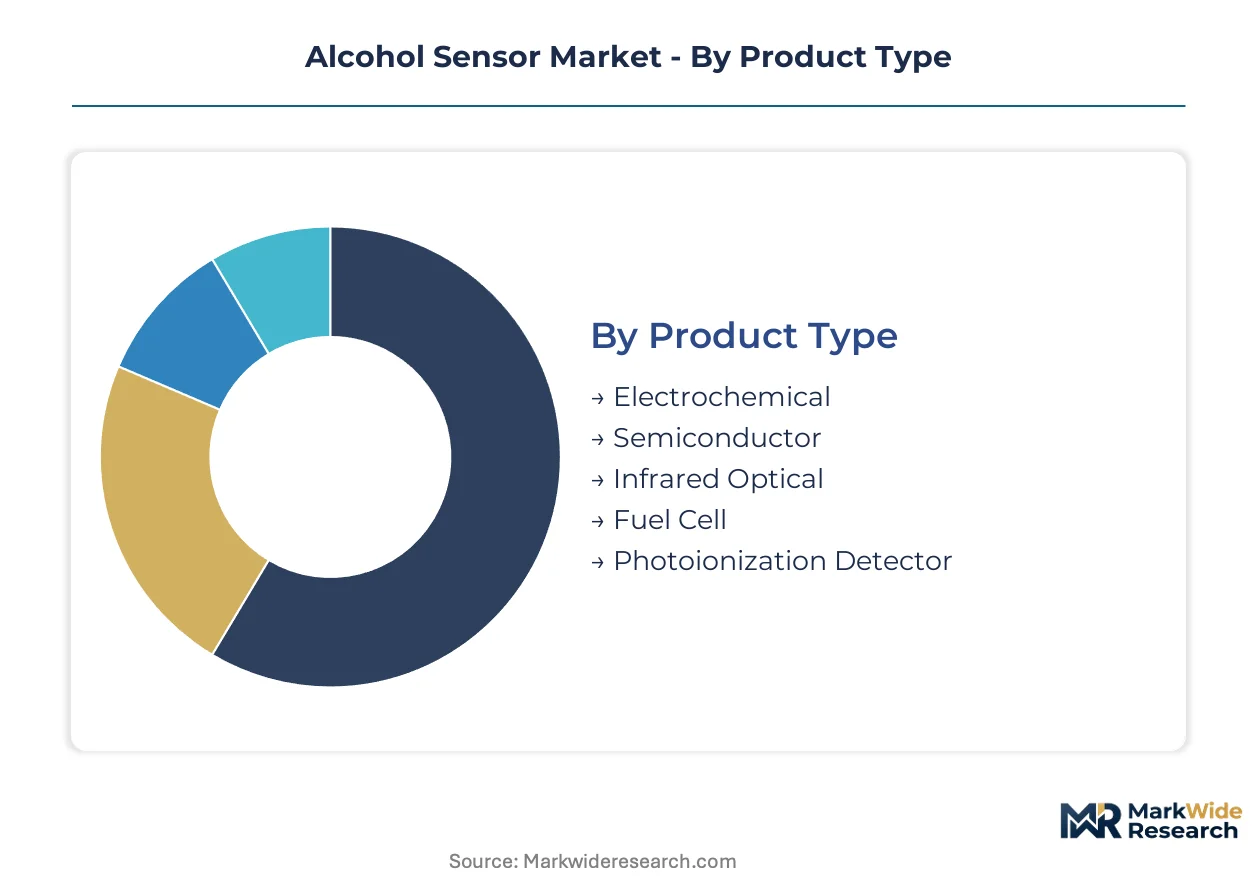
The alcohol sensor market is segmented to reveal the diverse technological approaches and end-use applications driving its expansion. This granular analysis highlights where value accrues across different product types and how specific user requirements dictate sensor performance and integration. Understanding these distinctions is crucial for strategic product development.
Product Type:
Supply concentration for alcohol sensor components primarily centers on advanced electrochemical and semiconductor manufacturing hubs.
- Electrochemical:These professional-grade sensors oxidize ethanol to generate a measurable electrical current, providing superior accuracy and stability for evidential use. Demand concentrates within law enforcement agencies and medical diagnostics due to stringent reliability requirements.
- Semiconductor:Lower-cost semiconductor units detect alcohol through changes in electrical resistance, offering an affordable solution for personal and consumer applications. These sensors find demand in personal breathalyzers, where cost-effectiveness often outweighs legal precision.
- Infrared Optical:Infrared optical sensors identify alcohol by measuring its absorption of specific infrared wavelengths, providing non-contact detection in some industrial settings.
- Fuel Cell:Fuel cell sensors operate by oxidizing alcohol to produce an electrical current, ensuring high specificity and long-term calibration stability for professional breath testing devices.
- Photoionization Detector:Photoionization detectors measure volatile organic compounds, including alcohol, by ionizing molecules with ultraviolet light for environmental monitoring.
Today's leader: Electrochemical. Tomorrow's challenger: Fuel Cell.
Application:
The deployment of alcohol sensors is primarily driven by specific functional needs across diverse operational environments.
- Automotive Safety Systems:These systems integrate passive alcohol detection directly into vehicles, mandated by regulations like those from the NHTSA, to prevent impaired driving incidents. Demand for these sensors is rapidly expanding within North American automotive manufacturing.
- Law Enforcement:Police forces utilize highly accurate, evidentiary-grade breathalyzers to measure blood alcohol content for legal proceedings and roadside screening. This application demands sensors with certified precision and robust calibration protocols.
- Breathalyzers:Personal breathalyzers provide individuals with a convenient tool for self-monitoring alcohol levels, typically employing lower-cost semiconductor or basic fuel cell technology.
- Workplace Safety:Industrial and commercial sectors implement alcohol screening devices to enforce zero-tolerance policies, protecting employees and assets in high-risk environments.
- Medical Diagnostics:Healthcare providers use alcohol detection devices for patient assessment, diagnosing intoxication, and managing treatment protocols in medical settings.
Automotive Safety Systems show the steepest expansion trajectory, while Law Enforcement maintains its foundational demand.
Technology:
Innovation in alcohol sensor technology is concentrating on enhancing precision, miniaturization, and seamless integration capabilities.
- Gas Sensing:This foundational technology involves detecting ethanol vapor in breath samples, primarily through electrochemical or semiconductor principles, forming the core of most breathalyzer devices. Its application is widespread in both professional and consumer units.
- Wireless Communication:Integrating sensors with wireless protocols enables real-time data transmission for remote monitoring, essential for fleet management and court-mandated interlock programs. This technology is gaining share fastest in IoT-enabled safety solutions.
- Optical Sensing:Optical methods use light absorption or reflection to identify alcohol molecules, offering potential for non-contact detection and advanced analytical systems.
- Chemical Sensing:Chemical sensing technologies utilize specific chemical reactions to detect alcohol, often employed in specialized industrial or laboratory instruments.
- Nanotechnology:Nanotechnology leverages nanoscale materials to create highly sensitive and miniaturized alcohol sensors, enabling integration into wearable devices.
Gas Sensing remains the dominant technological approach, with Wireless Communication exhibiting significant upward momentum.
End User:
Customer requirements for alcohol sensors vary significantly, driven by regulatory compliance, operational safety, and personal wellness goals.
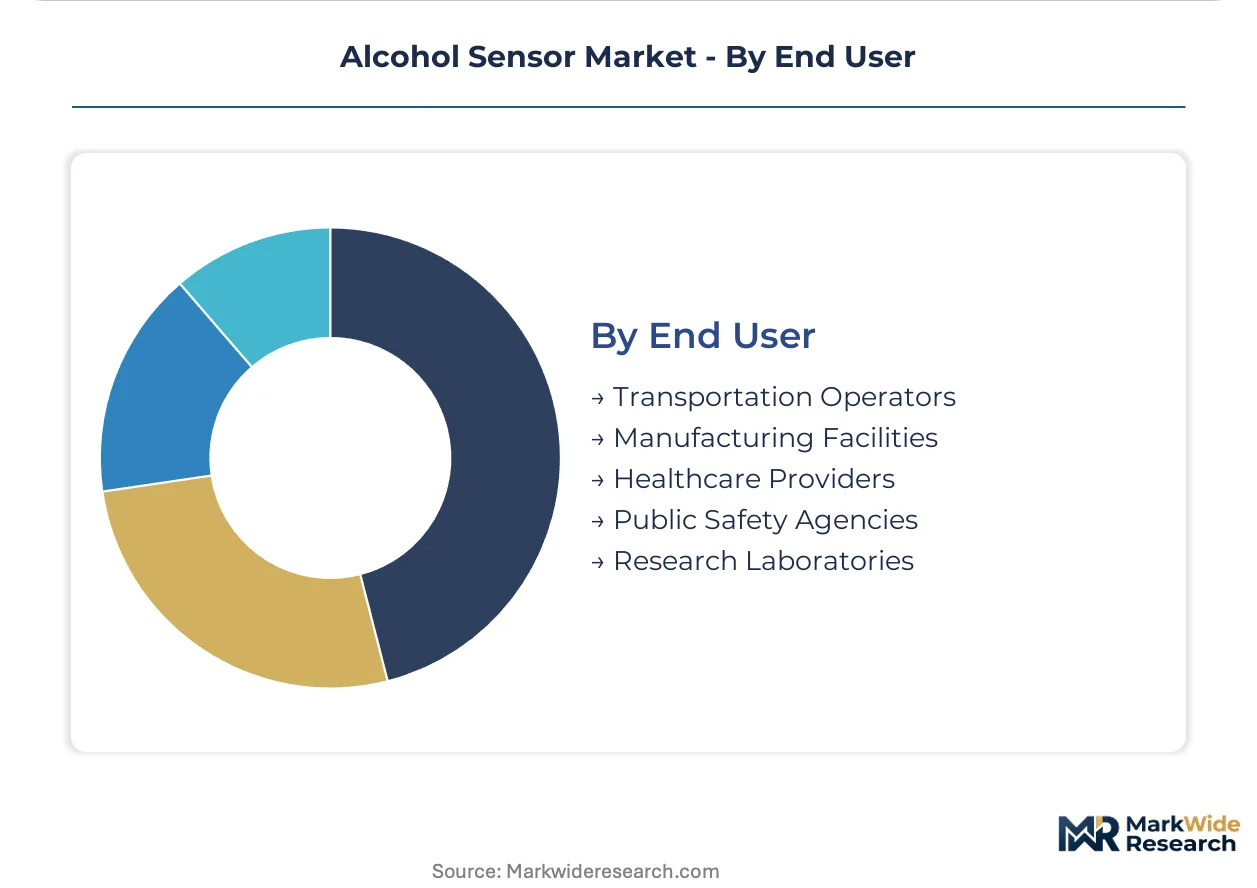
- Public Safety Agencies:Law enforcement and emergency services require certified, highly accurate alcohol sensors for evidentiary breath testing and roadside screening. These agencies prioritize reliability and regulatory compliance for their operations.
- Transportation Operators:Commercial fleets, logistics companies, and public transport providers implement alcohol screening to ensure driver sobriety and adhere to strict safety regulations. Demand from this segment is expanding due to increased workplace safety policies.
- Healthcare Providers:Hospitals and clinics utilize alcohol detection devices for patient assessment, diagnosing intoxication, and managing treatment protocols in medical settings.
- Manufacturing Facilities:Industrial plants and production facilities deploy alcohol sensors to enforce workplace safety standards, preventing accidents caused by impairment.
- Research Laboratories:Academic and private research institutions use alcohol sensors for controlled experiments and developing new detection methodologies.
Public Safety Agencies form the core demand segment, while Transportation Operators are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highly skilled engineering talent drives innovation within key automotive and medical device manufacturing hubs. These concentrations of expertise are crucial for advancing alcohol sensor technology. Regulatory mandates from national safety bodies further shape market expansion across diverse geographies.
United States
Demand for alcohol sensors intensifies from automotive safety mandates and law enforcement applications. The NHTSA's forthcoming regulations compel vehicle manufacturers to integrate passive alcohol detection systems. Detroit's automotive cluster focuses on integrating these advanced sensors into new vehicle platforms.
Germany
European directives, including CE marking requirements, influence the development of high-precision alcohol sensors for medical and professional use. Drägerwerk AG & Co. KGaA, based in Lübeck, exemplifies German engineering in certified devices for police and medical applications. The automotive sector in Bavaria also drives demand for in-vehicle safety systems.
China
Significant growth in automotive production and increasing road safety awareness propel the alcohol sensor market. The MIIT's focus on intelligent vehicle safety systems encourages local manufacturers to innovate. Manufacturing hubs in the Yangtze River Delta are developing both professional-grade and consumer alcohol detection units.
India
Expanding road safety laws and stricter drunk-driving enforcement create substantial opportunities for personal breathalyzers and interlock devices. BIS standards for automotive components will increasingly include alcohol detection systems. Automotive manufacturing centers like Chennai and Pune are exploring integration into new vehicle models.
Australia
Workplace safety policies in mining and logistics sectors, alongside tightening road safety laws, increase demand for certified alcohol screening. The TGA mandates compliance for medical-grade breathalyzers used in healthcare settings. Sydney's technology sector sees interest in smart device integration for personal wellness monitoring.
Alcohol Sensor Market Key Industry Players
Top-tier vendors anchor the professional and medical-grade segments, while lower-cost semiconductor unit providers cater to the consumer market. The competitive landscape features a distinct bifurcation between specialized manufacturers of high-precision evidentiary devices and firms targeting broader consumer segments. Strategic archetypes include precision instrument specialists, mass-market consumer electronics suppliers, and automotive system integrators. Companies pursue strategic partnerships for automotive integration and portfolio diversification into new application areas, alongside continuous R&D for miniaturization.
Within the precision instrument specialist archetype, Drägerwerk AG & Co. KGaA, a German company, maintains its position through certified devices for police and medical applications, emphasizing rigorous quality control. Lifeloc Technologies, Inc., a US-based corporation, exemplifies expertise in fuel cell-based breathalyzers, competing on accuracy and reliability for professional markets. Intoximeters, Inc. also occupies this segment, focusing on evidentiary breath testing devices that meet stringent performance requirements. These firms collectively demonstrate a commitment to high-end solutions, contrasting with providers in the consumer segment.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Lifeloc Technologies, Inc. |
| Intoximeters, Inc. |
| Alcohol Countermeasure Systems Corporation |
| AlcoPro, Inc. |
| Abbott |
| Honeywell International Inc. |
| Asahi Kasei Corporation |
| Quest Products, Inc. |
| Others |
Cost & Logistics Intelligence
Miniaturized electrochemical sensors based on MEMS technology are reshaping production economics, driving down unit costs while concentrating supply among specialized component manufacturers. This shift influences pricing strategies and global supply chain dynamics within the alcohol sensor market.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing in the alcohol sensor market, with subscription-based monitoring services dominating judicial and fleet management segments. These services offer comprehensive packages including calibration and data reporting, contrasting with per-unit transactional pricing for standalone devices. Price differentiation stems from certification levels, such as NHTSA or CE marking, and the accuracy grade of the sensor technology. Pricing pressure intensifies due to high input material costs like platinum for professional-grade electrochemical sensors. Consumer segments exhibit the highest price sensitivity, prioritizing affordability over stringent performance.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers of platinum-based electrochemical fuel cells, a critical catalyst for high-performance sensors. Geographic supply concentrations are notable in China for general manufacturing and Germany for precision devices. Raw material dependencies include platinum and advanced MEMS components, contributing to commodity price volatility as a structural risk. Distribution runs through direct sales channels to law enforcement, Tier-1 automotive suppliers, and consumer electronics retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alcohol sensor market presents a clear margin-expansion story, driven by the increasing integration of premium, certified sensors into automotive safety systems. Miniaturization through MEMS technology also offers significant cost-down opportunities, enhancing profitability.
For Market Incumbents: Anticipate intensifying regulatory pressures by proactively investing in NHTSA and CE marking certifications for new automotive-grade sensors. Form strategic partnerships with Tier-1 automotive suppliers to secure design wins and mitigate market entry barriers from emerging competitors. Deepen R&D efforts into miniaturized electrochemical sensors to counter the threat of lower-cost semiconductor units. Maintain strong relationships with law enforcement agencies through consistent product quality and reliable calibration services.
For New Entrants and Emerging Players: Underserved consumer electronics users represent a significant white space for personal alcohol monitoring solutions. Target this segment with miniaturized, cost-effective semiconductor sensors integrated into smart devices and wearables. Leverage IoT connectivity to offer subscription-based personal wellness monitoring and parental control applications. Focus on user experience and seamless integration to differentiate from established professional-grade providers.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component manufacturers with strong IP in MEMS technology or advanced sensor materials. The market offers long-term viability due to robust regulatory tailwinds and expanding automotive integration. Target acquisition candidates include software providers offering IoT connectivity and data analytics for fleet management or remote monitoring. Watch for increasing OEM announcements regarding standard integration of passive alcohol detection in new vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Pursue NHTSA & CE Certification | Secures market access for passive alcohol detection systems in North American and European automotive sectors. |
| Invest in MEMS Miniaturization | Reduces sensor footprint and power consumption, enabling broader integration into wearables and smart devices. |
| Develop Subscription Monitoring Services | Shifts revenue model from one-time hardware sales to recurring income streams for judicial and fleet clients. |
| Form Automotive Tier-1 Partnerships | Facilitates seamless integration of alcohol sensors into new vehicle platforms, meeting OEM requirements. |
| Expand in Asia-Pacific Markets | Captures demand from tightening road safety laws and increased drunk-driving enforcement in growing economies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Industry stakeholders, including automotive engineers, law enforcement procurement officers, medical device specialists, and regulatory body representatives, provided critical perspectives. Secondary data sources encompassed NHTSA reports, EU General Safety Regulation documents, company annual reports, and patent databases. This approach enabled comprehensive bottom-up and top-down triangulation for market sizing.
The forecast window was anchored to historical reference periods, establishing a baseline for future projections over the projection horizon. The analytical framework modeled market dynamics across product type, application, technology, end user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical growth patterns and projected regulatory impacts. Key inputs included global vehicle production forecasts and regulatory mandate implementation timelines.
Underlying measurement precision varies by segment; law enforcement and medical applications carry tighter precision than consumer segments. Forecasts reflect assumptions regarding regulatory enforcement and technological breakthroughs. Platinum price volatility and automotive certification delays could revise projections, so outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Beacon Technology Market
Sensors
Traffic Sensor Market
Sensors
Mobile Lidar Scanner Market
Sensors
Data Buoy Market
Sensors
Robot Sensor Market
Sensors
Industrial Barcode Scanners Market
Sensors
Voice Sounders Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
2D Barcode Reader Market
Sensors
Underground Service Locator Market
Sensors
Beacon Market
Sensors
Digital Olfaction Products Market
Sensors
IO Link Market
Sensors
Europe RFID Market
Sensors
Global Positioning Systems Market
Sensors
Global Real-Time Locating Systems (RTLS) Market