
 Connected Smart Thermostats Market | 2026-2036
Connected Smart Thermostats Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Smart Thermostats Market Insights
The EU Green Deal's building renovation targets is realigning procurement criteria across European property portfolios toward connected climate controls. Google Nest leverages its AI-driven learning algorithms to sustain premium positioning in self-install channels. ecobee anchors its competitive stance through deep utility rebate partnerships across North American electricity markets. Honeywell International Inc. dominates commercial-grade installations with BACnet-integrated systems for building automation networks.
Connected smart thermostats are network-enabled environmental controls that modulate heating, ventilation, and air conditioning through wireless protocols such as Zigbee, Z-Wave, or Wi-Fi, typically operating within 2.4 GHz frequency bands and supporting API-level integration with broader building management platforms. Their primary commercial purpose is to reduce energy consumption through occupancy sensing, weather-responsive scheduling, and remote diagnostics while providing granular consumption data to utilities and facility operators. Wi-Fi connectivity captures the largest installed base due to router-native compatibility and minimal gateway requirements, though Zigbee segments are expanding fastest in multi-device smart home ecosystems where mesh networking improves whole-home reliability. Professional installation retains margin concentration in commercial and hospitality end-user segments where commissioning complexity and warranty liability deter DIY approaches.
The U.S. EPA ENERGY STAR certification program and the EU Ecodesign Directive jointly establish minimum efficiency thresholds and testing protocols that determine retail access and rebate eligibility on both sides of the Atlantic. The U.S. Inflation Reduction Act's Home Energy Performance-Based, Whole-House Rebates program directly conditions federal funding on smart thermostat deployment as part of comprehensive retrofit packages. Stakeholders must monitor how fragmented national building codes evolve to mandate interoperable IoT protocols, as this will determine which connectivity standards achieve de facto regulatory lock-in and which hardware ecosystems face stranded asset risk.
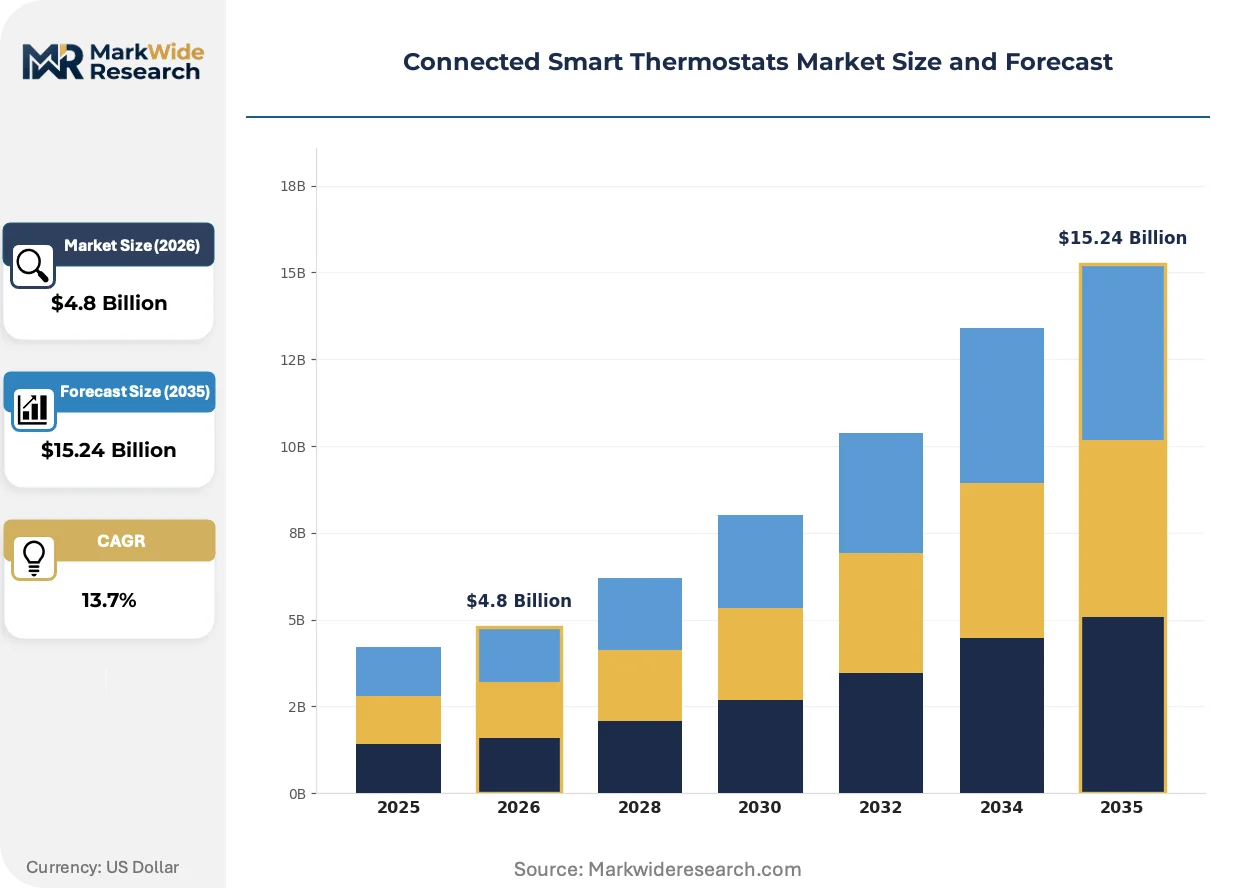
Market Dynamics
The U.S. Inflation Reduction Act's Home Energy Performance-Based, Whole-House Rebates program is restructuring residential procurement by conditioning federal funding on smart thermostat deployment within comprehensive retrofit packages, forcing hardware vendors to align certification pathways with EPA ENERGY STAR testing protocols.
Growth Catalysts
- EU Green Deal building renovation targets:Germany's multifamily housing stock is accelerating smart HVAC upgrades as the framework mandates connected climate controls in renovated properties.
- Wi-Fi router-native compatibility:Residential builders across the United States are expanding procurement of Wi-Fi-enabled units due to minimal gateway requirements and seamless integration.
- Utility rebate partnerships:North American electricity markets are deepening rebate programs that subsidize device costs, reducing consumer acquisition friction.
Market Restraints
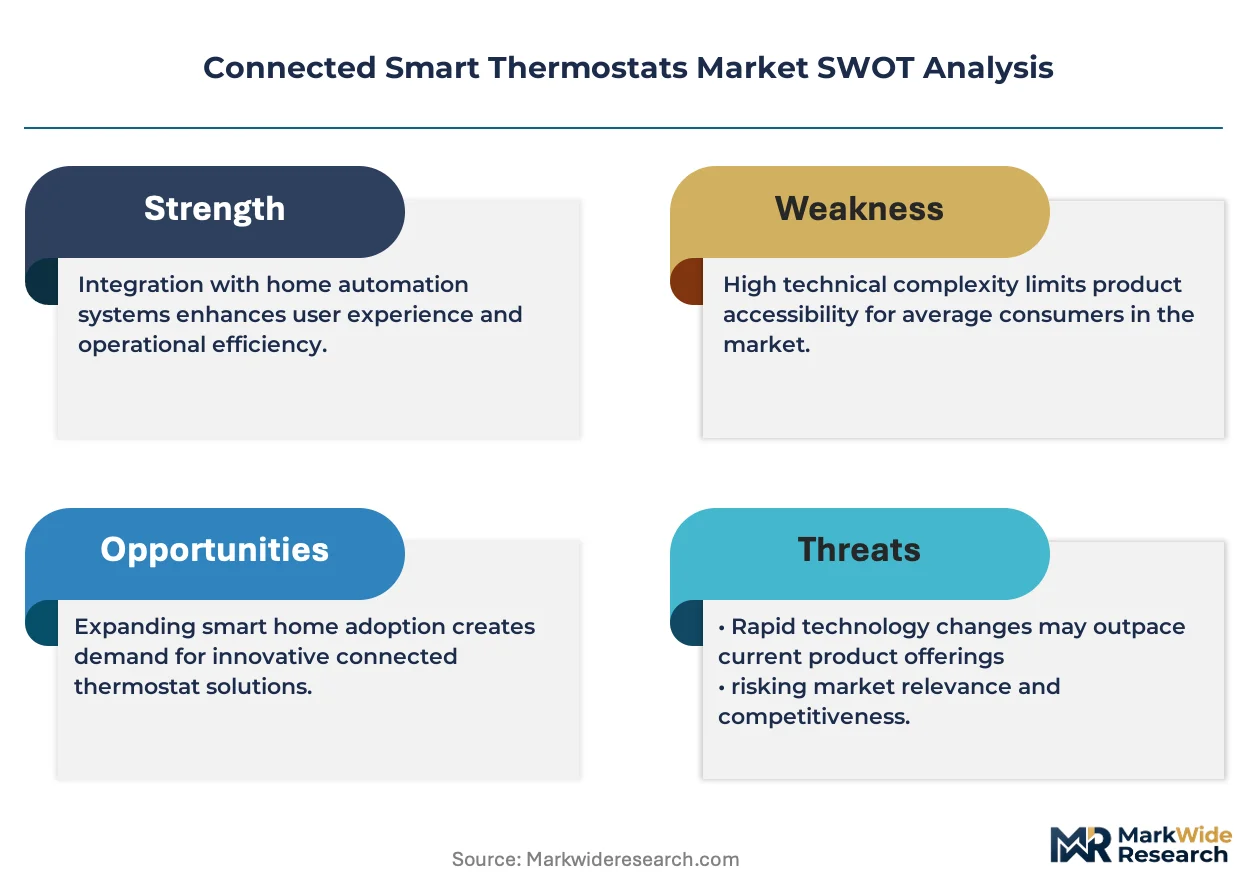
- Silicon supply concentration:Semiconductor fabrication for wireless chipsets remains concentrated in East Asian foundries, exposing hardware vendors to input volatility.
- Gateway dependency for Zigbee:Mesh networking protocols require proprietary hubs, creating consumer friction versus router-native Wi-Fi alternatives.
- Fragmented national building codes:Inconsistent IoT protocol mandates across U.S. states and EU member countries risk stranded asset exposure for ecosystem-specific hardware.
Strategic Opportunities
- Commercial building automation:BACnet-integrated systems for hospitality and office segments remain underpenetrated relative to residential, offering margin concentration through professional installation.
- Weather-responsive scheduling convergence:Machine learning algorithms combined with real-time meteorological APIs are enabling predictive HVAC modulation.
- India's smart city infrastructure:The country's national building efficiency mandates are creating first-mover advantages for vendors establishing local certification.
Industry Challenges
- Commissioning complexity:Commercial and hospitality segments require certified technician networks, constraining scalable deployment.
- Interoperability certification timelines:Multi-protocol testing against Zigbee, Z-Wave, and Wi-Fi standards extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Smart Thermostats Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Residential, Commercial, Industrial, Hospitality Connectivity Mode: Cloud-Based, Local Control, Hybrid, Remote Access Installation Type: DIY, Professional, Retrofit, New Construction |
| Companies Covered | Google Nest, ecobee, Honeywell International Inc., Emerson Electric Co., Resideo Technologies, Carrier Corporation, Robert Bosch GmbH, Lennox International Inc., Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Smart Thermostats Market Trends and Innovations
Artificial intelligence is compressing the gap between device-level optimization and whole-building energy management, enabling predictive modulation that reduces utility peak demand charges while generating granular consumption data streams.
Matter protocol development is unifying previously fragmented smart home ecosystems by enabling cross-platform device communication across Apple HomeKit, Google Home, and Amazon Alexa environments. HVAC manufacturers are adopting Matter certification to reduce SKU proliferation and simplify retail packaging. This unification is compressing hardware margin pressure by commoditizing connectivity-layer differentiation.
The U.S. EPA ENERGY STAR certification program has tightened testing protocols for connected thermostats, requiring verified savings claims through standardized field studies. Retailers are conditioning shelf placement on certification compliance. The residential retrofit segment is responding by prioritizing rebate-eligible models in contractor training programs.
Utility-managed demand response programs are displacing consumer-scheduled temperature setbacks as the dominant optimization mode. Aggregators are enrolling devices into grid-scale virtual power plants, compensating homeowners for automated load curtailment. This shift is most visible in Texas and California electricity markets where real-time pricing volatility creates arbitrage value.
Connected Smart Thermostats Market Segmentation
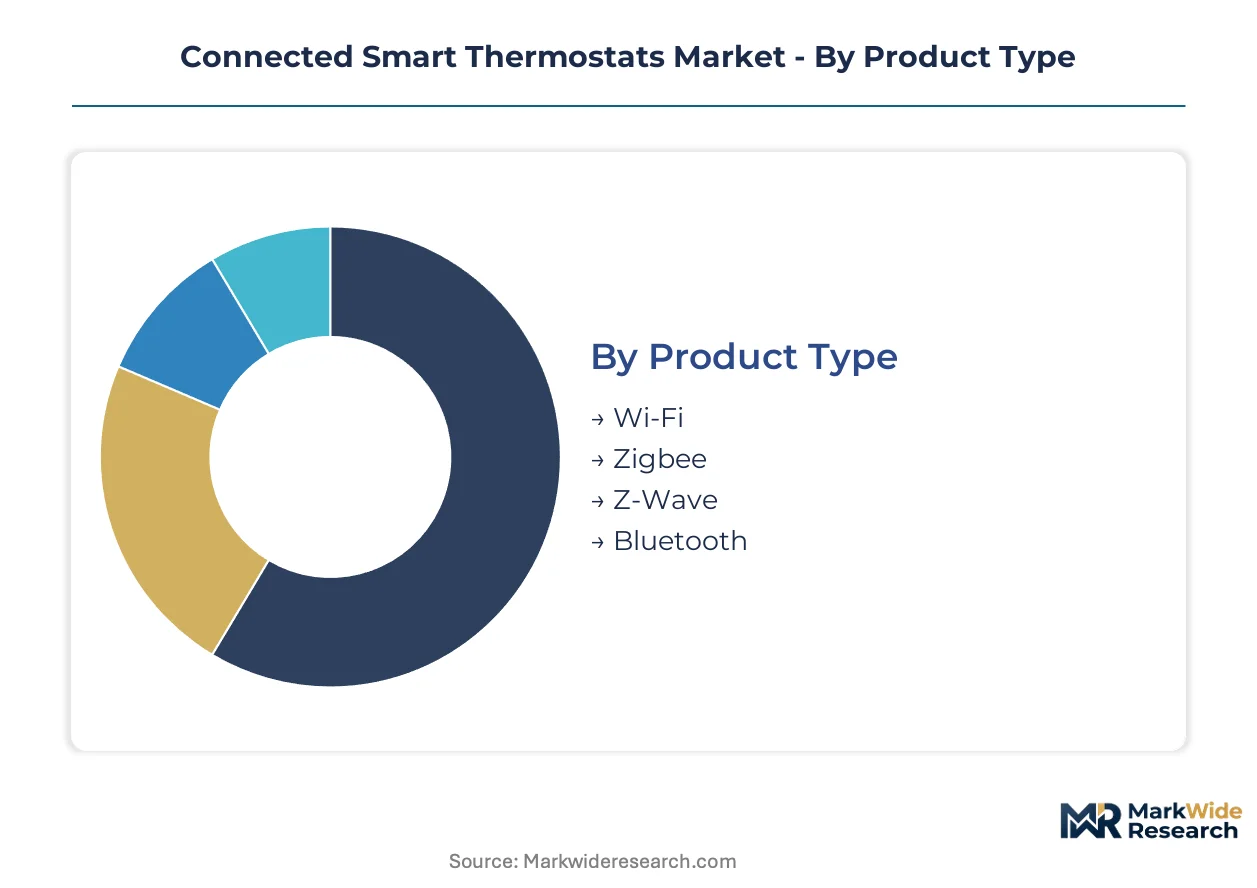
Segmentation in connected smart thermostats reveals how procurement criteria diverge across connectivity standards, installation complexity, and regulatory compliance pathways. Buyers prioritize router-native compatibility in residential retrofits while commercial portfolios demand BACnet-integrated commissioning and warranty coverage.
Product Type:
Connectivity protocol selection determines gateway requirements, mesh network reliability, and integration depth with broader building management platforms.
- Wi-Fi:Direct router integration eliminates proprietary hubs and minimizes consumer setup friction. Residential builders across the United States are expanding procurement of Wi-Fi-enabled units as the Inflation Reduction Act subsidizes home energy retrofits requiring minimal installation complexity.
- Zigbee:Mesh networking architecture improves whole-home reliability in multi-device ecosystems where signal propagation through walls matters. Germany's multifamily housing stock under EU Green Deal renovation mandates is accelerating Zigbee deployments for centralized HVAC control in apartment complexes.
- Z-Wave:Sub-GHz frequency operation reduces interference in dense urban RF environments. Utility-managed demand response programs in North American electricity markets favor Z-Wave for its proven interoperability with legacy utility gateway infrastructure.
- Bluetooth:Low-energy beaconing enables proximity-based occupancy sensing without persistent cloud connectivity. Hospitality segments deploy Bluetooth for guest room entry integration and localized climate pre-conditioning.
Volume sits with Wi-Fi; growth tilts toward Zigbee.
End User:
Margin concentration and procurement authority vary sharply between consumer self-installation and facility-managed enterprise deployment.
- Residential:Self-install channels dominate with AI-driven learning algorithms reducing manual scheduling. EPA ENERGY STAR certification determines rebate eligibility and retail shelf placement across North American big-box retailers.
- Commercial:BACnet-integrated systems command premium pricing through professional installation networks. Commissioning complexity and warranty liability deter DIY approaches in office and retail portfolios.
- Industrial:Harsh-environment enclosures and process-control integration distinguish this tier from standard commercial offerings. Facility operators demand API-level integration with SCADA and energy management platforms.
- Hospitality:Property management system integration and guest-facing mobile apps define procurement specifications. Franchise operators prioritize unified fleet management across distributed properties.
Revenue concentrates in Commercial; expansion is steepest in Residential retrofit channels.
Connectivity Mode:
Data sovereignty requirements and latency tolerance shape architecture selection across regulated and unregulated building portfolios.
- Cloud-Based:Continuous telemetry enables utility-managed demand response and predictive maintenance algorithms. Texas and California electricity markets leverage cloud connectivity for real-time pricing arbitrage and automated load curtailment.
- Local Control:On-device processing satisfies GDPR data residency constraints and eliminates cloud dependency for critical infrastructure. European multifamily operators facing EU AI Act algorithmic transparency mandates favor local inference.
- Hybrid:Edge-cloud partitioning optimizes bandwidth costs while preserving remote diagnostics capability. Large commercial portfolios use hybrid modes to isolate sensitive operational data from consumer-facing features.
- Remote Access:Mobile-first interfaces dominate consumer expectations but introduce cybersecurity attack surfaces. NIST cybersecurity framework compliance is becoming a procurement gate in federal building retrofits.
Deployment share favors Cloud-Based; compliance pressures are elevating Hybrid architectures.
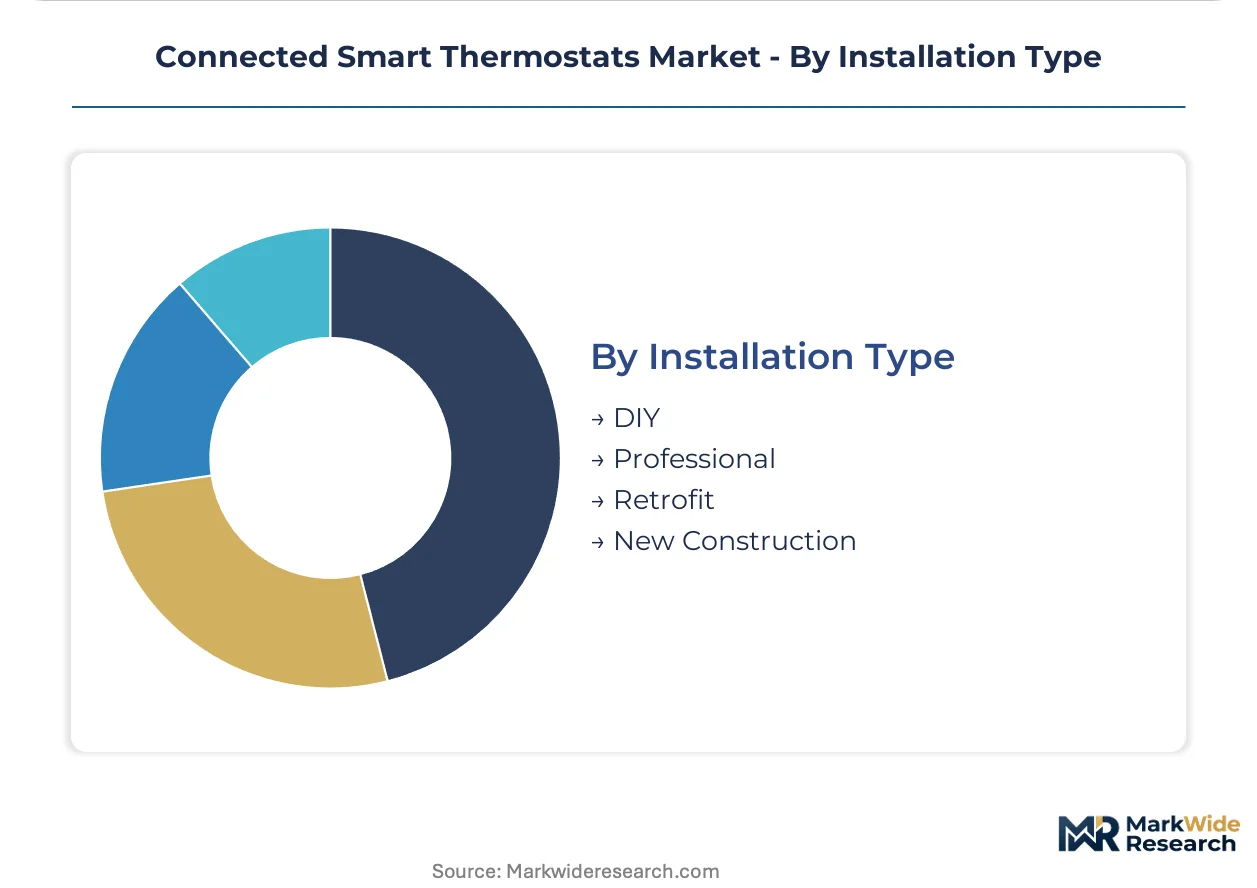
Installation Type:
Labor cost structures and skill availability create divergent go-to-market economics across channel partners.
- DIY:Retail self-install captures volume in single-family residential where wiring compatibility is standardized. Matter protocol certification is reducing SKU proliferation and simplifying packaging for mass-market channels.
- Professional:Certified technician networks command margin concentration in commercial and hospitality segments where commissioning determines warranty validity. Honeywell International Inc. dominates this tier through building automation contractor relationships.
- Retrofit:Existing building stock renovation drives replacement cycles tied to HVAC end-of-life and regulatory efficiency mandates. The U.S. Inflation Reduction Act's Whole-House Rebates program conditions federal funding on smart thermostat inclusion in comprehensive retrofit packages.
- New Construction:Pre-wiring and builder specification lock-in create long-term ecosystem capture. Residential builders across North America are expanding procurement of Wi-Fi-enabled units as standard equipment in energy-certified homes.
Transaction volume flows through DIY; value capture concentrates in Professional installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian semiconductor foundries while consumption tilts toward North American and European retrofit markets. Regulatory subsidy programs in Germany and the United States are accelerating procurement velocity ahead of production capacity expansion.
United States
Residential builders are expanding Wi-Fi-enabled thermostat procurement as the Inflation Reduction Act subsidizes whole-house energy retrofits. The EPA ENERGY STAR certification program determines rebate eligibility and retail shelf placement across big-box channels. Texas and California electricity markets lead utility-managed demand response enrollment.
Germany
Multifamily housing stock is accelerating smart HVAC upgrades under EU Green Deal building renovation mandates. The country's national building efficiency regulator enforces connected climate control inclusion in renovated properties. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate HVAC contractor networks and professional installation capacity.
China
Domestic demand for smart home ecosystems is expanding Zigbee mesh network deployments in high-density urban housing. The Ministry of Industry and Information Technology governs wireless protocol certification for IoT devices. Manufacturing concentrates in the Yangtze River Delta and Pearl River Delta regions for wireless chipset fabrication and device assembly.
Japan
Commercial building automation is adopting BACnet-integrated systems for office energy management under METI efficiency guidelines. The country's industrial standards body certifies interoperability protocols for HVAC control networks. The Kanto region around Tokyo anchors professional installation networks and facility management service providers.
India
National smart city infrastructure programs are creating first-mover opportunities for vendors establishing local certification pathways. The Bureau of Indian Standards governs electronics safety and wireless equipment approvals. Maharashtra and Karnataka states concentrate technology deployment pilots and contractor training programs.
Connected Smart Thermostats Market Competitive Landscape
The competitive structure tilts toward platform-integrated technology providers with established utility rebate channels. Market concentration is moderate, with distinct tiers separating consumer self-install specialists from commercial-grade building automation vendors. Three archetypes dominate: AI-driven learning algorithm developers, deep utility partnership operators, and BACnet-integrated commercial systems providers. Strategic moves center on Matter protocol certification for SKU reduction and demand response aggregator partnerships for grid-scale virtual power plant enrollment.
Within the AI-driven consumer tier, Google Nest and ecobee exemplify divergent channel strategies—one leveraging retail algorithmic differentiation, the other anchoring utility rebate networks. Honeywell International Inc. occupies the commercial-grade installation tier through building automation contractor relationships. These three represent the spectrum from mass-market self-install to professional commissioning-dependent enterprise deployment.
| Leading Market Players |
|---|
| Google Nest |
| ecobee |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Resideo Technologies |
| Carrier Corporation |
| Robert Bosch GmbH |
| Lennox International Inc. |
| Trane Technologies |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between EPA ENERGY STAR-eligible and uncertified hardware manifests in both pricing power and supply chain sourcing strategies. Premium-tier vendors command rebate-anchored price points through vertical integration into semiconductor sourcing, while commodity producers compete on router-native Wi-Fi compatibility and minimal gateway requirements.
Pricing Analysis
Margin tightening in the DIY residential tier reflects Matter protocol commoditization compressing connectivity-layer differentiation. Three-tier pricing structure across premium AI-enabled, standard connected, and economy non-learning models stratifies by algorithm sophistication and utility partnership depth. Pricing pressure intensifies in Wi-Fi segments as router-native compatibility becomes table stakes. Commercial BACnet-integrated buyers demonstrate lowest price sensitivity due to warranty liability and commissioning complexity, while retail self-install channels face acute cost-down demands.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries for wireless chipset fabrication, particularly Zigbee and Z-Wave radio modules. Manufacturing concentrates in China, Taiwan, and South Korea for semiconductor wafer production and device assembly. Raw material dependencies include silicon wafers, rare-earth magnet components for HVAC actuators, and lithium coin cells for battery-backed units. Tariff exposure on Chinese electronics imports threatens margin stability for cost-optimized product lines. Distribution runs through building automation contractor networks for commercial tiers and big-box retail for residential self-install.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive control over wireless chipset supply and utility rebate channel access determines competitive survival. Incumbents and challengers alike must secure upstream semiconductor sourcing or downstream aggregator partnerships to defend position.
For Market Incumbents: Cement utility rebate channel exclusivity through EPA ENERGY STAR certification investment and demand response aggregator partnerships. Acquire Zigbee chipset design capabilities to reduce Taiwan foundry dependency. Matter protocol certification mandates threaten ecosystem lock-in advantages. For New Entrants and Emerging Players: Enter via India's smart city infrastructure programs where local BIS certification creates first-mover moats. Target hospitality property management system integration as the most penetrable commercial segment. Pursue white-label manufacturing partnerships with Yangtze River Delta assembly houses to bypass capital-intensive fabrication. For Investors and Strategic Acquirers: Re-rating potential sits with BACnet-integrated commercial specialists given EU Green Deal building renovation mandates accelerating professional installation demand. Long-term viability favors vendors with backward integration into wireless chipset design and utility-managed demand response enrollment scale. Watch Texas and California virtual power plant enrollment curves as inflection indicators for grid-scale revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Reduces SKU proliferation across Apple HomeKit, Google Home, and Amazon Alexa ecosystems. |
| Utility Rebate Partnership Expansion | Secures EPA ENERGY STAR-conditioned federal funding access under IRA Whole-House Rebates. |
| Demand Response Aggregator Enrollment | Enables virtual power plant participation in FERC-jurisdictional electricity markets. |
| Backward Integration into Chipset Design | Mitigates Taiwan foundry concentration risk for Zigbee and Z-Wave radio modules. |
| Local Control Architecture Development | Addresses GDPR data residency and EU AI Act algorithmic transparency mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with HVAC contractor network managers, utility demand response program officers, smart home platform engineers, and big-box retail category buyers combined with EPA ENERGY STAR certification databases, FCC equipment authorization filings, and EU Ecodesign Directive implementation reports. Bottom-up unit shipment modeling and top-down retrofit spending allocation triangulated market sizing across connectivity protocols and installation types.
Granularity-level modeling operated at the connectivity standard-by-end-user intersection, with separate trajectory calibration for Wi-Fi, Zigbee, Z-Wave, and Bluetooth segments across residential, commercial, industrial, and hospitality deployments. CAGRs derived from regulatory subsidy program scaling curves and HVAC replacement cycle analysis. Machine learning algorithm adoption rates and utility-managed demand response enrollment velocity served as industry-specific forecast inputs throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios and fragmented national building code evolution. Forecasts reflect documented assumptions regarding IRA rebate program implementation pace and EU Green Deal renovation target achievement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Bluetooth Photo Capture Device Market
Sensors
Industrial Automation Sensors Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Underground Utility Mapping Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Lidar Market
Sensors
Eye Tracking Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Mobile Lidar Scanner Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Cloud Camera Market
Sensors
Smart Mat Market
Sensors
Refrigeration Monitoring Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Lidar in Construction Market
Sensors
Smart Barcode Readers Market