
 Global Supply Chain Management (SCM) Market | 2026-2036
Global Supply Chain Management (SCM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Supply Chain Management (SCM) Market Foresight
Buyer concentration among automotive OEMs and large retail chains is hardening as procurement teams consolidate vendor relationships onto fewer integrated platforms. SAP leverages its S/4HANA supply chain suite to anchor enterprise manufacturing accounts across Germany and Japan. Oracle competes through cloud-native logistics modules that extend its ERP footprint into transportation and warehouse operations. Kinaxis differentiates via concurrent planning architecture that positions its RapidResponse platform for semiconductor and pharmaceutical demand volatility.
Supply chain management encompasses the integrated planning, execution, and monitoring of material flows, information exchanges, and financial transactions from raw material sourcing through final delivery, typically orchestrated through software platforms employing optimization algorithms, real-time data ingestion, and multi-echelon inventory logic. Cloud-based deployment models are capturing the fastest expansion as manufacturers migrate from legacy on-premises installations to SaaS architectures with lower total cost of ownership and faster implementation cycles. Warehouse management solutions sustain the largest revenue pool among solution offerings due to persistent labor constraints and automation integration requirements in e-commerce fulfillment centers.
The EU AI Act, REACH chemical tracking obligations, and FDA pharmaceutical traceability mandates collectively elevate compliance tracking and risk management module priorities across regulated industries. ISO 28000 supply chain security standards and IEC 62443 industrial cybersecurity frameworks further shape product certification requirements for platform vendors serving critical infrastructure sectors. Stakeholders must monitor evolving algorithmic audit obligations in Europe and emerging carbon disclosure rules that will embed emissions tracking directly into procurement and logistics workflows.
Market Dynamics
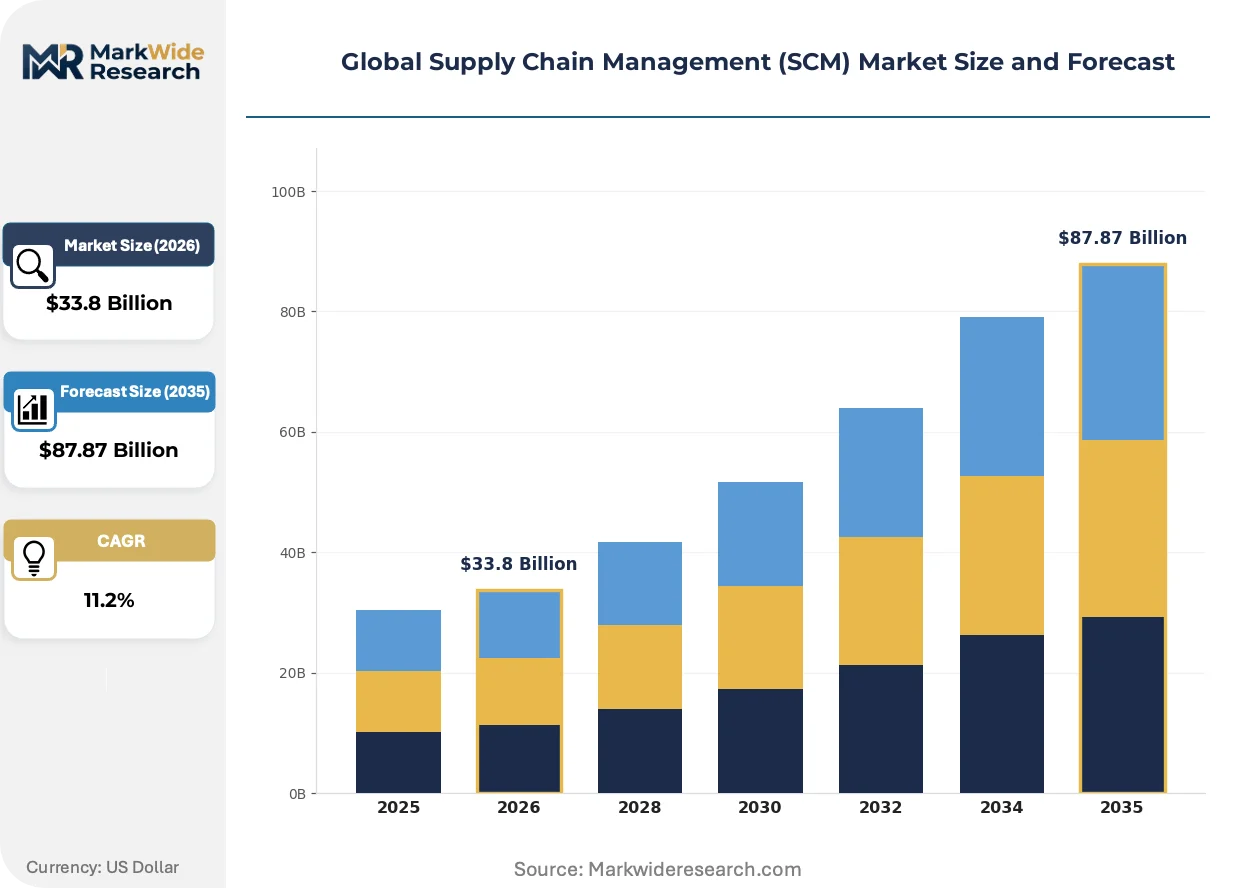
Automotive OEM procurement consolidation is compressing vendor ecosystems as multi-tier supplier coordination demands unify onto integrated planning platforms. The EU AI Act's algorithmic audit requirements are forcing compliance module redesigns across European deployments.
Growth Catalysts
- Multi-tier supplier visibility mandates:Automotive OEMs require real-time coordination across three-plus supplier tiers. Cloud-native architectures enable this granularity where legacy ERP fragments.
- REACH chemical tracking obligations:European manufacturers must embed substance compliance into procurement workflows. SCM platforms with integrated regulatory databases capture this spend.
- Warehouse labor scarcity:E-commerce fulfillment centers face persistent staffing gaps. Automation-integrated WMS modules address throughput constraints directly.
Market Restraints
- Cloud migration cost structure:Manufacturers face 18-36 month payback periods for SaaS transitions. On-premises sunk costs and retraining expenses delay procurement decisions.
- Semiconductor supply concentration:Planning platform hardware dependencies cluster in Taiwan and South Korea. Geopolitical friction elevates delivery risk for on-premise appliance deployments.
- Legacy system interoperability:Decades-old MRP installations lack API-native architectures. Point-to-point integration requirements inflate implementation timelines.
Strategic Opportunities
- Indian manufacturing digitization:PLI scheme beneficiaries require supply chain visibility for incentive compliance. Domestic cloud infrastructure maturity enables SaaS delivery.
- Carbon disclosure integration:CSRD mandates embed emissions tracking into procurement workflows. Platforms with Scope 3 calculation engines differentiate in European RFPs.
- AI-optimization convergence:Machine learning demand forecasting merges with digital twin simulation. Pharmaceutical cold chain applications represent early validation terrain.
Industry Challenges
- Concurrent planning expertise scarcity:Kinaxis-style architecture deployment requires specialized supply chain mathematicians. Talent pools concentrate in Toronto, Munich, and Bangalore.
- IEC 62443 certification timelines:Industrial cybersecurity framework compliance adds 8-14 months to platform releases. Critical infrastructure buyers mandate this accreditation.
- Multi-echelon inventory logic integration:Legacy safety stock calculations conflict with optimization engine outputs. Change management resistance prolongs pilot phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Supply Chain Management (SCM) Market |
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $87.87 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Inventory Management, Transportation Management, Warehouse Management, Supplier Management, Demand Planning, Order Fulfillment Deployment Model: Cloud-Based, On-Premises, Hybrid, Hosted, SaaS, Managed Services Application: Procurement, Logistics Optimization, Production Scheduling, Risk Management, Customer Service, Compliance Tracking End User Industry: Manufacturing, Wholesale Distribution, Third-Party Logistics, Retail Chains, E-commerce Platforms, Automotive OEMs |
| Companies Covered | SAP, Oracle, Blue Yonder, E2open, Manhattan Associates, Infor, IBM, Kinaxis, WiseTech Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Supply Chain Management (SCM) Market Shifts & Advancements
Digital twin simulation is compressing planning cycles from weeks to hours. Regulatory algorithmic transparency mandates are embedding audit trails directly into optimization engines. Buyer procurement consolidation is elevating platform-switching costs and entrenching incumbent vendors.
Digital twin technology is integrating physics-based simulation with real-time ERP data ingestion. Pharmaceutical and semiconductor manufacturers deploy these models for scenario stress-testing. The technology is integrating demand volatility response into continuous planning rather than batch cycles.
EU AI Act algorithmic transparency requirements are mandating explainable optimization logic in automated procurement decisions. Vendors must document decision pathways for high-risk supply chain AI applications. German automotive clusters are piloting audit-ready platforms ahead of enforcement timelines.
Automotive OEM procurement teams are consolidating vendor relationships onto fewer integrated suites. Discrete point solutions for transportation or warehouse management lose standalone viability. This concentration is most visible in Stuttgart and Munich industrial corridors where SAP and Oracle anchor enterprise accounts.
Global Supply Chain Management (SCM) Market Segmentation
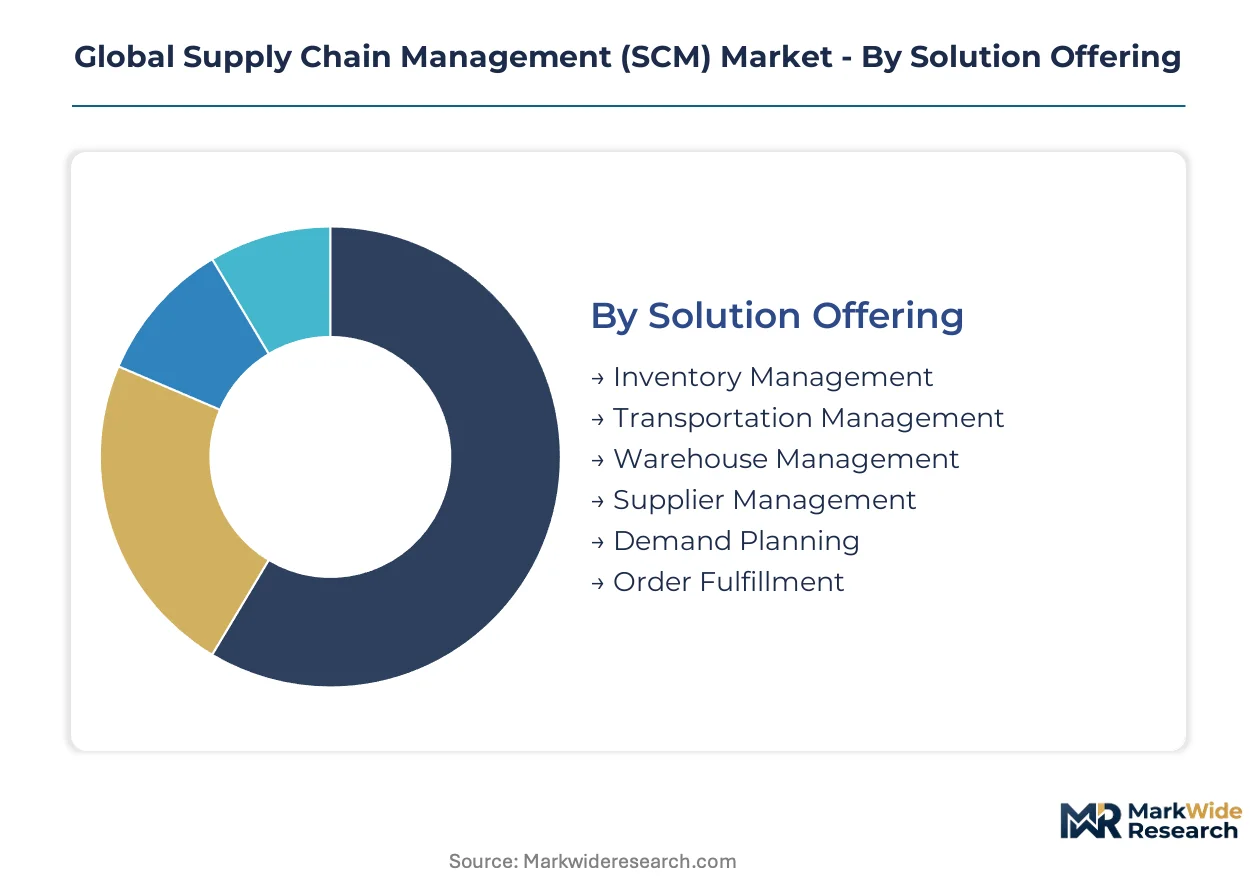
SCM procurement decisions hinge on matching deployment architecture to operational maturity and regulatory exposure. Segment boundaries blur as integrated suites subsume point solutions, yet buyers still evaluate modules through distinct functional lenses.
Solution Offering:
Standardized modules dominate mid-market procurement, while enterprise buyers demand configurable engines that accommodate multi-echelon inventory logic and custom constraint modeling.
- Warehouse Management:Automation-orchestration platforms coordinate robotics, AS/RS systems, and labor pools through real-time task optimization. E-commerce fulfillment centers in Germany and the United States drive procurement as throughput requirements outpace staffing availability. Labor scarcity and same-day delivery SLAs elevate WMS to the largest revenue pool within solution categories.
- Transportation Management:Multi-modal optimization engines ingest carrier rates, transit times, and carbon emissions data for route selection. Pharmaceutical cold chain shippers and automotive OEMs in Stuttgart industrial clusters prioritize TMS modules with temperature excursion alerts and customs documentation automation.
- Inventory Management:Multi-echelon safety stock algorithms balance service levels against carrying costs.
- Supplier Management:Multi-tier visibility dashboards track performance scorecards and risk indicators.
- Demand Planning:Statistical forecasting engines incorporate machine learning for volatility absorption.
- Order Fulfillment:Omnichannel orchestration modules unify allocation logic across warehouse and store networks.
Leading the category by volume: Warehouse Management. Growing fastest: Transportation Management.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises installations from operational-expense SaaS contracts, with hybrid architectures occupying the middle ground for manufacturers with legacy ERP dependencies.
- Cloud-Based:Scalable infrastructure enables rapid multi-site rollouts without data center investment. Automotive OEMs and third-party logistics providers in Japan and India accelerate migration as total cost of ownership advantages compound across distributed networks.
- SaaS:Subscription pricing aligns vendor incentives with customer success metrics and reduces implementation risk. Mid-market manufacturers in France and Brazil favor SaaS for rapid deployment without dedicated IT infrastructure.
- On-Premises:Appliance-based deployments persist where data sovereignty requirements or air-gapped security mandates apply.
- Hybrid:Split architectures keep sensitive planning data local while extending execution modules to cloud.
- Hosted:Single-tenant managed infrastructure offers customization latitude without capital expenditure.
- Managed Services:Outsourced platform administration transfers operational burden to vendor or partner teams.
Expanding most quickly: Cloud-Based and SaaS. Contracting: On-Premises.
Application:
Customer type differentiation separates compliance-heavy regulated industries from velocity-focused retail operations, with module selection reflecting audit intensity versus throughput optimization priorities.
- Compliance Tracking:Regulatory database integration automates REACH chemical verification and FDA pharmaceutical traceability. European chemical manufacturers and medical device producers mandate these modules for audit readiness under EU AI Act algorithmic transparency requirements.
- Risk Management:Scenario simulation engines stress-test networks against supplier insolvency, port congestion, and geopolitical disruption. Semiconductor and pharmaceutical manufacturers with concentrated Taiwan and South Korean supply dependencies prioritize risk modules for continuity planning.
- Procurement:Sourcing automation with embedded carbon accounting supports CSRD disclosure obligations.
- Logistics Optimization:Network design tools minimize total landed cost across distribution footprints.
- Production Scheduling:Constraint-based finite capacity planning synchronizes material availability with equipment utilization.
- Customer Service:Order promising engines calculate available-to-promise dates across complex supply networks.
Highest procurement priority: Compliance Tracking. Steepest expansion trajectory: Risk Management.
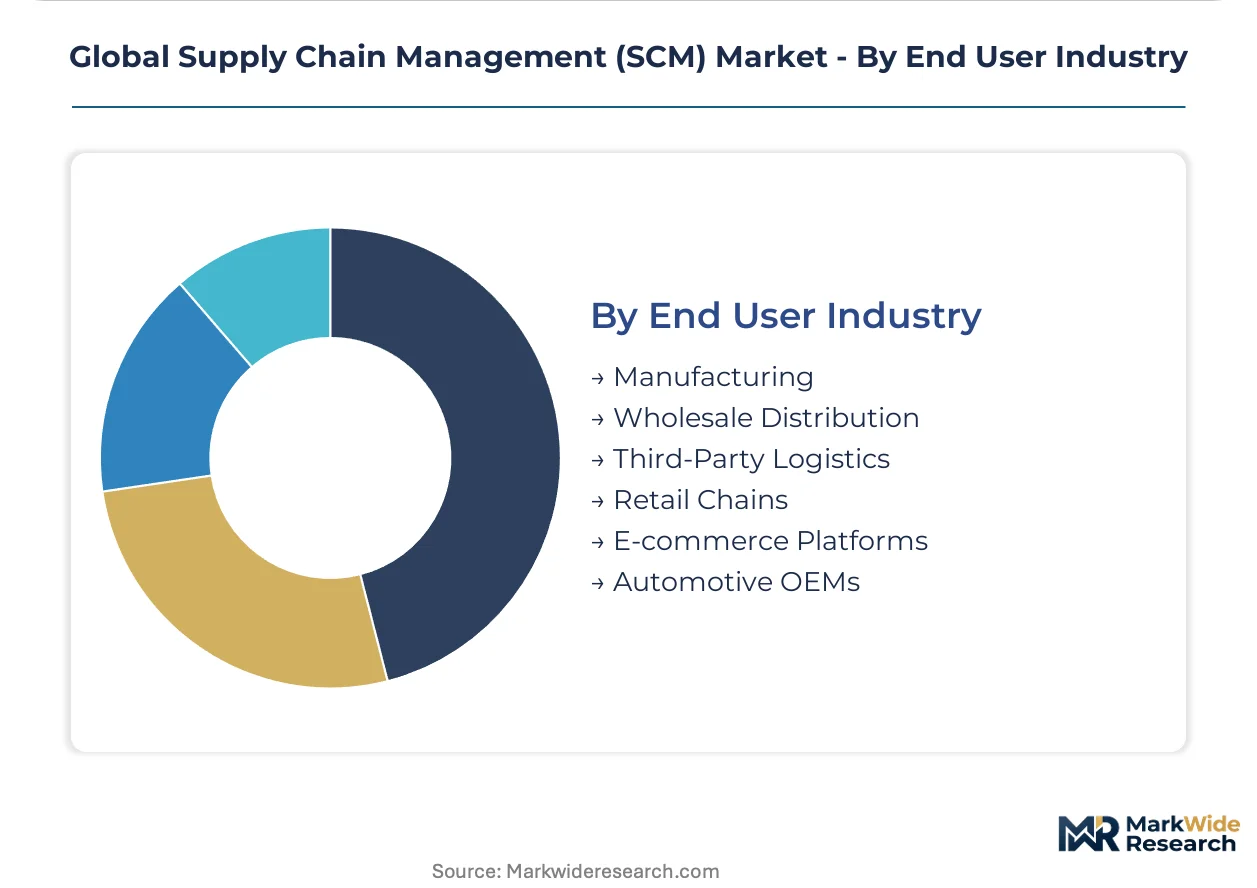
End User Industry:
Maturity gradients separate digitally native e-commerce platforms from industrial manufacturers with decades-old MRP installations, with implementation complexity and change management requirements scaling inversely with digital starting position.
- Automotive OEMs:Multi-tier supplier coordination demands unify procurement onto integrated planning platforms. Stuttgart and Munich industrial clusters consolidate vendor relationships as three-plus tier visibility mandates harden across German, Japanese, and South Korean manufacturing networks.
- E-commerce Platforms:Real-time inventory visibility and same-day fulfillment optimization require cloud-native architectures with elastic scaling. Fulfillment center automation investments in the United States and China drive WMS and order fulfillment module procurement.
- Manufacturing:Discrete and process producers balance lean inventory targets with service level commitments.
- Third-Party Logistics:Multi-customer visibility requirements demand tenant-isolated platform architectures.
- Retail Chains:Omnichannel allocation engines optimize fulfillment from distribution centers and store backrooms.
- Wholesale Distribution:Bulk order processing and vendor-managed inventory programs shape module selection.
Gaining share fastest: E-commerce Platforms. Anchoring procurement volume: Automotive OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams concentrate demand in Germany and Japan, while cloud migration accelerates fastest in India and Brazil. Regulatory complexity elevates compliance module priorities across European chemical and pharmaceutical clusters.
United States
E-commerce fulfillment centers and automotive Tier-1 suppliers drive WMS and TMS procurement. FDA pharmaceutical traceability mandates elevate audit-ready platform specifications. Dallas-Fort Worth logistics corridors anchor third-party logistics provider consolidation onto cloud-native suites.
Germany
Automotive OEMs mandate multi-tier supplier visibility across Stuttgart and Munich industrial clusters. EU AI Act algorithmic transparency requirements force optimization engine redesigns for automated procurement decisions. Baden-Württemberg planning system procurement concentrates around integrated S/4HANA deployments.
China
Dual carbon goals and MIIT smart manufacturing directives embed emissions tracking into procurement workflows. Yangtze River Delta electronics manufacturers accelerate SaaS migration for distributed supplier coordination. Shanghai-based semiconductor fabs prioritize risk management modules for Taiwan supply concentration exposure.
India
PLI scheme beneficiaries require supply chain visibility for incentive compliance verification. Domestic cloud infrastructure maturity enables rapid SaaS rollout across Maharashtra and Gujarat manufacturing zones. Bangalore and Hyderabad tech corridors concentrate concurrent planning expertise for pharmaceutical demand volatility applications.
Japan
METI supply chain resilience initiatives mandate multi-tier visibility for automotive and electronics networks. Toyota and Honda procurement consolidation compresses vendor ecosystems onto integrated platforms. Nagoya industrial corridor anchors enterprise manufacturing accounts with hybrid cloud deployments.
Global Supply Chain Management (SCM) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized concurrent planning and carbon accounting niches. The vendor base stratifies across ERP-anchored suites, cloud-native logistics specialists, and optimization engine pure-plays. Three archetypes dominate: integrated platform incumbents extending ERP footprints, best-of-breed WMS/TMS vendors capturing automation integration spend, and concurrent planning specialists serving semiconductor and pharmaceutical volatility. Competitive intensity manifests through M&A consolidation of point solutions and strategic partnerships embedding AI forecasting into digital twin architectures.
Within the integrated platform tier, SAP and Oracle exemplify ERP-anchored market presence, while Kinaxis occupies a distinct position in concurrent planning specialization. SAP leverages S/4HANA supply chain suites across German and Japanese automotive OEM accounts. Oracle extends cloud-native logistics modules into transportation and warehouse operations. Kinaxis positions its RapidResponse platform for demand volatility absorption in semiconductor and pharmaceutical verticals.
| Leading Market Players |
|---|
| SAP |
| Oracle |
| Blue Yonder |
| E2open |
| Manhattan Associates |
| Infor |
| IBM |
| Kinaxis |
| WiseTech Global |
| Others |
Supply & Pricing Matrix
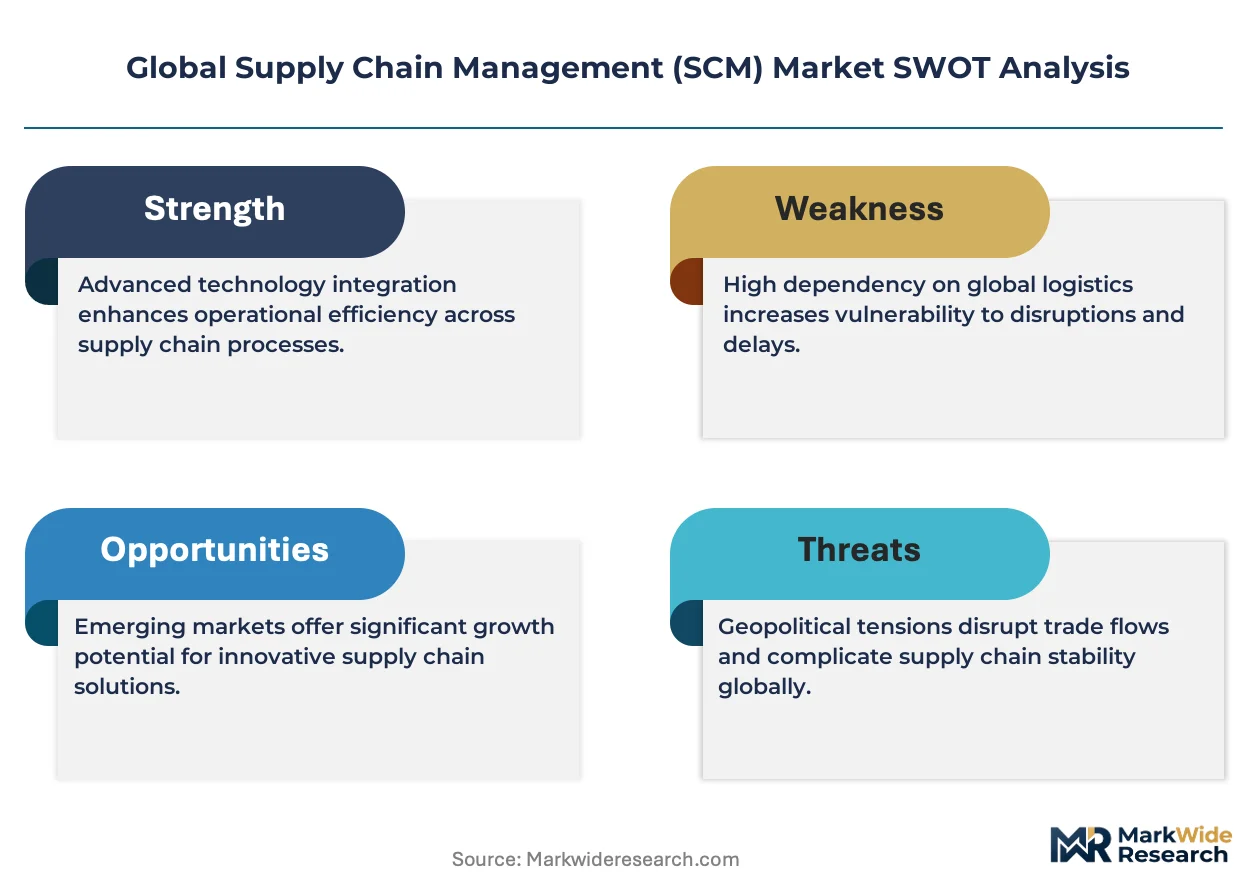
EU AI Act algorithmic transparency mandates gate qualified supply and premium-tier pricing access, as vendors without audit-ready optimization engines face exclusion from Stuttgart and Munich automotive procurement clusters while certified platforms command subscription premiums.
Pricing Analysis
Volume concentrates in standardized SaaS tiers while margins accrue to configurable engines with multi-echelon inventory logic. Three-tier pricing structure across premium, standard, and economy levels separates concurrent planning specialists from mid-market SaaS providers. Cost compression in standard tiers is intensifying because cloud infrastructure commoditization erodes differentiation. Mid-market manufacturers in France and Brazil exhibit highest price sensitivity; semiconductor and pharmaceutical buyers prioritize capability over cost.
Supply Chain Analysis
Dual-sourcing requirements for planning platform hardware mandate qualification across Taiwan, South Korea, and USA semiconductor fabrication facilities. SCM software development draws from Indian cloud infrastructure, German industrial automation expertise, and USA hyperscaler compute capacity. Single-source vulnerability clusters in Taiwan foundry capacity for on-premise appliance deployments. Distribution runs through direct enterprise sales teams and systems integrator partnerships anchored in regional industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Supply Chain Management (SCM) Market operates as a vertical-integration race where control over concurrent planning mathematics and carbon accounting engines determines pricing power and account retention.
For Market Incumbents: Cement platform-switching costs through embedded digital twin architectures that increase customer retraining expenses. Deepen upstream control over semiconductor supply risk analytics to offset Kinaxis-style specialist encroachment. Invest in IEC 62443 certification acceleration to compress 8-14 month compliance timelines and lock out uncertified competitors from critical infrastructure accounts.
For New Entrants and Emerging Players: Launch via carbon accounting modules targeting CSRD disclosure mandates in European chemical and pharmaceutical verticals. The most penetrable white-space sits in Scope 3 calculation engines for mid-market manufacturers lacking in-house sustainability expertise. Pursue partnership routes with domestic cloud providers in India to bypass SAP and Oracle channel dominance.
For Investors and Strategic Acquirers: EU AI Act enforcement acceleration is the leading indicator that audit-ready platform valuations will decouple from commodity SaaS multiples. Long-term viability favors vendors with concurrent planning expertise concentrated in Toronto, Munich, and Bangalore talent pools. Acquisition target archetype: optimization engine pure-plays serving semiconductor demand volatility with established pharmaceutical validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidation of point solutions onto S/4HANA suites captures Stuttgart automotive procurement volume. |
| Acquisition of Specialist Firm | Purchase of concurrent planning pure-plays adds volatility-absorption capability for pharmaceutical accounts. |
| Strategic Partnership | AI forecasting alliances with digital twin vendors compress planning cycles from weeks to hours. |
| Geographic Expansion | Indian cloud infrastructure investment enables PLI scheme compliance tracking for domestic manufacturers. |
| Product Launch | Audit-ready optimization engines with embedded EU AI Act documentation capture European RFP priority. |
Research Methodology
Independent corroboration across supply chain software vendor executives, automotive OEM procurement directors, and pharmaceutical logistics managers underwrites the qualitative findings. Primary interviews with warehouse automation integrators, cloud infrastructure specialists, and regulatory compliance officers combined with secondary validation from SEC 10-K filings, EU AI Act implementation guidance, and customs trade data. Bottom-up deployment model sizing and top-down industry spend analysis provide cross-check triangulation.
Comparable-period anchoring to historical cloud migration cycles and on-premise replacement timelines shaped the projection horizon. Segmentation dimensions modeled span deployment architecture, solution module, end-user industry vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating semiconductor supply concentration risk and REACH compliance spend requirements.
Geopolitical friction in Taiwan semiconductor supply, EU AI Act enforcement timing variation, and cloud infrastructure cost volatility are the dominant revision risks. Deviation in Taiwan supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
United States Managed Services Market
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
Helpdesk Management Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Shared Services Center Market
Enterprise Services
North America Contingent Workforce Management Market
Enterprise Services
Middle East and Africa IT Services Market